Chapter 12 Part 1 The Statement of Cash
- Slides: 90
Chapter 12 – Part 1 The Statement of Cash Flows Use Table of Contents to switch between slides
Objectives § State the Cash Flow’s primary purpose, its usefulness § Discuss & understand operating, investing, and financing activities, and noncash. § Analyze a company’s cash flow statement. § Prepare one using: the indirect method § § Note: you are not responsible to know the worksheet or direct method. (appendix 13 A and 13 B) NOTE: SUPPLEMENTARY MATERIAL – Product Life Cycle and Cash Flow. Warning: Not in book!!!
The Primary Purpose of the Statement of Cash Flows Is. . . § To provide information about: • cash receipts, • cash payments, and • the net change in cash resulting from: Ø operating, Ø investing, and Ø financing activities of a company during a period.
Classification of Cash Flows
Questions the Statement of Cash Flow Answers
Operating Activities. . . Include: § The cash effects of transactions that create revenues and expenses and § Enter into determination of net income. Involve Income Statement Items
Types of Cash Flows Operating Activities Cash inflows: • From sale of goods or services • From interest received and dividends received • To receive cash on account § Cash outflows: • To suppliers for inventory • To pay down accounts payable • To employees for services • To government for taxes • To lenders for interest • To others for expenses §
Operating Activities - ALERT § Some cash flows relating to investing or financing activities are classified as operating activities. For example. . . • Receipts of investment revenue (interest and dividends) and • Payments of interest to lenders • Sale or Purchase of Trading Securities
Investing Activities. . . Include: § Purchasing and disposing of investments and productive long-lived assets using cash and § Lending money and collecting the loans. Involve Investments and Long. Term Asset Items
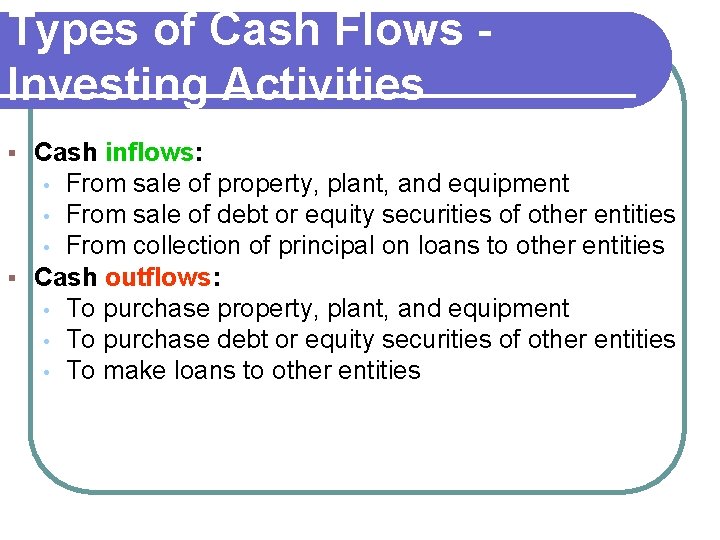
Types of Cash Flows Investing Activities Cash inflows: • From sale of property, plant, and equipment • From sale of debt or equity securities of other entities • From collection of principal on loans to other entities § Cash outflows: • To purchase property, plant, and equipment • To purchase debt or equity securities of other entities • To make loans to other entities §
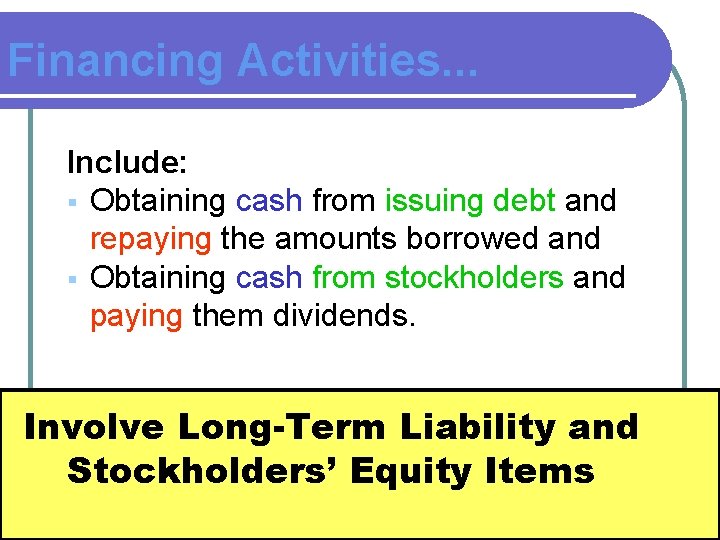
Financing Activities. . . Include: § Obtaining cash from issuing debt and repaying the amounts borrowed and § Obtaining cash from stockholders and paying them dividends. Involve Long-Term Liability and Stockholders’ Equity Items
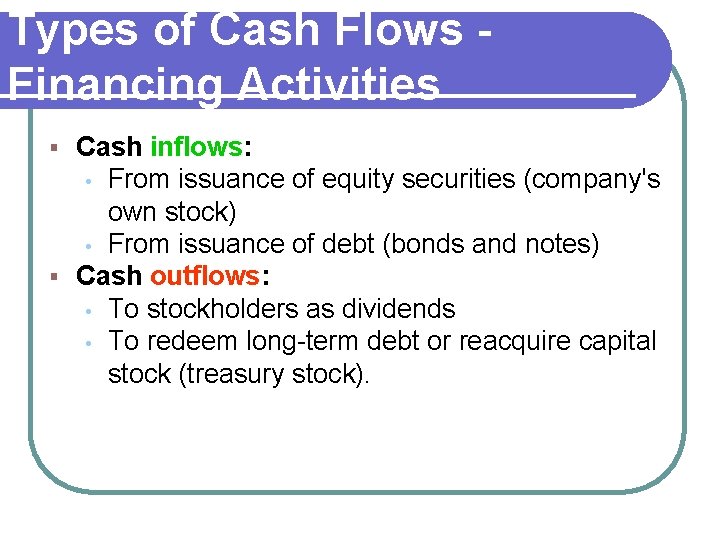
Types of Cash Flows Financing Activities Cash inflows: • From issuance of equity securities (company's own stock) • From issuance of debt (bonds and notes) § Cash outflows: • To stockholders as dividends • To redeem long-term debt or reacquire capital stock (treasury stock). §
Significant Noncash Activities. . . That do not affect cash are NOT reported in the body of the statement of cash flows. § Are reported: • Separately--bottom of CF statement or • Separately--note to the financial statements. §
Significant Noncash Activities. . . 1. Issuance of common stock to purchase assets. 2. Conversion of bonds into common stock. 3. Issuance of debt to purchase assets. 4. Exchanges of plant assets. For IFRS, non cash items must be reported in notes.
Accrual Basis versus Cash Basis of Accounting Accrual Basis – Recognizes Revenues at the time the earnings process is complete, and expenses at the time they are incurred, regardless of cash flow. Cash Basis– Recognizes Revenues when the Cash is Received, and Expenses at the time the Cash is Paid.
Financial Statements are prepared using the Accrual Basis of Accounting The Statement of Cash Flows – Requires that the Accrual Basis be converted to the Cash Basis of Accounting. This Can be Done either: l Directly – by examining each item on the Income Statement, or l Indirectly – By Adjusting Net Income for the changes in the Non-Cash Balance Sheet Accounts.
Why Report the Causes of Changes in Cash? Because investors, creditors, and other interested parties want to know what is happening to a company’s most liquid asset, CASH
Statement of Cash Flows Helps Users Evaluate 1. Future cash flows? 2. Pay Dividends and meet obligations? 3. Reasons for differences between net income and net cash provided (used) by operating activities 4. What happened in investing and financing?
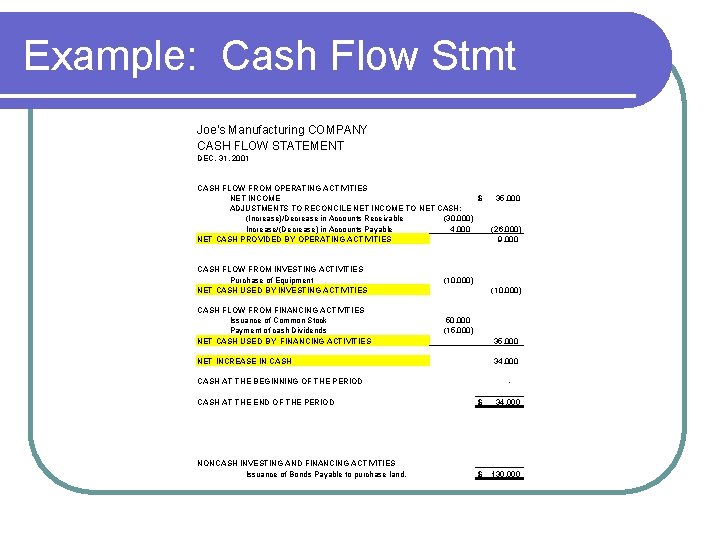
Example: Cash Flow Stmt Joe's Manufacturing COMPANY CASH FLOW STATEMENT DEC. 31, 2001 CASH FLOW FROM OPERATING ACTIVITIES NET INCOME $ 35, 000 ADJUSTMENTS TO RECONCILE NET INCOME TO NET CASH: (Increase)/Decrease in Accounts Receivable (30, 000) Increase/(Decrease) in Accounts Payable 4, 000 (26, 000) NET CASH PROVIDED BY OPERATING ACTIVITIES 9, 000 CASH FLOW FROM INVESTING ACTIVITIES Purchase of Equipment NET CASH USED BY INVESTING ACTIVITIES CASH FLOW FROM FINANCING ACTIVITIES Issuance of Common Stock Payment of cash Dividends NET CASH USED BY FINANCING ACTIVITIES (10, 000) 50, 000 (15, 000) 35, 000 NET INCREASE IN CASH 34, 000 CASH AT THE BEGINNING OF THE PERIOD CASH AT THE END OF THE PERIOD - $ 34, 000 NONCASH INVESTING AND FINANCING ACTIVITIES Issuance of Bonds Payable to purchase land. $ 130, 000
End of Part 1
Chapter 12 – Part 2 The Statement of Cash Flows Use Table of Contents to switch between slides
Preparing the Cash Flow Statement
Preparing the Cash Flow Statement Information required to prepare the Cash Flow Statement: Comparative balance sheet § Current income statement § Additional information §
Small EXAMPLE…. See Course Pack
Statement Of Cash Flows - Indirect Method l The transactions of Joe’s Repair Company for the year ended 2000 are used to illustrate the preparation of a statement of cash flows. l Joe’s Repair Company started in January 1, 2000, when it issued 50, 000 shares of $1 par value common stock for $50, 000 cash. l The company rented its office space and furniture and performed consulting services throughout the first year.
Steps in Preparing Statement of Cash Flows STEP #1 Determine the NET CHANGE in CASH Increase? Decrease? $34, 000 - 0 = $34, 000 INCREASE
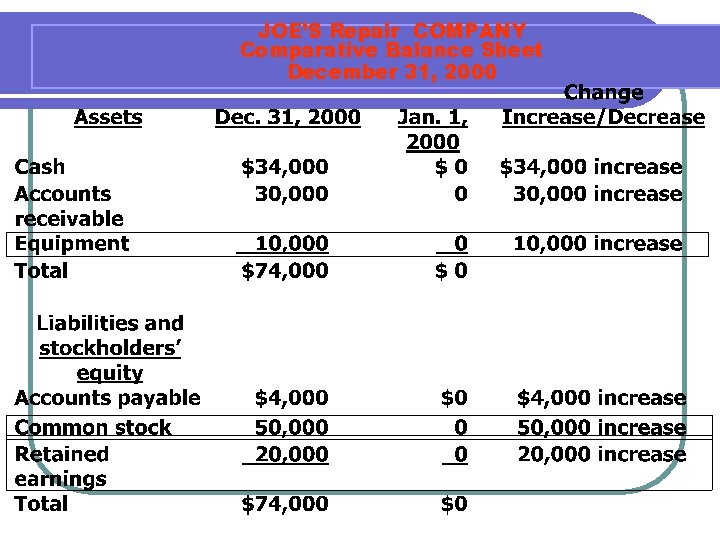
JOE’S Repair COMPANY Comparative Balance Sheet December 31, 2000
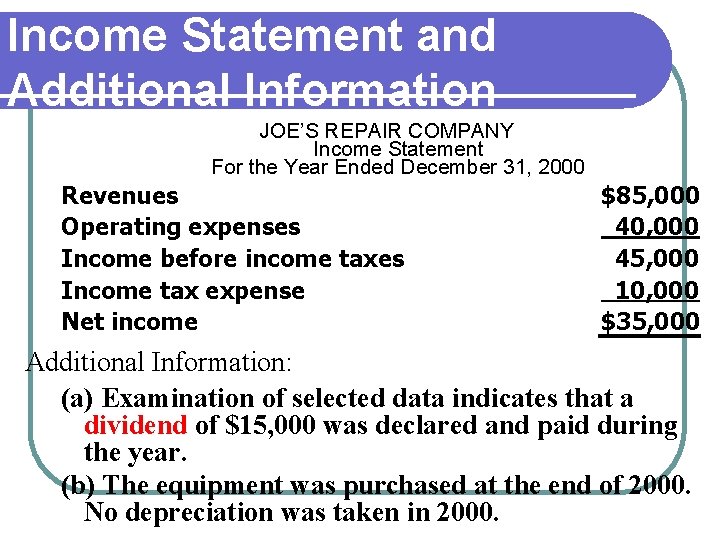
Income Statement and Additional Information JOE’S REPAIR COMPANY Income Statement For the Year Ended December 31, 2000 Revenues Operating expenses Income before income taxes Income tax expense Net income $85, 000 40, 000 45, 000 10, 000 $35, 000 Additional Information: (a) Examination of selected data indicates that a dividend of $15, 000 was declared and paid during the year. (b) The equipment was purchased at the end of 2000. No depreciation was taken in 2000.
Steps in Preparing Statement of Cash Flows STEP #2 Determine the NET CHANGE PROVIDED by Operating Activities You must analyze the Income Statement and some of the Balance Sheet net changes (current assets and liabilities) to convert Net Income (accrual) to a cash basis. (You might need additional information also).
Determine Net Cash Provided/Used By Operating Activities l Adjust net income for items that did not affect cash. l Net income must be converted because earned revenues may include credit sales that have not been collected in cash and expenses incurred that may not have been paid in cash.
Determine Net Cash Provided/Used By Operating Activities Receivables, payables, prepayments, and inventories must be analyzed for their effects on cash.
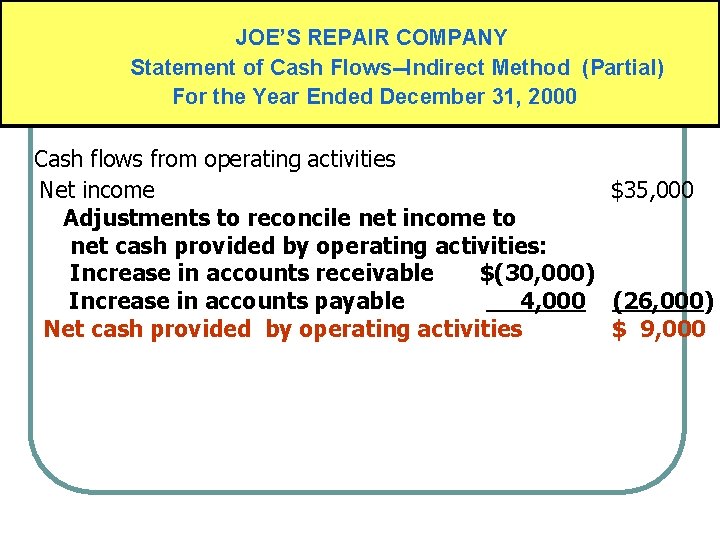
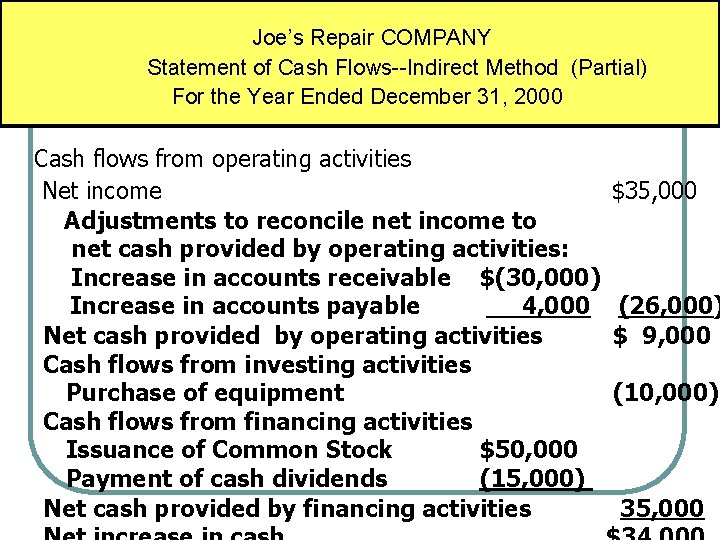
Determine Net Cash Provided/Used By Operating Activities l Joe’s Repair Company (JRC) had revenues of $85, 000 in its first year of operations. l However, JRC collected only $55, 000 in cash. Accrual basis revenue was $85, 000, cash basis revenue would be $55, 000. l The increase in accounts receivable of $30, 000 must be deducted from net income. l (If accounts receivable decrease, the decrease must be added to net income).
Determine Net Cash Provided/Used By Operating Activities (con’t) Accounts payable - When accounts payable increase during a year, operating expenses are higher (accrual) than they are on a cash basis. l For JRC, operating expenses reported in the income statement were $40, 000. l Since Accounts Payable increased $4, 000, $36, 000 ($40, 000 – $4, 000) of the expenses were paid in cash. l So. . an increase in accounts payable must be added to net income, (a decrease subtracted). l
JOE’S REPAIR COMPANY Statement of Cash Flows--Indirect Method (Partial) For the Year Ended December 31, 2000 Cash flows from operating activities Net income $35, 000 Adjustments to reconcile net income to net cash provided by operating activities: Increase in accounts receivable $(30, 000) Increase in accounts payable 4, 000 (26, 000) Net cash provided by operating activities $ 9, 000
Steps in Preparing Statement of Cash Flows STEP #3 Determine the NET CHANGE PROVIDED by Investing and Financing Activities You must analyze the some of the Balance Sheet net changes (long term assets and long term liabilities and equity) to see their effects on cash.
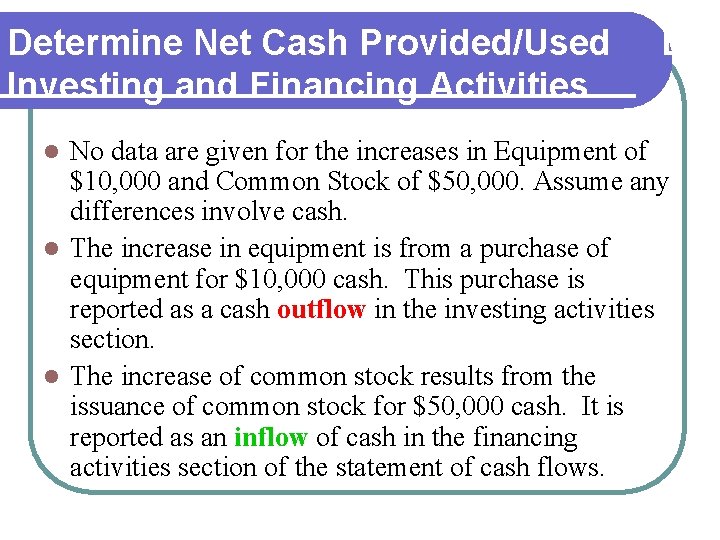
Determine Net Cash Provided/Used By Investing and Financing Activities No data are given for the increases in Equipment of $10, 000 and Common Stock of $50, 000. Assume any differences involve cash. l The increase in equipment is from a purchase of equipment for $10, 000 cash. This purchase is reported as a cash outflow in the investing activities section. l The increase of common stock results from the issuance of common stock for $50, 000 cash. It is reported as an inflow of cash in the financing activities section of the statement of cash flows. l
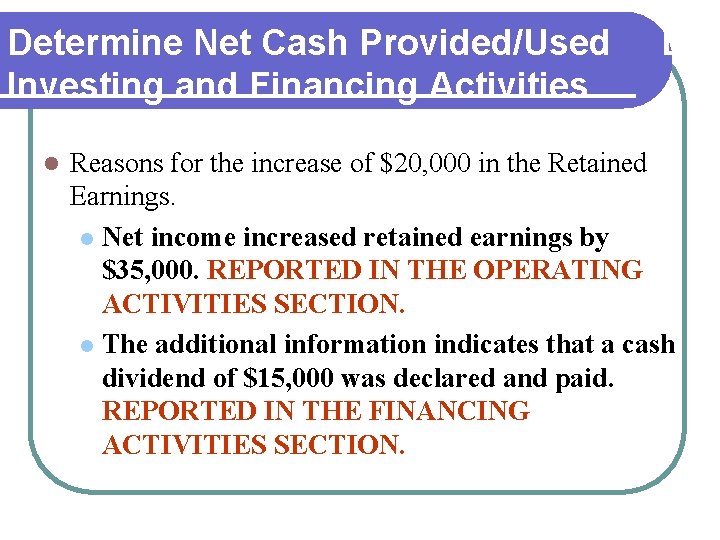
Determine Net Cash Provided/Used By Investing and Financing Activities l Reasons for the increase of $20, 000 in the Retained Earnings. l Net income increased retained earnings by $35, 000. REPORTED IN THE OPERATING ACTIVITIES SECTION. l The additional information indicates that a cash dividend of $15, 000 was declared and paid. REPORTED IN THE FINANCING ACTIVITIES SECTION.
Joe’s Repair COMPANY Statement of Cash Flows--Indirect Method (Partial) For the Year Ended December 31, 2000 Cash flows from operating activities Net income Adjustments to reconcile net income to net cash provided by operating activities: Increase in accounts receivable $(30, 000) Increase in accounts payable 4, 000 Net cash provided by operating activities Cash flows from investing activities Purchase of equipment Cash flows from financing activities Issuance of Common Stock $50, 000 Payment of cash dividends (15, 000) Net cash provided by financing activities $35, 000 (26, 000) $ 9, 000 (10, 000) 35, 000
End of Part 2
Chapter 12 – Part 3 The Statement of Cash Flows Use Table of Contents to switch between slides
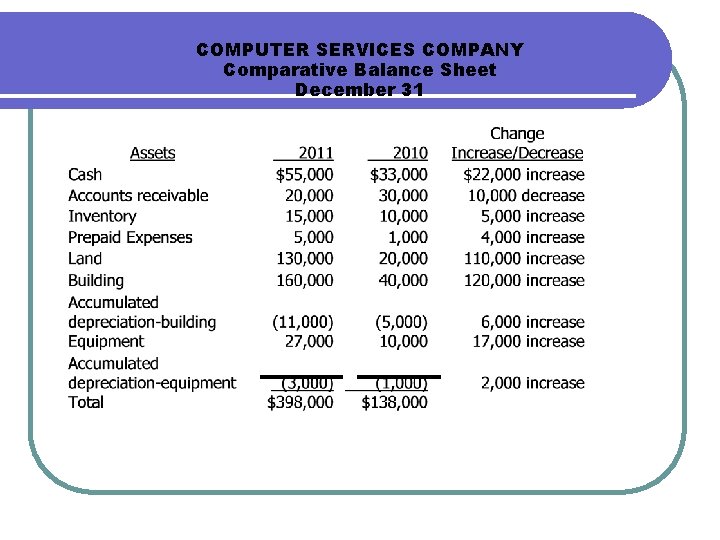
BIGGER EXAMPLE…. Computer Services Company is an established company. Let’s prepare a Statement of Cash Flows for the year ending 2011. This will be more complicated than Joe’s Repair Service.
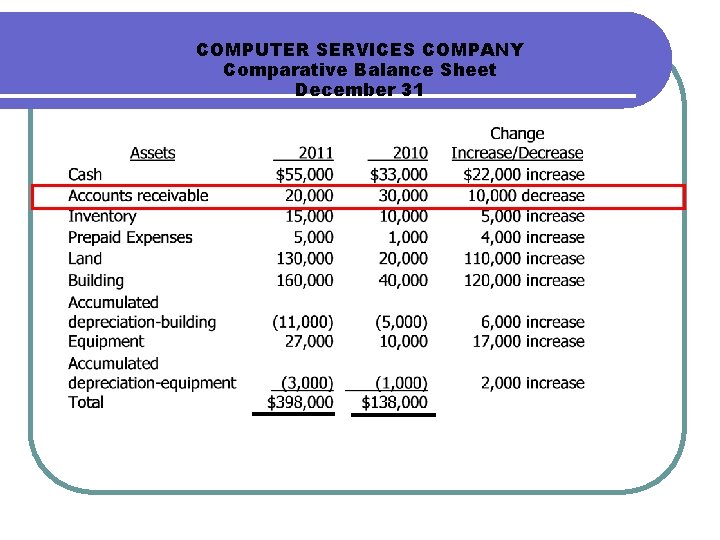
COMPUTER SERVICES COMPANY Comparative Balance Sheet December 31
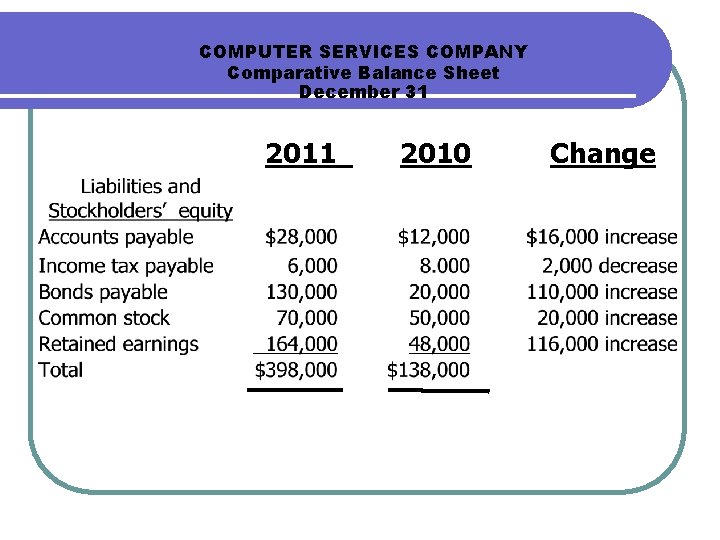
COMPUTER SERVICES COMPANY Comparative Balance Sheet December 31 2010 Change
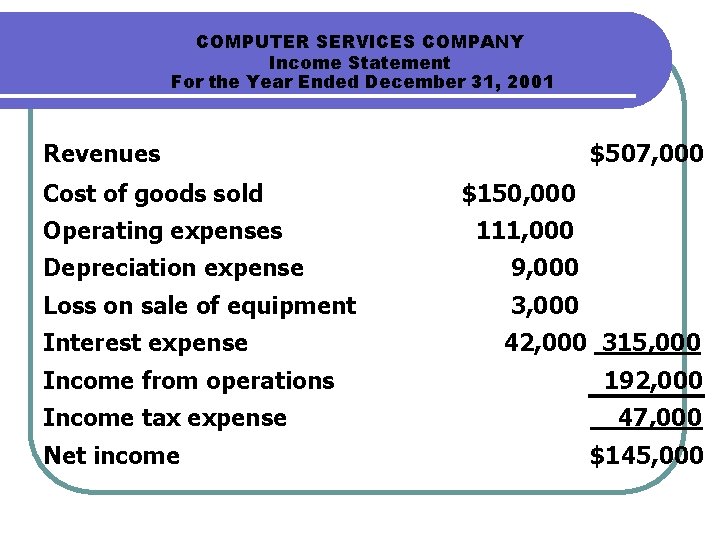
COMPUTER SERVICES COMPANY Income Statement For the Year Ended December 31, 2001 Revenues Cost of goods sold Operating expenses $507, 000 $150, 000 111, 000 Depreciation expense 9, 000 Loss on sale of equipment 3, 000 Interest expense 42, 000 315, 000 Income from operations Income tax expense Net income 192, 000 47, 000 $145, 000
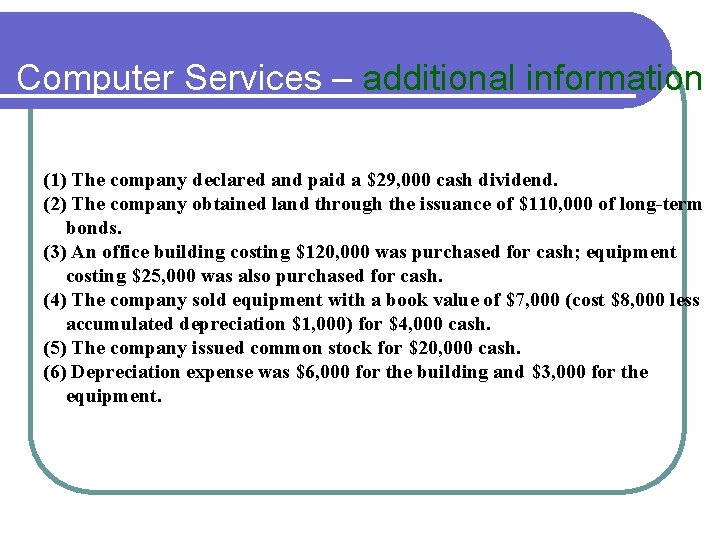
Computer Services – additional information (1) The company declared and paid a $29, 000 cash dividend. (2) The company obtained land through the issuance of $110, 000 of long-term bonds. (3) An office building costing $120, 000 was purchased for cash; equipment costing $25, 000 was also purchased for cash. (4) The company sold equipment with a book value of $7, 000 (cost $8, 000 less accumulated depreciation $1, 000) for $4, 000 cash. (5) The company issued common stock for $20, 000 cash. (6) Depreciation expense was $6, 000 for the building and $3, 000 for the equipment.
Determine the Net Increase or Decrease in Cash STEP #1 Cash increased $22, 000 ($55, 000 -$33, 000)
Determine Net Cash Provided/Used By Operating Activities Adjust net income for items that did not affect cash. For example: l l l Add back non-cash expenses (depreciation, amortization, depletion Deduct Gains Add back Losses Changes in Current assets Changes in Current liabilities
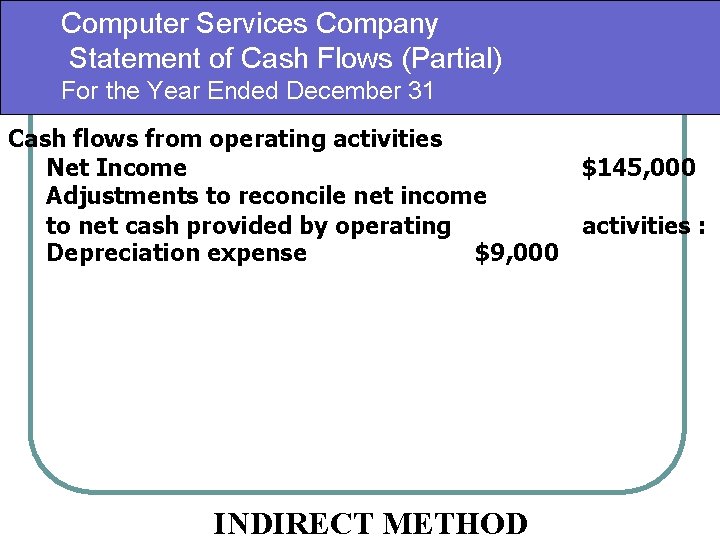
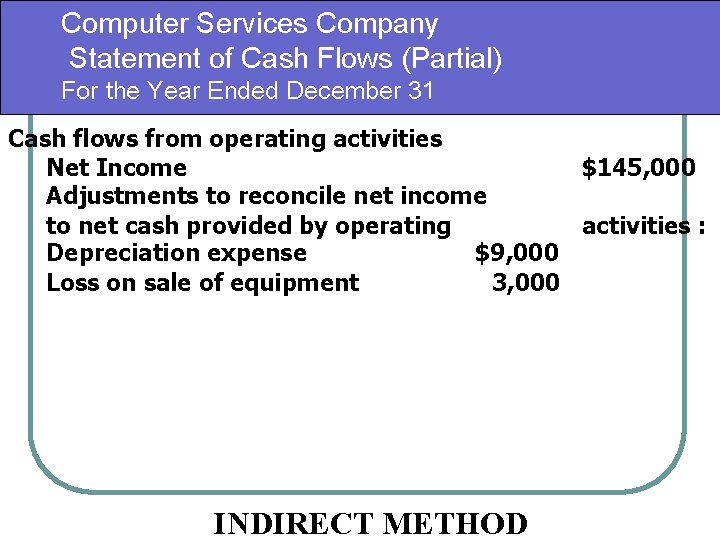
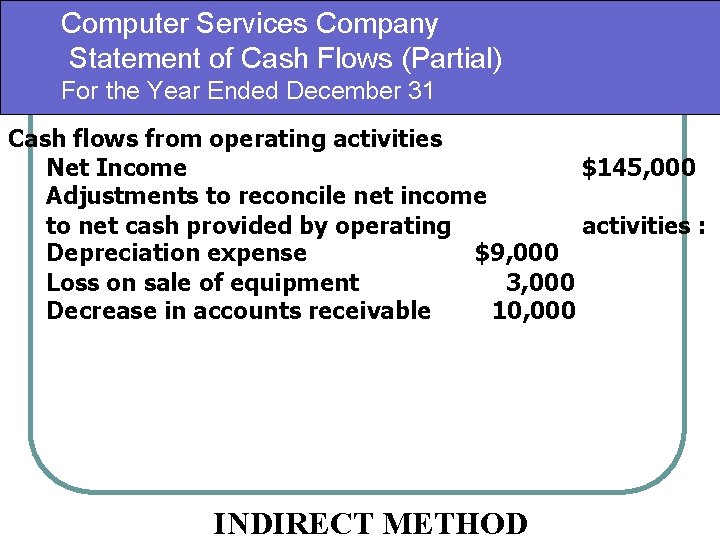
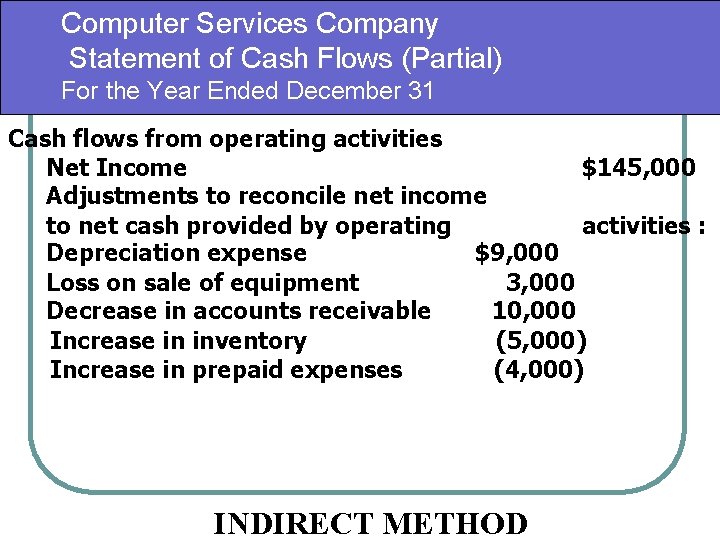
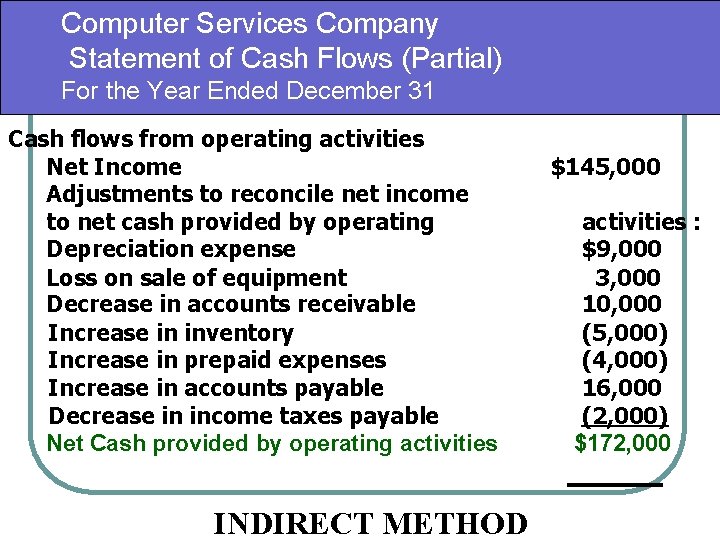
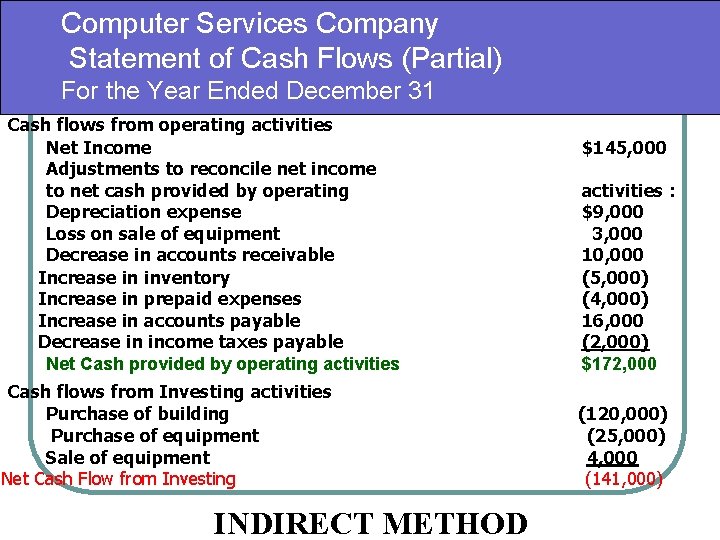
Determine Net Cash Provided/Used By Operating Activities l Depreciation expense – The company reported depreciation expense of $9, 000. l Depreciation and other charges that do not require the use of cash, such as amortization of intangible assets are added to net income.
Computer Services Company Statement of Cash Flows (Partial) For the Year Ended December 31 Cash flows from operating activities Net Income $145, 000 Adjustments to reconcile net income to net cash provided by operating activities : Depreciation expense $9, 000 INDIRECT METHOD
Determine Net Cash Provided/Used By Operating Activities Loss on Sale of Equipment – The company reported a $3, 000 loss on the sale of equipment (book value $7, 000 less cash proceeds $4, 000). l The loss reduced net income but did not reduce cash. l The $3, 000 loss is added to net income in determining net cash provided by operating activities. l
Computer Services Company Statement of Cash Flows (Partial) For the Year Ended December 31 Cash flows from operating activities Net Income $145, 000 Adjustments to reconcile net income to net cash provided by operating activities : Depreciation expense $9, 000 Loss on sale of equipment 3, 000 INDIRECT METHOD
Determine Net Cash Provided/Used By Operating Activities STEP #2 Current Assets l Accounts Receivable - Accounts receivable decreases during the period because cash receipts are higher than revenues reported on an accrual basis. The decrease of $10, 000 must be added to net income, as a cash inflow. Why? You collected the cash!
COMPUTER SERVICES COMPANY Comparative Balance Sheet December 31
Computer Services Company Statement of Cash Flows (Partial) For the Year Ended December 31 Cash flows from operating activities Net Income $145, 000 Adjustments to reconcile net income to net cash provided by operating activities : Depreciation expense $9, 000 Loss on sale of equipment 3, 000 Decrease in accounts receivable 10, 000 INDIRECT METHOD
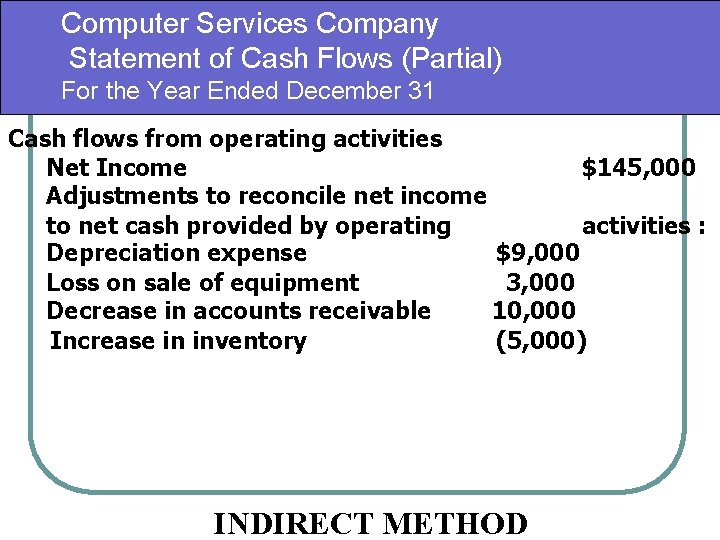
Determine Net Cash Provided/Used By Operating Activities l Inventory- Inventory increases during a period when merchandise purchases exceed the cost of goods sold. Or, you spent cash on inventory that you haven’t “expensed” yet through cost of goods sold. The increase of $5, 000 in inventory must be deducted from net income as it is a cash outflow.
Computer Services Company Statement of Cash Flows (Partial) For the Year Ended December 31 Cash flows from operating activities Net Income $145, 000 Adjustments to reconcile net income to net cash provided by operating activities : Depreciation expense $9, 000 Loss on sale of equipment 3, 000 Decrease in accounts receivable 10, 000 Increase in inventory (5, 000) INDIRECT METHOD
Determine Net Cash Provided/Used By Operating Activities l Prepaid Expenses - Prepaid expenses increase during a period because cash paid for expenses is greater than expenses reported on an accrual basis. l The increase of $4, 000 in prepaid expenses must be deducted from net income.
Computer Services Company Statement of Cash Flows (Partial) For the Year Ended December 31 Cash flows from operating activities Net Income $145, 000 Adjustments to reconcile net income to net cash provided by operating activities : Depreciation expense $9, 000 Loss on sale of equipment 3, 000 Decrease in accounts receivable 10, 000 Increase in inventory (5, 000) Increase in prepaid expenses (4, 000) INDIRECT METHOD
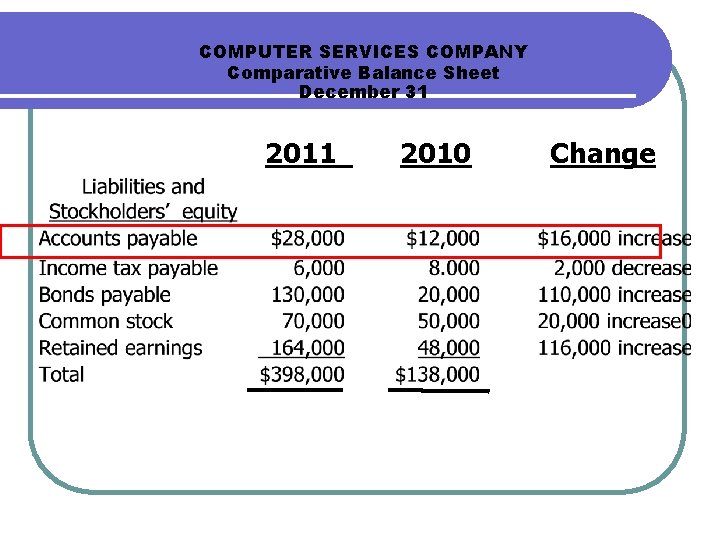
Determine Net Cash Provided/Used By Operating Activities l Accounts Payable - The increase of $16, 000 in accounts payable must be added to net income. Why? This means the company received more inventory (and other items) than it actually paid for). Cash inflow
COMPUTER SERVICES COMPANY Comparative Balance Sheet December 31 2010 Change
Determine Net Cash Provided/Used By Operating Activities l Income Taxes Payable – The decrease of $2, 000 in accounts payable must be subtracted from net income. Why? This means the company owed money, but then paid some of it – Cash outflow
Computer Services Company Statement of Cash Flows (Partial) For the Year Ended December 31 Cash flows from operating activities Net Income $145, 000 Adjustments to reconcile net income to net cash provided by operating activities : Depreciation expense $9, 000 Loss on sale of equipment 3, 000 Decrease in accounts receivable 10, 000 Increase in inventory (5, 000) Increase in prepaid expenses (4, 000) Increase in accounts payable 16, 000 Decrease in income taxes payable (2, 000) Net Cash provided by operating activities $172, 000 INDIRECT METHOD
Determine Net Cash Provided/Used By Investing Activities STEP #3 l Study the balance sheet to determine changes in noncurrent assets. l Changes in each noncurrent account are analyzed using selected transaction data to determine the effect, if any, the changes had on cash.
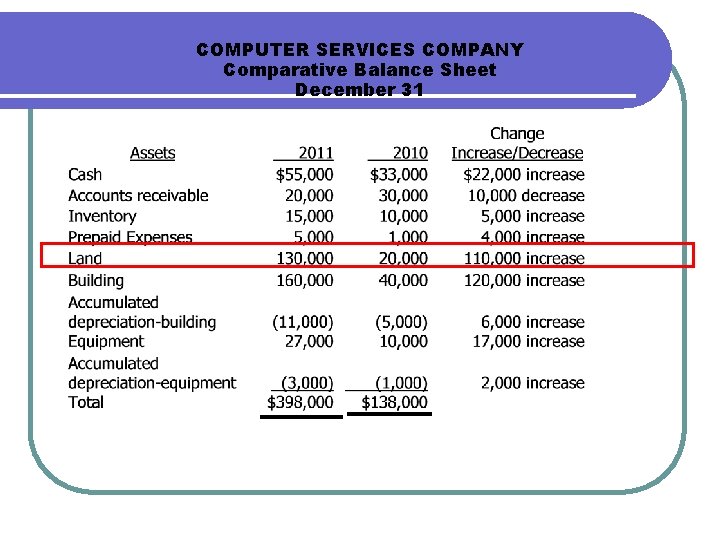
Determine Net Cash Provided/Used By Investing Activities l Land - Land of $110, 000 was purchased through the issuance of long-term bonds. l Although the exchange of bonds payable for land has no effect on cash, it is a significant noncash investing and financing activity that must be disclosed.
COMPUTER SERVICES COMPANY Comparative Balance Sheet December 31
Determine Net Cash Provided/Used By Investing Activities l Building - An office building was acquired using cash of $120, 000. l This transaction is a cash outflow reported in the investing activities section.
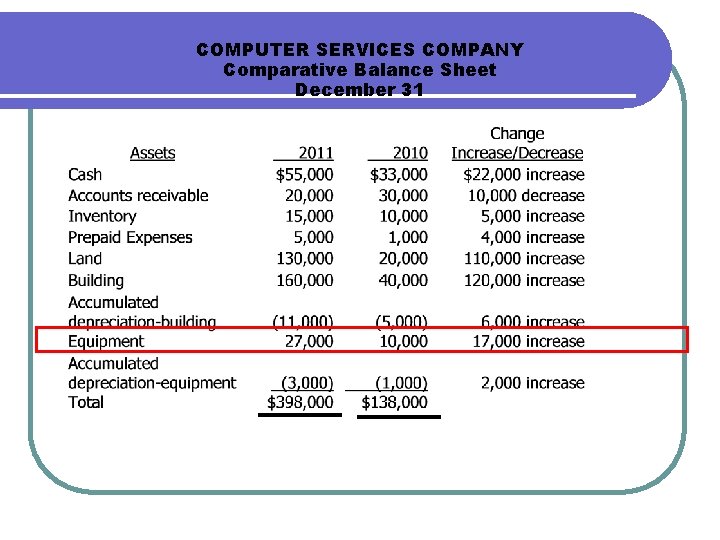
Determine Net Cash Provided/Used By Investing Activities l Equipment - The equipment account increased $17, 000. l The additional information provided, reveals that this was a net increase resulting from two transactions l (1) a purchase of equipment for $25, 000 l (2) sale of equipment costing $8, 000 for $4, 000. l The purchase of equipment should be shown as a $25, 000 outflow of cash and the sale of equipment should be shown as a cash inflow of $4, 000.
COMPUTER SERVICES COMPANY Comparative Balance Sheet December 31
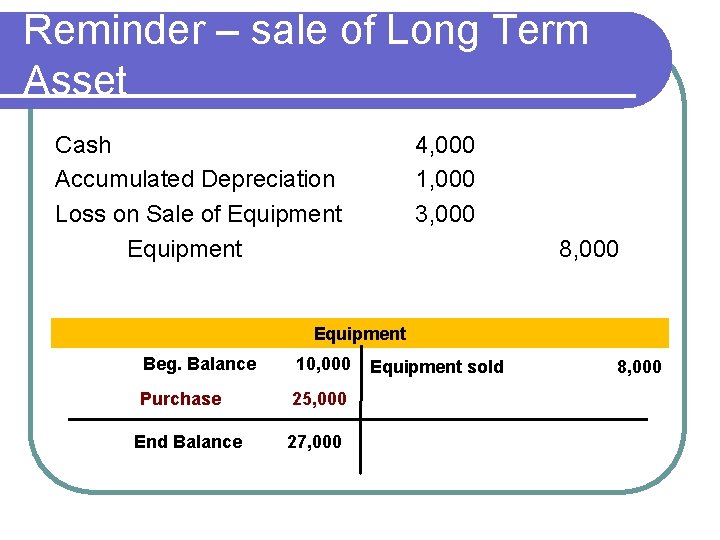
Reminder – sale of Long Term Asset Cash Accumulated Depreciation Loss on Sale of Equipment 4, 000 1, 000 3, 000 8, 000 Equipment Beg. Balance 10, 000 Purchase 25, 000 End Balance 27, 000 Equipment sold 8, 000
Computer Services Company Statement of Cash Flows (Partial) For the Year Ended December 31 Cash flows from operating activities Net Income Adjustments to reconcile net income to net cash provided by operating Depreciation expense Loss on sale of equipment Decrease in accounts receivable Increase in inventory Increase in prepaid expenses Increase in accounts payable Decrease in income taxes payable Net Cash provided by operating activities Cash flows from Investing activities Purchase of building Purchase of equipment Sale of equipment Net Cash Flow from Investing INDIRECT METHOD $145, 000 activities : $9, 000 3, 000 10, 000 (5, 000) (4, 000) 16, 000 (2, 000) $172, 000 (120, 000) (25, 000) 4, 000 (141, 000)
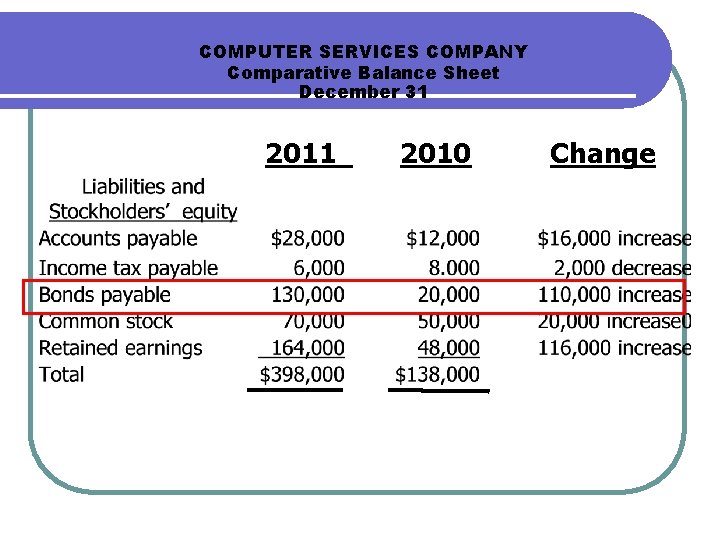
Determine Net Cash Provided/Used By Financing Activities l Bonds Payable - The bonds payable account increased by $110, 000. The issuance of bonds for land is a noncash transaction reported in a separate schedule at the bottom of the statement of cash flows.
COMPUTER SERVICES COMPANY Comparative Balance Sheet December 31 2010 Change
Determine Net Cash Provided/Used By Financing Activities l Common Stock- increased by $20, 000. The additional information notes that this was for cash.
Determine Net Cash Provided/Used By Financing Activities Retained Earnings - Retained Earnings increased by $116, 000. l The increase is a net of l (1) Net income of $145, 000 that increased Retained Earnings and l (2) dividends of $29, 000 that decreased Retained earnings. l Net income is converted to net cash provided by operations. l Payment of the dividend is a cash outflow that is reported as a financing activity. l
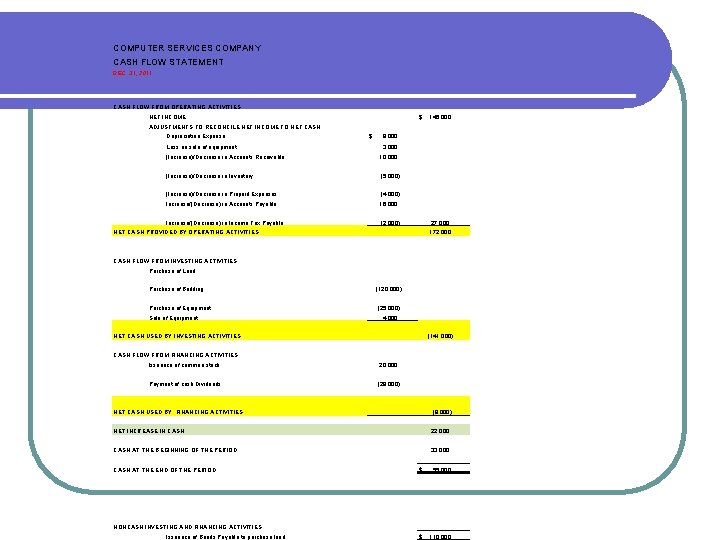
COMPUTER SERVICES COMPANY CASH FLOW STATEMENT DEC. 31, 2011 CASH FLOW FROM OPERATING ACTIVITIES NET INCOME $ 145, 000 ADJUSTMENTS TO RECONCILE NET INCOME TO NET CASH: Depreciation Expense $ 9, 000 Loss on sale of equipment 3, 000 (Increase)/Decrease in Accounts Receivable 10, 000 (Increase)/Decrease in Inventory (5, 000) (Increase)/Decrease in Prepaid Expenses (4, 000) Increase/(Decrease) in Accounts Payable 16, 000 Increase/(Decrease) in Income Tax Payable (2, 000) 27, 000 172, 000 NET CASH PROVIDED BY OPERATING ACTIVITIES CASH FLOW FROM INVESTING ACTIVITIES Purchase of Land Purchase of Building (120, 000) Purchase of Equipment (25, 000) Sale of Equipment 4, 000 NET CASH USED BY INVESTING ACTIVITIES (141, 000) CASH FLOW FROM FINANCING ACTIVITIES Issuance of common stock 20, 000 Payment of cash Dividends (29, 000) NET CASH USED BY FINANCING ACTIVITIES (9, 000) NET INCREASE IN CASH 22, 000 CASH AT THE BEGINNING OF THE PERIOD 33, 000 CASH AT THE END OF THE PERIOD $ 55, 000 NONCASH INVESTING AND FINANCING ACTIVITIES Issuance of Bonds Payable to purchase land. $ 110, 000
End of Part 3
Chapter 12 – Part 4 The Statement of Cash Flows Use Table of Contents to switch between slides
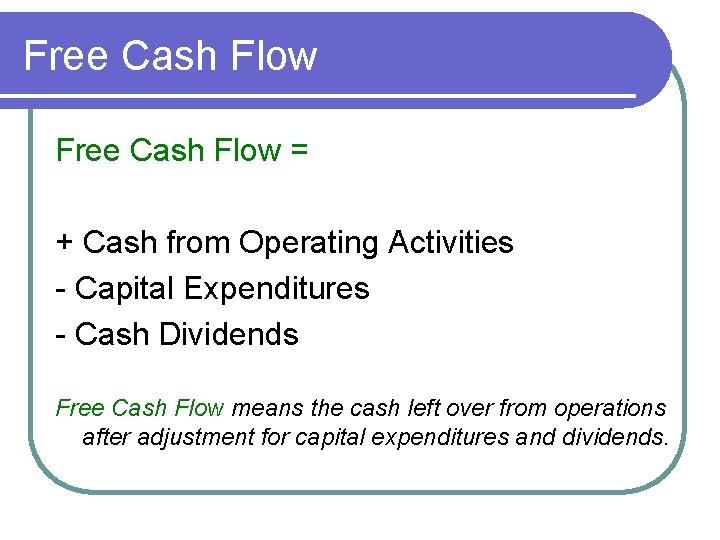
Free Cash Flow = + Cash from Operating Activities - Capital Expenditures - Cash Dividends Free Cash Flow means the cash left over from operations after adjustment for capital expenditures and dividends.
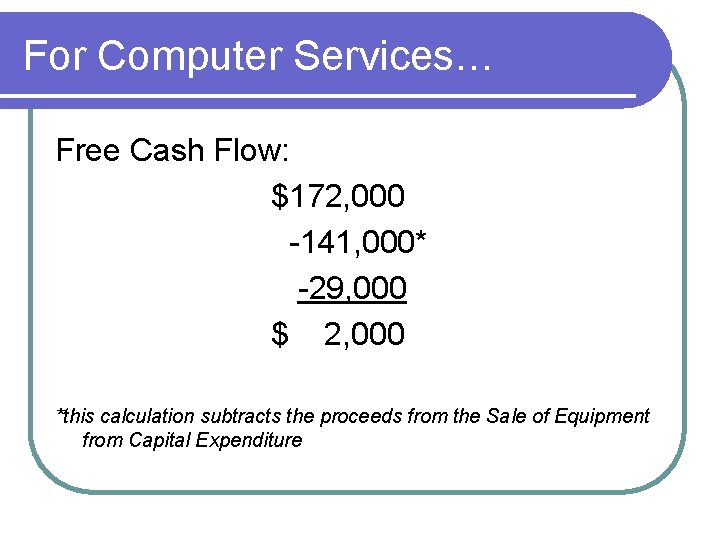
For Computer Services… Free Cash Flow: $172, 000 -141, 000* -29, 000 $ 2, 000 *this calculation subtracts the proceeds from the Sale of Equipment from Capital Expenditure
Supplementary Material l Cash Flow and the Product Life Cycle
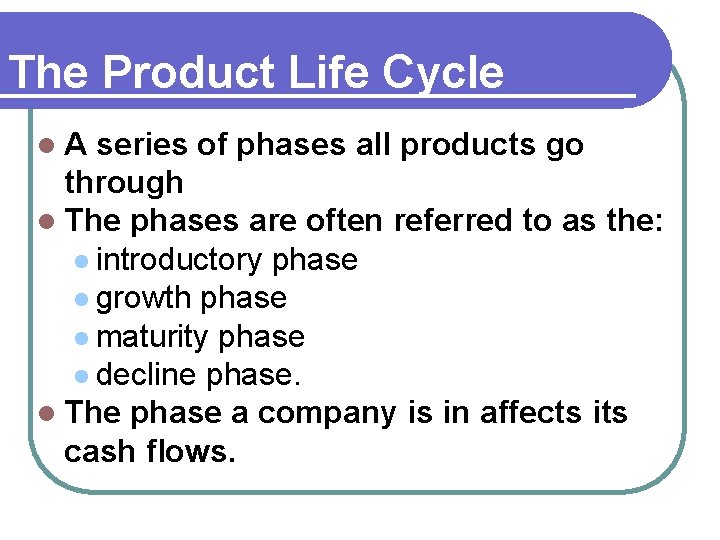
The Product Life Cycle l A series of phases all products go through l The phases are often referred to as the: l introductory phase l growth phase l maturity phase l decline phase. l The phase a company is in affects its cash flows.
Introductory Phase To support asset purchases the company may issue stock or debt. Expect: í cash from operations to be negative í cash from investing to be negative. í cash from financing to be positive.
Growth Phase The company is striving to expand its production and sales. Expect: í small amounts of cash to be generated from operations. í cash from investing to be negative. í cash from financing to be positive
Maturity Phase Sales and production level-off Expect: í cash from operations to exceed investing needs í cash from investing to be neutral í cash from financing to be negative
Decline Phase Sales and production decline Expect: í cash from operations to decline í cash from investing to possibly become positive í cash from financing to possibly become negative
Be prepared to…. l Review a Cash Flow Statement l Discuss WHERE a company appears to be in the Product Life Cycle, based on evidence in its Cash Flow Statement
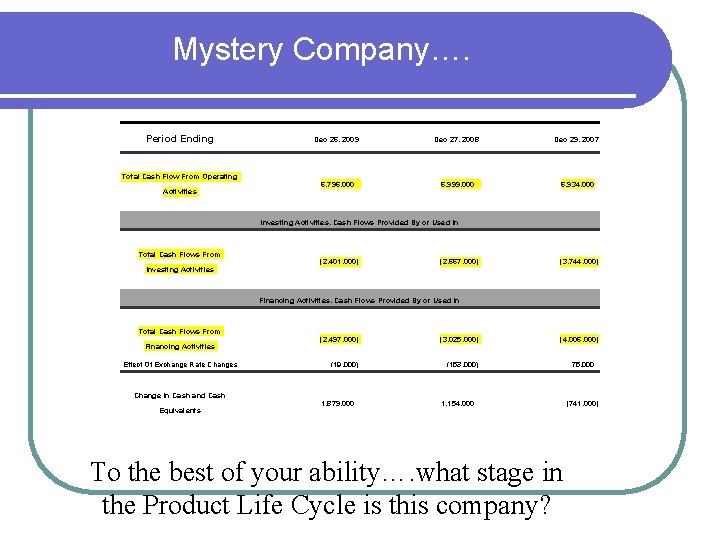
Mystery Company…. Period Ending Total Cash Flow From Operating Activities Dec 26, 2009 Dec 27, 2008 Dec 29, 2007 6, 796, 000 6, 999, 000 6, 934, 000 Investing Activities, Cash Flows Provided By or Used In Total Cash Flows From Investing Activities (2, 401, 000) (2, 667, 000) (3, 744, 000) Financing Activities, Cash Flows Provided By or Used In Total Cash Flows From Financing Activities Effect Of Exchange Rate Changes Change In Cash and Cash Equivalents (2, 497, 000) (3, 025, 000) (4, 006, 000) (19, 000) (153, 000) 75, 000 1, 879, 000 1, 154, 000 (741, 000) To the best of your ability…. what stage in the Product Life Cycle is this company?
Possible answer Cash from Operations is positive l Cash from Investing is negative l This is strong evidence the company is growing, investing in new stores, manufacturing plants, new equipment or buildings That cash from financing is negative is confusing, however, it could mean that this is an established company that is paying back creditors and also paying dividends, but still expanding. And its strong positive cash flow from operations is a sign of growth and overall financial strength
And the company is…. .
End of Chapter 13 Good Bye and Good Luck.