MEASUREMENT AND PRESENTATION OF INCOME A DAC 202



- Slides: 69
MEASUREMENT AND PRESENTATION OF INCOME A DAC 202: ACCOUNTING FOR EQUITIES PRESENTATION 2012
Objectives of Presentation AFTER END OF PRESENTATION YOU SHOULD: 1. Understand the uses and limitations of an income statement. 2. Prepare a single-step income statement. 3. Prepare a multiple-step income statement. 4. Explain how to report irregular items. 5. Explain intra-period tax allocation. 6. Identify where & how to report earnings per share information. 7. Prepare a retained earnings statement. 8. Explain how to report other comprehensive income.
Statement of Income and Related Information Statement of Income Usefulness Limitations Quality of Earnings Format of the Statement of Income Elements Single-step Multiple-step Condensed income statements Reporting Irregular Items Special Reporting Issues Discontinued operations Exceptional items Unusual gains and losses Changes in accounting principles Changes in estimates Changes in Entity Corrections of errors Intraperiod tax allocation Earnings per share Retained earnings statement Comprehensive income
Statement of Income- Overview Usefulness Evaluate past performance. Predicting future performance. Help assess the risk or uncertainty of achieving future cash flows.
Statement of Income- Overview cont… Limitations Companies omit items that cannot be measured reliably. Income is affected by the accounting methods employed. Income measurement involves judgment.
Statement of Income- Overview cont… Quality of Earnings Companies have incentives to manage income to meet or beat capital market expectations, so that market price of stock increases and value of stock options increase. Quality of earnings is reduced if earnings management results in information that is less useful for predicting future earnings and cash flows.
Statement of Income- Overview cont… Elements of the Statement of Income Revenues – Inflows or other enhancements of assets or settlements of its liabilities that constitute the entity’s ongoing major or central operations. Examples of Revenue Accounts Sales Fee revenue Interest revenue Dividend revenue Rent revenue
Statement of Income- Overview cont… Elements of the Statement of Income Expenses – Outflows or other using-up of assets or incurrence of liabilities that constitute the entity’s ongoing major or central operations. Examples of Expense Accounts Cost of goods sold Depreciation expense Interest expense Rent expense Salary expense
Statement of Income- Overview cont. . Elements of the Income Statement Gains – Increases in equity (net assets) from peripheral or incidental transactions. Losses - Decreases in equity (net assets) from peripheral or incidental transactions. Gains and losses can result from sale of investments or plant assets, settlement of liabilities, write-offs of assets.
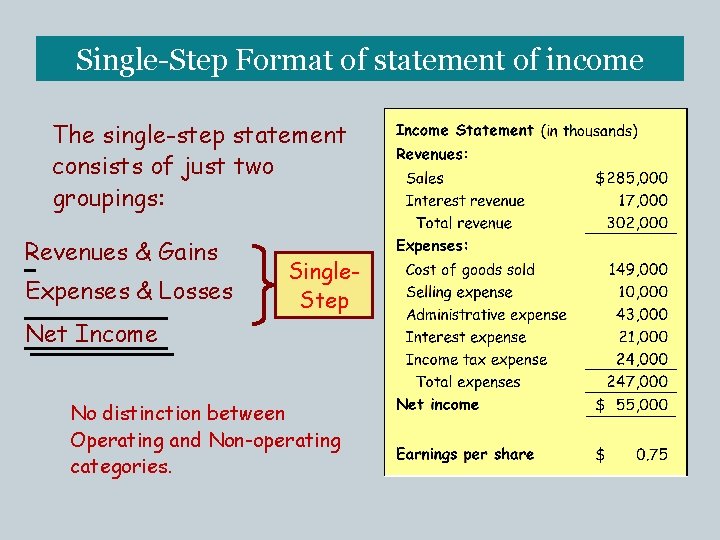
Single-Step Format of statement of income The single-step statement consists of just two groupings: Revenues & Gains Expenses & Losses Single. Step Net Income No distinction between Operating and Non-operating categories.
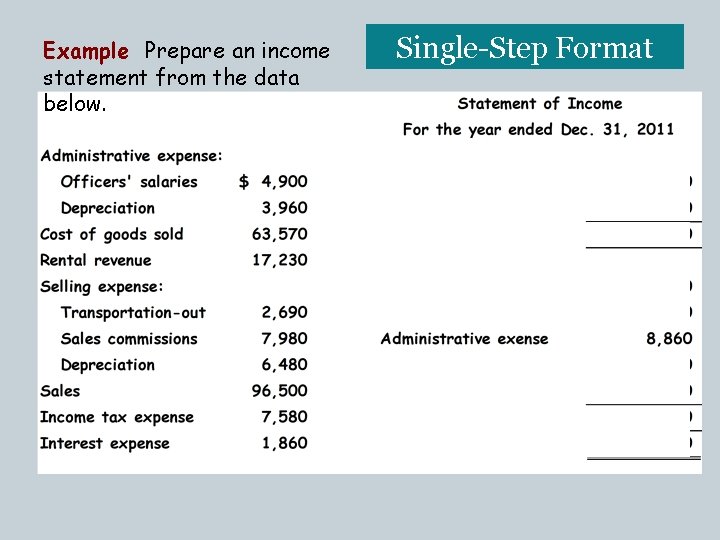
Example Prepare an income statement from the data below. Single-Step Format
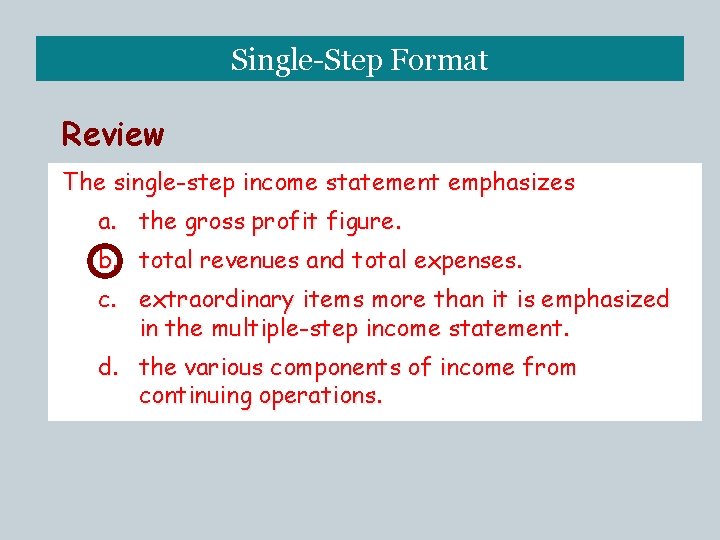
Single-Step Format Review The single-step income statement emphasizes a. the gross profit figure. b. total revenues and total expenses. c. extraordinary items more than it is emphasized in the multiple-step income statement. d. the various components of income from continuing operations.
Multiple-Step Format Background Separates operating transactions from nonoperating transactions. Matches costs and expenses with related revenues. Highlights certain intermediate components of income that analysts use.
Multiple-Step Format Statement of Income Sections 1. Operating section 2. Non-operating section 3. Income tax 4. Discontinued operations 5. Exceptional items 6. Earnings per share
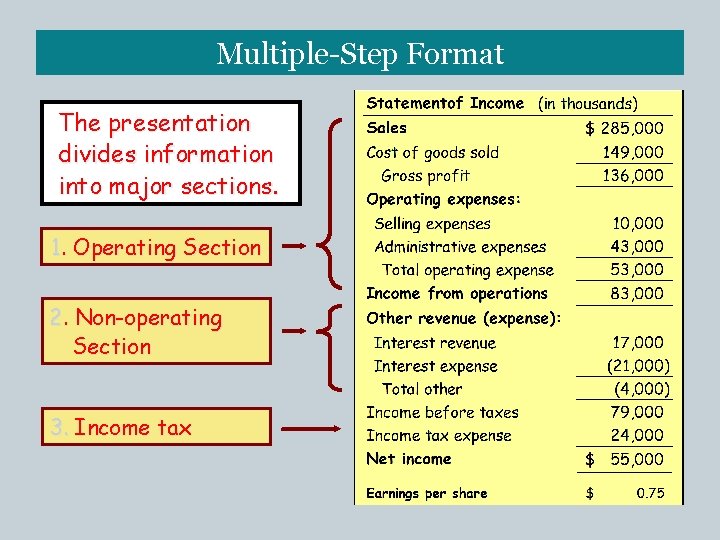
Multiple-Step Format The presentation divides information into major sections. 1. Operating Section 2. Non-operating Section 3. Income tax
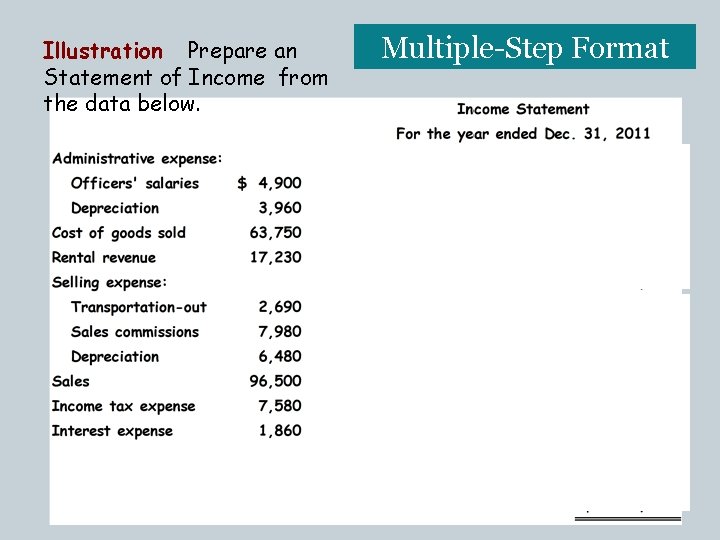
Illustration Prepare an Statement of Income from the data below. Multiple-Step Format
Reporting Irregular Items Irregular items fall into seven categories 1. Discontinued operations. 2. Exceptional items. 3. Unusual gains and losses. 4. Changes in accounting principle. 5. Changes in estimates. 6. Changes in the reporting entity 7. Corrections of Prior period errors (Done in the Retained Earnings Statement).
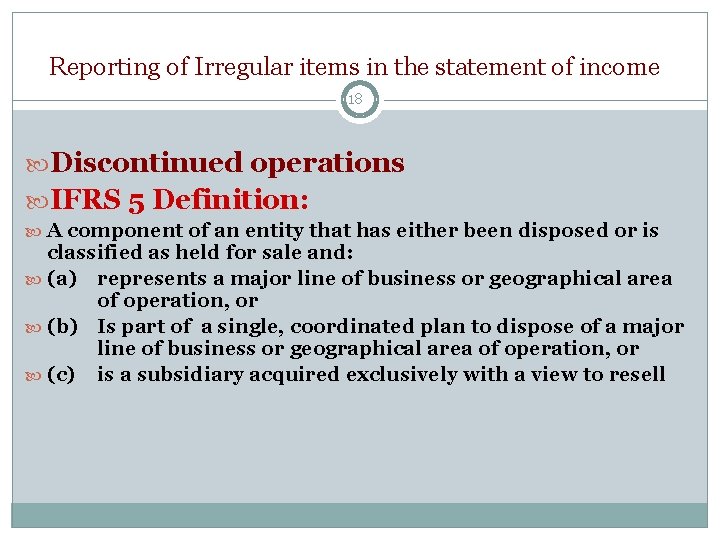
Reporting of Irregular items in the statement of income 18 Discontinued operations IFRS 5 Definition: A component of an entity that has either been disposed or is classified as held for sale and: (a) represents a major line of business or geographical area of operation, or (b) Is part of a single, coordinated plan to dispose of a major line of business or geographical area of operation, or (c) is a subsidiary acquired exclusively with a view to resell
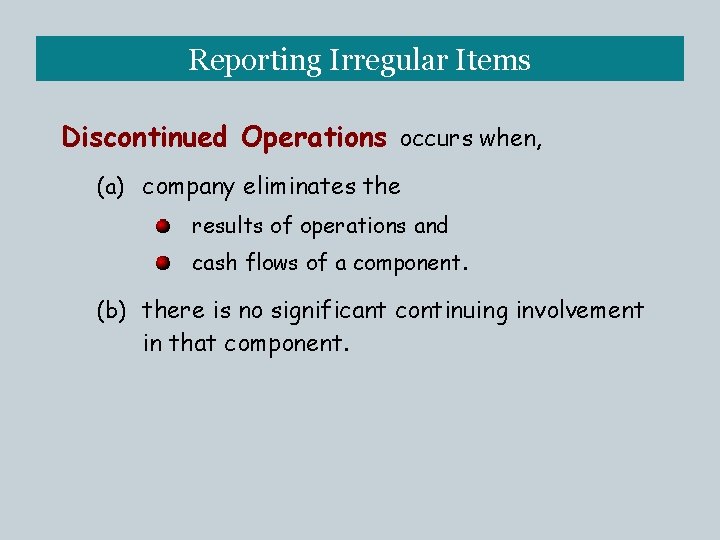
Reporting Irregular Items Discontinued Operations occurs when, (a) company eliminates the results of operations and cash flows of a component. (b) there is no significant continuing involvement in that component.
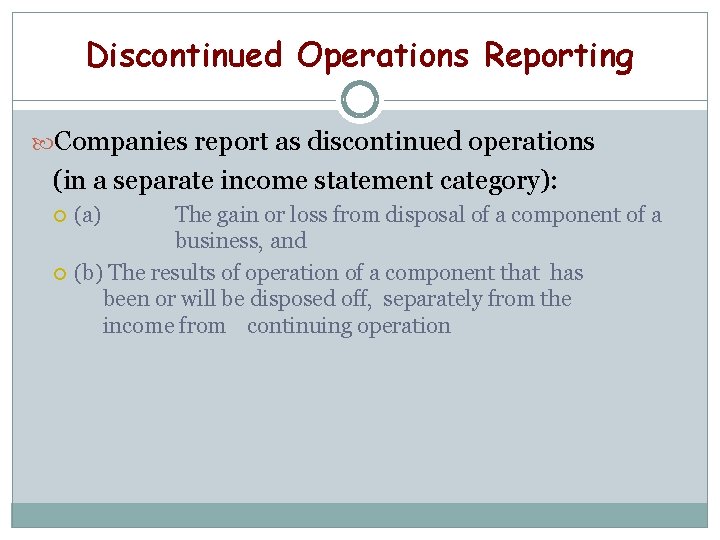
Discontinued Operations Reporting Companies report as discontinued operations (in a separate income statement category): (a) The gain or loss from disposal of a component of a business, and (b) The results of operation of a component that has been or will be disposed off, separately from the income from continuing operation
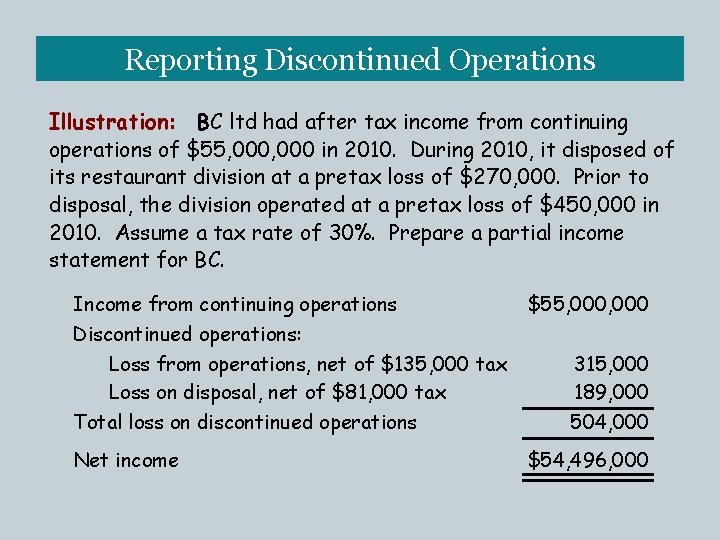
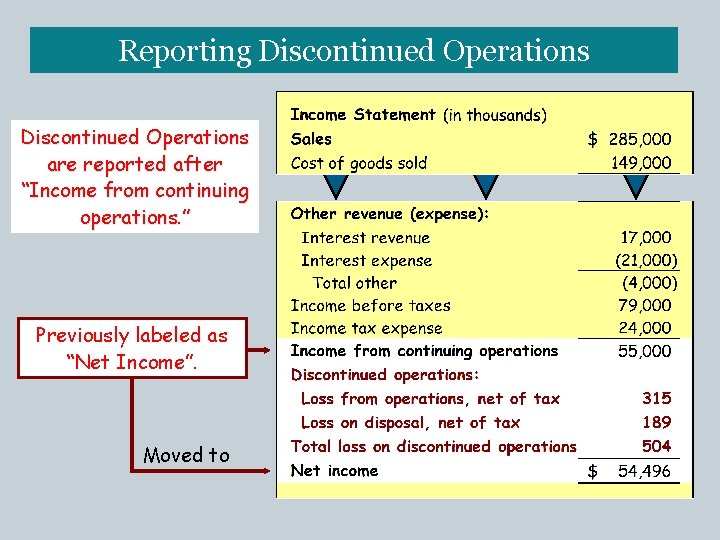
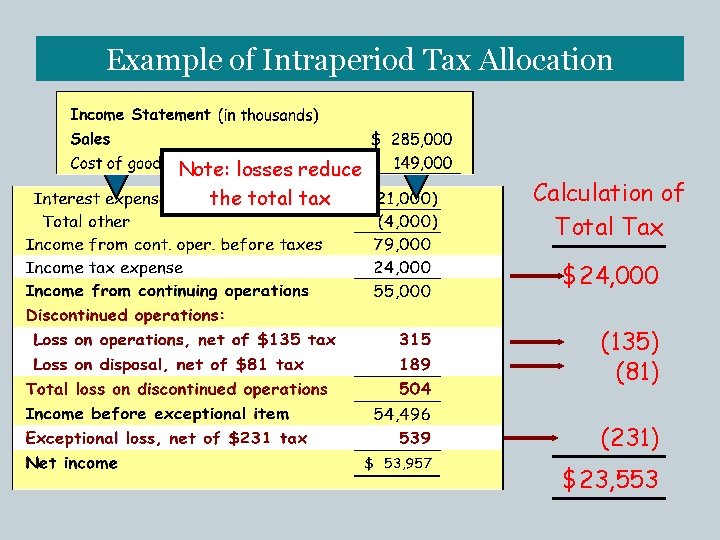
Reporting Discontinued Operations Illustration: BC ltd had after tax income from continuing operations of $55, 000 in 2010. During 2010, it disposed of its restaurant division at a pretax loss of $270, 000. Prior to disposal, the division operated at a pretax loss of $450, 000 in 2010. Assume a tax rate of 30%. Prepare a partial income statement for BC. Income from continuing operations $55, 000 Discontinued operations: Loss from operations, net of $135, 000 tax 315, 000 Loss on disposal, net of $81, 000 tax 189, 000 Total loss on discontinued operations 504, 000 Net income $54, 496, 000
Reporting Discontinued Operations are reported after “Income from continuing operations. ” Previously labeled as “Net Income”. Moved to
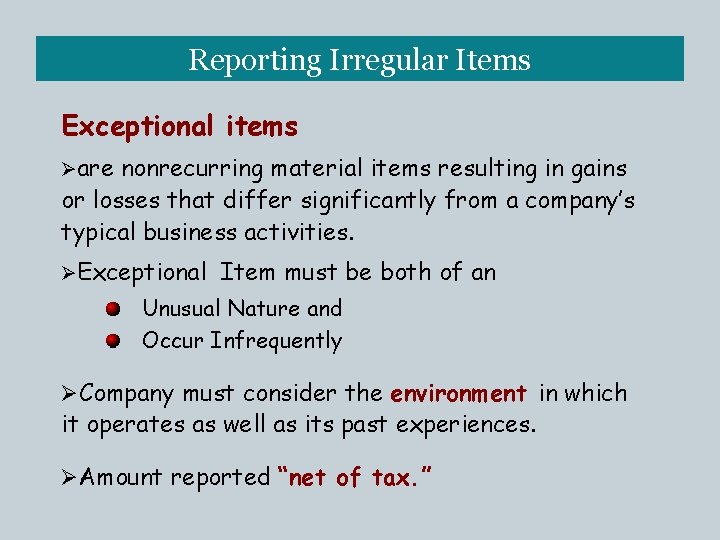
Reporting Irregular Items Exceptional items Øare nonrecurring material items resulting in gains or losses that differ significantly from a company’s typical business activities. ØExceptional Item must be both of an Unusual Nature and Occur Infrequently ØCompany must consider the environment in which it operates as well as its past experiences. ØAmount reported “net of tax. ”
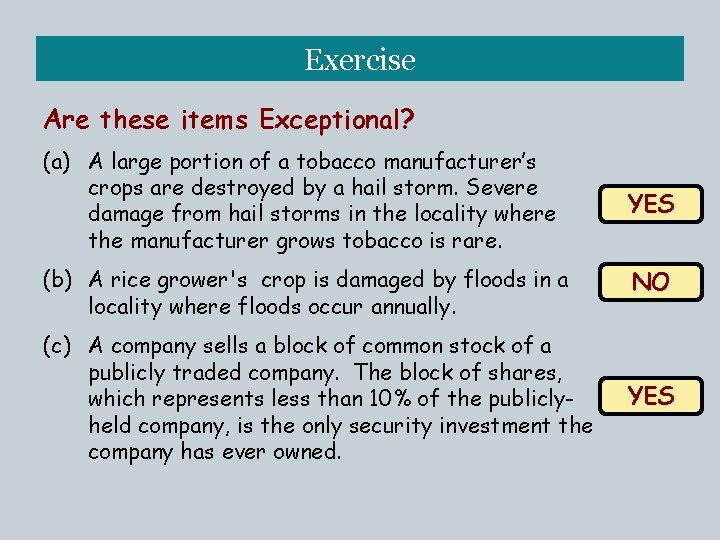
Exercise Are these items Exceptional? (a) A large portion of a tobacco manufacturer’s crops are destroyed by a hail storm. Severe damage from hail storms in the locality where the manufacturer grows tobacco is rare. (b) A rice grower's crop is damaged by floods in a locality where floods occur annually. (c) A company sells a block of common stock of a publicly traded company. The block of shares, which represents less than 10% of the publiclyheld company, is the only security investment the company has ever owned. YES NO YES
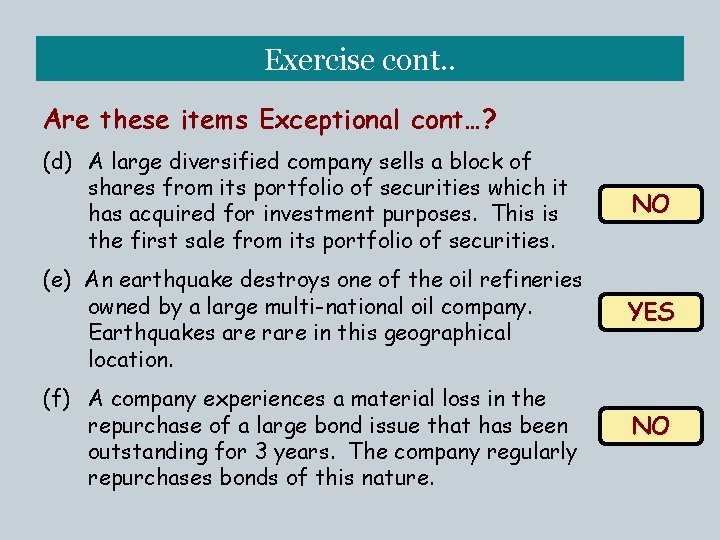
Exercise cont. . Are these items Exceptional cont…? (d) A large diversified company sells a block of shares from its portfolio of securities which it has acquired for investment purposes. This is the first sale from its portfolio of securities. NO (e) An earthquake destroys one of the oil refineries owned by a large multi-national oil company. Earthquakes are rare in this geographical location. YES (f) A company experiences a material loss in the repurchase of a large bond issue that has been outstanding for 3 years. The company regularly repurchases bonds of this nature. NO
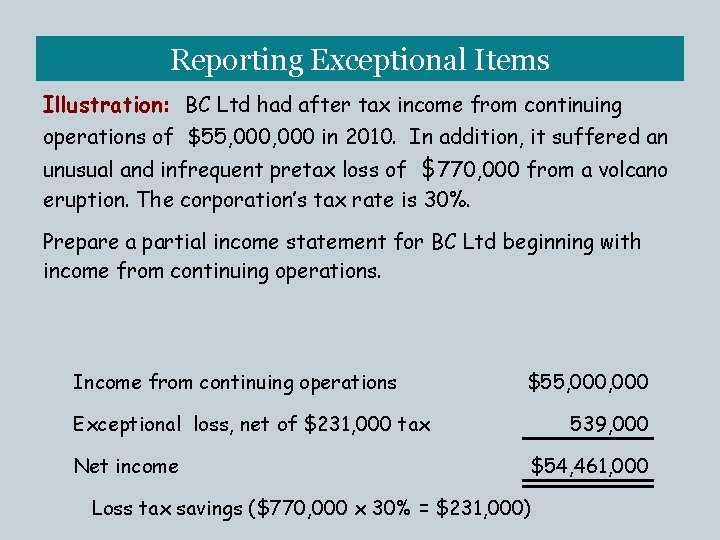
Reporting Exceptional Items Illustration: BC Ltd had after tax income from continuing operations of $55, 000 in 2010. In addition, it suffered an unusual and infrequent pretax loss of $770, 000 from a volcano eruption. The corporation’s tax rate is 30%. Prepare a partial income statement for BC Ltd beginning with income from continuing operations. Income from continuing operations $55, 000 Exceptional loss, net of $231, 000 tax Net income 539, 000 $54, 461, 000 Loss tax savings ($770, 000 x 30% = $231, 000)
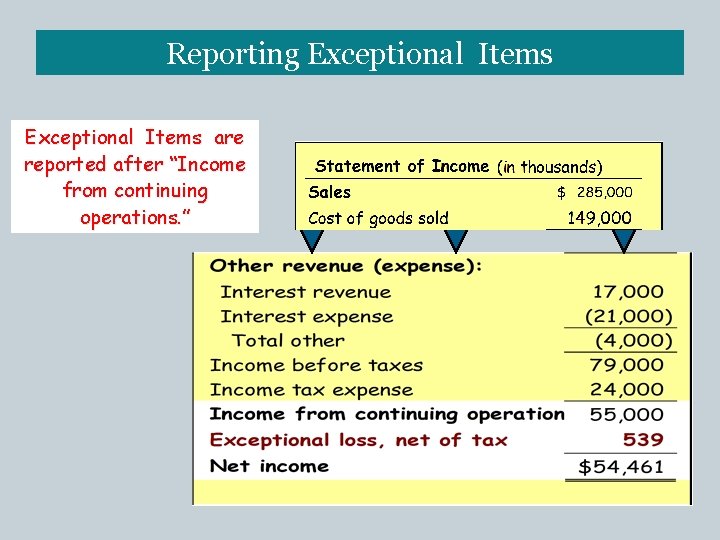
Reporting Exceptional Items are reported after “Income from continuing operations. ”
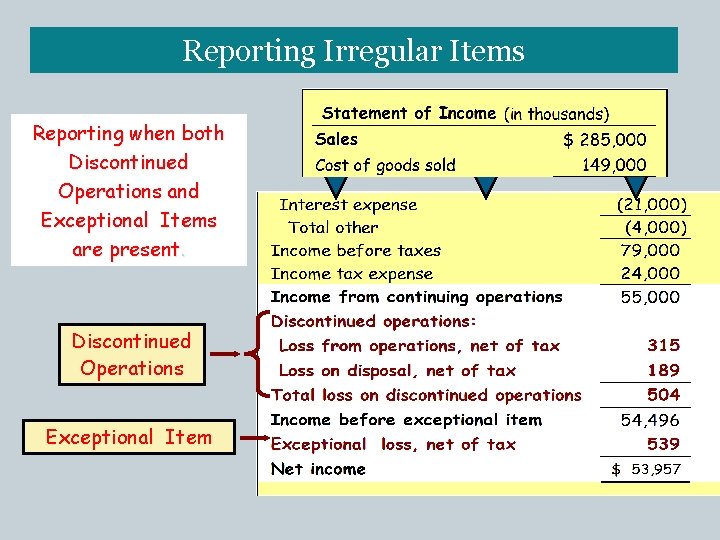
Reporting Irregular Items Reporting when both Discontinued Operations and Exceptional Items are present. Discontinued Operations Exceptional Item
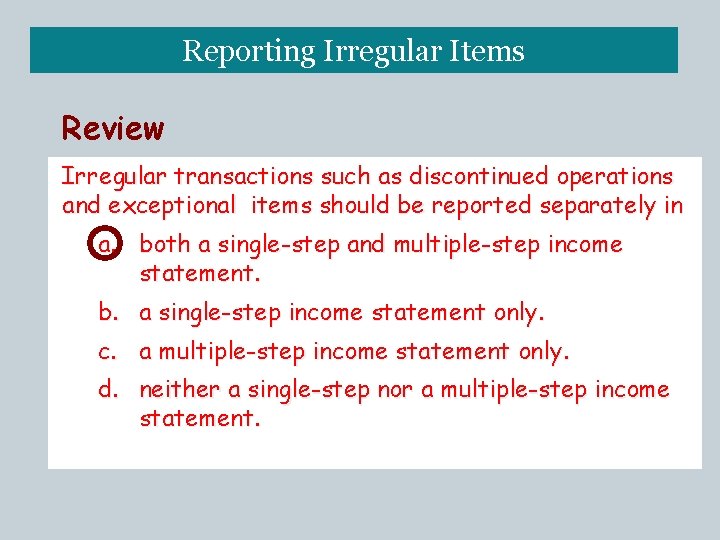
Reporting Irregular Items Review Irregular transactions such as discontinued operations and exceptional items should be reported separately in a. both a single-step and multiple-step income statement. b. a single-step income statement only. c. a multiple-step income statement only. d. neither a single-step nor a multiple-step income statement.
Reporting Irregular Items Unusual Gains and Losses Material items that are unusual or infrequent, but not both, should be reported in a separate section just above “Income from continuing operations before income taxes. ” Examples can include: Write-downs of inventories Foreign exchange transaction gains and losses The IFRS’s prohibits net-of-tax treatment for these items.
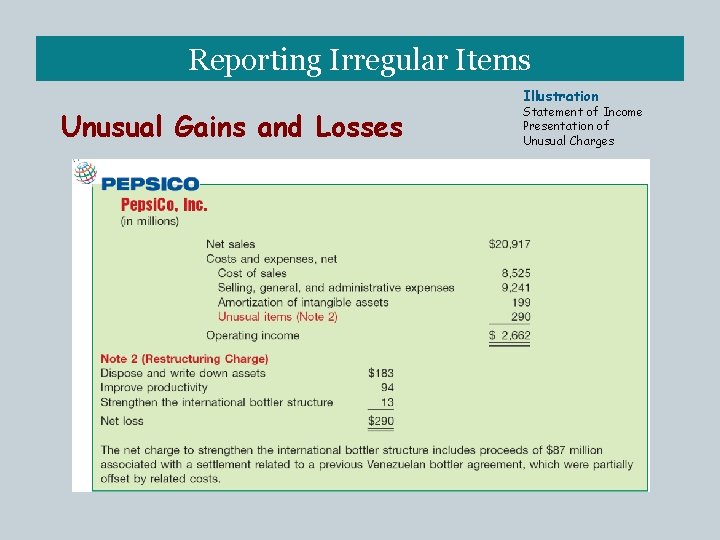
Reporting Irregular Items Unusual Gains and Losses Illustration Statement of Income Presentation of Unusual Charges
Changes in Accounting They frequently occur in practice because important events or conditions may be in dispute or uncertain as at the financial statement date. Examples of accounting changes include: Change in Accounting Principles Changes in Estimates Changes in the Reporting Entity
Changes in Accounting Principle • This refers to change from one acceptable accounting method to another. • . Examples include: Ø change from FIFO to average cost Ø change from the percentage-of-completion to the completed-contract method Ø Change from the straight line to sum of years’ digit of depreciation
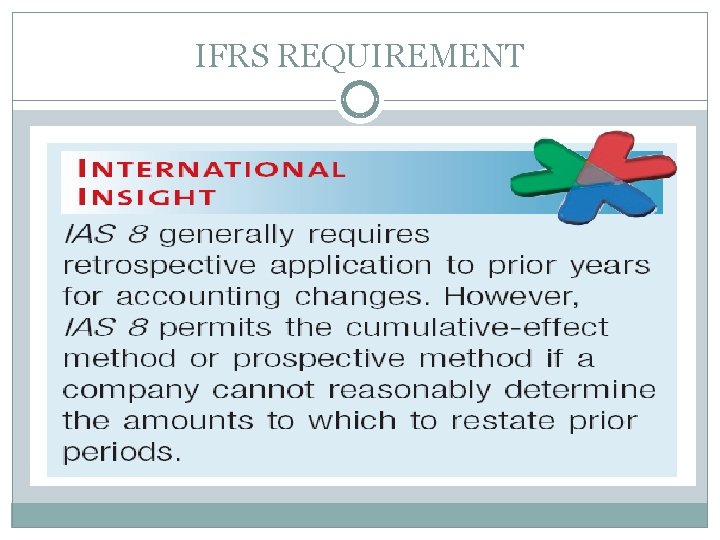
IFRS REQUIREMENT
Accounting for Changes in Accounting Principle A company recognizes a change in accounting principle by making a retrospective adjustment to the financial statements. Such adjustment recasts the financial statements on a basis consistent with the newly adopted principle The company may also adjusts the cumulative effect of the change for prior years as an adjustment to the beginning retained earnings of the earliest period presented.
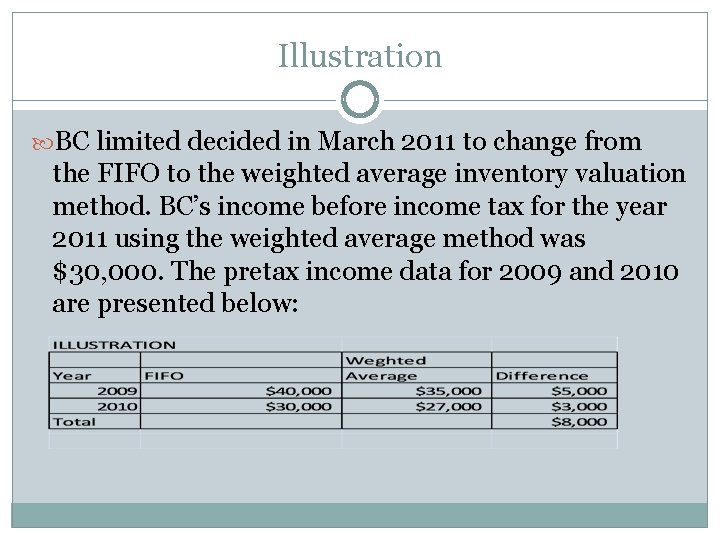
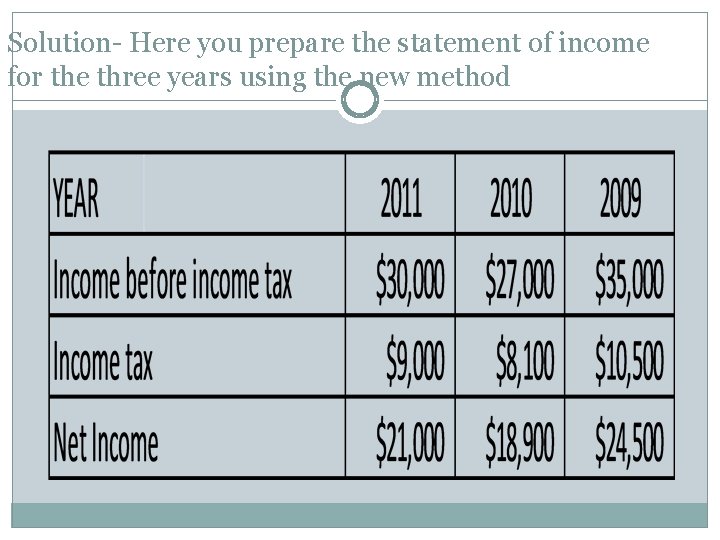
Illustration BC limited decided in March 2011 to change from the FIFO to the weighted average inventory valuation method. BC’s income before income tax for the year 2011 using the weighted average method was $30, 000. The pretax income data for 2009 and 2010 are presented below:
Illustration cont… Required: Assuming the corporate tax rate is 30 percent, show the comparative statements of income for the three years to reflect the effect of change in accounting principle.
Solution- Here you prepare the statement of income for the three years using the new method
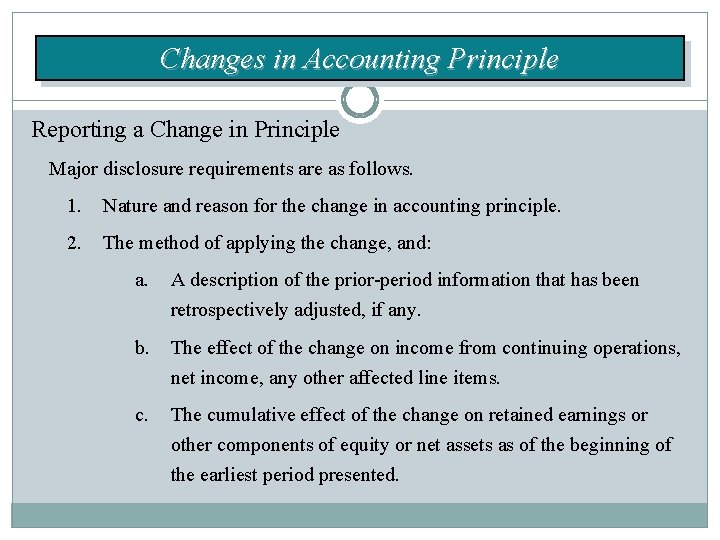
Changes in Accounting Principle Reporting a Change in Principle Major disclosure requirements are as follows. 1. Nature and reason for the change in accounting principle. 2. The method of applying the change, and: a. A description of the prior-period information that has been retrospectively adjusted, if any. b. The effect of the change on income from continuing operations, net income, any other affected line items. c. The cumulative effect of the change on retained earnings or other components of equity or net assets as of the beginning of the earliest period presented.
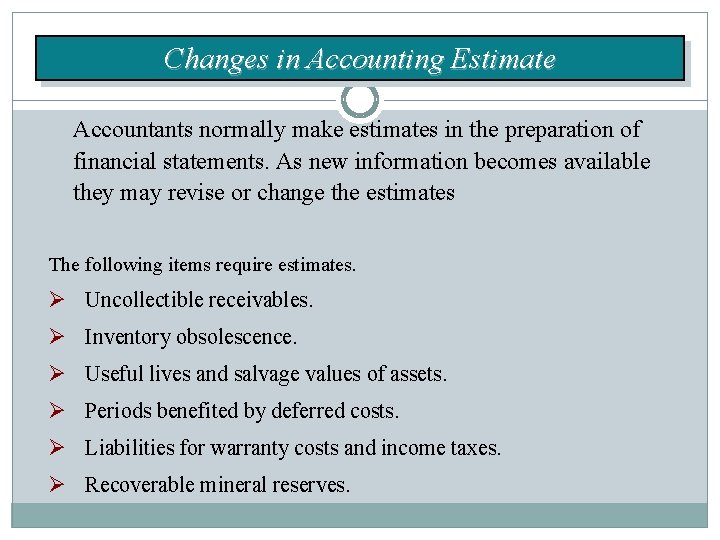
Changes in Accounting Estimate Accountants normally make estimates in the preparation of financial statements. As new information becomes available they may revise or change the estimates The following items require estimates. Ø Uncollectible receivables. Ø Inventory obsolescence. Ø Useful lives and salvage values of assets. Ø Periods benefited by deferred costs. Ø Liabilities for warranty costs and income taxes. Ø Recoverable mineral reserves.
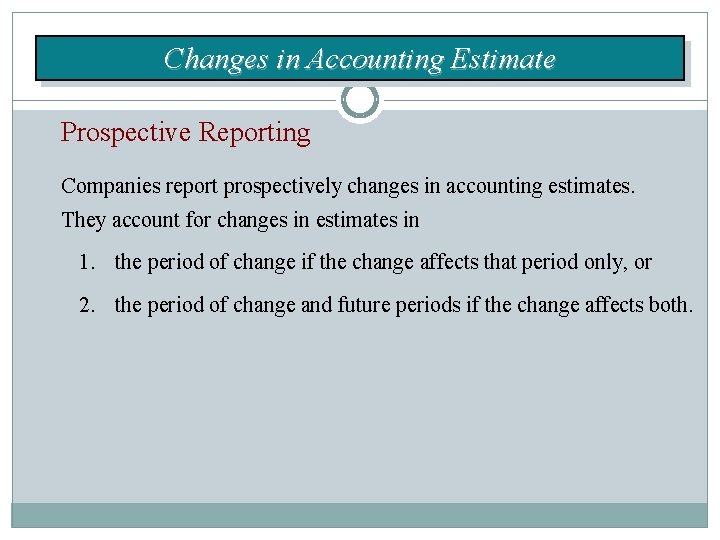
Changes in Accounting Estimate Prospective Reporting Companies report prospectively changes in accounting estimates. They account for changes in estimates in 1. the period of change if the change affects that period only, or 2. the period of change and future periods if the change affects both.
Reporting Irregular Items Accounting for Changes in Estimate Accounted for in the period of change and future periods Not handled retrospectively Not considered errors or exceptional items Examples include: Ø Useful lives and salvage values of depreciable assets Ø Allowance for uncollectible receivables Ø Inventory obsolescence
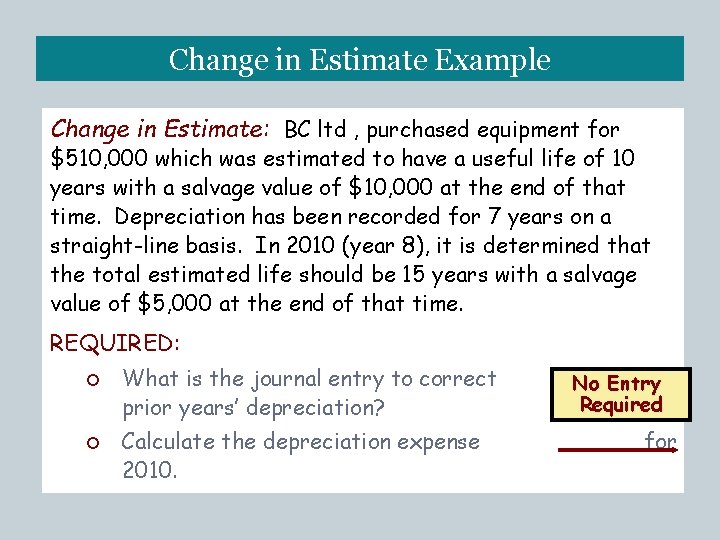
Change in Estimate Example Change in Estimate: BC ltd , purchased equipment for $510, 000 which was estimated to have a useful life of 10 years with a salvage value of $10, 000 at the end of that time. Depreciation has been recorded for 7 years on a straight-line basis. In 2010 (year 8), it is determined that the total estimated life should be 15 years with a salvage value of $5, 000 at the end of that time. REQUIRED: What is the journal entry to correct prior years’ depreciation? Calculate the depreciation expense 2010. the No Entry Required for
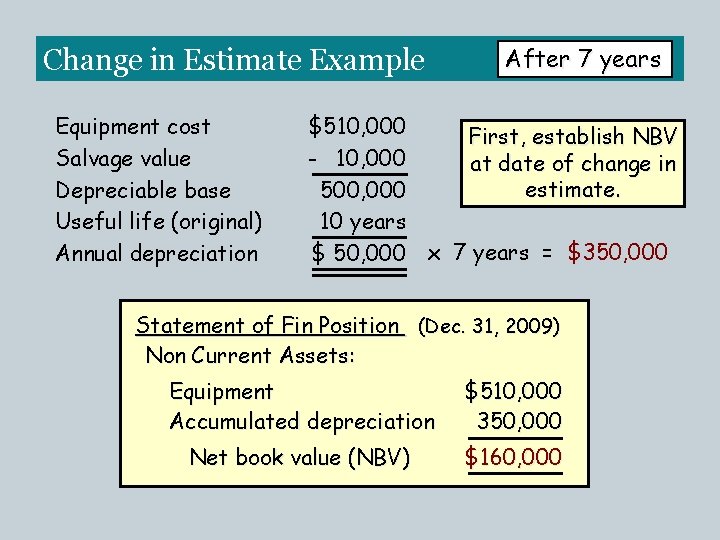
Change in Estimate Example Equipment cost Salvage value Depreciable base Useful life (original) Annual depreciation After 7 years $510, 000 First, establish NBV - 10, 000 at date of change in estimate. 500, 000 10 years $ 50, 000 x 7 years = $350, 000 Statement of Fin Position (Dec. 31, 2009) Non Current Assets: Equipment Accumulated depreciation $510, 000 350, 000 Net book value (NBV) $160, 000
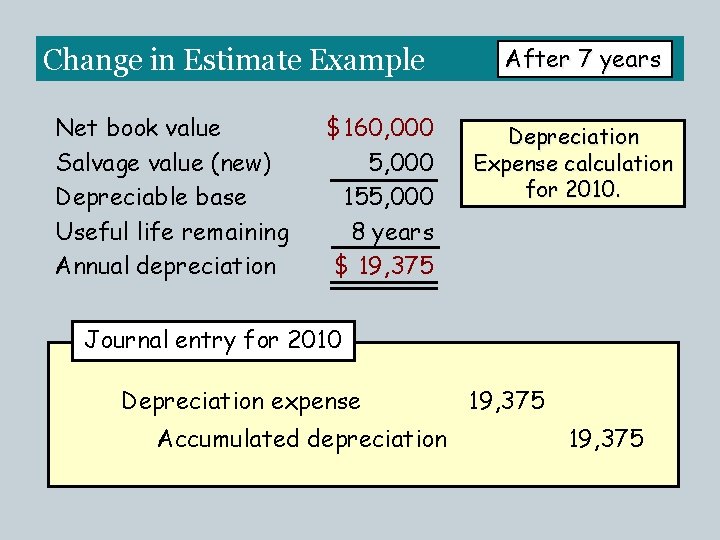
Change in Estimate Example Net book value Salvage value (new) Depreciable base Useful life remaining Annual depreciation $160, 000 5, 000 155, 000 8 years $ 19, 375 After 7 years Depreciation Expense calculation for 2010. Journal entry for 2010 Depreciation expense Accumulated depreciation 19, 375
Changes in Accounting Estimate Disclosures Companies need not disclose changes in accounting estimate made as part of normal operations, such as bad debt allowances or inventory obsolescence, unless such changes are material. However, for a change in estimate that affects several periods (such as a change in the service lives of depreciable assets), companies should disclose the effect on income from continuing operations and related per-share amounts of the current period.
Change in Reporting Entity Examples of a change in reporting entity are: 1. Presenting consolidated statements in place of statements of individual companies. 2. Changing specific subsidiaries that constitute the group of companies for which the entity presents consolidated financial statements. 3. Changing the companies included in combined financial statements. 4. Changing the cost, equity, or consolidation method of accounting for subsidiaries and investments. Reported by changing the financial statements of all prior periods presented.
Reporting Irregular Items Corrections of Errors Result from: mathematical mistakes Ø mistakes in application of accounting principles Ø oversight or misuse of facts Ø Corrections treated as prior period adjustments Adjustment to the beginning balance of retained earnings
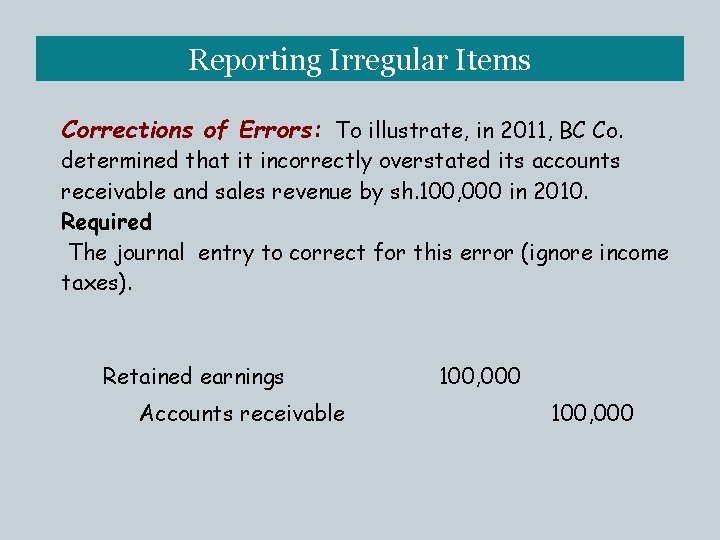
Reporting Irregular Items Corrections of Errors: To illustrate, in 2011, BC Co. determined that it incorrectly overstated its accounts receivable and sales revenue by sh. 100, 000 in 2010. Required The journal entry to correct for this error (ignore income taxes). Retained earnings Accounts receivable 100, 000
Special Reporting Issues Intraperiod Tax Allocation ØRefers to the allocation of income tax expense to the specific items that give rise to the amount of the tax expense. ØIncome tax is allocated to the following items: (1) Income from continuing operations before tax (2) Discontinued operations (3) Exceptional items (4) Changes in accounting principle (5) Correction of errors
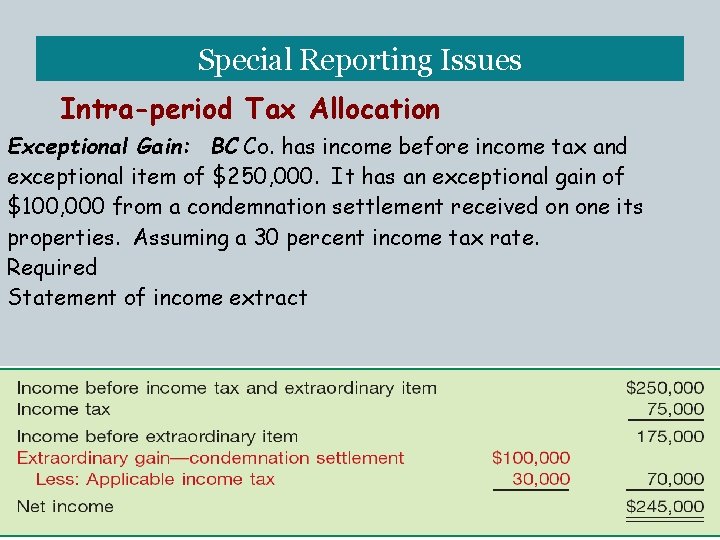
Special Reporting Issues Intra-period Tax Allocation Exceptional Gain: BC Co. has income before income tax and exceptional item of $250, 000. It has an exceptional gain of $100, 000 from a condemnation settlement received on one its properties. Assuming a 30 percent income tax rate. Required Statement of income extract
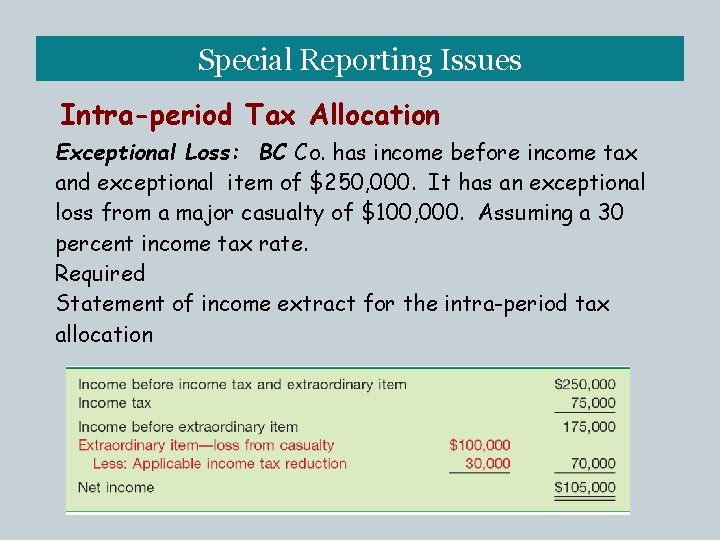
Special Reporting Issues Intra-period Tax Allocation Exceptional Loss: BC Co. has income before income tax and exceptional item of $250, 000. It has an exceptional loss from a major casualty of $100, 000. Assuming a 30 percent income tax rate. Required Statement of income extract for the intra-period tax allocation
Example of Intraperiod Tax Allocation Note: losses reduce the total tax Calculation of Total Tax $24, 000 (135) (81) (231) $23, 553
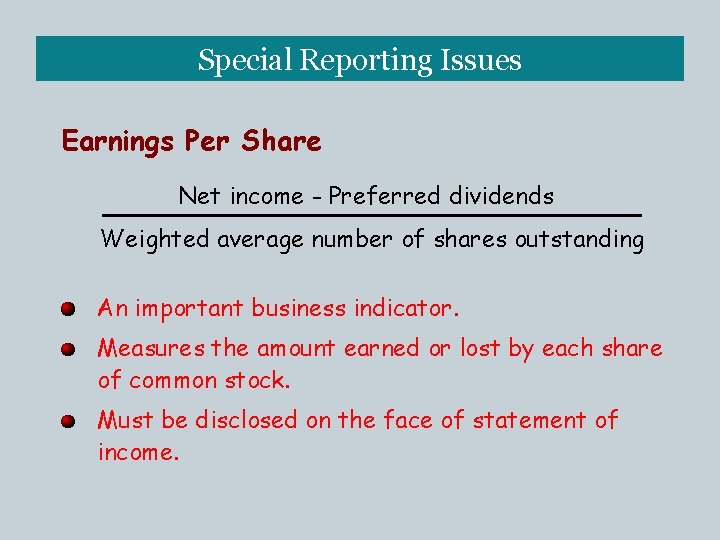
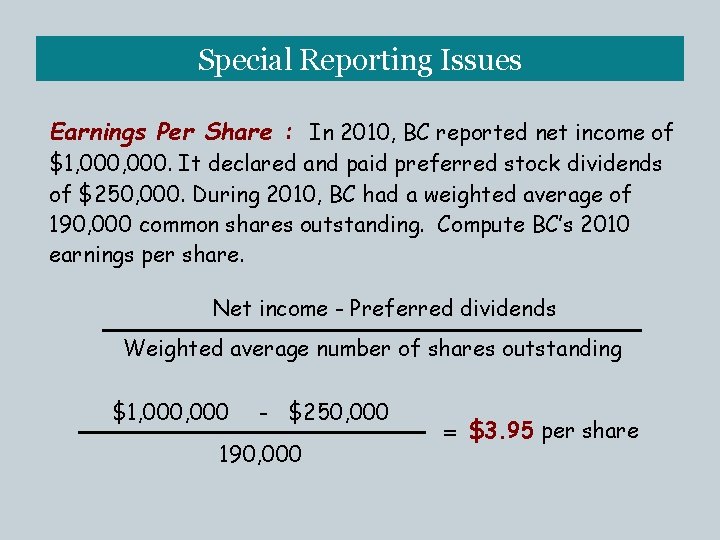
Special Reporting Issues Earnings Per Share Net income - Preferred dividends Weighted average number of shares outstanding An important business indicator. Measures the amount earned or lost by each share of common stock. Must be disclosed on the face of statement of income.
Special Reporting Issues Earnings Per Share : In 2010, BC reported net income of $1, 000. It declared and paid preferred stock dividends of $250, 000. During 2010, BC had a weighted average of 190, 000 common shares outstanding. Compute BC’s 2010 earnings per share. Net income - Preferred dividends Weighted average number of shares outstanding $1, 000 - $250, 000 190, 000 = $3. 95 per share
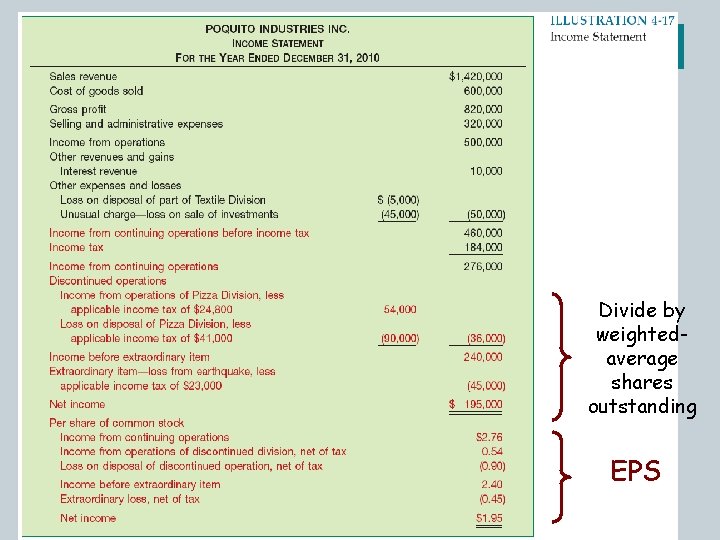
Special Reporting Issues Divide by weightedaverage shares outstanding EPS
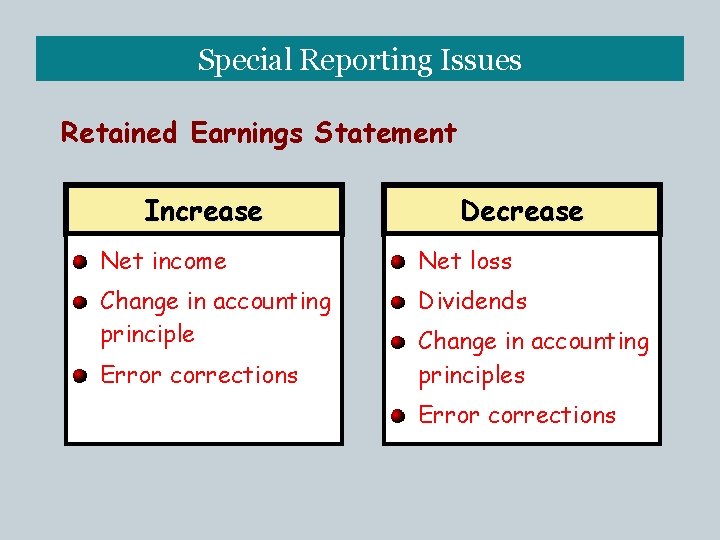
Special Reporting Issues Retained Earnings Statement Increase Decrease Net income Net loss Change in accounting principle Dividends Error corrections Change in accounting principles Error corrections
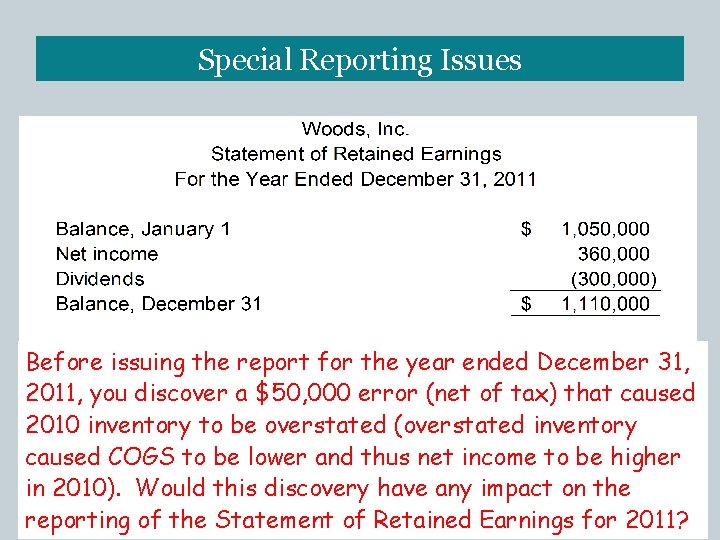
Special Reporting Issues Before issuing the report for the year ended December 31, 2011, you discover a $50, 000 error (net of tax) that caused 2010 inventory to be overstated (overstated inventory caused COGS to be lower and thus net income to be higher in 2010). Would this discovery have any impact on the reporting of the Statement of Retained Earnings for 2011?
Special Reporting Issues
Special Reporting Issues Restricted Retained Earnings Disclosed In notes to the financial statements As Appropriated Retained Earnings
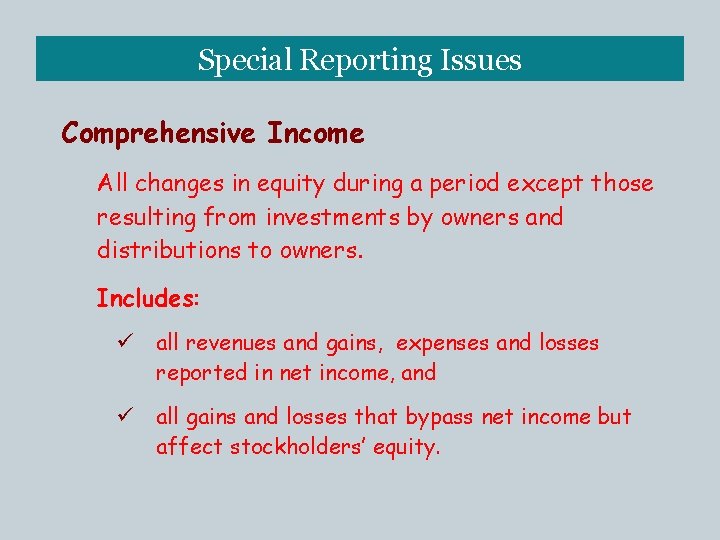
Special Reporting Issues Comprehensive Income All changes in equity during a period except those resulting from investments by owners and distributions to owners. Includes: ü all revenues and gains, expenses and losses reported in net income, and ü all gains and losses that bypass net income but affect stockholders’ equity.
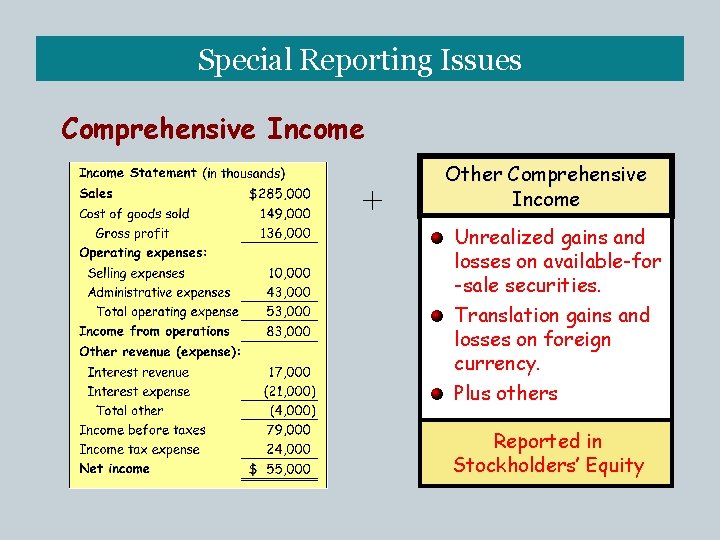
Special Reporting Issues Comprehensive Income + Other Comprehensive Income Unrealized gains and losses on available-for -sale securities. Translation gains and losses on foreign currency. Plus others Reported in Stockholders’ Equity
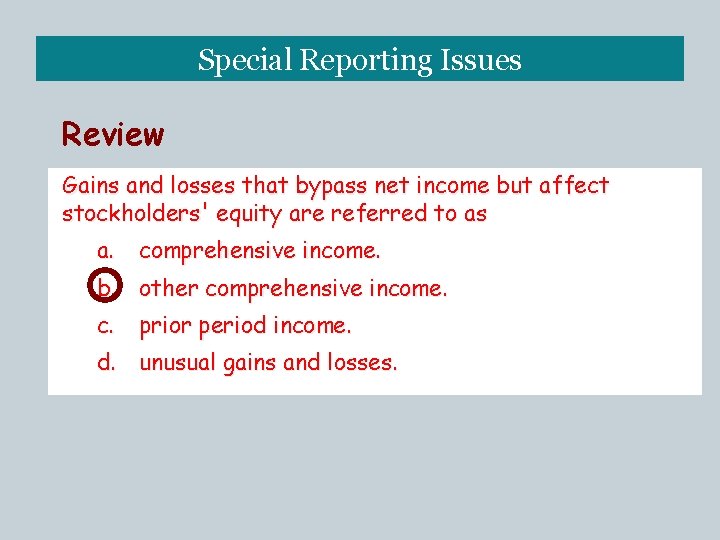
Special Reporting Issues Review Gains and losses that bypass net income but affect stockholders' equity are referred to as a. comprehensive income. b. other comprehensive income. c. prior period income. d. unusual gains and losses.
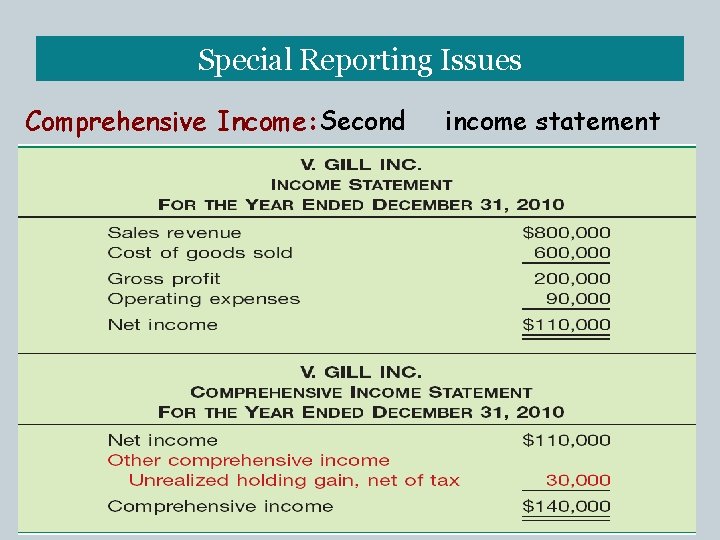
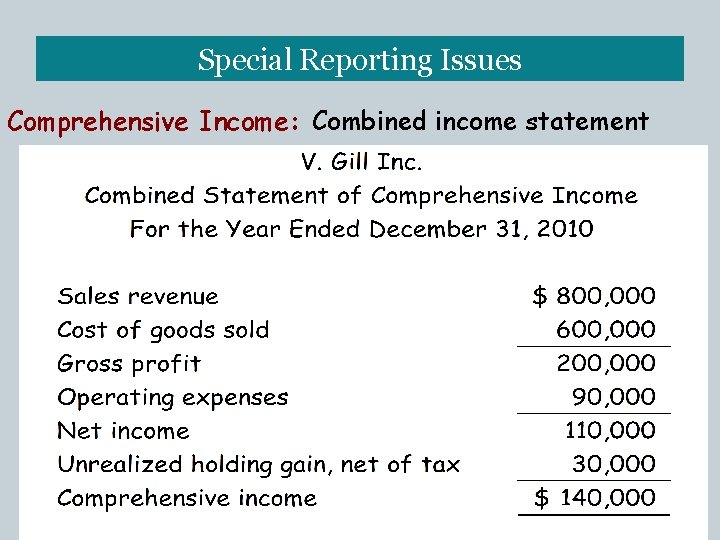
Special Reporting Issues Two approaches to reporting Comprehensive Income (IAS 1): 1. A second separate income statement and other comprehensive income ; or 2. A combined statement of comprehensive income;
Special Reporting Issues Comprehensive Income: Second income statement
Special Reporting Issues Comprehensive Income: Combined income statement
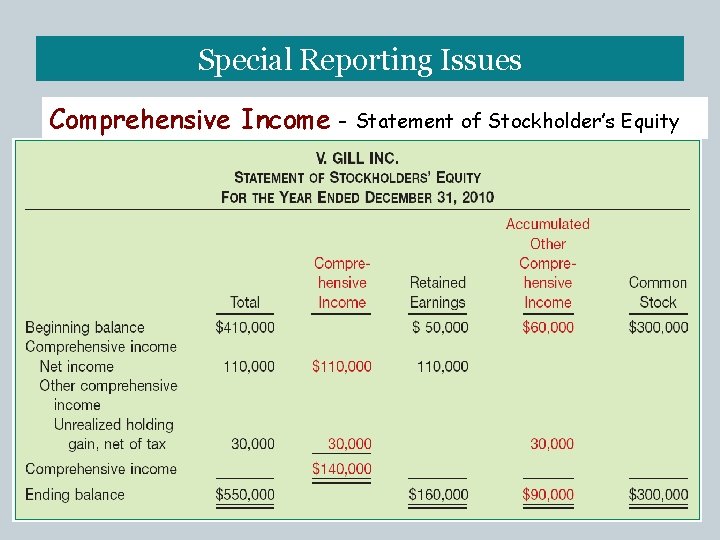
Special Reporting Issues Comprehensive Income - Statement of Stockholder’s Equity
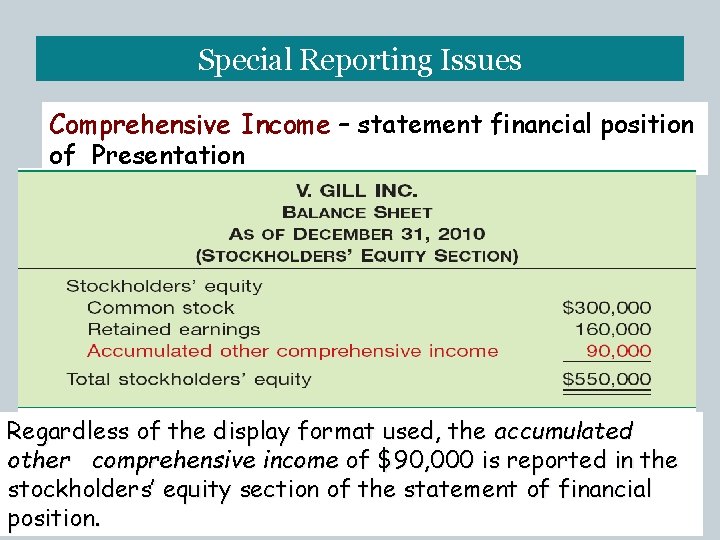
Special Reporting Issues Comprehensive Income – statement financial position of Presentation Regardless of the display format used, the accumulated other comprehensive income of $90, 000 is reported in the stockholders’ equity section of the statement of financial position.
END OF PRESENTATION THANK YOU