Succession w The Roles of Specialized Assets and
- Slides: 40
Succession w The Roles of Specialized Assets and Transfer Costs w Corporate Governance and Product Market Competition Yin-Hua Yeh (NCTU, Taiwan) 1
Succession: The Roles of Specialized Assets and Transfer Costs Joseph P. H. Fan (CUHK) Ming Jian (NTU, Singapore) Yin-Hua Yeh (NCTU, Taiwan) Rewrite and submit to the special issue of JCF (by including Morten Bennedsen as an additional co-author) 2
Succession as An Urgent Issue w Many Asian entrepreneurial firms have experienced succession In our research, we identified numerous succession cases in the past decades There are more to come soon 3
4
Research Questions w Family ownership of business is popular around the world. How successful are family firms? Recent economics research in developed economies report a mixed picture (Smith and Amoako-Adu, 1999; Morck, Strangeland, and Yeung, 2000; Anderson and Reeb, 2003; Perez. Gonzales, 2006; Villalonga and Amit, 2006) w If heir succession is bad, why do some firms insist? A second-best solution in weak institutional environments Interest alignment with the family (Bhattacharya and Ravikumar, 2002) The 2003) threat of expropriation (Burkart, Panuzi, and Shleifer, 5
Research Questions Family ownership and family succession w To protect specialized assets that are difficult to partition, value, and transfer across organizational boundaries (Alchian, 1965; 1969). Research Questions w How successful are successions? w What determine the success (or failure) of succession? w What determine the choice between an heir and an unrelated successor? 6
The Specialized Assets w The property right approach w Asset specificity activities governance structures of business Asset specificity and transfer costs in entrepreneurial activities Surviving firms probably possess competitive advantages. Entrepreneurial activities often consume a large amount of entrepreneurs’ personal time, effort, and financial capital, dictating an ideology to take on these activities and associated risks. Entrepreneurial activities often involve strong team spirit. 7
The Specialized Assets w The specialized assets are difficulties to partition and transfer across individuals and/or firm boundaries. A founder’s ideology, reputation in business, and political connections are specific to the founder, Intangible assets such as relationships with employees and banks, or Assets jointly controlled by family members and/or co-founders.
Hypothesis development w Family or outside succession Because of the transfer difficulties of the specialized assets, we expect to observe persistent concentrated ownership and control of the assets. We expect that an heir or a close relative would be chosen as the successor if the extent of asset specificity is large. Conversely, an important condition for outside succession is that the firm’s assets are standardized and easy to transfer across generations. 9
Hypothesis development w Firm value We expect an overall decline in firm capitalized value within the process of succession. Across different firms, the extent of value dissipation depends on the degree of asset specificity within their different activities. w We expect that the asset specificity induces high transfer costs, and hence the likelihood of family succession, high family ownership concentration, and poor performance in the succession process. 10
Definition of Succession w Succession as an event in which a controlling owner/manager steps down from the top executive (usually chairman in Asia) positions w Our succession events provide a unique opportunity to test theory, because, by the natural force of aging, the old leadership has to be terminated and ownership and control transferred to the new generation. w Typically succession is a process that takes time to complete We track firms from 5 years before to 3 years after their chairman turnovers. 11
Sample w Hong Kong, Singapore and Taiwan The prevalence of firms controlled by Chinese families. Keep track of turnovers of the top executive (typically chairman) for each of the firms starting from IPO year. w We exclude firms that are controlled by non-Chinese or governments, are in financial distress around succession, and an entrepreneur steps down from chairmanship but remains a director on the board. If any two turnovers of the same firm occur within 5 years, we exclude the earlier turnover as it is likely a transitory arrangement.
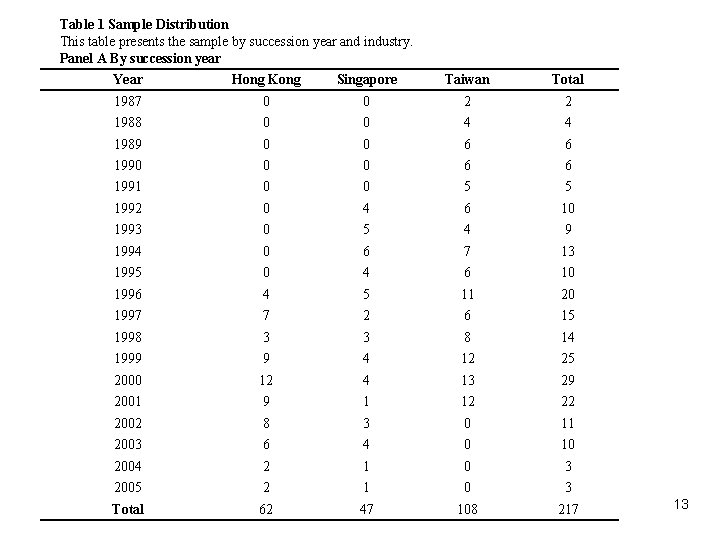
Table 1 Sample Distribution This table presents the sample by succession year and industry. Panel A By succession year Year Hong Kong Singapore Taiwan Total 1987 0 0 2 2 1988 0 0 4 4 1989 0 0 6 6 1990 0 0 6 6 1991 0 0 5 5 1992 0 4 6 10 1993 0 5 4 9 1994 0 6 7 13 1995 0 4 6 10 1996 4 5 11 20 1997 7 2 6 15 1998 3 3 8 14 1999 9 4 12 25 2000 12 4 13 29 2001 9 1 12 22 2002 8 3 0 11 2003 6 4 0 10 2004 2 1 0 3 2005 2 1 0 3 Total 62 47 108 217 13
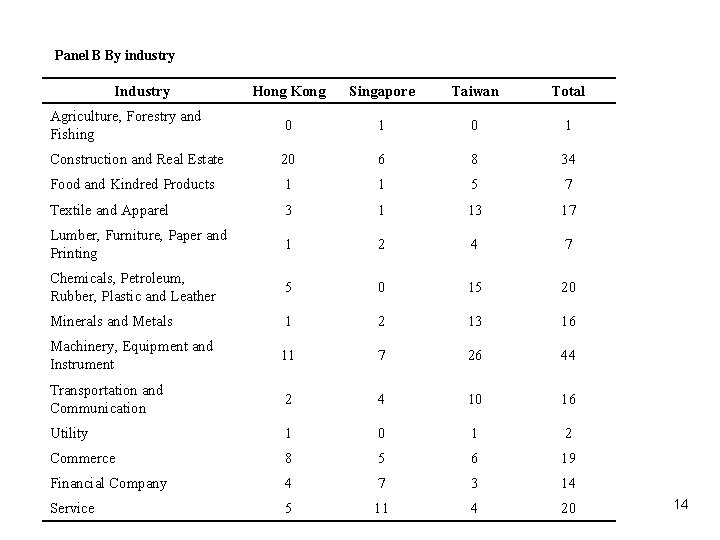
Panel B By industry Industry Hong Kong Singapore Taiwan Total Agriculture, Forestry and Fishing 0 1 Construction and Real Estate 20 6 8 34 Food and Kindred Products 1 1 5 7 Textile and Apparel 3 1 13 17 Lumber, Furniture, Paper and Printing 1 2 4 7 Chemicals, Petroleum, Rubber, Plastic and Leather 5 0 15 20 Minerals and Metals 1 2 13 16 Machinery, Equipment and Instrument 11 7 26 44 Transportation and Communication 2 4 10 16 Utility 1 0 1 2 Commerce 8 5 6 19 Financial Company 4 7 3 14 Service 5 11 4 20 14
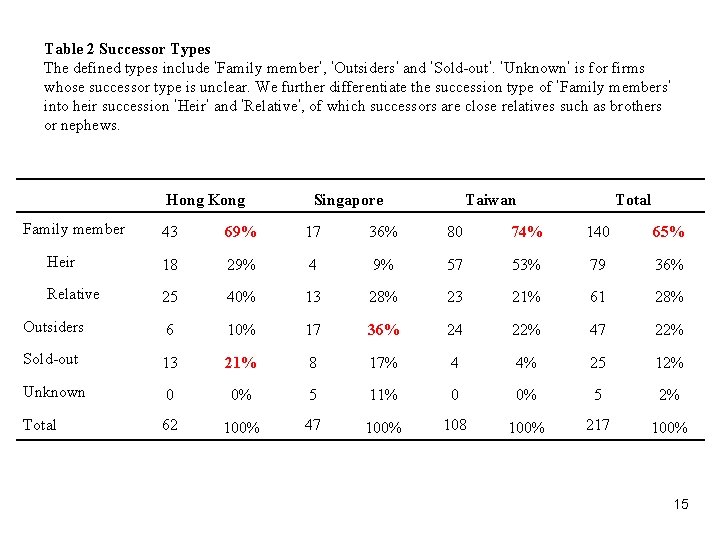
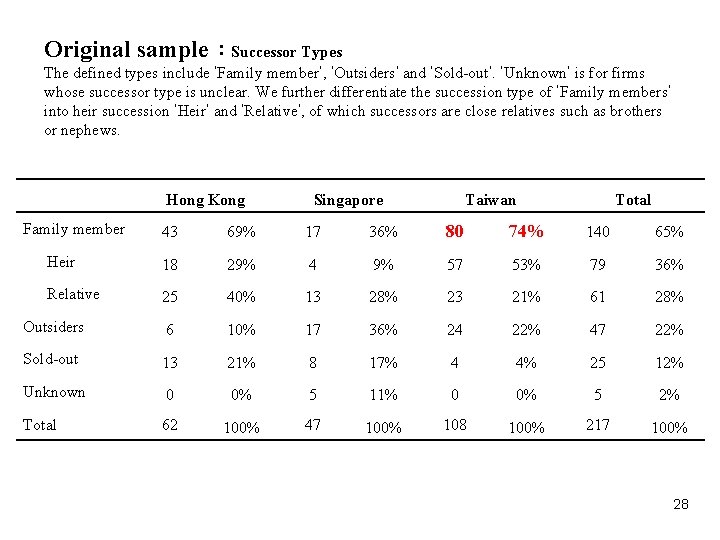
Table 2 Successor Types The defined types include ‘Family member’, ‘Outsiders’ and ‘Sold-out’. ‘Unknown’ is for firms whose successor type is unclear. We further differentiate the succession type of ‘Family members’ into heir succession ‘Heir’ and ‘Relative’, of which successors are close relatives such as brothers or nephews. Hong Kong Family member Singapore Taiwan Total 43 69% 17 36% 80 74% 140 65% Heir 18 29% 4 9% 57 53% 79 36% Relative 25 40% 13 28% 23 21% 61 28% Outsiders 6 10% 17 36% 24 22% 47 22% Sold-out 13 21% 8 17% 4 4% 25 12% Unknown 0 0% 5 11% 0 0% 5 2% Total 62 100% 47 100% 108 100% 217 100% 15
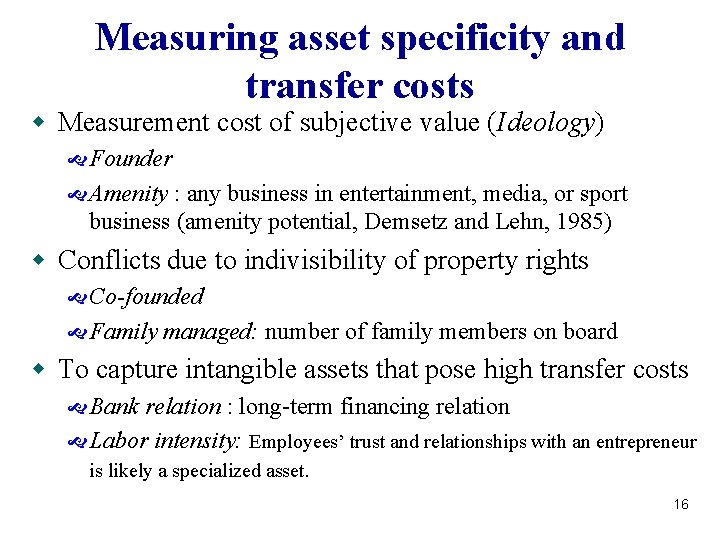
Measuring asset specificity and transfer costs w Measurement cost of subjective value (Ideology) Founder Amenity : any business in entertainment, media, or sport business (amenity potential, Demsetz and Lehn, 1985) w Conflicts due to indivisibility of property rights Co-founded Family managed: number of family members on board w To capture intangible assets that pose high transfer costs Bank relation : long-term financing relation Labor intensity: Employees’ trust and relationships with an entrepreneur is likely a specialized asset. 16
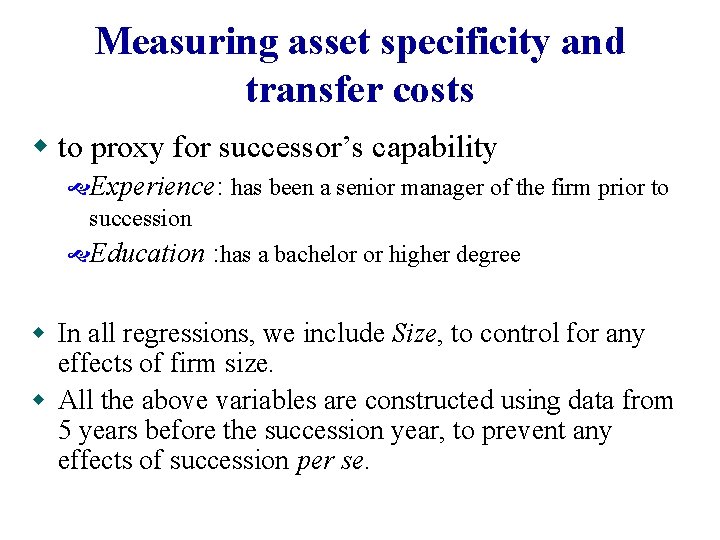
Measuring asset specificity and transfer costs w to proxy for successor’s capability Experience: has been a senior manager of the firm prior to succession Education : has a bachelor or higher degree w In all regressions, we include Size, to control for any effects of firm size. w All the above variables are constructed using data from 5 years before the succession year, to prevent any effects of succession per se.
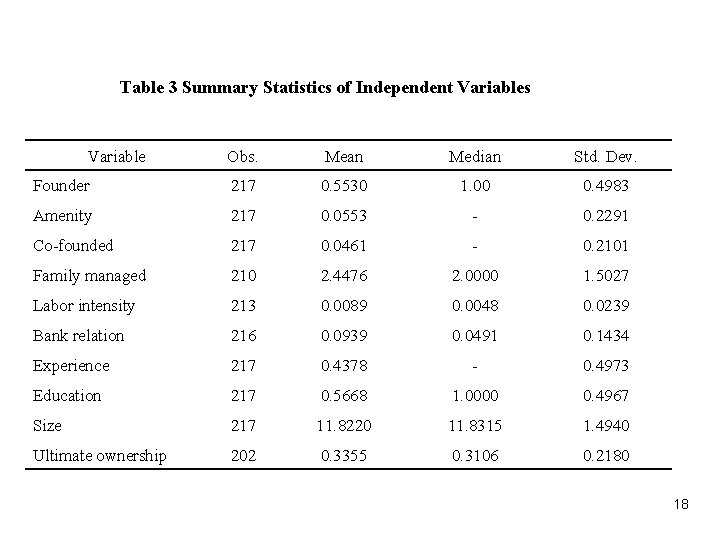
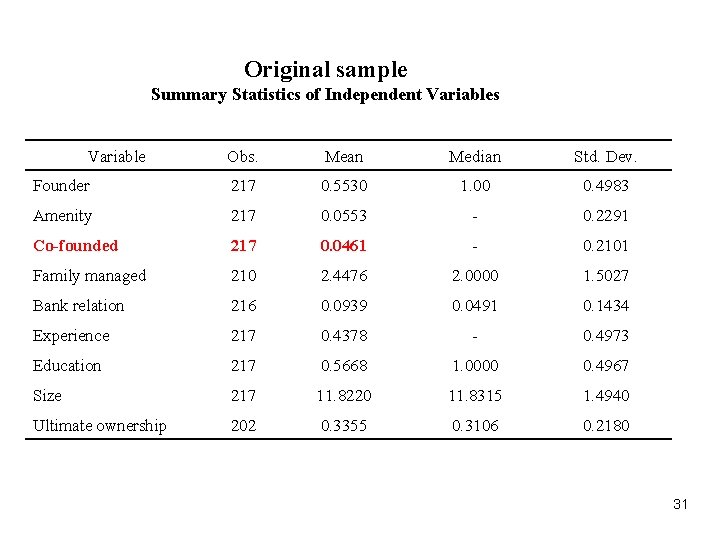
Table 3 Summary Statistics of Independent Variables Variable Obs. Mean Median Std. Dev. Founder 217 0. 5530 1. 00 0. 4983 Amenity 217 0. 0553 - 0. 2291 Co-founded 217 0. 0461 - 0. 2101 Family managed 210 2. 4476 2. 0000 1. 5027 Labor intensity 213 0. 0089 0. 0048 0. 0239 Bank relation 216 0. 0939 0. 0491 0. 1434 Experience 217 0. 4378 - 0. 4973 Education 217 0. 5668 1. 0000 0. 4967 Size 217 11. 8220 11. 8315 1. 4940 Ultimate ownership 202 0. 3355 0. 3106 0. 2180 18
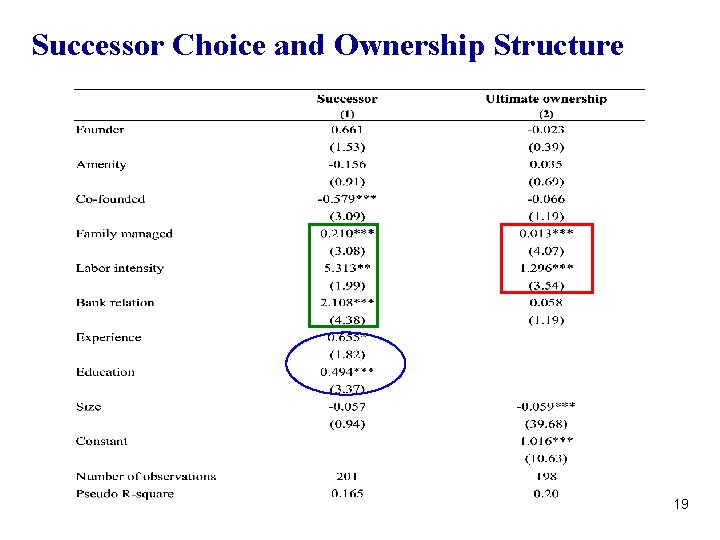
Successor Choice and Ownership Structure 19
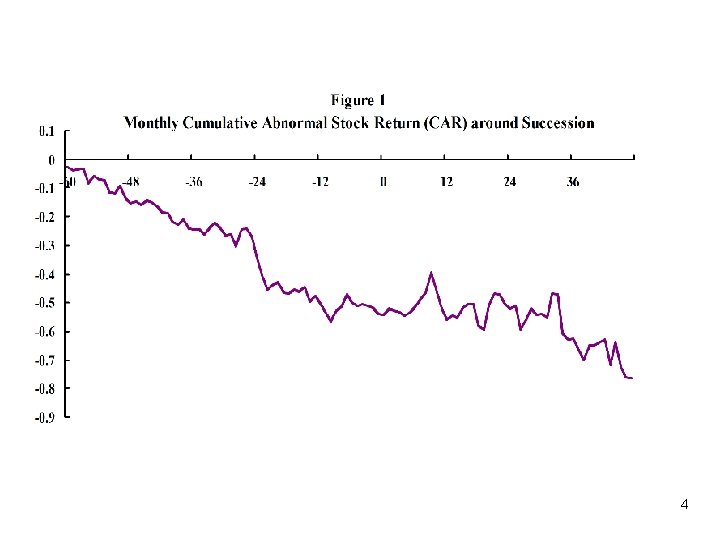
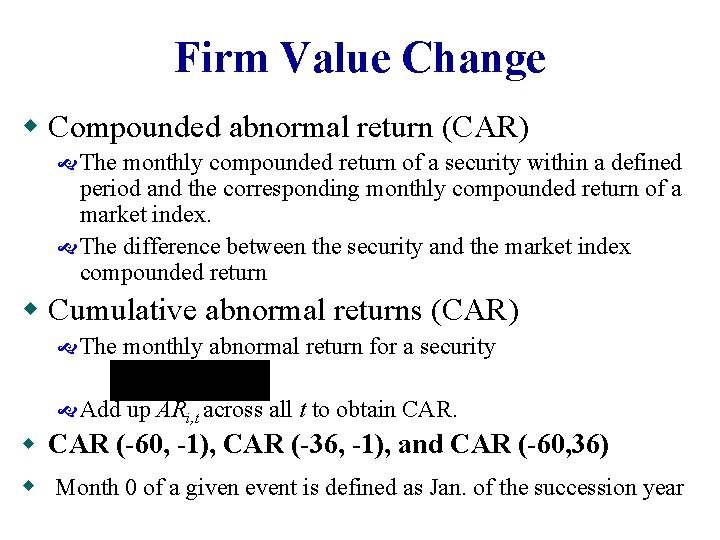
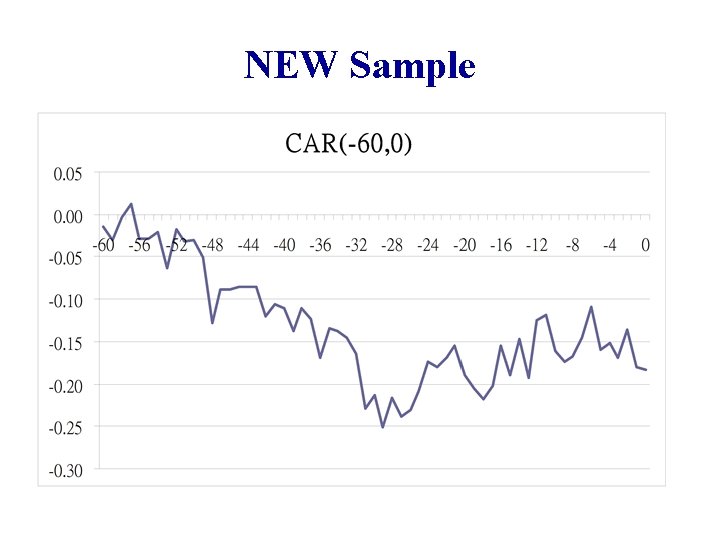
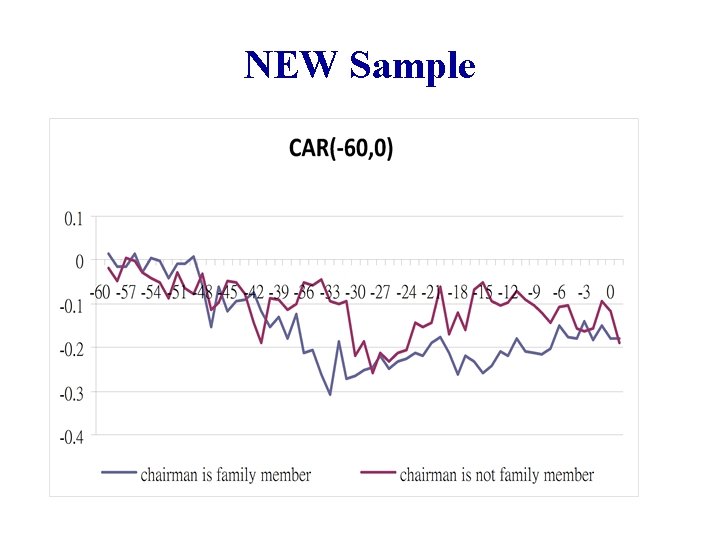
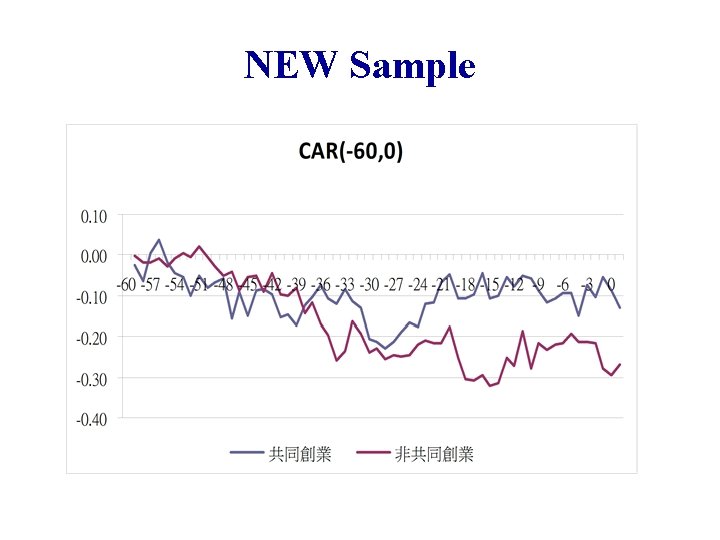
Firm Value Change w Compounded abnormal return (CAR) The monthly compounded return of a security within a defined period and the corresponding monthly compounded return of a market index. The difference between the security and the market index compounded return w Cumulative abnormal returns (CAR) The monthly abnormal return for a security Add up ARi, t across all t to obtain CAR. w CAR (-60, -1), CAR (-36, -1), and CAR (-60, 36) w Month 0 of a given event is defined as Jan. of the succession year
21
Table 5 Statistics of Abnormal Stock Returns around Succession Variable Obs. Mean Median Std. Dev. CAR (-60, 0) 144 -0. 5558 -0. 5412 1. 1225 CAR (-36, 0) 161 -0. 1560 -0. 2728 0. 8471 CAR (0, +48) 179 -0. 0288 -0. 0754 0. 8302 CAR (-60, 0) 54 -1. 2567 -1. 0224 0. 8656 CAR (-36, 0) 58 -0. 5400 -0. 7600 0. 7163 CAR (0, +48) 54 0. 0233 -0. 0930 1. 0643 CAR (-60, 0) 30 0. 2217 0. 0484 0. 7734 CAR (-36, 0) 32 0. 1884 -0. 0950 0. 7176 CAR (0, +48) 32 -0. 1849 -0. 3734 0. 8080 CAR (-60, 0) 60 -0. 3139 -0. 4101 1. 1270 CAR (-36, 0) 71 0. 0025 -0. 2244 0. 8902 CAR (0, +48) 93 -0. 0054 -0. 0409 0. 6712 Full sample Hong Kong Singapore Taiwan 22
Regression results of firm value changes around succession 23
Summary and Conclusion w Specialized assets play a crucial role in the emergence of family ownership A tendency that entrepreneurial firms, through family successions, evolve into family owned and managed firms The slow (or lack of) diffusion of ownership and control can be explained by the desire to protect value associated with specialized assets A pronounced dissipation of firm value during succession, which is positively related to asset specificity 24
Succession: Corporate Governance and Product Market Competition Yin-Hua Yeh (NCTU, Taiwan) 25
Co-founded firms Family succession Firm value Asset specificity Corporate Governance Product Market Competition
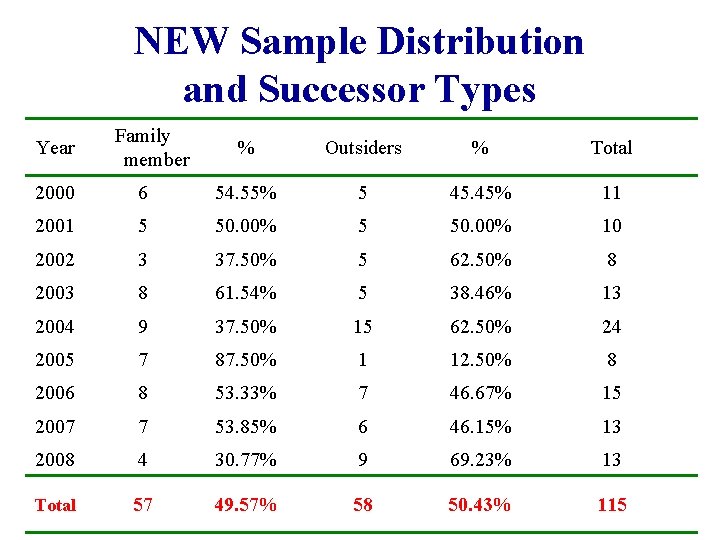
NEW Sample Distribution and Successor Types Year Family member % Outsiders % Total 2000 6 54. 55% 5 45. 45% 11 2001 5 50. 00% 10 2002 3 37. 50% 5 62. 50% 8 2003 8 61. 54% 5 38. 46% 13 2004 9 37. 50% 15 62. 50% 24 2005 7 87. 50% 1 12. 50% 8 2006 8 53. 33% 7 46. 67% 15 2007 7 53. 85% 6 46. 15% 13 2008 4 30. 77% 9 69. 23% 13 Total 57 49. 57% 58 50. 43% 115
Original sample :Successor Types The defined types include ‘Family member’, ‘Outsiders’ and ‘Sold-out’. ‘Unknown’ is for firms whose successor type is unclear. We further differentiate the succession type of ‘Family members’ into heir succession ‘Heir’ and ‘Relative’, of which successors are close relatives such as brothers or nephews. Hong Kong Family member Singapore Taiwan Total 43 69% 17 36% 80 74% 140 65% Heir 18 29% 4 9% 57 53% 79 36% Relative 25 40% 13 28% 23 21% 61 28% Outsiders 6 10% 17 36% 24 22% 47 22% Sold-out 13 21% 8 17% 4 4% 25 12% Unknown 0 0% 5 11% 0 0% 5 2% Total 62 100% 47 100% 108 100% 217 100% 28
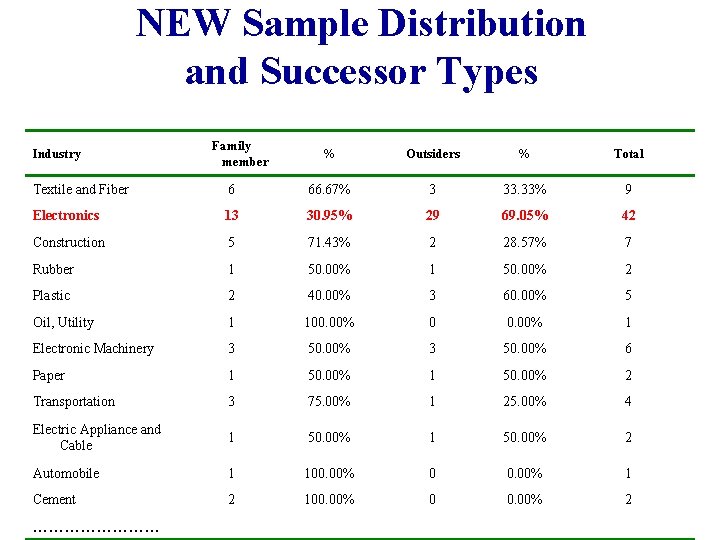
NEW Sample Distribution and Successor Types Industry Family member % Outsiders % Total Textile and Fiber 6 66. 67% 3 33. 33% 9 Electronics 13 30. 95% 29 69. 05% 42 Construction 5 71. 43% 2 28. 57% 7 Rubber 1 50. 00% 2 Plastic 2 40. 00% 3 60. 00% 5 Oil, Utility 1 100. 00% 0 0. 00% 1 Electronic Machinery 3 50. 00% 6 Paper 1 50. 00% 2 Transportation 3 75. 00% 1 25. 00% 4 Electric Appliance and Cable 1 50. 00% 2 Automobile 1 100. 00% 0 0. 00% 1 Cement 2 100. 00% 0 0. 00% 2 …………
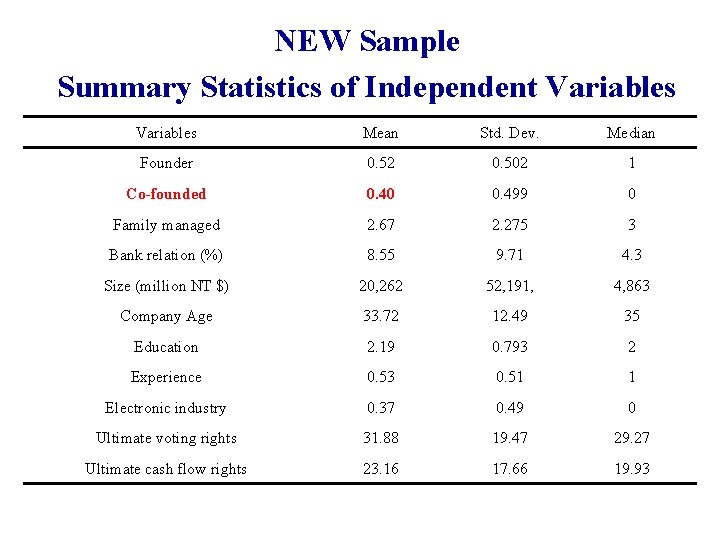
NEW Sample Summary Statistics of Independent Variables Mean Std. Dev. Median Founder 0. 52 0. 502 1 Co-founded 0. 40 0. 499 0 Family managed 2. 67 2. 275 3 Bank relation (%) 8. 55 9. 71 4. 3 Size (million NT $) 20, 262 52, 191, 4, 863 Company Age 33. 72 12. 49 35 Education 2. 19 0. 793 2 Experience 0. 53 0. 51 1 Electronic industry 0. 37 0. 49 0 Ultimate voting rights 31. 88 19. 47 29. 27 Ultimate cash flow rights 23. 16 17. 66 19. 93
Original sample Summary Statistics of Independent Variables Variable Obs. Mean Median Std. Dev. Founder 217 0. 5530 1. 00 0. 4983 Amenity 217 0. 0553 - 0. 2291 Co-founded 217 0. 0461 - 0. 2101 Family managed 210 2. 4476 2. 0000 1. 5027 Bank relation 216 0. 0939 0. 0491 0. 1434 Experience 217 0. 4378 - 0. 4973 Education 217 0. 5668 1. 0000 0. 4967 Size 217 11. 8220 11. 8315 1. 4940 Ultimate ownership 202 0. 3355 0. 3106 0. 2180 31
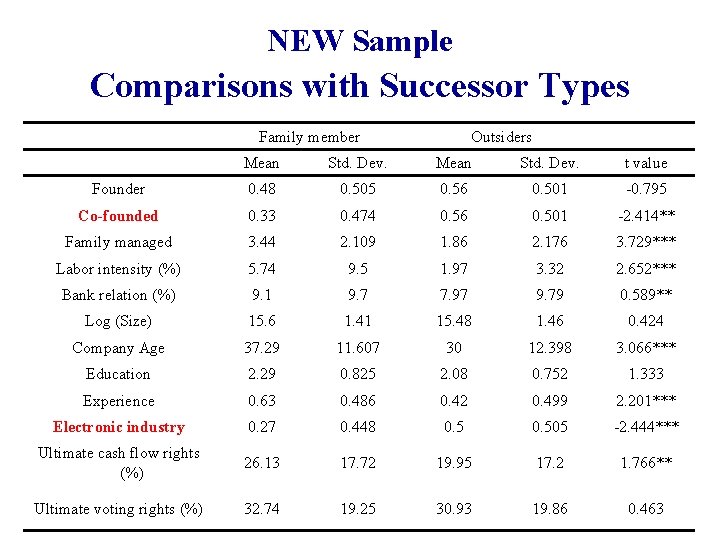
NEW Sample Comparisons with Successor Types Family member Outsiders Mean Std. Dev. t value Founder 0. 48 0. 505 0. 56 0. 501 -0. 795 Co-founded 0. 33 0. 474 0. 56 0. 501 -2. 414** Family managed 3. 44 2. 109 1. 86 2. 176 3. 729*** Labor intensity (%) 5. 74 9. 5 1. 97 3. 32 2. 652*** Bank relation (%) 9. 1 9. 7 7. 97 9. 79 0. 589** Log (Size) 15. 6 1. 41 15. 48 1. 46 0. 424 Company Age 37. 29 11. 607 30 12. 398 3. 066*** Education 2. 29 0. 825 2. 08 0. 752 1. 333 Experience 0. 63 0. 486 0. 42 0. 499 2. 201*** Electronic industry 0. 27 0. 448 0. 505 -2. 444*** Ultimate cash flow rights (%) 26. 13 17. 72 19. 95 17. 2 1. 766** Ultimate voting rights (%) 32. 74 19. 25 30. 93 19. 86 0. 463
NEW Sample
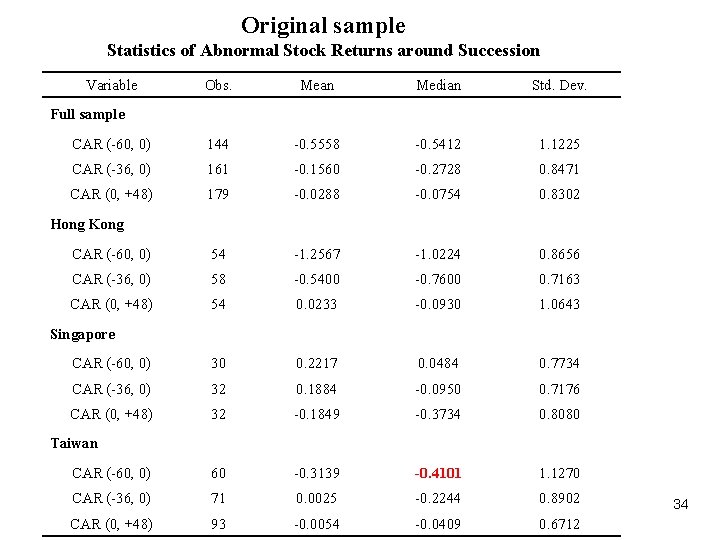
Original sample Statistics of Abnormal Stock Returns around Succession Variable Obs. Mean Median Std. Dev. CAR (-60, 0) 144 -0. 5558 -0. 5412 1. 1225 CAR (-36, 0) 161 -0. 1560 -0. 2728 0. 8471 CAR (0, +48) 179 -0. 0288 -0. 0754 0. 8302 CAR (-60, 0) 54 -1. 2567 -1. 0224 0. 8656 CAR (-36, 0) 58 -0. 5400 -0. 7600 0. 7163 CAR (0, +48) 54 0. 0233 -0. 0930 1. 0643 CAR (-60, 0) 30 0. 2217 0. 0484 0. 7734 CAR (-36, 0) 32 0. 1884 -0. 0950 0. 7176 CAR (0, +48) 32 -0. 1849 -0. 3734 0. 8080 CAR (-60, 0) 60 -0. 3139 -0. 4101 1. 1270 CAR (-36, 0) 71 0. 0025 -0. 2244 0. 8902 CAR (0, +48) 93 -0. 0054 -0. 0409 0. 6712 Full sample Hong Kong Singapore Taiwan 34
NEW Sample
NEW Sample
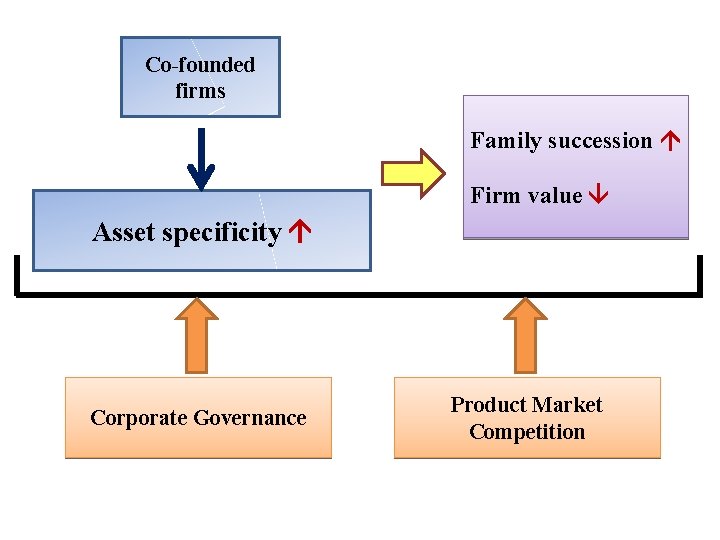
The Role of Co-founded Firms w Co-founded firms are subject to more serious infighting for property right re-distribution during succession. w However, co-founded firms can mitigate the transfer costs in succession because they are mutually managed and monitored. the shareholdings of co-founders
Product market competition w Can help entrepreneurial firms professionalize their business early on to mitigate the transfer costs in succession. w More serious agency problems are in noncompetitive industries, and competitive forces can reduce the need for shareholders to bear the costs of monitoring agents and increase the frequency of CEO turnover (Giroud and Muller, 2011; Leventis, et al. , 2011; de Bettignies and Baggs, 2005; De Fond and Park, 1999)
CG index w Can help entrepreneurial firms systematize their business before succession. w CGI is a composite corporate governance index (Yeh, Shu and Su, 2012) Controlling shareholders’ cash flow rights cash/control the proportion of the directory membership being controlled by the controlling shareholders the proportion of supervisory membership being controlled by the controlling shareholders the proportion of directors’ and supervisors’ shareholdings being pledged to bank loans the proportion of related-party sales the proportion of related-party loans and the proportion of related-party loan guarantees
Preliminary Results w Assets specificity also provide good explanation of successor choice w The negative relation between Co-founded firms and CAR disappear and change to a positive relation when co-founders hold high shareholdings. w We expect product market competition and governance quality will moderate the probability of family succession and the value loss during succession