The Pain and the Mystery of Original Sin
- Slides: 51
The Pain and the Mystery of Original Sin Barry Eichengreen Ricardo Hausmann Ugo Panizza 1
Outline and Summary n Definition and Facts n Most countries do not borrow abroad in their own currencies, a problem we refer to as “original sin” n If a country has a net foreign debt, this creates an aggregate currency mismatch n n Pain n n Of course a country can decide not to have a mismatch by not borrowing or holding a lot of reserves We show that original sin is associated with limited XR flexibility, high volatility, low credit ratings Mystery n We show that standard explanations based on poor policies or institutions do not do a good job at explaining original sin 2
Work on Original Sin n First papers on the topic: n n Original Sin book: n n Eichengreen and Hausmann (1999) Hausmann, Panizza, and Stein (2001) Hausmann and Panizza (2003) Cespedes, Chang and Velasco, Corsetti and Mackowiak, Jeanne and Zettelmeyer, Flandreau and Sussman, Bordo, Meissner and Redish, Chamon and Hausmann Critics: n n Goldstein and Turner (2003) Burger and Warnock (2003) Reinhart, Rogoff, and Savastano (2003) Eichengreen, Hausmann, and Panizza (2003) 3
Definition n n Eichengreen and Hausmann (1999) definition: “a situation in which the domestic currency is not used to borrow abroad or to borrow long term even domestically” Here we mostly focus on “international original sin” n n n Better data on international original sin Domestic original sin seems easier to solve and some countries are doing progress in this direction However, we also try to say something on “domestic original sin” 4
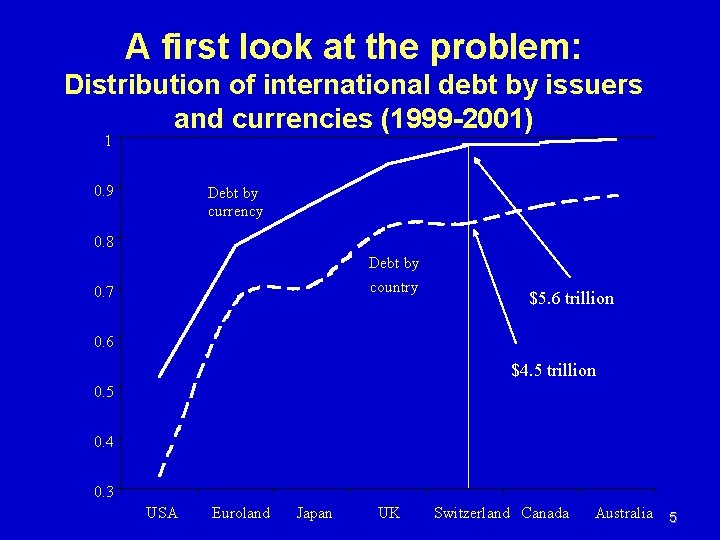
A first look at the problem: Distribution of international debt by issuers and currencies (1999 -2001) 1 0. 9 Debt by currency 0. 8 Debt by country 0. 7 $5. 6 trillion 0. 6 $4. 5 trillion 0. 5 0. 4 0. 3 USA Euroland Japan UK Switzerland Canada Australia 5
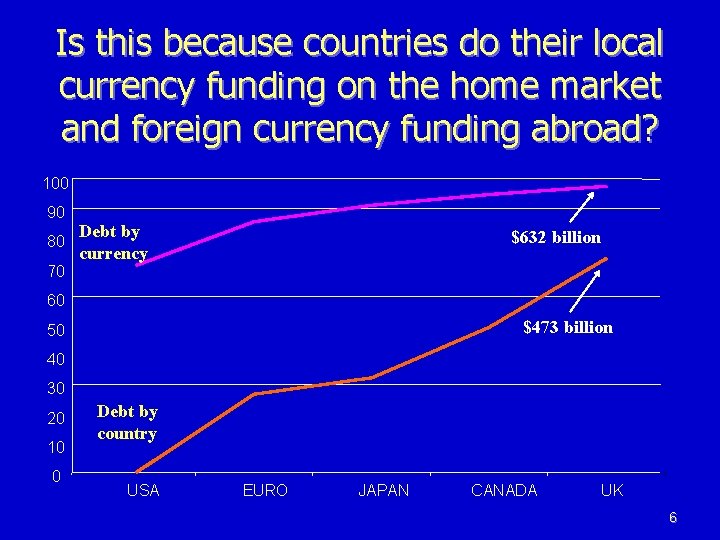
Is this because countries do their local currency funding on the home market and foreign currency funding abroad? 100 90 80 70 Debt by currency $632 billion 60 $473 billion 50 40 30 20 10 0 Debt by country USA EURO JAPAN CANADA UK 6
Measurement n n Measuring original sin is not straightforward In principle, we want to measure external liabilities in own currency as a share of total external liabilities We use data gathered by the BIS on the currency denomination of bonds and money market instruments We also consider BIS data on cross-border bank lending, although the data are less complete (both in country coverage and currency breakdown) 7
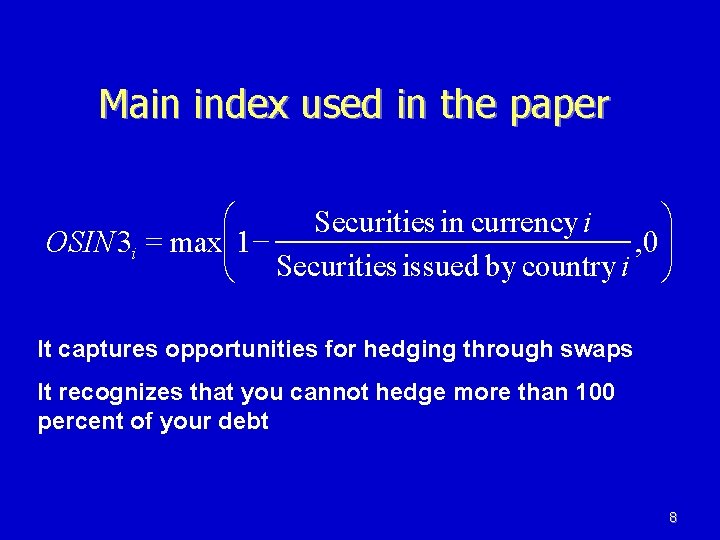
Main index used in the paper æ ö Securities in currency i OSIN 3 i = maxçç 1 , 0 ÷÷ è Securities issued by country i ø It captures opportunities for hedging through swaps It recognizes that you cannot hedge more than 100 percent of your debt 8
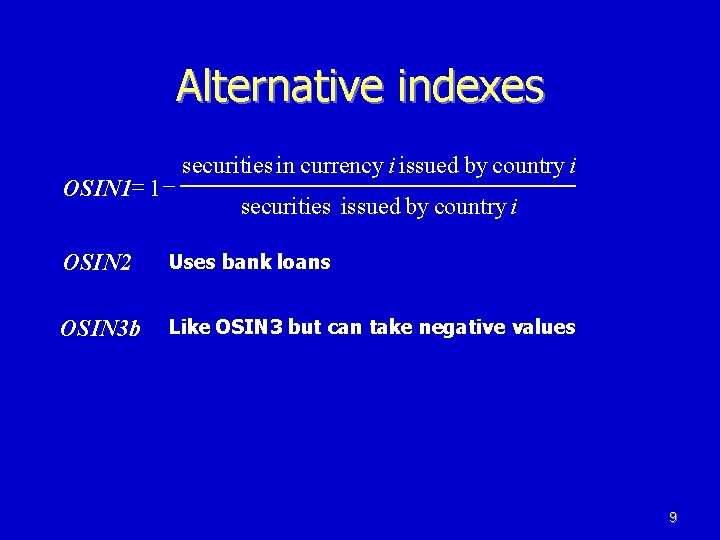
Alternative indexes OSIN 1= 1 - securities in currency i issued by country i securities issued by country i OSIN 2 Uses bank loans OSIN 3 b Like OSIN 3 but can take negative values 9
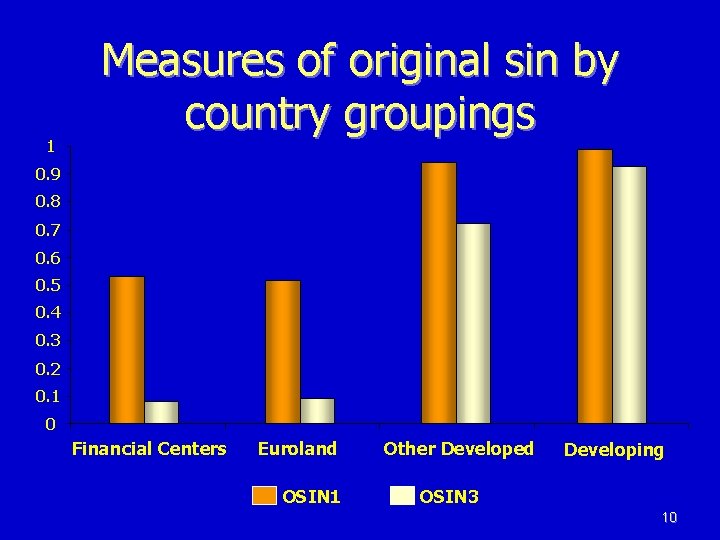
1 Measures of original sin by country groupings 0. 9 0. 8 0. 7 0. 6 0. 5 0. 4 0. 3 0. 2 0. 1 0 Financial Centers Euroland OSIN 1 Other Developed Developing OSIN 3 10
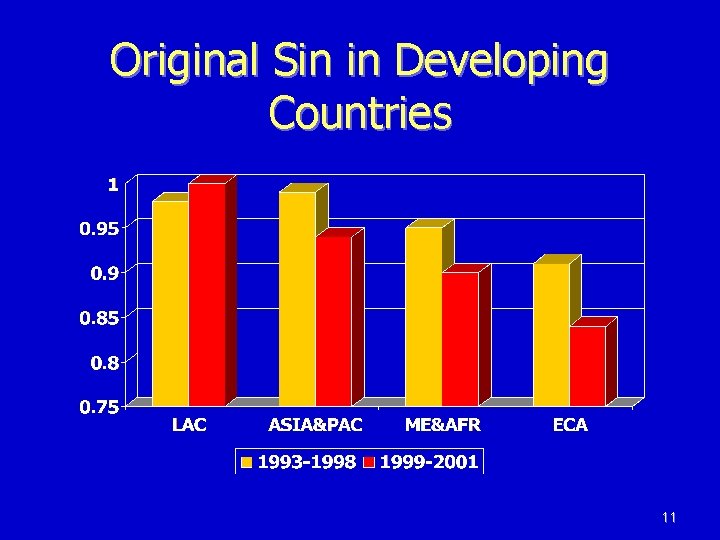
Original Sin in Developing Countries 11
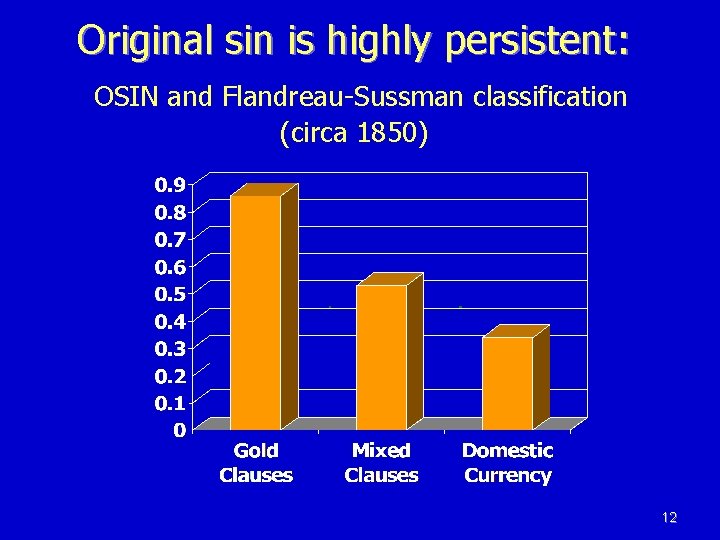
Original sin is highly persistent: OSIN and Flandreau-Sussman classification (circa 1850) 12
The Pain of Original Sin (The consequences)
n Exchange rate flexibility n Output and capital flow volatility n Credit ratings 14
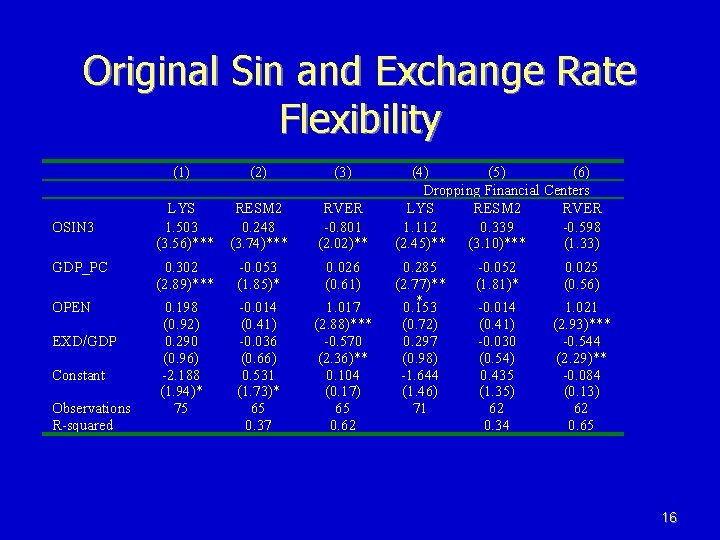
Original Sin and Exchange Rate Flexibility n n n If an original sin country has a net foreign debt, then there is an aggregate currency mismatch. Movements in the RER will have an aggregated wealth effect This renders the CB less willing to let the exchange rate move (fear of floating, Calvo and Reinhart, 2002) As a consequence, the CB holds more reserves and uses them, together with the interest rate, to intervene in the foreign exchange market (Hausmann, Panizza, Stein, 2001) 15
Original Sin and Exchange Rate Flexibility (1) OSIN 3 (2) LYS RESM 2 1. 503 0. 248 (3. 56)*** (3. 74)*** (3) RVER -0. 801 (2. 02)** GDP_PC 0. 302 (2. 89)*** -0. 053 (1. 85)* 0. 026 (0. 61) OPEN 0. 198 (0. 92) 0. 290 (0. 96) -2. 188 (1. 94)* 75 -0. 014 (0. 41) -0. 036 (0. 66) 0. 531 (1. 73)* 65 0. 37 1. 017 (2. 88)*** -0. 570 (2. 36)** 0. 104 (0. 17) 65 0. 62 EXD/GDP Constant Observations R-squared (4) (5) (6) Dropping Financial Centers LYS RESM 2 RVER 1. 112 0. 339 -0. 598 (2. 45)** (3. 10)*** (1. 33) 0. 285 (2. 77)** * 0. 153 (0. 72) 0. 297 (0. 98) -1. 644 (1. 46) 71 -0. 052 (1. 81)* 0. 025 (0. 56) -0. 014 (0. 41) -0. 030 (0. 54) 0. 435 (1. 35) 62 0. 34 1. 021 (2. 93)*** -0. 544 (2. 29)** -0. 084 (0. 13) 62 0. 65 16
Original Sin and Exchange Rate Flexibility n n The results are generally robust to alternative definitions of original sin, to dropping weights, and to augmenting the regressions with a developing country dummy Causality is a big issue (Burnside, Eichenbaum, and Rebelo, 2001) n IV regressions confirm the results but instrument (SIZE) is lousy n n n We tried to go in the other direction. OSIN on the left and LYS on the right instrumented with openness. We found no correlation between LYS and OSIN Using lagged OSIN in a panel confirms the results Devereux and Lane (2003) 17
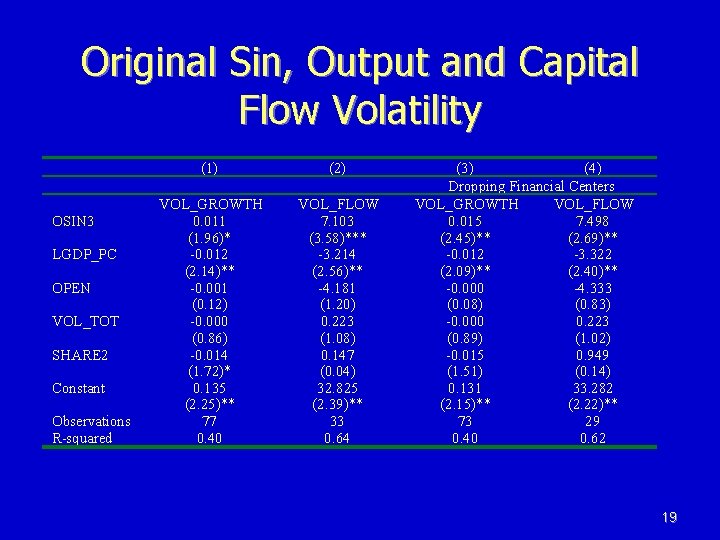
Original Sin, Output and Capital Flow Volatility n n Original sin limits the scope and effectiveness of counter-cyclical policies (Cespedes, Chang and Velasco, 2003) Original Sin limits the CB ability of acting as a LOLR (Chang and Velasco, 2000) Dollar liabilities are likely to increase the cost of a currency crisis Dollar liabilities could be associated with Sudden Stops in capital flows (Calvo, Izquierdo and Mejia, 2003) 18
Original Sin, Output and Capital Flow Volatility OSIN 3 LGDP_PC OPEN VOL_TOT SHARE 2 Constant Observations R-squared (1) (2) VOL_GROWTH 0. 011 (1. 96)* -0. 012 (2. 14)** -0. 001 (0. 12) -0. 000 (0. 86) -0. 014 (1. 72)* 0. 135 (2. 25)** 77 0. 40 VOL_FLOW 7. 103 (3. 58)*** -3. 214 (2. 56)** -4. 181 (1. 20) 0. 223 (1. 08) 0. 147 (0. 04) 32. 825 (2. 39)** 33 0. 64 (3) (4) Dropping Financial Centers VOL_GROWTH VOL_FLOW 0. 015 7. 498 (2. 45)** (2. 69)** -0. 012 -3. 322 (2. 09)** (2. 40)** -0. 000 -4. 333 (0. 08) (0. 83) -0. 000 0. 223 (0. 89) (1. 02) -0. 015 0. 949 (1. 51) (0. 14) 0. 131 33. 282 (2. 15)** (2. 22)** 73 29 0. 40 0. 62 19
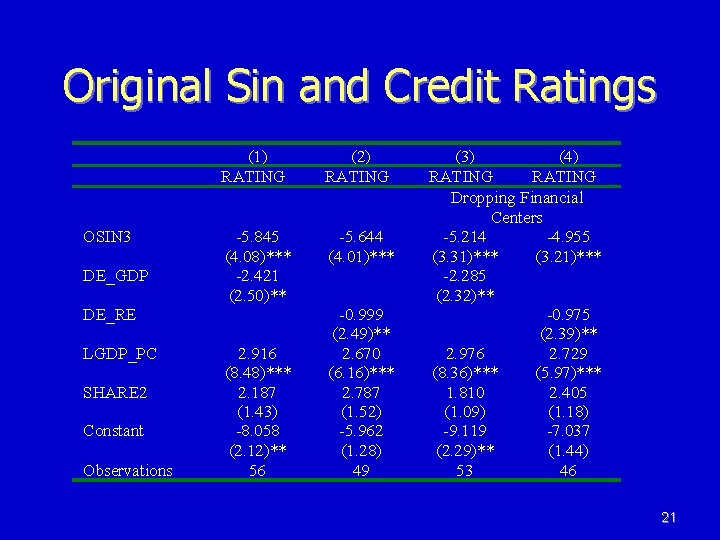
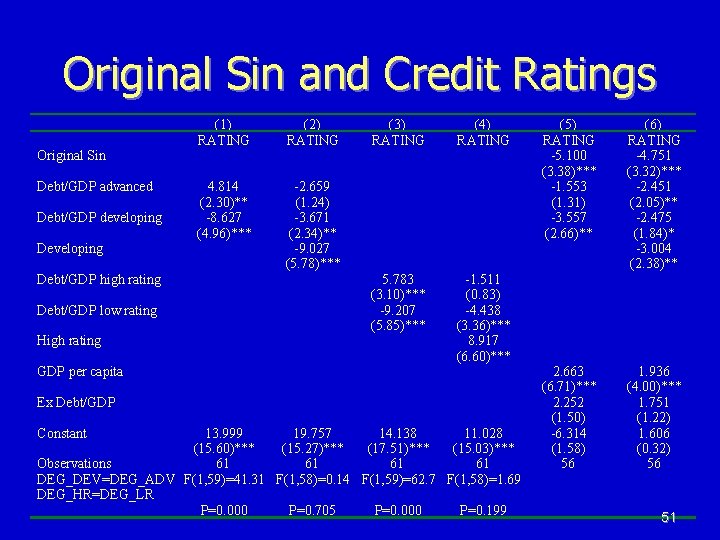
Original Sin and Credit Ratings n If a country’s debt is denominated in foreign currency, its capacity to pay will not be related to its LCU GDP but to its dollar GDP n n n Original Sin makes the real exchange rate matter for debt service This is important because in developing countries the volatility of dollar GDP is much higher than the volatility of LCU GDP, and sudden drops of dollar GDP are usually associated with much smaller drops in real GDP Other things equal, countries with Original Sin should be riskier than countries that borrow in own currency 20
Original Sin and Credit Ratings OSIN 3 DE_GDP (1) RATING (2) RATING -5. 845 (4. 08)*** -2. 421 (2. 50)** -5. 644 (4. 01)*** DE_RE LGDP_PC SHARE 2 Constant Observations 2. 916 (8. 48)*** 2. 187 (1. 43) -8. 058 (2. 12)** 56 -0. 999 (2. 49)** 2. 670 (6. 16)*** 2. 787 (1. 52) -5. 962 (1. 28) 49 (3) (4) RATING Dropping Financial Centers -5. 214 -4. 955 (3. 31)*** (3. 21)*** -2. 285 (2. 32)** -0. 975 (2. 39)** 2. 976 2. 729 (8. 36)*** (5. 97)*** 1. 810 2. 405 (1. 09) (1. 18) -9. 119 -7. 037 (2. 29)** (1. 44) 53 46 21
The Mystery of Original Sin (the causes)
Key Question from this Point of View n n Does the inability to borrow internationally in domestic currency reflect problems with country policies and institutions or systematic problems? We argue that the problem is too pervasive (and too weakly correlated with country characteristics) to be entirely explicable on the first set of grounds. 23
Five possible explanations n n n Underdevelopment of institutions and policies in general Inadequate monetary credibility Fiscal profligacy Weak contract enforcement Political economy stories 24
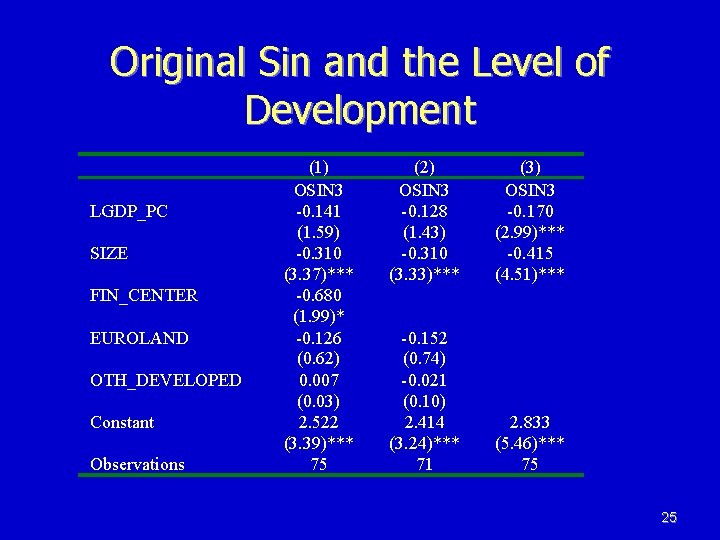
Original Sin and the Level of Development LGDP_PC SIZE FIN_CENTER EUROLAND OTH_DEVELOPED Constant Observations (1) OSIN 3 -0. 141 (1. 59) -0. 310 (3. 37)*** -0. 680 (1. 99)* -0. 126 (0. 62) 0. 007 (0. 03) 2. 522 (3. 39)*** 75 (2) OSIN 3 -0. 128 (1. 43) -0. 310 (3. 33)*** (3) OSIN 3 -0. 170 (2. 99)*** -0. 415 (4. 51)*** -0. 152 (0. 74) -0. 021 (0. 10) 2. 414 (3. 24)*** 71 2. 833 (5. 46)*** 75 25
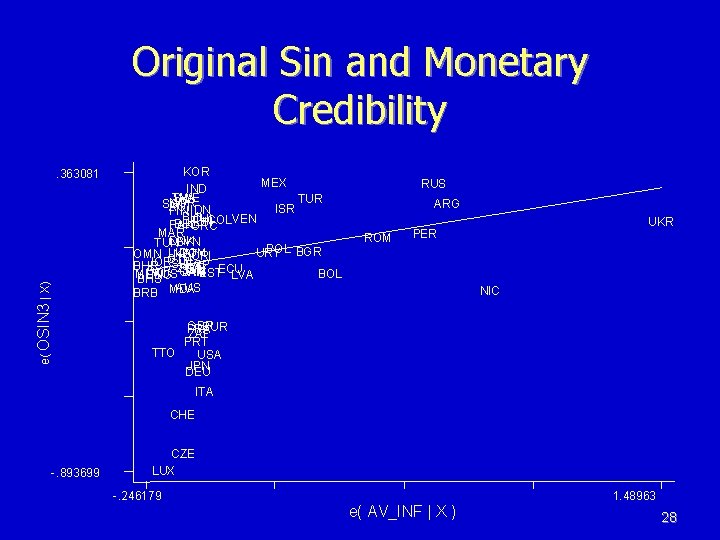
Original Sin and Monetary Credibility n n Lack of monetary credibility is the true cause of Original Sin (Jeanne, 2002) The government has an incentive to inflate away domestic currency debt held by foreigners, and the presence of foreign currency debt can act as commitment device and improve credibility (Tirole, 2002, Calvo and Guidotti, 1990) n Why don’t we observe inflation indexed debt? (Chamon, 2002) 26
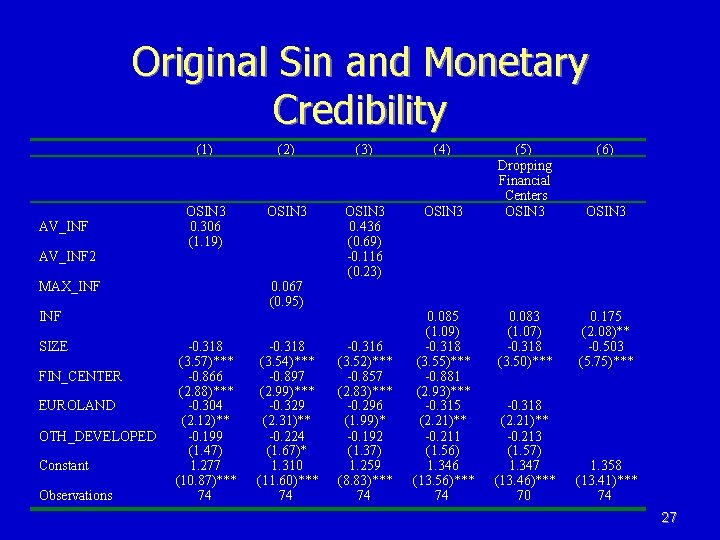
Original Sin and Monetary Credibility AV_INF 2 (1) (2) (3) (4) OSIN 3 0. 306 (1. 19) OSIN 3 0. 436 (0. 69) -0. 116 (0. 23) OSIN 3 MAX_INF 0. 067 (0. 95) INF SIZE FIN_CENTER EUROLAND OTH_DEVELOPED Constant Observations -0. 318 (3. 57)*** -0. 866 (2. 88)*** -0. 304 (2. 12)** -0. 199 (1. 47) 1. 277 (10. 87)*** 74 -0. 318 (3. 54)*** -0. 897 (2. 99)*** -0. 329 (2. 31)** -0. 224 (1. 67)* 1. 310 (11. 60)*** 74 -0. 316 (3. 52)*** -0. 857 (2. 83)*** -0. 296 (1. 99)* -0. 192 (1. 37) 1. 259 (8. 83)*** 74 0. 085 (1. 09) -0. 318 (3. 55)*** -0. 881 (2. 93)*** -0. 315 (2. 21)** -0. 211 (1. 56) 1. 346 (13. 56)*** 74 (5) Dropping Financial Centers OSIN 3 (6) OSIN 3 0. 083 (1. 07) -0. 318 (3. 50)*** 0. 175 (2. 08)** -0. 503 (5. 75)*** -0. 318 (2. 21)** -0. 213 (1. 57) 1. 347 (13. 46)*** 70 1. 358 (13. 41)*** 74 27
Original Sin and Monetary Credibility e( OSIN 3 | X) . 363081 KOR MEX IND SWE THA TUR NOR SGP AUT ISR IDN FIN PHL COLVEN HUN BEL PAK GRC MAR DNK SVN TUN POL BGR URY DOM LKA OMN GTM NET CRI JOR SLV ESP ECU BHR ZWE ISL SVK CYP JAM EST LVA MLT BOL MUS CAN PNG BHS AUS BRB MDA RUS ARG ROM UKR PER NIC GBR SUR FRA ZAF PRT TTO USA JPN DEU ITA CHE -. 893699 CZE LUX -. 246179 e( AV_INF | X ) 1. 48963 28
Original Sin and Monetary Credibility n n n Low inflation seems to be a necessary but not sufficient condition for escaping Original Sin Results are robust to longer lags (1970 s) They are robust to instrumenting inflation with an index of CB independence 29
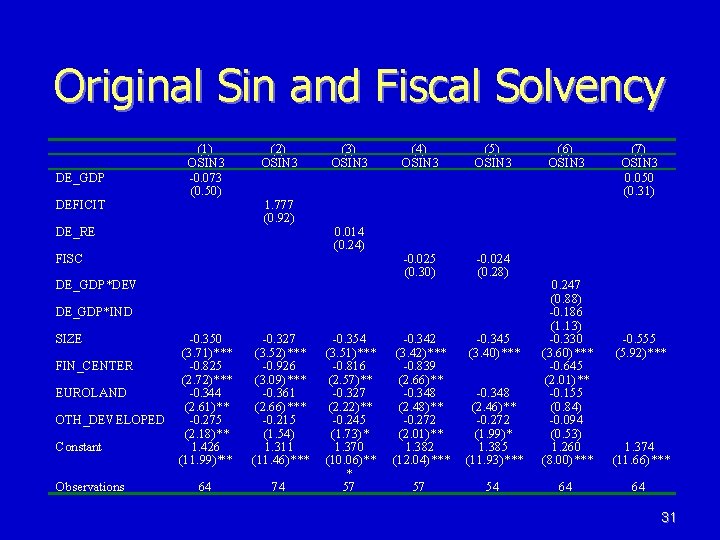
Original Sin and Fiscal Solvency n n A government with weak fiscal accounts has an incentive to debase its currency in order to erode the value of its real obligations (Lucas and Stokey, 1983) Corsetti and Mackowiack (2002) find that there is a vicious circle in which, in the presence of weak public finances, a large stock of foreign currency debt limits the ability to borrow in domestic currency 30
Original Sin and Fiscal Solvency DE_GDP DEFICIT (1) OSIN 3 -0. 073 (0. 50) DE_RE (2) OSIN 3 1. 777 (0. 92) FISC (3) OSIN 3 0. 014 (0. 24) DE_GDP*DEV (4) OSIN 3 (5) OSIN 3 -0. 025 (0. 30) -0. 024 (0. 28) FIN_CENTER EUROLAND OTH_DEVELOPED Constant Observations -0. 350 (3. 71)*** -0. 825 (2. 72)*** -0. 344 (2. 61)** -0. 275 (2. 18)** 1. 426 (11. 99)*** -0. 327 (3. 52)*** -0. 926 (3. 09)*** -0. 361 (2. 66)*** -0. 215 (1. 54) 1. 311 (11. 46)*** 64 74 -0. 354 (3. 51)*** -0. 816 (2. 57)** -0. 327 (2. 22)** -0. 245 (1. 73)* 1. 370 (10. 06)** * 57 -0. 342 (3. 42)*** -0. 839 (2. 66)** -0. 348 (2. 48)** -0. 272 (2. 01)** 1. 382 (12. 04)*** -0. 345 (3. 40)*** 57 (7) OSIN 3 0. 050 (0. 31) -0. 348 (2. 46)** -0. 272 (1. 99)* 1. 385 (11. 93)*** 0. 247 (0. 88) -0. 186 (1. 13) -0. 330 (3. 60)*** -0. 645 (2. 01)** -0. 155 (0. 84) -0. 094 (0. 53) 1. 260 (8. 00)*** 1. 374 (11. 66)*** 54 64 64 DE_GDP*IND SIZE (6) OSIN 3 -0. 555 (5. 92)*** 31
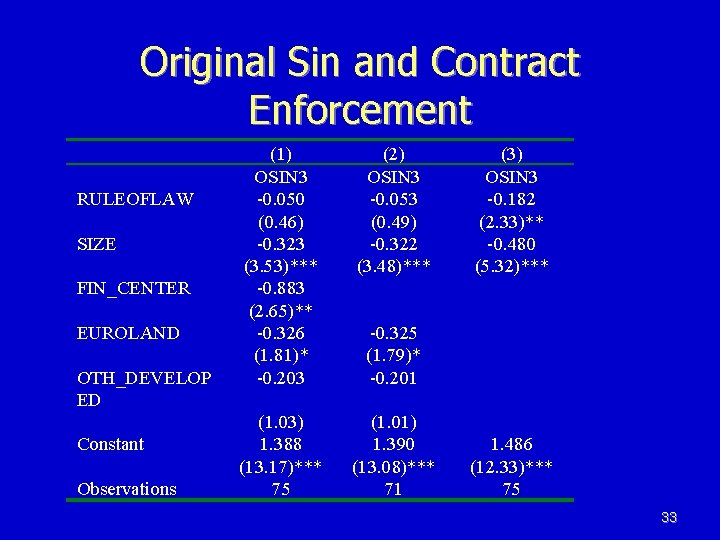
Original Sin and Contract Enforcement n n n Investors are reluctant to lend in countries where the institutions designed to enforce their claims are weak Chamon (2002) and Aghion, Bacchetta and Banerjee (2001) show that if depreciation and default risk are correlated and, if in case of default, assets are divided among creditors in proportion to their nominal claims, domestic currency market will disappear This problem could be solved if courts could enforce complicated contracts that distinguish among creditors of different seniority 32
Original Sin and Contract Enforcement RULEOFLAW SIZE FIN_CENTER EUROLAND OTH_DEVELOP ED Constant Observations (1) OSIN 3 -0. 050 (0. 46) -0. 323 (3. 53)*** -0. 883 (2. 65)** -0. 326 (1. 81)* -0. 203 (2) OSIN 3 -0. 053 (0. 49) -0. 322 (3. 48)*** (1. 03) 1. 388 (13. 17)*** 75 (1. 01) 1. 390 (13. 08)*** 71 (3) OSIN 3 -0. 182 (2. 33)** -0. 480 (5. 32)*** -0. 325 (1. 79)* -0. 201 1. 486 (12. 33)*** 75 33
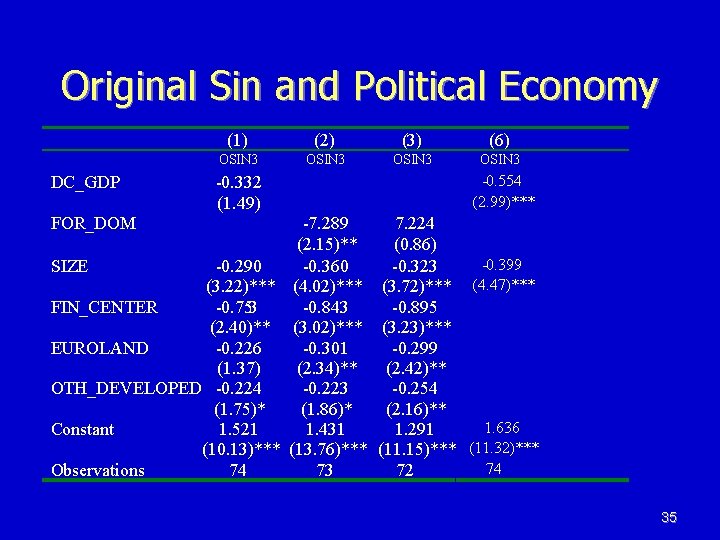
Original Sin and Political Economy n n Original sin could be due to the absence of a domestic constituency of local currency debtholders prepared to penalize a government that debase the currency Tirole (2002) suggests that Original Sin may arise from the government’s inability to commit to protect the rights of foreigners 34
Original Sin and Political Economy DC_GDP FOR_DOM (1) (2) (3) (6) OSIN 3 -0. 332 (1. 49) -7. 289 (2. 15)** SIZE -0. 290 -0. 360 (3. 22)*** (4. 02)*** FIN_CENTER -0. 753 -0. 843 (2. 40)** (3. 02)*** EUROLAND -0. 226 -0. 301 (1. 37) (2. 34)** OTH_DEVELOPED -0. 224 -0. 223 (1. 75)* (1. 86)* Constant 1. 521 1. 431 (10. 13)*** (13. 76)*** Observations 74 73 -0. 554 (2. 99)*** 7. 224 (0. 86) -0. 399 -0. 323 (3. 72)*** (4. 47)*** -0. 895 (3. 23)*** -0. 299 (2. 42)** -0. 254 (2. 16)** 1. 636 1. 291 (11. 15)*** (11. 32)*** 74 72 35
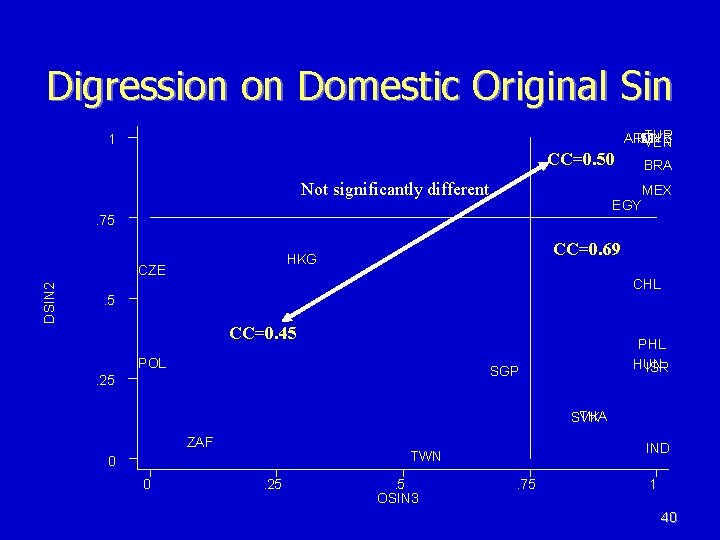
Digression on Domestic Original Sin n n It may be the case that the previous regressions do not yield any result because we are not able to measure the “real” size of the domestic local currency market This would require building a measure of domestic original sin and looking at how it relates to international original sin 36
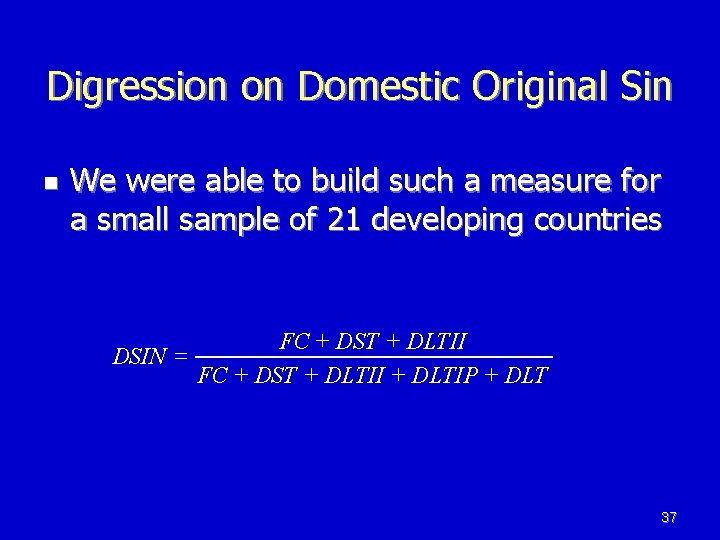
Digression on Domestic Original Sin n We were able to build such a measure for a small sample of 21 developing countries FC + DST + DLTII DSIN = FC + DST + DLTII + DLTIP + DLT 37
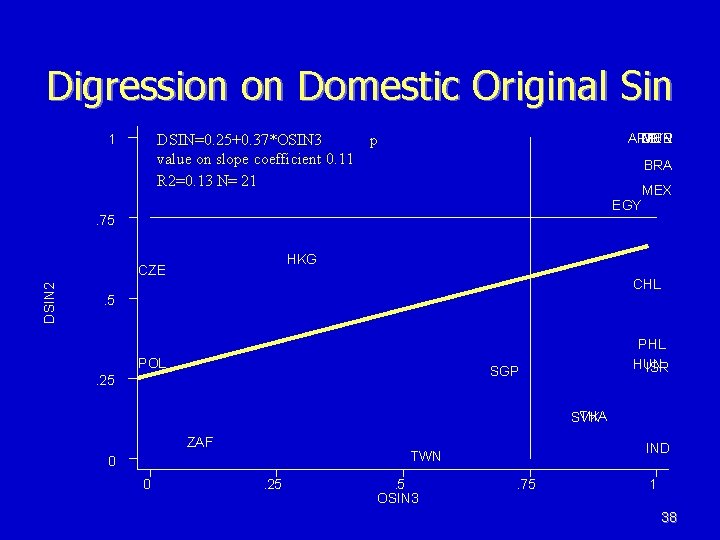
Digression on Domestic Original Sin DSIN=0. 25+0. 37*OSIN 3 value on slope coefficient 0. 11 R 2=0. 13 N= 21 1 ARG IDN MYS VEN TUR p BRA EGY . 75 HKG CZE DSIN 2 MEX CHL . 5 POL PHL HUN ISR SGP . 25 THA SVK ZAF 0 IND TWN 0. 25 . 5 OSIN 3 . 75 1 38
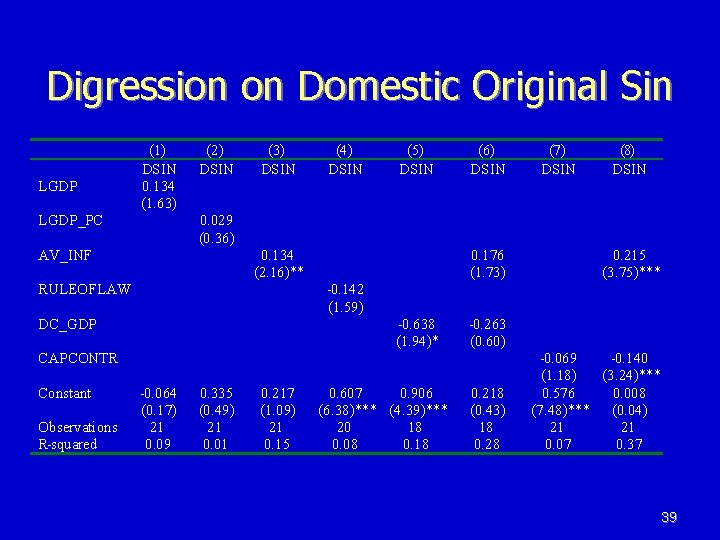
Digression on Domestic Original Sin LGDP (1) DSIN 0. 134 (1. 63) LGDP_PC (2) DSIN (3) DSIN (4) DSIN (5) DSIN (6) DSIN 0. 134 (2. 16)** RULEOFLAW 0. 176 (1. 73) 0. 215 (3. 75)*** -0. 142 (1. 59) DC_GDP -0. 638 (1. 94)* -0. 263 (0. 60) CAPCONTR Observations R-squared (8) DSIN 0. 029 (0. 36) AV_INF Constant (7) DSIN -0. 064 (0. 17) 21 0. 09 0. 335 (0. 49) 21 0. 01 0. 217 (1. 09) 21 0. 15 0. 607 0. 906 (6. 38)*** (4. 39)*** 20 18 0. 08 0. 18 0. 218 (0. 43) 18 0. 28 -0. 069 -0. 140 (1. 18) (3. 24)*** 0. 576 0. 008 (7. 48)*** (0. 04) 21 21 0. 07 0. 37 39
Digression on Domestic Original Sin 1 CC=0. 50 Not significantly different DSIN 2 BRA EGY . 75 MEX CC=0. 69 HKG CZE TUR ARG IDN MYS VEN CHL . 5 CC=0. 45 POL PHL HUN ISR SGP . 25 THA SVK ZAF 0 IND TWN 0. 25 . 5 OSIN 3 . 75 1 40
Digression on Domestic Original Sin n n There is some (weak) evidence that capital controls may help in reducing domestic original sin However, it looks as if capital controls are bad for international original sin 41
Back to International Original Sin
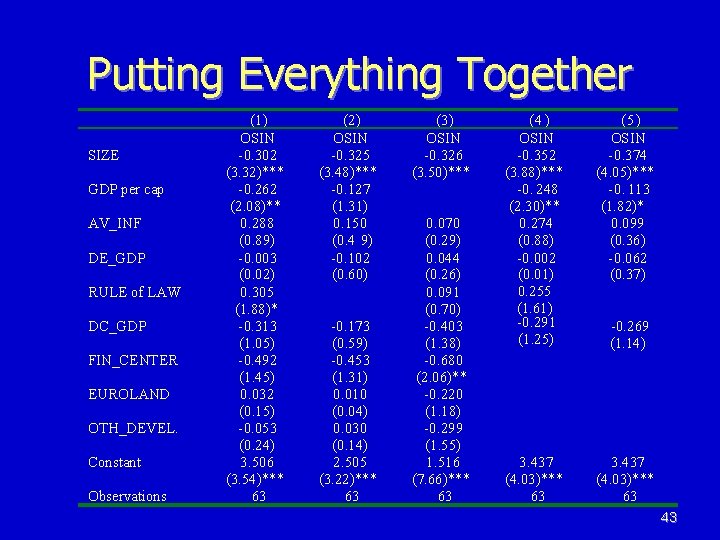
Putting Everything Together SIZE GDP per cap AV_INF DE_GDP RULE of LAW DC_GDP FIN_CENTER EUROLAND OTH_DEVEL. Constant Observations (1) OSIN -0. 302 (3. 32)*** -0. 262 (2. 08)** 0. 288 (0. 89) -0. 003 (0. 02) 0. 305 (1. 88)* -0. 313 (1. 05) -0. 492 (1. 45) 0. 032 (0. 15) -0. 053 (0. 24) 3. 506 (3. 54)*** 63 (2) OSIN -0. 325 (3. 48)*** -0. 127 (1. 31) 0. 150 (0. 4 9) -0. 102 (0. 60) -0. 173 (0. 59) -0. 453 (1. 31) 0. 010 (0. 04) 0. 030 (0. 14) 2. 505 (3. 22)*** 63 (3) OSIN -0. 326 (3. 50)*** 0. 070 (0. 29) 0. 044 (0. 26) 0. 091 (0. 70) -0. 403 (1. 38) -0. 680 (2. 06)** -0. 220 (1. 18) -0. 299 (1. 55) 1. 516 (7. 66)*** 63 (4 ) OSIN -0. 352 (3. 88)*** -0. 248 (2. 30)** 0. 274 (0. 88) -0. 002 (0. 01) 0. 255 (1. 61) -0. 291 (1. 25) (5 ) OSIN -0. 374 (4. 05)*** -0. 113 (1. 82)* 0. 099 (0. 36) -0. 062 (0. 37) 3. 437 (4. 03)*** 63 -0. 269 (1. 14) 43
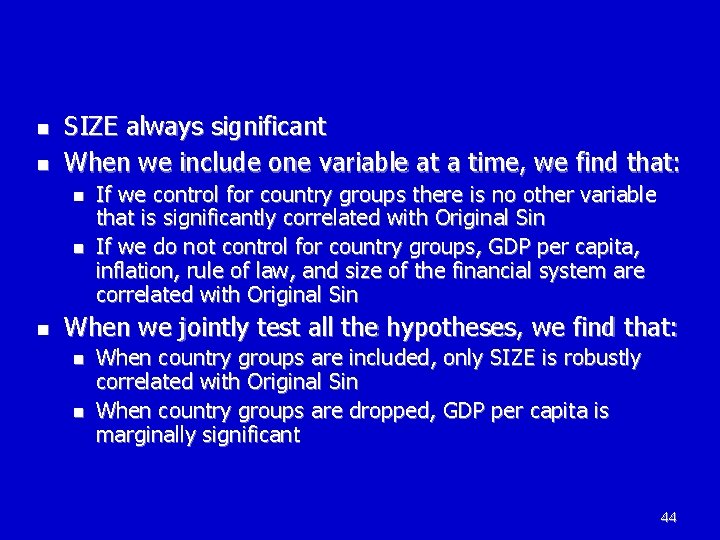
n n SIZE always significant When we include one variable at a time, we find that: n n n If we control for country groups there is no other variable that is significantly correlated with Original Sin If we do not control for country groups, GDP per capita, inflation, rule of law, and size of the financial system are correlated with Original Sin When we jointly test all the hypotheses, we find that: n n When country groups are included, only SIZE is robustly correlated with Original Sin When country groups are dropped, GDP per capita is marginally significant 44
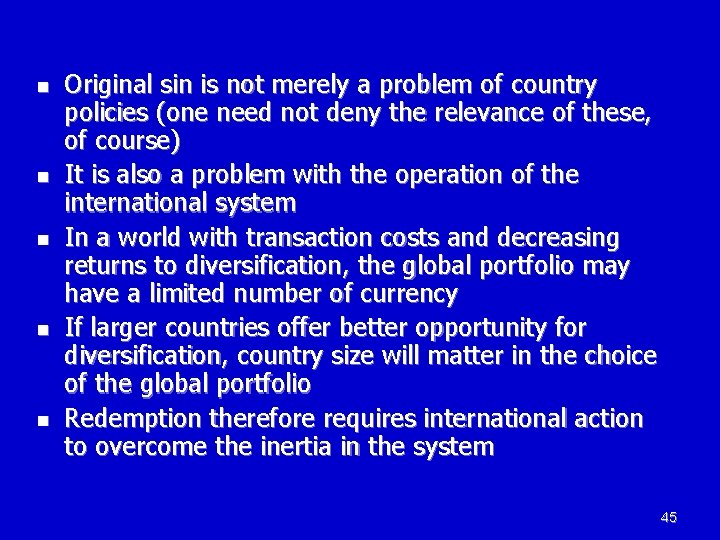
n n n Original sin is not merely a problem of country policies (one need not deny the relevance of these, of course) It is also a problem with the operation of the international system In a world with transaction costs and decreasing returns to diversification, the global portfolio may have a limited number of currency If larger countries offer better opportunity for diversification, country size will matter in the choice of the global portfolio Redemption therefore requires international action to overcome the inertia in the system 45
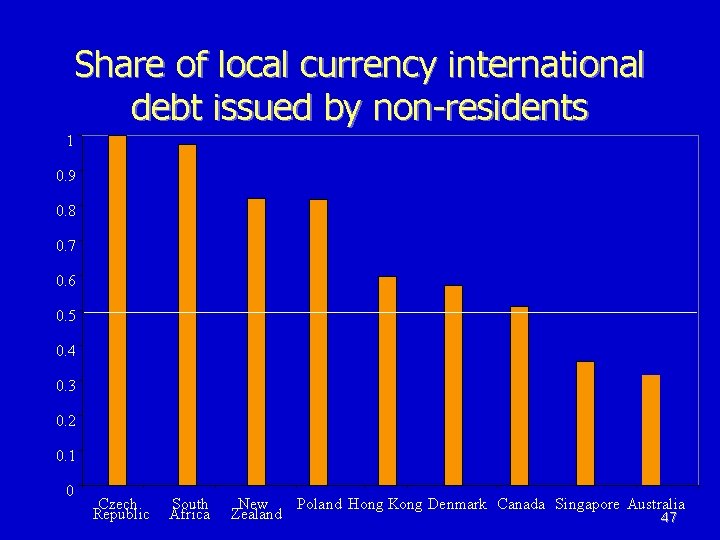
Lessons from outliers n An interesting fact about the international issuance of bonds in exotic currency is that it is mostly done by non-residents who then swap the debt-service obligation back to US dollar 46
Share of local currency international debt issued by non-residents 1 0. 9 0. 8 0. 7 0. 6 0. 5 0. 4 0. 3 0. 2 0. 1 0 Czech Republic South Africa New Poland Hong Kong Denmark Canada Singapore Australia Zealand 47
Lessons from outliers n n An interesting fact about the international issuance of bonds in exotic currency is that it is mostly done by non-residents who then swap the debt-service obligation back to US dollar They do this to reduce cost of funding n n n But, why is this complex operation cheaper than borrowing directly in dollar? A possibility is that the market values the possibility of separating currency and credit risk The IFIs have a natural hedge and could play a role in expanding this market 48
Conclusions n n Original Sin is a widespread phenomenon It has costs n n n Limits the ability to conduct monetary policy Increases volatility Increases credit risk It cannot be easily explained by weak policies or institutions Country size seems to be important The IFIs could play a role in reducing Original Sin 49
The Pain and the Mystery of Original Sin Barry Eichengreen Ricardo Hausmann Ugo Panizza 50
Original Sin and Credit Ratings Original Sin Debt/GDP advanced Debt/GDP developing Debt/GDP high rating Debt/GDP low rating High rating (1) RATING (2) RATING 4. 814 (2. 30)** -8. 627 (4. 96)*** -2. 659 (1. 24) -3. 671 (2. 34)** -9. 027 (5. 78)*** (3) RATING (4) RATING 5. 783 (3. 10)*** -9. 207 (5. 85)*** -1. 511 (0. 83) -4. 438 (3. 36)*** 8. 917 (6. 60)*** GDP per capita Ex Debt/GDP Constant 13. 999 19. 757 14. 138 11. 028 (15. 60)*** (15. 27)*** (17. 51)*** (15. 03)*** Observations 61 61 DEG_DEV=DEG_ADV F(1, 59)=41. 31 F(1, 58)=0. 14 F(1, 59)=62. 7 F(1, 58)=1. 69 DEG_HR=DEG_LR P=0. 000 P=0. 705 P=0. 000 P=0. 199 (5) RATING -5. 100 (3. 38)*** -1. 553 (1. 31) -3. 557 (2. 66)** (6) RATING -4. 751 (3. 32)*** -2. 451 (2. 05)** -2. 475 (1. 84)* -3. 004 (2. 38)** 2. 663 (6. 71)*** 2. 252 (1. 50) -6. 314 (1. 58) 56 1. 936 (4. 00)*** 1. 751 (1. 22) 1. 606 (0. 32) 56 51