PCD Impact Assessment on Food Security in Tanzania
- Slides: 82
PCD Impact Assessment on Food Security in Tanzania Assessing Linkages between OECD Policies and Tanzania’s Agro-Food Systems and Food Security Conditions Workshop 2, Dar Es Salaam, 27/11/2014 With support from the Ministry for Foreign Affairs of Finland ECDPM Page 1
INTRODUCTION AND REMINDER ECDPM Page 2
Policy Coherence for Development: Concepts • Non-development cooperation policies of OECD countries (e. g. , agriculture, trade, international investment, tax, science and technology, migration, etc. ) can have (negative/positive) spillover effects on developing countries • Those effects can be incoherent with development objectives (whether they are the objectives of a particular developing country, a region, developing countries as a whole, or the objectives of development cooperation policies of OECD countries) • Different dimensions of development: economic growth, poverty reduction, food security, health, human development, environmental sustainability, etc. ECDPM Page 3
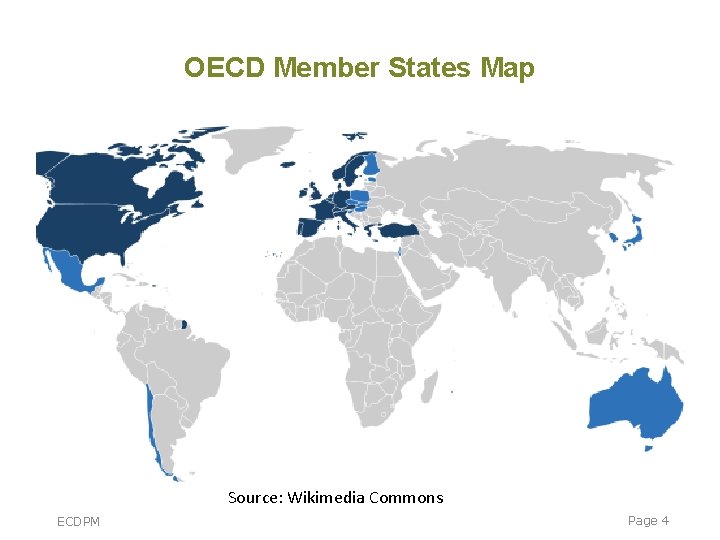
OECD Member States Map Source: Wikimedia Commons ECDPM Page 4
Policy Coherence for Development: Concepts • European Union: ‘The EU seeks to minimise contradictions and to build synergies between policies other than development cooperation that have an impact on developing countries, for the benefit of overseas development’ • OECD: ‘The pursuit of development objectives through the systematic promotion of mutually reinforcing policy actions on the part of both OECD and development countries’ • Two implications: “Do not harm”; “do good” – Ensure that all policies are “development-friendly” – Promote synergies among policies with regards to development objectives ECDPM Page 5
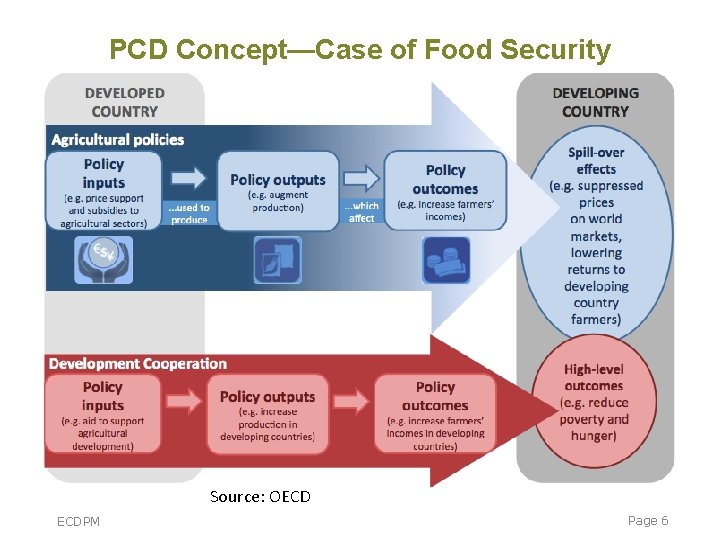
PCD Concept—Case of Food Security Source: OECD ECDPM Page 6
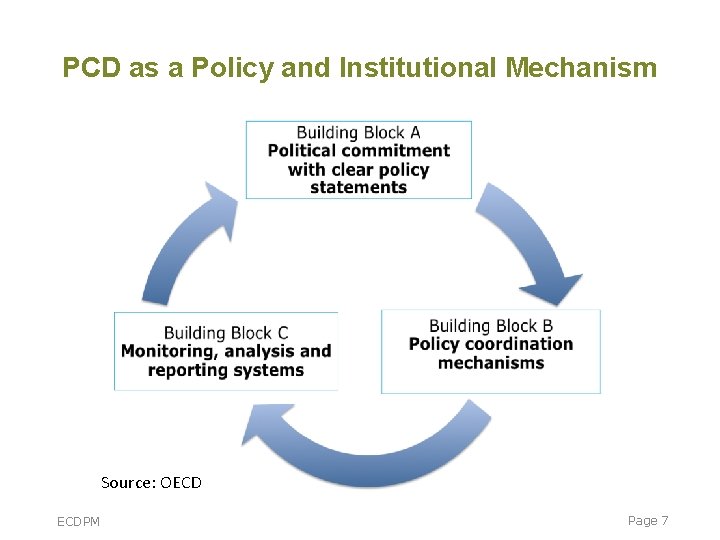
PCD as a Policy and Institutional Mechanism Source: OECD ECDPM Page 7
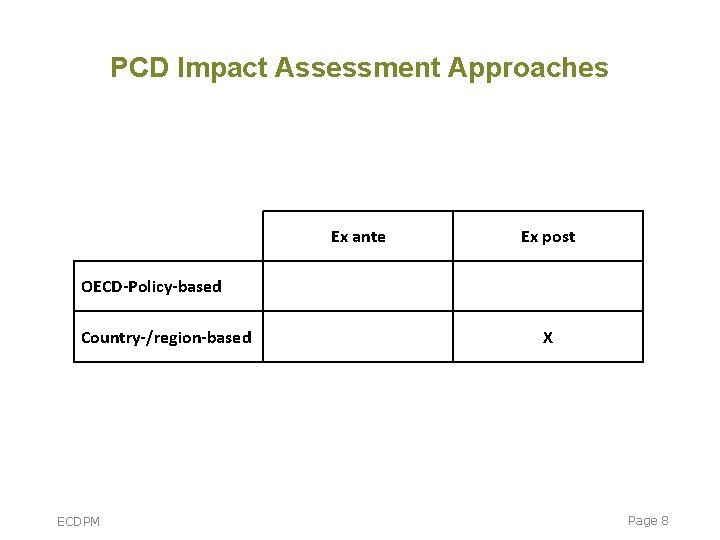
PCD Impact Assessment Approaches Ex ante Ex post OECD-Policy-based Country-/region-based ECDPM X Page 8
Our PCD Impact Assessment Approach • Developing a methodology for ex post, country-level PCD assessments with a focus on food security • Involving local and OECD stakeholders (participatory approach) • Supporting OECD Development Assistance Committee in improving PCD, fostering policy change and addressing trade-offs between domestic and international goals based on evidence • Supporting developing country actors (governments, private sector and civil society) in understanding OECD policies’ impacts on their countries, advocating for improved PCD and formulating policy responses ECDPM Page 9
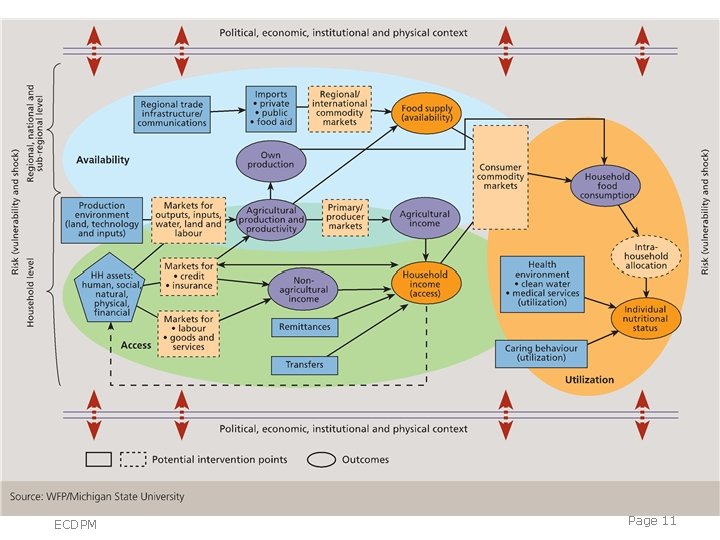
Food Security Analysis Framework • • Food availability Access to food Food utilization Stability ECDPM Page 10
ECDPM Page 11
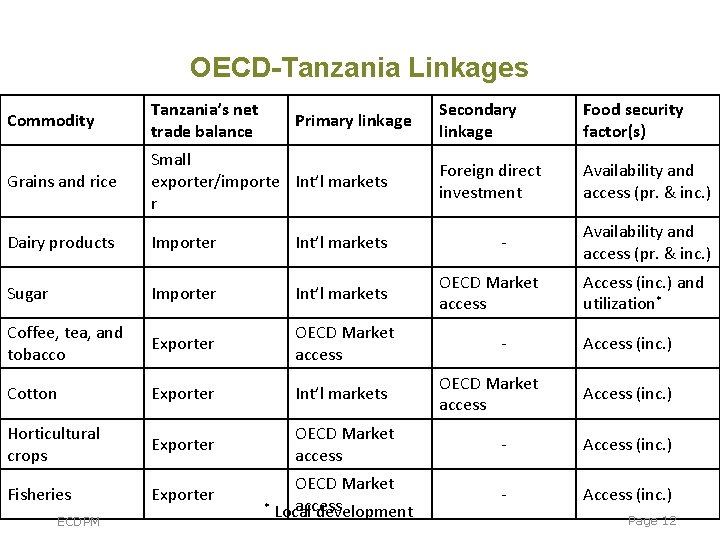
OECD-Tanzania Linkages Commodity Tanzania’s net trade balance Grains and rice Small exporter/importe Int’l markets r Dairy products Importer Int’l markets Sugar Importer Int’l markets Coffee, tea, and tobacco Exporter OECD Market access Cotton Exporter Int’l markets Horticultural crops Exporter OECD Market access Fisheries Exporter ECDPM Primary linkage OECD Market access * Local development Secondary linkage Food security factor(s) Foreign direct investment Availability and access (pr. & inc. ) OECD Market access Availability and access (pr. & inc. ) Access (inc. ) and utilization* Access (inc. ) - Access (inc. ) Page 12
OECD-Tanzania Linkages • Investigating changes in OECD policies and market outcomes over an adequate period of time and identifying negative/positive spillover effects • Taking into account contextual changes (e. g. , domestic/regional market and policy changes, global market and policy changes, etc. ) ECDPM Page 13
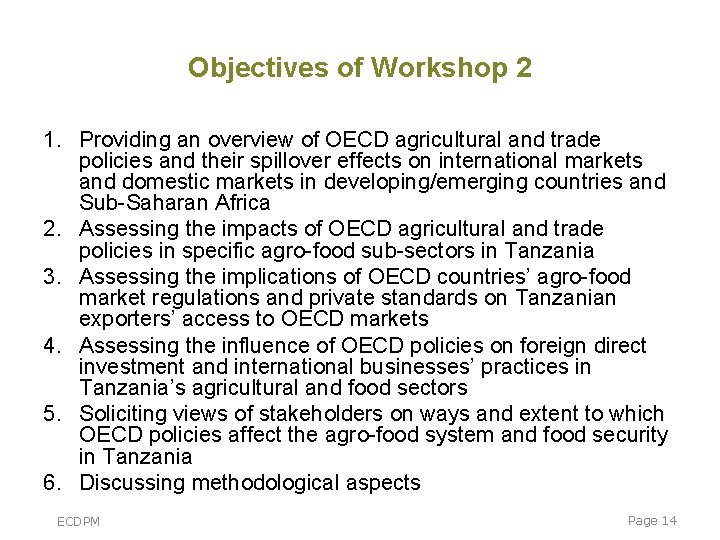
Objectives of Workshop 2 1. Providing an overview of OECD agricultural and trade policies and their spillover effects on international markets and domestic markets in developing/emerging countries and Sub-Saharan Africa 2. Assessing the impacts of OECD agricultural and trade policies in specific agro-food sub-sectors in Tanzania 3. Assessing the implications of OECD countries’ agro-food market regulations and private standards on Tanzanian exporters’ access to OECD markets 4. Assessing the influence of OECD policies on foreign direct investment and international businesses’ practices in Tanzania’s agricultural and food sectors 5. Soliciting views of stakeholders on ways and extent to which OECD policies affect the agro-food system and food security in Tanzania 6. Discussing methodological aspects ECDPM Page 14
Q&A • According to you, what does Policy Coherence for Development mean for Tanzania? ECDPM Page 15
MODULE 3 PART 1 OECD domestic agricultural policies and spillover effects on Tanzania through international markets Overview of OECD domestic agricultural policies and spillover effects on international markets ECDPM Page 16
Objectives 1/ Have a common understanding of the global context in which Tanzania operates Þ Reality check on the recent evolutions globally and in Tanzania 2/ Present assumptions on theoretical impact pathways through international prices and evidence of their relevance in the litterature ECDPM Page 17
Methodology • So far desk-based research – Official data (OECD etc. ) – Academic literarure and « grey » literature (reports) • Limitations: – Limited up to date data – Publications on very specific commodities or dimensions (2008 crisis) =>Risk of using specific cases as general lessons => Your feedbacks are key ECDPM Page 18
Initial assumptions: Impact of OECD policies through intl markets Assumption 1: OECD policies act as discentives to produce food for Tanzanian farmers, lowering supply of locally produced food and income of farmers Assumption 2: OECD policies act as barriers to trade (through tariffs) reducing the quantity exported to OECD markets by Tanzanian farmers, lowering their income ECDPM Page 19
Assumption 1: discentives to supply of locally produced food Channel 1: => depress price levels for Tanzanian farmers Through competition from low cost imports ECDPM Page 20
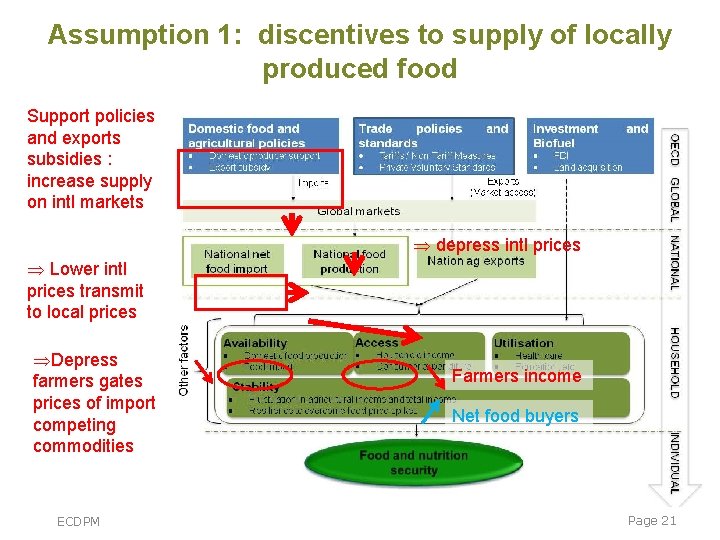
Assumption 1: discentives to supply of locally produced food Support policies and exports subsidies : increase supply on intl markets Þ depress intl prices Þ Lower intl prices transmit to local prices ÞDepress farmers gates prices of import competing commodities ECDPM Farmers income Net food buyers Page 21
Assumption 1: discentives to supply of locally produced food Channel 2: => increase price volatility which act as a discentive for farmers to invest in ag production ECDPM Page 22
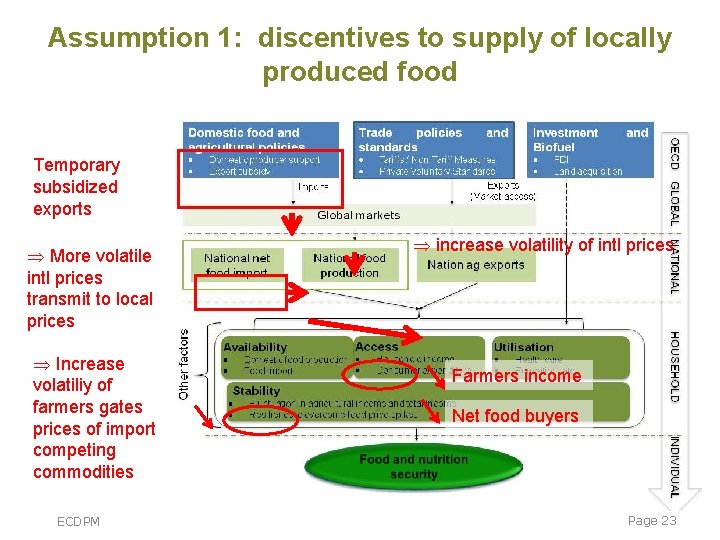
Assumption 1: discentives to supply of locally produced food Temporary subsidized exports Þ More volatile intl prices transmit to local prices Þ Increase volatiliy of farmers gates prices of import competing commodities ECDPM Þ increase volatility of intl prices Farmers income Net food buyers Page 23
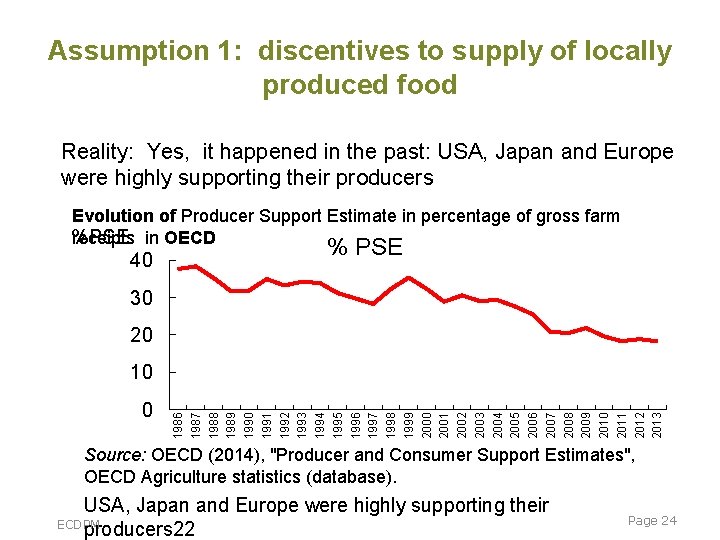
Assumption 1: discentives to supply of locally produced food Reality: Yes, it happened in the past: USA, Japan and Europe were highly supporting their producers Evolution of Producer Support Estimate in percentage of gross farm receipts in OECD %PSE 40 % PSE 30 20 0 1986 1987 1988 1989 1990 1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 10 Source: OECD (2014), "Producer and Consumer Support Estimates", OECD Agriculture statistics (database). USA, Japan and Europe were highly supporting their ECDPM producers 22 Page 24
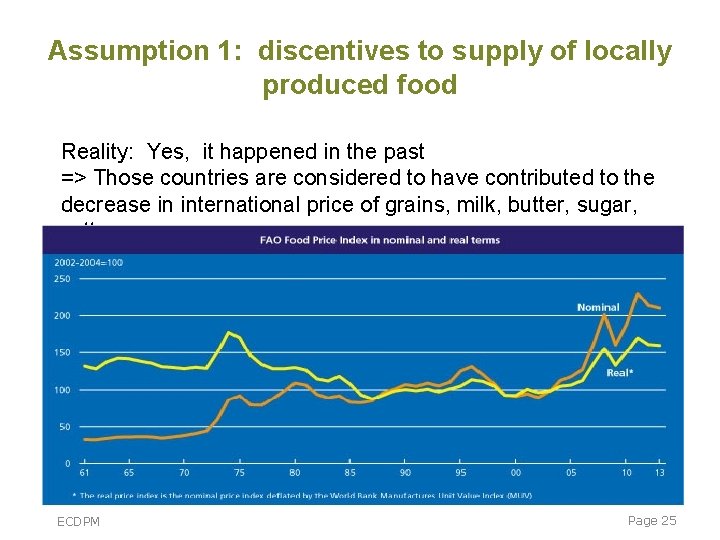
Assumption 1: discentives to supply of locally produced food Reality: Yes, it happened in the past => Those countries are considered to have contributed to the decrease in international price of grains, milk, butter, sugar, cotton ECDPM Page 25
Assumption 1: discentives to supply of locally produced food Yes, but - Since then reduction of supports by OECD, Globally increase in non OECD emerging economies (China, Ind - Since 2000 s increase in international prices (3 spikes, : 2008, 2010, - has since become self sufficient in maize and rice lack of market integration within - local prices in Tanzania have been shown to be Tanzania and price higher than intl markets prices transmission with Tanzania more volatile intl Þ Availability and accessibility problems of grains in Tanzania are due DOMESTIC factors and inefficiencies ECDPM Page 26
Assumption 1: discentives to supply of locally produced food Yes, but REALITY CHECK: Regarding international prices of grains, no case to accuse OECD policies of incoherence nowadays ÞCoton USA ? ECDPM Page 27
Assumption 2: Reduced market access for exporters Channel 1 Barriers to entrance in the OECD markets - tariffs - non tariff measures ECDPM Page 28
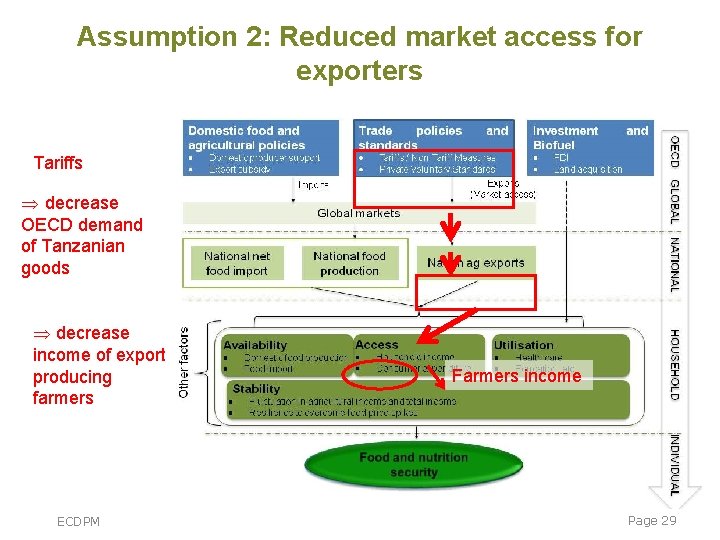
Assumption 2: Reduced market access for exporters Tariffs Þ decrease OECD demand of Tanzanian goods Þ decrease income of export producing farmers ECDPM Farmers income Page 29
Assumption 2: Reduced market access for exporters Channel 2 Increase of tariff with stage of processing in the value chain ( « tariff escalation » ) => Disencentives to transform products locally and capture higher share of value addition ECDPM Page 30
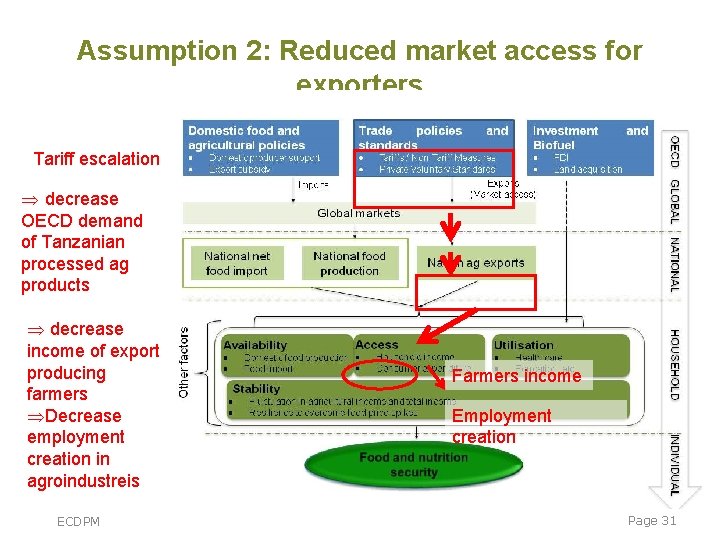
Assumption 2: Reduced market access for exporters Tariff escalation Þ decrease OECD demand of Tanzanian processed ag products Þ decrease income of export producing farmers ÞDecrease employment creation in agroindustreis ECDPM Farmers income Employment creation Page 31
Assumption 2: Reduced market access for exporters Yes, historically agricultural products more protected than other types of products But Tanzania has benefitted from preferences : - Historically from the EU as an ACP country (Lomé, Cotonou etc. ) -Since 2000 s from preferential agreements from other OECD countries as a LDC (EBA from EU, AGOA from USA etc. ) -=> Many preferential agreements: question is what is also provided to competitors ? -=> Example of sugar. ECDPM Page 32
CASE OF SUGAR IMPACTS OF OECD POLICIES ON TANZANIA’S SECTOR ECDPM Page 33
Tanzanian Sugar Sector • • A major agro-food sector Tanzania, a net importer of sugar Four large sugar factories, some new projects underway Low sugar cane yields relatively to Southern African producers and other Eastern African producers (lack of irrigation, low-performance varieties, low fertiliser use and other production and marketing factors) • Privatization and efforts to rehabilitate the sector in the 1990 s led to productivity enhancement and production increase ECDPM Page 34
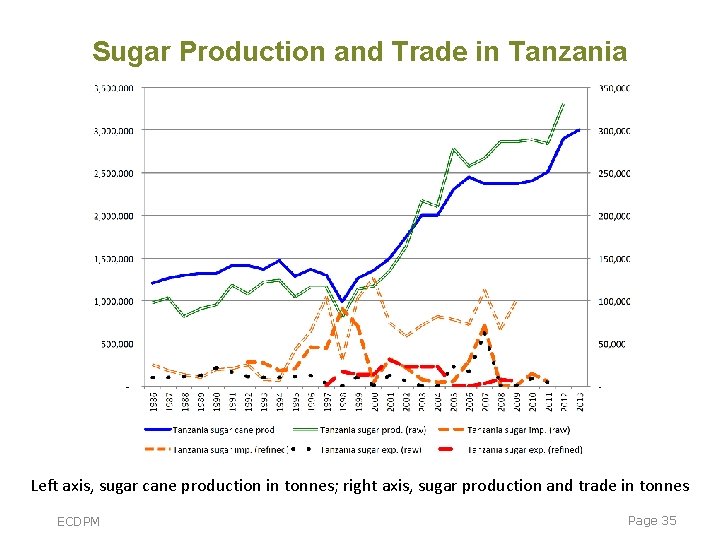
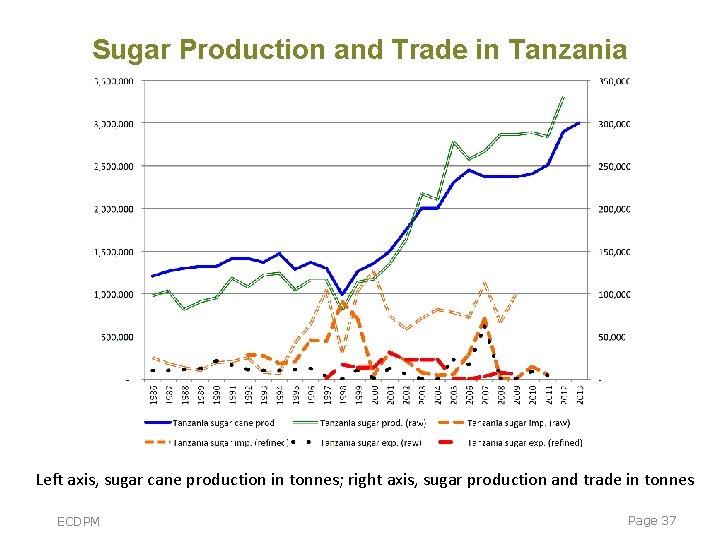
Sugar Production and Trade in Tanzania Left axis, sugar cane production in tonnes; right axis, sugar production and trade in tonnes ECDPM Page 35
Sugar Trade • Tanzania exports sugar mostly to the EU under the EBA regime (10, 000 tonnes, but export licenses are difficult to obtain reportedly) • Import duties and quotas (licenses) • Large volumes of sugar imported illegally • Sugar factories have experience difficulty competing with cheap sugar imports, notably sugar from Latin America, Southern Africa, and some Asian exporters • Import surges/dumping cases in the late 1990 s and early 2000 s, incl. sugar from the EU among other origins • Need to strengthen capacity to implement countervailing duties and other safeguard measures ECDPM Page 36
Sugar Production and Trade in Tanzania Left axis, sugar cane production in tonnes; right axis, sugar production and trade in tonnes ECDPM Page 37
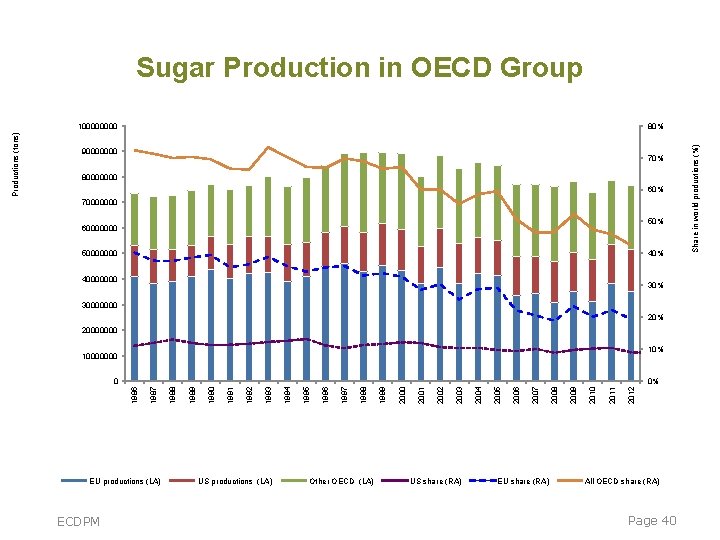
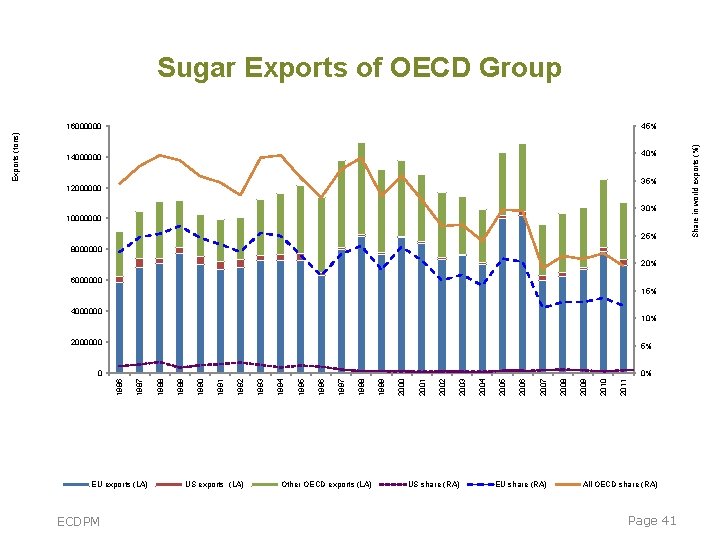
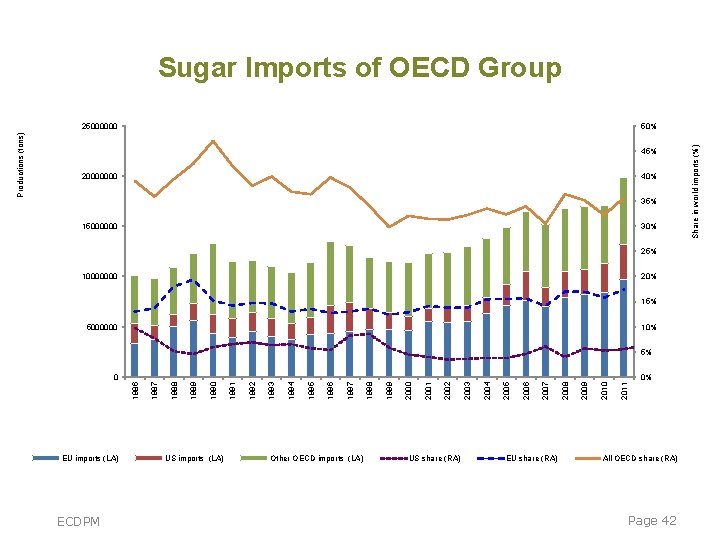
International Sugar Markets • 2/3 of world sugar production from Brazil, Australia, Cuba and Thailand • Other big producers: India, EU, and South Africa • Net exporting regions: Americas, Oceania • Net importing regions: Asia, Europe, Africa • Largest exporters: Brazil, EU, Australia, Cuba and Thailand • Largest importers: Russia, EU, and Japan • Concentrated sector; e. g. , EU imports done by a few multinational companies • About ⅓ of world sugar production is trade internationally • Most of international trade in sugar is done under trade agreements; residual trade thru spot markets; as a result (in addition to the fact that sugar cane is a perennial crop), this market is very volatile ECDPM Page 38
International Sugar Markets • Decline in international prices in the 1990 s (rise of Brazil as a producer and an exporter), rise in prices in the 2000 s; EU and US became net exporters after having been net importers (e. g. , in the 1970 s) ECDPM Page 39
Sugar Production in OECD Group 90000000 70% 80000000 60% 70000000 50% 60000000 50000000 40% 40000000 30% 30000000 20% 20000000 10% 10000000 EU productions (LA) ECDPM US productions (LA) Other OECD (LA) US share (RA) EU share (RA) 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 1996 1995 1994 1993 1992 1991 1990 1989 1988 0% 1987 0 All OECD share (RA) Page 40 Share in world productions (%) 80% 1986 Productions (tons) 10000
45% 14000000 40% 35% 12000000 30% 10000000 25% 8000000 20% 6000000 15% 4000000 10% EU exports (LA) ECDPM US exports (LA) Other OECD exports (LA) US share (RA) EU share (RA) 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 1996 1995 1994 1993 1992 1991 1990 0% 1989 0 1988 5% 1987 2000000 All OECD share (RA) Page 41 Share in world exports (%) 16000000 1986 Exports (tons) Sugar Exports of OECD Group
Sugar Imports of OECD Group 45% 20000000 40% 35% 15000000 30% 25% 10000000 20% 15% 5000000 10% 5% EU imports (LA) ECDPM US imports (LA) Other OECD imports (LA) US share (RA) EU share (RA) 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 1996 1995 1994 1993 1992 1991 1990 1989 1988 0% 1987 0 All OECD share (RA) Page 42 Share in world imports (%) 50% 1986 Productions (tons) 25000000
International Sugar Markets • Sugar trade regimes – EU’s preferential tariff and quota trade regimes: • EU Special Preferential Sugar (SPS) arrangements, bilateral agreements with ACP countries, annual TRQ for raw cane sugar • Sugar protocol of the EU-ACP Cotonou Partnership Agreement, TRQ with guaranteed prices – US’ preferential tariff and quota regime (Puerto Rico, Philippines and other countries with whom the US has special trade relations—not for EA countries and excl. other low-cost producers) – Commonwealth Sugar Agreement: TRQ for exports to UK until Lomé Agreement Sugar Protocol • Other international agreements for sugar, incl. bilateral agreements (e. g. , Cuba-Russia Sugar Agreement) • ECDPM WTO MFN regime (residual spot market) Page 43
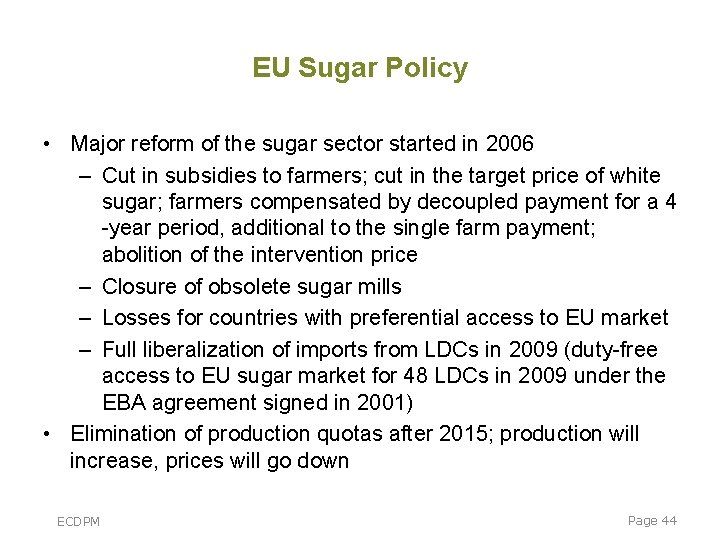
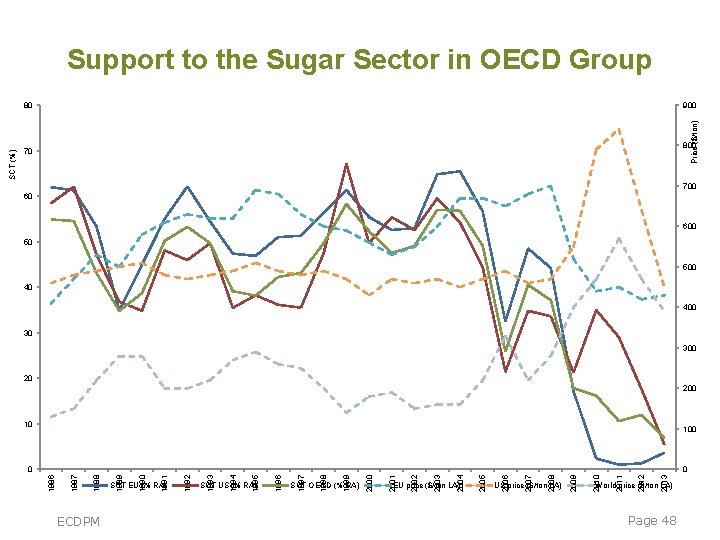
EU Sugar Policy • Major reform of the sugar sector started in 2006 – Cut in subsidies to farmers; cut in the target price of white sugar; farmers compensated by decoupled payment for a 4 -year period, additional to the single farm payment; abolition of the intervention price – Closure of obsolete sugar mills – Losses for countries with preferential access to EU market – Full liberalization of imports from LDCs in 2009 (duty-free access to EU sugar market for 48 LDCs in 2009 under the EBA agreement signed in 2001) • Elimination of production quotas after 2015; production will increase, prices will go down ECDPM Page 44
EU Sugar Policy ECDPM Quantities in tonnes Page 45
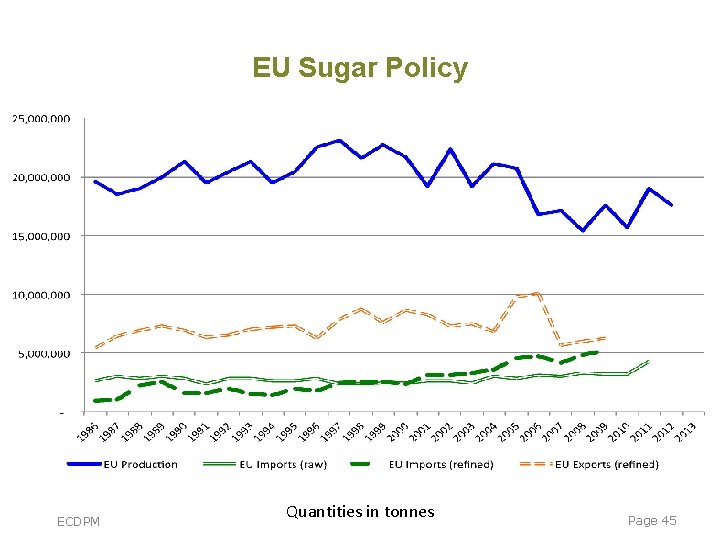
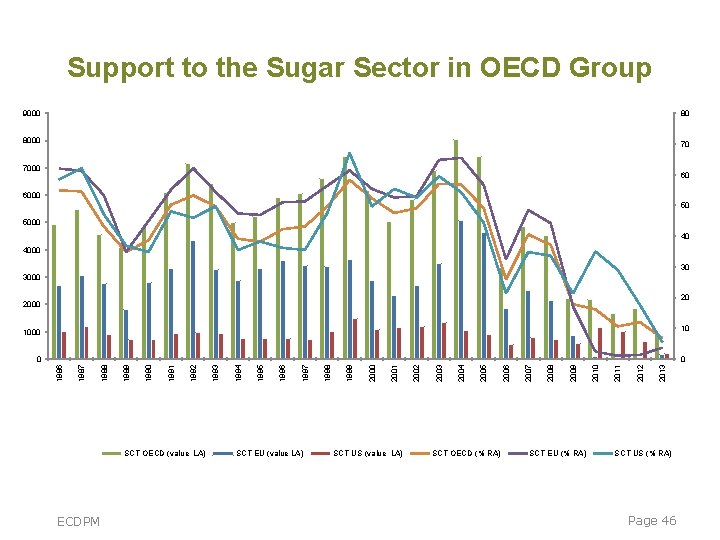
Support to the Sugar Sector in OECD Group 9000 80 8000 70 7000 60 6000 50 5000 40 4000 30 3000 20 2000 10 1000 SCT OECD (value LA) ECDPM SCT EU (value LA) SCT US (value LA) SCT OECD (% RA) SCT EU (% RA) 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 1996 1995 1994 1993 1992 1991 1990 1989 1988 1987 0 1986 0 SCT US (% RA) Page 46
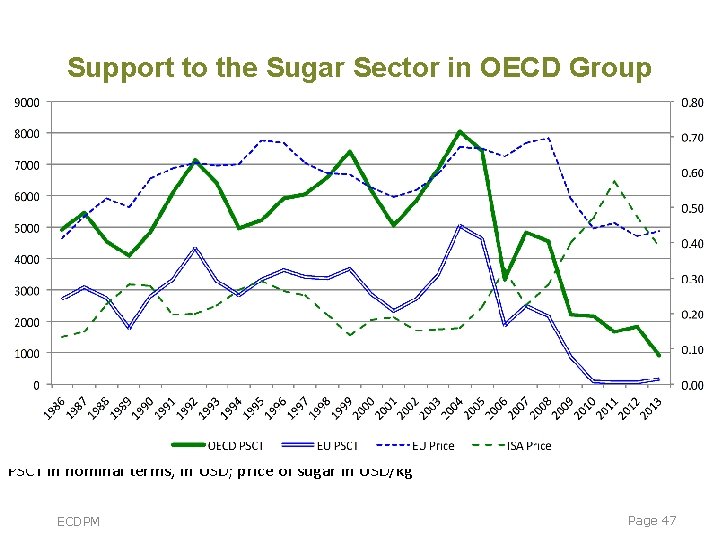
Support to the Sugar Sector in OECD Group PSCT in nominal terms, in USD; price of sugar in USD/kg ECDPM Page 47
Support to the Sugar Sector in OECD Group Price ($/ton) 900 800 70 700 60 600 50 500 40 400 30 300 20 200 10 100 ECDPM 2013 2012 2011 2010 US price ($/ton LA) 2009 2008 2007 2006 EU price ($/ton LA) 2005 2004 2003 2002 2001 SCT OECD (% RA) 2000 1999 1998 1997 SCT US (% RA) 1996 1995 1994 1993 SCT EU (% RA) 1992 1991 1990 1989 1988 0 1987 0 1986 SCT (%) 80 World price ($/ton LA) Page 48
Sugar Markets in Africa • Southern African producers more cost-competitive than Eastern and Central Africa producers – Malawi, Mauritius, Sudan, Zambia, Zimbabwe, South Africa: lowcost sugar producers (SADC more competitive than EAC in general, production costs relatively high in Eastern Africa) – Kenya, Swaziland, and Tanzania: higher-cost producers (indebted sugar companies in Kenya and Tanzania in early 2000 s, late payments to farmers) • Regional market protection in the EAC customs union; tariff protection; sensitive industry • In the late 1990 s, near collapse of the industry in the region (period of low prices, consumer prices at or below sugar production costs); after that, development of safeguard measures; due to lack of policy planning and administrative capacities, the regional industry is still affected by cases of dumping (as of 2006); low-cost imports from Brazil, Southern Africa and Australia ECDPM Page 49
EU Development Assistance for the Sugar Sector • Sugar Protocol Accompanying Measures introduced as part of the 2006 reform; assistance package for ACP countries; 40 m euros • ACP Sugar Research and Innovation Programme, to fund research to enhance sugar productivity, diversify uses of sugar cane (biofuels, bio-fertilisers, bio-polymers, etc. ) and generally ensure that the sugar industry remains viable; about 20 m US$, mostly from EU, also from Australia, US and ACP countries ECDPM Page 50
Q&A ECDPM Page 51
MODULE 3 PART 2 OECD non-tariff measures and private standards Overview of OECD standards and implications for market access for Tanzania’s exports and food security conditions ECDPM Page 52
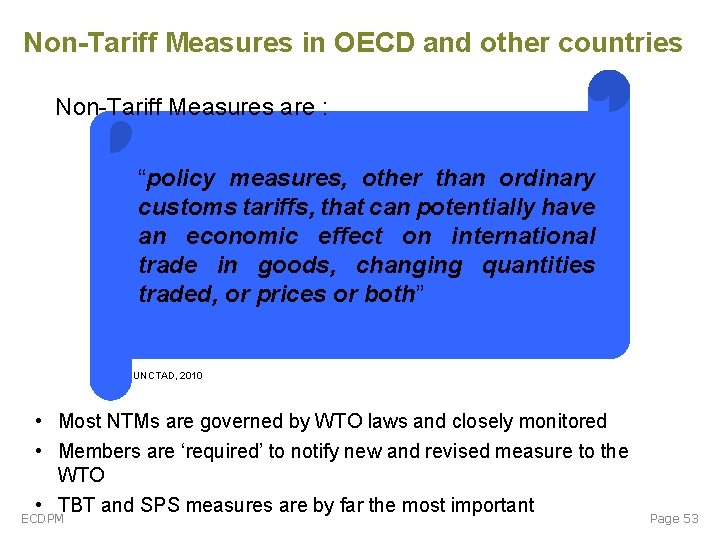
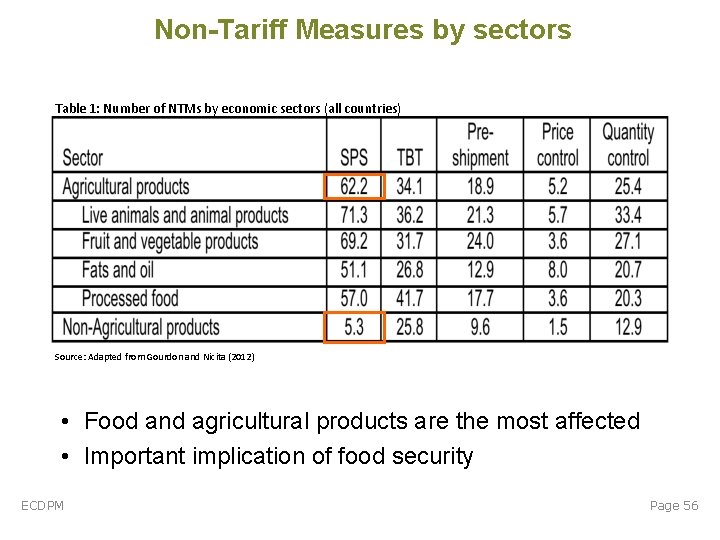
Non-Tariff Measures in OECD and other countries Non-Tariff Measures are : “policy measures, other than ordinary customs tariffs, that can potentially have an economic effect on international trade in goods, changing quantities traded, or prices or both” UNCTAD, 2010 • Most NTMs are governed by WTO laws and closely monitored • Members are ‘required’ to notify new and revised measure to the WTO • TBT and SPS measures are by far the most important ECDPM Page 53
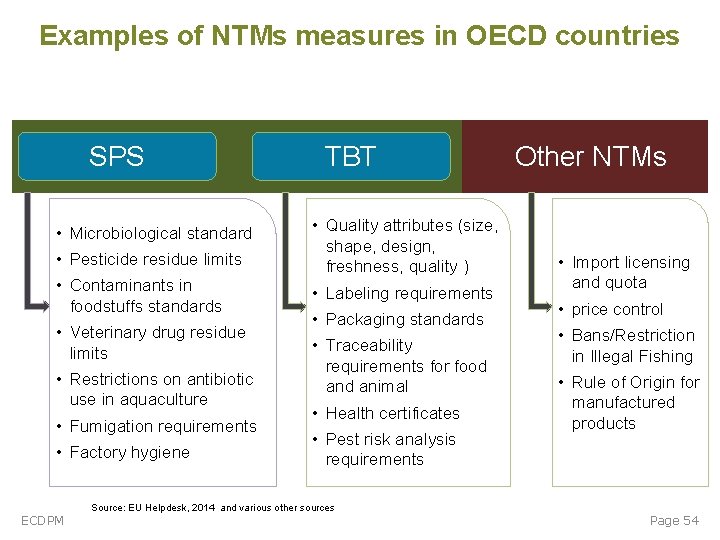
Examples of NTMs measures in OECD countries SPS • Microbiological standard • Pesticide residue limits • Contaminants in foodstuffs standards • Veterinary drug residue limits • Restrictions on antibiotic use in aquaculture • Fumigation requirements • Factory hygiene ECDPM TBT • Quality attributes (size, shape, design, freshness, quality ) • Labeling requirements • Packaging standards • Traceability requirements for food animal • Health certificates • Pest risk analysis requirements Source: EU Helpdesk, 2014 and various other sources Other NTMs • Import licensing and quota • price control • Bans/Restriction in Illegal Fishing • Rule of Origin for manufactured products Page 54
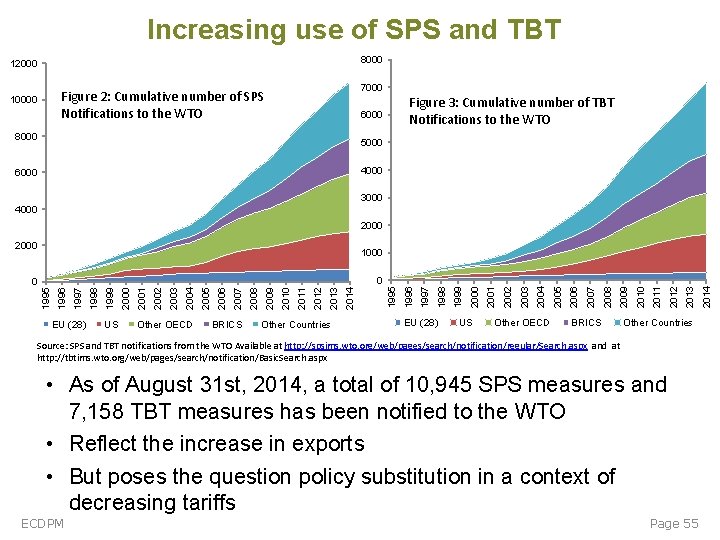
Increasing use of SPS and TBT 8000 12000 7000 Figure 2: Cumulative number of SPS Notifications to the WTO 10000 Figure 3: Cumulative number of TBT Notifications to the WTO 6000 8000 5000 4000 6000 3000 4000 2000 EU (28) US Other OECD BRICS Other Countries Source: SPS and TBT notifications from the WTO Available at http: //spsims. wto. org/web/pages/search/notification/regular/Search. aspx and at http: //tbtims. wto. org/web/pages/search/notification/Basic. Search. aspx • As of August 31 st, 2014, a total of 10, 945 SPS measures and 7, 158 TBT measures has been notified to the WTO • Reflect the increase in exports • But poses the question policy substitution in a context of decreasing tariffs ECDPM Page 55 2014 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 1996 1995 2014 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 1996 0 1995 0 1000
Non-Tariff Measures by sectors Table 1: Number of NTMs by economic sectors (all countries) Source: Adapted from Gourdon and Nicita (2012) • Food and agricultural products are the most affected • Important implication of food security ECDPM Page 56
Rising role of Private Voluntary Standards are : “are written requirements or set of written requirements of a nongovernmental entity which are related to food safety, animal or plant life or health and for common and repeated use” Working definition proposed by China and New Zeeland to WTO ECDPM Page 57
Too many PVS ? More than 400 (UNCTAD and EU estimates) Source: Standardmap, ITC ECDPM Page 58
Rising role of Private Voluntary Standards… • Despite their voluntary nature, PVSs are ‘de facto’ mandatory for to access developed countries markets (Henson and Northen, 1998). • PVSs versus Public Standards? • PVSs are used by retailers to establish and maintain reputations, minimise monitoring and inspection costs due to public standards • PVSs are more complex and stringent and are not necessarily being based on scientific evidences (Henson and Humphrey 2009). • PVSs cover number of dimension (social, environment, equity, organic production, etc. ) not covered by public standards ECDPM Page 59
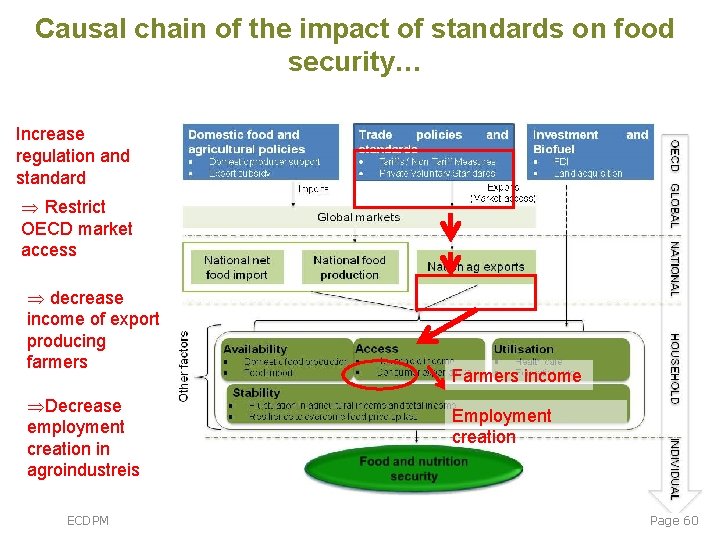
Causal chain of the impact of standards on food security… Increase regulation and standard Þ Restrict OECD market access Þ decrease income of export producing farmers ÞDecrease employment creation in agroindustreis ECDPM Farmers income Employment creation Page 60
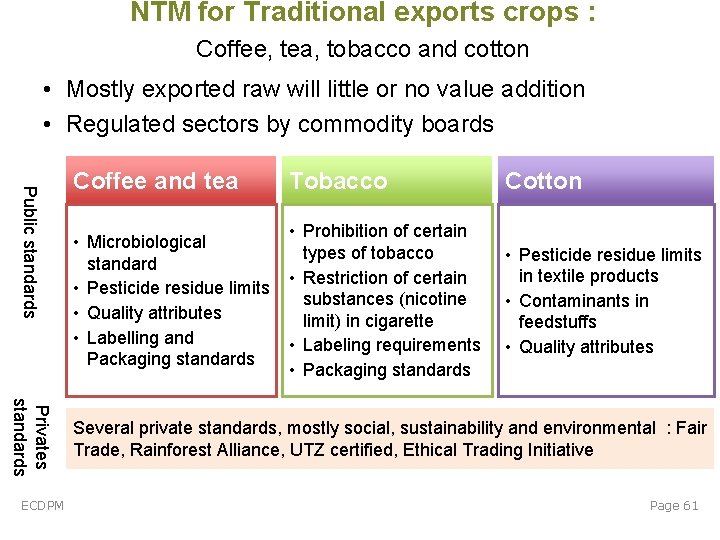
NTM for Traditional exports crops : Coffee, tea, tobacco and cotton • Mostly exported raw will little or no value addition • Regulated sectors by commodity boards Public standards Privates standards ECDPM Coffee and tea Tobacco Cotton • Microbiological standard • Pesticide residue limits • Quality attributes • Labelling and Packaging standards • Prohibition of certain types of tobacco • Restriction of certain substances (nicotine limit) in cigarette • Labeling requirements • Packaging standards • Pesticide residue limits in textile products • Contaminants in feedstuffs • Quality attributes Several private standards, mostly social, sustainability and environmental : Fair Trade, Rainforest Alliance, UTZ certified, Ethical Trading Initiative Page 61
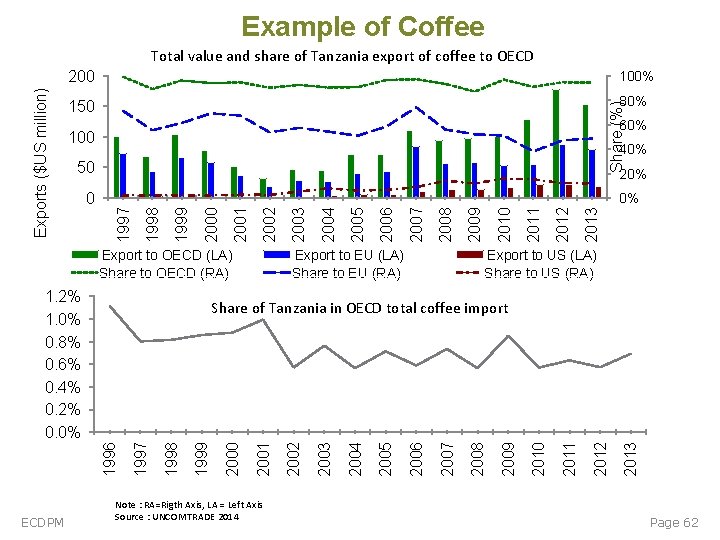
Example of Coffee 100% 150 80% Share (%) 200 60% 100 40% 50 20% 0 Export to OECD (LA) Share to OECD (RA) 1. 2% 1. 0% 0. 8% 0. 6% 0. 4% 0. 2% 0. 0% 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 Export to EU (LA) Share to EU (RA) Export to US (LA) Share to US (RA) Note : RA=Rigth Axis, LA = Left Axis Source : UNCOMTRADE 2014 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 Share of Tanzania in OECD total coffee import 1996 ECDPM 2003 2002 2001 2000 1999 1998 0% 1997 Exports ($US million) Total value and share of Tanzania export of coffee to OECD Page 62
Traditional exports crops access to OECD • Standards are realities in traditional export crops • But, they are not major barrier to access OECD market • Other factors are major constraints to the development of these sectors • Domestics policies • Low value addition (but why? ) • Lack infrastructures and low productivity • Instead private certification offer the opportunity : • to expand trade and access niche markets (coffee and tea) • earn ‘decent’ prices (fair trade) • In the medium term, private standards could become majors challenges (carbon footprint, etc. ) ECDPM Page 63
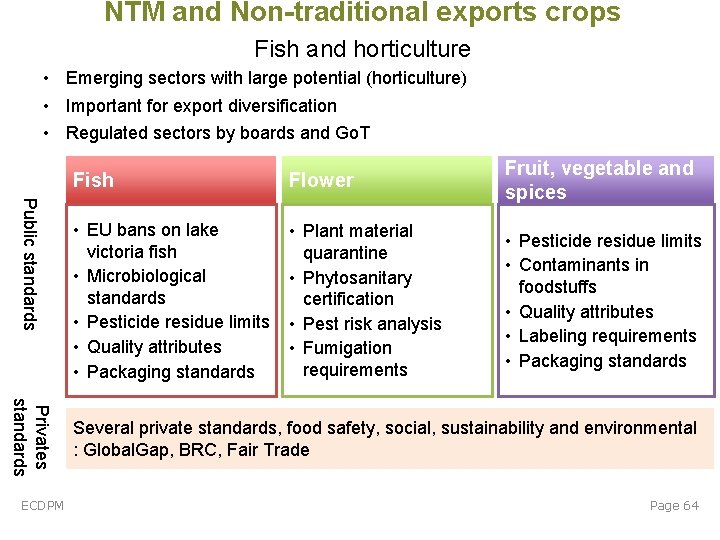
NTM and Non-traditional exports crops Fish and horticulture • Emerging sectors with large potential (horticulture) • Important for export diversification • Regulated sectors by boards and Go. T Public standards Privates standards ECDPM Fish Flower Fruit, vegetable and spices • EU bans on lake victoria fish • Microbiological standards • Pesticide residue limits • Quality attributes • Packaging standards • Plant material quarantine • Phytosanitary certification • Pest risk analysis • Fumigation requirements • Pesticide residue limits • Contaminants in foodstuffs • Quality attributes • Labeling requirements • Packaging standards Several private standards, food safety, social, sustainability and environmental : Global. Gap, BRC, Fair Trade Page 64
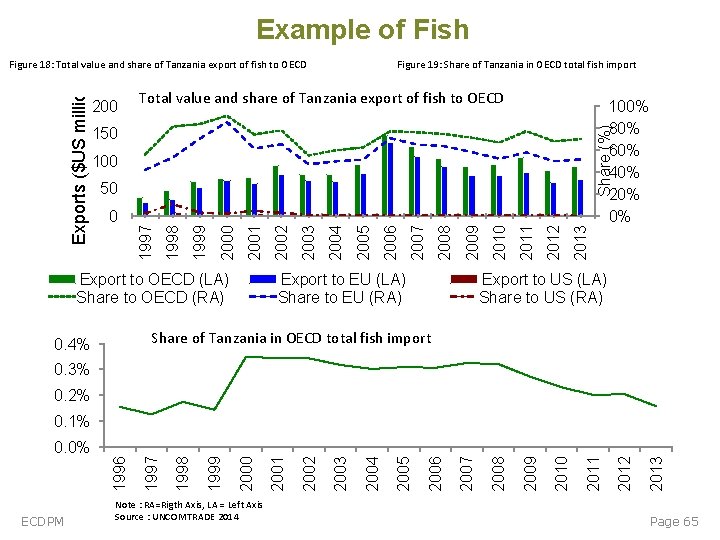
Example of Fish 200 Figure 19: Share of Tanzania in OECD total fish import Total value and share of Tanzania export of fish to OECD 100% 80% 60% 40% 20% 0% Share (%) 150 100 50 Export to OECD (LA) Share to OECD (RA) Export to EU (LA) Share to EU (RA) 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 0 1997 Exports ($US million) Figure 18: Total value and share of Tanzania export of fish to OECD Export to US (LA) Share to US (RA) Share of Tanzania in OECD total fish import 0. 4% 0. 3% 0. 2% 0. 1% ECDPM Note : RA=Rigth Axis, LA = Left Axis Source : UNCOMTRADE 2014 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1997 1996 0. 0% Page 65
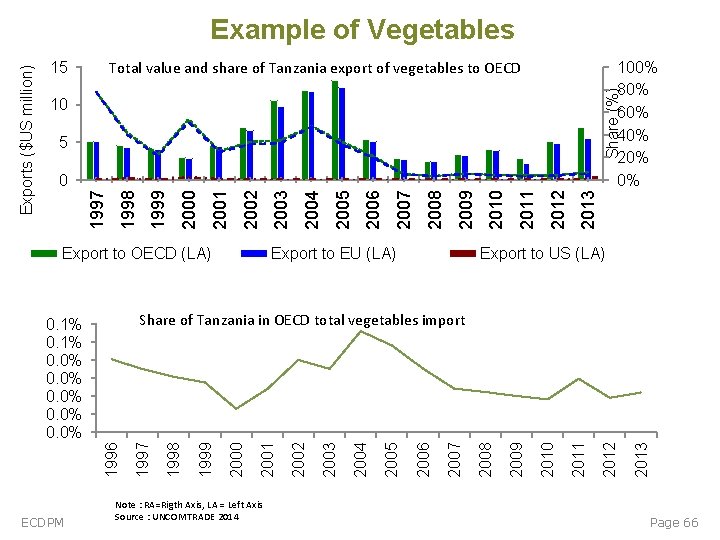
Total value and share of Tanzania export of vegetables to OECD 100% 80% 60% 40% 20% 0% Share (%) 15 10 5 Export to OECD (LA) 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 Export to EU (LA) Export to US (LA) Note : RA=Rigth Axis, LA = Left Axis Source : UNCOMTRADE 2014 2013 2012 2011 2010 2009 2008 2007 2006 2005 2004 2003 2002 2001 2000 1999 1998 1996 1997 Share of Tanzania in OECD total vegetables import 0. 1% 0. 0% ECDPM 2003 2002 2001 2000 1999 1998 0 1997 Exports ($US million) Example of Vegetables Page 66
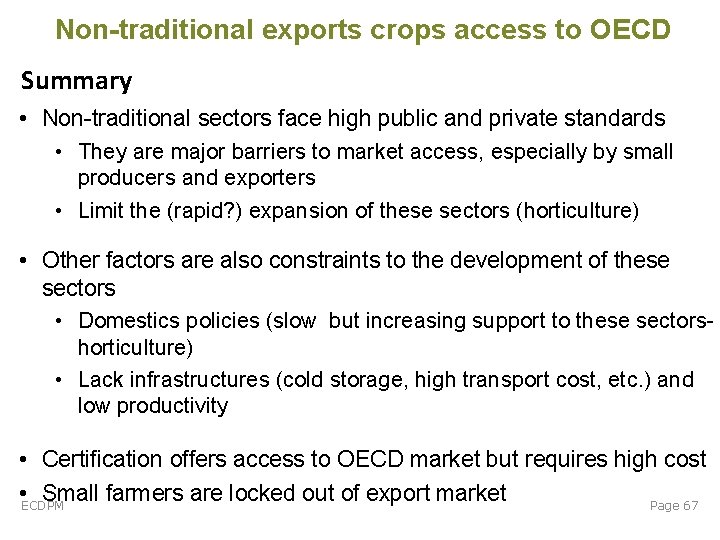
Non-traditional exports crops access to OECD Summary • Non-traditional sectors face high public and private standards • They are major barriers to market access, especially by small producers and exporters • Limit the (rapid? ) expansion of these sectors (horticulture) • Other factors are also constraints to the development of these sectors • Domestics policies (slow but increasing support to these sectorshorticulture) • Lack infrastructures (cold storage, high transport cost, etc. ) and low productivity • Certification offers access to OECD market but requires high cost • ECDPM Small farmers are locked out of export market Page 67
Technical assistances to Developing countries The SPS agreementions, “members shall take account of the special needs of developing country Members, and in particular of the least-developed country Members” (Article 10. 1). Example of initiative • WTO/FAO Standards and Trade Development Facility • Support to Horticulture Development Council of Tanzania • EU /COLEACP Pesticide Initiative Program (PIP) • 11 producing/exporting companies/farmers’ groups supported in Tanzania • Many programs/project from other partners These supports are essential to ensure the compliance of smallhollders But what about the million of non-beneficiary smallholders? ECDPM Page 68
Q&A
MODULE 3 PART 3 Foreign direct investment and land acquisition Overview of FDI and implication for food security in Tanzania
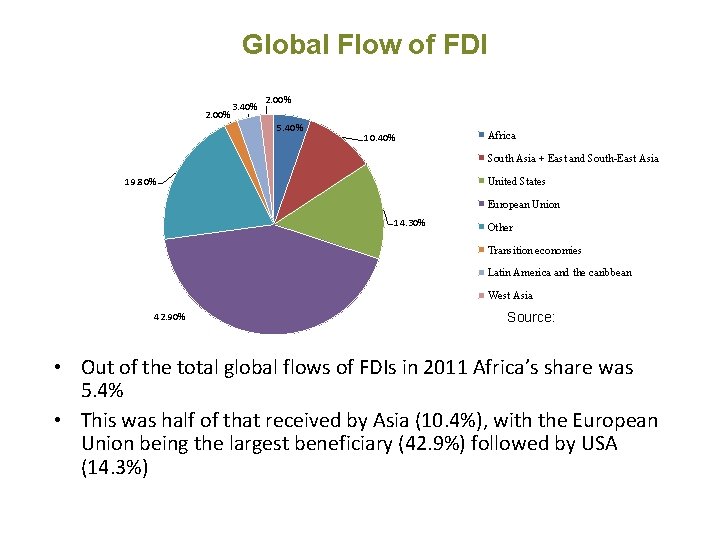
Global Flow of FDI 2. 00% 3. 40% 2. 00% 5. 40% 10. 40% Africa South Asia + East and South-East Asia 19. 80% United States European Union 14. 30% Other Transition economies Latin America and the caribbean West Asia 42. 90% Source: • Out of the total global flows of FDIs in 2011 Africa’s share was 5. 4% • This was half of that received by Asia (10. 4%), with the European Union being the largest beneficiary (42. 9%) followed by USA (14. 3%)
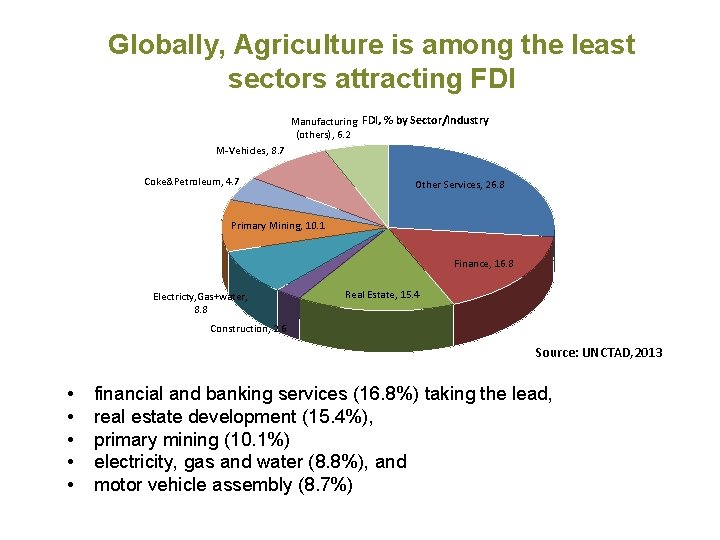
Globally, Agriculture is among the least sectors attracting FDI Manufacturing FDI, % by Sector/Industry (others), 6. 2 M-Vehicles, 8. 7 Coke&Petroleum, 4. 7 Other Services, 26. 8 Primary Mining, 10. 1 Finance, 16. 8 Electricty, Gas+water, 8. 8 Real Estate, 15. 4 Construction, 2. 6 Source: UNCTAD, 2013 • • • financial and banking services (16. 8%) taking the lead, real estate development (15. 4%), primary mining (10. 1%) electricity, gas and water (8. 8%), and motor vehicle assembly (8. 7%)
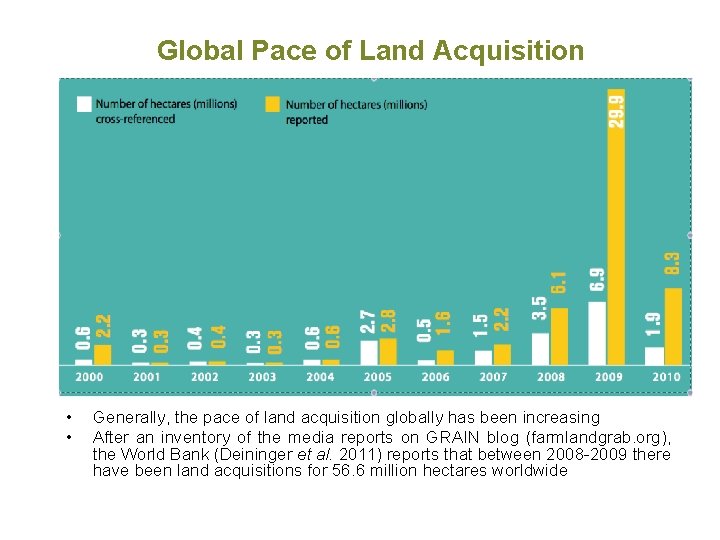
Global Pace of Land Acquisition • • Generally, the pace of land acquisition globally has been increasing After an inventory of the media reports on GRAIN blog (farmlandgrab. org), the World Bank (Deininger et al. 2011) reports that between 2008 -2009 there have been land acquisitions for 56. 6 million hectares worldwide
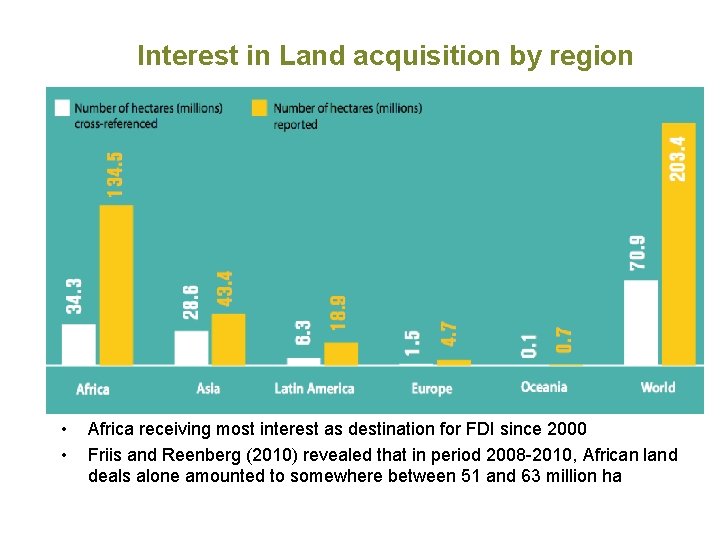
Interest in Land acquisition by region • • Africa receiving most interest as destination for FDI since 2000 Friis and Reenberg (2010) revealed that in period 2008 -2010, African land deals alone amounted to somewhere between 51 and 63 million ha
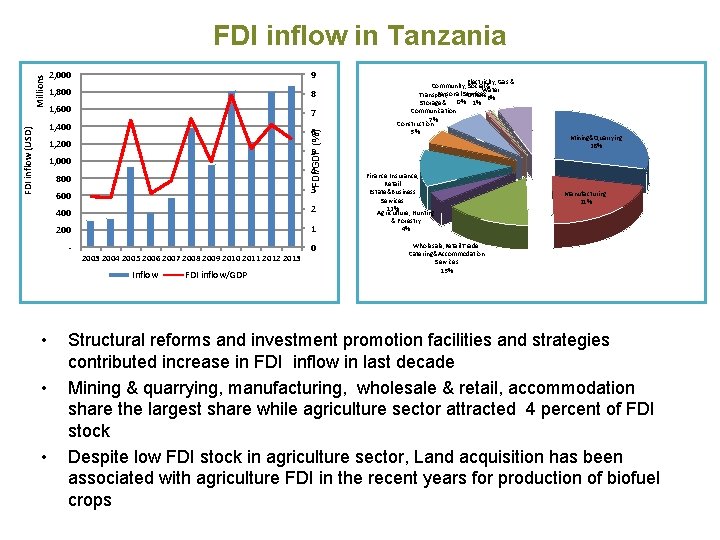
Millions FDI inflow in Tanzania 2, 000 9 1, 800 8 1, 600 7 6 FDI/GDP (%) FDI inflow (USD) 1, 400 1, 200 5 1, 000 4 800 3 600 400 2 200 1 - 0 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 Inflow • • • Electricity, Gas & Community, Social & Water Personal Services Transport, Others 6% 0% 1% Storage& Communication 7% Construction 5% FDI inflow/GDP Finance Insurance, Retail Estate&Business Services 12% Agriculture, Hunting Mining&Quarrying 28% Manufacturing 21% & Forestry 4% Wholesale, Retail Trade. Catering&Accommodation Services 15% Structural reforms and investment promotion facilities and strategies contributed increase in FDI inflow in last decade Mining & quarrying, manufacturing, wholesale & retail, accommodation share the largest share while agriculture sector attracted 4 percent of FDI stock Despite low FDI stock in agriculture sector, Land acquisition has been associated with agriculture FDI in the recent years for production of biofuel crops
Land acquisitions • Weak regulatory enforcement in land ownership and resource poor small holder farmers are at risk of losing livelihoods and food production land due to random sale of their land assets • More than 4 million hectares of land are in the hand of large investors • Local medium and small investors in agricultural land is rising but few land is optimally used
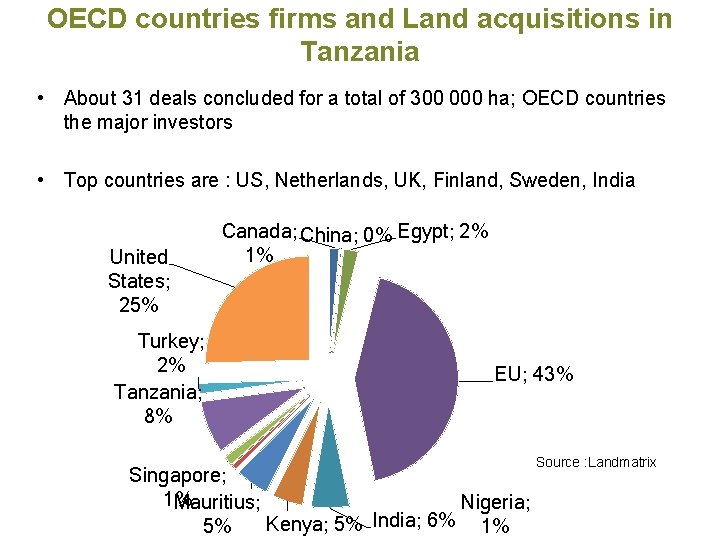
OECD countries firms and Land acquisitions in Tanzania • About 31 deals concluded for a total of 300 000 ha; OECD countries the major investors • Top countries are : US, Netherlands, UK, Finland, Sweden, India United States; 25% Turkey; 2% Tanzania; 8% Canada; China; 0% Egypt; 2% 1% EU; 43% Singapore; 1% Mauritius; Nigeria; Kenya; 5% India; 6% 1% 5% Source : Landmatrix
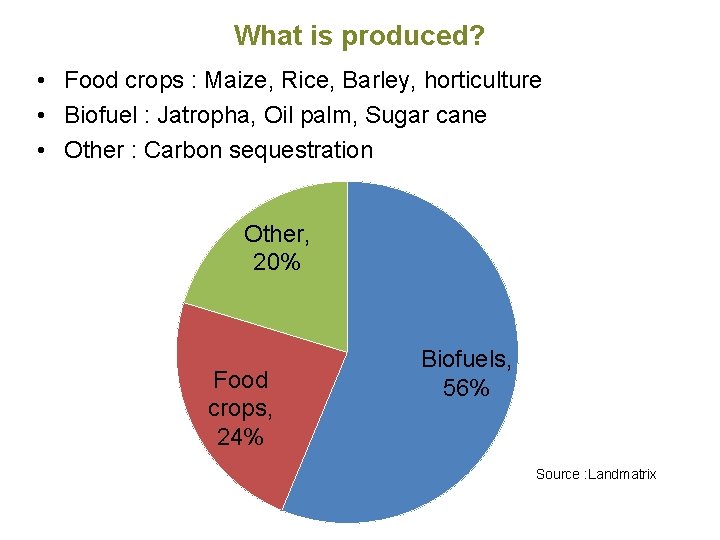
What is produced? • Food crops : Maize, Rice, Barley, horticulture • Biofuel : Jatropha, Oil palm, Sugar cane • Other : Carbon sequestration Other, 20% Food crops, 24% Biofuels, 56% Source : Landmatrix
What are links with OECD policies • EU and US biofuel policies? • Implication of land acquisition for local economy and food security? • OECD/EU code for responsible investment in Agricultures
What are the impacts to: • Livelihoods of local communities • Food security • Agriculture production
Q&A ECDPM Page 81
Thank you www. ecdpm. org www. slideshare. net/ecdpm Page 82