Chp 8 Theory of Rational Option Pricing Kangchaofeng
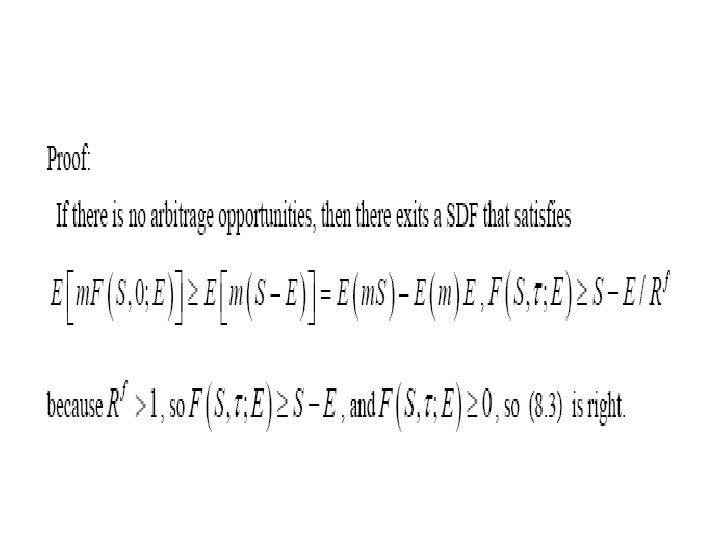
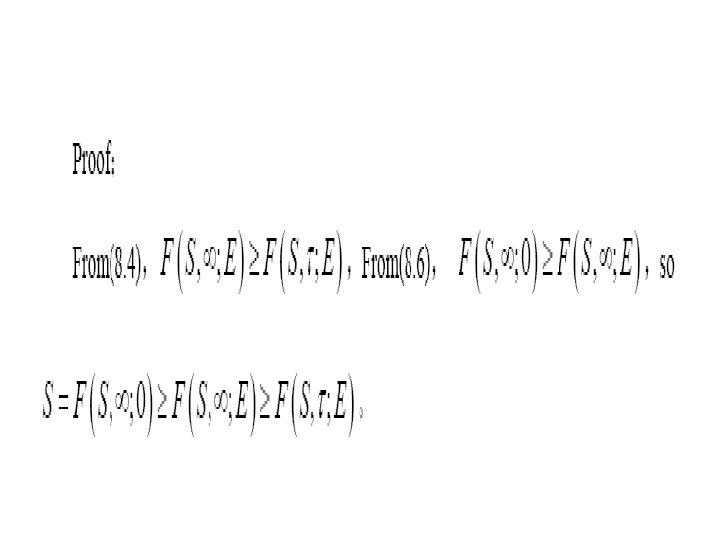
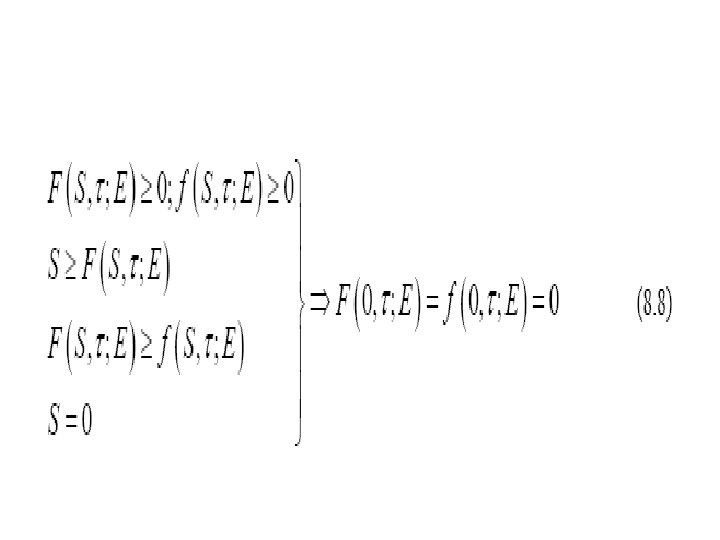
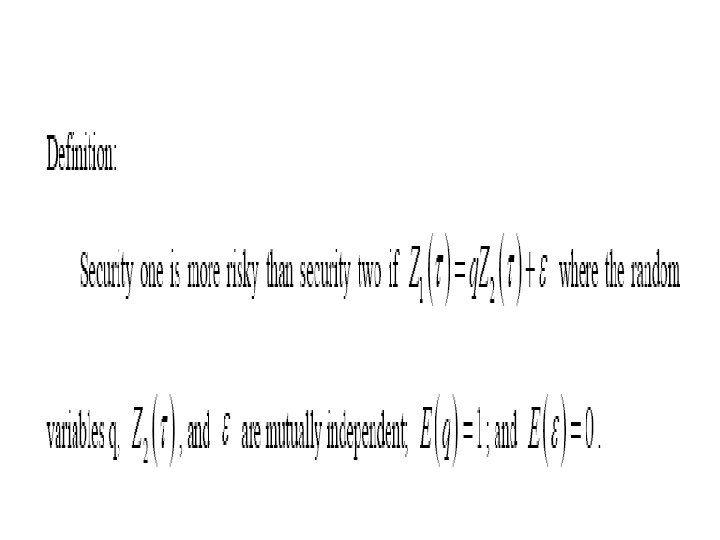
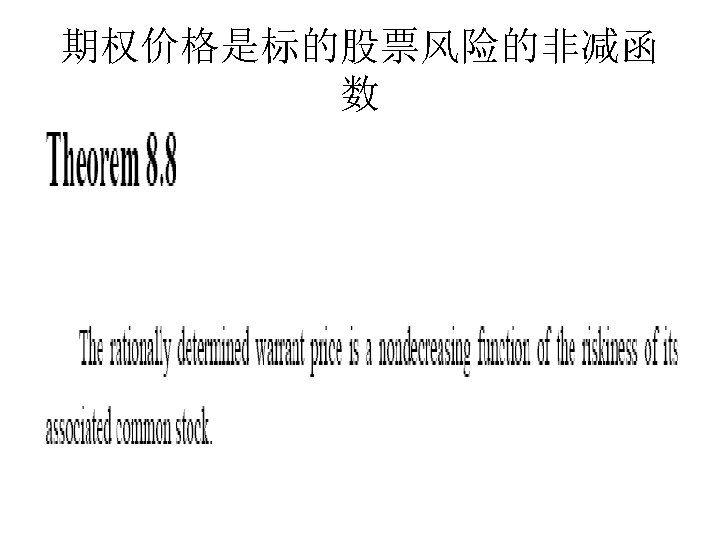
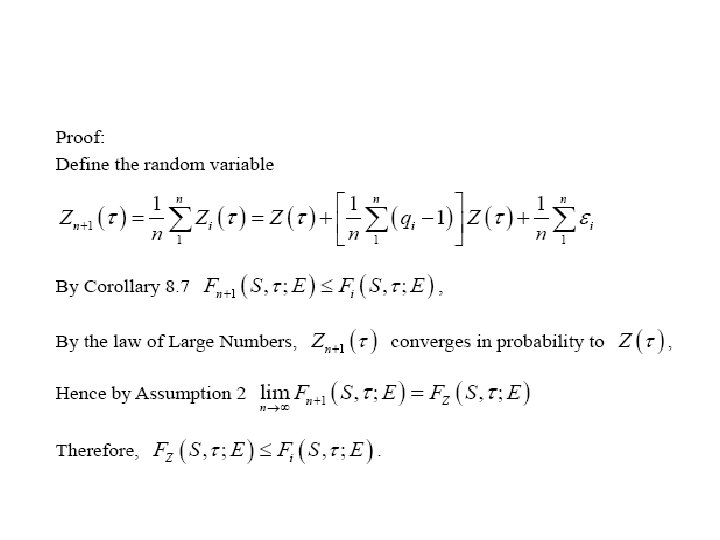
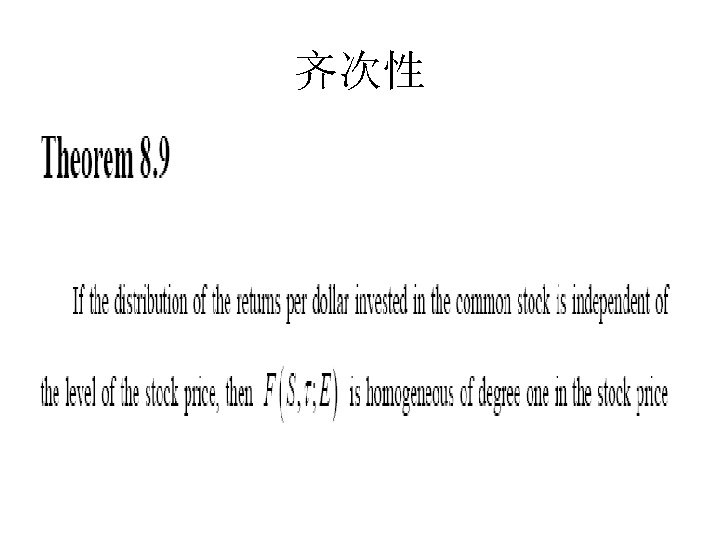
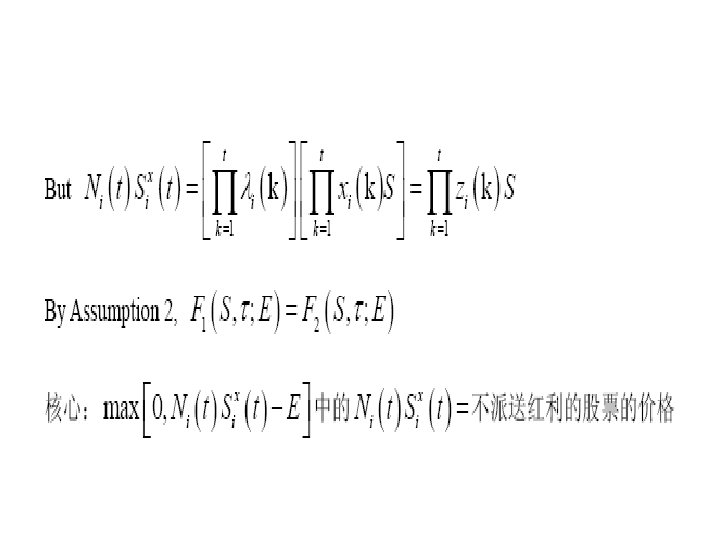
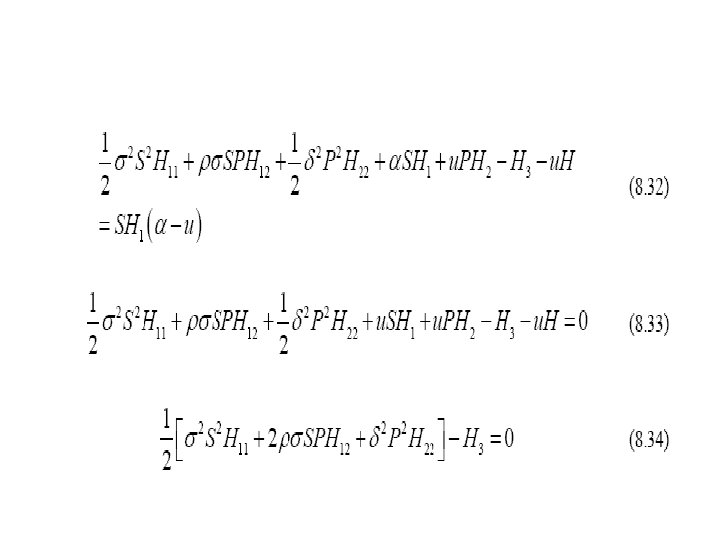
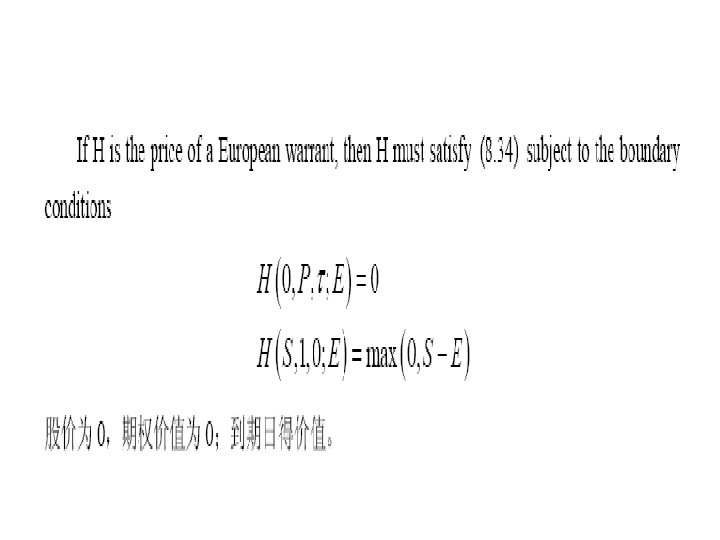
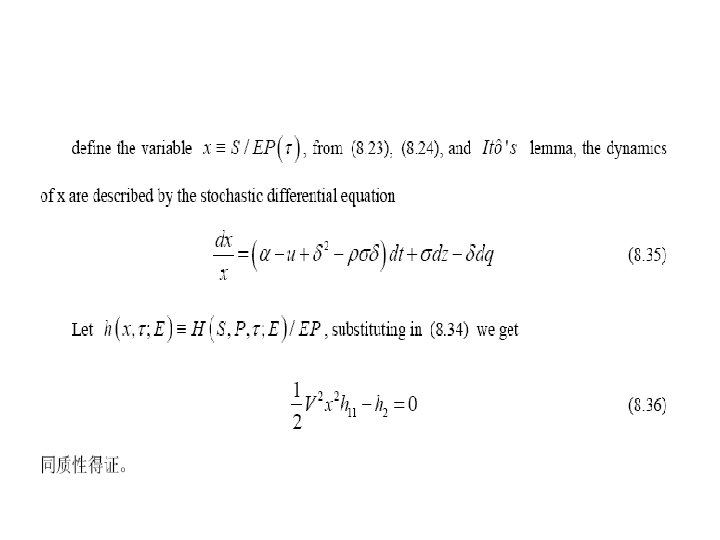
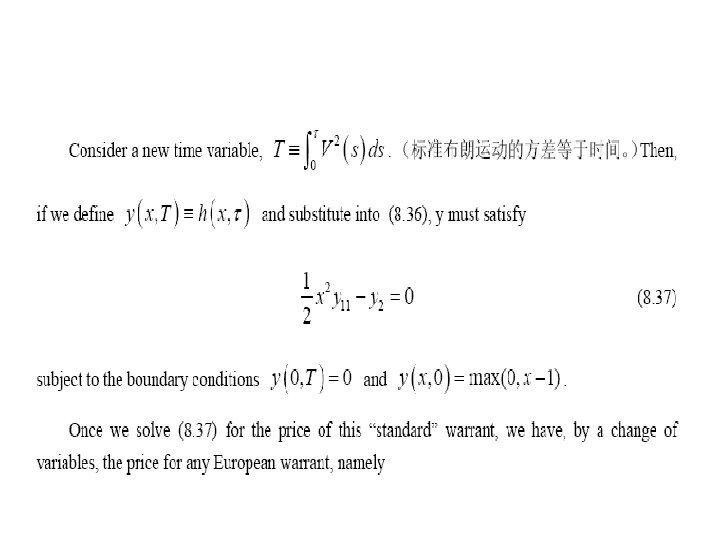
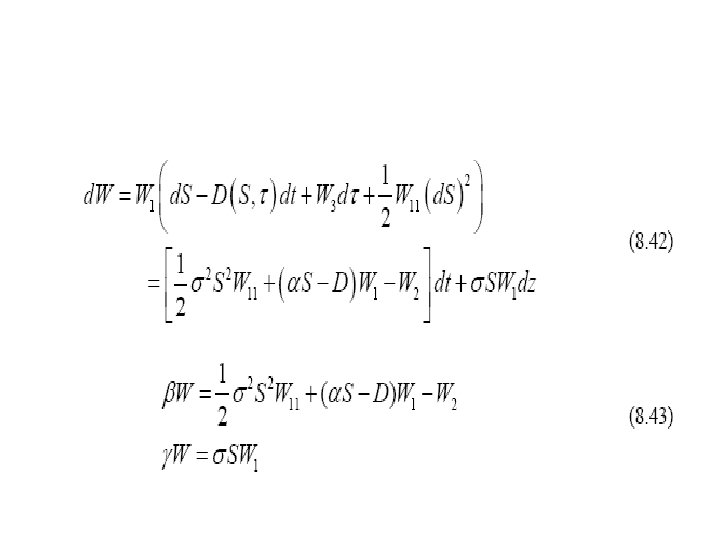
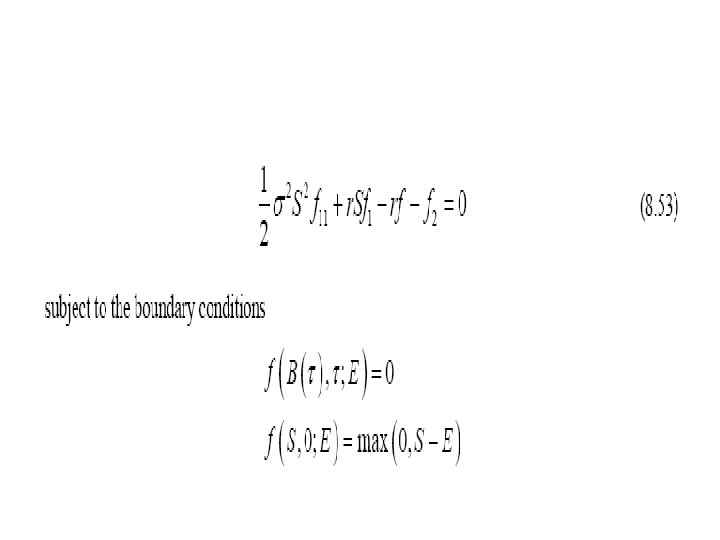
- Slides: 95
Chp. 8 Theory of Rational Option Pricing Kangchaofeng Kcfxm@163. com
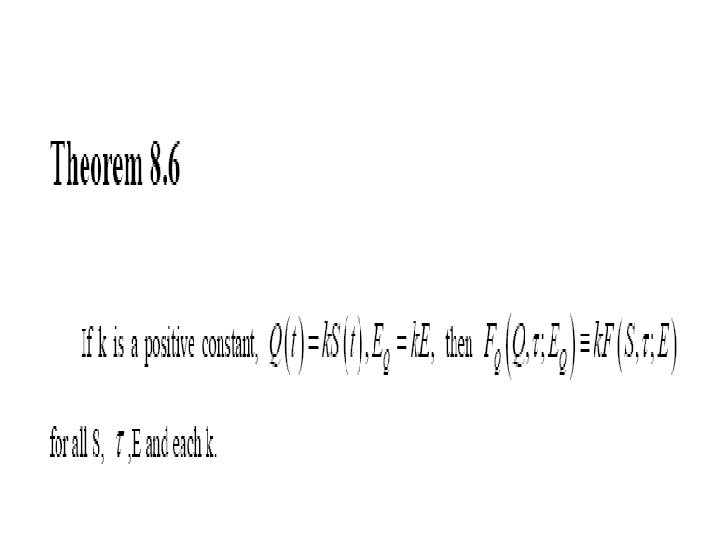
• 8. 1 Why? Option is a particularly simple type of contingent-claim asset, so a theory of option pricing may leading to general theory of contingent-claims pricing.
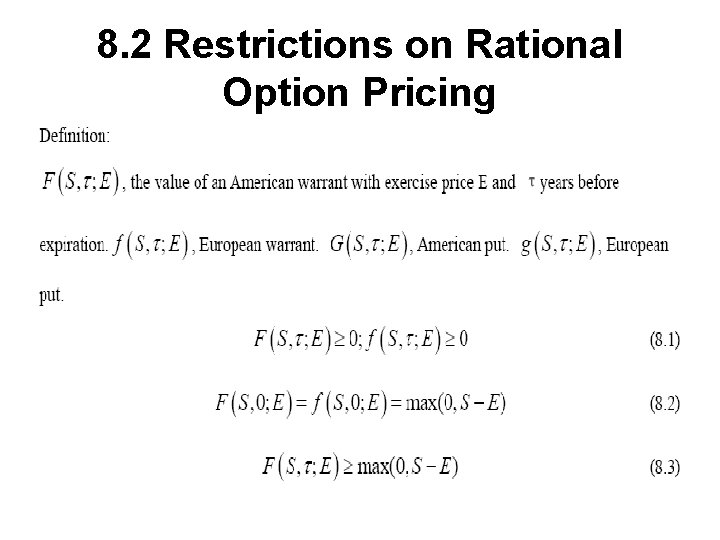
8. 2 Restrictions on Rational Option Pricing
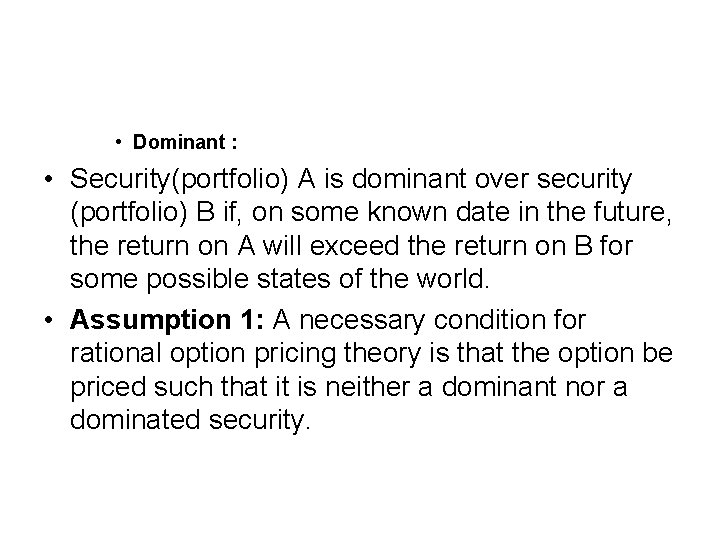
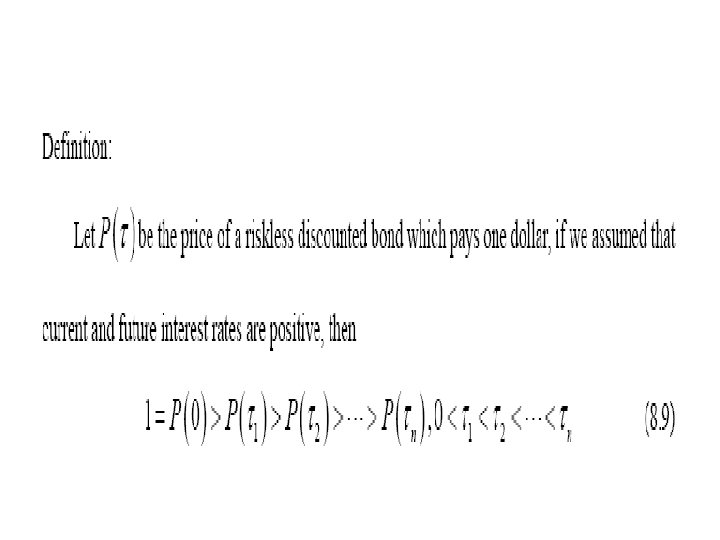
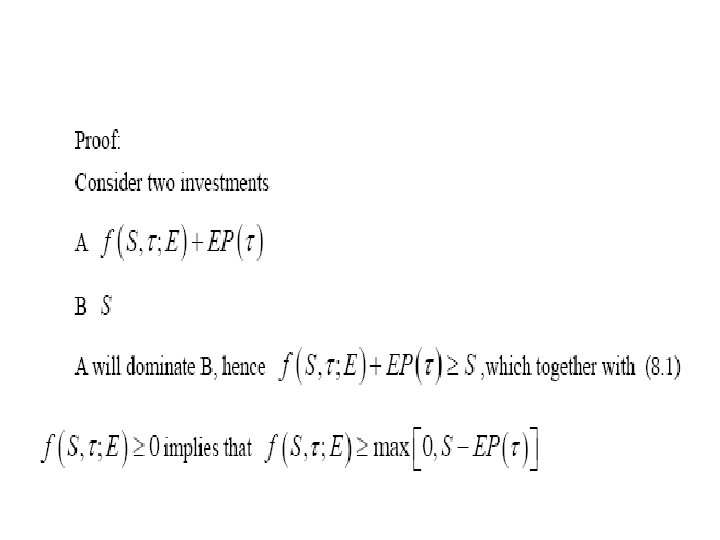
• Dominant : • Security(portfolio) A is dominant over security (portfolio) B if, on some known date in the future, the return on A will exceed the return on B for some possible states of the world. • Assumption 1: A necessary condition for rational option pricing theory is that the option be priced such that it is neither a dominant nor a dominated security.
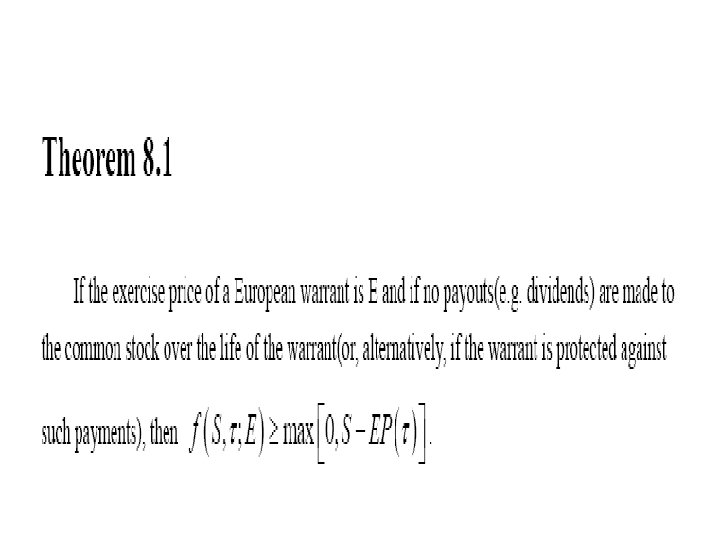
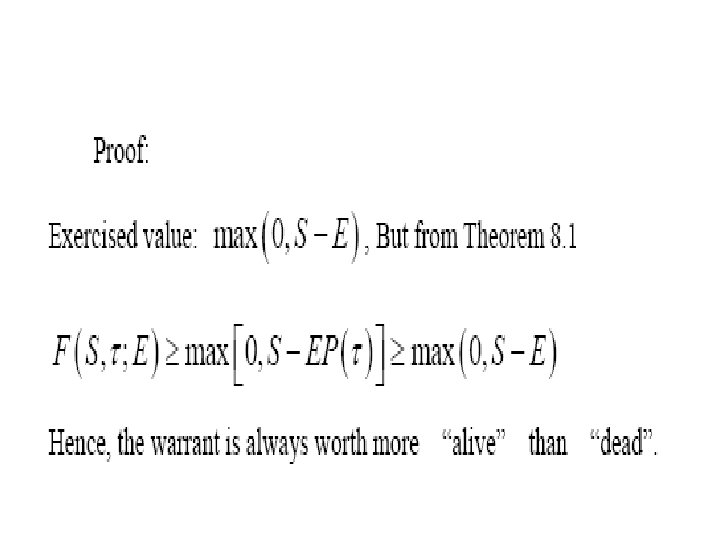
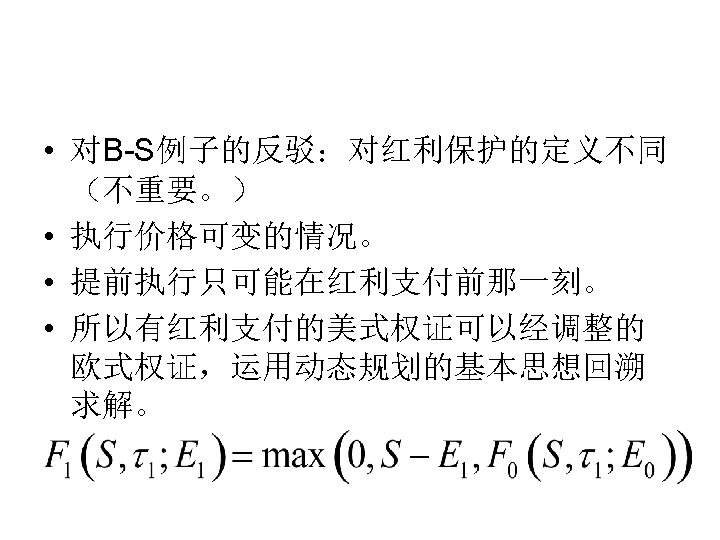
• Theorem 8. 2 • If the hypothesized conditions for Theorem 8. 1 hold, an American warrant will never be exercised prior to expiration, and hence it has the same value as a European warrant.
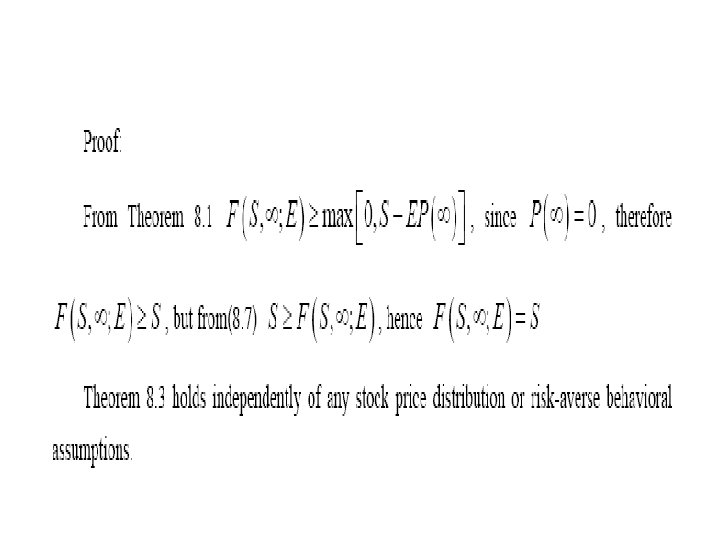
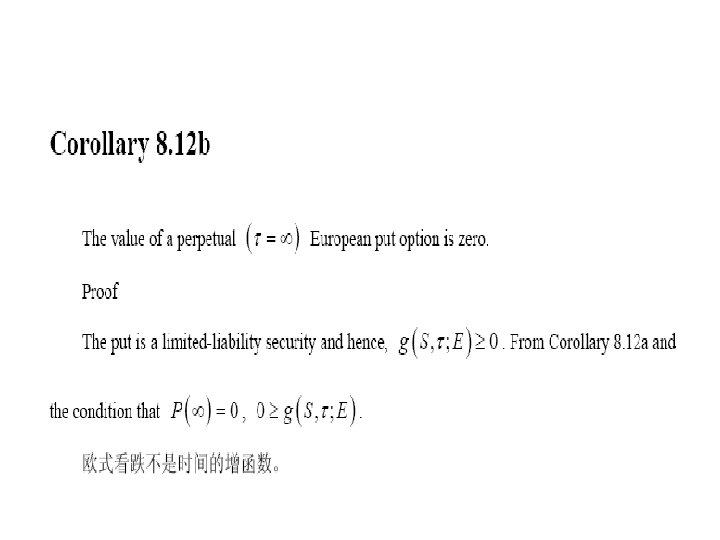
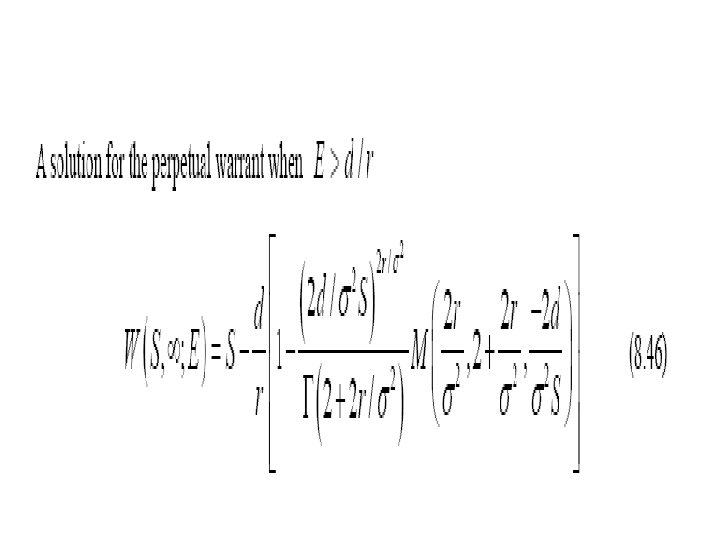
• Theorem 8. 3 • If the hypothesized conditions for Theorem 8. 1 hold, the value of a perpetual warrant must equal the value of the common stock.
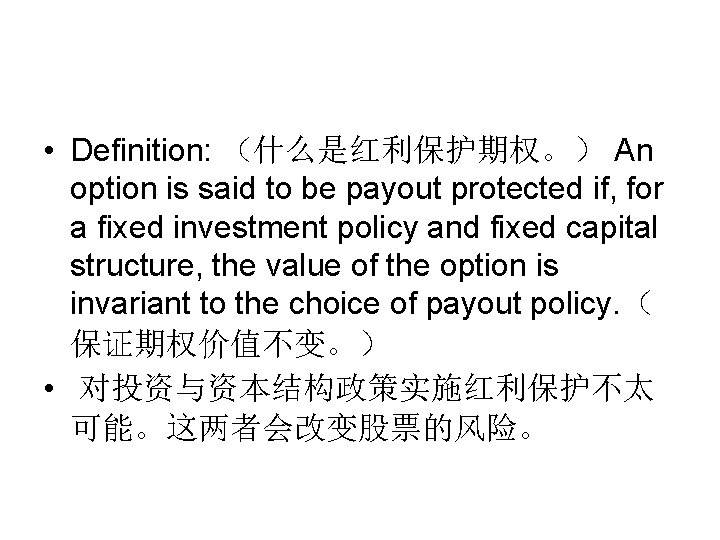
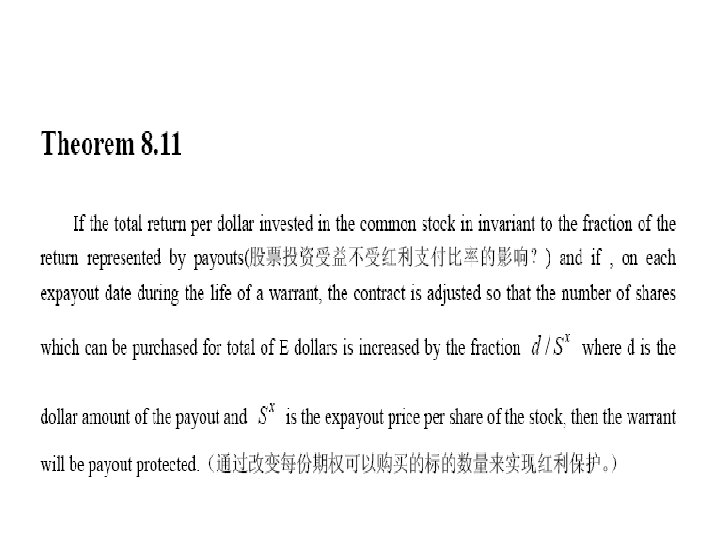
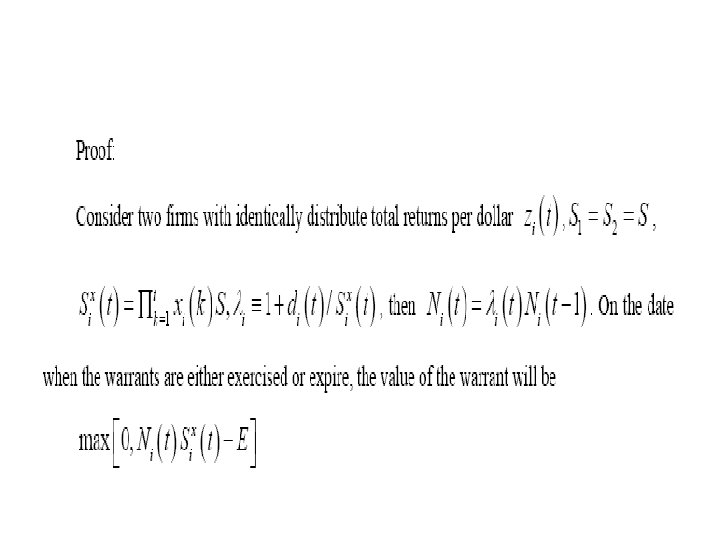
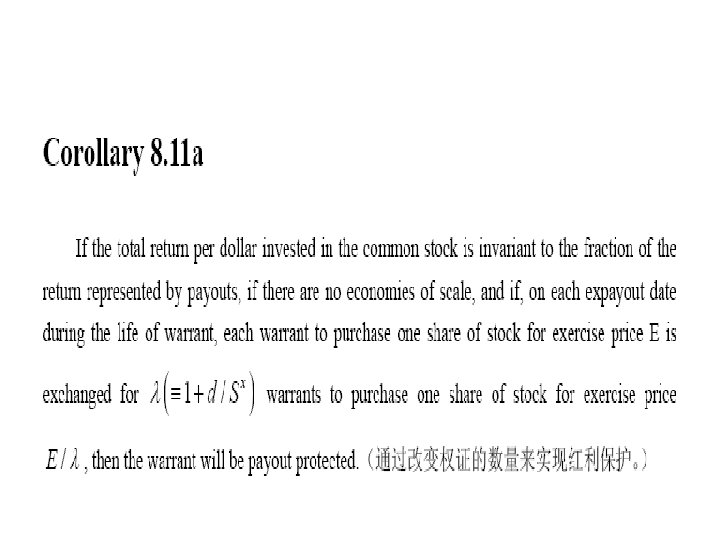
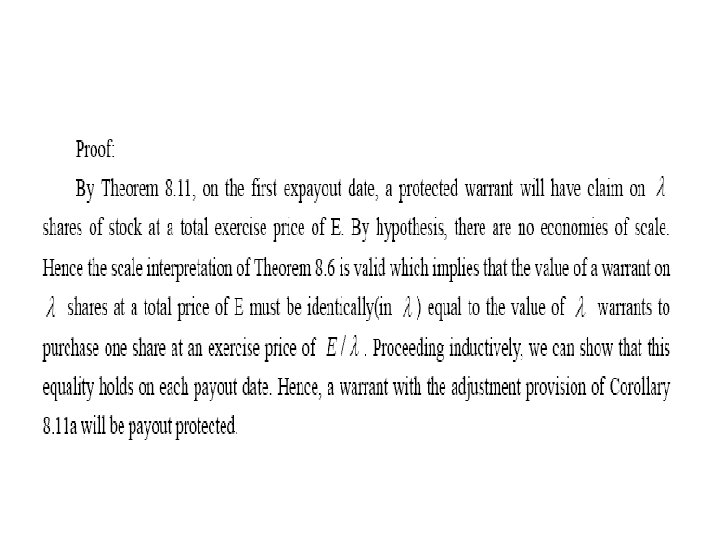
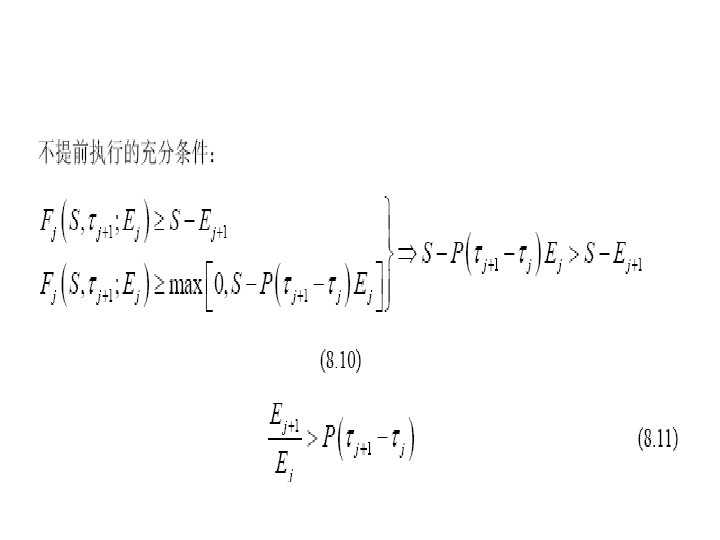
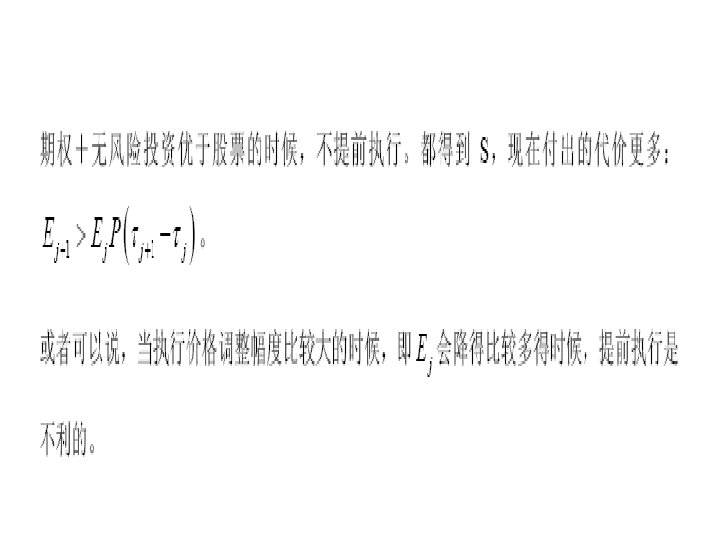
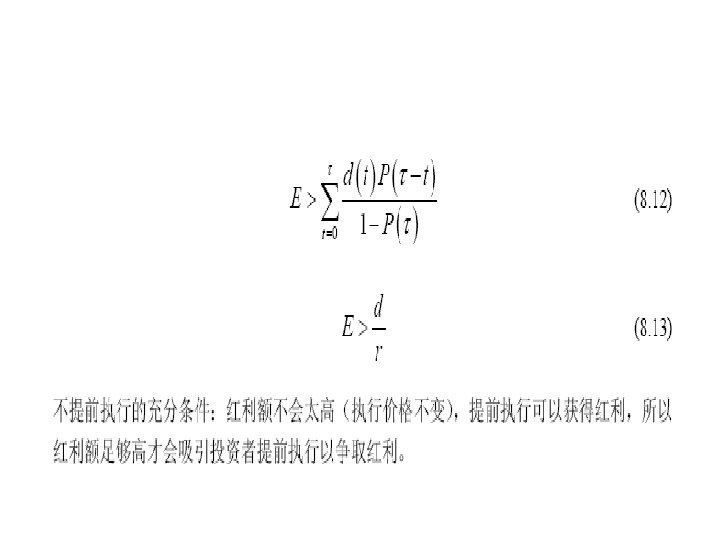
• Definition: (什么是红利保护期权。) An option is said to be payout protected if, for a fixed investment policy and fixed capital structure, the value of the option is invariant to the choice of payout policy. ( 保证期权价值不变。) • 对投资与资本结构政策实施红利保护不太 可能。这两者会改变股票的风险。
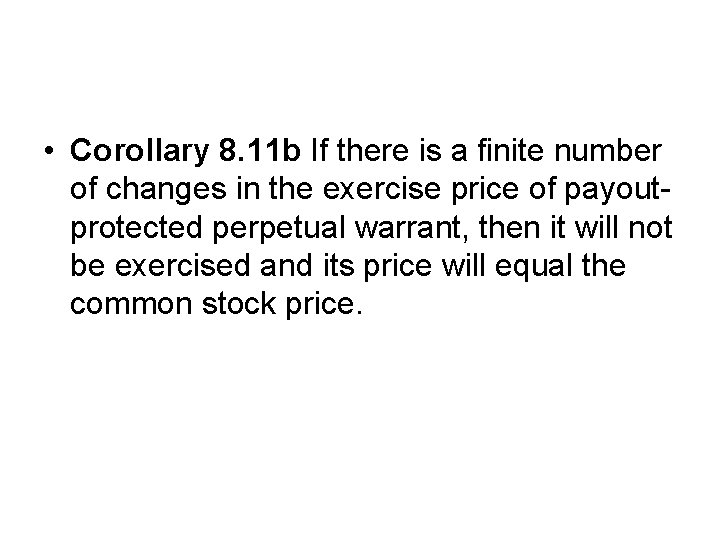
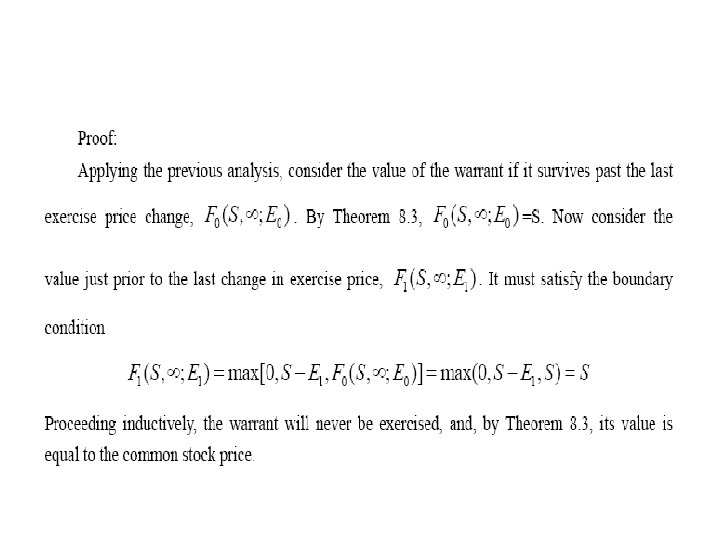
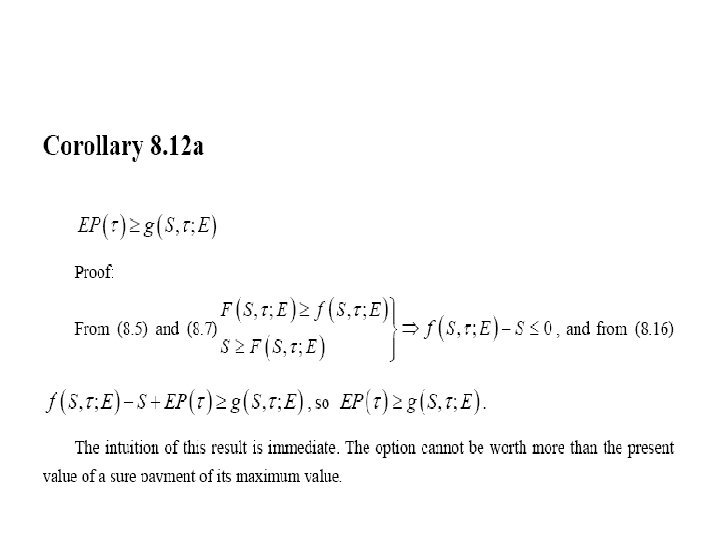
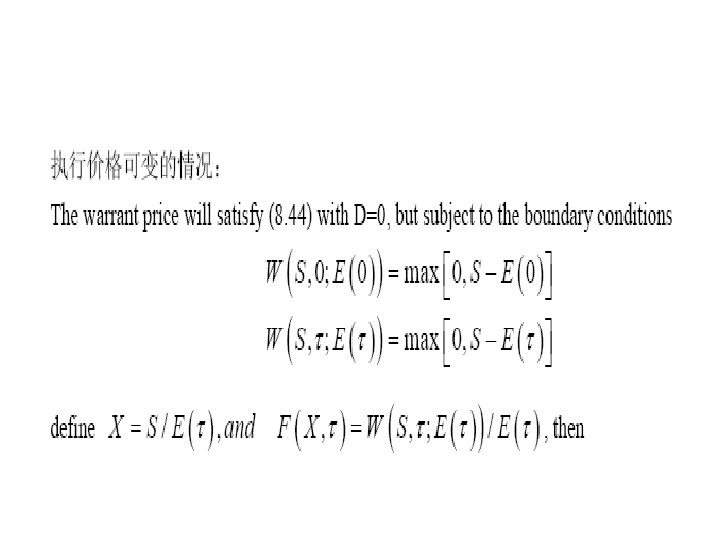
• Corollary 8. 11 b If there is a finite number of changes in the exercise price of payoutprotected perpetual warrant, then it will not be exercised and its price will equal the common stock price.
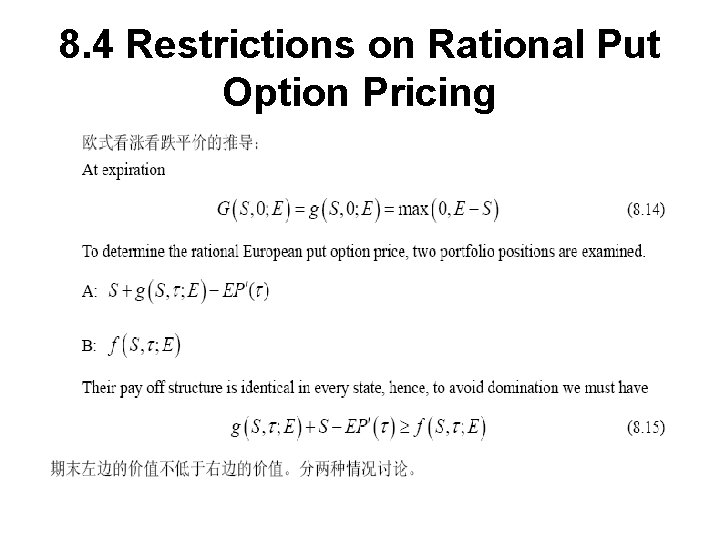
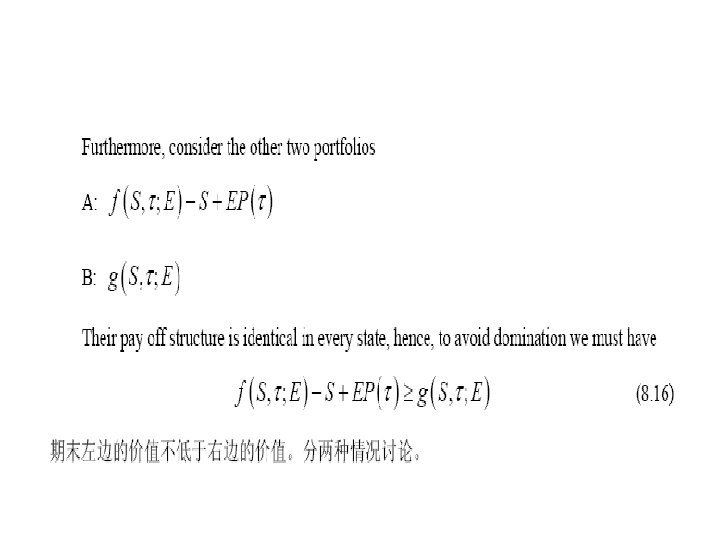
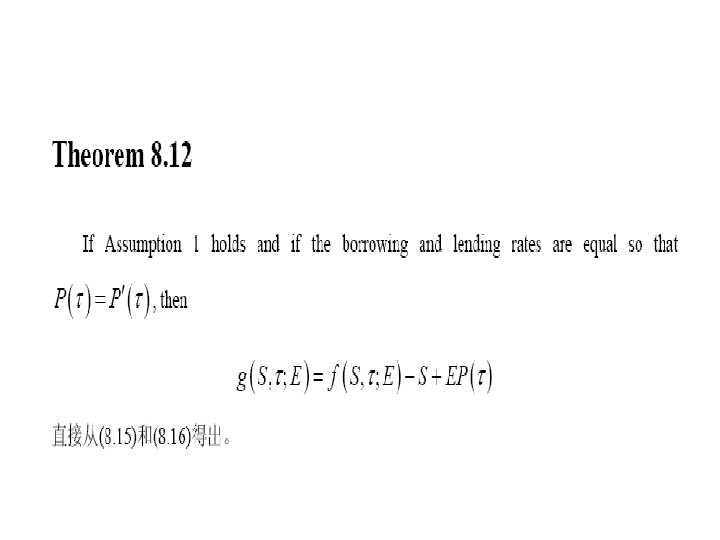
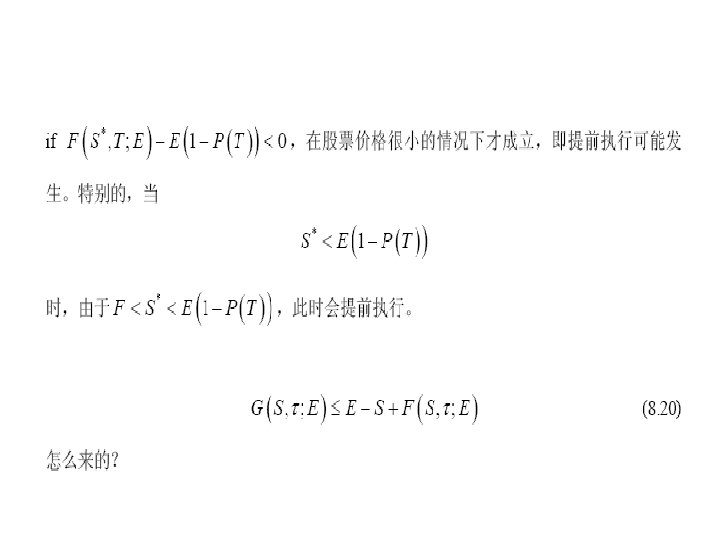
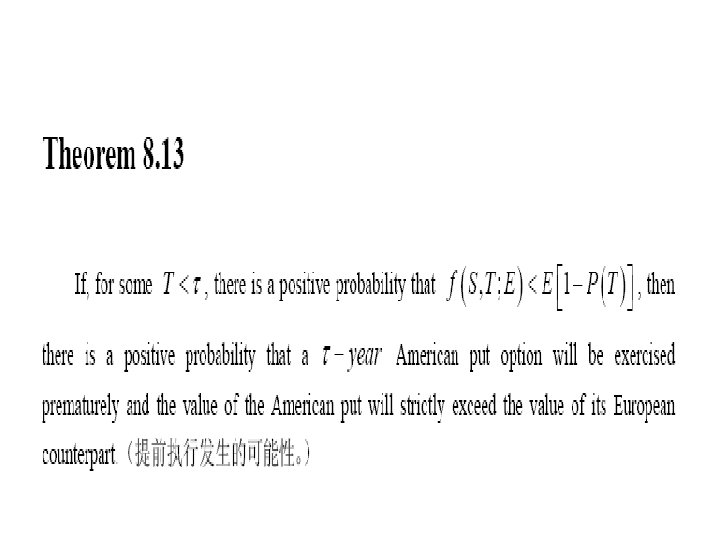
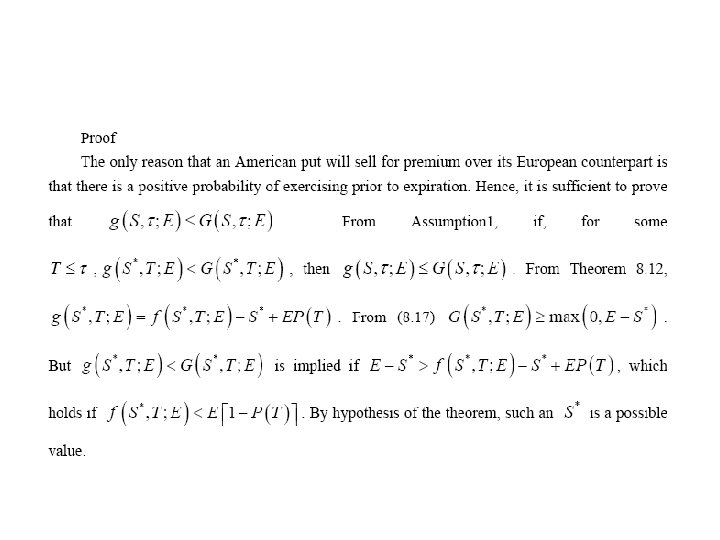
8. 4 Restrictions on Rational Put Option Pricing
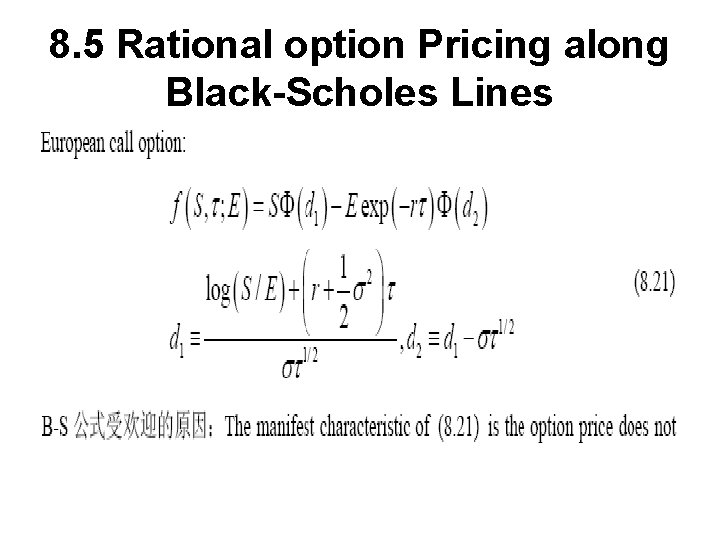
8. 5 Rational option Pricing along Black-Scholes Lines
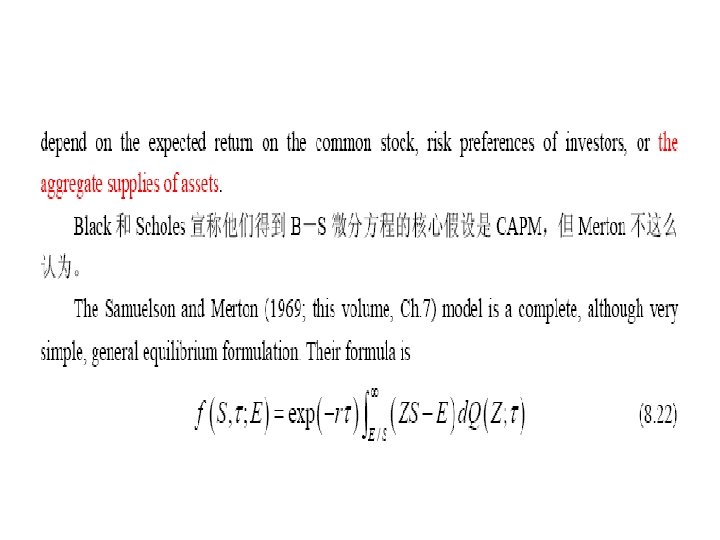
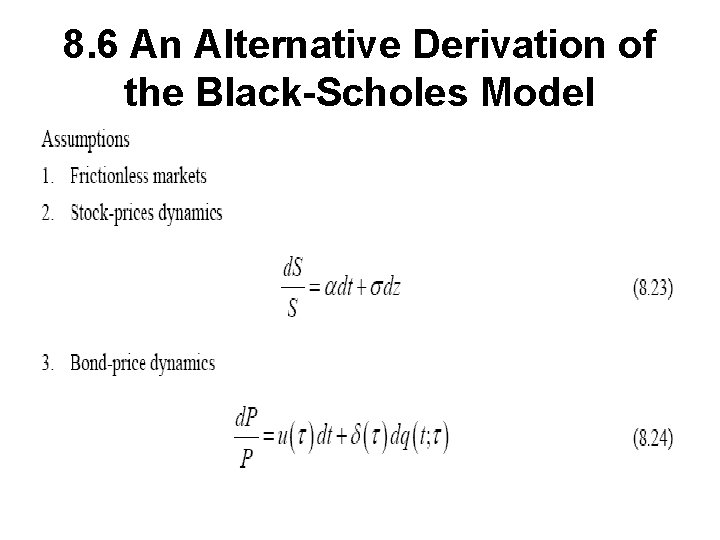
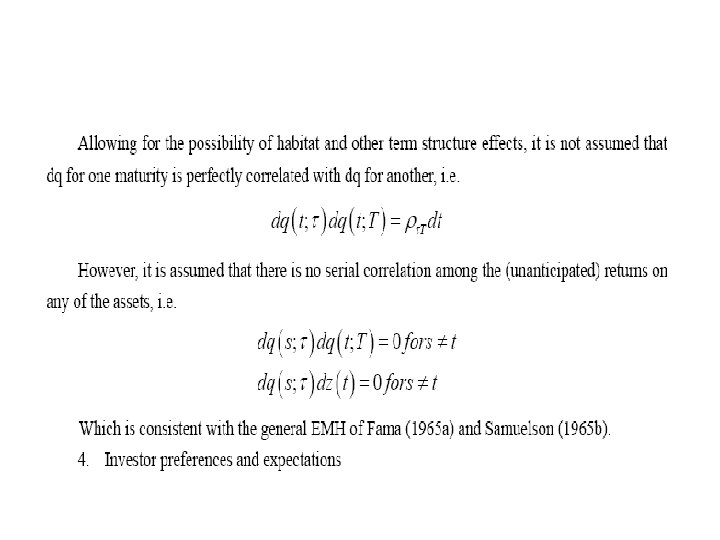
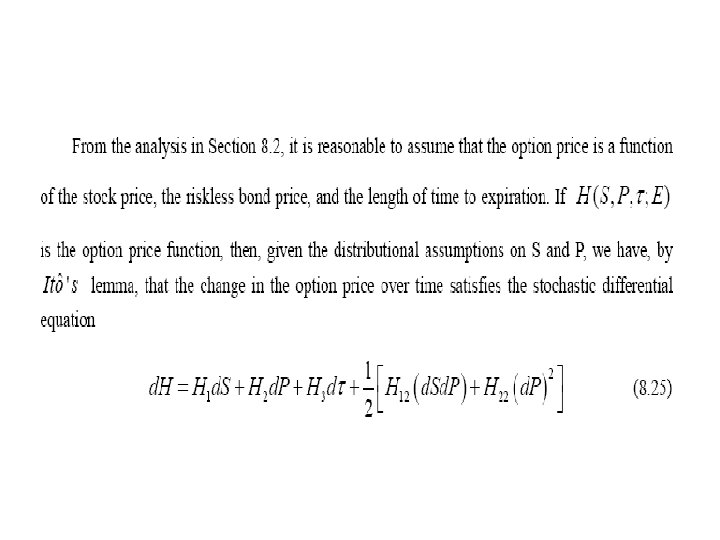
8. 6 An Alternative Derivation of the Black-Scholes Model
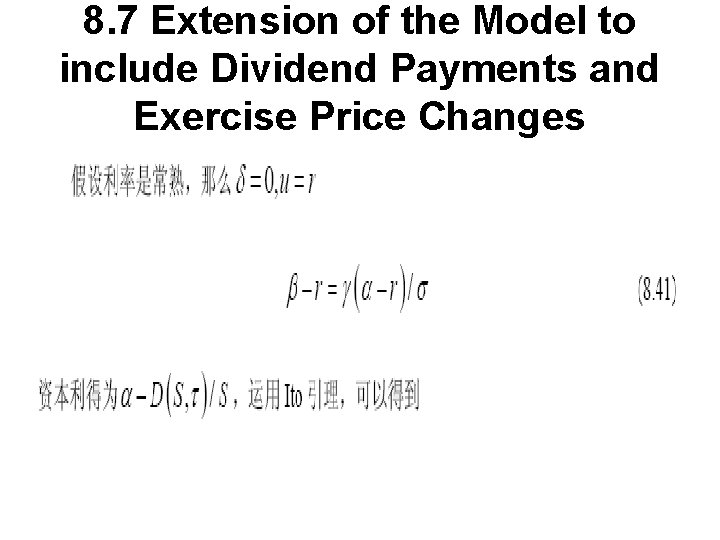
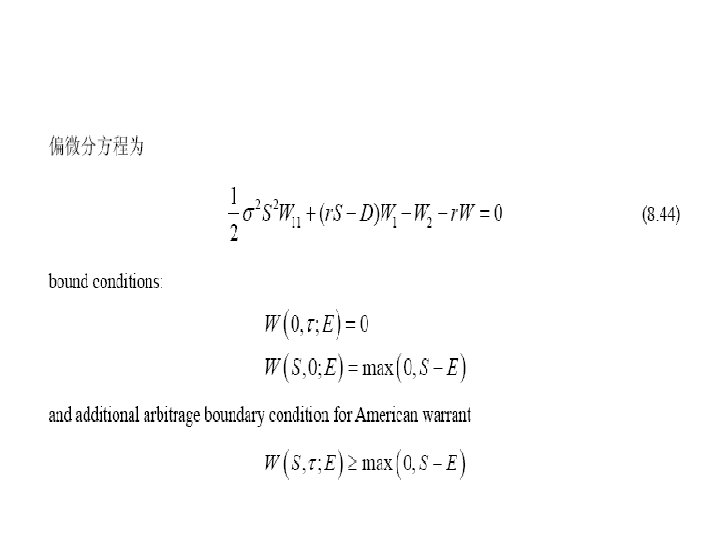
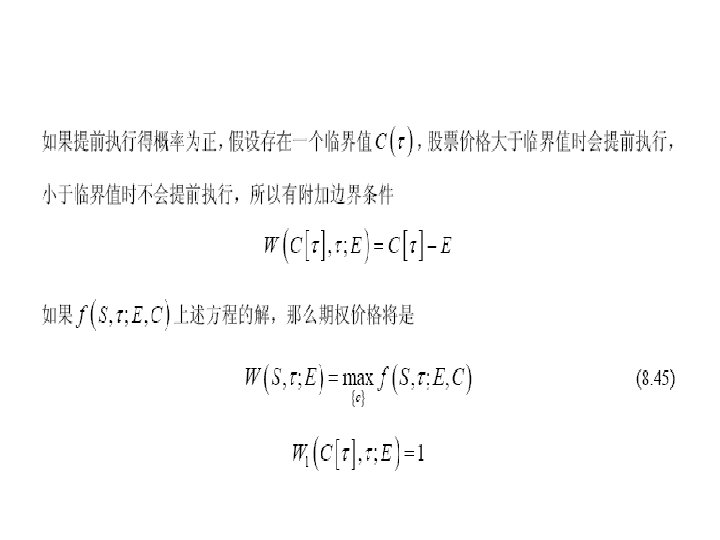
8. 7 Extension of the Model to include Dividend Payments and Exercise Price Changes
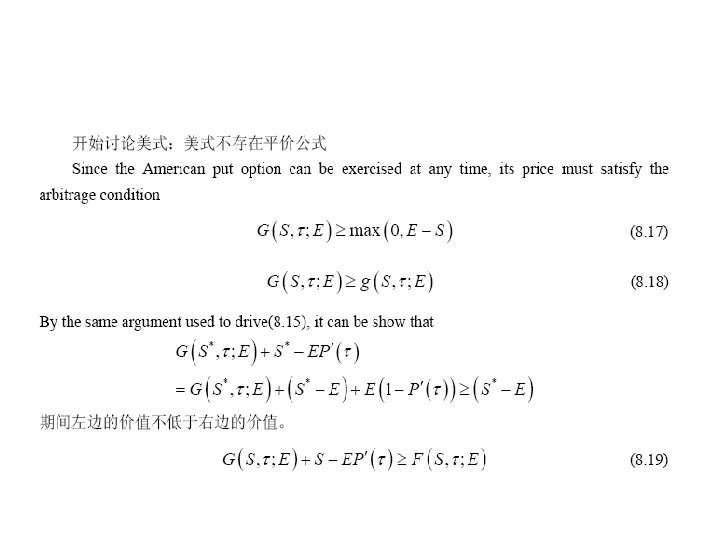
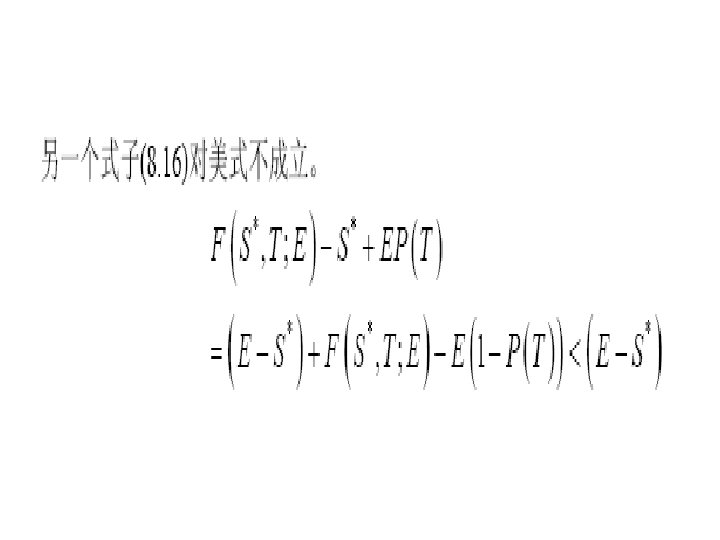
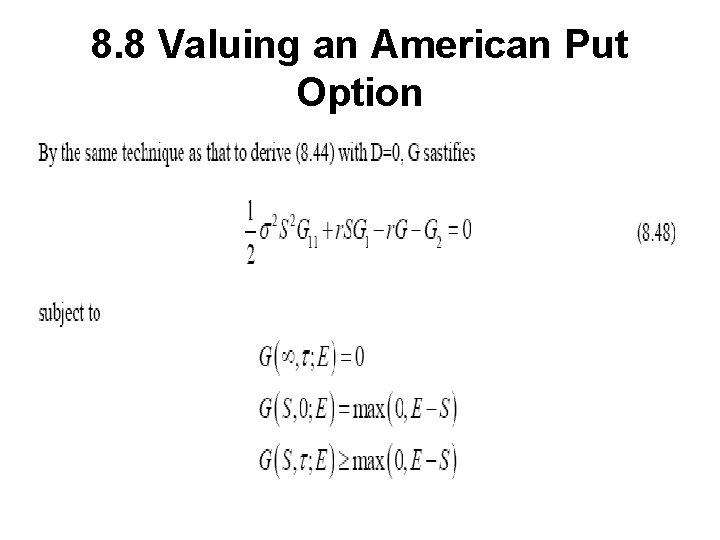
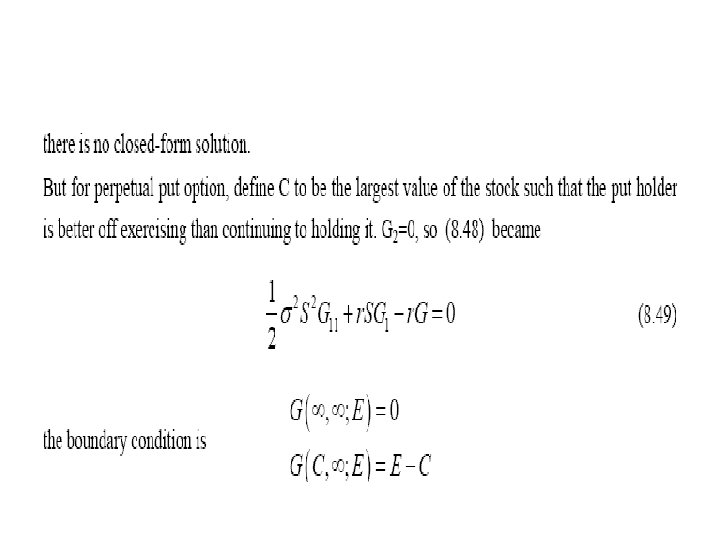
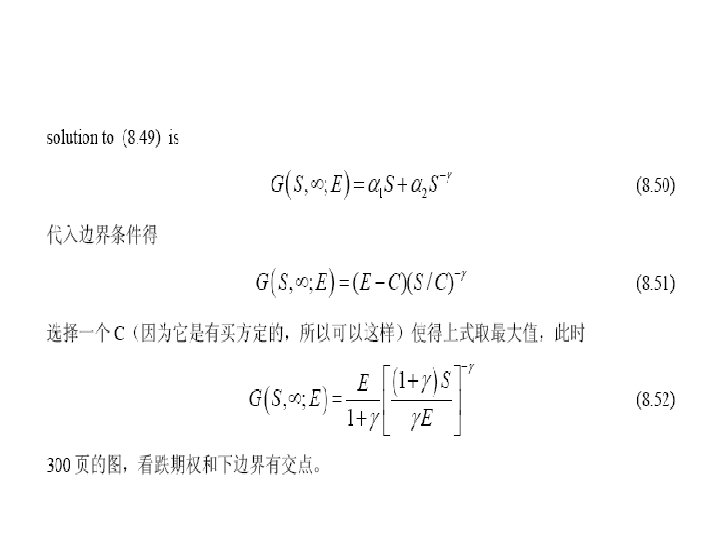
8. 8 Valuing an American Put Option
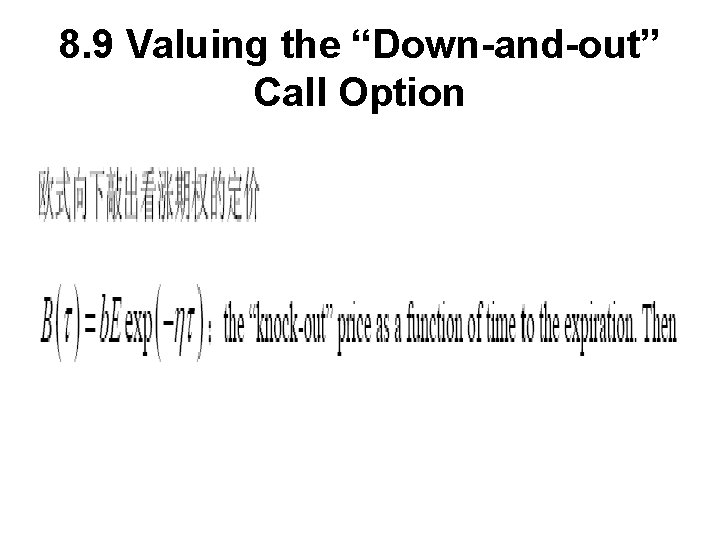
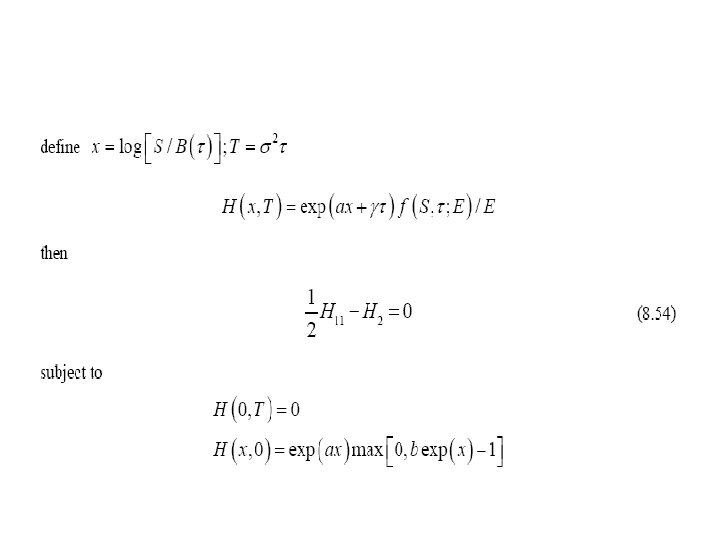
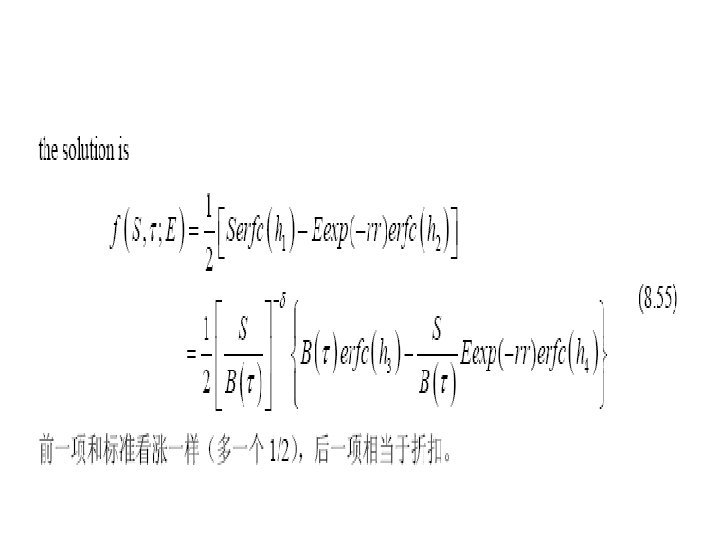
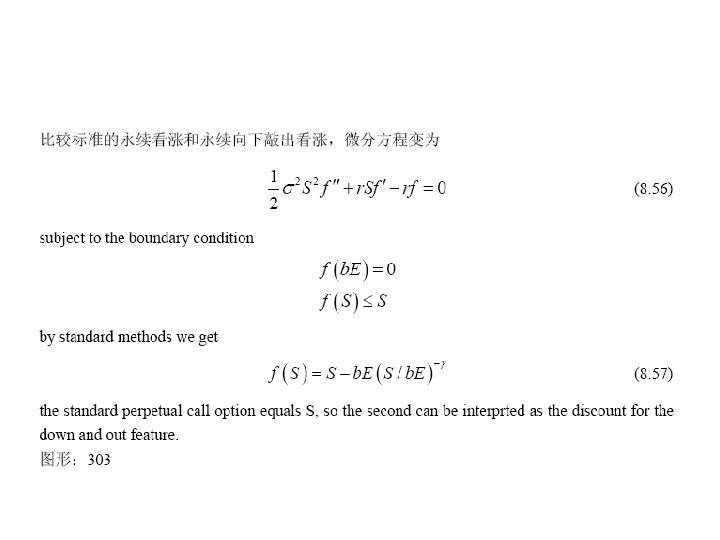
8. 9 Valuing the “Down-and-out” Call Option
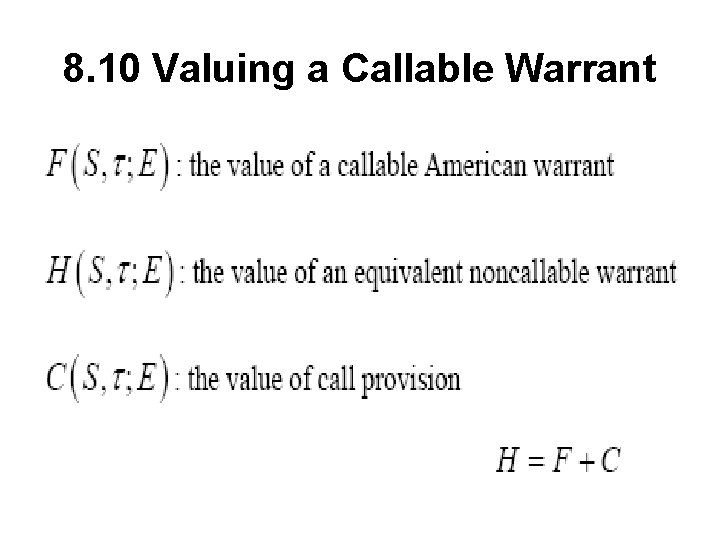
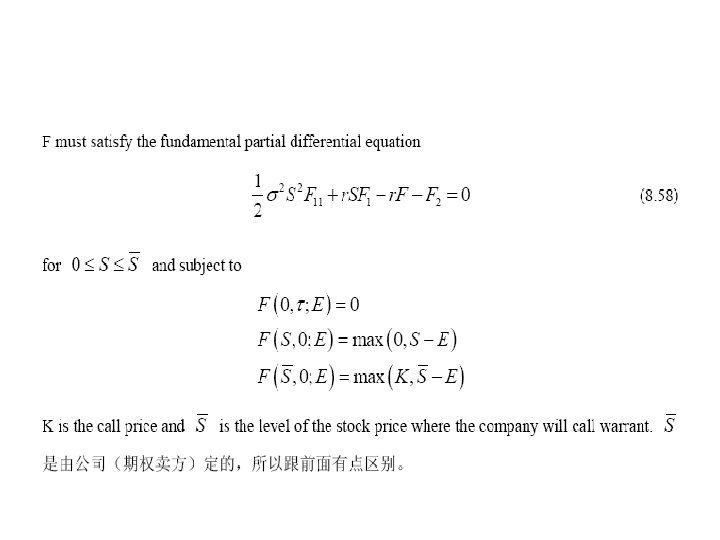
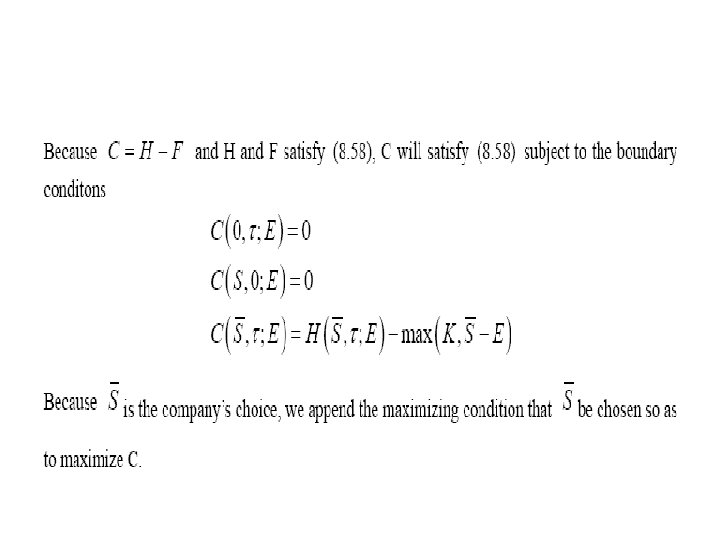
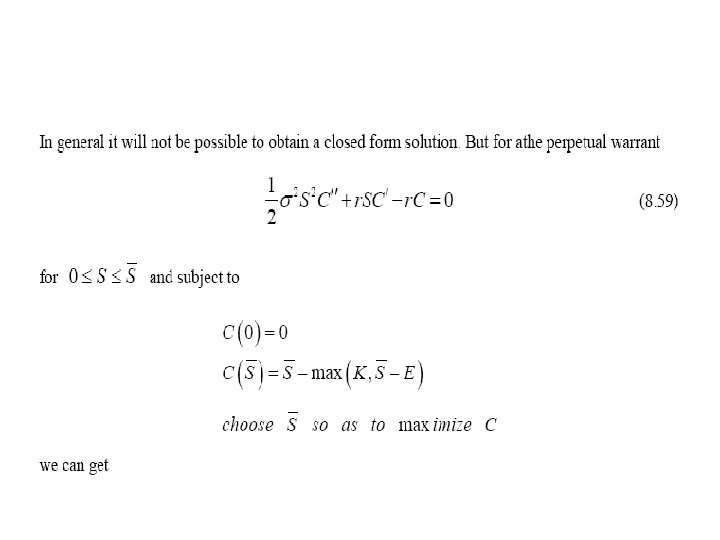
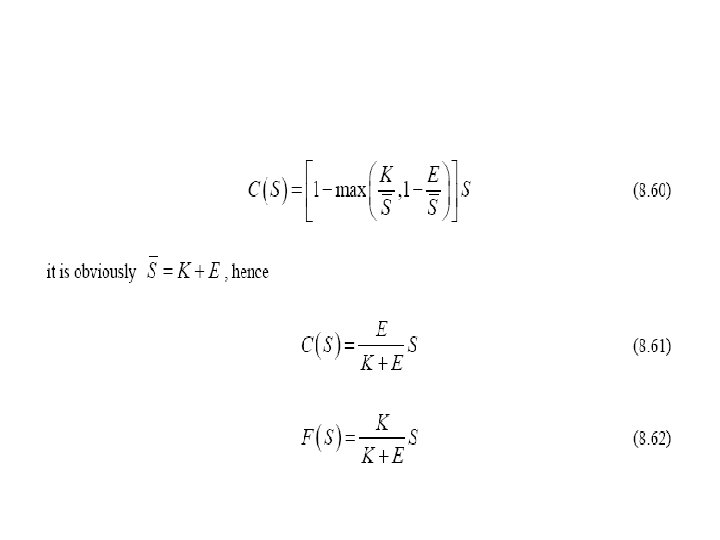
8. 10 Valuing a Callable Warrant