
SIMNYU The Job of the CFO Hybrid Securities
SIM/NYU The Job of the CFO Hybrid Securities Prof. Ian Giddy New York University
The Agenda What determines the optimal mix of debt and equity for a company? l How does altering the mix of debt and equity affect the value of a company? l What is the right kind of debt for a company? l Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 2
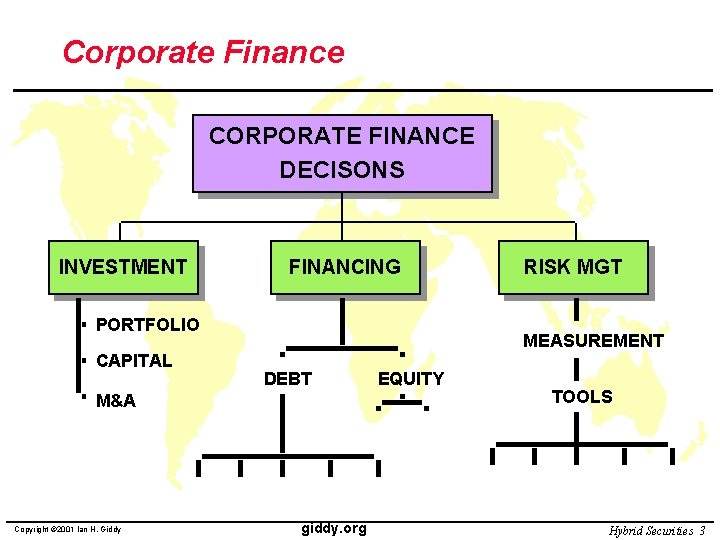
Corporate Finance CORPORATE FINANCE DECISONS INVESTMENT FINANCING PORTFOLIO CAPITAL MEASUREMENT DEBT M&A Copyright © 2001 Ian H. Giddy RISK MGT giddy. org EQUITY TOOLS Hybrid Securities 3
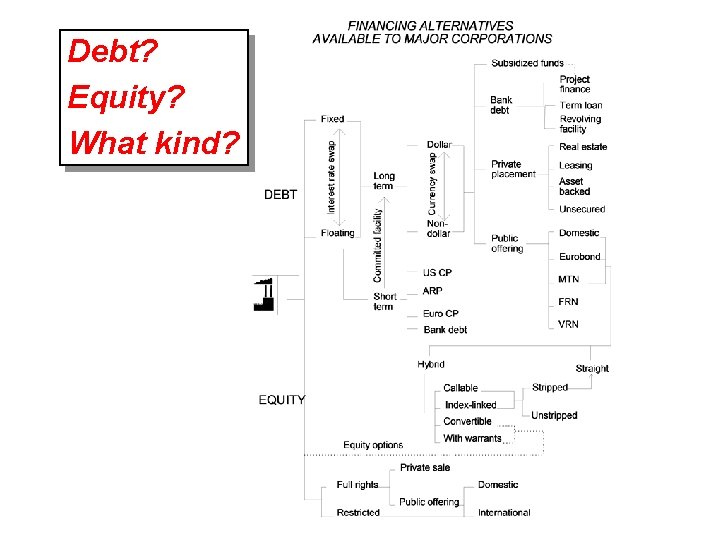
Debt? Equity? What kind?
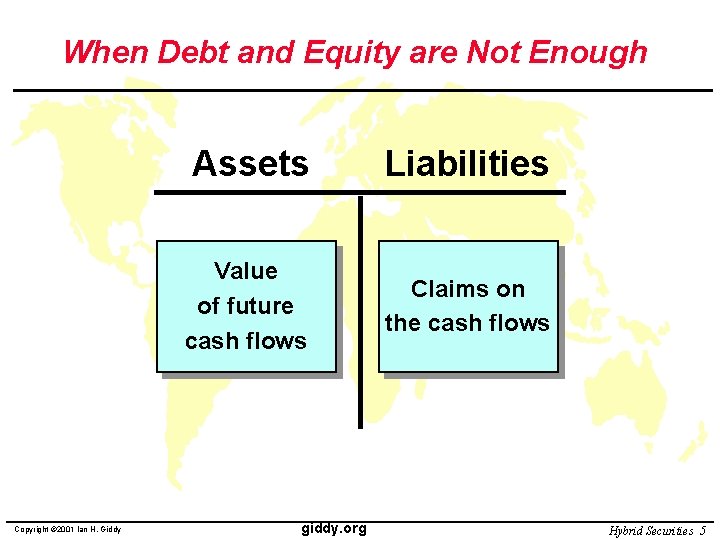
When Debt and Equity are Not Enough Copyright © 2001 Ian H. Giddy Assets Liabilities Value of future cash flows Claims on the cash flows giddy. org Hybrid Securities 5
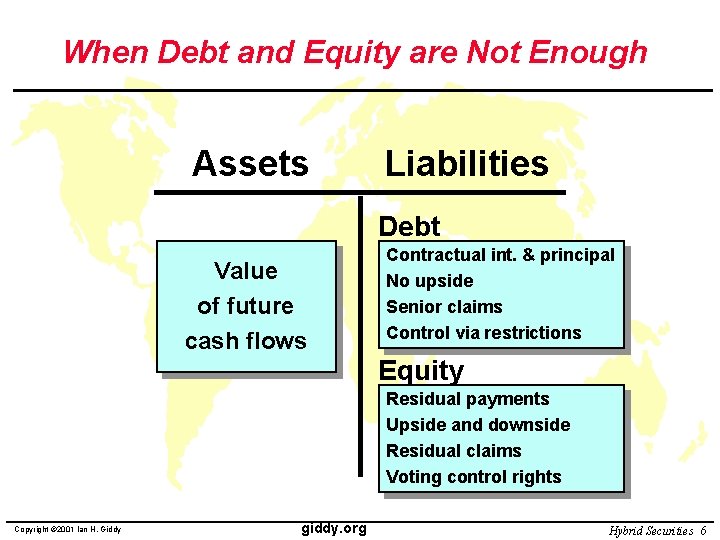
When Debt and Equity are Not Enough Assets Liabilities Debt Value of future cash flows Contractual int. & principal No upside Senior claims Control via restrictions Equity Residual payments Upside and downside Residual claims Voting control rights Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 6
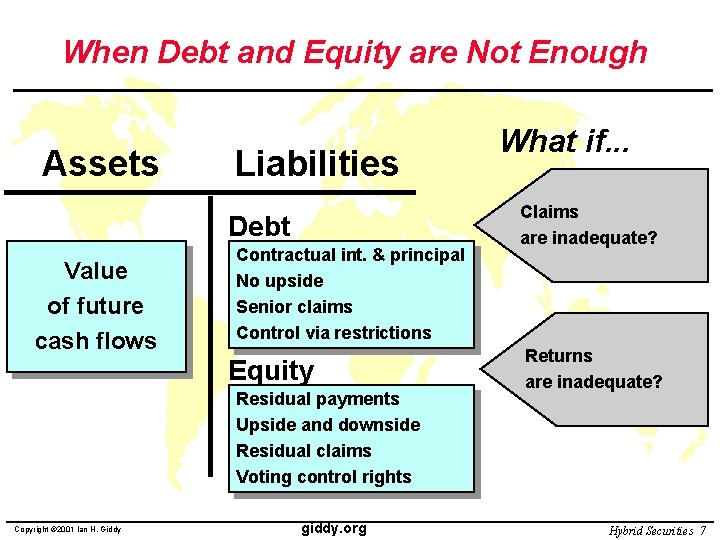
When Debt and Equity are Not Enough Assets Liabilities Debt Value of future cash flows Contractual int. & principal No upside Senior claims Control via restrictions Equity Residual payments Upside and downside Residual claims Voting control rights Copyright © 2001 Ian H. Giddy giddy. org What if. . . Claims are inadequate? Returns are inadequate? Hybrid Securities 7
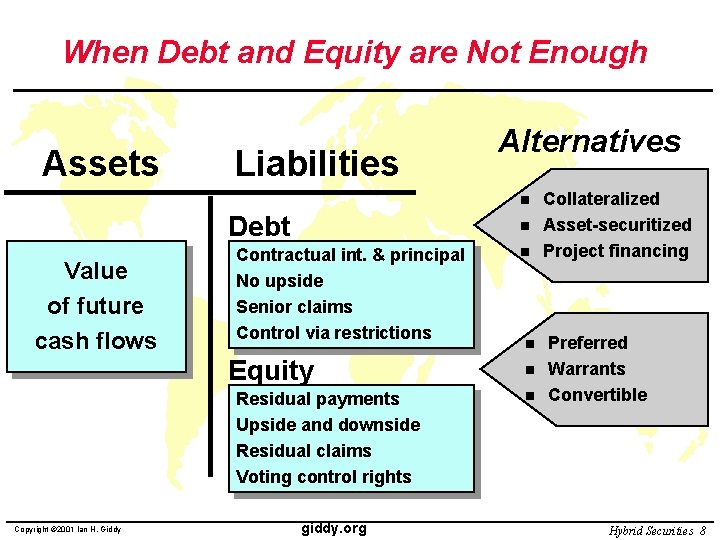
When Debt and Equity are Not Enough Assets Liabilities Alternatives n Debt Value of future cash flows n Contractual int. & principal No upside Senior claims Control via restrictions Equity Residual payments Upside and downside Residual claims Voting control rights Copyright © 2001 Ian H. Giddy giddy. org n n Collateralized Asset-securitized Project financing Preferred Warrants Convertible Hybrid Securities 8
Managing Hybrid Securities Principles of hybrid instruments l Market imperfections as motives for hybrids l Hybrids in the Eurobond market: l u. Asset-backed securities u. Warrant bonds and convertibles u. Index-linked bonds l Application: callable bonds Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 9
A Day in the Life of the Eurobond Market l Examine the deals u. Why were each done in that particular form? u. What determines the pricing? l Can you break the hybrids into their component parts? Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 10
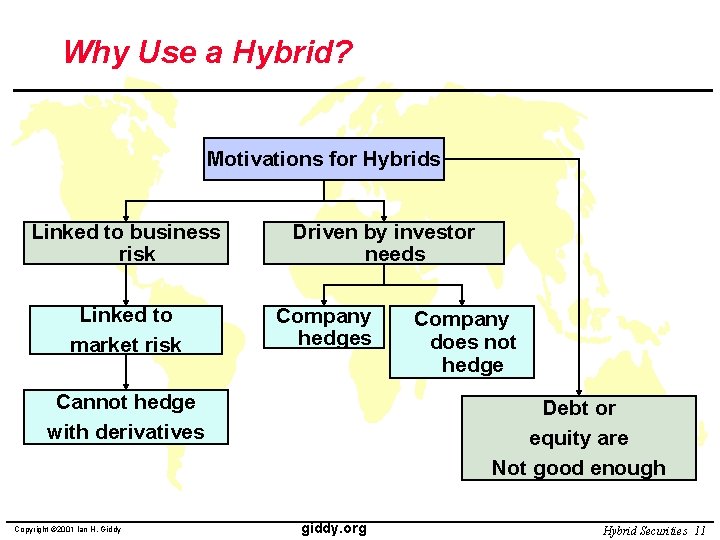
Why Use a Hybrid? Motivations for Hybrids Linked to business risk Linked to market risk Driven by investor needs Company hedges Cannot hedge with derivatives Copyright © 2001 Ian H. Giddy Company does not hedge Debt or equity are Not good enough giddy. org Hybrid Securities 11
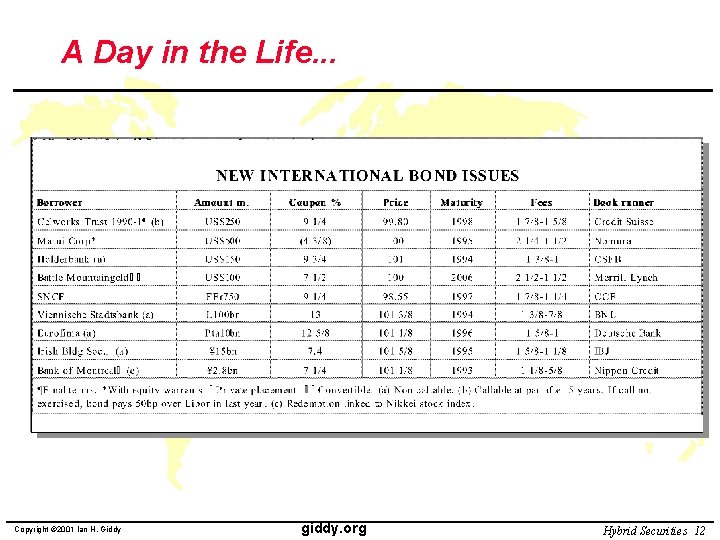
A Day in the Life. . . Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 12
Equity-Linked Eurobonds l Eurobonds with warrants u. Marui l Convertible Eurobonds u. Battle l Mountaingold Index-linked Eurobonds u. Bank Copyright © 2001 Ian H. Giddy of Montreal giddy. org Hybrid Securities 13
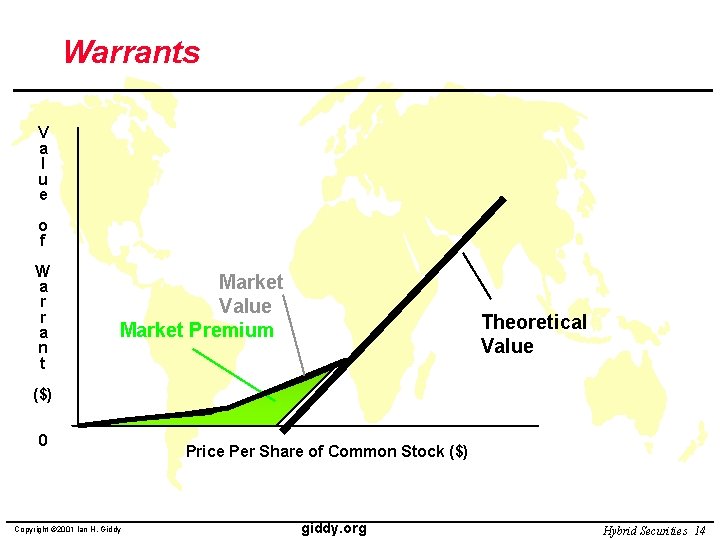
Warrants V a l u e o f W a r r a n t Market Value Market Premium Theoretical Value ($) 0 Copyright © 2001 Ian H. Giddy Price Per Share of Common Stock ($) giddy. org Hybrid Securities 14
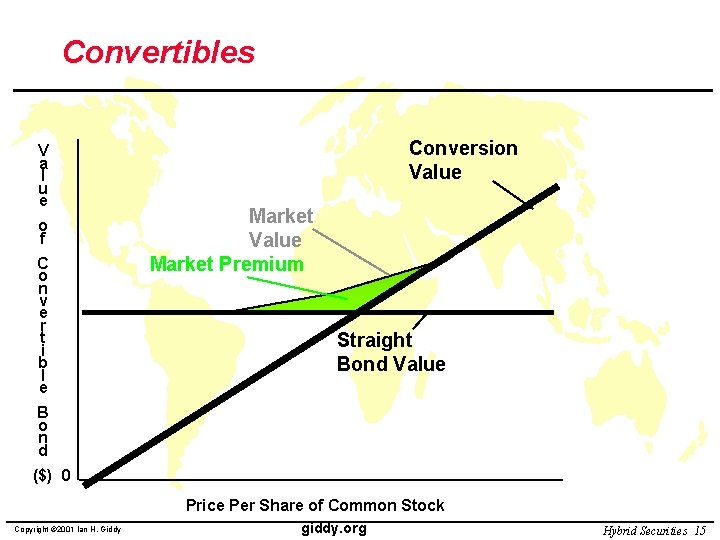
Convertibles V a l u e o f C o n v e r t i b l e Conversion Value Market Value Market Premium Straight Bond Value B o n d ($) 0 Price Per Share of Common Stock Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 15
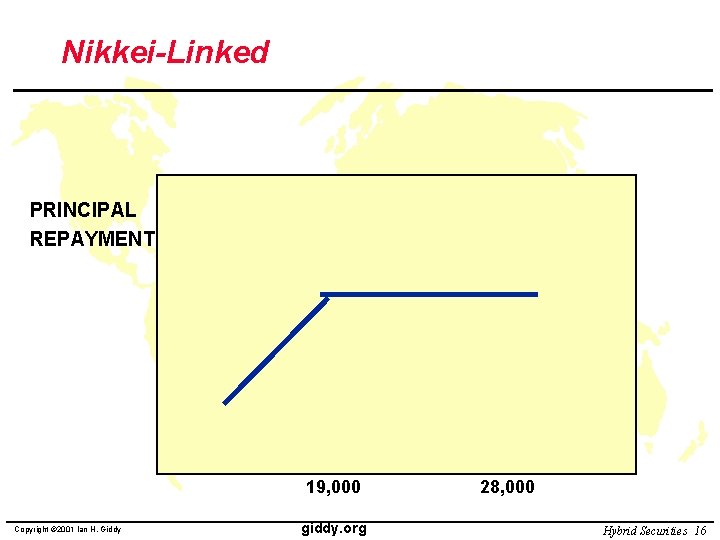
Nikkei-Linked PRINCIPAL REPAYMENT 19, 000 Copyright © 2001 Ian H. Giddy giddy. org 28, 000 Hybrid Securities 16
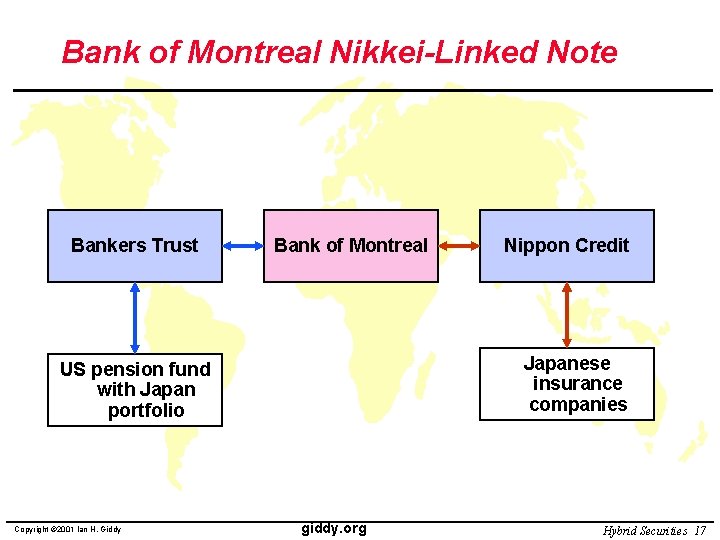
Bank of Montreal Nikkei-Linked Note Bankers Trust Bank of Montreal Japanese insurance companies US pension fund with Japan portfolio Copyright © 2001 Ian H. Giddy Nippon Credit giddy. org Hybrid Securities 17
Structured Notes l l l Bundling and unbundling basic instruments Exploiting market imperfections (sometimes temporary) Creating value added for investor and issuer by tailoring securities to their particular needs Key: For the innovation to work, it must provide value added to both issuer and investor. Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 18
es Carps III 100% CAPITAL-PROTECTED ZERO-COUPON USD EMTN LINKED TO FRANK RUSSELL JAPAN EQUITY FUND l l It l l l l Basic Structure a. This is a USD Euro-Medium Term Note with a maturity of 3 years. b. Societe Generale rated Aa 3 by Moody’s and AA- by S&P) c. Being a zero-coupon Note, the yield is linked to the performance of the Frank Russell Japan Equity Fund. Client Suitability Appropriate for ‘sophisticated investors’ who: a. require only 100% guarantee on capital on maturity b. believe that Japan is on a recovery path and that the stock market of Japan will see significant gains over the medium term c. believe that the Frank Russell Japan Equity Fund is capable of delivering a consistently above-market return with reduced risks. Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 19
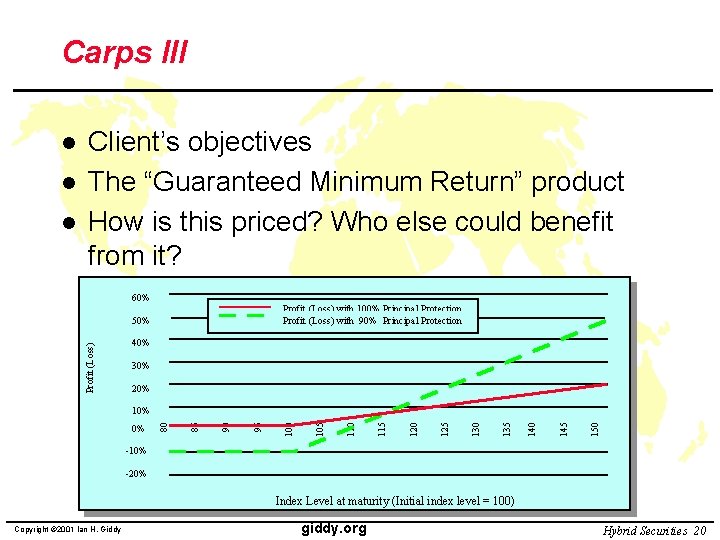
Carps III l l l Client’s objectives The “Guaranteed Minimum Return” product How is this priced? Who else could benefit from it? 60% Profit (Loss) with 100% Principal Protection Profit (Loss) with 90% Principal Protection Profit (Loss) 50% 40% 30% 20% 150 145 140 135 130 125 120 115 110 105 100 95 90 85 0% 80 10% -20% Index Level at maturity (Initial index level = 100) Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 20
Medium-Term Notes: Anatomy of a Deal Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 21
Anatomy of a Deal Issuer: u. Looking for large amounts of floating-rate USD and DEM funding for its loan porfolio. u. Wants low-cost funds: target CP-. 10 u. Is not too concerned about specific timing of issue, amount or maturity u. Is willing to consider hybrid structures. Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 22
Anatomy of a Deal Investor: u. Has distinctive preference for high grade investments u. Looking for investments that will improve portfolio returns relative to relevant indexes u. Invests in both floating rate and fixed rate sterling and dollar securities u. Can buy options to hedge portfolio but cannot sell options Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 23
Anatomy of a Deal Intermediary: u. Has experience and technical and legal background in structure finance u. Has active swap and option trading and positioning capabilities u. Has clients looking for caps and other forms of interest rate protection. Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 24
The Deal 1 2 3 4 Initiate medium term note programme for the borrower, allowing for a variety of currencies, maturities and special structures Structuring a MTN in such a way as to meet the investor’s needs and constraints Line up all potential counterparties and negociate numbers acceptable to all sides Upon issuer’s and investor’s approval, place the securities Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 25
The Deal / 2 5 6 For the issuer, swap and strip the issue into the form of funding that he requires Offer a degree of liquidity to the issuer by standing willing to buy back the securities at a later date. Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 26
The Issue l l l l Issuer: Deutsche Bank AG Amount: US$ 40 Million Coupon: First three years: semi-annual LIBOR + 3/8% p. a. , paid semi-annually Last 5 years: 8. 35% Price: 100 Maturity: February 10, 2000 Call: Issuer may redeem the notes in full at par on February 10, 1995 Fees: 30 bp Arranger: Credit Swiss First Boston Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 27
The Parties in the Deal SCOTTISH LIFE DEUTSCHE CSFB Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 28
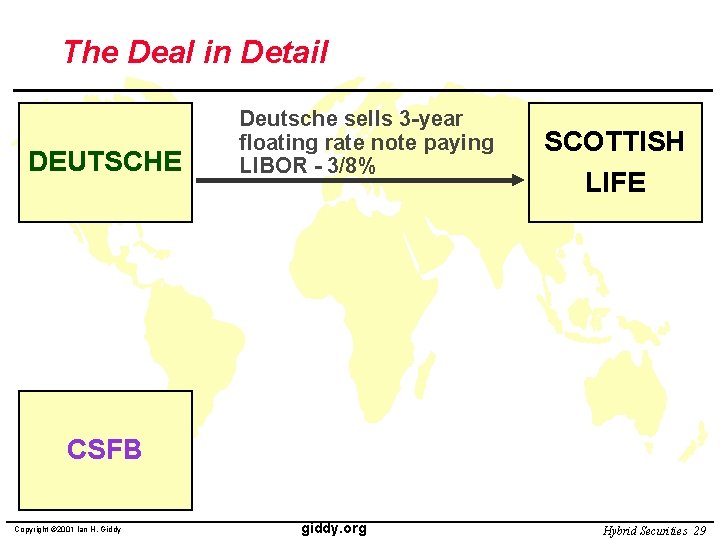
The Deal in Detail Deutsche sells 3 -year DEUTSCHE floating rate note paying LIBOR - 3/8% SCOTTISH LIFE CSFB Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 29
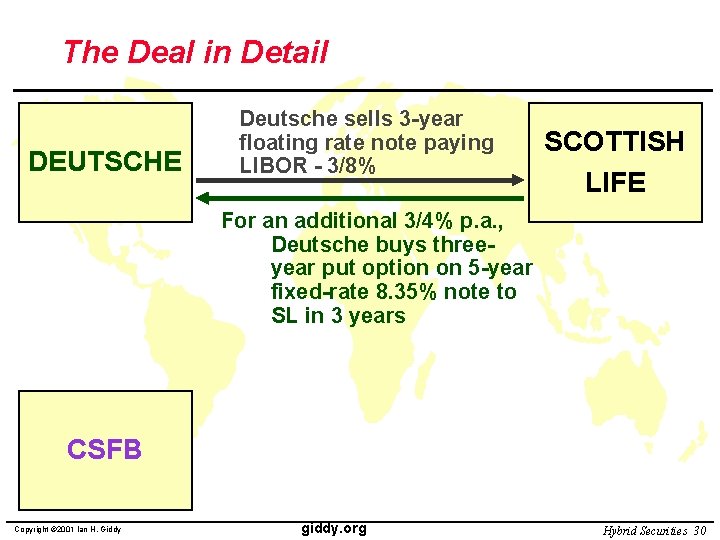
The Deal in Detail Deutsche sells 3 -year DEUTSCHE floating rate note paying LIBOR - 3/8% SCOTTISH LIFE For an additional 3/4% p. a. , Deutsche buys threeyear put option on 5 -year fixed-rate 8. 35% note to SL in 3 years CSFB Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 30
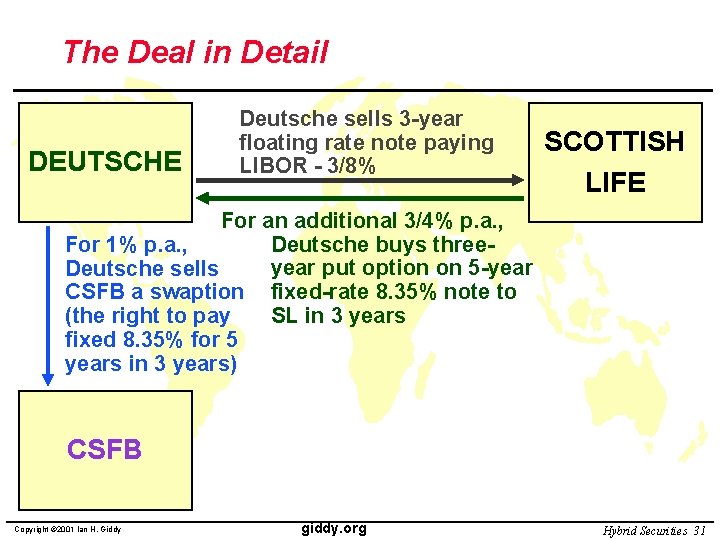
The Deal in Detail Deutsche sells 3 -year DEUTSCHE floating rate note paying LIBOR - 3/8% SCOTTISH LIFE For an additional 3/4% p. a. , Deutsche buys threeyear put option on 5 -year Deutsche sells CSFB a swaption fixed-rate 8. 35% note to SL in 3 years (the right to pay fixed 8. 35% for 5 years in 3 years) For 1% p. a. , CSFB Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 31
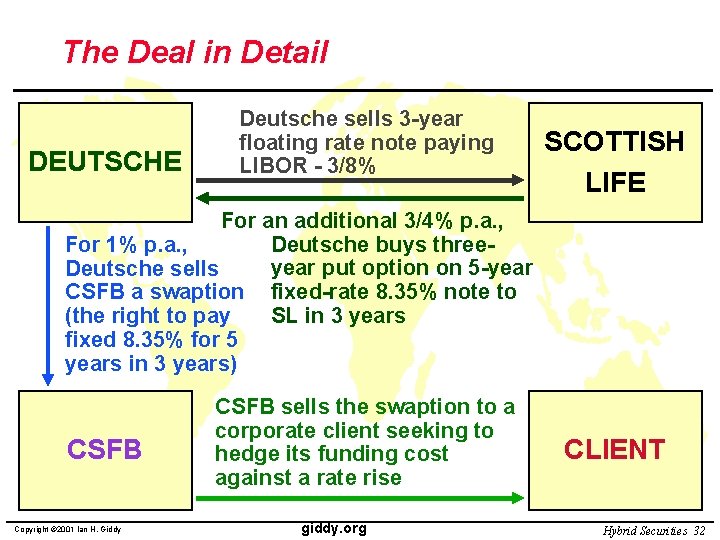
The Deal in Detail Deutsche sells 3 -year floating rate note paying LIBOR - 3/8% DEUTSCHE SCOTTISH LIFE For an additional 3/4% p. a. , Deutsche buys threeyear put option on 5 -year Deutsche sells CSFB a swaption fixed-rate 8. 35% note to SL in 3 years (the right to pay fixed 8. 35% for 5 years in 3 years) For 1% p. a. , CSFB sells the swaption to a CSFB Copyright © 2001 Ian H. Giddy corporate client seeking to hedge its funding cost against a rate rise giddy. org CLIENT Hybrid Securities 32
What’s Really Going On? Note: l l Issuer has agreed to pay an above-market rate on both the floating rate note and the fixed rate bond segment of the issue FRN portion: . 75 % above normal cost Fixed portion: . 50% above normal cost Issuer has in effect purchased the right to pay a fixed rate of 8. 35% on a five-year bond to be issued in three years time. Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 33
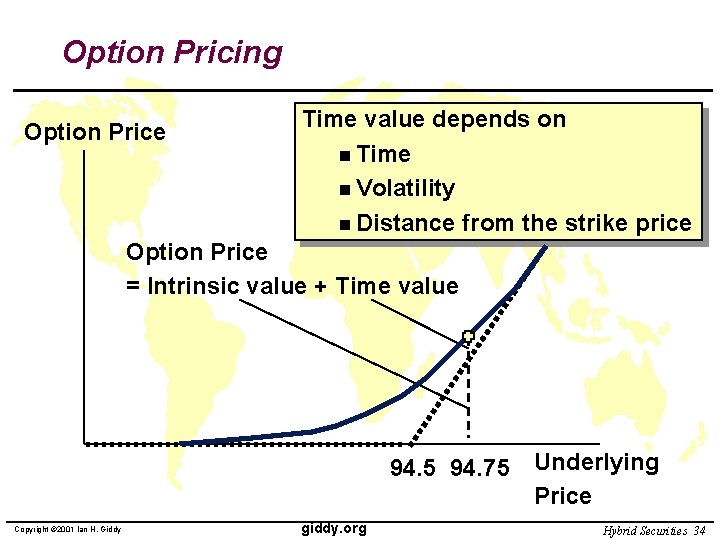
Option Pricing Option Price Time value depends on n Time n Volatility n Distance from the strike price Option Price = Intrinsic value + Time value 94. 5 94. 75 Underlying Price Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 34
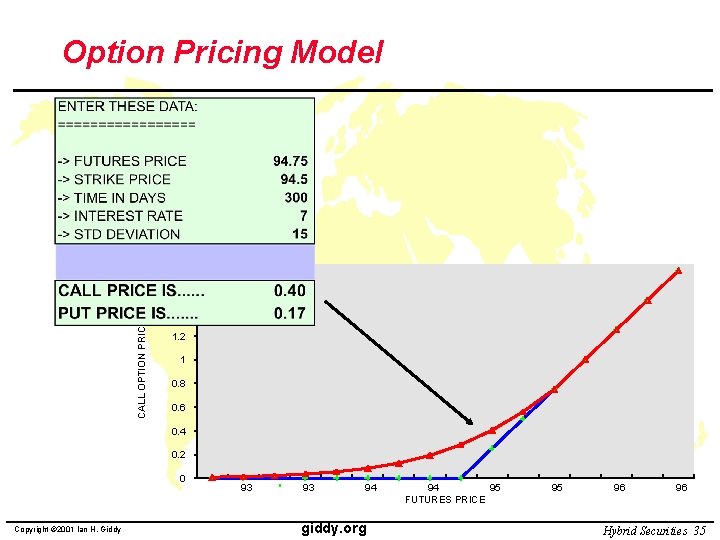
Option Pricing Model 1. 8 1. 6 CALL OPTION PRICE 1. 4 1. 2 1 0. 8 0. 6 0. 4 0. 2 0 Copyright © 2001 Ian H. Giddy 93 93 94 giddy. org 94 95 FUTURES PRICE 95 96 96 Hybrid Securities 35
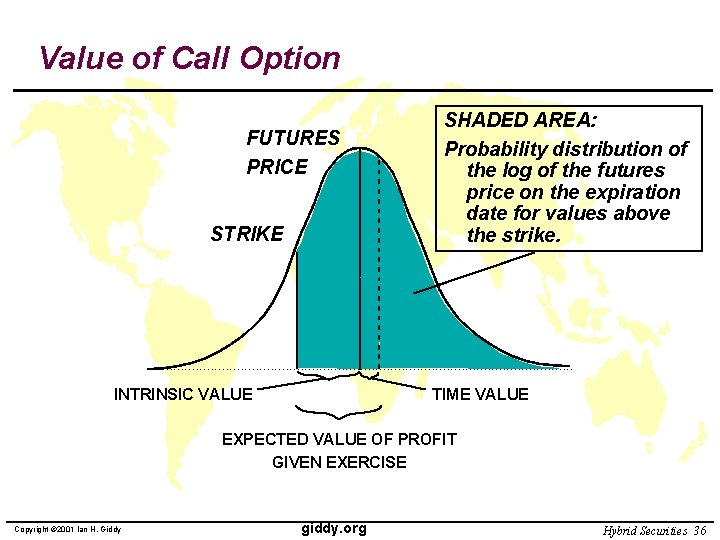
Value of Call Option FUTURES PRICE STRIKE INTRINSIC VALUE SHADED AREA: Probability distribution of the log of the futures price on the expiration date for values above the strike. TIME VALUE EXPECTED VALUE OF PROFIT GIVEN EXERCISE Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 36
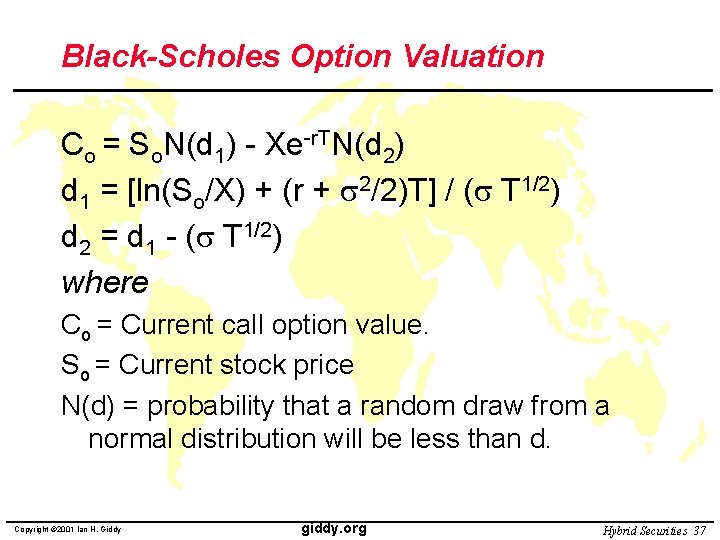
Black-Scholes Option Valuation Co = So. N(d 1) - Xe-r. TN(d 2) d 1 = [ln(So/X) + (r + 2/2)T] / ( T 1/2) d 2 = d 1 - ( T 1/2) where Co = Current call option value. So = Current stock price N(d) = probability that a random draw from a normal distribution will be less than d. Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 37
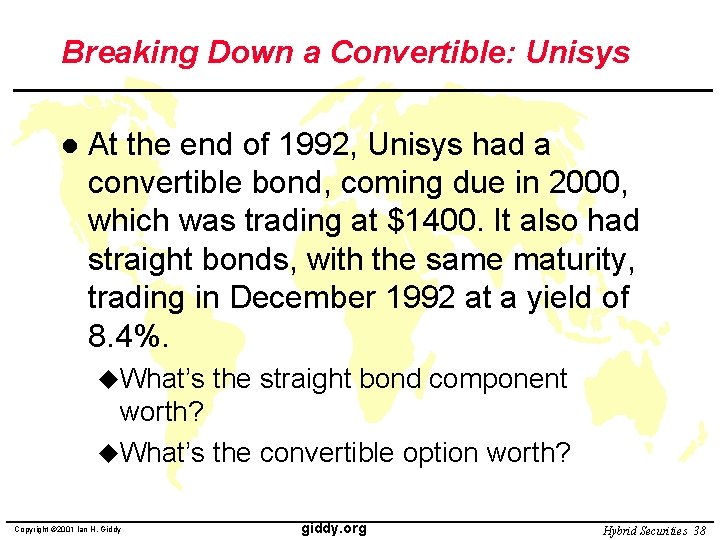
Breaking Down a Convertible: Unisys l At the end of 1992, Unisys had a convertible bond, coming due in 2000, which was trading at $1400. It also had straight bonds, with the same maturity, trading in December 1992 at a yield of 8. 4%. u. What’s the straight bond component worth? u. What’s the convertible option worth? Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 38
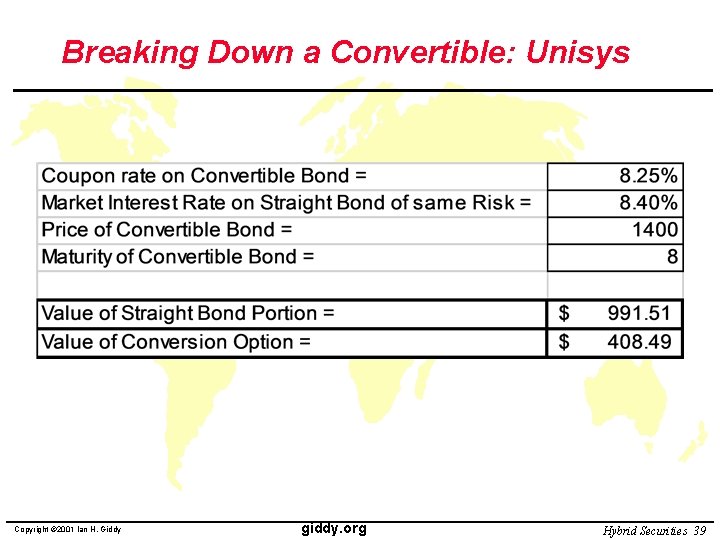
Breaking Down a Convertible: Unisys Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 39
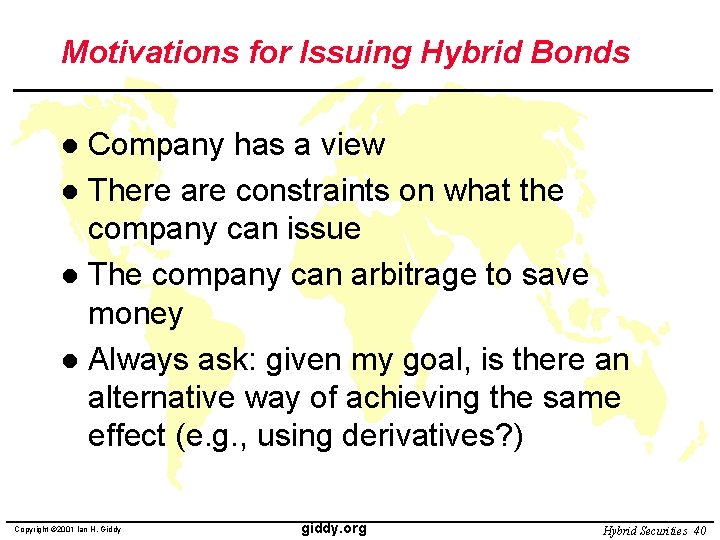
Motivations for Issuing Hybrid Bonds Company has a view l There are constraints on what the company can issue l The company can arbitrage to save money l Always ask: given my goal, is there an alternative way of achieving the same effect (e. g. , using derivatives? ) l Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 40
Economics of Financial Innovation Certain kinds of market imperfections allow hybrids to flourish l But innovation are readily copied; so only certain kinds of firm can profit from innovations. l There is a product cycle and profitability cycle of innovations. l Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 41
What Conditions Permit Hybrids to Thrive? l Government Rules and Regulations Example: Japan Air Lines Yen-linked Eurobond l Tax Distortions Example: Money Market Preferred l Constraint on Issuers or Investors Example: Nikkei-Linked Eurobond l Segmentation-Driven Innovation Example: Collateralized Mortgage Obligations (CMOs) Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 42
Why Innovations Fail The rationale evaporates l It’s too costly l It’s New Coke l Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 43
Case Study: Banpu Convertible n How did this work? n Why did Banpu use this technique? n Why did investors buy it? Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 44
Banpu Convertible Huh? Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 45
Thai Time n 1994 Copyright © 2001 Ian H. Giddy n 1997 n giddy. org 1999 n 2004 Hybrid Securities 46
Leveraged Finance Prof. Ian Giddy New York University
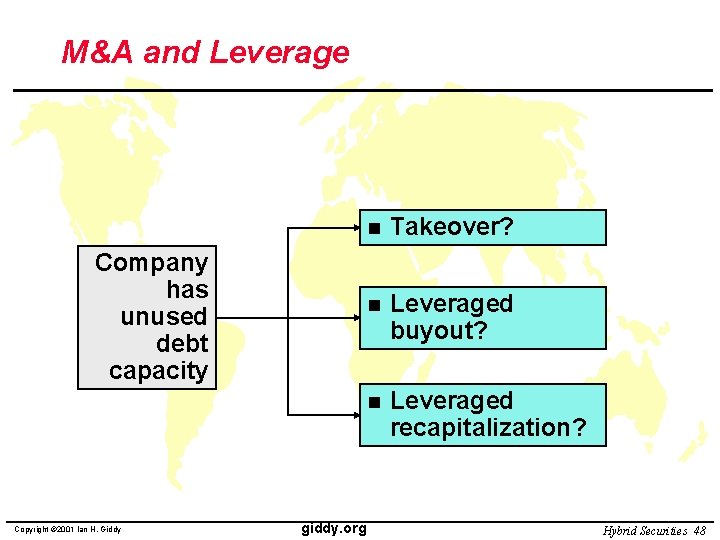
M&A and Leverage Company has unused debt capacity Copyright © 2001 Ian H. Giddy giddy. org n Takeover? n Leveraged buyout? n Leveraged recapitalization? Hybrid Securities 48
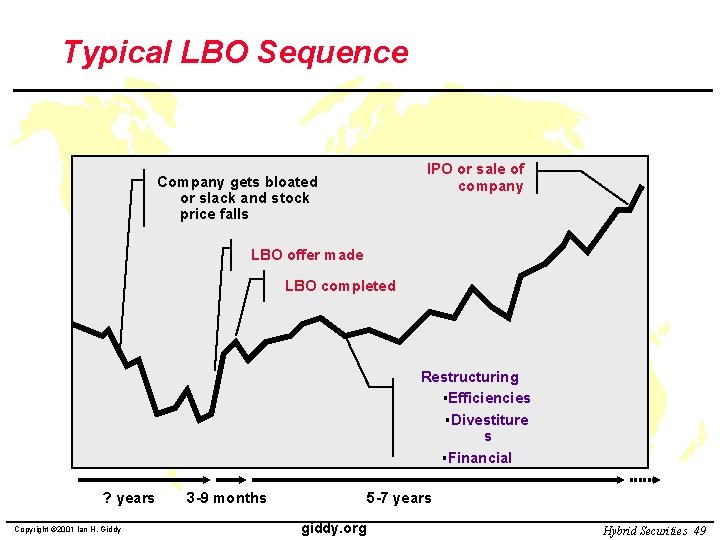
Typical LBO Sequence IPO or sale of company Company gets bloated or slack and stock price falls LBO offer made LBO completed Restructuring §Efficiencies §Divestiture s §Financial ? years Copyright © 2001 Ian H. Giddy 3 -9 months 5 -7 years giddy. org Hybrid Securities 49
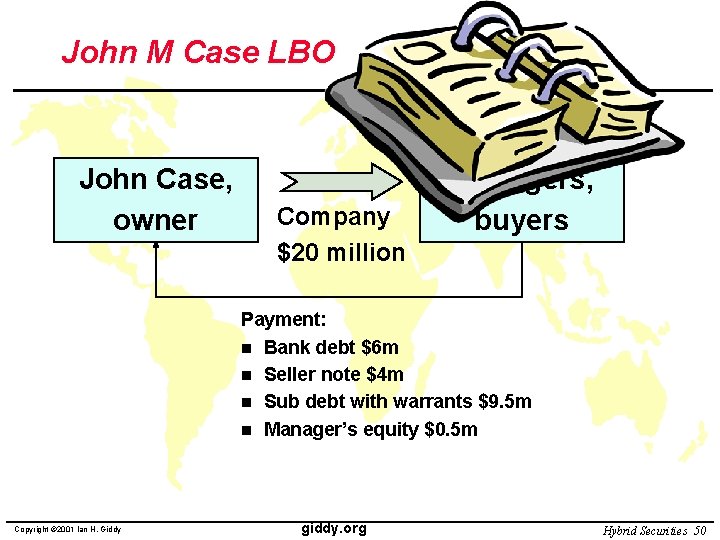
John M Case LBO John Case, owner Company $20 million Managers, buyers Payment: n Bank debt $6 m n Seller note $4 m n Sub debt with warrants $9. 5 m n Manager’s equity $0. 5 m Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 50
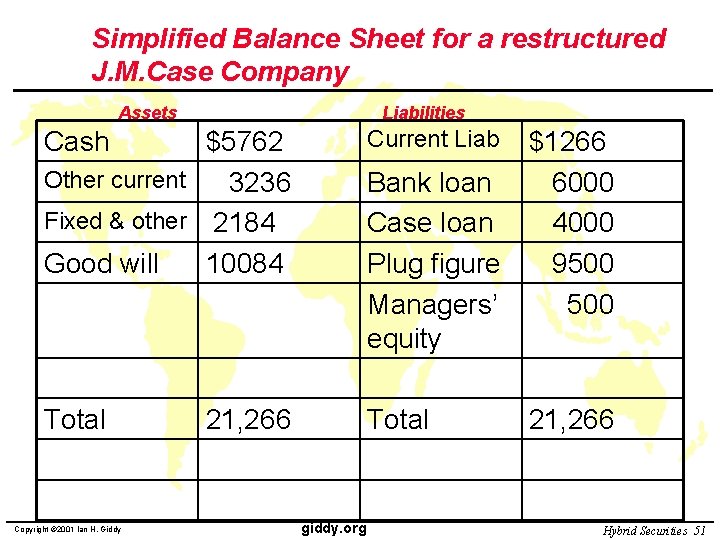
Simplified Balance Sheet for a restructured J. M. Case Company Assets Liabilities $5762 Other current 3236 Fixed & other 2184 Good will 10084 Current Liab Total Cash Copyright © 2001 Ian H. Giddy $1266 Bank loan 6000 Case loan 4000 Plug figure 9500 Managers’ 500 equity 21, 266 giddy. org 21, 266 Hybrid Securities 51
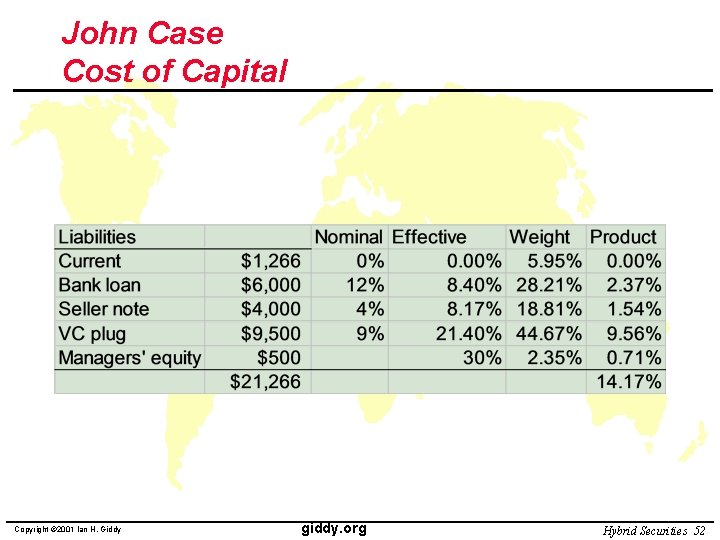
John Case Cost of Capital Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 52
giddyonline. com Ian Giddy NYU Stern School of Business Tel 212 -998 -0332; Fax 917 -463 -7629 ian. giddy@nyu. edu http: //www. giddy. org Copyright © 2001 Ian H. Giddy giddy. org Hybrid Securities 56
- Slides: 53