Chapter 4 Consolidation Techniques and Procedures to accompany


- Slides: 49
Chapter 4: Consolidation Techniques and Procedures to accompany Advanced Accounting, 11 th edition by Beams, Anthony, Bettinghaus, and Smith Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -1
Consolidation Techniques: Objectives 1. Prepare consolidation workpaper for the year of acquisition when the parent uses the complete equity method to account for its investment in a subsidiary. 2. Prepare consolidation workpaper for the years subsequent to acquisition. 3. Locate errors in consolidation workpaper. 4. Assign fair value to identifiable net assets. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -2
Objectives (continued) 5. Apply concepts to prepare a consolidated statement of cash flows. 6. Appendix: Understand the alternative trial balance consolidation workpaper format. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -3
Consolidation Techniques and Procedures 1: ACQUISITION-YEAR WORKPAPERS Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -4
Preparing the Worksheet Statements are entered onto the worksheet: v Income statement v Statement of retained earnings v Balance sheet Columns needed: v Parent v Subsidiary v DR and CR columns for elimination entries v Consolidated Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -5
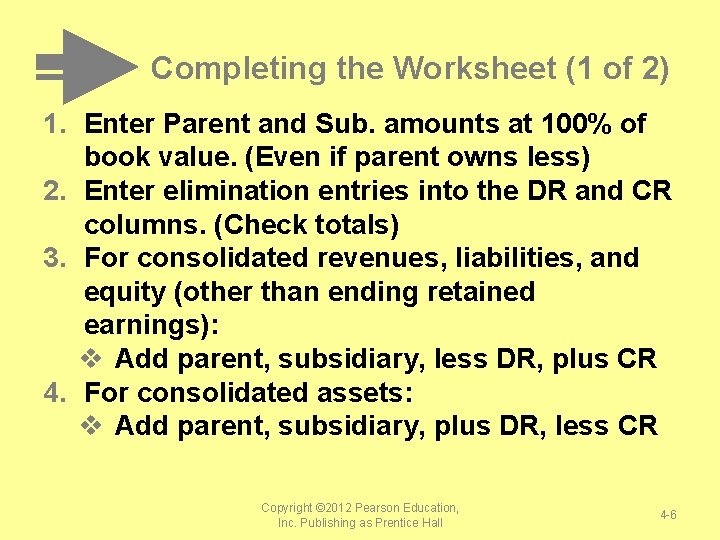
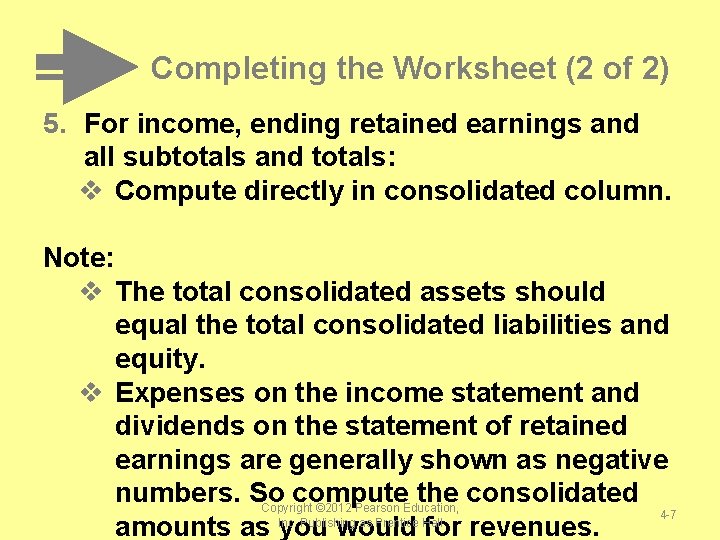
Completing the Worksheet (1 of 2) 1. Enter Parent and Sub. amounts at 100% of book value. (Even if parent owns less) 2. Enter elimination entries into the DR and CR columns. (Check totals) 3. For consolidated revenues, liabilities, and equity (other than ending retained earnings): v Add parent, subsidiary, less DR, plus CR 4. For consolidated assets: v Add parent, subsidiary, plus DR, less CR Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -6
Completing the Worksheet (2 of 2) 5. For income, ending retained earnings and all subtotals and totals: v Compute directly in consolidated column. Note: v The total consolidated assets should equal the total consolidated liabilities and equity. v Expenses on the income statement and dividends on the statement of retained earnings are generally shown as negative numbers. So compute the consolidated Copyright © 2012 Pearson Education, 4 -7 Inc. Publishing as Prentice Hall amounts as you would for revenues.
Workpaper Entries 1. Adjust for errors & omissions 2. Eliminate intercompany profits and losses 3. Eliminate income & dividends from sub. and bring Investment account to its beginning balance 4. Record noncontrolling interest in sub. 's earnings & dividends 5. Eliminate reciprocal Investment & sub. 's equity balances 6. Amortize fair value differentials 7. Eliminate other reciprocal balances Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -8
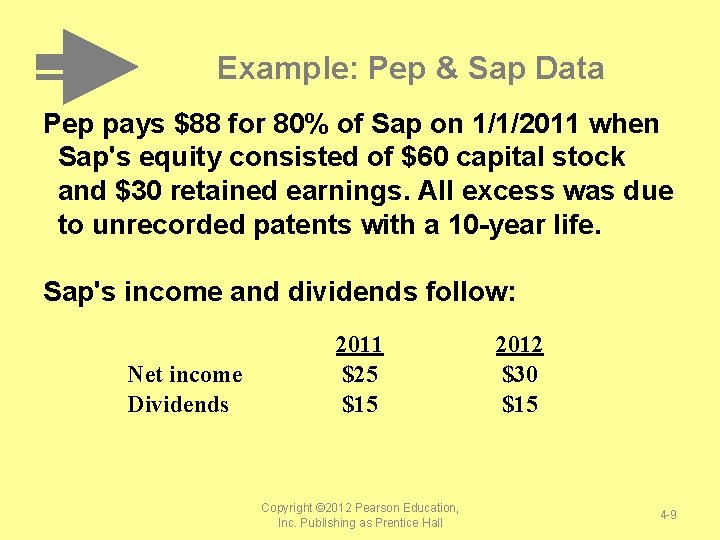
Example: Pep & Sap Data Pep pays $88 for 80% of Sap on 1/1/2011 when Sap's equity consisted of $60 capital stock and $30 retained earnings. All excess was due to unrecorded patents with a 10 -year life. Sap's income and dividends follow: Net income Dividends 2011 $25 $15 Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 2012 $30 $15 4 -9
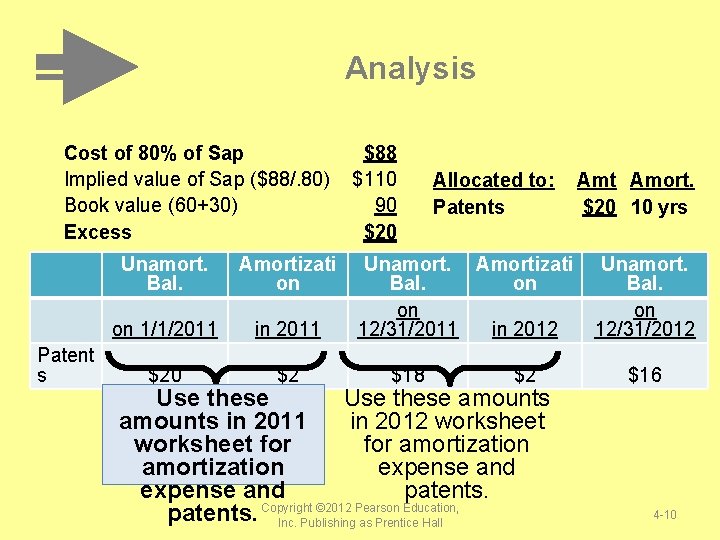
Analysis Cost of 80% of Sap Implied value of Sap ($88/. 80) Book value (60+30) Excess Patent s Unamort. Bal. Amortizati on on 1/1/2011 in 2011 $20 $2 $88 $110 90 $20 Allocated to: Patents Unamort. Amortizati Bal. on on 12/31/2011 in 2012 $18 $2 Use these amounts in 2011 in 2012 worksheet for amortization expense and patents. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall Amt Amort. $20 10 yrs Unamort. Bal. on 12/31/2012 $16 4 -10
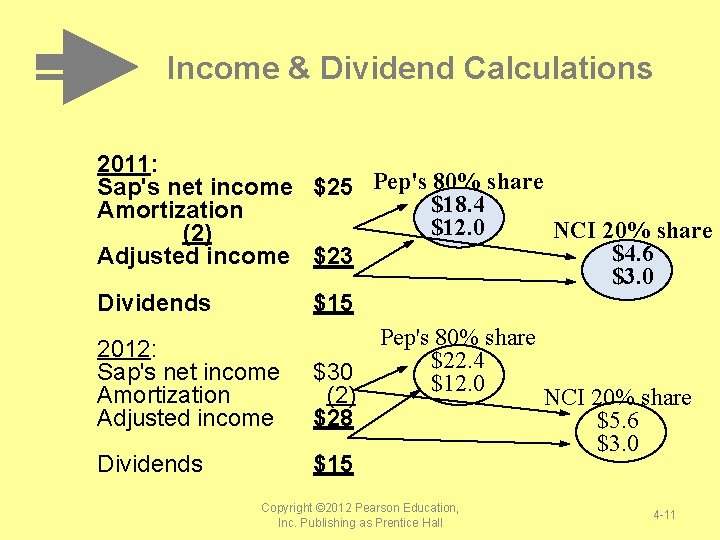
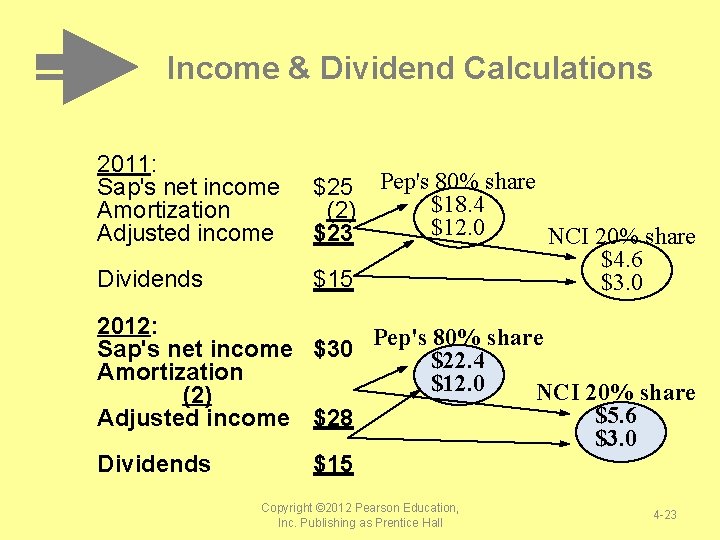
Income & Dividend Calculations 2011: Sap's net income $25 Pep's 80% share $18. 4 Amortization $12. 0 NCI 20% share (2) $4. 6 Adjusted income $23 $3. 0 Dividends $15 Pep's 80% share 2012: $22. 4 Sap's net income $30 $12. 0 Amortization (2) NCI 20% share Adjusted income $28 $5. 6 $3. 0 Dividends $15 Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -11
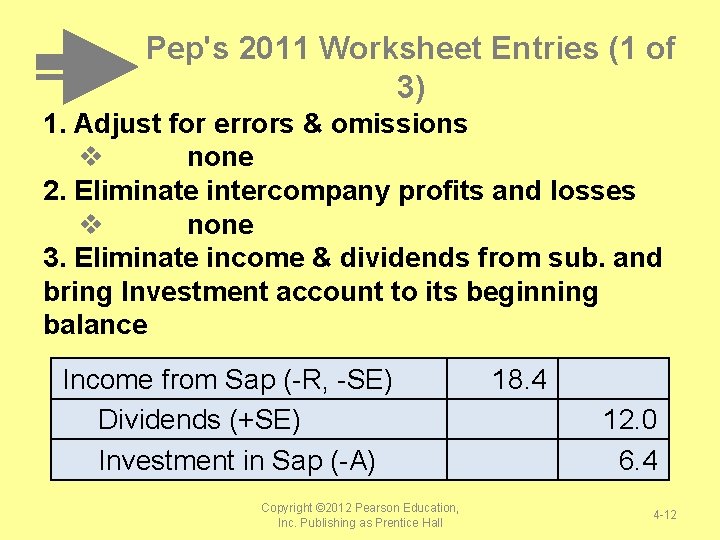
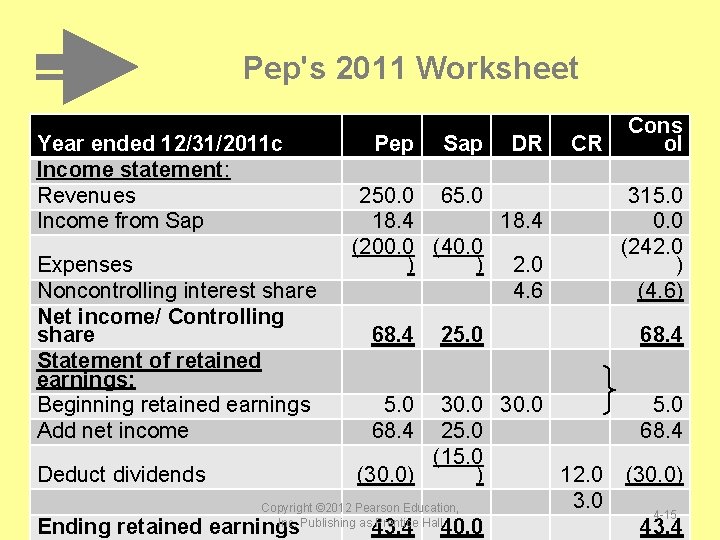
Pep's 2011 Worksheet Entries (1 of 3) 1. Adjust for errors & omissions v none 2. Eliminate intercompany profits and losses v none 3. Eliminate income & dividends from sub. and bring Investment account to its beginning balance Income from Sap (-R, -SE) Dividends (+SE) Investment in Sap (-A) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 18. 4 12. 0 6. 4 4 -12
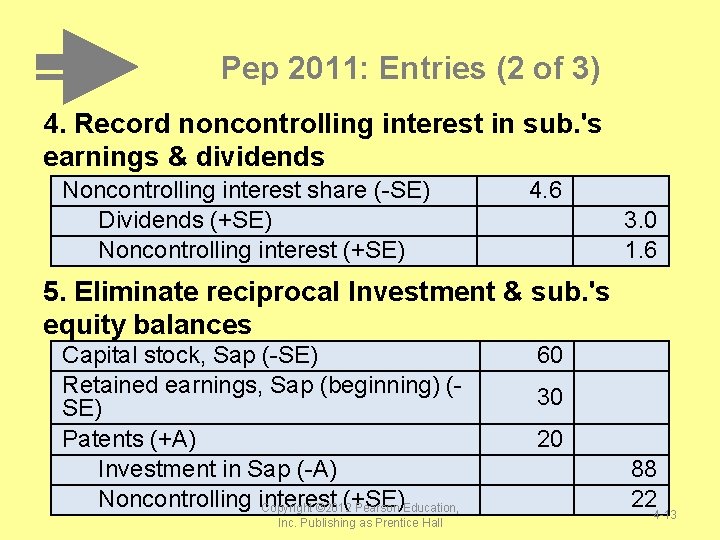
Pep 2011: Entries (2 of 3) 4. Record noncontrolling interest in sub. 's earnings & dividends Noncontrolling interest share (-SE) Dividends (+SE) Noncontrolling interest (+SE) 4. 6 3. 0 1. 6 5. Eliminate reciprocal Investment & sub. 's equity balances Capital stock, Sap (-SE) Retained earnings, Sap (beginning) (SE) Patents (+A) Investment in Sap (-A) Noncontrolling interest (+SE) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 60 30 20 88 22 4 -13
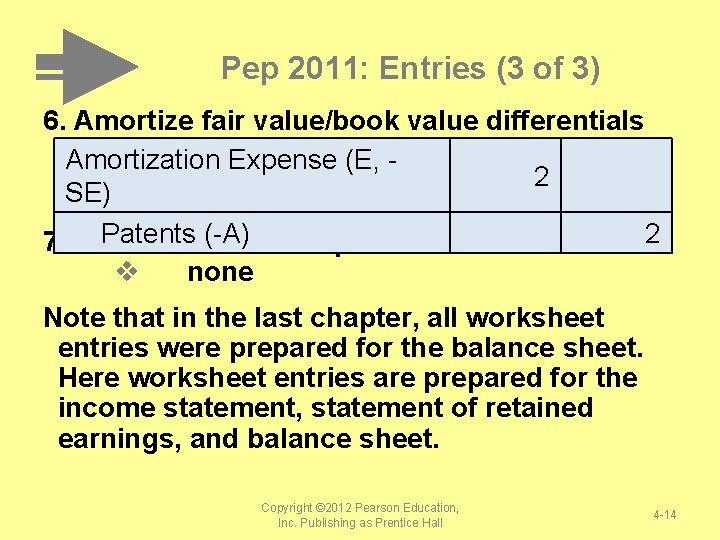
Pep 2011: Entries (3 of 3) 6. Amortize fair value/book value differentials Amortization Expense (E, 2 SE) Patents (-A) 2 7. Eliminate other reciprocal balances v none Note that in the last chapter, all worksheet entries were prepared for the balance sheet. Here worksheet entries are prepared for the income statement, statement of retained earnings, and balance sheet. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -14
Pep's 2011 Worksheet Year ended 12/31/2011 c Income statement: Revenues Income from Sap Expenses Noncontrolling interest share Net income/ Controlling share Statement of retained earnings: Beginning retained earnings Add net income Pep Sap DR CR 250. 0 65. 0 18. 4 (200. 0 (40. 0 ) ) 2. 0 4. 6 68. 4 25. 0 Cons ol 315. 0 0. 0 (242. 0 ) (4. 6) 68. 4 5. 0 30. 0 5. 0 68. 4 25. 0 68. 4 (15. 0 Deduct dividends (30. 0) ) 12. 0 (30. 0) 3. 0 Copyright © 2012 Pearson Education, 4 -15 Inc. Publishing as Prentice Hall Ending retained earnings 43. 4 40. 0 43. 4
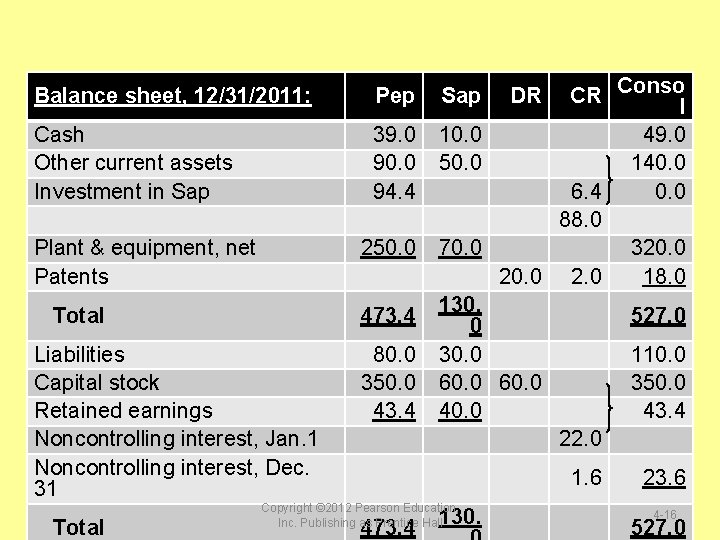
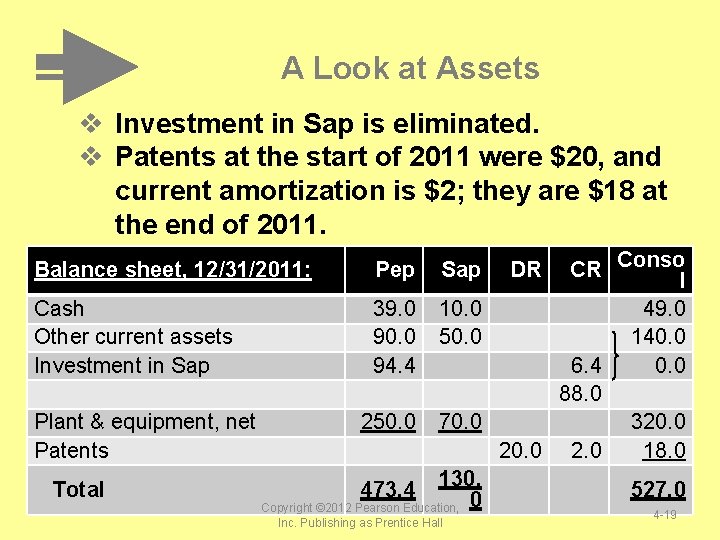
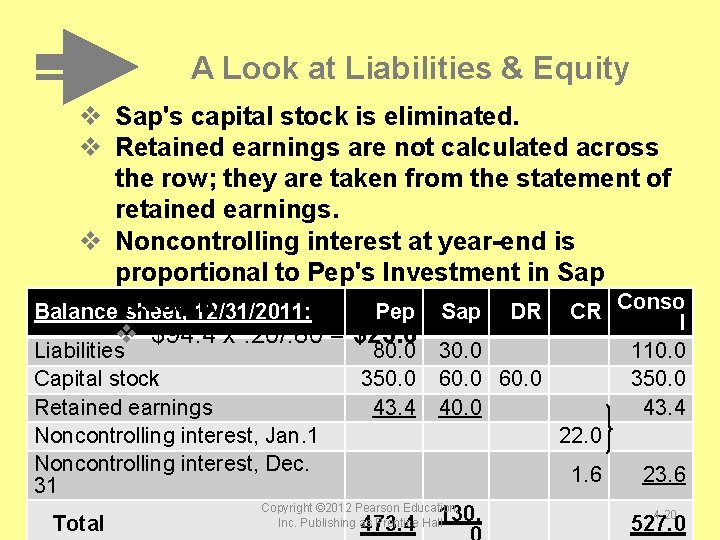
Balance sheet, 12/31/2011: Cash Other current assets Investment in Sap Plant & equipment, net Patents Total Liabilities Capital stock Retained earnings Noncontrolling interest, Jan. 1 Noncontrolling interest, Dec. 31 Total CR Consol 39. 0 10. 0 49. 0 90. 0 50. 0 140. 0 94. 4 6. 4 0. 0 88. 0 250. 0 70. 0 320. 0 2. 0 18. 0 473. 4 130. 527. 0 0 80. 0 30. 0 110. 0 350. 0 60. 0 350. 0 43. 4 40. 0 43. 4 22. 0 Pep Sap Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall DR 473. 4 130. 1. 6 23. 6 4 -16 527. 0
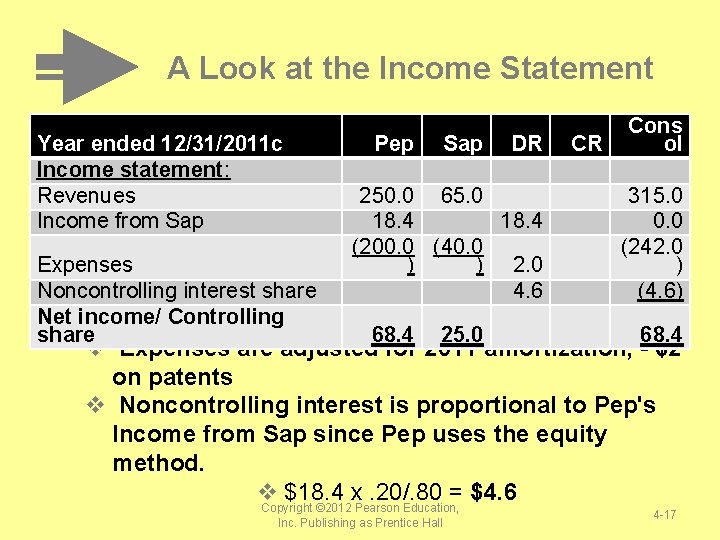
A Look at the Income Statement Year ended 12/31/2011 c Income statement: Revenues Income from Sap Pep Sap DR CR 250. 0 65. 0 18. 4 (200. 0 (40. 0 ) ) 2. 0 4. 6 Expenses Noncontrolling interest share Net income/ Controlling v Income from Sap is eliminated. share 68. 4 25. 0 Cons ol 315. 0 0. 0 (242. 0 ) (4. 6) 68. 4 v Expenses are adjusted for 2011 amortization, - $2 on patents v Noncontrolling interest is proportional to Pep's Income from Sap since Pep uses the equity method. v $18. 4 x. 20/. 80 = $4. 6 Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -17
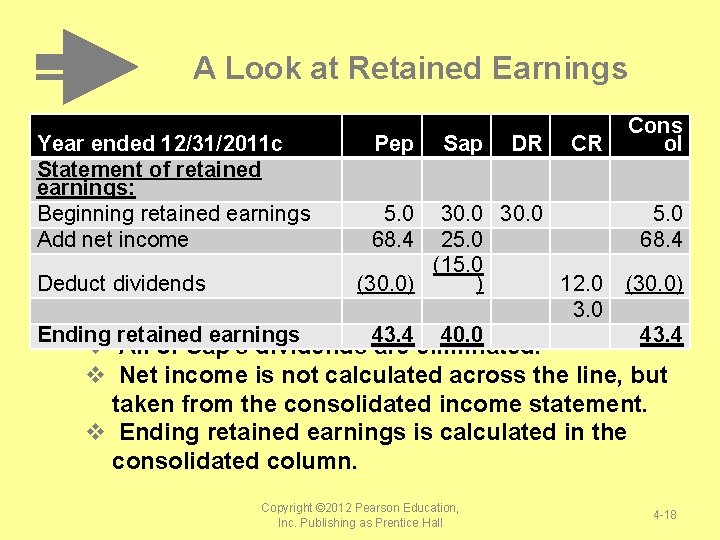
A Look at Retained Earnings Year ended 12/31/2011 c Statement of retained earnings: Beginning retained earnings Add net income Pep Sap DR CR Cons ol 5. 0 30. 0 5. 0 68. 4 25. 0 68. 4 (15. 0 Deduct dividends (30. 0) ) 12. 0 (30. 0) 3. 0 v Beginning retained earnings of Sap is eliminated. Ending retained earnings 43. 4 40. 0 43. 4 v All of Sap's dividends are eliminated. v Net income is not calculated across the line, but taken from the consolidated income statement. v Ending retained earnings is calculated in the consolidated column. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -18
A Look at Assets v Investment in Sap is eliminated. v Patents at the start of 2011 were $20, and current amortization is $2; they are $18 at the end of 2011. v The total is calculated in the consolidated Balance sheet, 12/31/2011: Pep Sap DR CR Consol column. Cash Other current assets Investment in Sap Plant & equipment, net Patents Total 39. 0 10. 0 90. 0 50. 0 94. 4 250. 0 70. 0 20. 0 473. 4 130. 0 Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 49. 0 140. 0 6. 4 88. 0 320. 0 2. 0 18. 0 527. 0 4 -19
A Look at Liabilities & Equity v Sap's capital stock is eliminated. v Retained earnings are not calculated across the row; they are taken from the statement of retained earnings. v Noncontrolling interest at year-end is proportional to Pep's Investment in Sap account. Balance sheet, 12/31/2011: Pep Sap DR CR Consol v $94. 4 x. 20/. 80 = $23. 6 Liabilities Capital stock Retained earnings Noncontrolling interest, Jan. 1 Noncontrolling interest, Dec. 31 Total 80. 0 30. 0 110. 0 350. 0 60. 0 350. 0 43. 4 40. 0 43. 4 22. 0 473. 4 130. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 1. 6 23. 6 4 -20 527. 0
Consolidation Techniques and Procedures 2: WORKPAPERS IN SUBSEQUENT YEARS Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -21
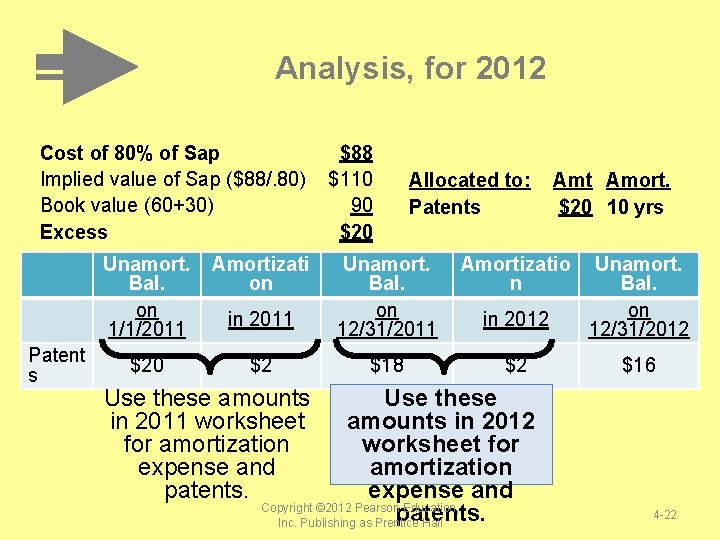
Analysis, for 2012 Cost of 80% of Sap Implied value of Sap ($88/. 80) Book value (60+30) Excess Unamort. Amortizati Bal. on on in 2011 1/1/2011 Patent s $20 $2 $88 $110 90 $20 Allocated to: Patents Amt Amort. $20 10 yrs Unamort. Bal. on 12/31/2011 Amortizatio n in 2012 Unamort. Bal. on 12/31/2012 $18 $2 $16 Use these amounts in 2011 worksheet for amortization expense and patents. Use these amounts in 2012 worksheet for amortization expense and Copyright © 2012 Pearson Education, patents. Inc. Publishing as Prentice Hall 4 -22
Income & Dividend Calculations 2011: Sap's net income Amortization Adjusted income Dividends $25 Pep's 80% share $18. 4 (2) $12. 0 $23 NCI 20% share $4. 6 $15 $3. 0 2012: 80% share Sap's net income $30 Pep's $22. 4 Amortization $12. 0 NCI 20% share (2) $5. 6 Adjusted income $28 $3. 0 Dividends $15 Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -23
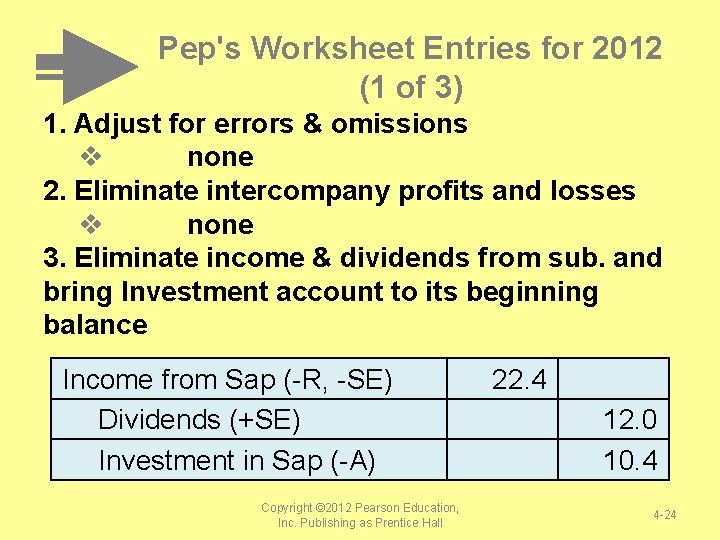
Pep's Worksheet Entries for 2012 (1 of 3) 1. Adjust for errors & omissions v none 2. Eliminate intercompany profits and losses v none 3. Eliminate income & dividends from sub. and bring Investment account to its beginning balance Income from Sap (-R, -SE) Dividends (+SE) Investment in Sap (-A) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 22. 4 12. 0 10. 4 4 -24
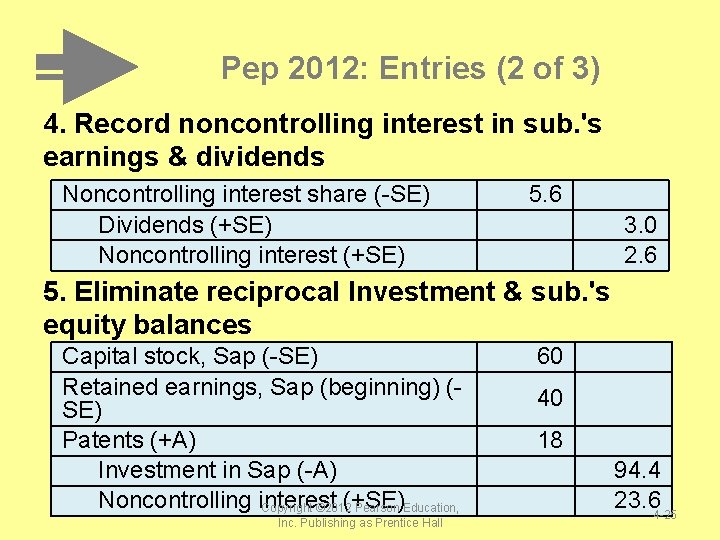
Pep 2012: Entries (2 of 3) 4. Record noncontrolling interest in sub. 's earnings & dividends Noncontrolling interest share (-SE) Dividends (+SE) Noncontrolling interest (+SE) 5. 6 3. 0 2. 6 5. Eliminate reciprocal Investment & sub. 's equity balances Capital stock, Sap (-SE) Retained earnings, Sap (beginning) (SE) Patents (+A) Investment in Sap (-A) Noncontrolling interest (+SE) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 60 40 18 94. 4 23. 64 -25
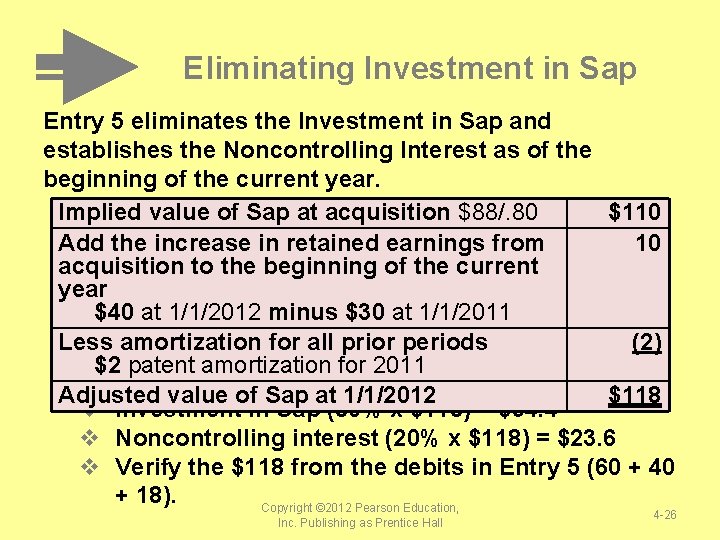
Eliminating Investment in Sap Entry 5 eliminates the Investment in Sap and establishes the Noncontrolling Interest as of the beginning of the current year. Implied value of Sap at acquisition $88/. 80 $110 Add the increase in retained earnings from 10 acquisition to the beginning of the current year $40 at 1/1/2012 minus $30 at 1/1/2011 Less amortization for all prior periods (2) $2 patent amortization for 2011 Adjusted value of Sap at 1/1/2012 $118 v Investment in Sap (80% x $118) = $94. 4 v Noncontrolling interest (20% x $118) = $23. 6 v Verify the $118 from the debits in Entry 5 (60 + 40 + 18). Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -26
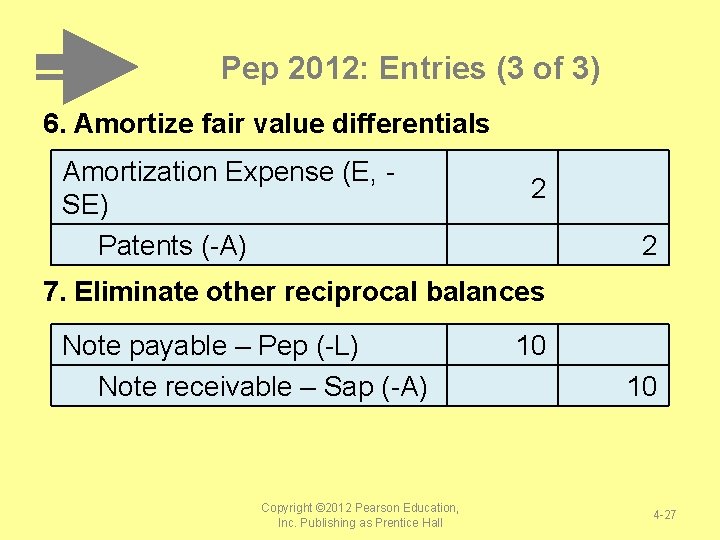
Pep 2012: Entries (3 of 3) 6. Amortize fair value differentials Amortization Expense (E, SE) Patents (-A) 2 2 7. Eliminate other reciprocal balances Note payable – Pep (-L) Note receivable – Sap (-A) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 10 4 -27
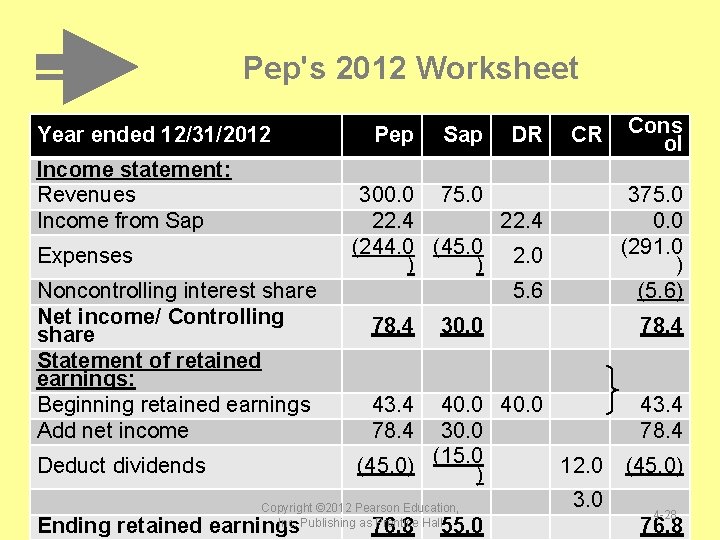
Pep's 2012 Worksheet Year ended 12/31/2012 Income statement: Revenues Income from Sap Expenses Noncontrolling interest share Net income/ Controlling share Statement of retained earnings: Beginning retained earnings Add net income Pep Sap DR 300. 0 22. 4 (244. 0 ) 75. 0 22. 4 (45. 0 2. 0 ) 5. 6 78. 4 30. 0 43. 4 78. 4 40. 0 30. 0 Deduct dividends (45. 0) (15. 0) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall Ending retained earnings 76. 8 55. 0 Cons ol CR 375. 0 0. 0 (291. 0 ) (5. 6) 78. 4 40. 0 43. 4 78. 4 12. 0 (45. 0) 3. 0 4 -28 76. 8
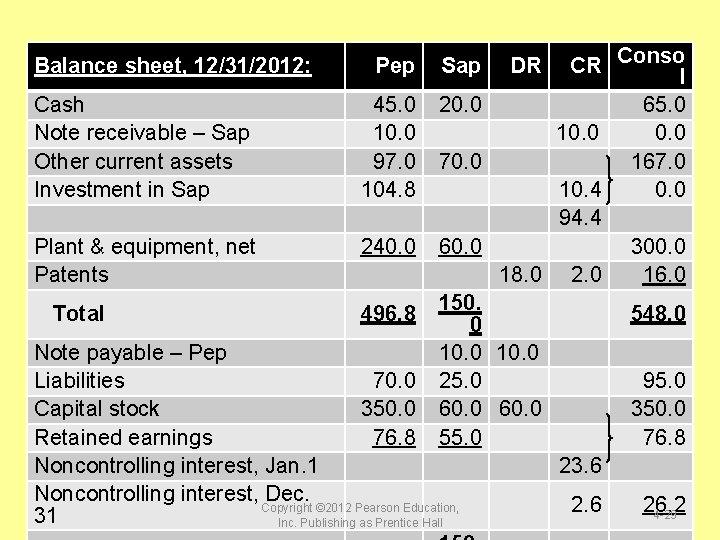
Balance sheet, 12/31/2012: Cash Note receivable – Sap Other current assets Investment in Sap Plant & equipment, net Patents Total CR Consol 45. 0 20. 0 65. 0 10. 0 97. 0 70. 0 167. 0 104. 8 10. 4 0. 0 94. 4 240. 0 60. 0 300. 0 18. 0 2. 0 16. 0 496. 8 150. 548. 0 0 10. 0 70. 0 25. 0 95. 0 350. 0 60. 0 350. 0 76. 8 55. 0 76. 8 23. 6 Pep Sap Note payable – Pep Liabilities Capital stock Retained earnings Noncontrolling interest, Jan. 1 Noncontrolling interest, Dec. Copyright © 2012 Pearson Education, 31 Inc. Publishing as Prentice Hall DR 2. 6 26. 2 4 -29
Consolidation Techniques and Procedures 3: ERRORS IN THE WORKPAPERS Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -30
Errors Most errors show up when the consolidated balance sheet does not balance. Common omissions: v Noncontrolling interest share (income) v Goodwill v Noncontrolling interest (equity) v Check equality of DR and CR adjustments. v Verify totals for parent and subsidiary statements. v Re-calculate the consolidated amounts. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -31
Consolidation Techniques and Procedures 4: ASSIGNING FAIR VALUE Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -32
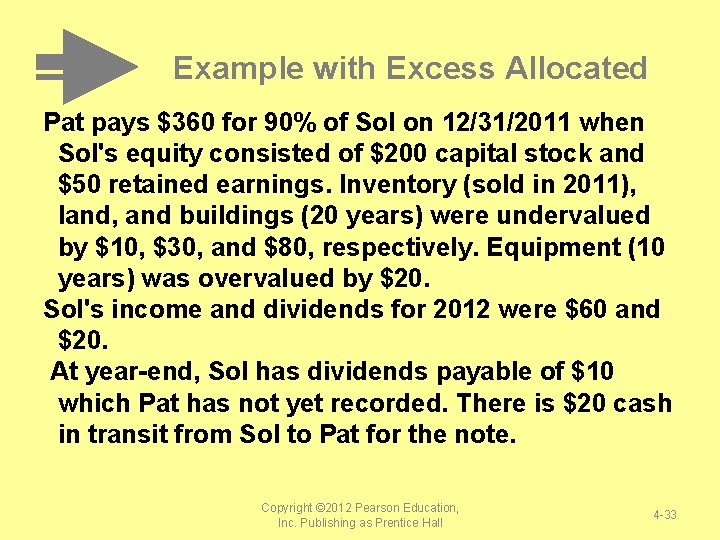
Example with Excess Allocated Pat pays $360 for 90% of Sol on 12/31/2011 when Sol's equity consisted of $200 capital stock and $50 retained earnings. Inventory (sold in 2011), land, and buildings (20 years) were undervalued by $10, $30, and $80, respectively. Equipment (10 years) was overvalued by $20. Sol's income and dividends for 2012 were $60 and $20. At year-end, Sol has dividends payable of $10 which Pat has not yet recorded. There is $20 cash in transit from Sol to Pat for the note. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -33
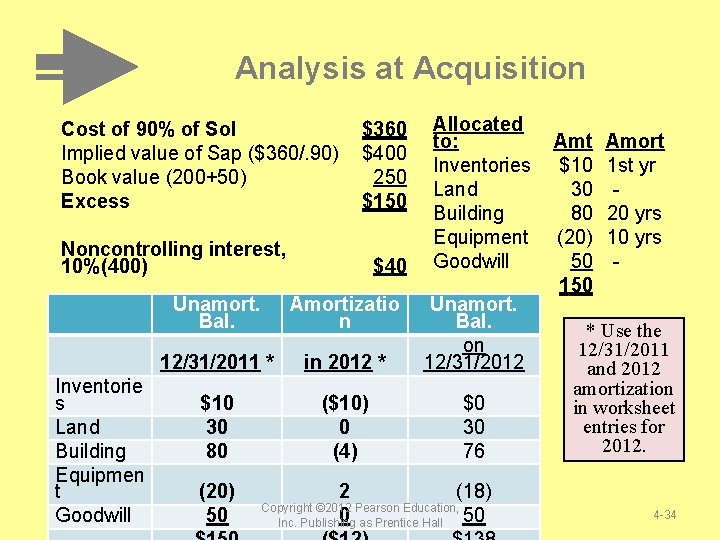
Analysis at Acquisition Allocated to: Inventories Land Building Equipment Noncontrolling interest, 10%(400) $40 Goodwill Unamort. Amortizatio Unamort. Bal. n Bal. on 12/31/2011 * in 2012 * 12/31/2012 Inventorie s $10 ($10) $0 Land 30 0 30 Building 80 (4) 76 Equipmen t (20) 2 (18) Copyright © 2012 Pearson Education, Goodwill 50 0 50 Inc. Publishing as Prentice Hall Cost of 90% of Sol Implied value of Sap ($360/. 90) Book value (200+50) Excess $360 $400 250 $150 Amt $10 30 80 (20) 50 150 Amort 1 st yr - 20 yrs 10 yrs * Use the 12/31/2011 and 2012 amortization in worksheet entries for 2012. 4 -34
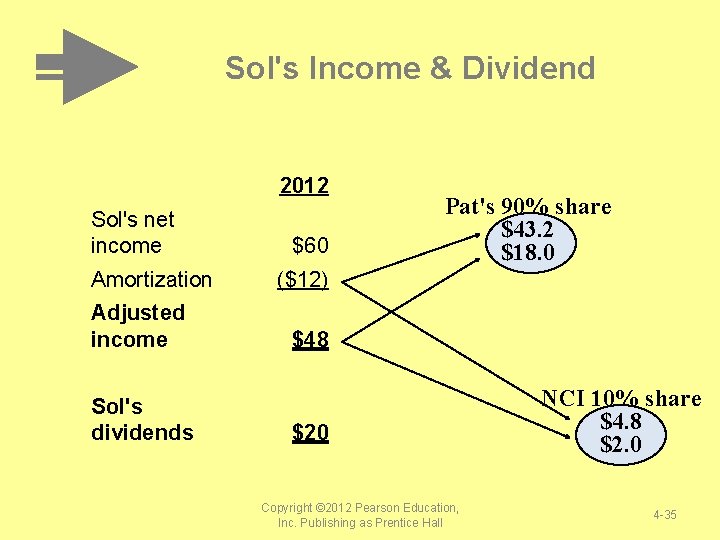
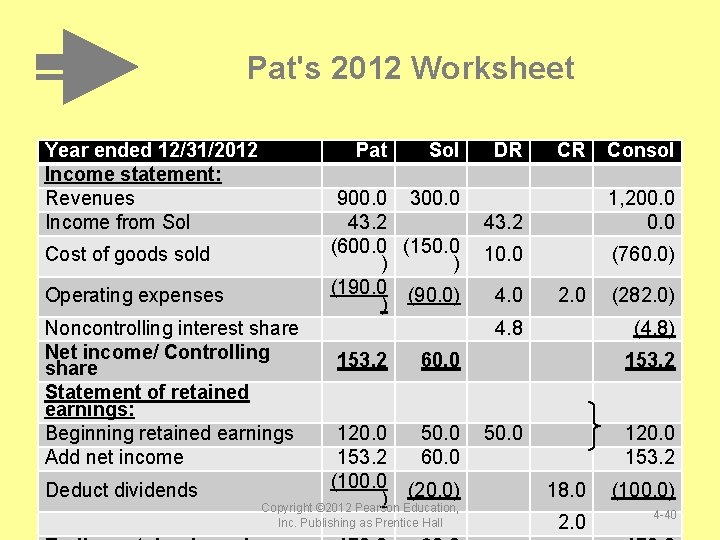
Sol's Income & Dividend Sol's net income Amortization Adjusted income Sol's dividends 2012 $60 Pat's 90% share $43. 2 $18. 0 ($12) $48 $20 Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall NCI 10% share $4. 8 $2. 0 4 -35
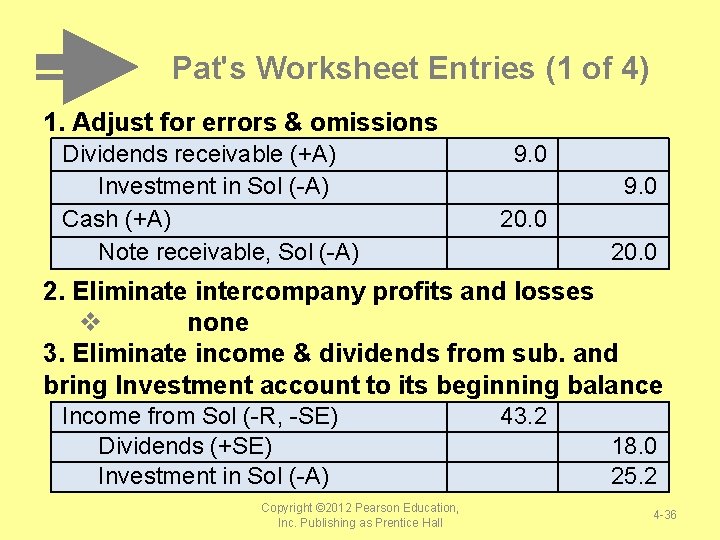
Pat's Worksheet Entries (1 of 4) 1. Adjust for errors & omissions Dividends receivable (+A) Investment in Sol (-A) Cash (+A) Note receivable, Sol (-A) 9. 0 20. 0 2. Eliminate intercompany profits and losses v none 3. Eliminate income & dividends from sub. and bring Investment account to its beginning balance Income from Sol (-R, -SE) Dividends (+SE) Investment in Sol (-A) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 43. 2 18. 0 25. 2 4 -36
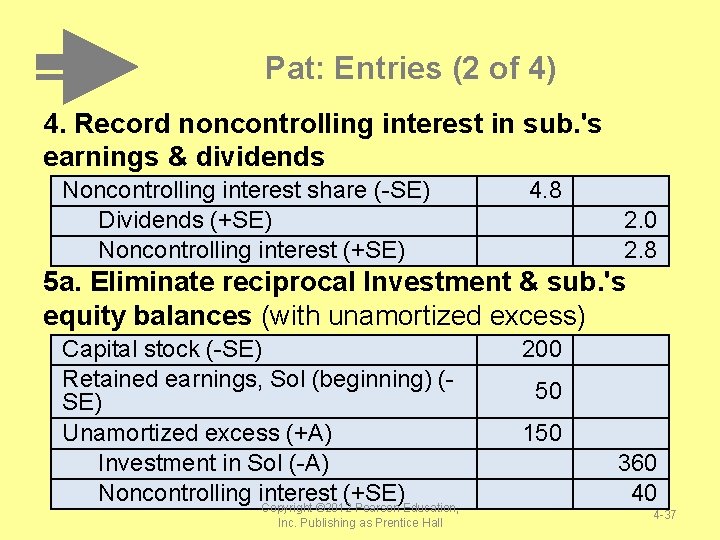
Pat: Entries (2 of 4) 4. Record noncontrolling interest in sub. 's earnings & dividends Noncontrolling interest share (-SE) Dividends (+SE) Noncontrolling interest (+SE) 4. 8 2. 0 2. 8 5 a. Eliminate reciprocal Investment & sub. 's equity balances (with unamortized excess) Capital stock (-SE) Retained earnings, Sol (beginning) (SE) Unamortized excess (+A) Investment in Sol (-A) Noncontrolling interest (+SE) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 200 50 150 360 40 4 -37
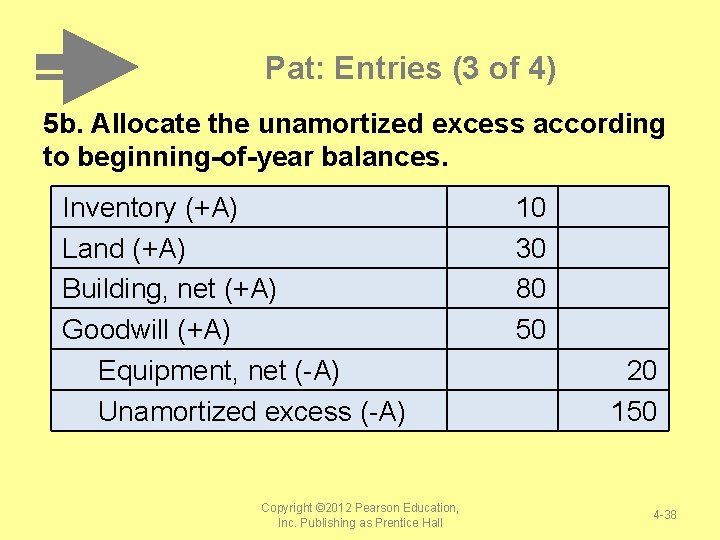
Pat: Entries (3 of 4) 5 b. Allocate the unamortized excess according to beginning-of-year balances. Inventory (+A) Land (+A) Building, net (+A) Goodwill (+A) Equipment, net (-A) Unamortized excess (-A) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 10 30 80 50 20 150 4 -38
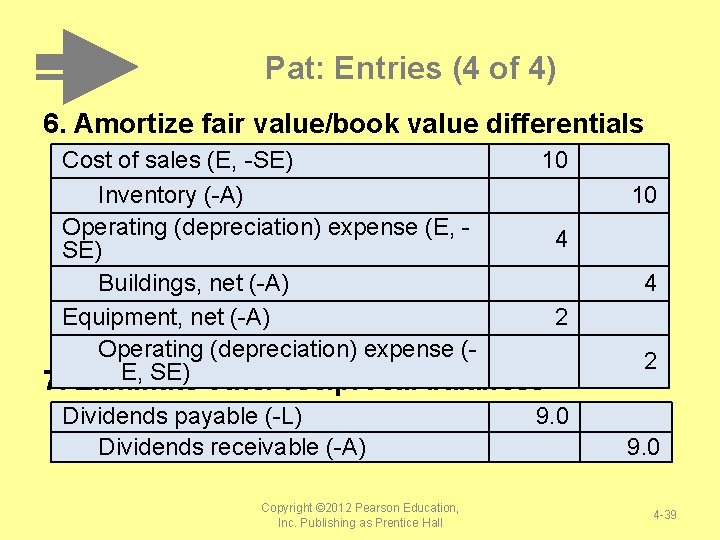
Pat: Entries (4 of 4) 6. Amortize fair value/book value differentials Cost of sales (E, -SE) 10 Inventory (-A) Operating (depreciation) expense (E, 4 SE) Buildings, net (-A) Equipment, net (-A) 2 Operating (depreciation) expense (E, SE) 7. Eliminate other reciprocal balances Dividends payable (-L) Dividends receivable (-A) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 10 4 2 9. 0 4 -39
Pat's 2012 Worksheet Year ended 12/31/2012 Income statement: Revenues Income from Sol Cost of goods sold Operating expenses Noncontrolling interest share Net income/ Controlling share Statement of retained earnings: Beginning retained earnings Add net income Deduct dividends Pat Sol DR 900. 0 300. 0 43. 2 (600. 0 (150. 0 10. 0 ) ) (190. 0 (90. 0) 4. 0 ) 4. 8 CR Consol 1, 200. 0 (760. 0) 2. 0 (282. 0) (4. 8) 153. 2 60. 0 153. 2 120. 0 50. 0 153. 2 60. 0 (100. 0 (20. 0) 18. 0 ) Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 2. 0 120. 0 153. 2 (100. 0) 4 -40
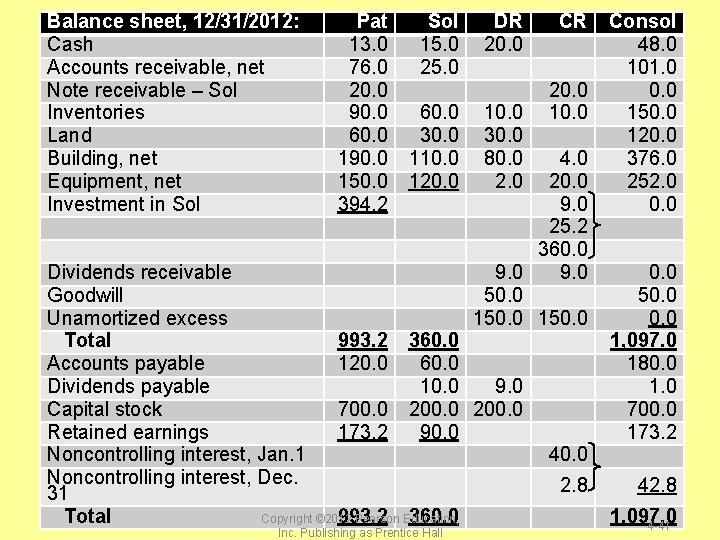
Balance sheet, 12/31/2012: Pat Sol DR CR Consol Cash 13. 0 15. 0 20. 0 48. 0 Accounts receivable, net 76. 0 25. 0 101. 0 Note receivable – Sol 20. 0 Inventories 90. 0 60. 0 10. 0 150. 0 Land 60. 0 30. 0 120. 0 Building, net 190. 0 110. 0 80. 0 4. 0 376. 0 Equipment, net 150. 0 120. 0 252. 0 Investment in Sol 394. 2 9. 0 0. 0 25. 2 360. 0 Dividends receivable 9. 0 0. 0 Goodwill 50. 0 Unamortized excess 150. 0 Total 993. 2 360. 0 1, 097. 0 Accounts payable 120. 0 60. 0 180. 0 Dividends payable 10. 0 9. 0 1. 0 Capital stock 700. 0 200. 0 700. 0 Retained earnings 173. 2 90. 0 173. 2 Noncontrolling interest, Jan. 1 40. 0 Noncontrolling interest, Dec. 2. 8 42. 8 31 Total 993. 2 360. 0 1, 097. 0 Copyright © 2012 Pearson Education, 4 -41 Inc. Publishing as Prentice Hall
Consolidation Techniques and Procedures 5: CONSOLIDATED STATEMENT OF CASH FLOWS Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -42
Consolidated Cash Flows The consolidated statement of cash flows is prepared from: v Consolidated balance sheets, beginning & ending v Consolidated income statement v Other information Procedure similar to an "unconsolidated" statement of cash flows Look at items specific to companies with: v Subsidiaries v Equity investments Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -43
Investing & Financing Cash Flows Investing cash flows: v Include cash acquisition and/or disposition of subsidiaries v Include cash acquisition and/or disposition of equity investees Financing cash flows: v Include cash dividends paid to noncontrolling interests Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -44
Operating Cash Flows Direct method: v Include cash dividends received from equity investees (not equity method income) Indirect method: v Start with controlling share of net income v Add the noncontrolling interest share v Deduct the excess of equity method income over cash dividends received from equity investees Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -45
Consolidation Techniques and Procedures 6: APPENDIX – TRIAL BALANCE FORMAT Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -46
Alternative Worksheet Format Worksheet format presented earlier used the basic financial statements Alternative uses the ADJUSTED trial balances of the parent and subsidiary. Columns on worksheet: v Parent and subsidiary adjusted trial balances, v DR and CR adjustments, v Income statement, v Statement of retained earnings, and v Balance sheet columns Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -47
Completing the Worksheet 1. Enter worksheet elimination entries into the DR and CR columns. 2. Add accounts as needed (e. g. , noncontrolling interest, goodwill, noncontrolling interest share). 3. Carry consolidated balances to income statement, retained earnings, or balance sheet columns, as appropriate. 4. Move controlling share of income to the retained earnings column. 5. Move ending retained earnings to the balance sheet column. Copyright © 2012 Pearson Education, Inc. Publishing as Prentice Hall 4 -48
This work is protected by United States copyright laws and is provided solely for the use of instructors in teaching their courses and assessing student learning. Dissemination or sale of any part of this work (including on the World Wide Web) will destroy the integrity of the work and is not permitted. The work and materials from it is should never be made available to students except by instructors using the accompanying text in their classes. All recipients of this work are expected to abide by these restrictions and to honor the intended pedagogical purposes and the needs of other instructors who rely on these materials. ! All rights reserved. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, in any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the publisher. Printed in the United States of America. Copyright © 2012 Pearson Education, 4 -49 Inc. Publishing as Prentice Hall