7e 5 Inventories and Cost of Goods Sold
- Slides: 66
7/e 5 Inventories and Cost of Goods Sold Power. Point Author: Catherine Lumbattis COPYRIGHT © 2011 South-Western/Cengage Learning
Inventory of Wholesalers and Retailers v Purchased in finished form v Resold without transformation v Classified as “Merchandise Inventory” on balance sheet LO 1
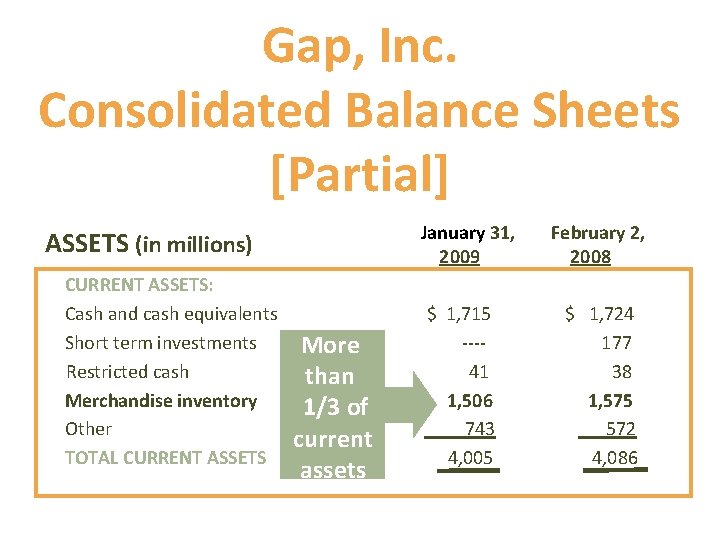
Gap, Inc. Consolidated Balance Sheets [Partial] January 31, 2009 ASSETS (in millions) CURRENT ASSETS: Cash and cash equivalents Short term investments Restricted cash Merchandise inventory Other TOTAL CURRENT ASSETS More than 1/3 of current assets $ 1, 715 ---41 1, 506 743 4, 005 February 2, 2008 $ 1, 724 177 38 1, 575 572 4, 086
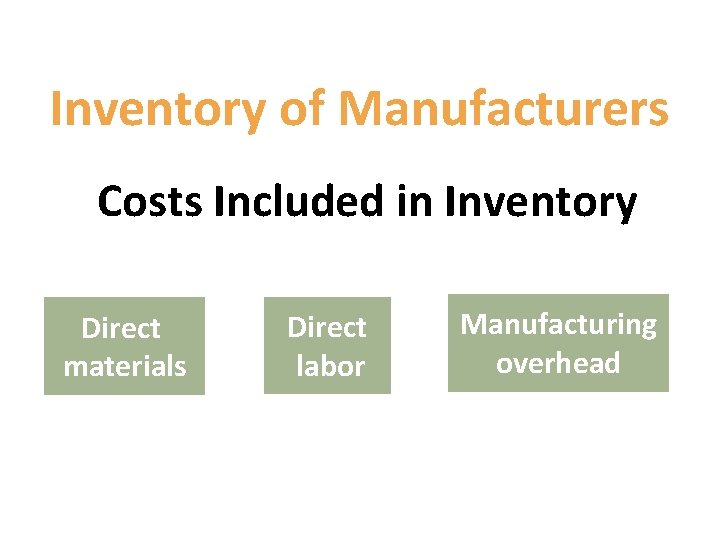
Inventory of Manufacturers Costs Included in Inventory Direct materials Direct labor Manufacturing overhead
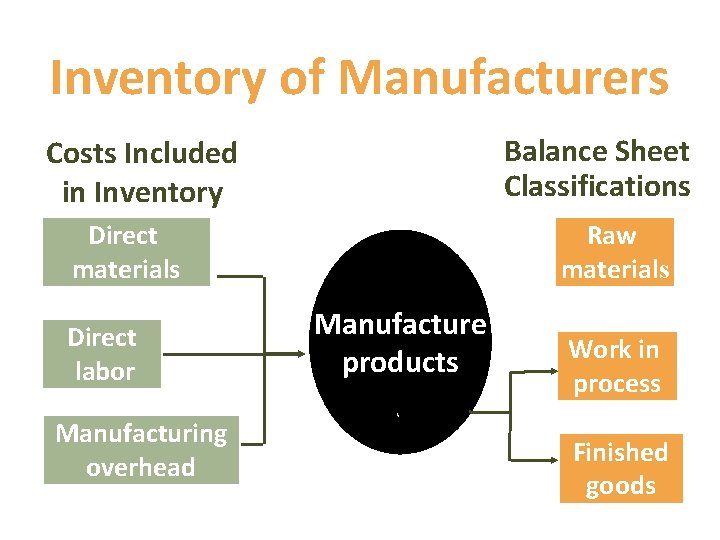
Inventory of Manufacturers Balance Sheet Classifications Costs Included in Inventory Direct materials Direct labor Manufacturing overhead Raw materials Manufacture products Work in process Finished goods
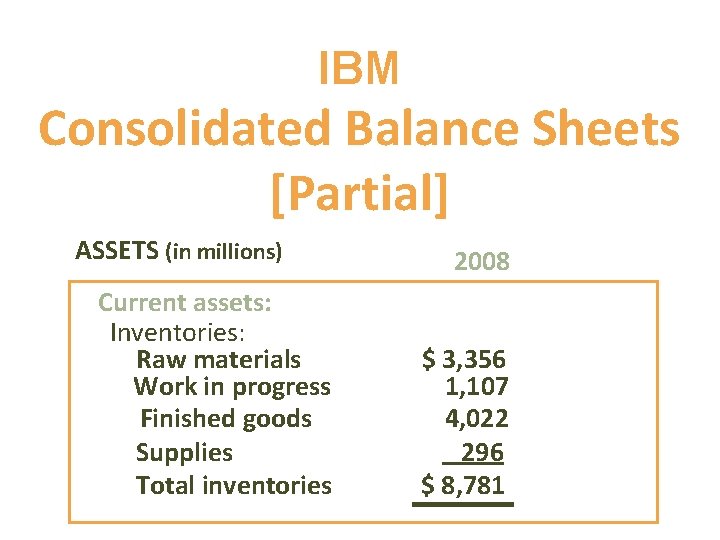
IBM Consolidated Balance Sheets [Partial] ASSETS (in millions) Current assets: Inventories: Raw materials Work in progress Finished goods Supplies Total inventories 2008 $ 3, 356 1, 107 4, 022 296 $ 8, 781
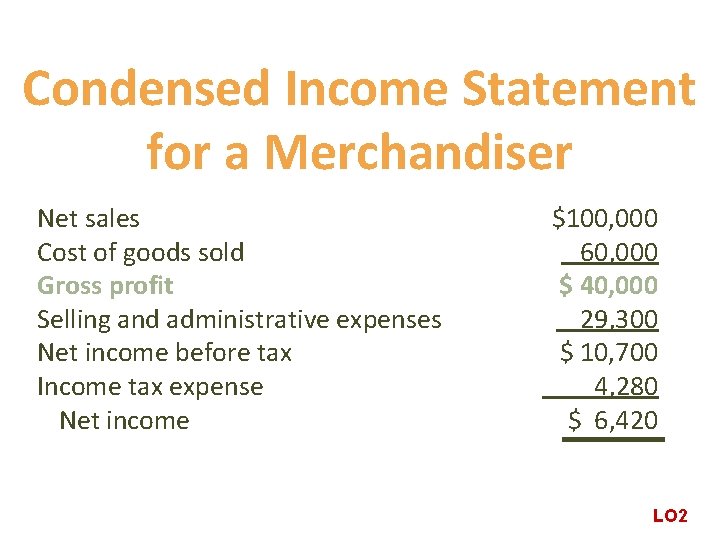
Condensed Income Statement for a Merchandiser Net sales Cost of goods sold Gross profit Selling and administrative expenses Net income before tax Income tax expense Net income $100, 000 60, 000 $ 40, 000 29, 300 $ 10, 700 4, 280 $ 6, 420 LO 2
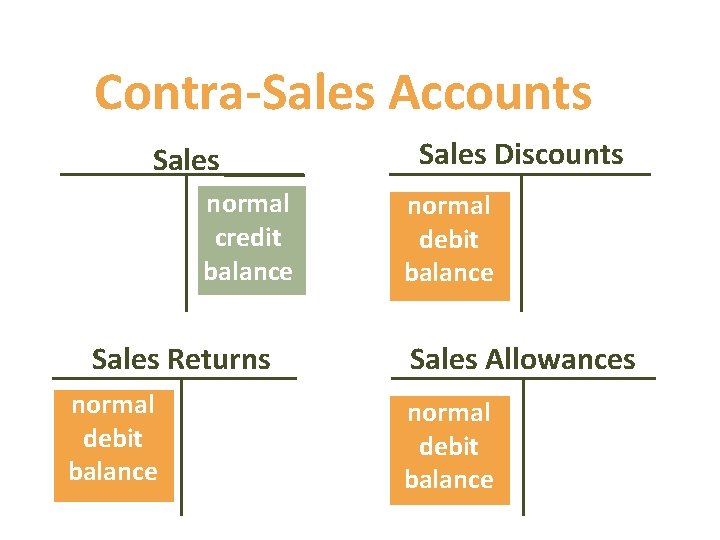
Contra-Sales Accounts Sales normal credit balance Sales Returns normal debit balance Sales Discounts normal debit balance Sales Allowances normal debit balance
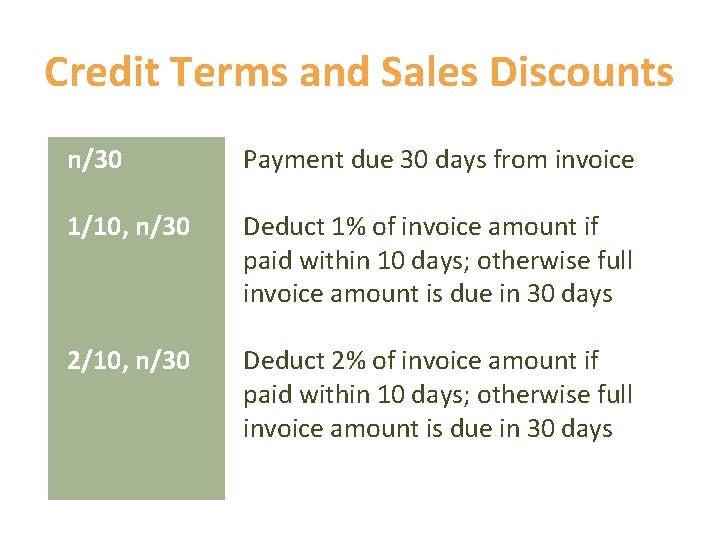
Credit Terms and Sales Discounts n/30 Payment due 30 days from invoice 1/10, n/30 Deduct 1% of invoice amount if paid within 10 days; otherwise full invoice amount is due in 30 days 2/10, n/30 Deduct 2% of invoice amount if paid within 10 days; otherwise full invoice amount is due in 30 days
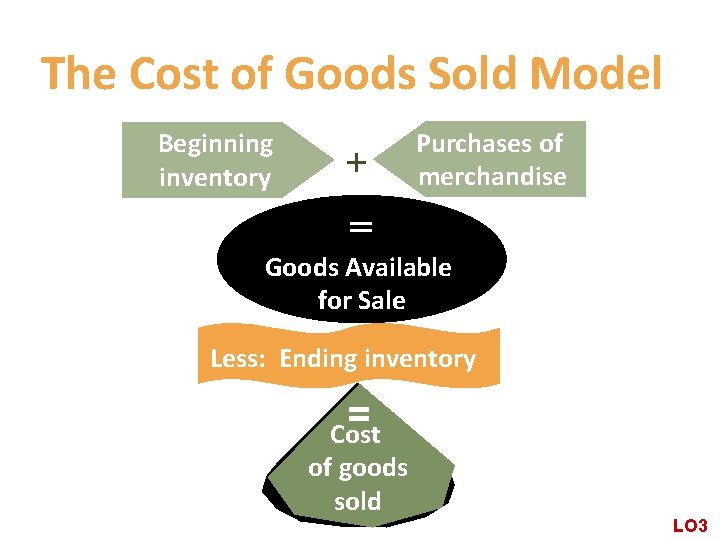
The Cost of Goods Sold Model Beginning inventory + Purchases of merchandise = Goods Available for Sale Less: Ending inventory = Cost of goods sold LO 3
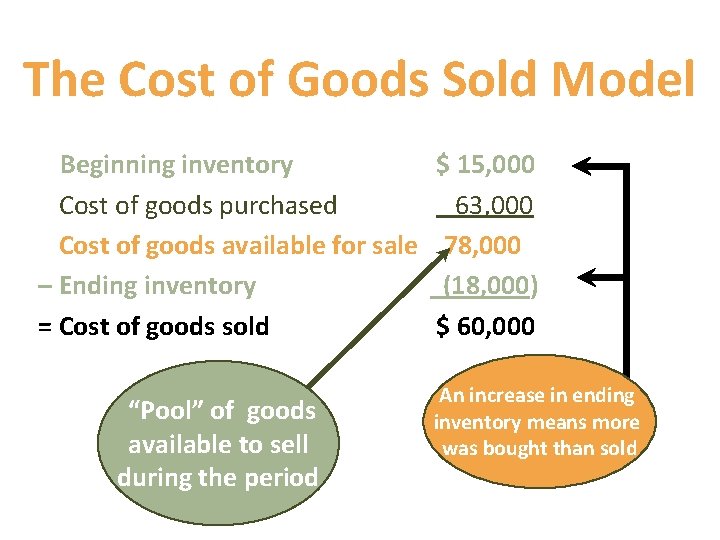
The Cost of Goods Sold Model Beginning inventory + Cost of goods purchased = Cost of goods available for sale – Ending inventory = Cost of goods sold “Pool” of goods available to sell during the period $ 15, 000 63, 000 78, 000 (18, 000) $ 60, 000 An increase in ending inventory means more was bought than sold
Perpetual Inventory Systems Inventory records are updated after each purchase or sale v Point-of-sale terminals have improved the ability of mass merchandisers to maintain perpetual systems
Periodic Inventory Systems Inventory records are updated periodically based on physical inventory counts v Reduces record keeping but also decreases the ability to track theft, breakage, etc. , and prepare interim financial statements
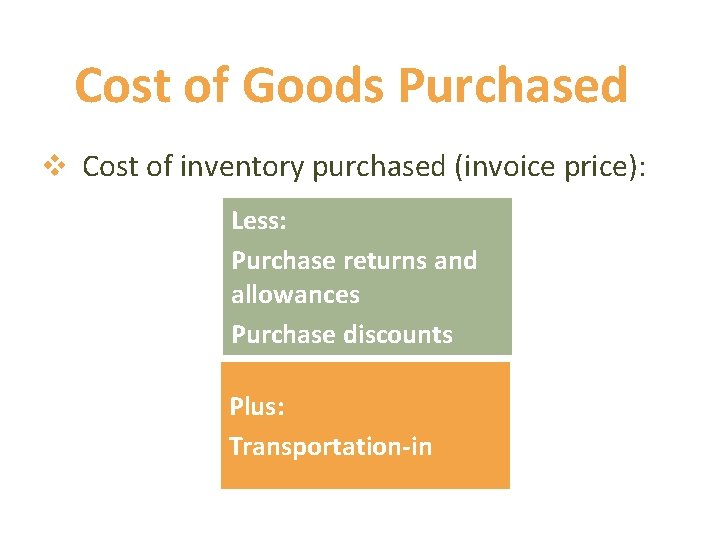
Cost of Goods Purchased v Cost of inventory purchased (invoice price): Less: Purchase returns and allowances Purchase discounts Plus: Transportation-in
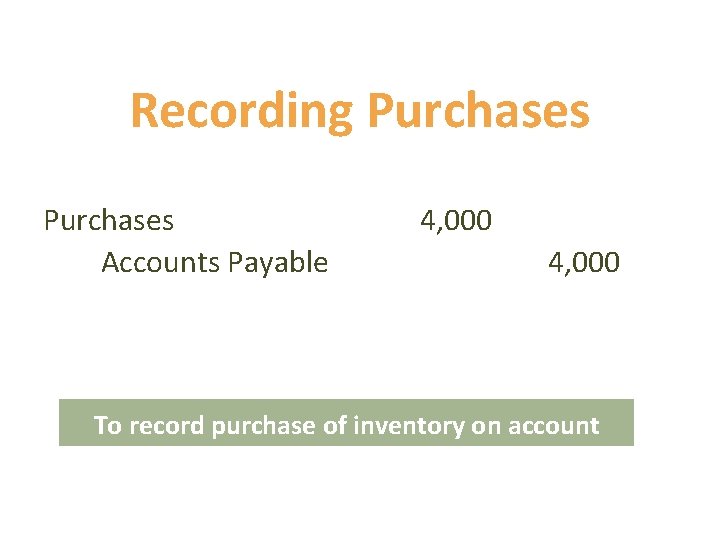
Recording Purchases Accounts Payable 4, 000 To record purchase of inventory on account
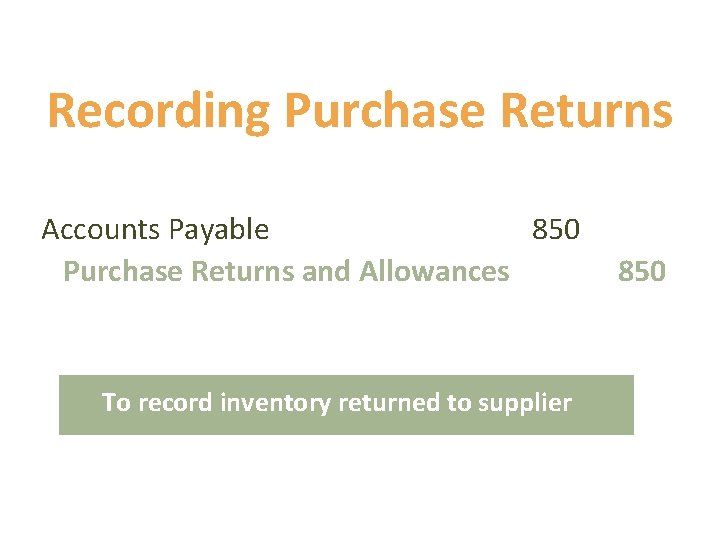
Recording Purchase Returns Accounts Payable 850 Purchase Returns and Allowances To record inventory returned to supplier 850
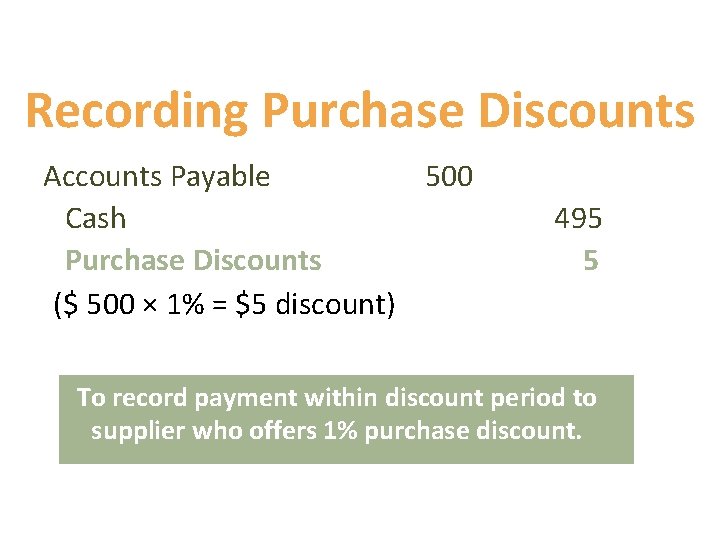
Recording Purchase Discounts Accounts Payable 500 Cash Purchase Discounts ($ 500 × 1% = $5 discount) 495 5 To record payment within discount period to supplier who offers 1% purchase discount.
FOB Destination Point Title passes at destination v No sale or purchase until inventory reaches its destination v Seller responsible for inventory while in transit
FOB Shipping Point v Both sale and purchase recorded upon shipment v Buyer responsible for inventory while in transit Title passes when shipped
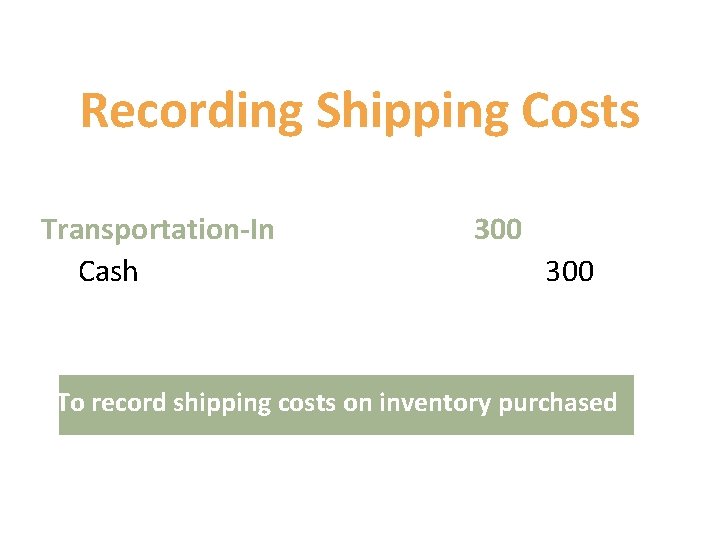
Recording Shipping Costs Transportation-In Cash 300 To record shipping costs on inventory purchased
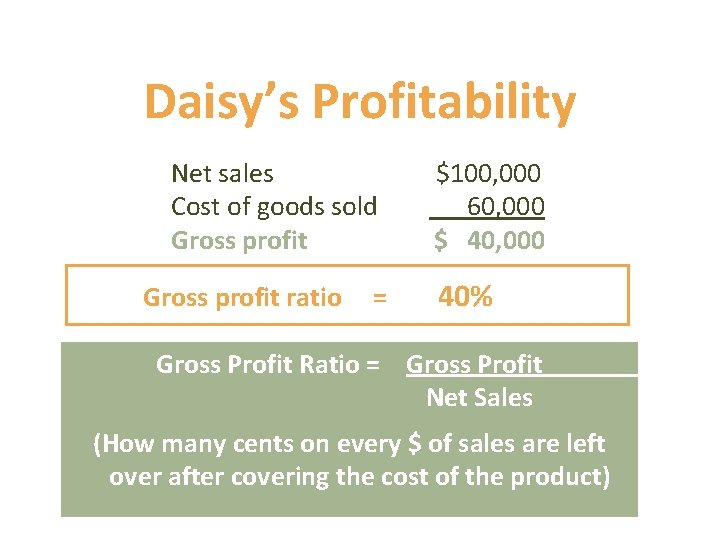
Analysis of Profitability Of particular interest to current and potential investors Gross Profit % LO 4
Daisy’s Profitability Net sales Cost of goods sold Gross profit ratio = $100, 000 60, 000 $ 40, 000 40% Gross Profit Ratio = Gross Profit Net Sales (How many cents on every $ of sales are left over after covering the cost of the product)
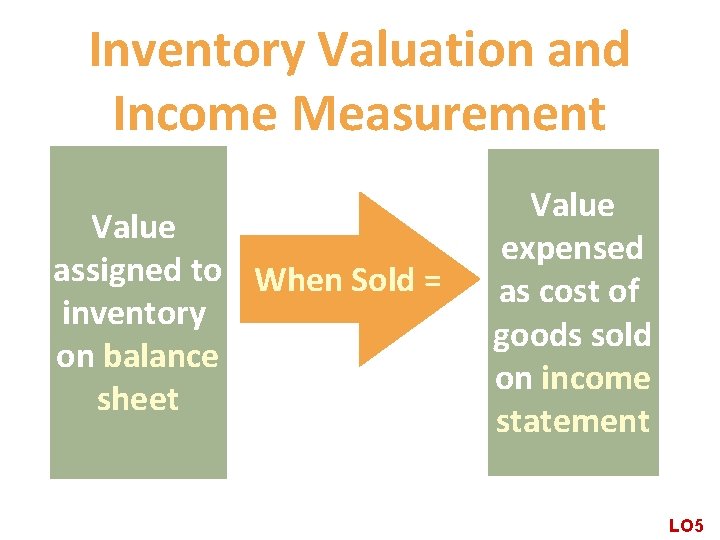
Inventory Valuation and Income Measurement Value assigned to When Sold = inventory on balance sheet Value expensed as cost of goods sold on income statement LO 5
Inventory Costs Included v Any freight costs incurred by buyer v Cost of insurance for inventory in transit v Cost of storing inventory before selling v Excise and sales taxes
Inventory Costing Methods Four costing methods available: Specific Identification Weighted Average First-in, First-out (FIFO) Last-in, First-out (LIFO) LO 6
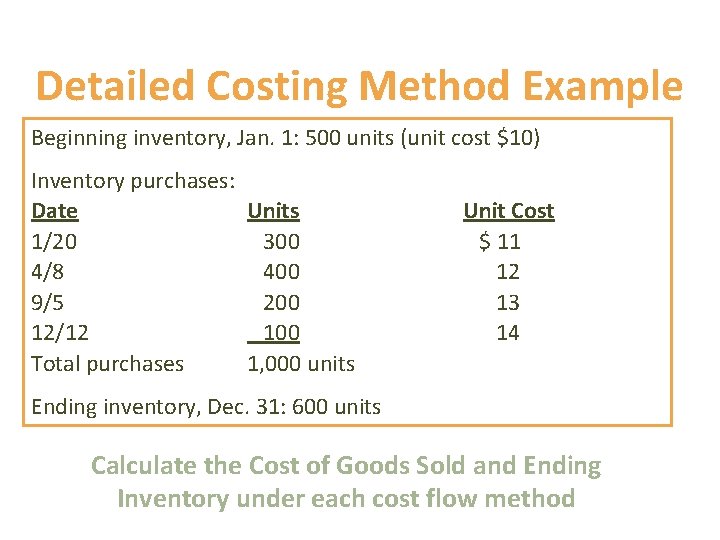
Detailed Costing Method Example Beginning inventory, Jan. 1: 500 units (unit cost $10) Inventory purchases: Date Units 1/20 300 4/8 400 9/5 200 12/12 100 Total purchases 1, 000 units Unit Cost $ 11 12 13 14 Ending inventory, Dec. 31: 600 units Calculate the Cost of Goods Sold and Ending Inventory under each cost flow method
Specific Identification Method Step 1: Identify the specific units in inventory at the end of the year and their costs.
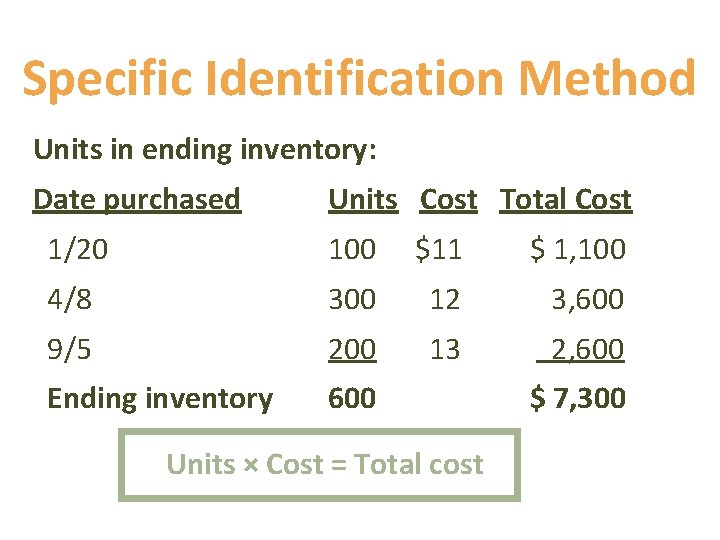
Specific Identification Method Units in ending inventory: Date purchased Units Cost Total Cost 1/20 100 $11 $ 1, 100 4/8 300 12 3, 600 9/5 200 13 2, 600 Ending inventory 600 Units × Cost = Total cost $ 7, 300
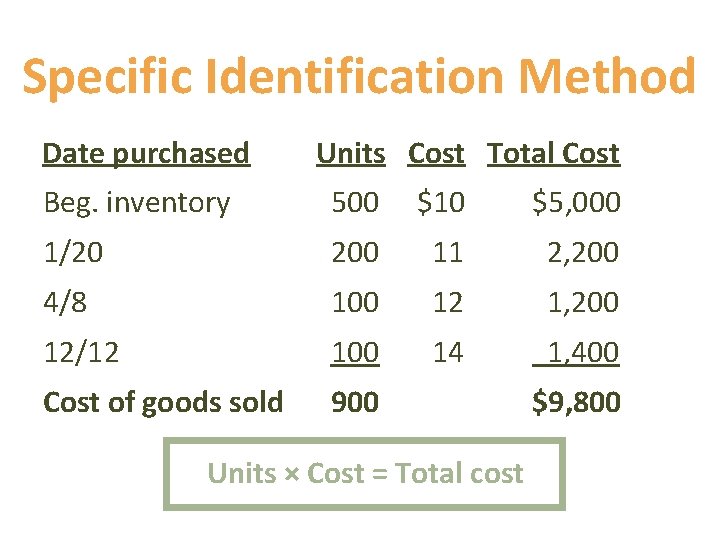
Specific Identification Method Step 2: Identify the units sold and calculate the cost of goods sold.
Specific Identification Method Date purchased Units Cost Total Cost Beg. inventory 500 $10 $5, 000 1/20 200 11 2, 200 4/8 100 12 1, 200 12/12 100 14 1, 400 Cost of goods sold 900 Units × Cost = Total cost $9, 800
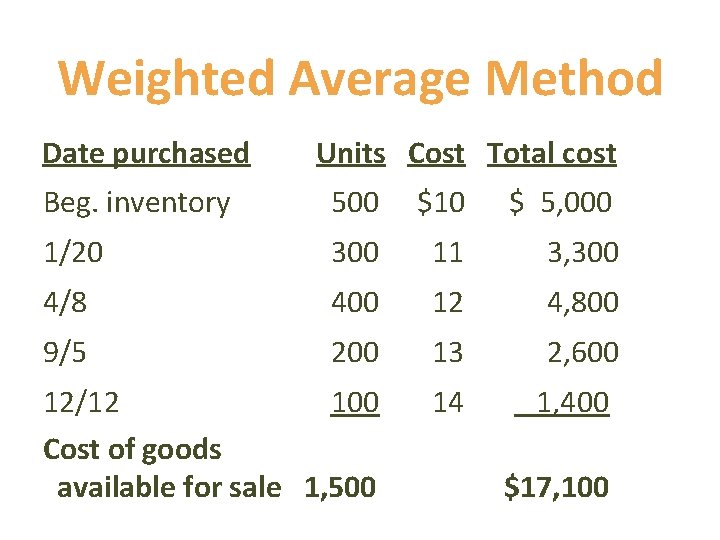
Weighted Average Method Step 1: Calculate the cost of goods available for sale.
Weighted Average Method Date purchased Units Cost Total cost Beg. inventory 500 $10 $ 5, 000 1/20 300 11 3, 300 4/8 400 12 4, 800 9/5 200 13 2, 600 12/12 100 Cost of goods available for sale 1, 500 14 1, 400 $17, 100
Weighted Average Method Step 2: Divide the cost of goods available for sale by the total units to determine the weighted average cost per unit.
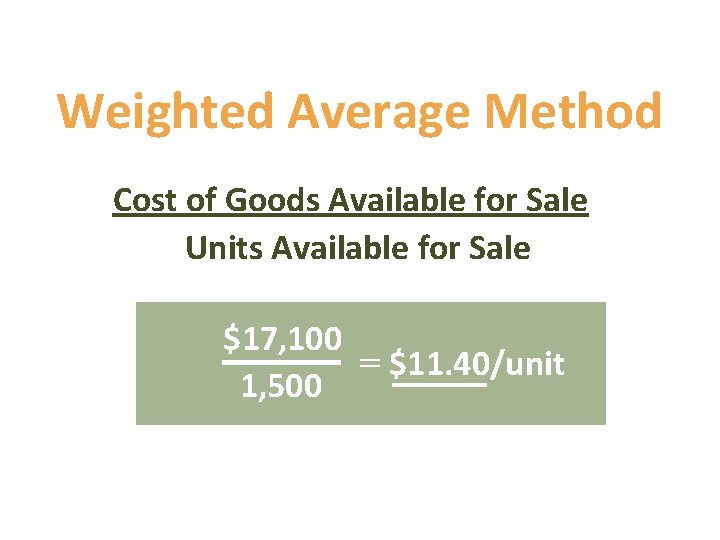
Weighted Average Method Cost of Goods Available for Sale Units Available for Sale $17, 100 = $11. 40/unit 1, 500
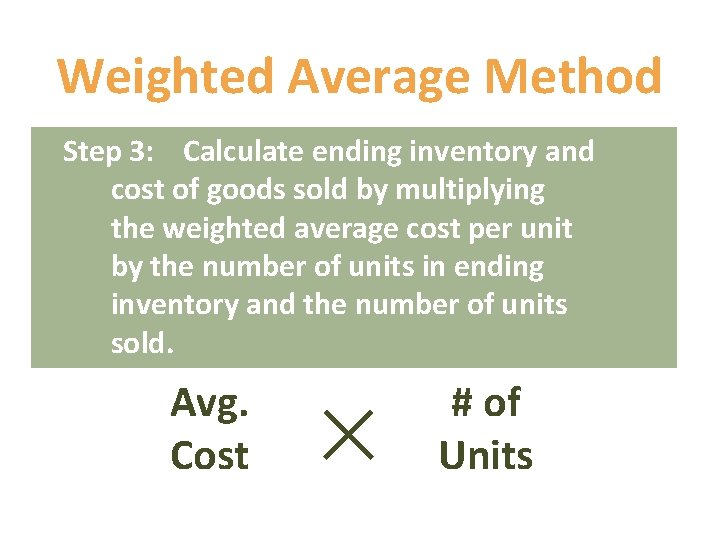
Weighted Average Method Step 3: Calculate ending inventory and cost of goods sold by multiplying the weighted average cost per unit by the number of units in ending inventory and the number of units sold. Avg. Cost × # of Units
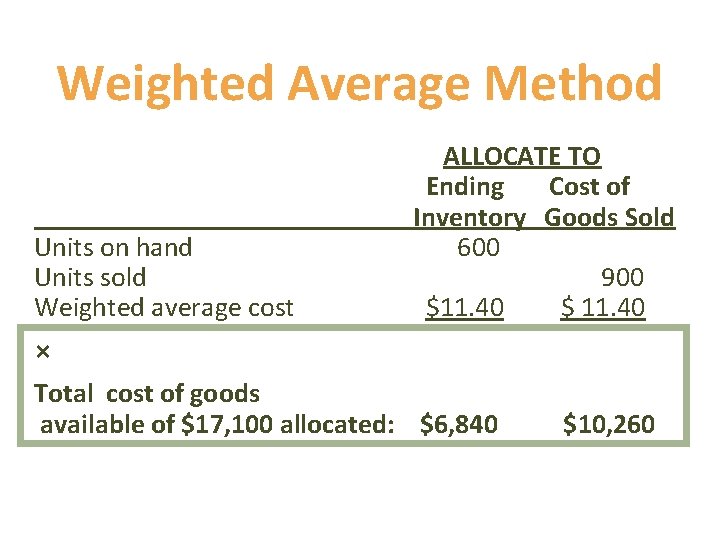
Weighted Average Method Units on hand Units sold Weighted average cost ALLOCATE TO Ending Cost of Inventory Goods Sold 600 900 $11. 40 $ 11. 40 × Total cost of goods available of $17, 100 allocated: $6, 840 $10, 260
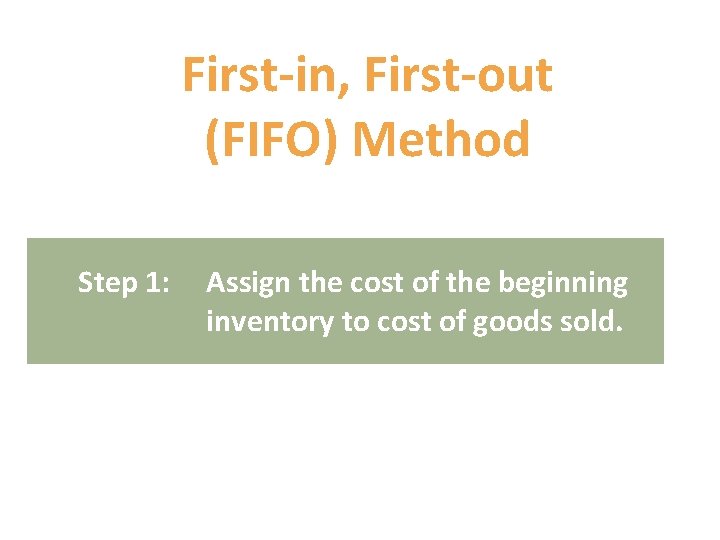
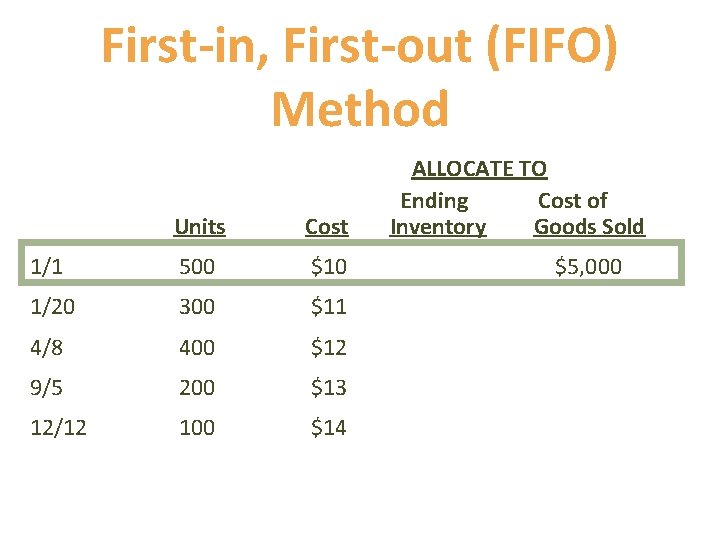
First-in, First-out (FIFO) Method Step 1: Assign the cost of the beginning inventory to cost of goods sold.
First-in, First-out (FIFO) Method Units Cost 1/1 500 $10 1/20 300 $11 4/8 400 $12 9/5 200 $13 12/12 100 $14 ALLOCATE TO Ending Cost of Inventory Goods Sold $5, 000
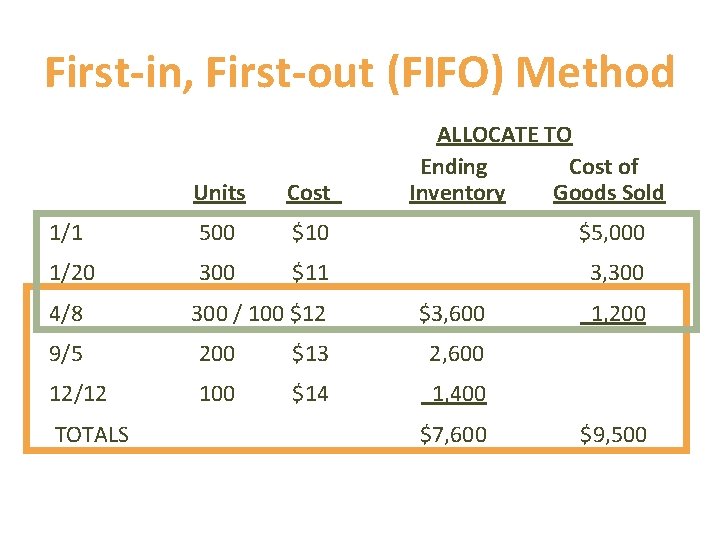
First-in, First-out (FIFO) Method Step 2: Continue to work forward until you assign the total number of units sold during the period to cost of goods sold. Allocate the remaining costs to ending inventory.
First-in, First-out (FIFO) Method ALLOCATE TO Ending Cost of Inventory Goods Sold Units Cost 1/1 500 $10 $5, 000 1/20 300 $11 3, 300 4/8 300 / 100 $12 $3, 600 9/5 200 $13 2, 600 12/12 100 $14 1, 400 TOTALS $7, 600 1, 200 $9, 500
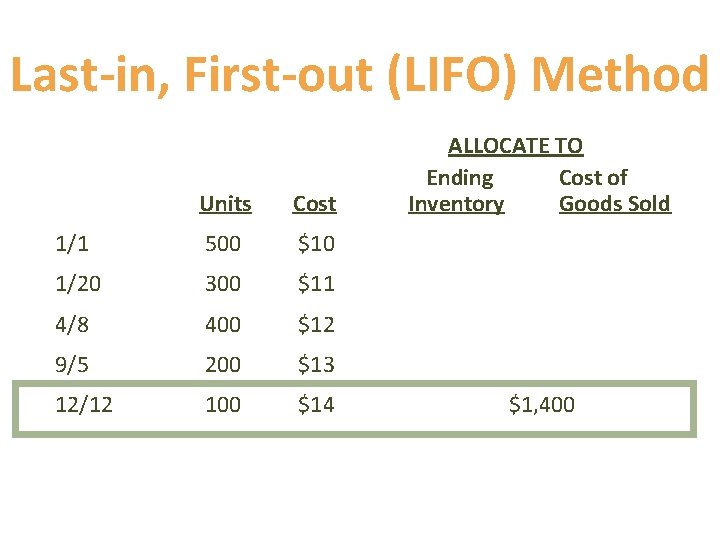
Last-in, First-out (LIFO) Method Step 1: Assign the cost of the last units purchased to cost of goods sold.
Last-in, First-out (LIFO) Method Units Cost 1/1 500 $10 1/20 300 $11 4/8 400 $12 9/5 200 $13 12/12 100 $14 ALLOCATE TO Ending Cost of Inventory Goods Sold $1, 400
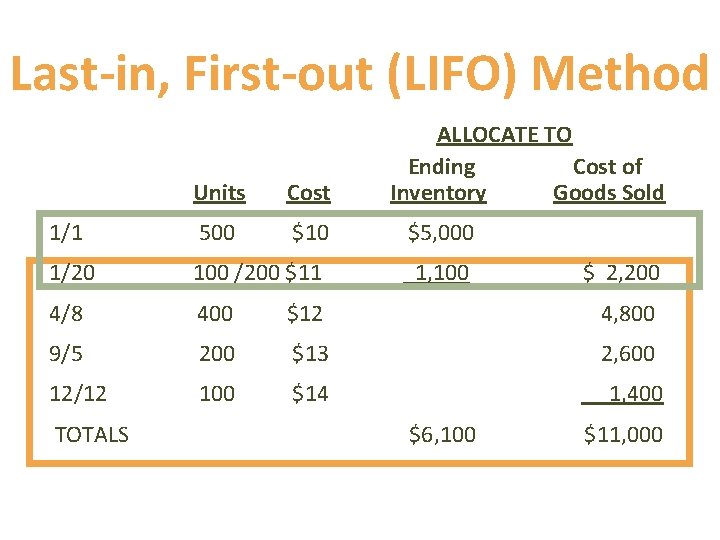
Last-in, First-out (LIFO) Method Step 2: Work backwards until you assign the total number of units sold during the period to cost of goods sold (allocate the remaining costs to ending inventory).
Last-in, First-out (LIFO) Method ALLOCATE TO Ending Cost of Inventory Goods Sold Units Cost 1/1 500 $10 $5, 000 1/20 100 /200 $11 1, 100 4/8 400 $12 4, 800 9/5 200 $13 2, 600 12/12 100 $14 TOTALS $ 2, 200 1, 400 $6, 100 $11, 000
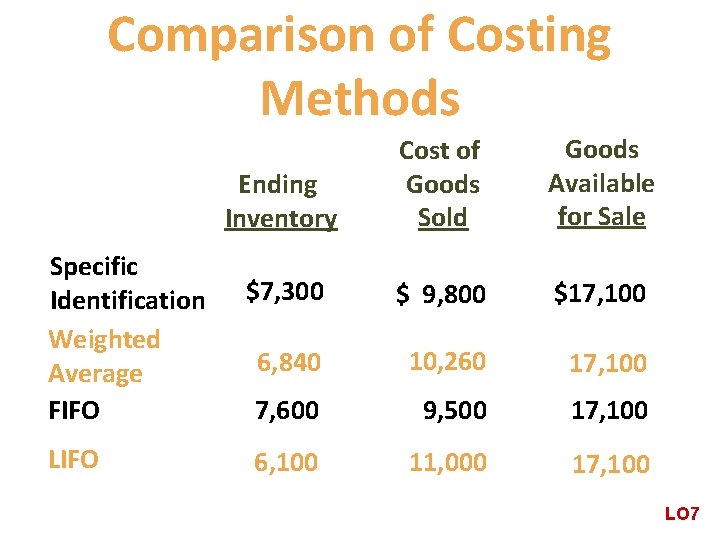
Comparison of Costing Methods Specific Identification Weighted Average FIFO LIFO Ending Inventory Cost of Goods Sold Goods Available for Sale $7, 300 $ 9, 800 $17, 100 6, 840 10, 260 17, 100 7, 600 9, 500 17, 100 6, 100 11, 000 17, 100 LO 7
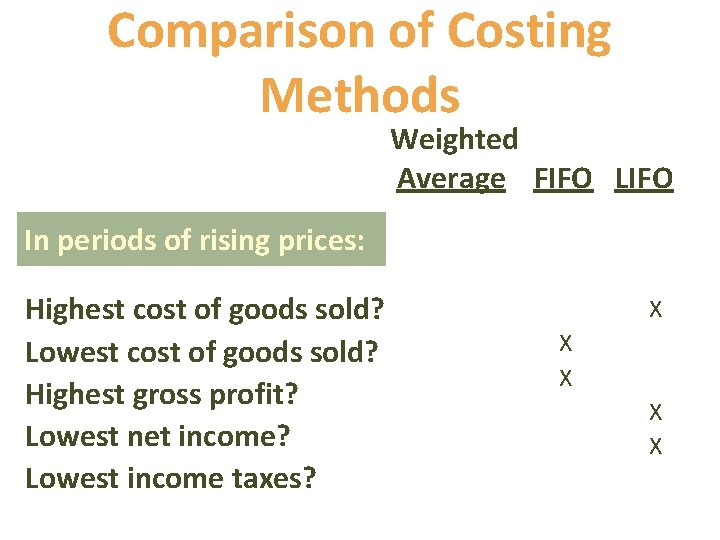
Comparison of Costing Methods Weighted Average FIFO LIFO In periods of rising prices: Highest cost of goods sold? Lowest cost of goods sold? Highest gross profit? Lowest net income? Lowest income taxes? X X X
LIFO Issues v LIFO liquidation • Liquidation can result in high gross profit (and large tax bill) v LIFO conformity rule • If used for tax, LIFO must also be used for books v LIFO reserve • Difference between inventory value stated at FIFO and value stated at LIFO
International Inventory Valuation Methods v Acceptable methods of costing inventory in the United States may not be acceptable in other countries • LIFO is generally accepted in the United States • IASB (international standards) prohibit the use of LIFO by companies that follow international standards v It is uncertain whether LIFO will survive as an acceptable inventory valuation method
Reasons for Inventory Errors v Mathematical mistakes v Physical inventory counting errors v Cutoff problems – in-transit v Goods on consignment LO 8
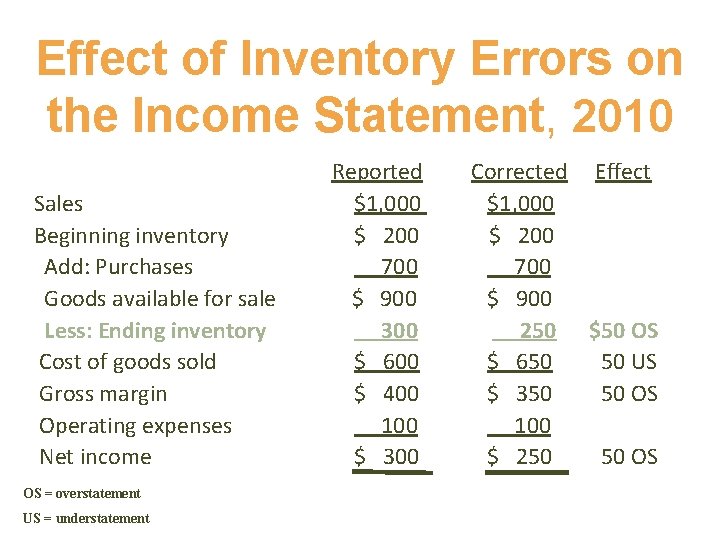
Effect of Inventory Errors on the Income Statement, 2010 Sales Beginning inventory Add: Purchases Goods available for sale Less: Ending inventory Cost of goods sold Gross margin Operating expenses Net income OS = overstatement US = understatement Reported $1, 000 $ 200 700 $ 900 300 $ 600 $ 400 100 $ 300 Corrected Effect $1, 000 $ 200 700 $ 900 250 $50 OS $ 650 50 US $ 350 50 OS 100 $ 250 50 OS
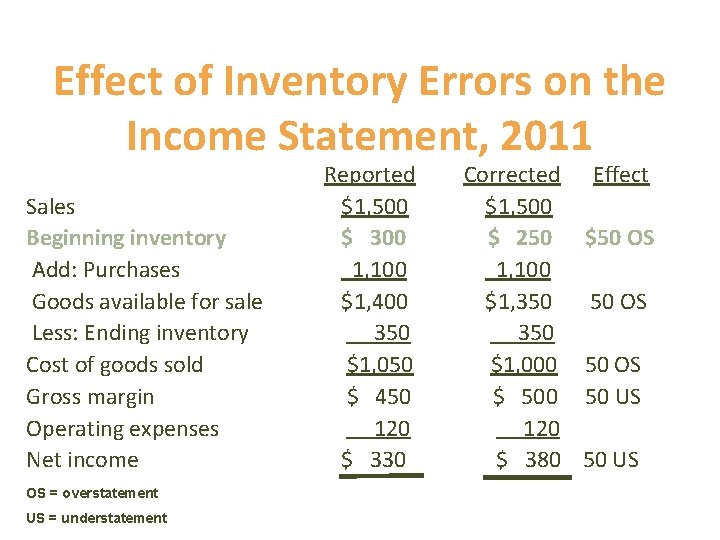
Effect of Inventory Errors on the Income Statement, 2011 Sales Beginning inventory Add: Purchases Goods available for sale Less: Ending inventory Cost of goods sold Gross margin Operating expenses Net income OS = overstatement US = understatement Reported $1, 500 $ 300 1, 100 $1, 400 350 $1, 050 $ 450 120 $ 330 Corrected $1, 500 $ 250 1, 100 $1, 350 $1, 000 $ 500 120 $ 380 Effect $50 OS 50 US
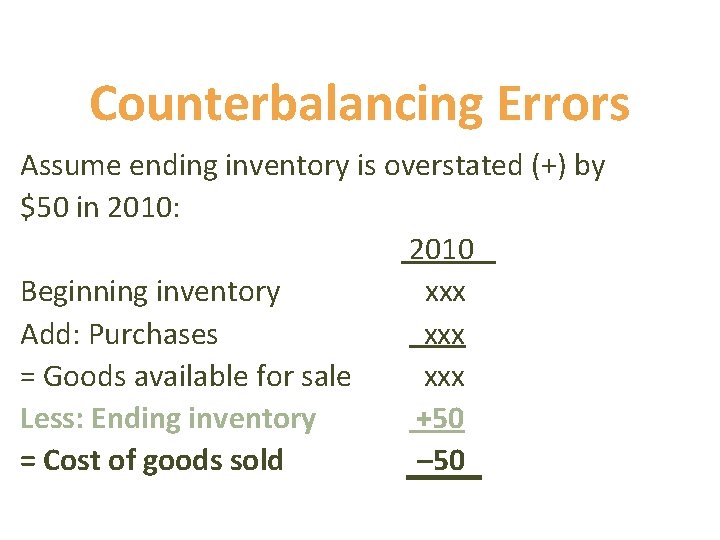
Counterbalancing Errors Assume ending inventory is overstated (+) by $50 in 2010: 2010 Beginning inventory xxx Add: Purchases xxx = Goods available for sale xxx Less: Ending inventory +50 = Cost of goods sold – 50
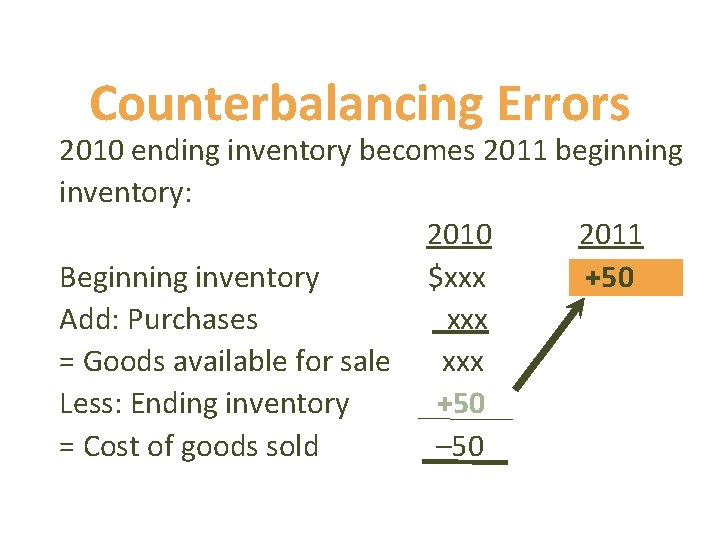
Counterbalancing Errors 2010 ending inventory becomes 2011 beginning inventory: 2010 2011 Beginning inventory $xxx +50 Add: Purchases xxx = Goods available for sale xxx Less: Ending inventory +50 = Cost of goods sold – 50
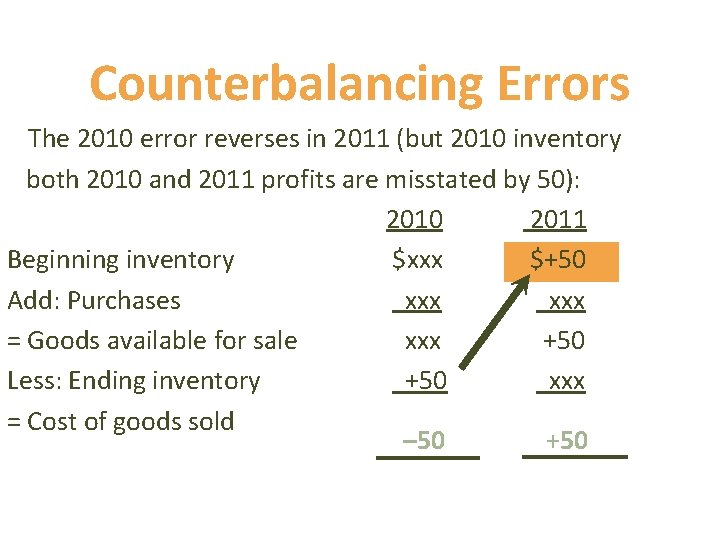
Counterbalancing Errors The 2010 error reverses in 2011 (but 2010 inventory both 2010 and 2011 profits are misstated by 50): 2010 2011 Beginning inventory $xxx $+50 Add: Purchases xxx = Goods available for sale xxx +50 Less: Ending inventory +50 xxx = Cost of goods sold – 50 +50
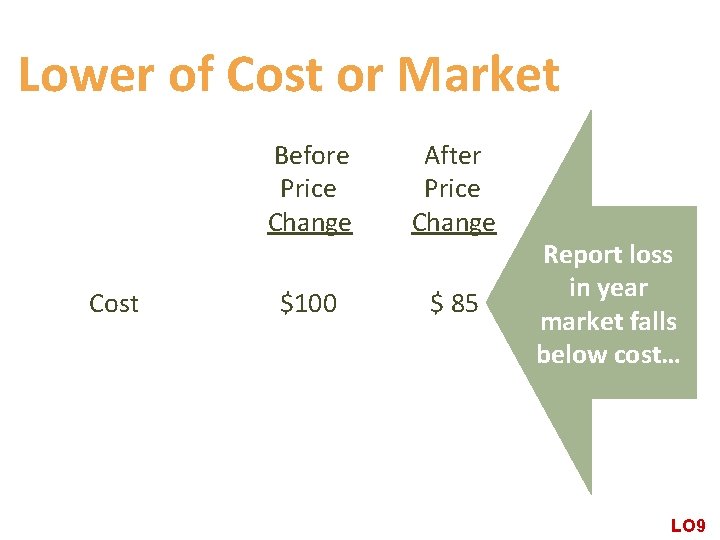
Lower of Cost or Market Cost Before Price Change After Price Change $100 $ 85 Report loss in year market falls below cost… LO 9
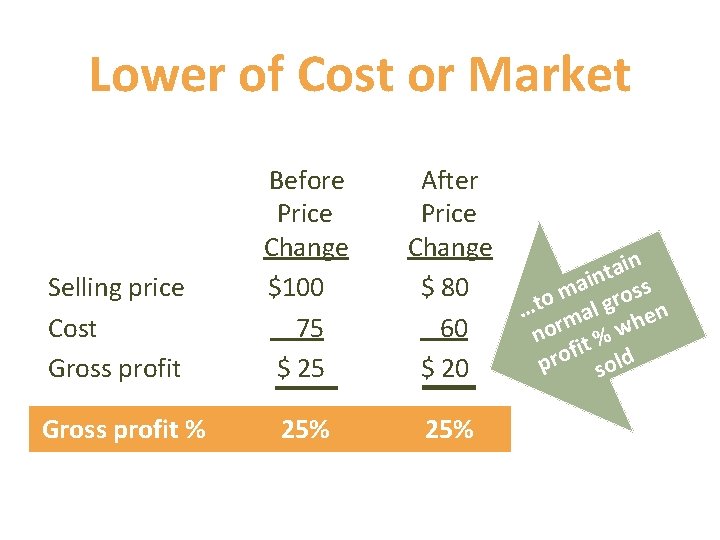
Lower of Cost or Market Selling price Cost Gross profit Before Price Change $100 75 $ 25 After Price Change $ 80 60 $ 20 Gross profit % 25% in a t ain oss m …to mal gr en h nor it % w f pro sold
Lower of Cost or Market v Market = replacement cost (not retail value) v Cost determined under one of the costing methods v Justified on basis of conservatism v Can be applied to: • Entire inventory • Individual items • Groups of items
Lower of Cost or Market under International Standards v Both U. S. GAAP and international financial reporting standards (IFRS) require lower-of -cost-or-market v Differences between U. S. GAAP and IFRS • How market value is defined • Recording changes in market value in future periods
Inventory Turnover Ratio Cost of Goods Sold Average Inventory The number of times period inventory is turned over (ie. sold) LO 10
Number of Days’ Sales in Inventory Number of Days in the Period Inventory Turnover Ratio The average number of days inventory is on hand before its sold
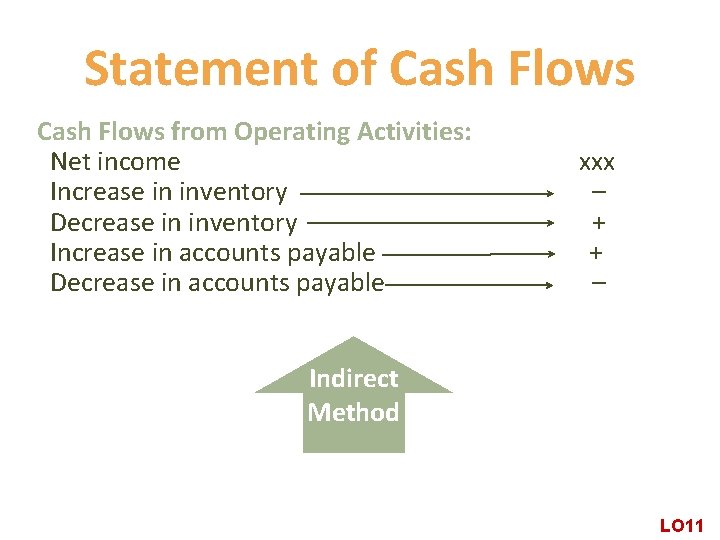
Statement of Cash Flows from Operating Activities: Net income Increase in inventory Decrease in inventory Increase in accounts payable Decrease in accounts payable xxx – + + – Indirect Method LO 11
Appendix Accounting Tools: Inventory Costing Methods with the Use of a Perpetual Inventory System
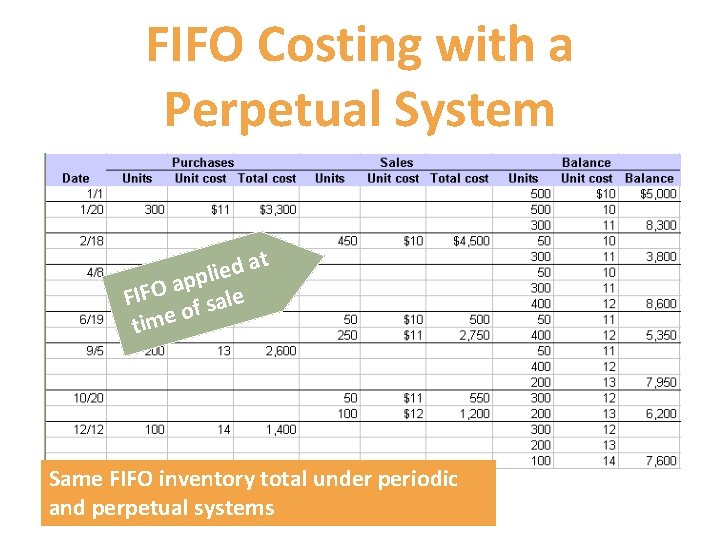
FIFO Costing with a Perpetual System t a d e pli p a FIFO f sale o e m i t Same FIFO inventory total under periodic and perpetual systems
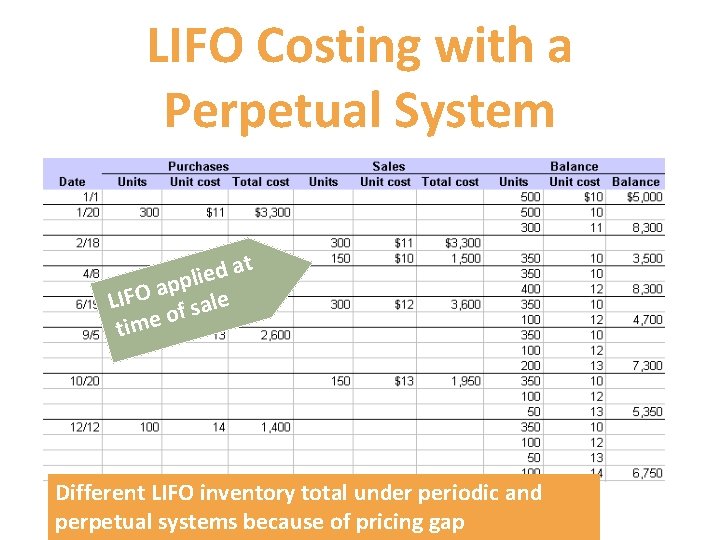
LIFO Costing with a Perpetual System t a d e i pl p a LIFO f sale o e m i t Different LIFO inventory total under periodic and perpetual systems because of pricing gap
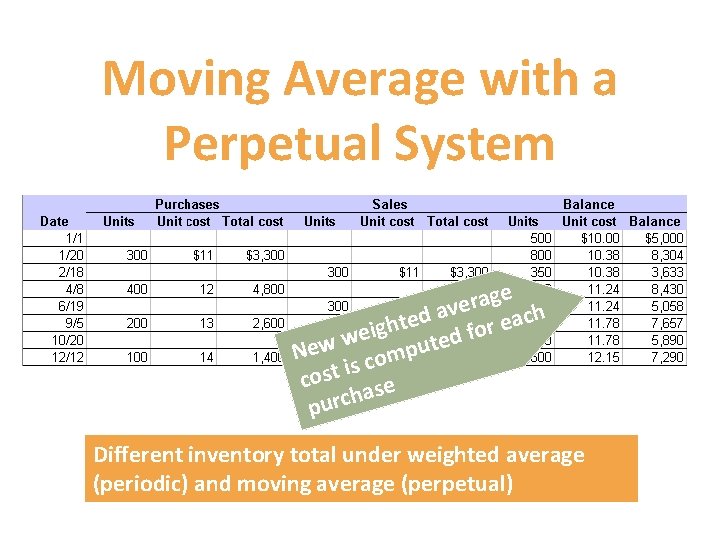
Moving Average with a Perpetual System age r e v a ch d a e t e h r ig fo e d w e t New compu is t s o c e s a h c pur Different inventory total under weighted average (periodic) and moving average (perpetual)
End of Chapter 5