Association of Provident Funds Risks of offshore investing
- Slides: 60
Association of Provident Funds Risks of offshore investing Greg Liddell JUNE 2013
Benefits of Overseas Investing › Access to different companies and sectors › Diversification of economic/growth cycle › Diversification of interest rate cycle › Benefits of currency diversification › Reduction of home country bias p. 2
Risks Of Offshore Investing › Market Risk o Equity market risk o Credit o Currency › Manager Risk › Operational Risks o Counter party o Settlement o Custodian p. 3
Risks Management – Market Crises › 1972 World Oil Crisis (1 Dec’ 72 – 30 Sep’ 74) › 1987 Crash (14 Oct’ 87 – 19 Oct’ 87) › 1990 Recession (17 Jul’ 90 – 15 Nov’ 92) › 2000 Argentine Economic Crisis (3 Mar’ 00 – 26 Jun’ 02) › 2001 Dot-Com Slowdown (10 Mar’ 01 – 9 Oct’ 02) › 2002 Accounting Scandals & World. Com (30 Apr’ 02 – 23 Jul’ 02) › 2008 Global Financial Crisis (1 Oct’ 07 – 27 Feb’ 09) p. 4
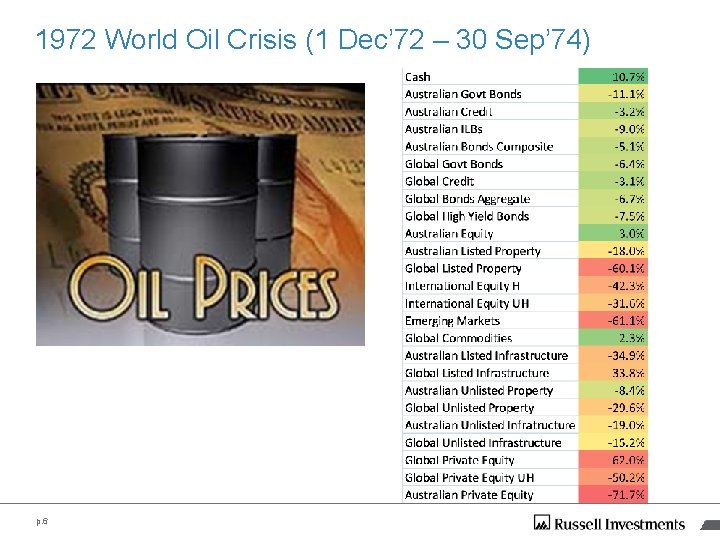
1972 World Oil Crisis (1 Dec’ 72 – 30 Sep’ 74) › Overview of market conditions o Severe downturn in global equity markets o High inflation o Australian interest rates jump sharply => negative bond returns o Property market collapses p. 5
1972 World Oil Crisis (1 Dec’ 72 – 30 Sep’ 74) p. 6
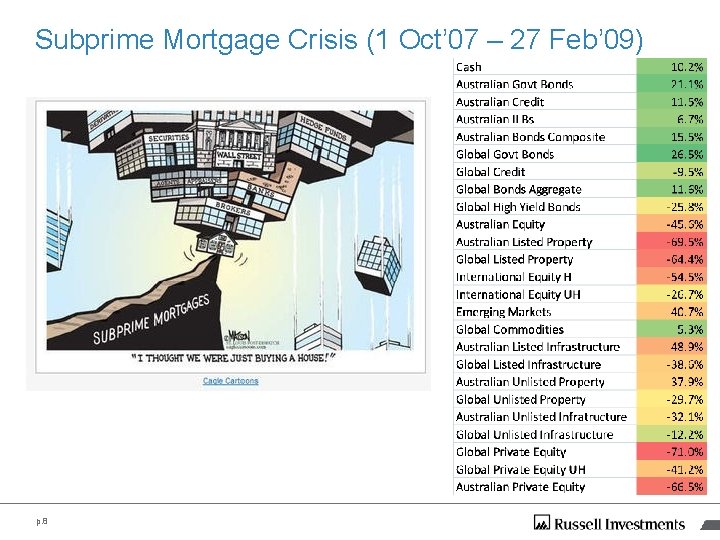
Subprime Mortgage Crisis (1 Oct’ 07 – 27 Feb’ 09) › Complex and multi-faceted crisis › Followed extended period of artificially low US interest rates => lower investment disciplines › Credit failures led to equity falls › Losses extended to other risk asset classes › Sovereign bonds the best performing asset class p. 7
Subprime Mortgage Crisis (1 Oct’ 07 – 27 Feb’ 09) p. 8
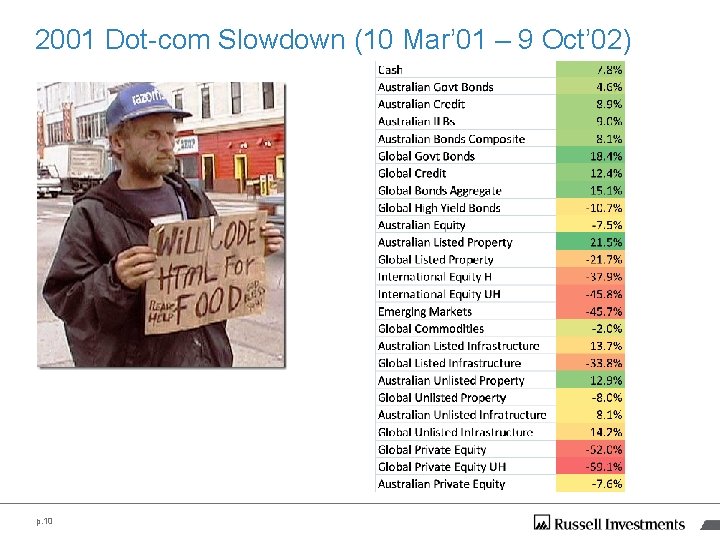
2001 Dot-com Slowdown (10 Mar’ 01 – 9 Oct’ 02) › Fall in equity markets following speculative tech bubble burst in April 2000 › General slump in investor sentiment › Spread to other global risk assets e. g. listed property › Australian shares underperformed during bubble build up and outperformed as it burst p. 9
2001 Dot-com Slowdown (10 Mar’ 01 – 9 Oct’ 02) p. 10
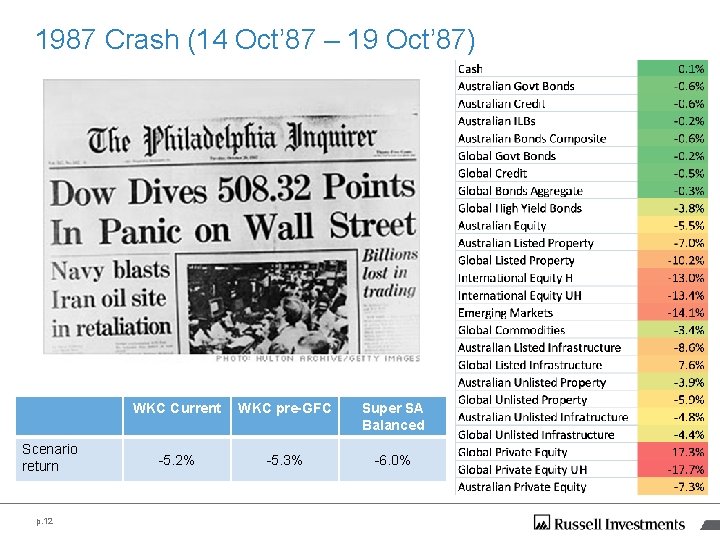
1987 Crash (14 Oct’ 87 – 19 Oct’ 87) › Short period of equity market decline globally › Prior years saw relaxed investment, governance and balance sheet disciplines › Largest one-day percentage fall in the Dow Jones Industrial Average of 22. 6% › Economic fundamentals unaffected p. 11
1987 Crash (14 Oct’ 87 – 19 Oct’ 87) Scenario return p. 12 WKC Current WKC pre-GFC Super SA Balanced -5. 2% -5. 3% -6. 0%
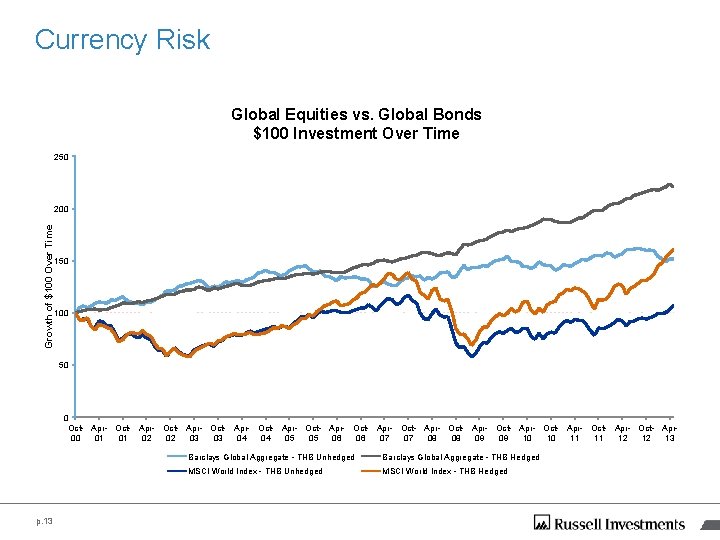
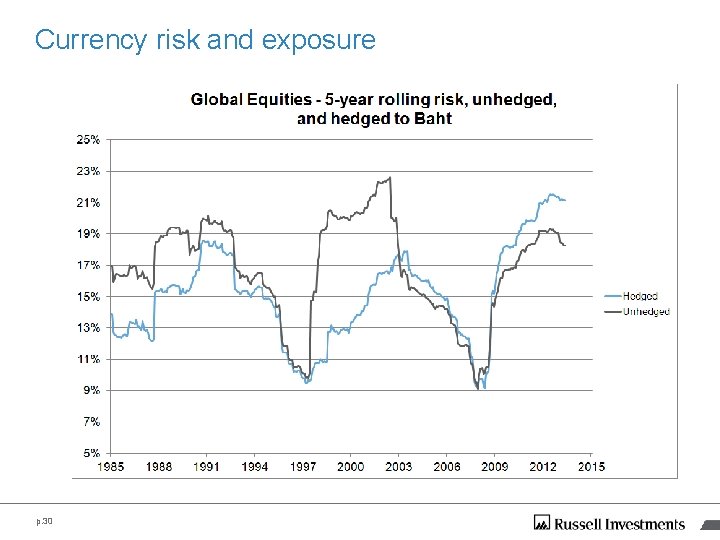
Currency Risk Global Equities vs. Global Bonds $100 Investment Over Time 250 Growth of $100 Over Time 200 150 100 50 0 Oct- Apr- Oct- Apr- Oct- Apr- Oct- Apr 00 01 01 02 02 03 03 04 04 05 05 06 06 07 07 08 08 09 09 10 10 11 11 12 12 13 p. 13 Barclays Global Aggregate - THB Unhedged Barclays Global Aggregate - THB Hedged MSCI World Index - THB Unhedged MSCI World Index - THB Hedged
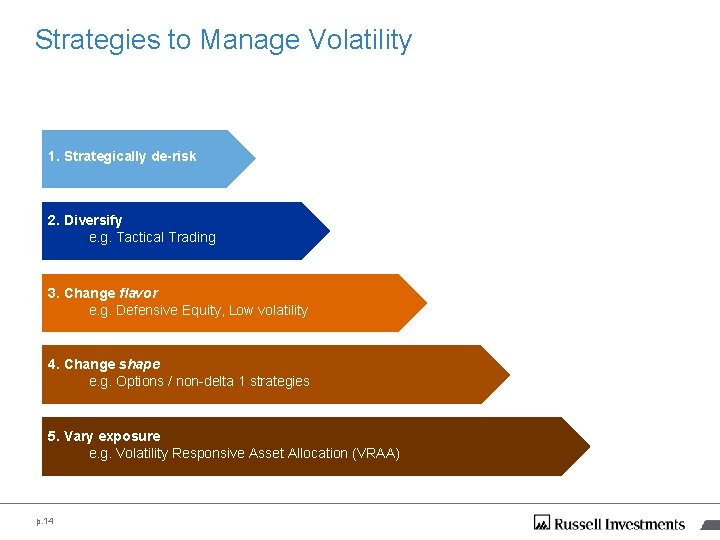
Strategies to Manage Volatility 1. Strategically de-risk 2. Diversify e. g. Tactical Trading 3. Change flavor e. g. Defensive Equity, Low volatility 4. Change shape e. g. Options / non-delta 1 strategies 5. Vary exposure e. g. Volatility Responsive Asset Allocation (VRAA) p. 14
Operational Risks › Counter Party Risk o Fraud o Negligence/Error or Omission o Bankruptcy › Can Impact o Fund Managers o Brokers o Custodians o Accountants/Auditors/Valuers o Exchanges p. 15
Operational Risk Mitigation › Risk audit › Operational due diligence › Contract review – use of credit support annexes (CSA) › Jurisdiction › Mark-to-market › Counter-party identification and use of credit limits › Agent versus principal › Agent liability › Settlement protocols e. g. Continuously Linked Settlement of FX p. 16
Association of Provident Funds Taxation of offshore investments Raewyn Williams, Director, After-Tax Investment Strategies JUNE 2013
I will cover… › Taxation of Thai provident funds in Thailand › Adding offshore investments – exploring the Australian tax impact › Conclusion – What does this mean for the investment strategies of Thai provident funds? p. 18
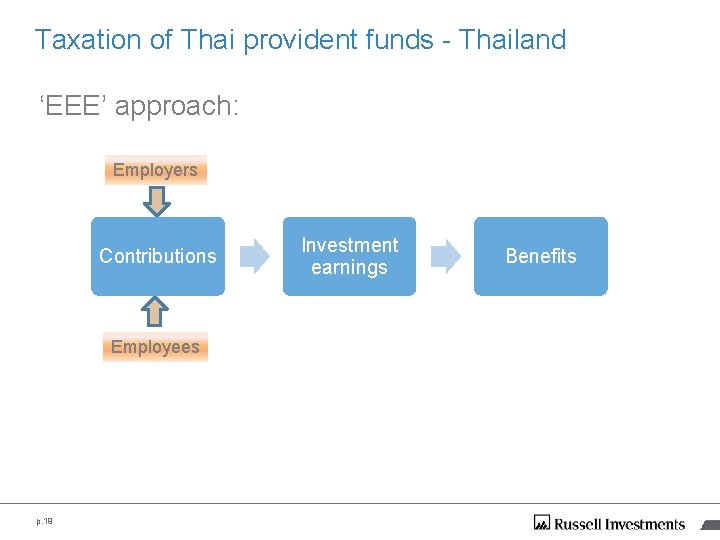
Taxation of Thai provident funds - Thailand ‘EEE’ approach: Employers Contributions Employees p. 19 Investment earnings Benefits
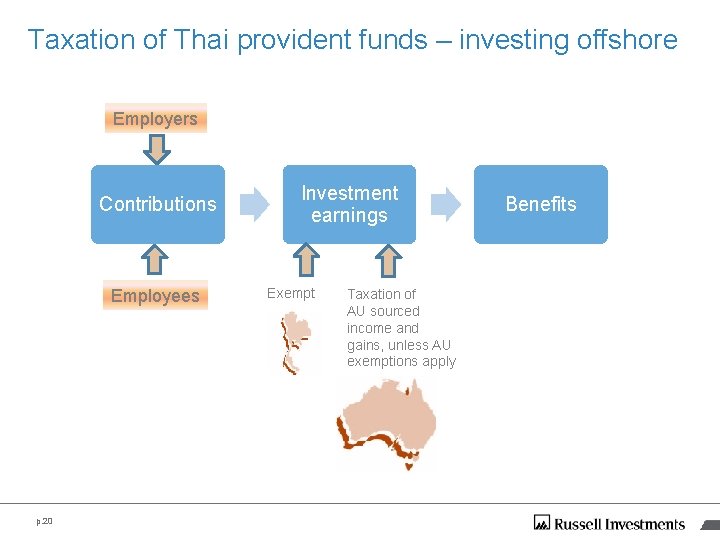
Taxation of Thai provident funds – investing offshore Employers Contributions Employees p. 20 Investment earnings Exempt Taxation of AU sourced income and gains, unless AU exemptions apply Benefits
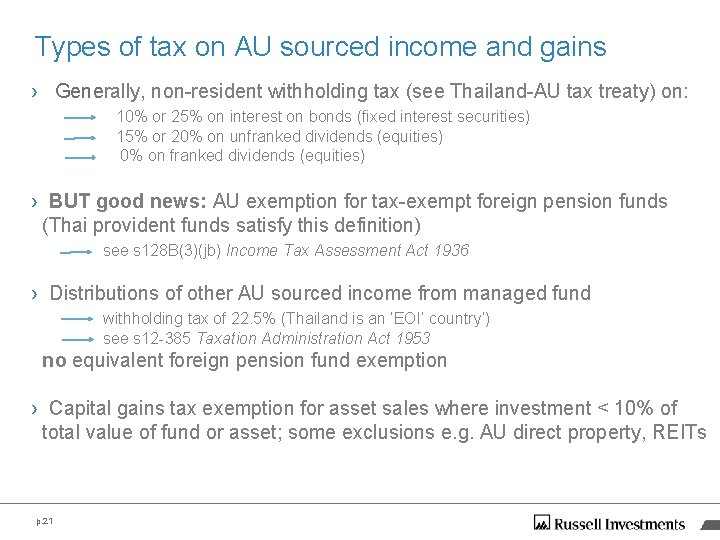
Types of tax on AU sourced income and gains › Generally, non-resident withholding tax (see Thailand-AU tax treaty) on: 10% or 25% on interest on bonds (fixed interest securities) 15% or 20% on unfranked dividends (equities) 0% on franked dividends (equities) › BUT good news: AU exemption for tax-exempt foreign pension funds (Thai provident funds satisfy this definition) see s 128 B(3)(jb) Income Tax Assessment Act 1936 › Distributions of other AU sourced income from managed fund withholding tax of 22. 5% (Thailand is an ‘EOI’ country’) see s 12 -385 Taxation Administration Act 1953 no equivalent foreign pension fund exemption › Capital gains tax exemption for asset sales where investment < 10% of total value of fund or asset; some exclusions e. g. AU direct property, REITs p. 21
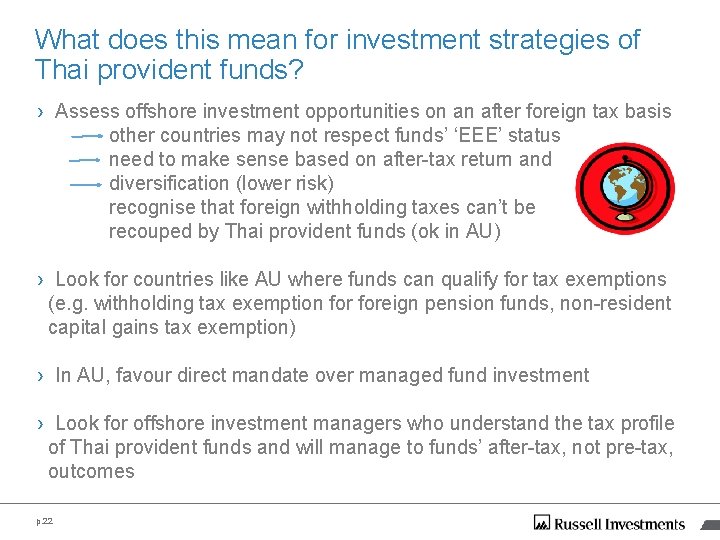
What does this mean for investment strategies of Thai provident funds? › Assess offshore investment opportunities on an after foreign tax basis other countries may not respect funds’ ‘EEE’ status need to make sense based on after-tax return and diversification (lower risk) recognise that foreign withholding taxes can’t be recouped by Thai provident funds (ok in AU) › Look for countries like AU where funds can qualify for tax exemptions (e. g. withholding tax exemption foreign pension funds, non-resident capital gains tax exemption) › In AU, favour direct mandate over managed fund investment › Look for offshore investment managers who understand the tax profile of Thai provident funds and will manage to funds’ after-tax, not pre-tax, outcomes p. 22
Taxation of offshore investments – an introduction Questions? “Russell, ” “Russell Investments, ” “Russell 1000, ” “Russell 2000, ” and “Russell 3000” are registered trademarks of the Frank Russell Company. www. russell. com/au
Association of Provident Fund Global Market Outlook and Risks Looking Forward Graham Harman – Investment Strategist, Asia-Pacific JUNE 2013
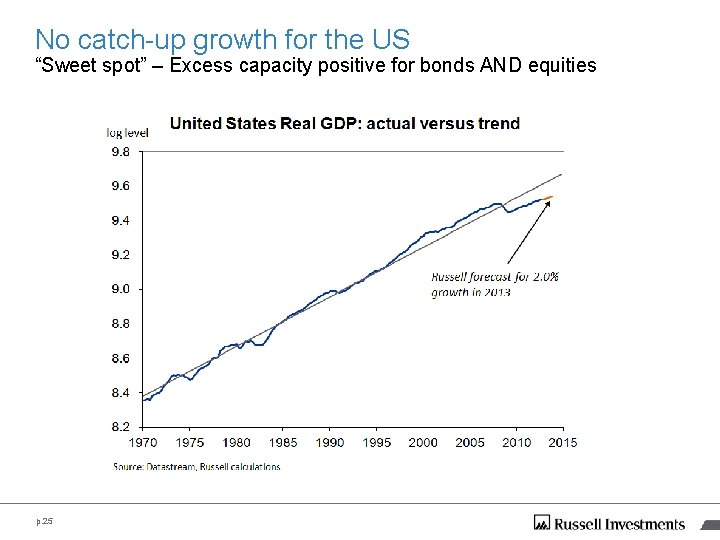
No catch-up growth for the US “Sweet spot” – Excess capacity positive for bonds AND equities p. 25
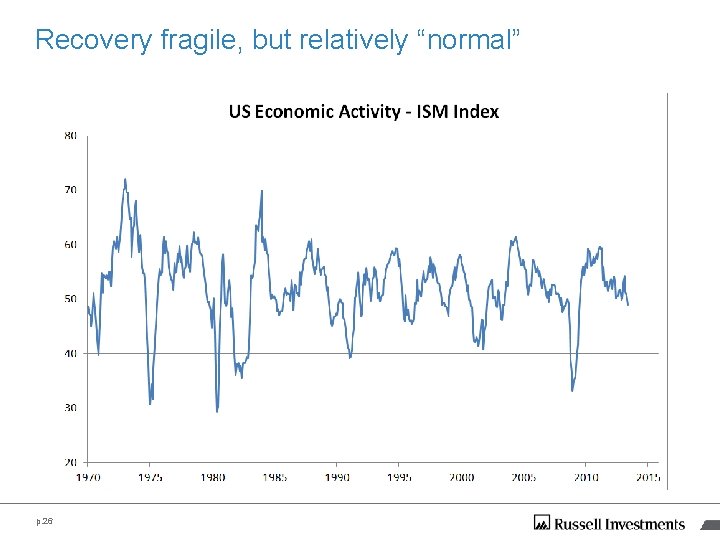
Recovery fragile, but relatively “normal” p. 26
Key messages › We are: o Cautious near-term on equities (longer-term there is upside) o Looking for a gradual rise in bond yields o Seeing moderate US growth, decreasingly worried about structural headwinds o Decreasingly worried about Europe, and see value longer term o Seeing a slowdown in China, but still like the story o Positive about Japan, although phase 2 will be more challenging o Seeing value, but no short term positive catalysts, for emerging market equities o Cautious about the “safe havens” of the past few years – gold, US treasuries, Australian dollar, emerging market debt p. 27
Risks 1. Valuation/duration 2. Currency 3. Economic growth 4. Inflation 5. Social fabric 6. Geopolitical 7. Agency p. 28
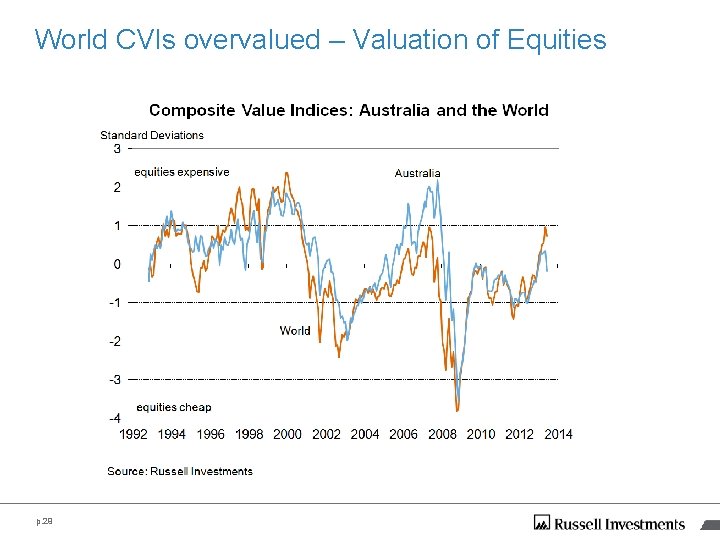
World CVIs overvalued – Valuation of Equities p. 29
Currency risk and exposure p. 30
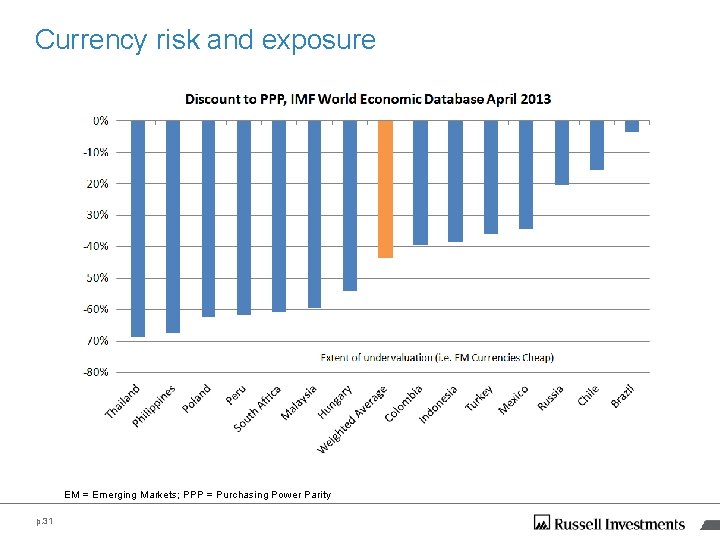
Currency risk and exposure EM = Emerging Markets; PPP = Purchasing Power Parity p. 31
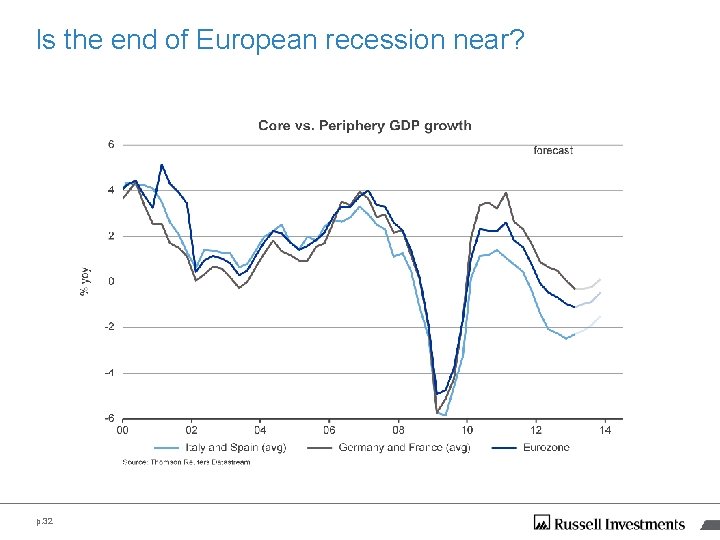
Is the end of European recession near? p. 32
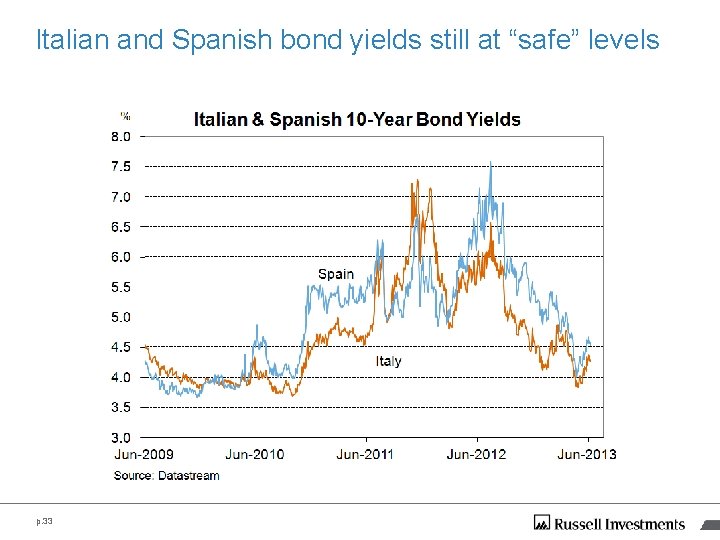
Italian and Spanish bond yields still at “safe” levels p. 33
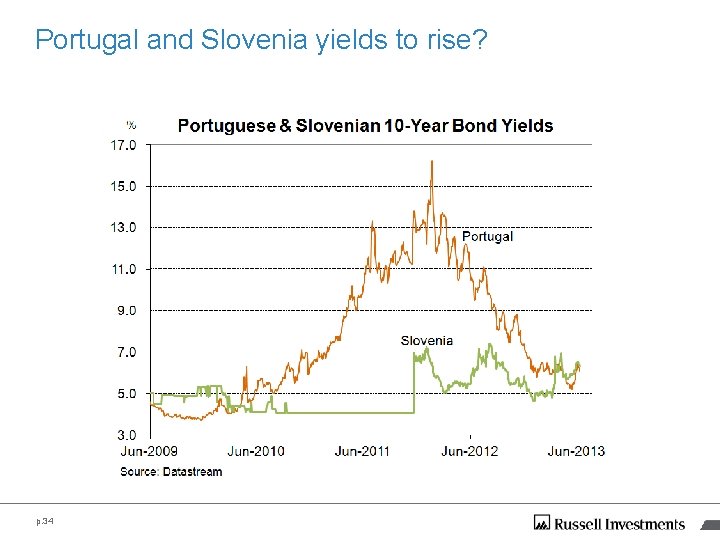
Portugal and Slovenia yields to rise? p. 34
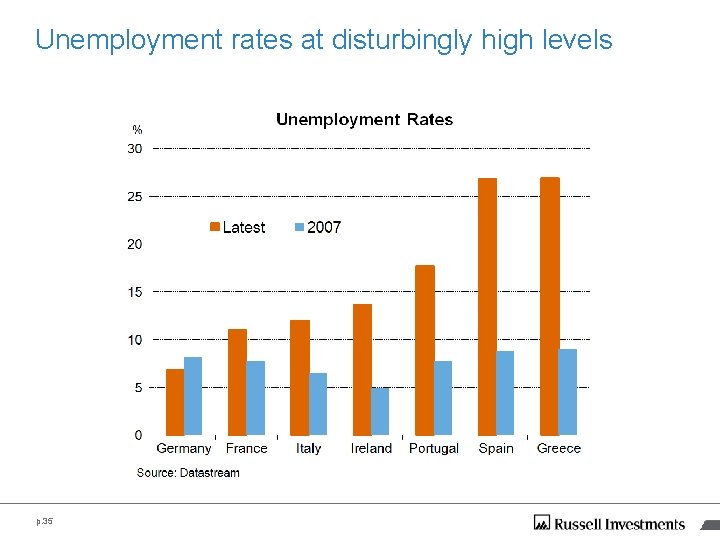
Unemployment rates at disturbingly high levels p. 35
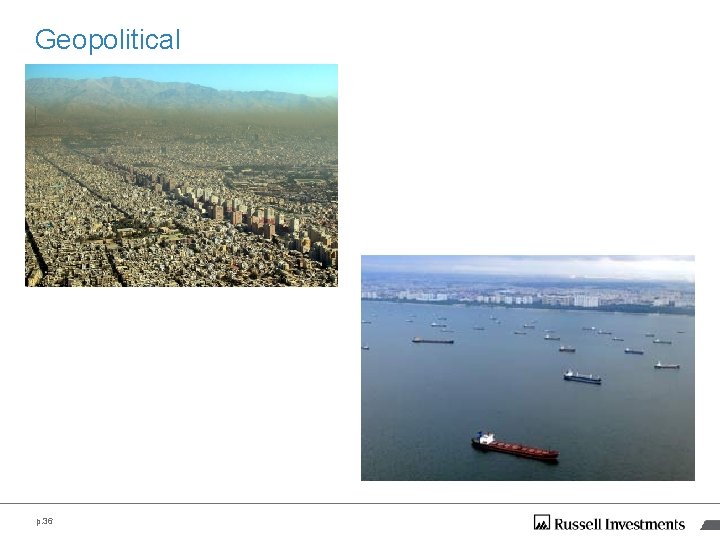
Geopolitical p. 36
Association of Provident Funds Australian Funds Management Industry Overview James Mc. Skimming JUNE 2013
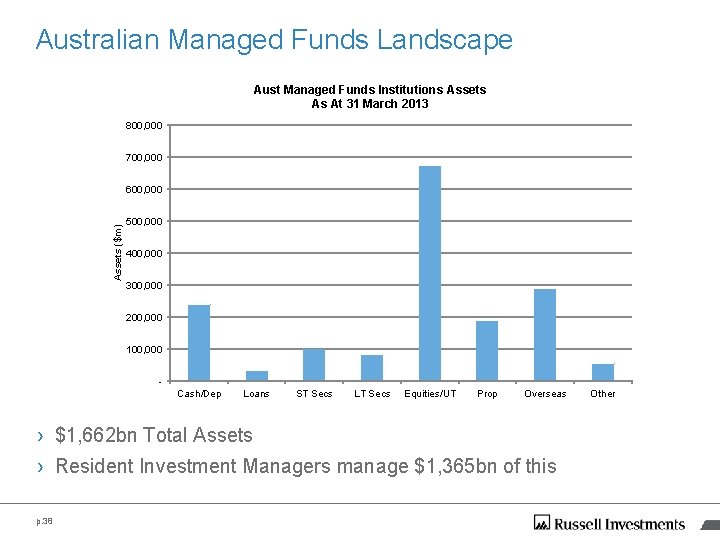
Australian Managed Funds Landscape Aust Managed Funds Institutions Assets As At 31 March 2013 800, 000 700, 000 Assets ($m) 600, 000 500, 000 400, 000 300, 000 200, 000 100, 000 Cash/Dep Loans ST Secs LT Secs Equities/UT Prop Overseas › $1, 662 bn Total Assets › Resident Investment Managers manage $1, 365 bn of this p. 38 Other
Australia’s Money Managers › Predominantly focussed on investing in Australia › Secondary interest in New Zealand, Asia Pac, Global › Few Global investment funds offered by resident money managers › Russell monitors and researches around 175 Aust Equity products, 110 Aust Cash and FI products › Boutique firms have dominated for the last ten years › Staff ownership › Life cycle challenge; Who will lead the firm tomorrow? › Institutional or global ownership - not a safer haven than boutiques › Competition and Consolidation › Internal management, overseas entrants, scale › Shifting emphasis in investment approaches › Eg Income, mortgage credit, managed volatility, beta variations, absolute return p. 39
Russell Asia-Pac Multi -asset capabilities Scott Fletcher Director, Client Investment Strategies JUNE 2013
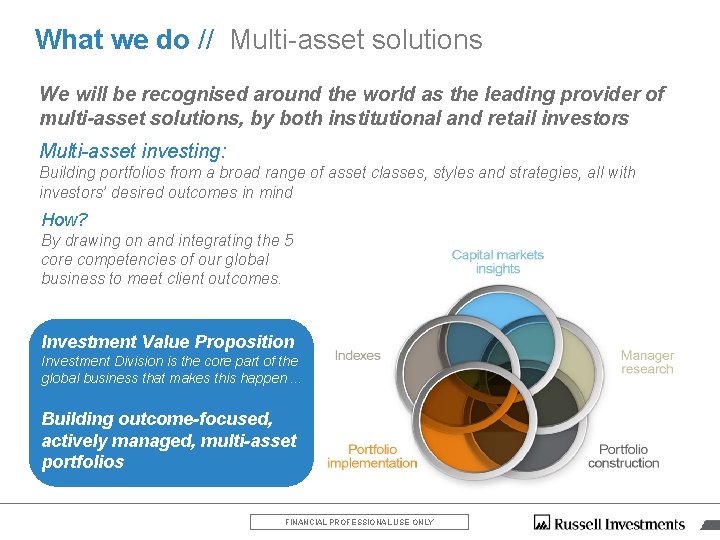
What we do // Multi-asset solutions We will be recognised around the world as the leading provider of multi-asset solutions, by both institutional and retail investors Multi-asset investing: Building portfolios from a broad range of asset classes, styles and strategies, all with investors’ desired outcomes in mind How? By drawing on and integrating the 5 core competencies of our global business to meet client outcomes. Investment Value Proposition Investment Division is the core part of the global business that makes this happen. . . Building outcome-focused, actively managed, multi-asset portfolios FINANCIAL PROFESSIONAL USE ONLY
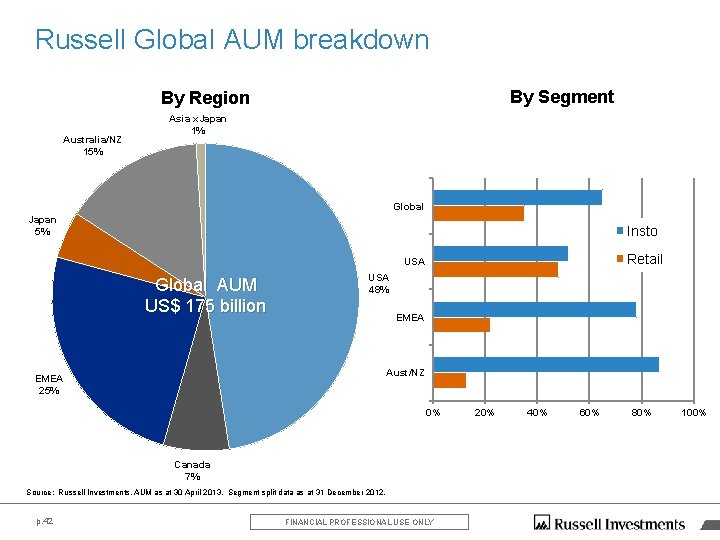
Russell Global AUM breakdown By Segment By Region Australia/NZ 15% Asia x. Japan 1% Global Japan 5% Insto Retail USA Global AUM US$ 175 billion USA 48% EMEA Aust/NZ EMEA 25% 0% Canada 7% Source: Russell Investments, AUM as at 30 April 2013. Segment split data as at 31 December 2012. p. 42 FINANCIAL PROFESSIONAL USE ONLY 20% 40% 60% 80% 100%
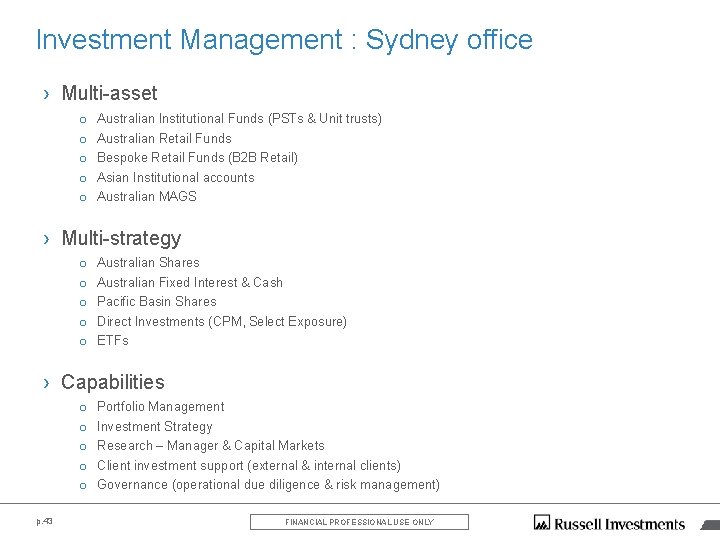
Investment Management : Sydney office › Multi-asset o o o Australian Institutional Funds (PSTs & Unit trusts) Australian Retail Funds Bespoke Retail Funds (B 2 B Retail) Asian Institutional accounts Australian MAGS › Multi-strategy o o o Australian Shares Australian Fixed Interest & Cash Pacific Basin Shares Direct Investments (CPM, Select Exposure) ETFs › Capabilities o o o p. 43 Portfolio Management Investment Strategy Research – Manager & Capital Markets Client investment support (external & internal clients) Governance (operational due diligence & risk management) FINANCIAL PROFESSIONAL USE ONLY
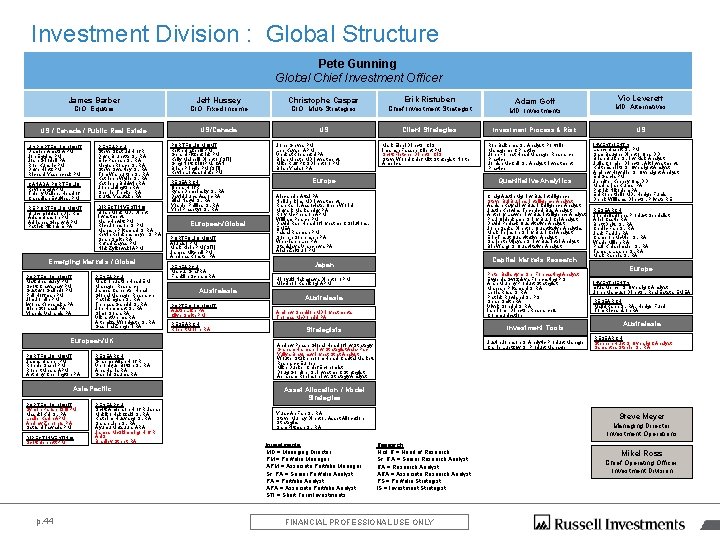
Investment Division : Global Structure Pete Gunning Global Chief Investment Officer James Barber Jeff Hussey Christophe Caspar Erik Ristuben CIO, Equities CIO, Fixed Income CIO, Multi-Strategies Chief Investment Strategist MD, Investments US / Canada / Public Real Estate US/Canada US Client Strategies Investment Process & Risk US PORTFOLIO MGMT Damien Amato APM Jon Eggins PM Josh Goodell PA Rob Kuharic PM Dave Hintz PM Richard Yasenchak PM CANADA PORTFOLIO Kevin Eng APM Thierry Vallee, Head of Canadian Equities, PM RE PORTFOLIO MGMT Bruce Eidelson Dir. RE Adam Babson PM Adrianna Giesey APM Patrick Nikodem PA RESEARCH Steve Skatrud H of R Dave Brunette Sr. RA Eric Papesh Sr. RA Megan Roach Sr. RA Steve Swartley Sr. RA Tom Warburton Sr. RA Kathleen Wylie Sr. RA Kathleen Baldwin RA John Lidington RA Sherrie Trecker RA Curtis Yasutake RA DIRECT INVESTING Brian Mock MD, Direct Investments Marc Hewitt PM Rich Johnson Sr PM Mahesh Pritamani Sr RA Kevin Reinkensmeyer Sr PA Sean Smith RA Rafael Zayas PM Nick Zylkowski APM Emerging Markets / Global PORTFOLIO MGMT Matt Beardsley PM Scott Crawshaw PM Gustavo Galindo PM Phil Hoffman PM Jim Jornlin PM Iwona Kochanska PA Olen Storaasli PA Yiannis Vairamis PA RESEARCH Mark Thurston Head EM Manager Research James Carpenter Head Global Manager Research Patrick Egan Sr. RA Tereasa Gandhi Sr. RA Joe Hemmant Sr. RA Simo Sorsa RA Vikrant Verma RA Artemiza Woodgate Sr. RA Gashirai Zengeni RA European/UK PORTFOLIO MGMT James Barber PM Ronnie Sabel PM Robert Mears APM Anthony Cherrington PA RESEARCH Graeme Allan H of R Veronique Botton Sr. RA Ana Harris RA Gabriel Sauma RA Asia Pacific PORTFOLIO MGMT Symon Parish CIO/PM Masaki Kai Sr. PA Leslie Kapin APM Andrew Zenonos PA Satoshi Tawada PM DIRECT INVESTING Scott Bennett PM p. 44 RESEARCH Scott Anderson H of R Japan Makiko Hakozaki Sr. RA Kathrine Husvaeg Sr. RA Sarah Lien Sr. RA Ayumu Matsuura ARA James Mc. Skimming H of R AUS Bradley Street. RA PORTFOLIO MGMT Keith Brakebill PM Gerard Fitzpatrick PM Kelly Mainelli Director (STI) Greg Nott CIO/PM, CAN Brian Pringle PM (STI) Kevin Lo Associate PM RESEARCH Open, H of R Ryan Dembinsky Sr. RA David Jurca Assoc RA Bilal Naqvi Sr. RA Yoshie Phillips Sr. RA Yoel Prasetyo Sr. RA European/Global PORTFOLIO MGMT Al Jalso PM Mark Klein PM (STI) James Mitchell PM Andreas Koester PA RESEARCH Marcus Graf RA Franklin Schram RA Australasia PORTFOLIO MGMT Austin Loke PA Clive Smith PM RESEARCH Robert Moore RA John Greves PM Lee Kayser APM Venkat Kopanathi PA Brian Meath MD Investments Mike Ruff PCS Director / PM Brian Yadao PA Mark Eibel Director CIS Iheshan Faasee Client PM Scott Fletcher Director CIS Steve Wood Chief Mkt Strategist, North America Adam Goff Rob Balkema Sr. Analyst, Portfolio Management Practice John Forrest Head Manager Research Practice Jordan Mc. Call Sr. Analyst, Investment Practice Quantitative Analytics Europe Craig Austin Mgr Inv Bus Intelligence Steve Bui Busines Intelligence Analyst Ashish Katyal Inv Bus Intelligence Analyst Justin Knowles Technical Bus Analyst Anthony Lawver Inv Bus Intelligence Analyst Paul Oldenkamp Sr Inv Bus Intel Analyst David Pedack Quantitative Analyst John Sacks Director, Quantitative Analytics Mark Terjeson Sr Inv Bus Intel Analyst Eric Thaut Quantitative Analyst Sanjeeth Vijayan Sr Inv Bus Intel Analyst Bin Wang Sr Quantitative Analyst Alexandre Attal PA Neil Jenkins MD Investments Ran Karni, Associate, Open World Mayank Markanday PA Rory Mc. Pherson APM William Pearce PM David Rae Head of Investment Solutions, EMEA Faisal Rahman PM Soerensen PA Wee-Tsen Lee PA Stanislava Vrabcheva PA Alain Zeitouni PM Capital Markets Research Japan Peter Ballantyne Snr Forecasting Analyst Evgenia Gvozdeva Forecasting PS Aran Murphy Product Strategist Mahesh Pritamani Sr RA Leola Ross Sr RA Patrick Rowland Sr. PS Sean Smith RA Vivek Sondhi Sr RA Ian Toner Director, Research & Communication Hiroyuki Nakagawa Director / PM Michinori Kanokogi APM Australasia Andrew Sneddon MD Investments Thomas Mc. Donald PA Investment Tools Strategists Justin Johnson Sr Analytic Product Manager Carrie Luetzow Sr Product Manager Andrew Pease Global Head of Inv Strategy Graham Harman Inv Strategist Asia-Pac Yuliya Brayshaw Invest Strat Analyst Wouter Sturkenboom Head, Capital Markets Research-Europe Mike Dueker Chief Economist Doug Gordon Sr. Investment Strategist Abraham Robinson Inv. Strategy Analyst Vic Leverett MD, Alternatives US INVESTMENTS Lance Babbit Sr. PM Sam Baughn Director Ops DD Brian Burke Sr. Inv Risk Analyst Julia Cormier Director, Alt Investments Keith Espirito Sr Oversight Analyst Andrew Howeiler Sr Oversight Analyst Ed Garcia PM Jennifer Keeney Ops DD Maniranjan Kumar PA Patrick Nikodem PA Ed Robertiello MD, Hedge Funds Derek Williams Director, Private RE RESEARCH Joe Belladonna Product Specialist Ariel Castle RA Brett Deits Sr. RA Cedric Fan Sr. RA Jack Fadule RA Cameron Mc. Vie Sr. RA Wade Millen RA Paul Kreiselmaier Sr. RA Tamara Larsen Sr. RA Mark Rapela Sr. RA Europe INVESTMENTS Efua Mercer Sr Oversight Analyst John Mancuso Director, Real Estate, EMEA RESEARCH Majid Kahn Sr. RA, Hedge Fund Tom Richardson RA Australasia RESEARCH Stephen Hunt Sr Oversight Analyst Samantha Steele Sr. RA Asset Allocation / Model Strategies Yuan-An Fan Sr. RA Steve Murray Director, Asset Allocation Strategies Sam Pittman Sr. RA Investments MD = Managing Director PM = Portfolio Manager APM = Associate Portfolio Manager Sr. PA = Senior Portfolio Analyst PA = Portfolio Analyst APA = Associate Portfolio Analyst STI = Short Term Investments Steve Meyer Managing Director, Investment Operations Research H of R = Head of Research Sr. RA = Senior Research Analyst RA = Research Analyst ARA = Associate Research Analyst PS = Portfolio Strategist IS = Investment Strategist FINANCIAL PROFESSIONAL USE ONLY Mikel Ross Chief Operating Officer, Investment Division
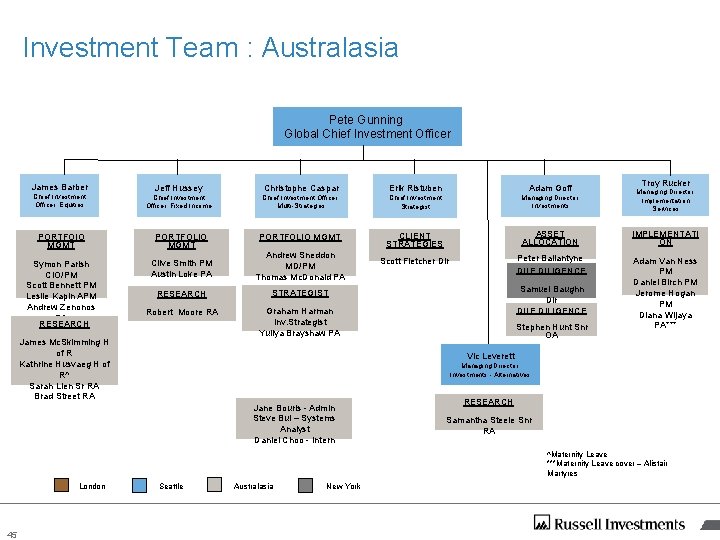
Investment Team : Australasia Pete Gunning Global Chief Investment Officer James Barber Jeff Hussey Chief Investment Officer, Equities Chief Investment Officer, Fixed Income Adam Goff Chief Investment Officer, Multi-Strategies Chief Investment Strategist Managing Director, Investments Managing Director, Implementation Services CLIENT STRATEGIES ASSET ALLOCATION IMPLEMENTATI ON Scott Fletcher Dir Peter Ballantyne CMA DUE DILIGENCE Adam Van Ness PM Daniel Birch PM Jerome Hogan PM Diana Wijaya PA*** PORTFOIO MGMT PORTFOLIO MGMT Symon Parish CIO/PM Scott Bennett PM Leslie Kapin APM Andrew Zenonos PA RESEARCH Clive Smith PM Austin Loke PA Andrew Sneddon MD/PM Thomas Mc. Donald PA RESEARCH STRATEGIST Robert Moore RA Graham Harman Inv. Strategist Yuliya Brayshaw PA James Mc. Skimming H of R Kathrine Husvaeg H of R^ Sarah Lien Sr RA Brad Street RA Troy Rucker Erik Ristuben Christophe Caspar Samuel Baughn Dir DUE DILIGENCE Stephen Hunt Snr OA Vic Leverett Managing Director, Investments - Alternatives Jane Bouris - Admin Steve Bui – Systems Analyst Daniel Choo - Intern RESEARCH Samantha Steele Snr RA ^Maternity Leave ***Maternity Leave cover – Alistair Martyres London 45 Seattle Australasia New York
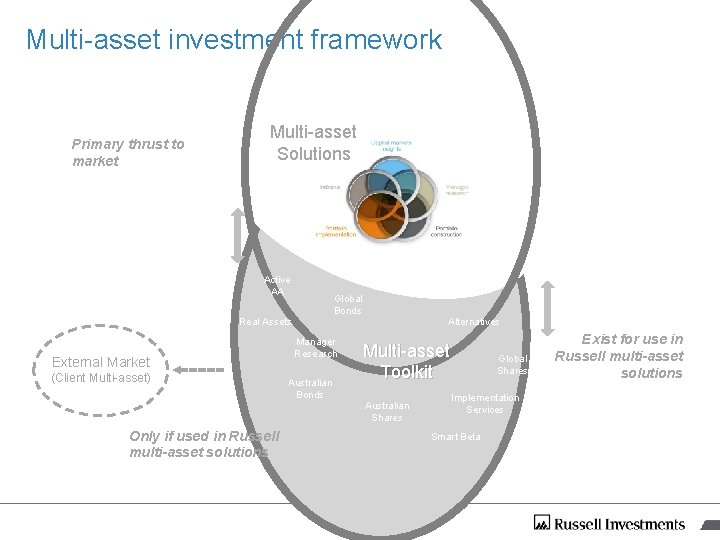
Multi-asset investment framework Primary thrust to market Multi-asset Solutions Active AA Global Bonds Real Assets External Market (Client Multi-asset) Manager Research Australian Bonds Alternatives Multi-asset Toolkit Australian Shares Only if used in Russell multi-asset solutions Global Shares Implementation Services Smart Beta Exist for use in Russell multi-asset solutions
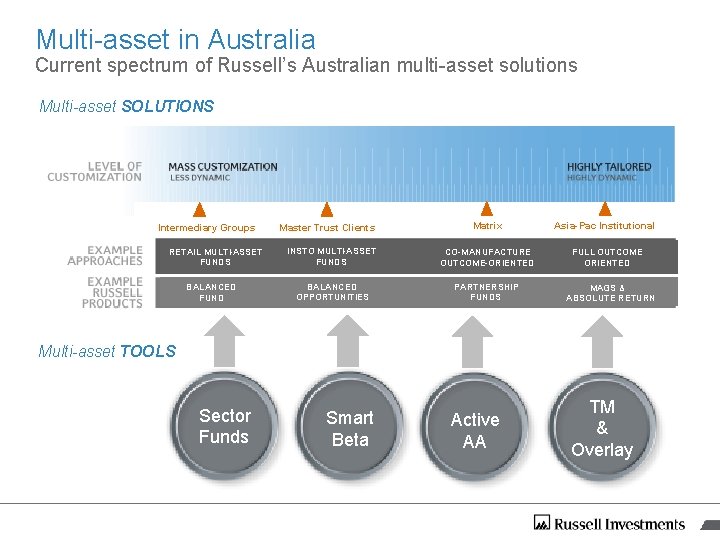
Multi-asset in Australia Current spectrum of Russell’s Australian multi-asset solutions Multi-asset SOLUTIONS Intermediary Groups RETAIL MULTI-ASSET FUNDS BALANCED FUND Matrix Asia-Pac Institutional INSTO MULTI-ASSET FUNDS CO-MANUFACTURE OUTCOME-ORIENTED FULL OUTCOME ORIENTED BALANCED OPPORTUNITIES PARTNERSHIP FUNDS Master Trust Clients MAGS & ABSOLUTE RETURN Multi-asset TOOLS Sector Funds Smart Beta Active AA TM & Overlay
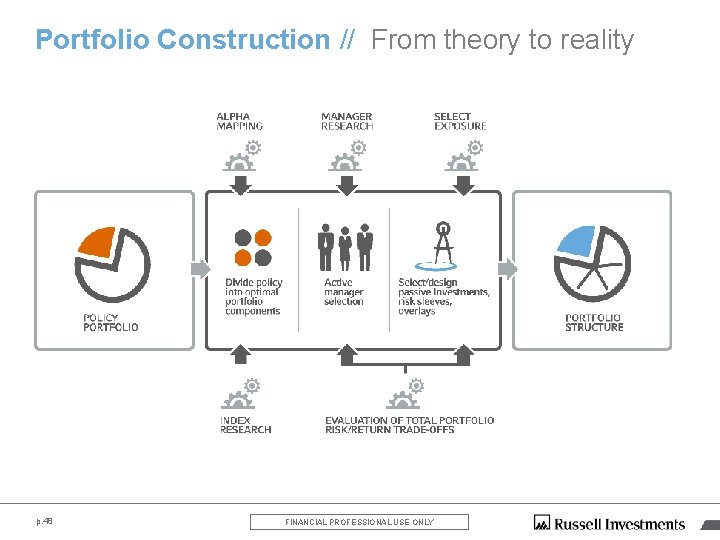
Portfolio Construction // From theory to reality p. 48 FINANCIAL PROFESSIONAL USE ONLY
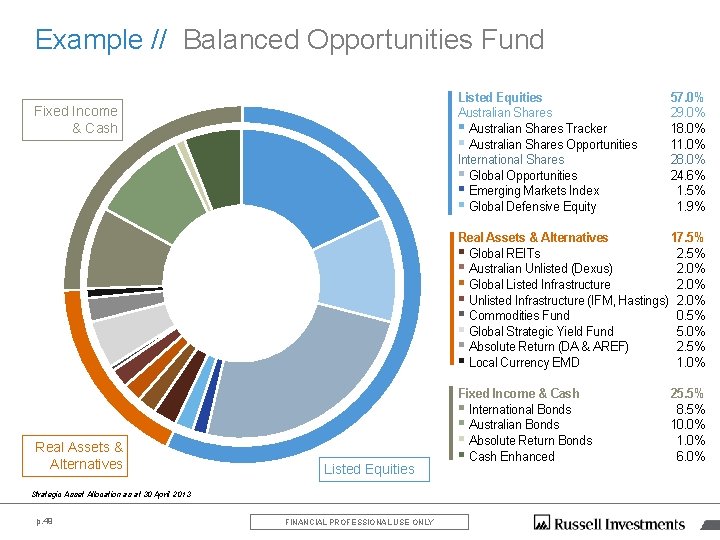
Example // Balanced Opportunities Fund Listed Equities Australian Shares § Australian Shares Tracker § Australian Shares Opportunities International Shares § Global Opportunities § Emerging Markets Index § Global Defensive Equity Fixed Income & Cash 57. 0% 29. 0% 18. 0% 11. 0% 28. 0% 24. 6% 1. 5% 1. 9% Real Assets & Alternatives 17. 5% § Global REITs 2. 5% § Australian Unlisted (Dexus) 2. 0% § Global Listed Infrastructure 2. 0% § Unlisted Infrastructure (IFM, Hastings) 2. 0% § Commodities Fund 0. 5% § Global Strategic Yield Fund 5. 0% § Absolute Return (DA & AREF) 2. 5% § Local Currency EMD 1. 0% Real Assets & Alternatives Listed Equities Strategic Asset Allocation as at 30 April 2013 p. 49 FINANCIAL PROFESSIONAL USE ONLY Fixed Income & Cash § International Bonds § Australian Bonds § Absolute Return Bonds § Cash Enhanced 25. 5% 8. 5% 10. 0% 1. 0% 6. 0%
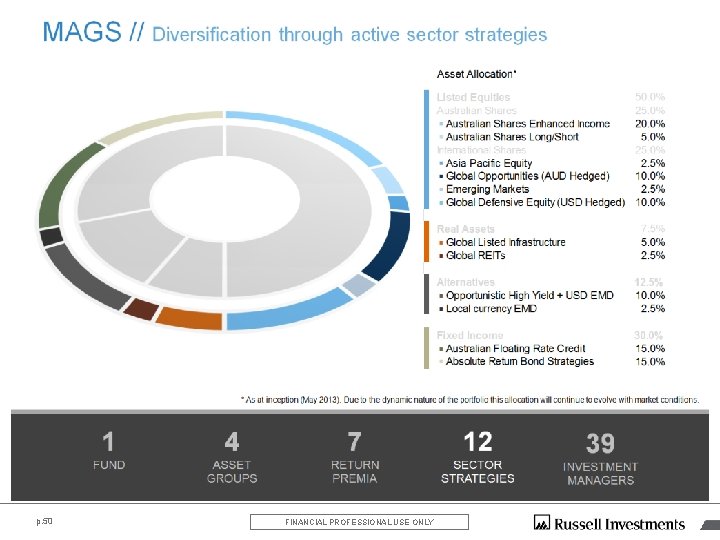
Portfolio Construction // From theory to reality p. 50 FINANCIAL PROFESSIONAL USE ONLY
Association of Provident Fund Russell Implementation Services - Passive Currency Overlay Daniel Birch JUNE 2013
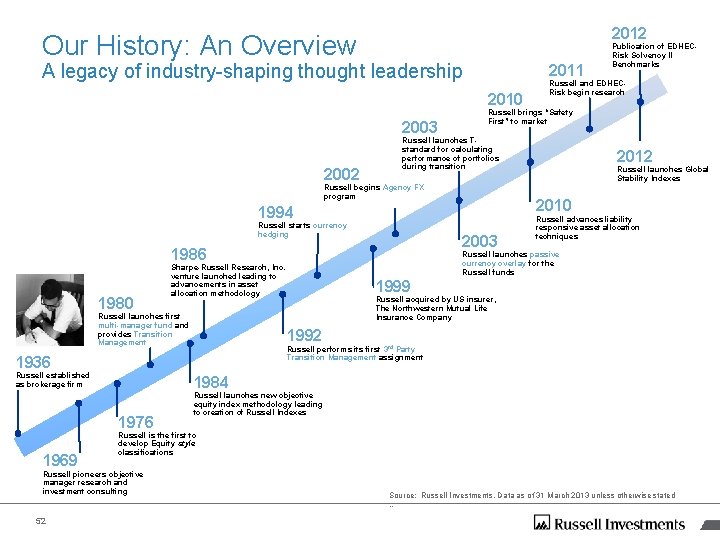
2012 Our History: An Overview A legacy of industry-shaping thought leadership 2011 2010 2003 2002 Russell brings “Safety First” to market Russell begins Agency FX program 2003 1986 Russell acquired by US insurer, The Northwestern Mutual Life Insurance Company Russell performs its first 3 rd Party Transition Management assignment Russell launches new objective equity index methodology leading to creation of Russell Indexes Russell is the first to develop Equity style classifications Russell pioneers objective manager research and investment consulting 52 1999 1984 1976 1969 Russell advances liability responsive asset allocation techniques 1992 1936 Russell established as brokerage firm Russell launches Global Stability Indexes Russell launches passive currency overlay for the Russell funds Sharpe-Russell Research, Inc. venture launched leading to advancements in asset allocation methodology Russell launches first multi-manager fund and provides Transition Management 2012 2010 1994 1980 Russell and EDHECRisk begin research Russell launches Tstandard for calculating performance of portfolios during transition Russell starts currency hedging Publication of EDHECRisk Solvency II Benchmarks Source: Russell Investments. Data as of 31 March 2013 unless otherwise stated. .
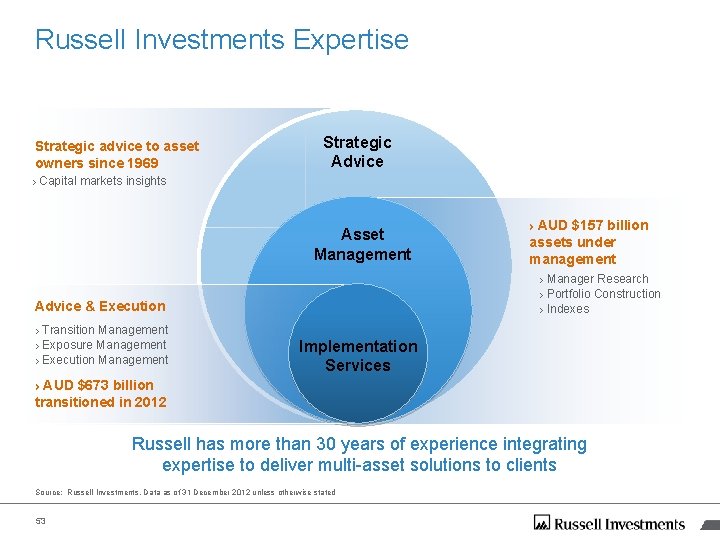
Russell Investments Expertise Strategic advice to asset owners since 1969 Strategic Advice › Capital markets insights Asset Management › Manager Research › Portfolio Construction › Indexes Advice & Execution › Transition Management › Exposure Management › Execution Management › AUD $157 billion assets under management Implementation Services › AUD $673 billion transitioned in 2012 Russell has more than 30 years of experience integrating expertise to deliver multi-asset solutions to clients Source: Russell Investments. Data as of 31 December 2012 unless otherwise stated. . 53
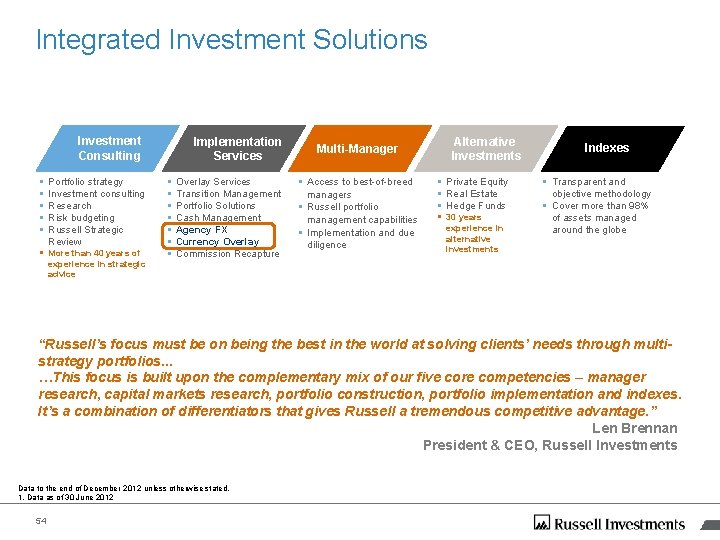
Integrated Investment Solutions Investment Consulting § § § Portfolio strategy Investment consulting Research Risk budgeting Russell Strategic Review § More than 40 years of experience in strategic advice Implementation Services § § § § Overlay Services Transition Management Portfolio Solutions Cash Management Agency FX Currency Overlay Commission Recapture Multi-Manager § Access to best-of-breed managers § Russell portfolio management capabilities § Implementation and due diligence Alternative Investments § Private Equity § Real Estate § Hedge Funds § 30 years experience in alternative investments Indexes § Transparent and objective methodology § Cover more than 98% of assets managed around the globe “Russell’s focus must be on being the best in the world at solving clients’ needs through multistrategy portfolios. . . …This focus is built upon the complementary mix of our five core competencies – manager research, capital markets research, portfolio construction, portfolio implementation and indexes. It’s a combination of differentiators that gives Russell a tremendous competitive advantage. ” Len Brennan President & CEO, Russell Investments Data to the end of December 2012 unless otherwise stated. 1. Data as of 30 June 2012 54 54
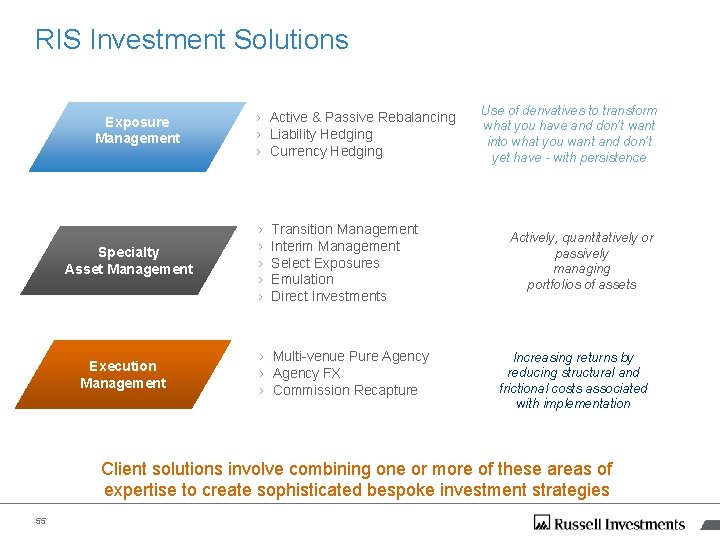
RIS Investment Solutions Exposure Management Specialty Asset Management Execution Management › Active & Passive Rebalancing › Liability Hedging › Currency Hedging › › › Transition Management Interim Management Select Exposures Emulation Direct Investments › Multi-venue Pure Agency › Agency FX › Commission Recapture Use of derivatives to transform what you have and don’t want into what you want and don’t yet have - with persistence Actively, quantitatively or passively managing portfolios of assets Increasing returns by reducing structural and frictional costs associated with implementation Client solutions involve combining one or more of these areas of expertise to create sophisticated bespoke investment strategies 55
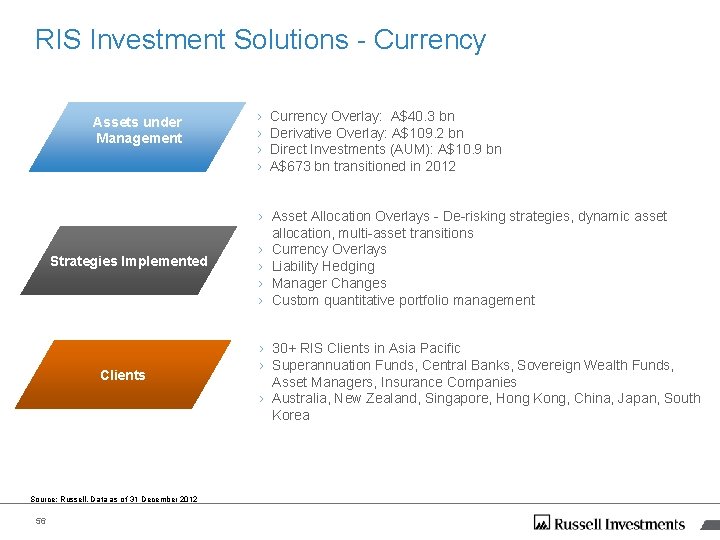
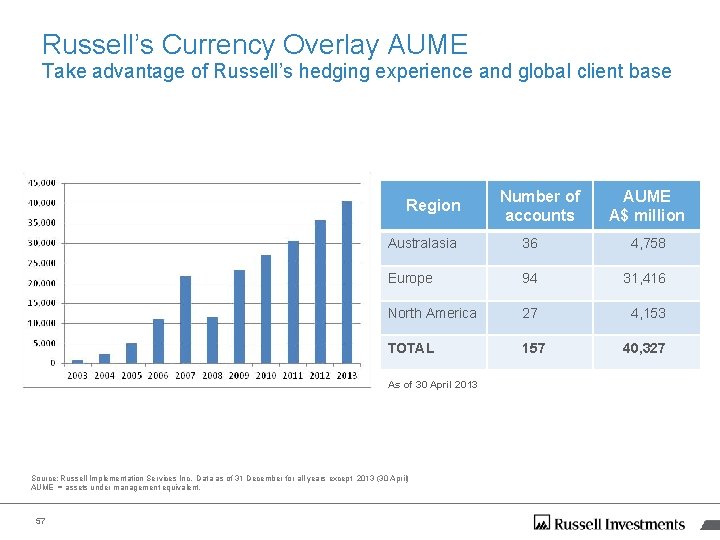
RIS Investment Solutions - Currency Assets under Management Strategies Implemented Clients Source: Russell. Data as of 31 December 2012 56 › › Currency Overlay: A$40. 3 bn Derivative Overlay: A$109. 2 bn Direct Investments (AUM): A$10. 9 bn A$673 bn transitioned in 2012 › Asset Allocation Overlays - De-risking strategies, dynamic asset allocation, multi-asset transitions › Currency Overlays › Liability Hedging › Manager Changes › Custom quantitative portfolio management › 30+ RIS Clients in Asia Pacific › Superannuation Funds, Central Banks, Sovereign Wealth Funds, Asset Managers, Insurance Companies › Australia, New Zealand, Singapore, Hong Kong, China, Japan, South Korea
Russell’s Currency Overlay AUME Take advantage of Russell’s hedging experience and global client base Region AUME A$ million Australasia 36 4, 758 Europe 94 31, 416 North America 27 4, 153 TOTAL 157 40, 327 As of 30 April 2013 Source: Russell Implementation Services Inc. Data as of 31 December for all years except 2013 (30 April) AUME = assets under management equivalent. 57 Number of accounts
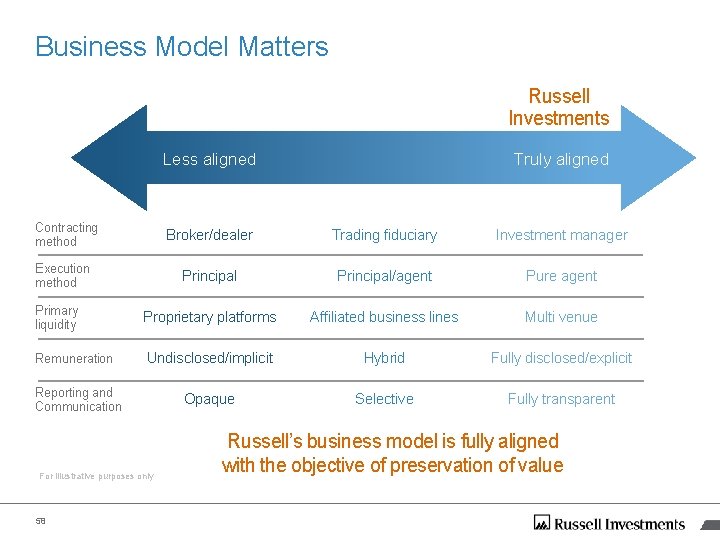
Business Model Matters Russell Investments Less aligned Contracting method Truly aligned Broker/dealer Trading fiduciary Investment manager Principal/agent Pure agent Primary liquidity Proprietary platforms Affiliated business lines Multi venue Remuneration Undisclosed/implicit Hybrid Fully disclosed/explicit Opaque Selective Fully transparent Execution method Reporting and Communication For illustrative purposes only 58 Russell’s business model is fully aligned with the objective of preservation of value
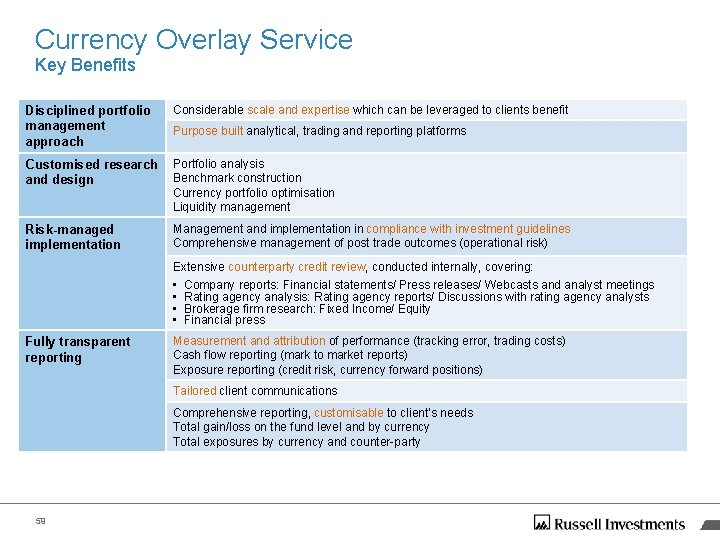
Currency Overlay Service Key Benefits Disciplined portfolio management approach Considerable scale and expertise which can be leveraged to clients benefit Customised research and design Portfolio analysis Benchmark construction Currency portfolio optimisation Liquidity management Risk-managed implementation Management and implementation in compliance with investment guidelines Comprehensive management of post trade outcomes (operational risk) Purpose built analytical, trading and reporting platforms Extensive counterparty credit review, conducted internally, covering: • • Fully transparent reporting Company reports: Financial statements/ Press releases/ Webcasts and analyst meetings Rating agency analysis: Rating agency reports/ Discussions with rating agency analysts Brokerage firm research: Fixed Income/ Equity Financial press Measurement and attribution of performance (tracking error, trading costs) Cash flow reporting (mark to market reports) Exposure reporting (credit risk, currency forward positions) Tailored client communications Comprehensive reporting, customisable to client’s needs Total gain/loss on the fund level and by currency Total exposures by currency and counter-party 59
Thank you “Russell, ” “Russell Investments, ” “Russell 1000, ” “Russell 2000, ” and “Russell 3000” are registered trademarks of the Frank Russell Company. www. russell. com/au