KRUK Group Presentation 3 Q 2016 Agenda Introduction

- Slides: 30
KRUK Group Presentation 3 Q 2016
Agenda Introduction Operating activities Market position Financial performance Strategy and summary Appendices 2
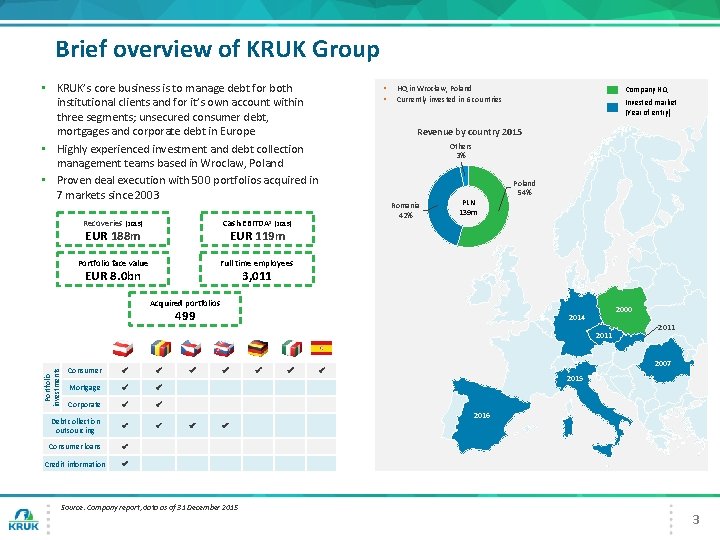
Brief overview of KRUK Group • KRUK’s core business is to manage debt for both institutional clients and for it’s own account within three segments; unsecured consumer debt, mortgages and corporate debt in Europe • Highly experienced investment and debt collection management teams based in Wroclaw, Poland • Proven deal execution with 500 portfolios acquired in 7 markets since 2003 Recoveries (2015) Cash EBITDA 1 (2015) Portfolio face value Full time employees EUR 188 m § § HQ in Wrocław, Poland Currently invested in 6 countries Company HQ Invested market (Year of entry) Revenue by country 2015 Others 3% Poland 54% Romania 42% PLN 139 m EUR 119 m EUR 8. 0 bn 3, 011 Acquired portfolios 499 2000 2014 2011 Mortgage Corporate Debt collection outsourcing Consumer loans Credit information Portfolio investments Consumer 2011 2007 2015 2016 Source: Company report, data as of 31 December 2015 3
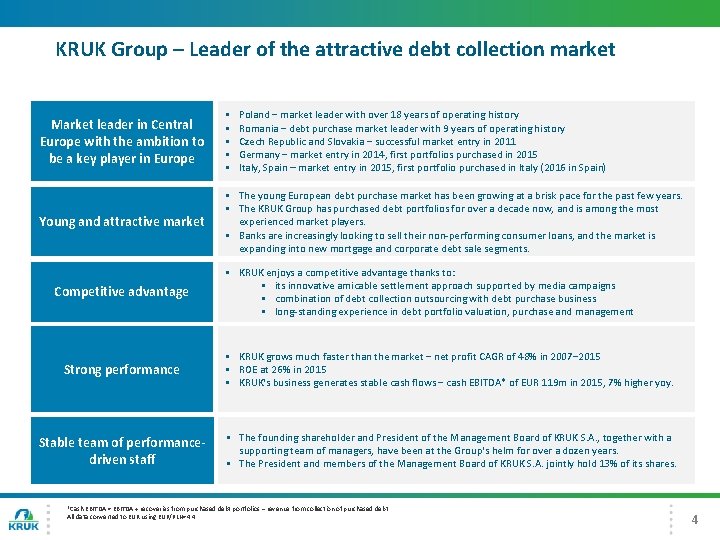
KRUK Group – Leader of the attractive debt collection market Poland − market leader with over 18 years of operating history Romania − debt purchase market leader with 9 years of operating history Czech Republic and Slovakia − successful market entry in 2011 Germany − market entry in 2014, first portfolios purchased in 2015 Italy, Spain – market entry in 2015, first portfolio purchased in Italy (2016 in Spain) Market leader in Central Europe with the ambition to be a key player in Europe § § § Young and attractive market § The young European debt purchase market has been growing at a brisk pace for the past few years. § The KRUK Group has purchased debt portfolios for over a decade now, and is among the most experienced market players. § Banks are increasingly looking to sell their non-performing consumer loans, and the market is expanding into new mortgage and corporate debt sale segments. Competitive advantage § KRUK enjoys a competitive advantage thanks to: § its innovative amicable settlement approach supported by media campaigns § combination of debt collection outsourcing with debt purchase business § long-standing experience in debt portfolio valuation, purchase and management Strong performance § KRUK grows much faster than the market − net profit CAGR of 48% in 2007− 2015 § ROE at 26% in 2015 § KRUK's business generates stable cash flows − cash EBITDA* of EUR 119 m in 2015, 7% higher yoy. Stable team of performancedriven staff § The founding shareholder and President of the Management Board of KRUK S. A. , together with a supporting team of managers, have been at the Group's helm for over a dozen years. § The President and members of the Management Board of KRUK S. A. jointly hold 13% of its shares. *Cash EBITDA = EBITDA + recoveries from purchased debt portfolios – revenue from collection of purchased debt All data converted to EUR using EUR/PLN=4. 4 4
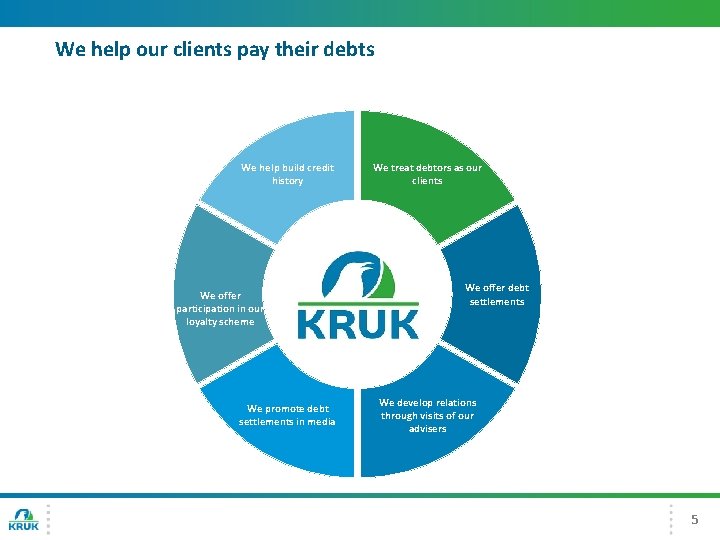
We help our clients pay their debts We help build credit history We offer participation in our loyalty scheme We promote debt settlements in media We treat debtors as our clients We offer debt settlements We develop relations through visits of our advisers 5
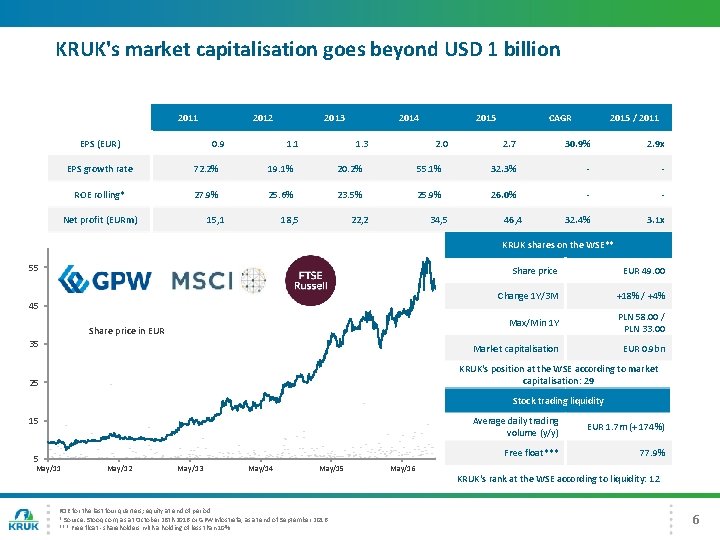
KRUK's market capitalisation goes beyond USD 1 billion 2011 EPS (EUR) 2012 0. 9 2013 1. 1 2014 1. 3 2015 2. 0 2015 / 2011 CAGR 2. 7 30. 9% 2. 9 x EPS growth rate 72. 2% 19. 1% 20. 2% 55. 1% 32. 3% - - ROE rolling* 27. 9% 25. 6% 23. 5% 25. 9% 26. 0% - - 32. 4% 3. 1 x Net profit (EURm) 15, 1 18, 5 22, 2 34, 5 900000 55 800000 700000 45 600000 Share price in EUR 35 500000 400000 25 46, 4 KRUK shares on the WSE** Share price EUR 49. 00 Change 1 Y/3 M +18% / +4% Max/Min 1 Y PLN 58. 00 / PLN 33. 00 Market capitalisation EUR 0. 9 bn KRUK's position at the WSE according to market capitalisation: 29 300000 Stock trading liquidity 200000 15 100000 5 0 May/11 May/12 May/13 May/14 May/15 ROE for the last four quarters; equity at end of period. * Source: Stooq. com, as at October 28 th 2016 or GPWInfostrefa, as at end of September 2016 *** Free float - shareholders with a holding of less than 10% May/16 Average daily trading volume (y/y) EUR 1. 7 m (+ 174%) Free float*** 77. 9% KRUK's rank at the WSE according to liquidity: 12 6
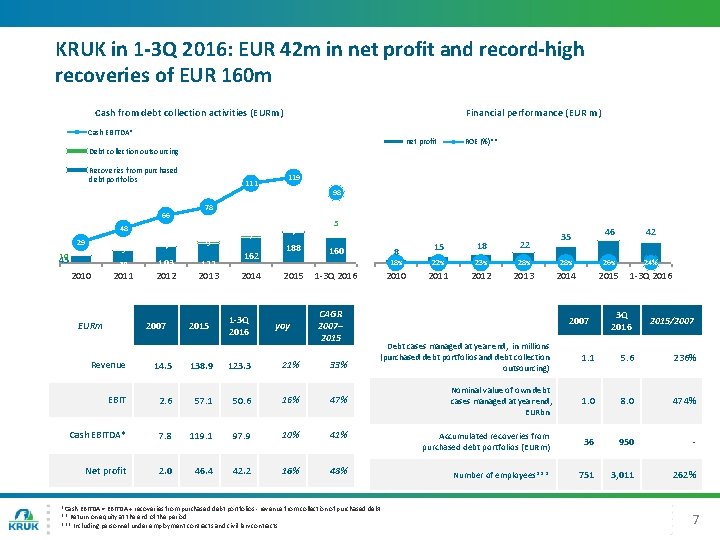
KRUK in 1 -3 Q 2016: EUR 42 m in net profit and record-high recoveries of EUR 160 m Cash from debt collection activities (EURm) Financial performance (EUR m) 200 Cash EBITDA* 5000% 4500% 180 net profit Debt collection outsourcing ROE (%)** 4000% 160 3500% 140 Recoveries from purchased debt portfolios 66 111 10 45 2010 9 78 103 2012 122 2013 2011 EURm 2007 2015 3000% 120 98 78 48 29 119 2500% 100 2000% 80 7 162 7 188 5 1500% 60 40 160 0 2014 1 -3 Q 2016 2015 yoy 1 -3 Q 2016 CAGR 2007– 2015 Revenue 14. 5 138. 9 123. 3 21% 33% EBIT 2. 6 57. 1 50. 6 16% 47% Cash EBITDA* 7. 8 119. 1 97. 9 10% 41% Net profit 2. 0 46. 4 42. 2 16% 48% 42 15 18 18% 22% 23% 28% 26% 24% 2010 2011 2012 2013 2014 2015 1 -3 Q 2016 8 20 46 35 22 1000% 500% 2007 0% 3 Q 2016 2015/2007 Debt cases managed at year end, in millions (purchased debt portfolios and debt collection outsourcing) 1. 1 5. 6 236% Nominal value of own debt cases managed at year end, EURbn 1. 0 8. 0 474% Accumulated recoveries from purchased debt portfolios (EURm) 36 950 - Number of employees*** 751 3, 011 262% *Cash EBITDA = EBITDA + recoveries from purchased debt portfolios - revenue from collection of purchased debt ** Return on equity at the end of the period *** Including personnel under employment contracts and civil law contracts 7
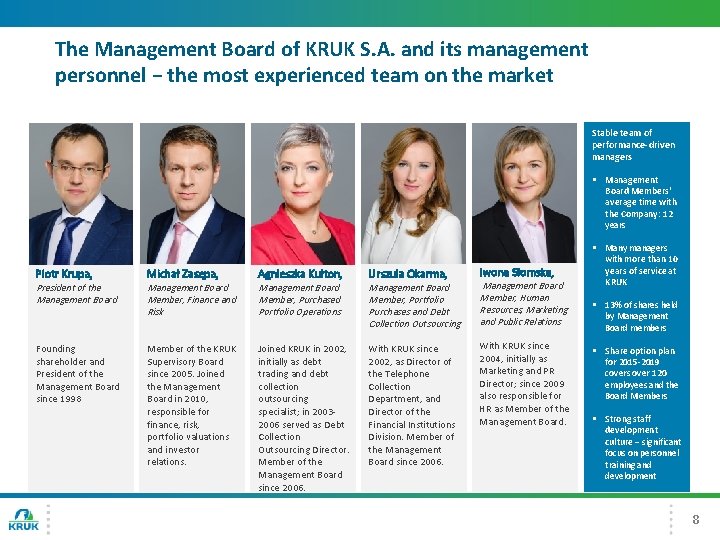
The Management Board of KRUK S. A. and its management personnel − the most experienced team on the market Stable team of performance-driven managers § Management Board Members' average time with the Company: 12 years § Many managers Piotr Krupa, President of the Management Board Founding shareholder and President of the Management Board since 1998 Michał Zasępa, Management Board Member, Finance and Risk Member of the KRUK Supervisory Board since 2005. Joined the Management Board in 2010, responsible for finance, risk, portfolio valuations and investor relations. Agnieszka Kułton, Management Board Member, Purchased Portfolio Operations Joined KRUK in 2002, initially as debt trading and debt collection outsourcing specialist; in 20032006 served as Debt Collection Outsourcing Director. Member of the Management Board since 2006. Urszula Okarma, Iwona Słomska, Management Board Member, Portfolio Purchases and Debt Collection Outsourcing Management Board Member, Human Resources, Marketing and Public Relations With KRUK since 2002, as Director of the Telephone Collection Department, and Director of the Financial Institutions Division. Member of the Management Board since 2006. With KRUK since 2004, initially as Marketing and PR Director; since 2009 also responsible for HR as Member of the Management Board. with more than 10 years of service at KRUK § 13% of shares held by Management Board members § Share option plan for 2015 -2019 covers over 120 employees and the Board Members § Strong staff development culture − significant focus on personnel training and development 8
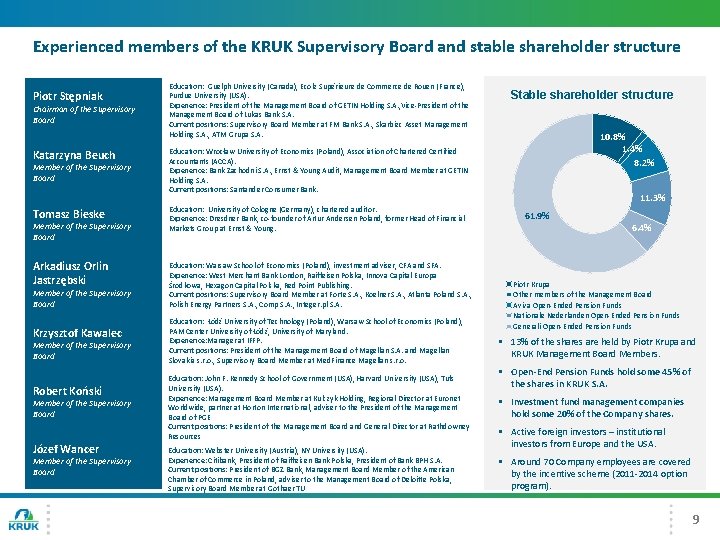
Experienced members of the KRUK Supervisory Board and stable shareholder structure Piotr Stępniak Chairman of the Supervisory Board Education: Guelph University (Canada), Ecole Supérieure de Commerce de Rouen (France), Purdue University (USA). Experience: President of the Management Board of GETIN Holding S. A. , Vice-President of the Management Board of Lukas Bank S. A. Current positions: Supervisory Board Member at FM Bank S. A. , Skarbiec Asset Management Holding S. A. , ATM Grupa S. A. Katarzyna Beuch Education: Wrocław University of Economics (Poland), Association of Chartered Certified Accountants (ACCA). Experience: Bank Zachodni S. A. , Ernst & Young Audit, Management Board Member at GETIN Holding S. A. Current positions: Santander Consumer Bank. Tomasz Bieske Education: University of Cologne (Germany), chartered auditor. Experience: Dresdner Bank, co-founder of Artur Andersen Poland, former Head of Financial Markets Group at Ernst & Young. Member of the Supervisory Board Arkadiusz Orlin Jastrzębski Member of the Supervisory Board Krzysztof Kawalec Member of the Supervisory Board Robert Koński Member of the Supervisory Board Józef Wancer Member of the Supervisory Board Education: Warsaw School of Economics (Poland), investment adviser, CFA and SFA. Experience: West Merchant Bank London, Raiffeisen Polska, Innova Capital Europa Środkowa, Hexagon Capital Polska, Red Point Publishing. Current positions: Supervisory Board Member at Forte S. A. , Koelner S. A. , Atlanta Poland S. A. , Polish Energy Partners S. A. , Comp S. A. , Integer. pl S. A. Education: Łódź University of Technology (Poland), Warsaw School of Economics (Poland), PAM Center University of Łódź, University of Maryland. Experience: Manager at IFFP. Current positions: President of the Management Board of Magellan S. A. and Magellan Slovakia s. r. o. , Supervisory Board Member at Med. Finance Magellan s. r. o. Education: John F. Kennedy School of Government (USA), Harvard University (USA), Tufs University (USA). Experience: Management Board Member at Kulczyk Holding, Regional Director at Euronet Worldwide, partner at Horton International, adviser to the President of the Management Board of PGE Current positions: President of the Management Board and General Director at Rathdowney Resources Education: Webster University (Austria), NY University (USA). Experience: Citibank, President of Raiffeisen Bank Polska, President of Bank BPH S. A. Current positions: President of BGŻ Bank, Management Board Member of the American Chamber of Commerce in Poland, adviser to the Management Board of Deloitte Polska, Supervisory Board Member at Gothaer TU Stable shareholder structure 10. 8% 1. 4% 8. 2% 11. 3% 61. 9% 6. 4% Piotr Krupa Other members of the Management Board Aviva Open-Ended Pension Funds Nationale Nederlanden Open-Ended Pension Funds Generali Open-Ended Pension Funds § 13% of the shares are held by Piotr Krupa and KRUK Management Board Members. § Open-End Pension Funds hold some 45% of the shares in KRUK S. A. § Investment fund management companies hold some 20% of the Company shares. § Active foreign investors – institutional investors from Europe and the USA. § Around 70 Company employees are covered by the incentive scheme (2011 -2014 option program). 9
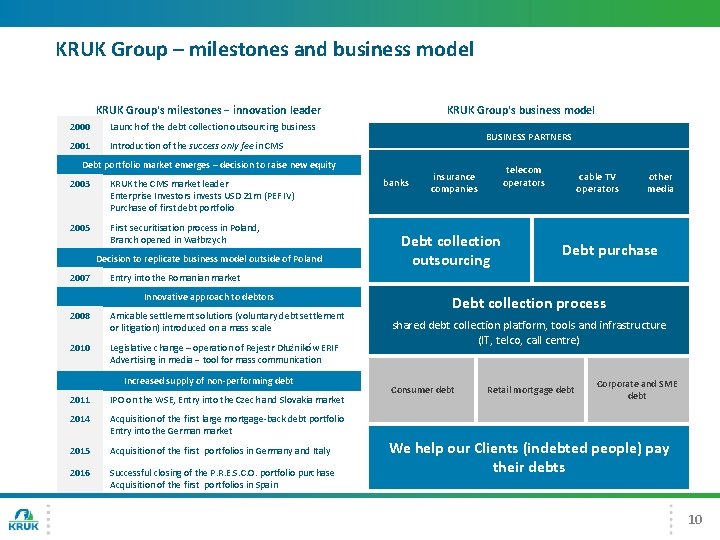
KRUK Group – milestones and business model KRUK Group's milestones − innovation leader 2000 Launch of the debt collection outsourcing business 2001 Introduction of the success only fee in CMS BUSINESS PARTNERS Debt portfolio market emerges – decision to raise new equity 2003 KRUK the CMS market leader Enterprise Investors invests USD 21 m (PEF IV) Purchase of first debt portfolio 2005 First securitisation process in Poland, Branch opened in Wałbrzych Decision to replicate business model outside of Poland 2007 banks telecom operators insurance companies Debt collection outsourcing cable TV operators other media Debt purchase Entry into the Romanian market Innovative approach to debtors 2008 Amicable settlement solutions (voluntary debt settlement or litigation) introduced on a mass scale 2010 Legislative change – operation of Rejestr Dłużników ERIF Advertising in media − tool for mass communication Increased supply of non-performing debt 2011 IPO on the WSE, Entry into the Czech and Slovakia market 2014 Acquisition of the first large mortgage-back debt portfolio Entry into the German market 2015 Acquisition of the first portfolios in Germany and Italy 2016 Successful closing of the P. R. E. S. C. O. portfolio purchase Acquisition of the first portfolios in Spain Debt collection process shared debt collection platform, tools and infrastructure (IT, telco, call centre) Consumer debt Retail mortgage debt Corporate and SME debt We help our Clients (indebted people) pay their debts 10
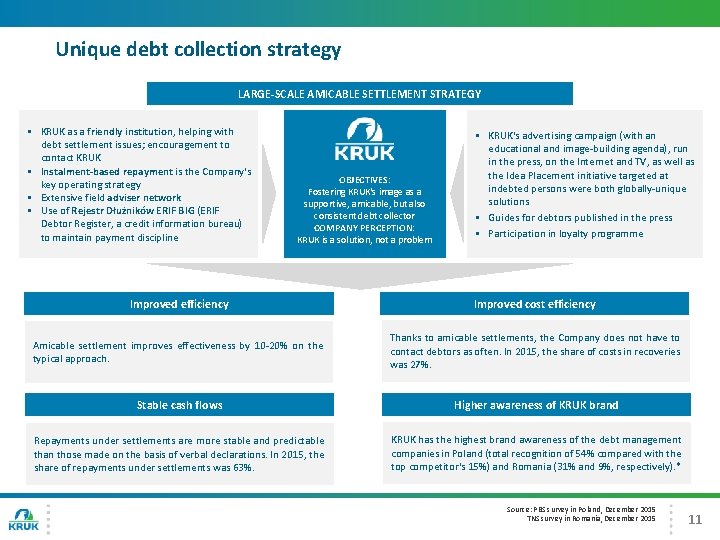
Unique debt collection strategy LARGE-SCALE AMICABLE SETTLEMENT STRATEGY § KRUK as a friendly institution, helping with debt settlement issues; encouragement to contact KRUK § Instalment-based repayment is the Company's key operating strategy § Extensive field adviser network § Use of Rejestr Dłużników ERIF BIG (ERIF Debtor Register, a credit information bureau) to maintain payment discipline OBJECTIVES: Fostering KRUK's image as a supportive, amicable, but also consistent debt collector COMPANY PERCEPTION: KRUK is a solution, not a problem § KRUK's advertising campaign (with an educational and image-building agenda), run in the press, on the Internet and TV, as well as the Idea Placement initiative targeted at indebted persons were both globally-unique solutions § Guides for debtors published in the press § Participation in loyalty programme Improved efficiency Improved cost efficiency Amicable settlement improves effectiveness by 10 -20% on the typical approach. Thanks to amicable settlements, the Company does not have to contact debtors as often. In 2015, the share of costs in recoveries was 27%. Stable cash flows Higher awareness of KRUK brand Repayments under settlements are more stable and predictable than those made on the basis of verbal declarations. In 2015, the share of repayments under settlements was 63%. KRUK has the highest brand awareness of the debt management companies in Poland (total recognition of 54% compared with the top competitor's 15%) and Romania (31% and 9%, respectively). * Source: PBS survey in Poland, December 2015 TNS survey in Romania, December 2015 11
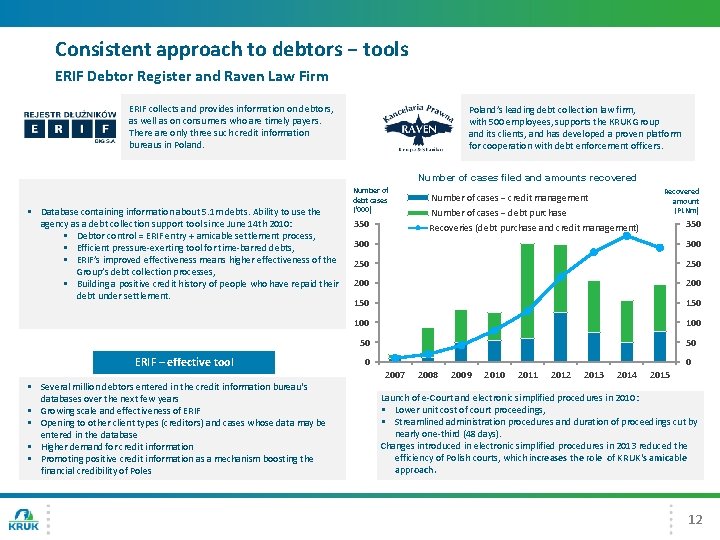
Consistent approach to debtors − tools ERIF Debtor Register and Raven Law Firm ERIF collects and provides information on debtors, as well as on consumers who are timely payers. There are only three such credit information bureaus in Poland’s leading debt collection law firm, with 500 employees, supports the KRUK Group and its clients, and has developed a proven platform for cooperation with debt enforcement officers. Number of cases filed and amounts recovered § Database containing information about 5. 1 m debts. Ability to use the agency as a debt collection support tool since June 14 th 2010: § Debtor control = ERIF entry + amicable settlement process, § Efficient pressure-exerting tool for time-barred debts, § ERIF’s improved effectiveness means higher effectiveness of the Group’s debt collection processes, § Building a positive credit history of people who have repaid their debt under settlement. ERIF – effective tool § Several million debtors entered in the credit information bureau's databases over the next few years § Growing scale and effectiveness of ERIF § Opening to other client types (creditors) and cases whose data may be entered in the database § Higher demand for credit information § Promoting positive credit information as a mechanism boosting the financial credibility of Poles Number of debt cases ('000) 350 Recovered amount (PLNm) Number of cases − credit management Number of cases − debt purchase 350 Recoveries (debt purchase and credit management) 300 250 200 150 100 50 50 0 0 2007 2008 2009 2010 2011 2012 2013 2014 2015 Launch of e-Court and electronic simplified procedures in 2010: § Lower unit cost of court proceedings, § Streamlined administration procedures and duration of proceedings cut by nearly one-third (48 days). Changes introduced in electronic simplified procedures in 2013 reduced the efficiency of Polish courts, which increases the role of KRUK's amicable approach. 12
Agenda Introduction Operating activities Market position Financial performance Strategy and summary Appendices 13
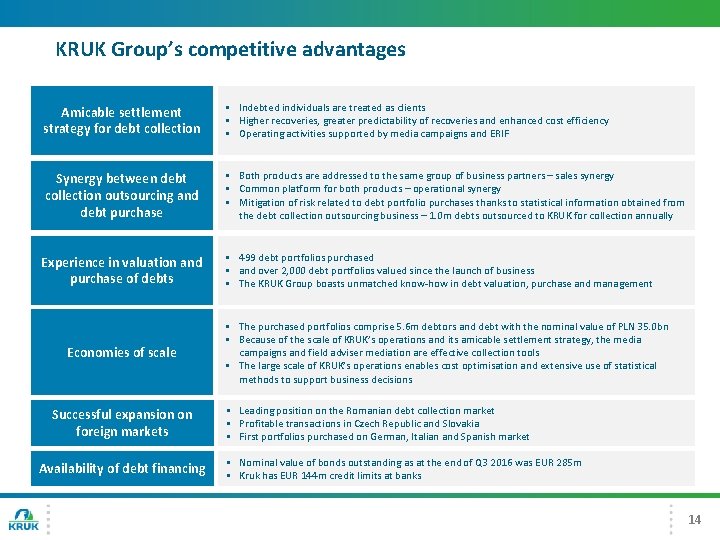
KRUK Group’s competitive advantages Amicable settlement strategy for debt collection § Indebted individuals are treated as clients § Higher recoveries, greater predictability of recoveries and enhanced cost efficiency § Operating activities supported by media campaigns and ERIF Synergy between debt collection outsourcing and debt purchase § Both products are addressed to the same group of business partners – sales synergy § Common platform for both products – operational synergy § Mitigation of risk related to debt portfolio purchases thanks to statistical information obtained from the debt collection outsourcing business – 1. 0 m debts outsourced to KRUK for collection annually Experience in valuation and purchase of debts Economies of scale Successful expansion on foreign markets Availability of debt financing § 499 debt portfolios purchased § and over 2, 000 debt portfolios valued since the launch of business § The KRUK Group boasts unmatched know-how in debt valuation, purchase and management § The purchased portfolios comprise 5. 6 m debtors and debt with the nominal value of PLN 35. 0 bn § Because of the scale of KRUK’s operations and its amicable settlement strategy, the media campaigns and field adviser mediation are effective collection tools § The large scale of KRUK’s operations enables cost optimisation and extensive use of statistical methods to support business decisions § Leading position on the Romanian debt collection market § Profitable transactions in Czech Republic and Slovakia § First portfolios purchased on German, Italian and Spanish market § Nominal value of bonds outstanding as at the end of Q 3 2016 was EUR 285 m § Kruk has EUR 144 m credit limits at banks 14
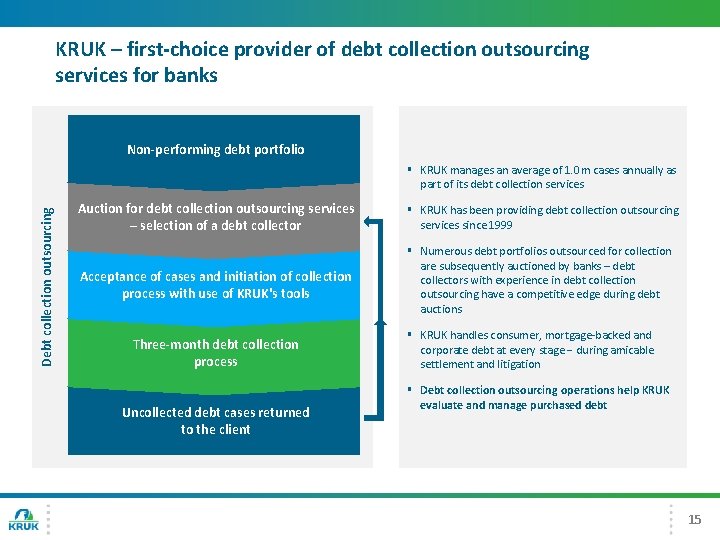
KRUK – first-choice provider of debt collection outsourcing services for banks Non-performing debt portfolio Debt collection outsourcing § KRUK manages an average of 1. 0 m cases annually as part of its debt collection services Auction for debt collection outsourcing services – selection of a debt collector § KRUK has been providing debt collection outsourcing services since 1999 Acceptance of cases and initiation of collection process with use of KRUK's tools § Numerous debt portfolios outsourced for collection are subsequently auctioned by banks – debt collectors with experience in debt collection outsourcing have a competitive edge during debt auctions Three-month debt collection process Uncollected debt cases returned to the client § KRUK handles consumer, mortgage-backed and corporate debt at every stage − during amicable settlement and litigation § Debt collection outsourcing operations help KRUK evaluate and manage purchased debt 15
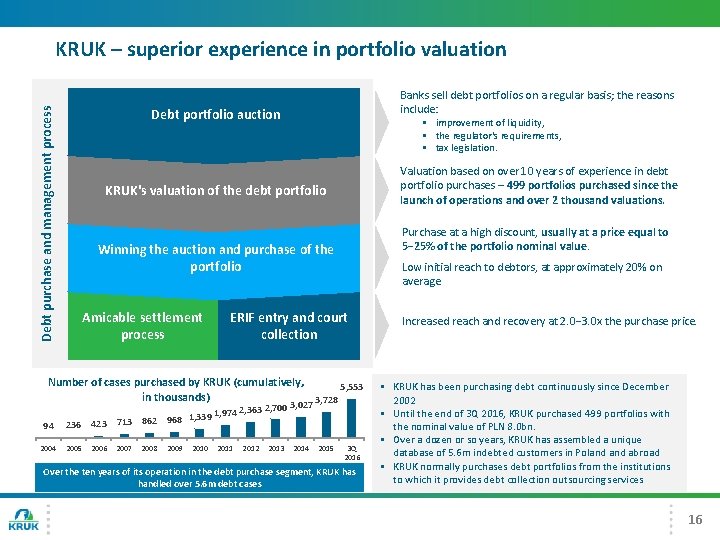
KRUK – superior experience in portfolio valuation Banks sell debt portfolios on a regular basis; the reasons include: Debt purchase and management process Debt portfolio auction § improvement of liquidity, § the regulator's requirements, § tax legislation. Valuation based on over 10 years of experience in debt portfolio purchases – 499 portfolios purchased since the launch of operations and over 2 thousand valuations. KRUK's valuation of the debt portfolio Purchase at a high discount, usually at a price equal to 5− 25% of the portfolio nominal value. Winning the auction and purchase of the portfolio Amicable settlement process Low initial reach to debtors, at approximately 20% on average. ERIF entry and court collection Number of cases purchased by KRUK (cumulatively, 5, 553 in thousands) 3, 728 3, 027 94 236 423 713 862 2004 2005 2006 2007 2008 1, 974 968 1, 339 2009 2010 2011 2, 363 2, 700 2012 2013 2014 2015 3 Q 2016 Over the ten years of its operation in the debt purchase segment, KRUK has handled over 5. 6 m debt cases Increased reach and recovery at 2. 0− 3. 0 x the purchase price. § KRUK has been purchasing debt continuously since December 2002 § Until the end of 3 Q 2016, KRUK purchased 499 portfolios with the nominal value of PLN 8. 0 bn. § Over a dozen or so years, KRUK has assembled a unique database of 5. 6 m indebted customers in Poland abroad § KRUK normally purchases debt portfolios from the institutions to which it provides debt collection outsourcing services 16
Agenda Introduction Operating activities Market position Financial performance Strategy and summary Appendices 17
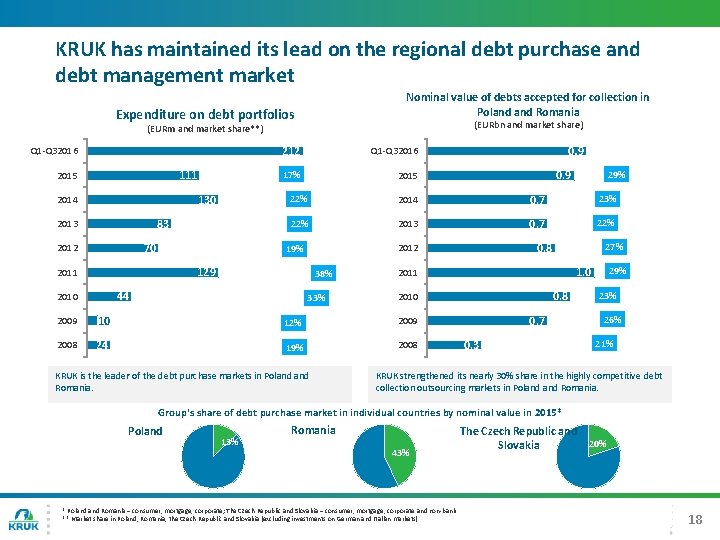
KRUK has maintained its lead on the regional debt purchase and debt management market Nominal value of debts accepted for collection in Poland Romania Expenditure on debt portfolios (EURbn and market share) (EURm and market share**) Q 1 -Q 32016 111 2015 130 2014 83 2013 70 2012 212 Q 1 -Q 32016 17% 2015 29% 2014 0. 7 23% 22% 2013 0. 7 22% 38% 44 0. 8 2012 129 2010 0. 9 22% 19% 2011 0, 9 33% 1. 0 2011 0. 8 2010 2009 10 12% 2009 2008 24 19% 2008 KRUK is the leader of the debt purchase markets in Poland Romania. 27% 0. 7 0. 3 29% 23% 26% 21% KRUK strengthened its nearly 30% share in the highly competitive debt collection outsourcing markets in Poland Romania. Group's share of debt purchase market in individual countries by nominal value in 2015* Poland 13% Romania 43% * Poland Romania – consumer, mortgage, corporate; The Czech Republic and Slovakia – consumer, mortgage, corporate and non-bank. ** Market share in Poland, Romania, the Czech Republic and Slovakia (excluding investments on German and Italian markets) The Czech Republic and Slovakia 20% 18
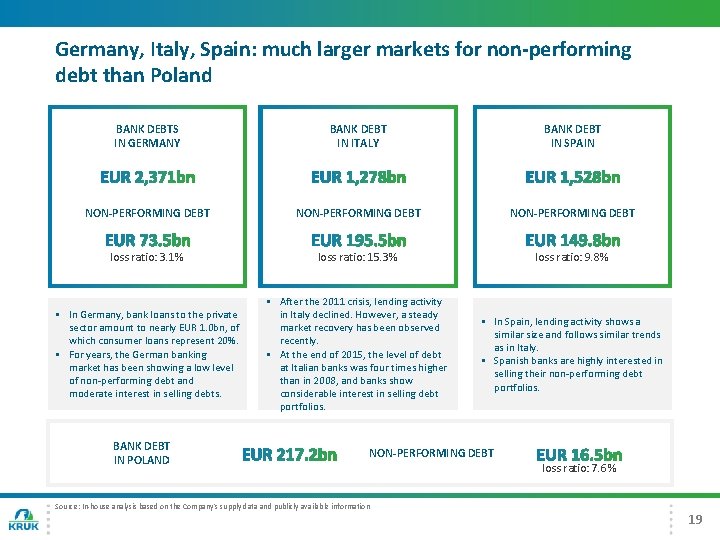
Germany, Italy, Spain: much larger markets for non-performing debt than Poland BANK DEBTS IN GERMANY BANK DEBT IN ITALY BANK DEBT IN SPAIN NON-PERFORMING DEBT loss ratio: 3. 1% loss ratio: 15. 3% loss ratio: 9. 8% § In Germany, bank loans to the private sector amount to nearly EUR 1. 0 bn, of which consumer loans represent 20%. § For years, the German banking market has been showing a low level of non-performing debt and moderate interest in selling debts. § After the 2011 crisis, lending activity in Italy declined. However, a steady market recovery has been observed recently. § At the end of 2015, the level of debt at Italian banks was four times higher than in 2008, and banks show considerable interest in selling debt portfolios. § In Spain, lending activity shows a similar size and follows similar trends as in Italy. § Spanish banks are highly interested in selling their non-performing debt portfolios. BANK DEBT IN POLAND NON-PERFORMING DEBT Source: In-house analysis based on the Company's supply data and publicly available information loss ratio: 7. 6% 19
Agenda Introduction Operating activities Market position Financial performance Strategy and summary Appendices 20
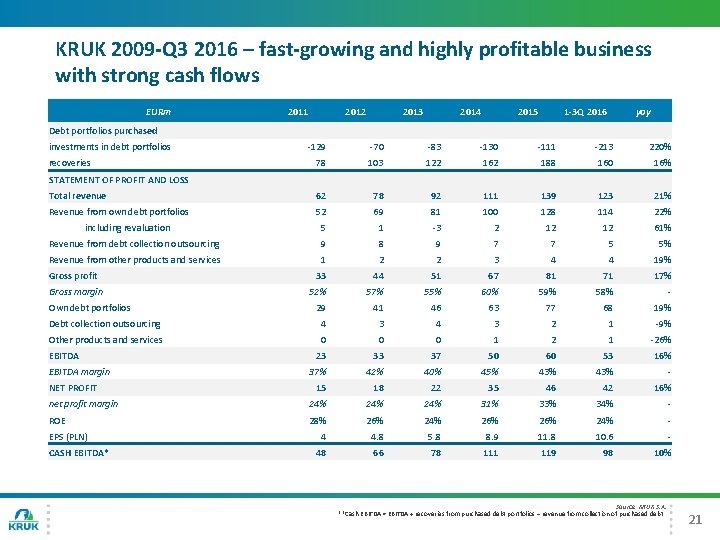
KRUK 2009 -Q 3 2016 – fast-growing and highly profitable business with strong cash flows EURm 2011 2012 2013 2014 2015 1 -3 Q 2016 yoy Debt portfolios purchased investments in debt portfolios -129 -70 -83 -130 -111 -213 220% 78 103 122 162 188 160 16% Total revenue 62 78 92 111 139 123 21% Revenue from own debt portfolios 52 69 81 100 128 114 22% 5 1 -3 2 12 12 61% Revenue from debt collection outsourcing 9 8 9 7 7 5 5% Revenue from other products and services 1 2 2 3 4 4 19% 33 44 51 67 81 71 17% 52% 57% 55% 60% 59% 58% - 29 41 46 63 77 68 19% Debt collection outsourcing 4 3 2 1 -9% Other products and services 0 0 0 1 2 1 -26% 23 33 37 50 60 53 16% 37% 42% 40% 45% 43% - 15 18 22 35 46 42 16% net profit margin 24% 24% 31% 33% 34% - ROE 28% 26% 24% - 4 4. 8 5. 8 8. 9 11. 8 10. 6 - 48 66 78 111 119 98 10% recoveries STATEMENT OF PROFIT AND LOSS including revaluation Gross profit Gross margin Own debt portfolios EBITDA margin NET PROFIT EPS (PLN) CASH EBITDA* Source: KRUK S. A. **Cash EBITDA = EBITDA + recoveries from purchased debt portfolios – revenue from collection of purchased debt. 21
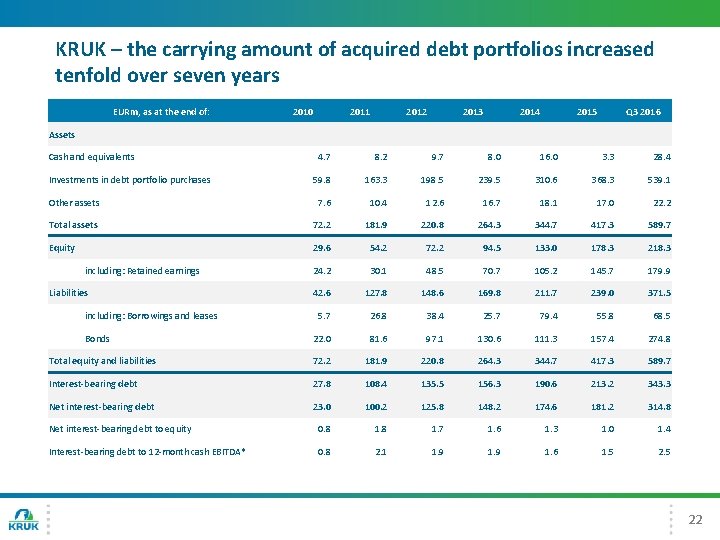
KRUK – the carrying amount of acquired debt portfolios increased tenfold over seven years EURm, as at the end of: 2010 2011 2012 2013 2014 2015 Q 3 2016 Assets Cash and equivalents 4. 7 8. 2 9. 7 8. 0 16. 0 3. 3 28. 4 59. 8 163. 3 198. 5 239. 5 310. 6 368. 3 539. 1 Other assets 7. 6 10. 4 12. 6 16. 7 18. 1 17. 0 22. 2 Total assets 72. 2 181. 9 220. 8 264. 3 344. 7 417. 3 589. 7 Equity 29. 6 54. 2 72. 2 94. 5 133. 0 178. 3 218. 3 24. 2 30. 1 48. 5 70. 7 105. 2 145. 7 179. 9 42. 6 127. 8 148. 6 169. 8 211. 7 239. 0 371. 5 5. 7 26. 8 38. 4 25. 7 79. 4 55. 8 68. 5 22. 0 81. 6 97. 1 130. 6 111. 3 157. 4 274. 8 Total equity and liabilities 72. 2 181. 9 220. 8 264. 3 344. 7 417. 3 589. 7 Interest-bearing debt 27. 8 108. 4 135. 5 156. 3 190. 6 213. 2 343. 3 Net interest-bearing debt 23. 0 100. 2 125. 8 148. 2 174. 6 181. 2 314. 8 Net interest-bearing debt to equity 0. 8 1. 7 1. 6 1. 3 1. 0 1. 4 Interest-bearing debt to 12 -month cash EBITDA* 0. 8 2. 1 1. 9 1. 6 1. 5 2. 5 Investments in debt portfolio purchases including: Retained earnings Liabilities including: Borrowings and leases Bonds 22
Agenda Introduction Operating activities Market position Financial performance Strategy and summary Appendices 23
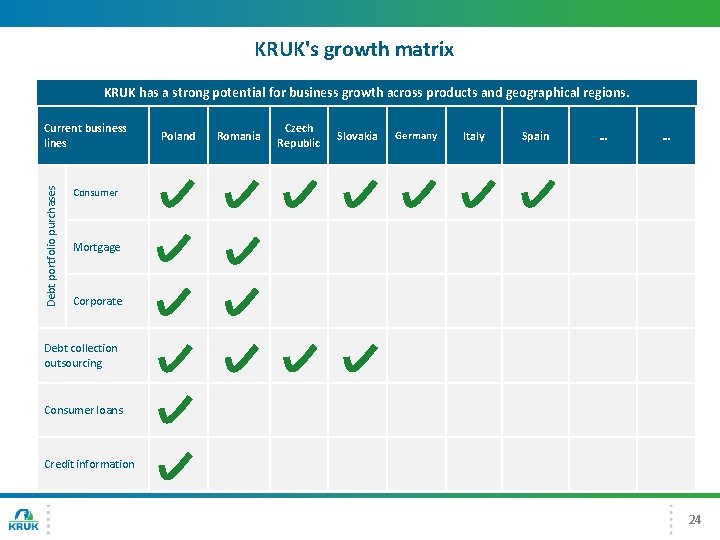
KRUK's growth matrix KRUK has a strong potential for business growth across products and geographical regions. Debt portfolio purchases Current business lines Poland Romania Czech Republic Slovakia Germany Italy Spain … … Consumer Mortgage Corporate Debt collection outsourcing Consumer loans Credit information 24
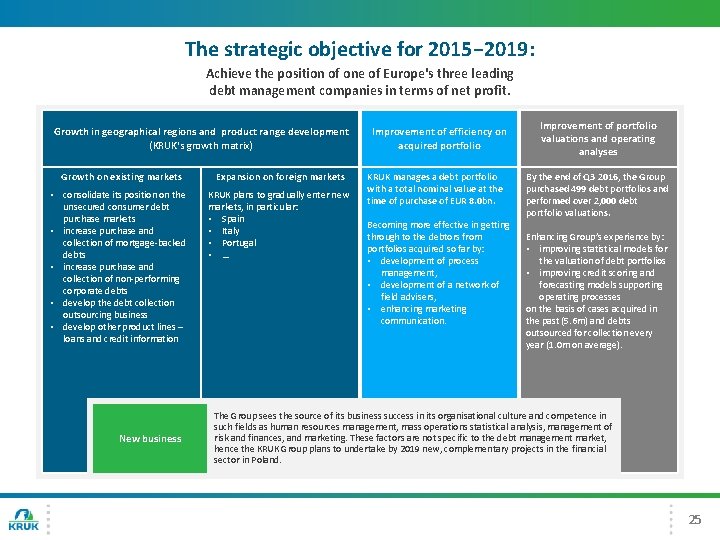
The strategic objective for 2015− 2019: Achieve the position of one of Europe's three leading debt management companies in terms of net profit. Growth in geographical regions and product range development (KRUK's growth matrix) Growth on existing markets § § § consolidate its position on the unsecured consumer debt purchase markets increase purchase and collection of mortgage-backed debts increase purchase and collection of non-performing corporate debts develop the debt collection outsourcing business develop other product lines – loans and credit information New business Expansion on foreign markets KRUK plans to gradually enter new markets, in particular: • Spain • Italy • Portugal • … Improvement of efficiency on acquired portfolio KRUK manages a debt portfolio with a total nominal value at the time of purchase of EUR 8. 0 bn. Becoming more effective in getting through to the debtors from portfolios acquired so far by: • development of process management, • development of a network of field advisers, • enhancing marketing communication. Improvement of portfolio valuations and operating analyses By the end of Q 3 2016, the Group purchased 499 debt portfolios and performed over 2, 000 debt portfolio valuations. Enhancing Group’s experience by: • improving statistical models for the valuation of debt portfolios • improving credit scoring and forecasting models supporting operating processes on the basis of cases acquired in the past (5. 6 m) and debts outsourced for collection every year (1. 0 m on average). The Group sees the source of its business success in its organisational culture and competence in such fields as human resources management, mass operations statistical analysis, management of risk and finances, and marketing. These factors are not specific to the debt management market, hence the KRUK Group plans to undertake by 2019 new, complementary projects in the financial sector in Poland. 25
Agenda Introduction Operating activities Market position Financial performance Strategy and summary Appendices 26
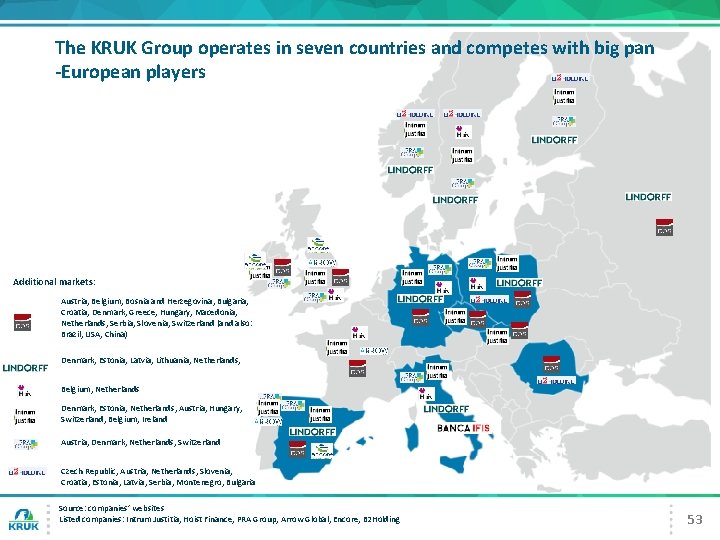
The KRUK Group operates in seven countries and competes with big pan -European players Additional markets: Austria, Belgium, Bosnia and Herzegovina, Bulgaria, Croatia, Denmark, Greece, Hungary, Macedonia, Netherlands, Serbia, Slovenia, Switzerland (and also: Brazil, USA, China) Denmark, Estonia, Latvia, Lithuania, Netherlands, Belgium, Netherlands Denmark, Estonia, Netherlands, Austria, Hungary, Switzerland, Belgium, Ireland Austria, Denmark, Netherlands, Switzerland Czech Republic, Austria, Netherlands, Slovenia, Croatia, Estonia, Latvia, Serbia, Montenegro, Bulgaria Source: companies’ websites Listed companies: Intrum Justitia, Hoist Finance, PRA Group, Arrow Global, Encore, B 2 Holding 53
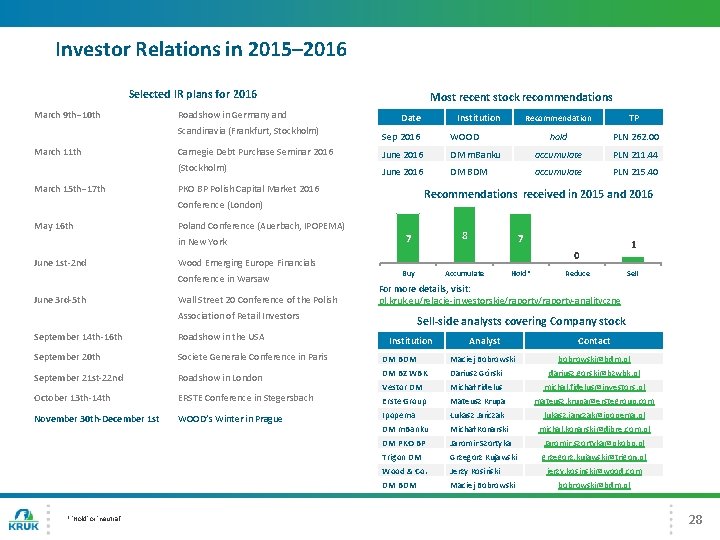
Investor Relations in 2015– 2016 Selected IR plans for 2016 March 9 th− 10 th Roadshow in Germany and Scandinavia (Frankfurt, Stockholm) March 11 th March 15 th− 17 th Most recent stock recommendations Date hold PLN 262. 00 WOOD June 2016 DM m. Banku accumulate PLN 211. 44 (Stockholm) June 2016 DM BDM accumulate PLN 215. 40 PKO BP Polish Capital Market 2016 Recommendations received in 2015 and 2016 Poland Conference (Auerbach, IPOPEMA) Wood Emerging Europe Financials Conference in Warsaw June 3 rd-5 th TP Sep 2016 in New York June 1 st-2 nd Recommendation Carnegie Debt Purchase Seminar 2016 Conference (London) May 16 th Institution Wall Street 20 Conference of the Polish 8 7 7 1 0 Buy Accumulate Hold* Reduce Sell For more details, visit: pl. kruk. eu/relacje-inwestorskie/raporty-analityczne Association of Retail Investors Sell-side analysts covering Company stock September 14 th-16 th Roadshow in the USA September 20 th Societe Generale Conference in Paris DM BDM Maciej Bobrowski September 21 st-22 nd Roadshow in London DM BZ WBK Dariusz Górski October 13 th-14 th ERSTE Conference in Stegersbach Vestor DM Michał Fidelus michal. fidelus@investors. pl Erste Group Mateusz Krupa mateusz. krupa@erstegroup. com November 30 th-December 1 st WOOD’s Winter in Prague Ipopema Łukasz Jańczak lukasz. janczak@ipopema. pl DM m. Banku Michał Konarski michal. konarski@dibre. com. pl DM PKO BP Jaromir Szortyka Jaromir. szortyka@pkobp. pl Trigon DM Grzegorz Kujawski grzegorz. kujawski@trigon. pl Wood & Co. Jerzy Kosiński DM BDM Maciej Bobrowski * 'Hold' or 'neutral' Institution Analyst Contact bobrowski@bdm. pl dariusz. gorski@bzwbk. pl jerzy. kosinski@wood. com bobrowski@bdm. pl 28
Disclaimer This presentation has not been prepared in connection with any public share or bond offering of KRUK S. A. The presentation is for information purposes only and as such should not be treated as an invitation, proposal or offer to purchase any financial instruments. Investing in KRUK S. A. shares and bonds involves risks inherent in such financial instruments. To the best of KRUK S. A. 's knowledge, the information contained in this presentation is consistent with the Company's financial statements available at http: //en. kruk. eu/en/for-investors/reports/interim-reports/, which are the only source of binding financial and non-financial information on KRUK S. A. The information presented herein should not be construed as a representation or warranty concerning the Company's future performance and results of operations. Neither KRUK S. A. nor any of the parties acting on its behalf shall be liable for any losses resulting from improper use of this presentation or any information contained herein. 29
KRUK S. A. ul. Wołowska 8 51 -116 Wrocław, Poland www. kruksa. pl Investor Relations: ir@kruksa. pl For investors: www. kruksa. pl/dla-inwestora