Dr Urmi Ray Qualcomm Technologies Inc Trends in
- Slides: 34
Dr. Urmi Ray Qualcomm Technologies, Inc. Trends in Mobile Industry and Impact on Packaging and Integration 1
Safe Harbor This presentationcontainsforward-lookingstatementsthat are inherently subjectto risks and uncertainties, including but not limitedto statements regarding company, industry, geographic, product, technology, network or consumerdemand projections, estimates, forecasts, trends, growth or opportunities, or our positioningor ability to capitalize thereon; our businessor financial outlook, projections, estimates, guidance, forecasts, trends, targets or growth; our business, technologyor growthinitiativesor strategies; projections, estimates, forecasts, trends, evolutionsor growthin 3 G, 3 G/4 G, LTE, smartphoneadoption, penetration, replacementor upgrade rates, mobileconnections, mobiledata traffic, small cells, or device shipments, sales or average selling prices; our product or technologyroadmap; devices which may containour products; or enhancementsto, advancementsor trends in, or future, products, devices, standards, solutions, technologies, innovations, features, functionality or performance. Forward-lookingstatementsare generally identified by words such as “estimates, ”“guidance, ” “expects, ” “anticipates, ” “intends, ” “plans, ” “believes, ” “seeks” and similar expressions. Actual results may differ materiallyfrom thosereferred to in the forward-looking statementsdue to a number of importantfactors, including but not limitedto risks associatedwith the commercialdeploymentof CDMA, OFDMA and other technologies, continuinggrowthin our customers’and licensees’sales of productsand servicesbased on these technologiesand our ability to continueto drive customerdemand for our productsand servicesbased on these technologies; competition; our dependence on a small number of customersand licensees; the continuedand future successof our licensing programs; attackson our licensing businessmodel, including current and future legal proceedingsor actionsof governmentalor quasi-governmentalbodiesor standards or industry organizations; the enforcementand protectionof our intellectualproperty rights; the commercialsuccessof our new technologies, productsand services; claimsby third parties that we infringe their intellectualproperty; our dependence on a limitednumber of third-party suppliers; our stockprice and earnings volatility; governmentregulationsand policies; strategictransactionsand investments; globaleconomicconditionsthat impact the mobile communicationsindustry; foreign currency fluctuations; and failures in our productsor services or in the productsof our customers, including those resulting from security vulnerabilities, defects or errors. These and other risks are set forth in our mostrecent Form 10 -K filed with the SEC, copies of which are available on our websiteat www. qualcomm. com. We undertake no obligationto update any forward-lookingstatements. This presentationincludes a discussionof “non-GAAP financial measures” as that term is defined in Regulation. G. The mostdirectly comparable GAAP financial measures and informationreconcilingthese non-GAAP financial measures to the Company’sfinancial results prepared in accordancewith GAAP have been included at the end of this presentation. Throughouttoday’spresentationswe refer to “Qualcomm”for ease of reference. However, please recall that in connectionwith our Fiscal 2013 reorganization, Qualcomm. Incorporatedcontinuesto operate QTL and own the vast majorityof our patentportfolio, while Qualcomm Technologies, Inc. , its wholly-ownedsubsidiary, now operates, along with its subsidiaries, substantially all of our productsand services businesses, including QCT, and substantiallyall of our research and developmentfunctions. PAGE 2
Outline 1 Mobile Revolution 2 Technology Trends in Handheld Devices 3 Mobile Architecture Tsunami 4 Wrap Up, Journey Ahead 3
Mobile Revolution 4
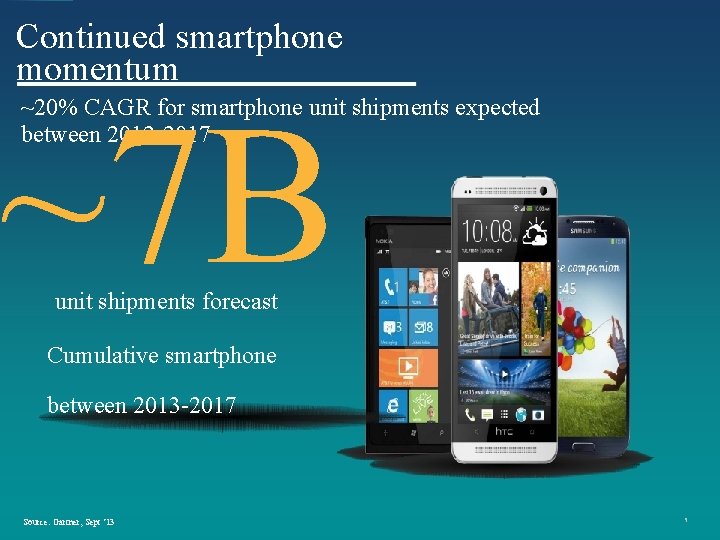
Continued smartphone momentum ~7 B ~20% CAGR for smartphone unit shipments expected between 2012 -2017 unit shipments forecast Cumulative smartphone between 2013 -2017 Source: Gartner, Sept ‘ 13 5
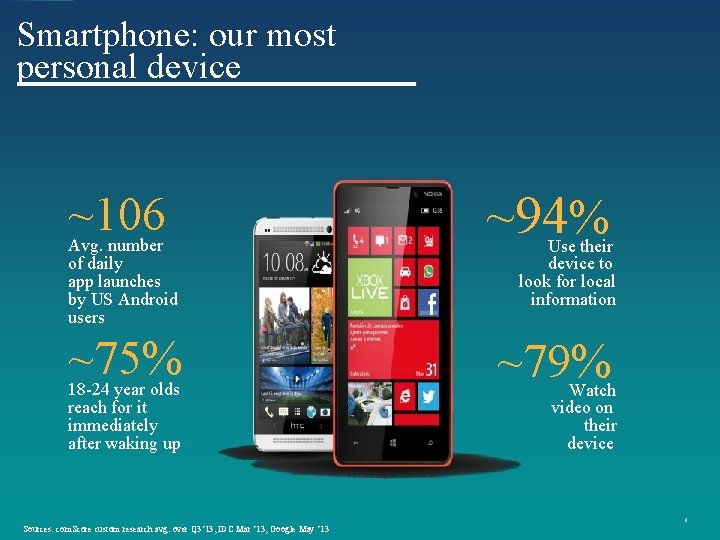
Smartphone: our most personal device ~106 ~94% ~75% ~79% Avg. number of daily app launches by US Android users 18 -24 year olds reach for it immediately after waking up Use their device to look for local information Watch video on their device 6 Sources: com. Score custom research avg. over Q 3’ 13, IDC Mar ’ 13, Google May ’ 13
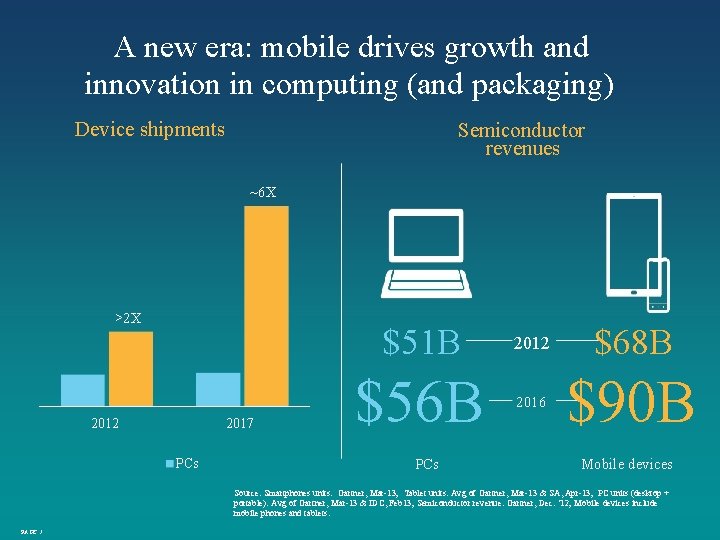
A new era: mobile drives growth and innovation in computing (and packaging) Device shipments Semiconductor revenues ~6 X >2 X 2012 2017 PCs $51 B 2012 $68 B $56 B 2016 $90 B PCs Mobile devices Source: Smartphones units: Gartner, Mar-13; Tablet units: Avg of Gartner, Mar-13 & SA, Apr-13; PC units (desktop + portable): Avg of Gartner, Mar-13 & IDC, Feb 13; Semiconductor revenue: Gartner, Dec. ’ 12; Mobile devices include mobile phones and tablets. PAGE 7
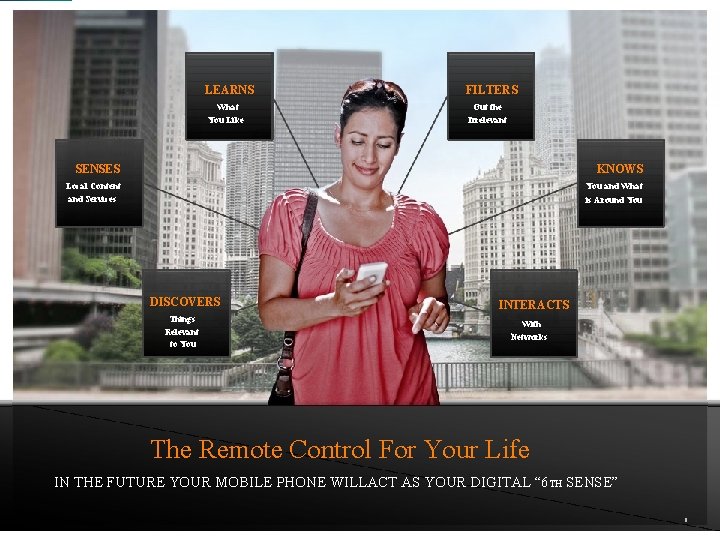
LEARNS What You Like FILTERS Out the Irrelevant SENSES KNOWS Local Content and Services You and What is Around You DISCOVERS Things Relevant to You INTERACTS With Networks The Remote Control For Your Life IN THE FUTURE YOUR MOBILE PHONE WILLACT AS YOUR DIGITAL “ 6 TH SENSE” 8
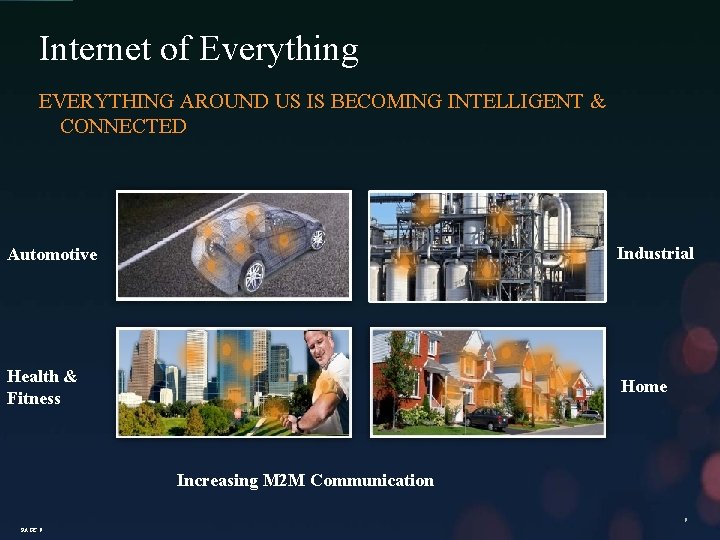
Internet of Everything EVERYTHING AROUND US IS BECOMING INTELLIGENT & CONNECTED Automotive Industrial Health & Fitness Home Increasing M 2 M Communication 9 PAGE 9
Technology Trends & Drivers for Handheld Devices 10
Mobile Chipset Trends Smartphones/Phablets are packing more and more features More memory BW and density Miniaturization of the chipset, especially in the Z dimension CMOS Scaling “slow down” beyond 10 nm A series of disruptive technology changes will be required 11
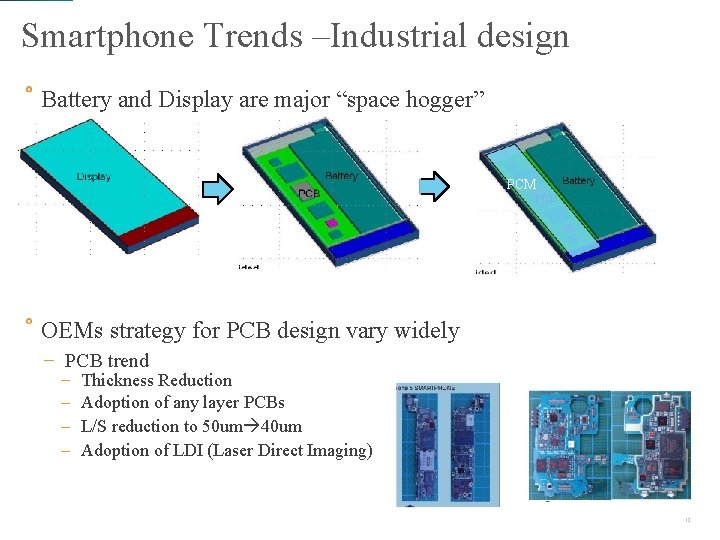
Smartphone Trends –Industrial design Battery and Display are major “space hogger” PCM OEMs strategy for PCB design vary widely − PCB trend − − Thickness Reduction Adoption of any layer PCBs L/S reduction to 50 um 40 um Adoption of LDI (Laser Direct Imaging) 12
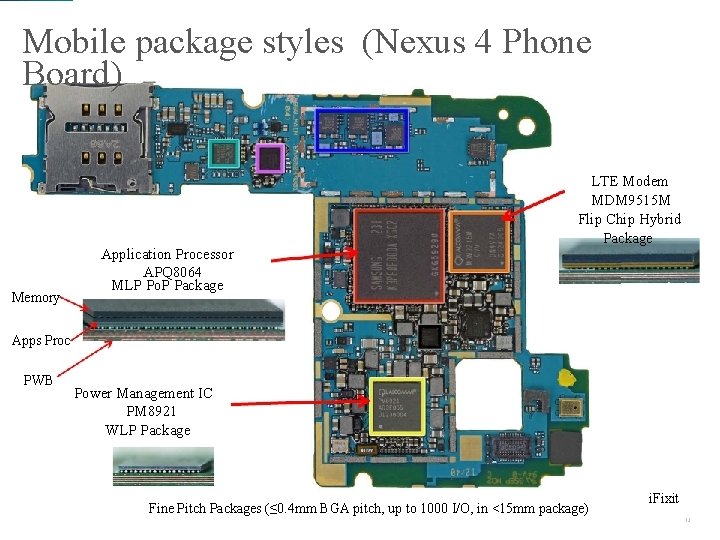
Mobile package styles (Nexus 4 Phone Board) Memory Application Processor APQ 8064 MLP Po. P Package LTE Modem MDM 9515 M Flip Chip Hybrid Package Apps Proc PWB Power Management IC PM 8921 WLP Package Fine Pitch Packages (≤ 0. 4 mm BGA pitch, up to 1000 I/O, in <15 mm package) i. Fixit 13
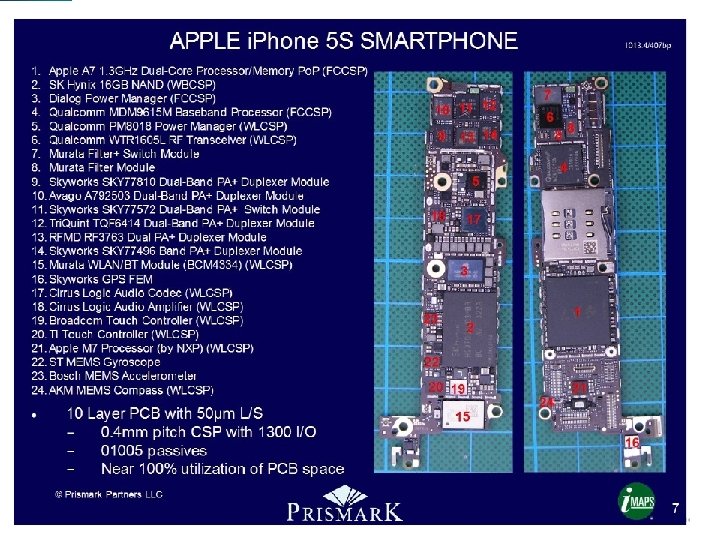
14
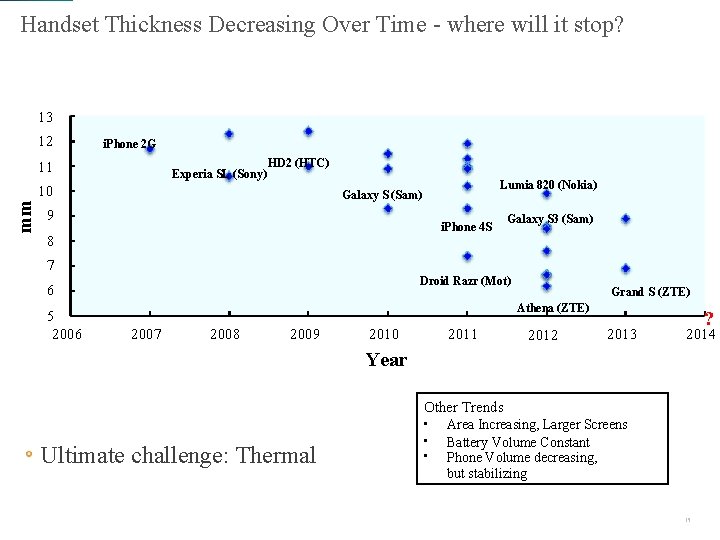
Handset Thickness Decreasing Over Time - where will it stop? 13 12 i. Phone 2 G mm 11 Experia SL (Sony) HD 2 (HTC) 10 Lumia 820 (Nokia) Galaxy S (Sam) 9 i. Phone 4 S 8 Galaxy S 3 (Sam) 7 Droid Razr (Mot) 6 5 2006 Grand S (ZTE) Athena (ZTE) 2007 2008 2009 2010 2011 2012 2013 ? 2014 Year Other Trends Ultimate challenge: Thermal • • • Area Increasing, Larger Screens Battery Volume Constant Phone Volume decreasing, but stabilizing 15
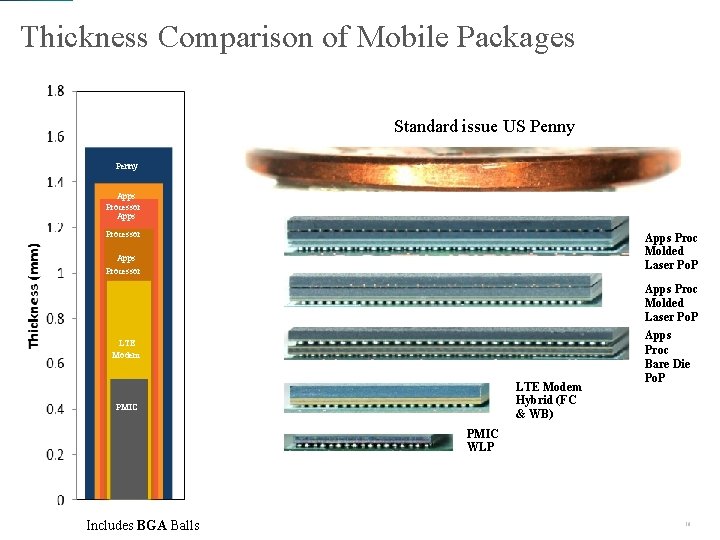
Thickness Comparison of Mobile Packages Standard issue US Penny Apps Processor Apps Proc Molded Laser Po. P LTE Modem Hybrid (FC & WB) PMIC Apps Proc Bare Die Po. P PMIC WLP Includes BGA Balls 16
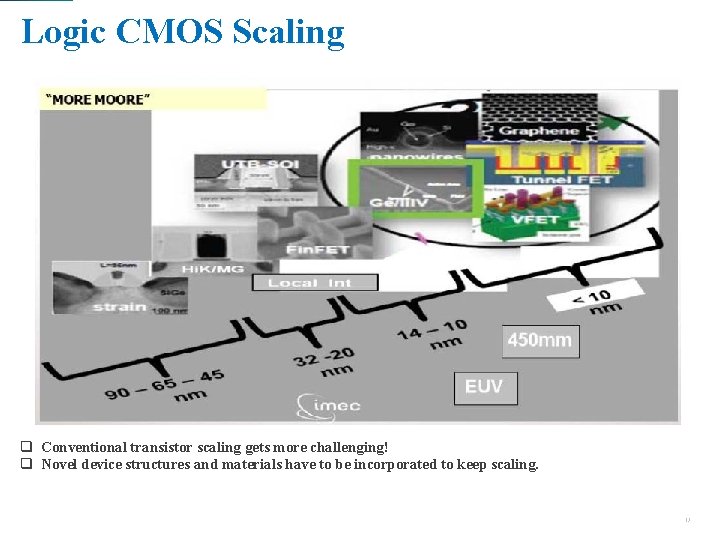
Logic CMOS Scaling Conventional transistor scaling gets more challenging! Novel device structures and materials have to be incorporated to keep scaling. 17
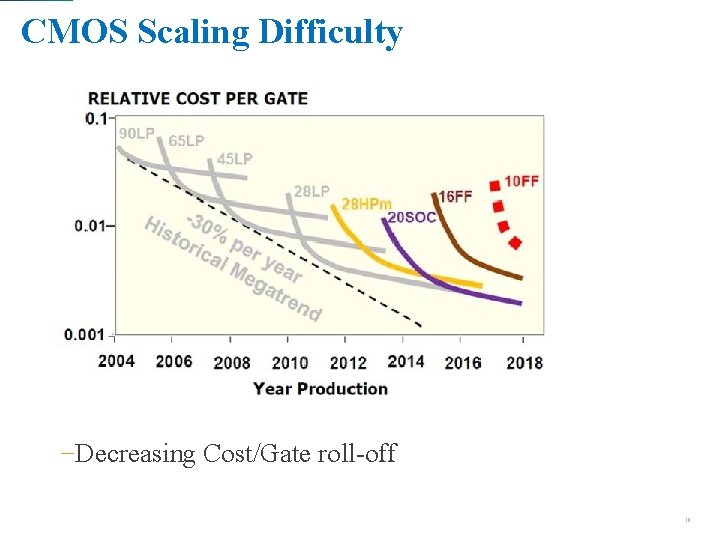
CMOS Scaling Difficulty −Decreasing Cost/Gate roll-off 18
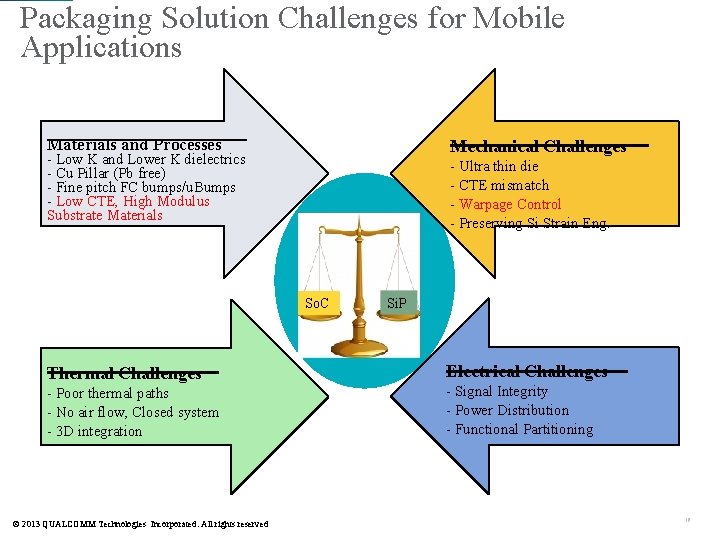
Packaging Solution Challenges for Mobile Applications Materials and Processes Mechanical Challenges - Low K and Lower K dielectrics - Cu Pillar (Pb free) - Fine pitch FC bumps/u. Bumps - Low CTE, High Modulus Substrate Materials - Ultra thin die - CTE mismatch - Warpage Control - Preserving Si Strain Eng. So. C Si. P Thermal Challenges Electrical Challenges - Poor thermal paths - No air flow, Closed system - 3 D integration - Signal Integrity - Power Distribution - Functional Partitioning © 2013 QUALCOMM Technologies Incorporated. All rights reserved 19
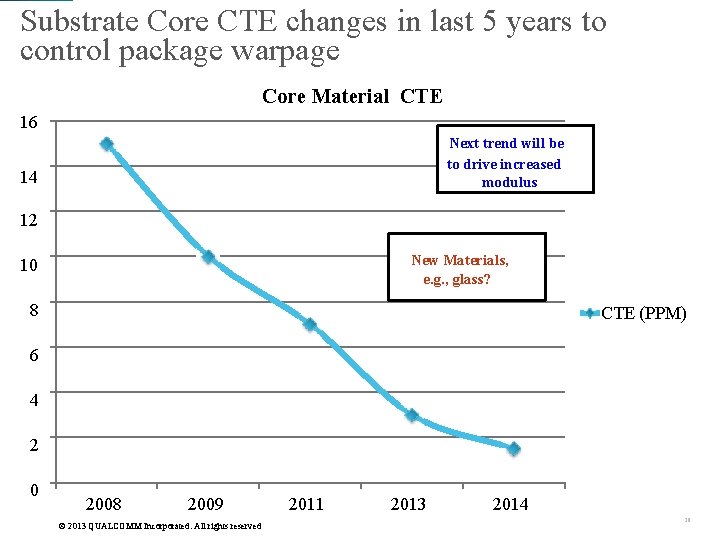
Substrate Core CTE changes in last 5 years to control package warpage Core Material CTE 16 Next trend will be to drive increased modulus 14 12 New Materials, e. g. , glass? 10 8 CTE (PPM) 6 4 2 0 2008 2009 © 2013 QUALCOMM Incorporated. All rights reserved 2011 2013 2014 20
Mobile Architecture Tsunami 21
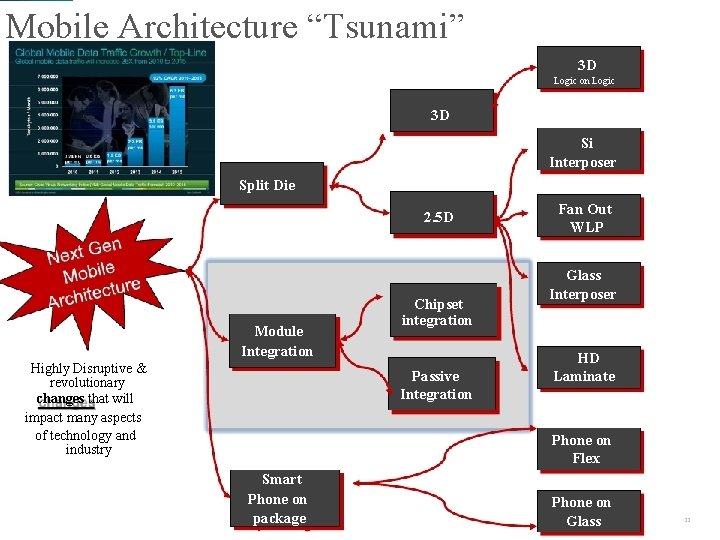
Mobile Architecture “Tsunami” 3 D Logic on Logic 3 D Si Interposer Split Die 2. 5 D Module Integration Highly Disruptive & revolutionary changes that will impact many aspects of technology and industry Chipset integration Passive Integration Fan Out WLP Glass Interposer HD Laminate Phone on Flex Smart Phone on package Phone on Glass 22
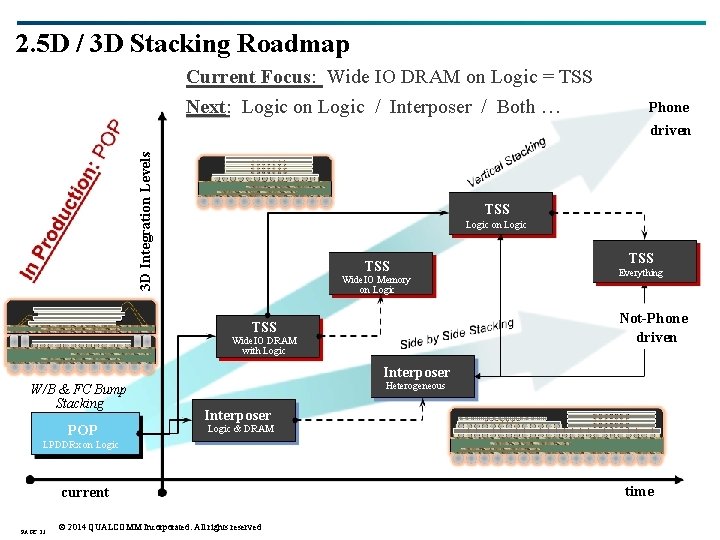
2. 5 D / 3 D Stacking Roadmap Current Focus: Wide IO DRAM on Logic = TSS Next: Logic on Logic / Interposer / Both … Phone 3 D Integration Levels driven TSS Logic on Logic TSS Wide. IO Memory on Logic TSS Everything Not-Phone driven TSS Wide. IO DRAM with Logic Interposer W/B & FC Bump Stacking POP Heterogeneous Interposer Logic & DRAM LPDDRx on Logic current PAGE 23 © 2014 QUALCOMM Incorporated. All rights reserved time
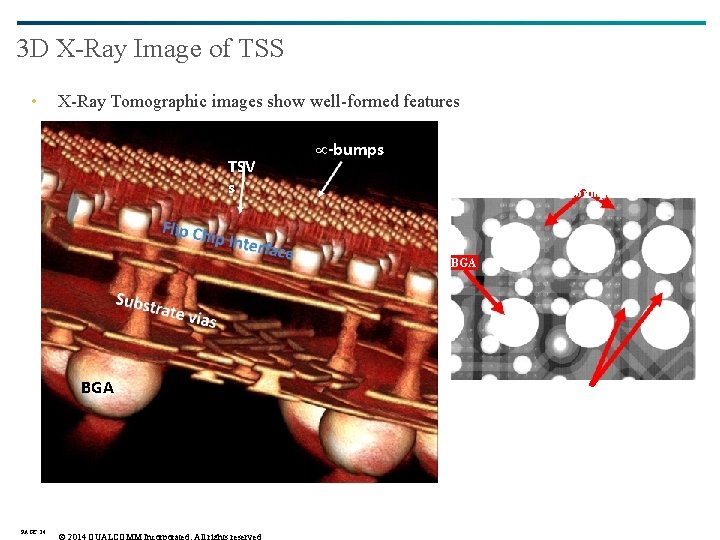
3 D X-Ray Image of TSS • X-Ray Tomographic images show well-formed features TSV s µ-bumps BGA PAGE 24 © 2014 QUALCOMM Incorporated. All rights reserved FC Bump
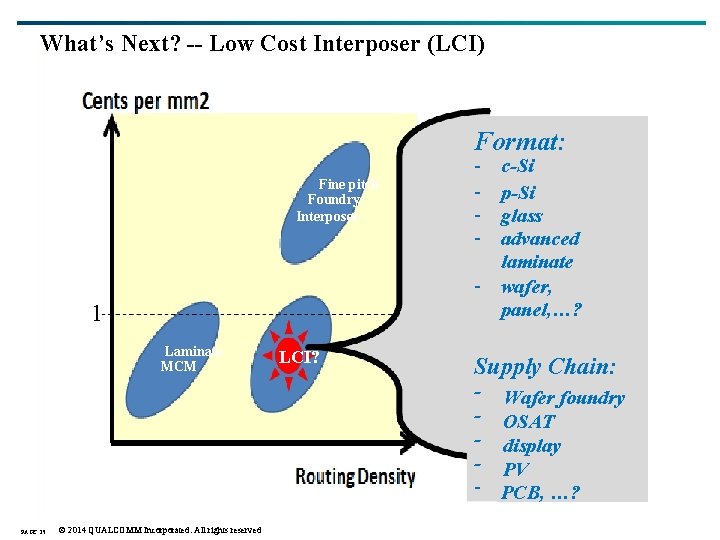
What’s Next? -- Low Cost Interposer (LCI) Format: Fine pitch Foundry Interposer - 1 Laminate MCM LCI? Supply Chain: - PAGE 25 © 2014 QUALCOMM Incorporated. All rights reserved c-Si p-Si glass advanced laminate wafer, panel, …? Wafer foundry OSAT display PV PCB, …?
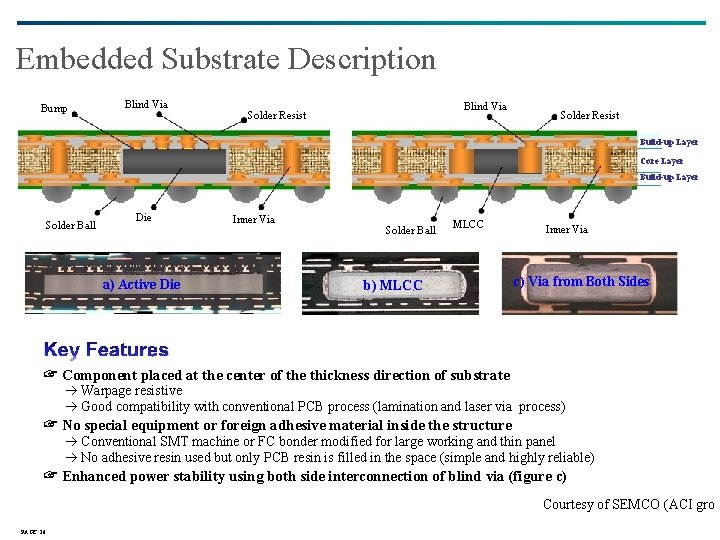
Embedded Substrate Description Bump Blind Via Solder Resist Build-up Layer Core Layer Build-up Layer Solder Ball Die a) Active Die Inner Via Solder Ball MLCC b) MLCC Inner Via c) Via from Both Sides ☞ Component placed at the center of the thickness direction of substrate Warpage resistive Good compatibility with conventional PCB process (lamination and laser via process) ☞ No special equipment or foreign adhesive material inside the structure Conventional SMT machine or FC bonder modified for large working and thin panel No adhesive resin used but only PCB resin is filled in the space (simple and highly reliable) ☞ Enhanced power stability using both side interconnection of blind via (figure c) Courtesy of SEMCO (ACI gro PAGE 26
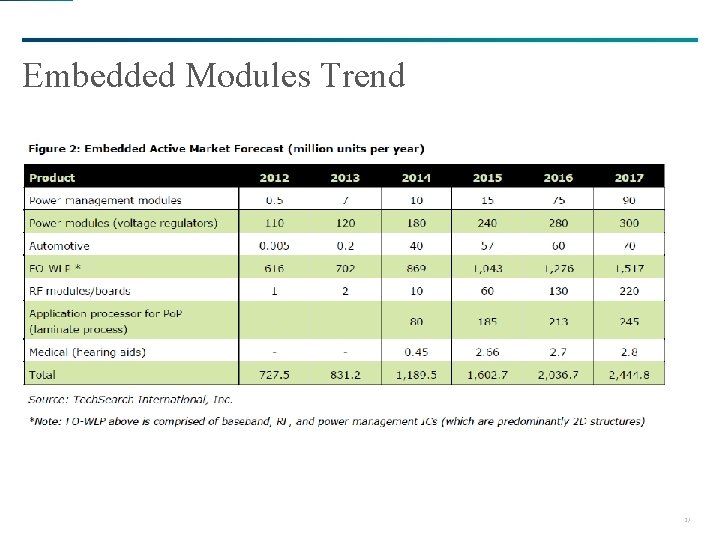
Embedded Modules Trend 27
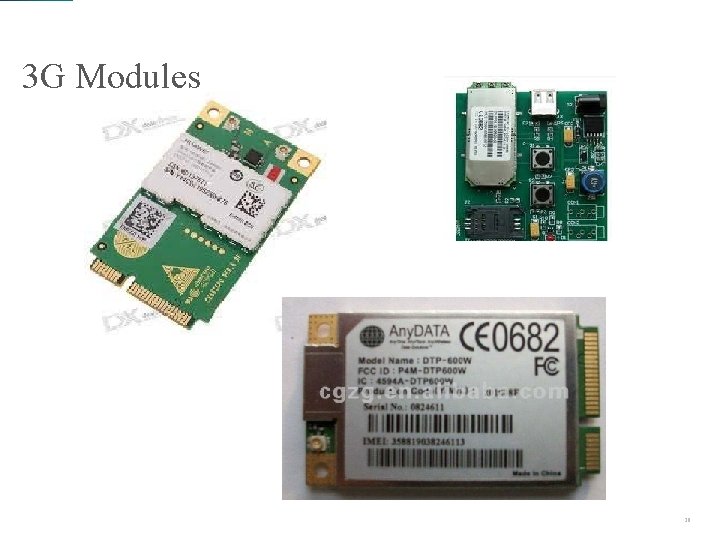
3 G Modules 28
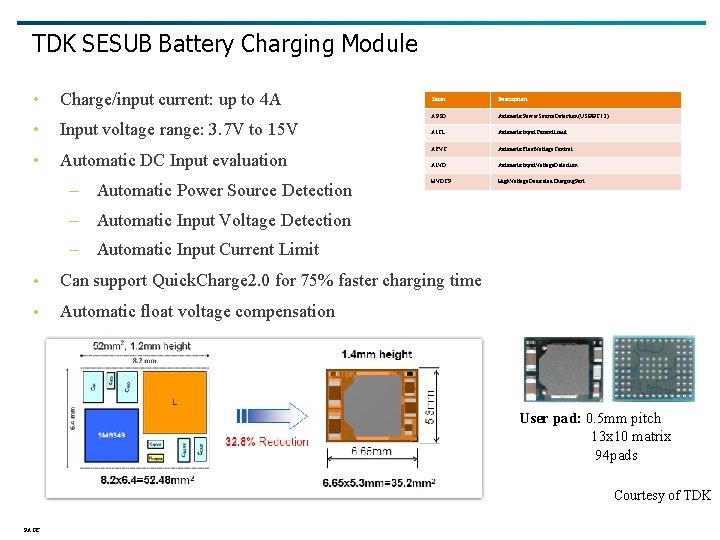
TDK SESUB Battery Charging Module • • • Charge/input current: up to 4 A Input voltage range: 3. 7 V to 15 V Automatic DC Input evaluation – Automatic Power Source Detection Term Description APSD Automatic. Power. Source. Detection(USBBC 1. 2) AICL Automatic. Input. Current. Limit AFVC Automatic. Float. Voltage. Control AIVD Automatic. Input. Voltage. Detection HVDCP High. Voltage. Dedicated. Charging. Port – Automatic Input Voltage Detection – Automatic Input Current Limit • Can support Quick. Charge 2. 0 for 75% faster charging time • Automatic float voltage compensation User pad: 0. 5 mm pitch 13 x 10 matrix 94 pads Courtesy of TDK PAGE
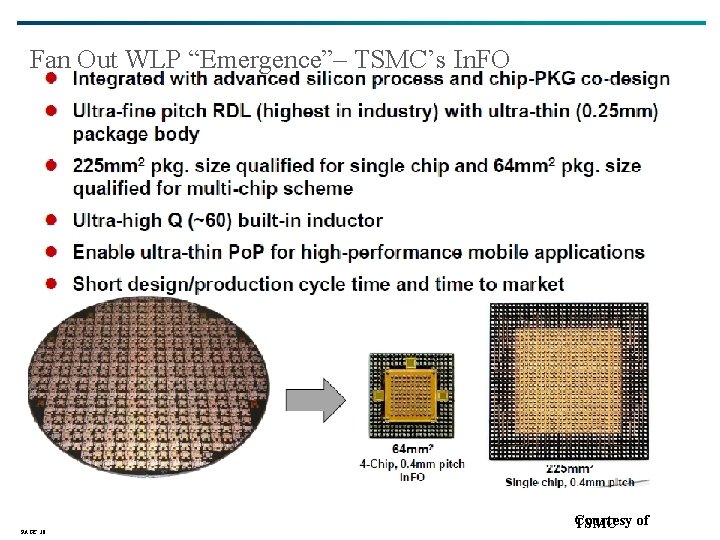
Fan Out WLP “Emergence”– TSMC’s In. FO PAGE 30 Courtesy TSMC of
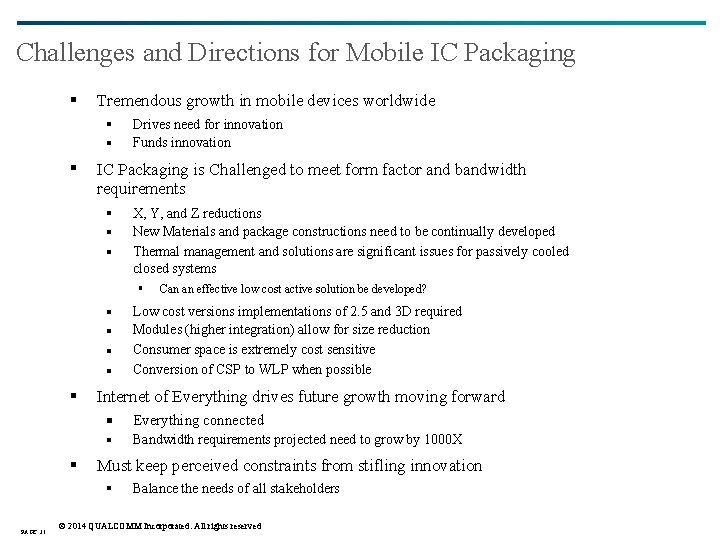
Challenges and Directions for Mobile IC Packaging Tremendous growth in mobile devices worldwide Drives need for innovation Funds innovation IC Packaging is Challenged to meet form factor and bandwidth requirements X, Y, and Z reductions New Materials and package constructions need to be continually developed Thermal management and solutions are significant issues for passively cooled closed systems Low cost versions implementations of 2. 5 and 3 D required Modules (higher integration) allow for size reduction Consumer space is extremely cost sensitive Conversion of CSP to WLP when possible Internet of Everything drives future growth moving forward Everything connected Bandwidth requirements projected need to grow by 1000 X Must keep perceived constraints from stifling innovation PAGE 31 Can an effective low cost active solution be developed? Balance the needs of all stakeholders © 2014 QUALCOMM Incorporated. All rights reserved
Wrap Up: Journey Ahead 32
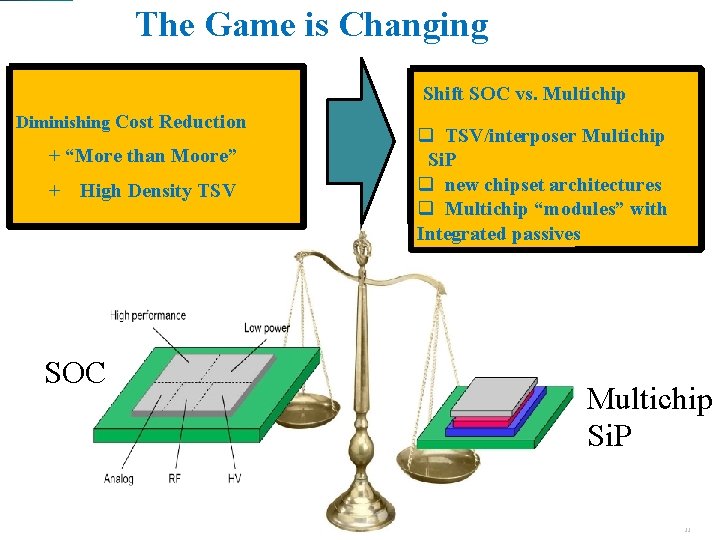
The Game is Changing Shift SOC vs. Multichip Diminishing Cost Reduction + “More than Moore” + High Density TSV SOC TSV/interposer Multichip Si. P new chipset architectures Multichip “modules” with Integrated passives Multichip Si. P 33
Thank you Follow us on: For more information on Qualcomm, visit us at: www. qualcomm. com & www. qualcomm. com/blog Qualcomm is a trademark of Qualcomm Incorporated, registered in the United States and other countries. Other products and brand names may be trademarks or registered trademarks of their respective owners © 2013 Qualcomm Technologies, Inc. Qualcomm, Snapdragon, Gobi, and Brew are trademarks of Qualcomm Incorporated, registered in the United States and other countries. Flexrender is a trademark of Qualcomm Incorporated. All Qualcomm Incorporated trademarks are used with permission. Other product and brand names may be trademarks or registered trademarks of their respective owners. 34