Chapter 16 Rollovers Under Section 85 Rollovers Defined

- Slides: 58
Chapter 16 Rollovers Under Section 85
Rollovers Defined © 2009, Clarence Byrd Inc. 2
Important Examples u Transfers Of Property At Tax Values • ITA 73: Inter Vivos To A Spouse • ITA 70: To A Spouse At Death • ITA 85: To A Corporation At Elected Values © 2009, Clarence Byrd Inc. 3
The Standard Section 85 Scenario u Example: An unincorporated business has assets with tax values of $800, 000 and liabilities of $200, 000 (net tax value of $600, 000). The assets have a net fair market value of $2, 000 (potential gain of $1, 400, 000). • Elect $800, 000 for assets, corporation assumes liabilities • $800, 000 = POD = ACB • Boot (Non-share consideration) = $800, 000 (including the $200, 000 in old liabilities) © 2009, Clarence Byrd Inc. 4
General Rules Transferor and Transferee u Who Can Make The Transfer • ITA 85(1) Taxpayer Individual u Trust u Corporation u • ITA 85(2) Partnership © 2009, Clarence Byrd Inc. 5
General Rules Transferor and Transferee u Type Of Corporation • Canadian (Resident) • Subject To Tax • Does Not Have To Be A New Corporation © 2009, Clarence Byrd Inc. 6
General Rules Eligible Property u Type Of Property - ITA 85(5. 1) • Inclusions: Capital Property u Canadian And Foreign Resource Properties u Eligible Capital Property u Inventories u Real Estate Owned By Non-Resident And Used In A Canadian Business u • Exclusions: Inventories Of Real Property u Real Estate Owned By Non-Residents (Unless used in a Canadian Business) u © 2009, Clarence Byrd Inc. 7
General Rules Consideration to the Transferor u Shares • Must Be Included (At Least One) • Common Shares (Growth) And Preferred Shares (Non-Growth) © 2009, Clarence Byrd Inc. 8
General Rules Consideration to the Transferor u Non-Share Consideration (Boot) • Cash, Other Assets, New Debt Or The Assumption Of Old Debt • Important because it can be a Tax Free Distribution © 2009, Clarence Byrd Inc. 9
General Rules Making the Election u u u Form T 2057 (taxpayer) or T 2058 (partnership) If an asset is not listed, it is deemed transferred at FMV (can be a significant problem) Late or amended (1/4 percent per month on any deferred gain: minimum $100 per month - maximum total $8, 000) © 2009, Clarence Byrd Inc. 10
Establishing the Transfer Price General Rules u Upper Limit [ITA 85(1)(c)] = Fair Market Value © 2009, Clarence Byrd Inc. 11
Establishing the Transfer Price General Rules u Lower Limit = Greater Of: • Boot [ITA 85(1)(b)] • Lesser Or Least Of u See Next Slides © 2009, Clarence Byrd Inc. 12
Detailed Transfer Price Rules u Accounts Receivable • Should not be transferred under ITA 85 • Should use ITA 22 election • See Chapter 5 for discussion of this election © 2009, Clarence Byrd Inc. 13
Detailed Transfer Price Rules u Inventories and Non-Depreciable Property – ITA 85(1)(c. 1) • Ceiling = FMV • Floor = greater of: u Boot u Lesser of • FMV • ACB © 2009, Clarence Byrd Inc. 14
Detailed Transfer Price Rules u Land with • ACB of $10, 000 • FMV of $15, 000 • Boot = $12, 000 u Ceiling = $15, 000 u Floor = $12, 000 © 2009, Clarence Byrd Inc. 15
Losses On Transfer Of Non-Depreciable Property To Affiliated Persons u Affiliated Persons (ITA 251. 1) • Individuals: Spouses Only • Corporation Is Affiliated With: A Person By Whom It Is Controlled u Each Member Of An Affiliated Group That Controls u Spouse Of Any Of The Above u © 2009, Clarence Byrd Inc. 16
Losses On Transfer Of Non-Depreciable Property To Affiliated Persons u Stop Loss Provision • ITA 40(2)(g) Deems Certain Losses To Be Nil (Including Superficial Losses) • Superficial Losses Include Transfers To A Corporation By An Affiliated Person © 2009, Clarence Byrd Inc. 17
Losses On Transfer Of Non-Depreciable Property To Affiliated Persons u Treatment Of Loss • Individuals: Add To ACB Of Property On Books Of Transferee • Corporations, Trusts, And Partnerships: Retained On The Books Of The Transferor u Loss Deferred Until u • Property Is Disposed Of • There Is An ITA 88(2) Winding Up • There Is An Acquisition Of Control Of The Transferor Corporation © 2009, Clarence Byrd Inc. 18
Detailed Transfer Price Rules u Depreciable capital property – ITA 85(1)(e) • Ceiling = FMV • Floor = Greater of: Boot u Least Of: u • FMV of the individual asset • Cost of the individual asset • UCC of the class © 2009, Clarence Byrd Inc. 19
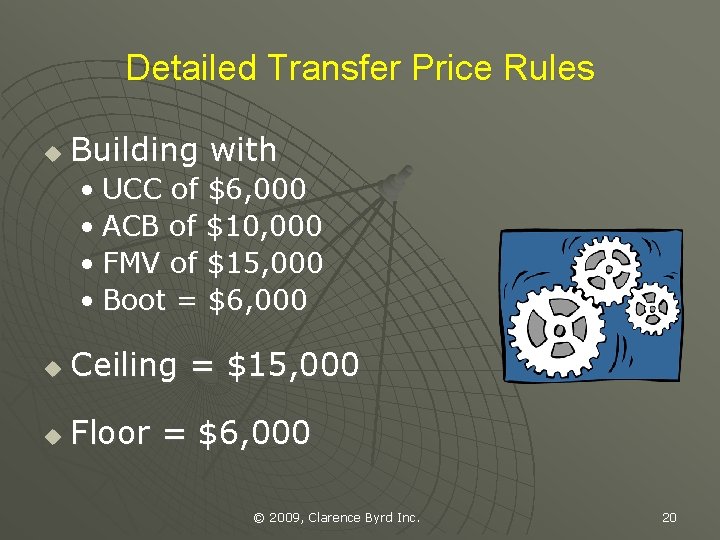
Detailed Transfer Price Rules u Building with • UCC of $6, 000 • ACB of $10, 000 • FMV of $15, 000 • Boot = $6, 000 u Ceiling = $15, 000 u Floor = $6, 000 © 2009, Clarence Byrd Inc. 20
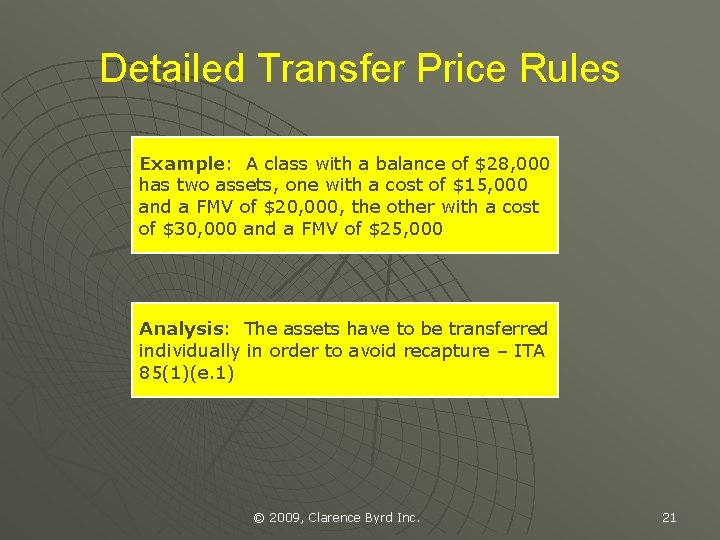
Detailed Transfer Price Rules Example: A class with a balance of $28, 000 has two assets, one with a cost of $15, 000 and a FMV of $20, 000, the other with a cost of $30, 000 and a FMV of $25, 000 Analysis: The assets have to be transferred individually in order to avoid recapture – ITA 85(1)(e. 1) © 2009, Clarence Byrd Inc. 21
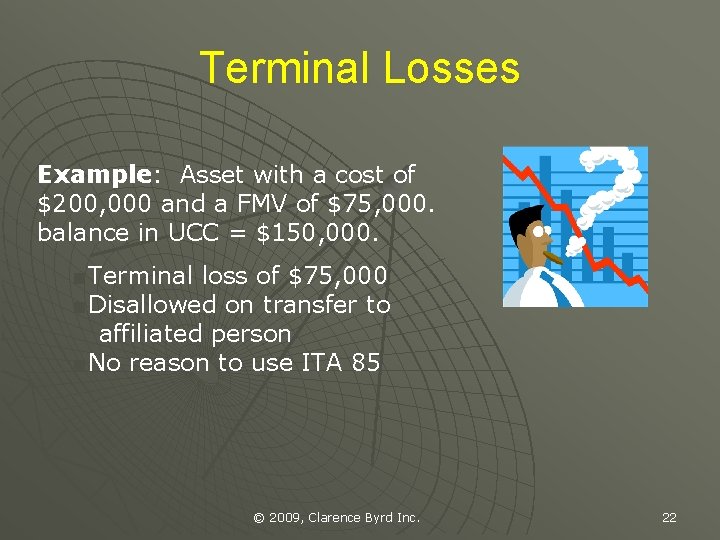
Terminal Losses Example: Asset with a cost of $200, 000 and a FMV of $75, 000. balance in UCC = $150, 000. ■Terminal loss of $75, 000 ■Disallowed on transfer to affiliated person ■No reason to use ITA 85 © 2009, Clarence Byrd Inc. 22
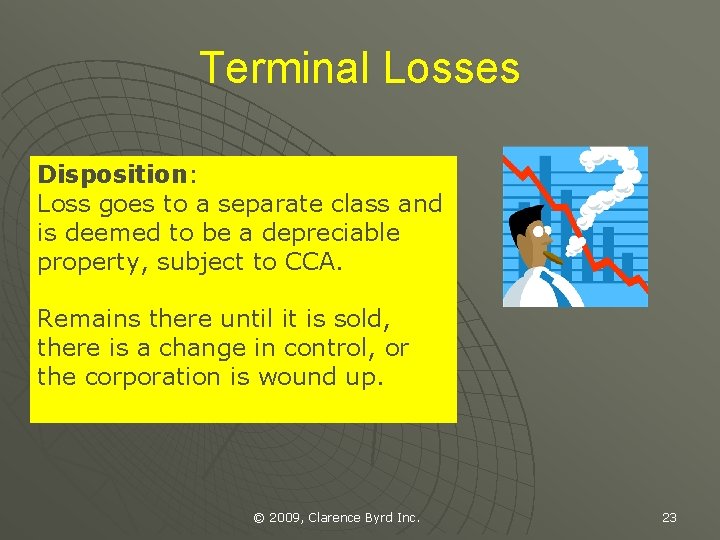
Terminal Losses Disposition: Loss goes to a separate class and is deemed to be a depreciable property, subject to CCA. Remains there until it is sold, there is a change in control, or the corporation is wound up. © 2009, Clarence Byrd Inc. 23
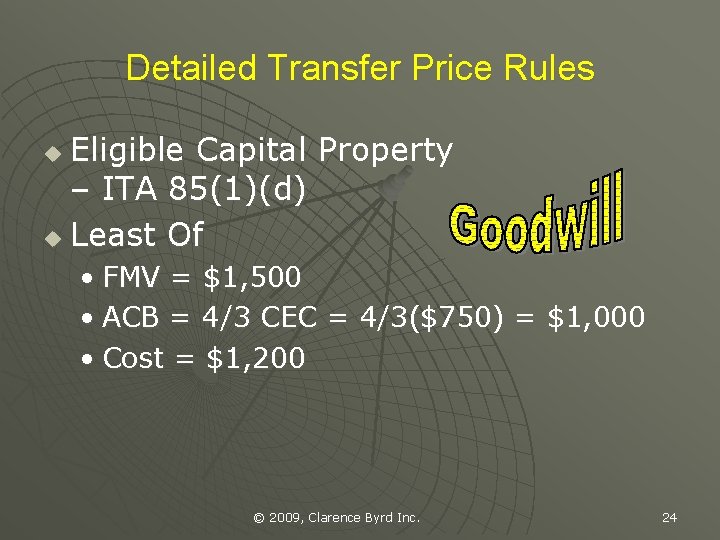
Detailed Transfer Price Rules Eligible Capital Property – ITA 85(1)(d) u Least Of u • FMV = $1, 500 • ACB = 4/3 CEC = 4/3($750) = $1, 000 • Cost = $1, 200 © 2009, Clarence Byrd Inc. 24
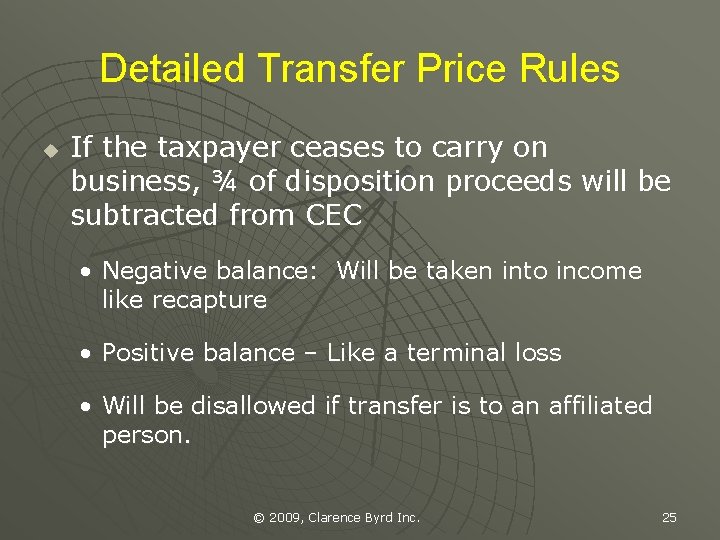
Detailed Transfer Price Rules u If the taxpayer ceases to carry on business, ¾ of disposition proceeds will be subtracted from CEC • Negative balance: Will be taken into income like recapture • Positive balance – Like a terminal loss • Will be disallowed if transfer is to an affiliated person. © 2009, Clarence Byrd Inc. 25
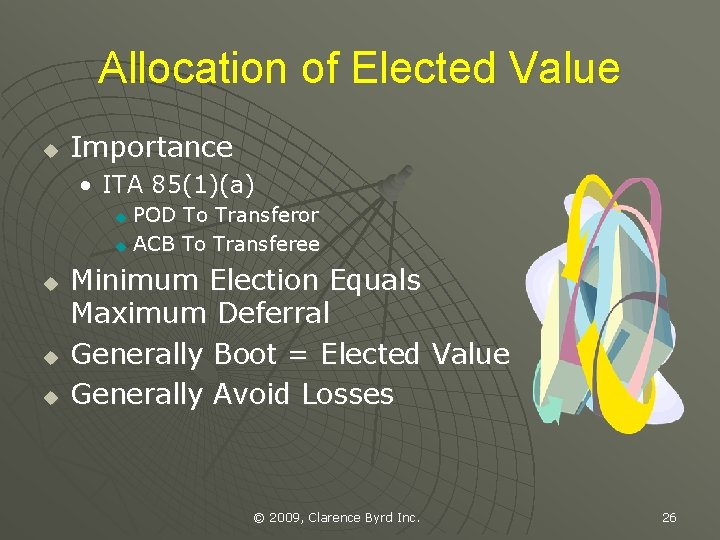
Allocation of Elected Value u Importance • ITA 85(1)(a) POD To Transferor u ACB To Transferee u u Minimum Election Equals Maximum Deferral Generally Boot = Elected Value Generally Avoid Losses © 2009, Clarence Byrd Inc. 26
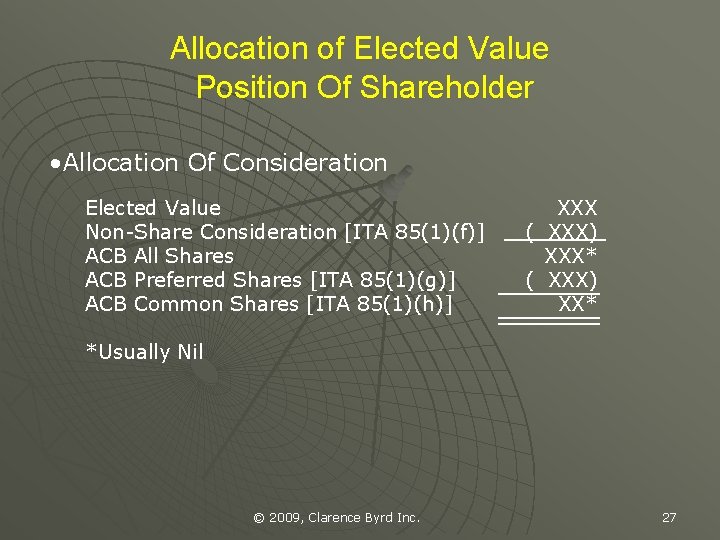
Allocation of Elected Value Position Of Shareholder • Allocation Of Consideration Elected Value Non-Share Consideration [ITA 85(1)(f)] ACB All Shares ACB Preferred Shares [ITA 85(1)(g)] ACB Common Shares [ITA 85(1)(h)] XXX ( XXX) XXX* ( XXX) XX* *Usually Nil © 2009, Clarence Byrd Inc. 27
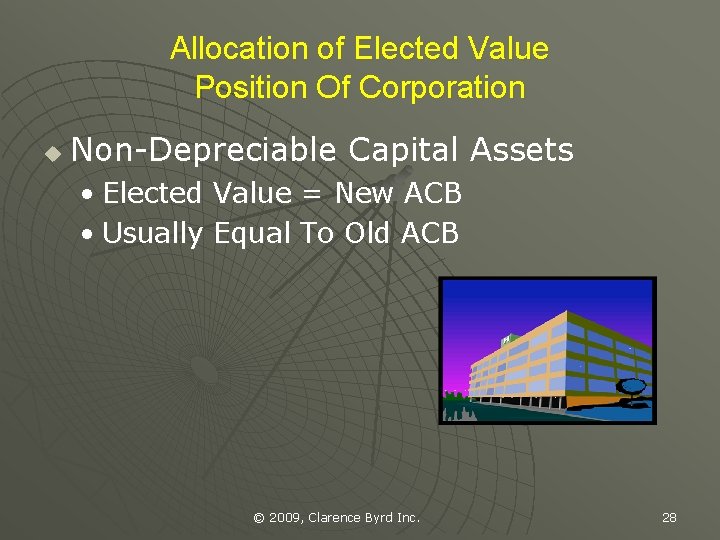
Allocation of Elected Value Position Of Corporation u Non-Depreciable Capital Assets • Elected Value = New ACB • Usually Equal To Old ACB © 2009, Clarence Byrd Inc. 28
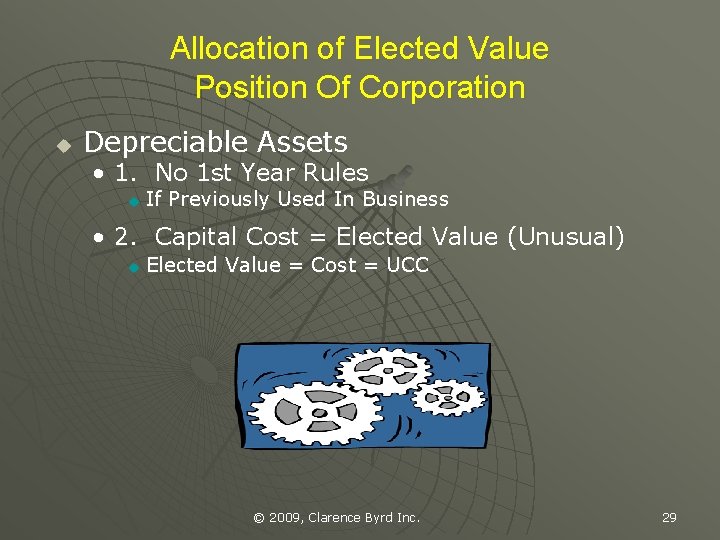
Allocation of Elected Value Position Of Corporation u Depreciable Assets • 1. No 1 st Year Rules u If Previously Used In Business • 2. Capital Cost = Elected Value (Unusual) u Elected Value = Cost = UCC © 2009, Clarence Byrd Inc. 29
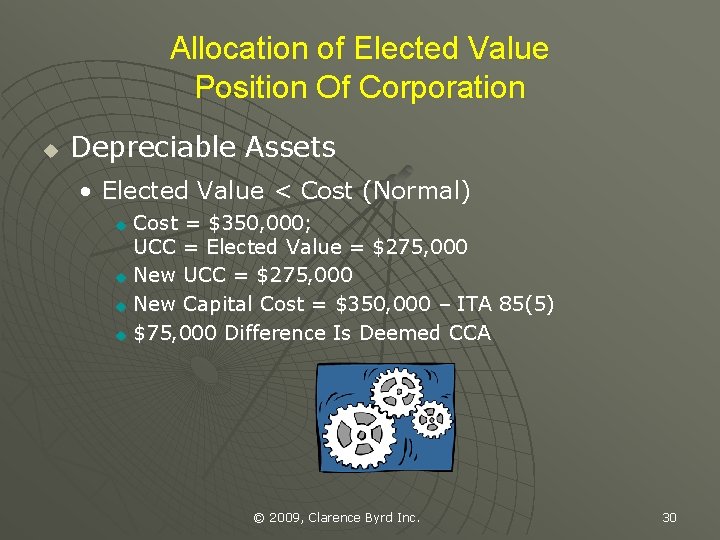
Allocation of Elected Value Position Of Corporation u Depreciable Assets • Elected Value < Cost (Normal) Cost = $350, 000; UCC = Elected Value = $275, 000 u New UCC = $275, 000 u New Capital Cost = $350, 000 – ITA 85(5) u $75, 000 Difference Is Deemed CCA u © 2009, Clarence Byrd Inc. 30
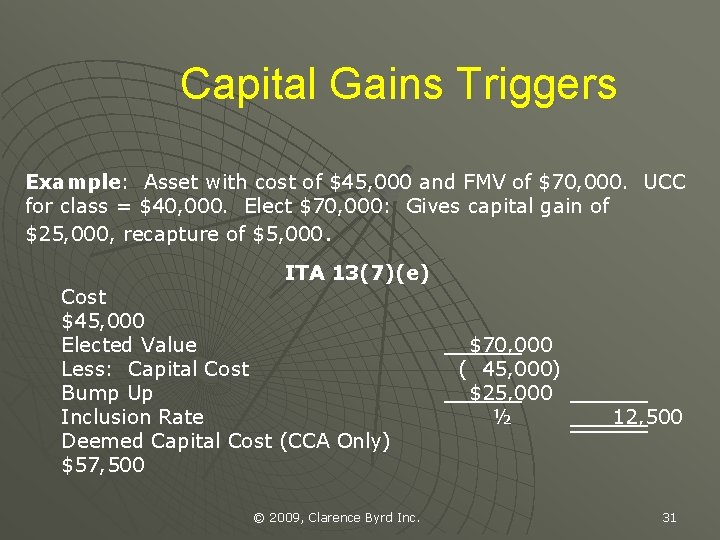
Capital Gains Triggers Example: Asset with cost of $45, 000 and FMV of $70, 000. UCC for class = $40, 000. Elect $70, 000: Gives capital gain of $25, 000, recapture of $5, 000. ITA 13(7)(e) Cost $45, 000 Elected Value Less: Capital Cost Bump Up Inclusion Rate Deemed Capital Cost (CCA Only) $57, 500 © 2009, Clarence Byrd Inc. $70, 000 ( 45, 000) $25, 000 ½ 12, 500 31
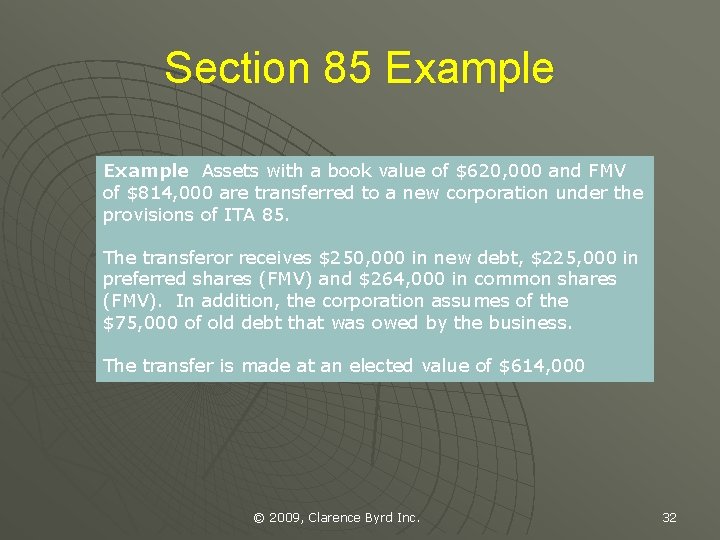
Section 85 Example Assets with a book value of $620, 000 and FMV of $814, 000 are transferred to a new corporation under the provisions of ITA 85. The transferor receives $250, 000 in new debt, $225, 000 in preferred shares (FMV) and $264, 000 in common shares (FMV). In addition, the corporation assumes of the $75, 000 of old debt that was owed by the business. The transfer is made at an elected value of $614, 000 © 2009, Clarence Byrd Inc. 32
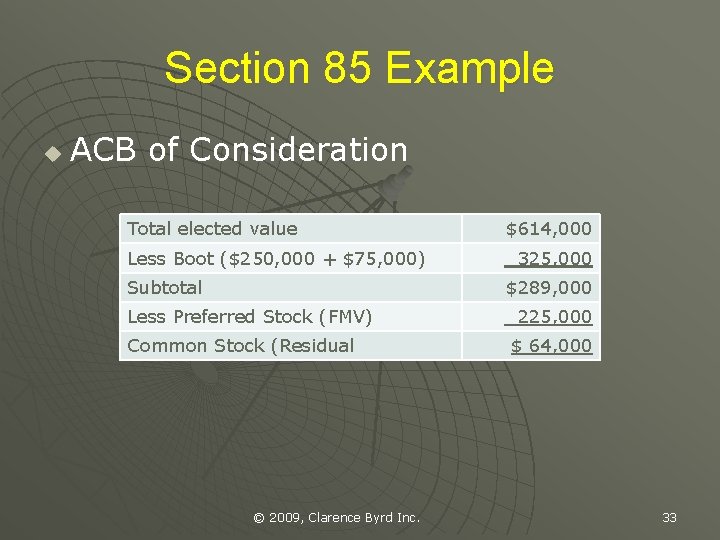
Section 85 Example u ACB of Consideration Total elected value Less Boot ($250, 000 + $75, 000) Subtotal $614, 000 325, 000 $289, 000 Less Preferred Stock (FMV) Common Stock (Residual © 2009, Clarence Byrd Inc. 225, 000 $ 64, 000 33
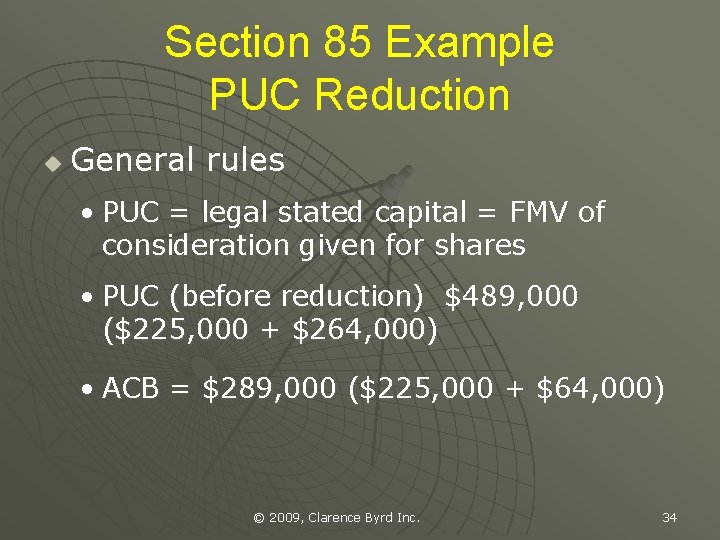
Section 85 Example PUC Reduction u General rules • PUC = legal stated capital = FMV of consideration given for shares • PUC (before reduction) $489, 000 ($225, 000 + $264, 000) • ACB = $289, 000 ($225, 000 + $64, 000) © 2009, Clarence Byrd Inc. 34
Section 85 Example u The Problem • Sale Of Shares Would Result In Capital Gain Of $200, 000 (Use Of ITA 110. 6) • Redemption Would Result In No ITA 84(3) Dividend A Capital Gain Of $200, 000 (Use Of ITA 110. 6) • However, PUC Of $489, 000 Could Be Removed Tax Free © 2009, Clarence Byrd Inc. 35
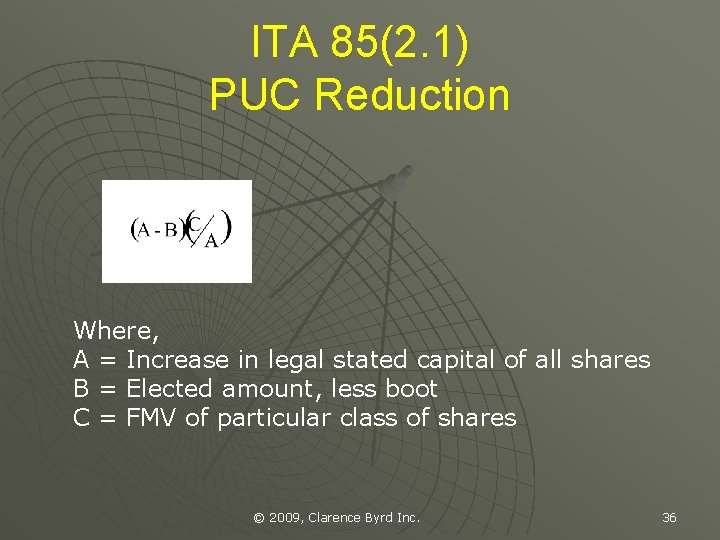
ITA 85(2. 1) PUC Reduction Where, A = Increase in legal stated capital of all shares B = Elected amount, less boot C = FMV of particular class of shares © 2009, Clarence Byrd Inc. 36
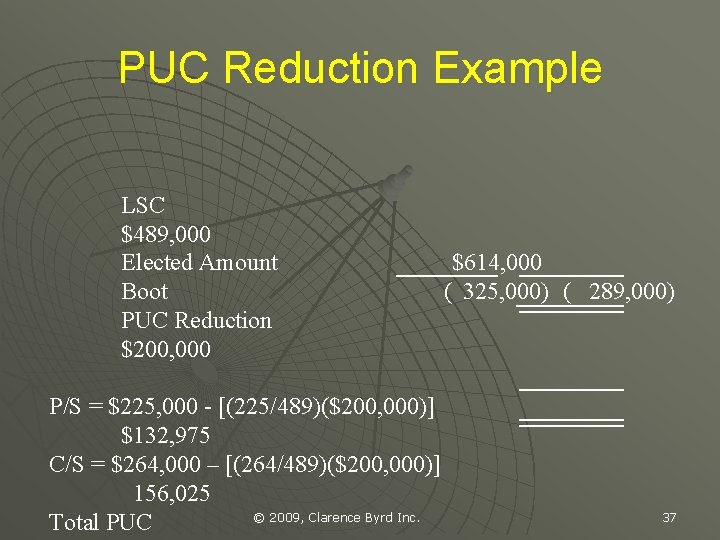
PUC Reduction Example LSC $489, 000 Elected Amount Boot PUC Reduction $200, 000 P/S = $225, 000 - [(225/489)($200, 000)] $132, 975 C/S = $264, 000 – [(264/489)($200, 000)] 156, 025 © 2009, Clarence Byrd Inc. Total PUC $614, 000 ( 325, 000) ( 289, 000) 37
PUC Reduction Example Note The allocation of the PUC reduction is pro rata on the basis of fair market value of the two classes of shares. ACB is allocated sequentially, starting with Boot, followed by preferred shares, and ending with common stock as a residual. © 2009, Clarence Byrd Inc. 38
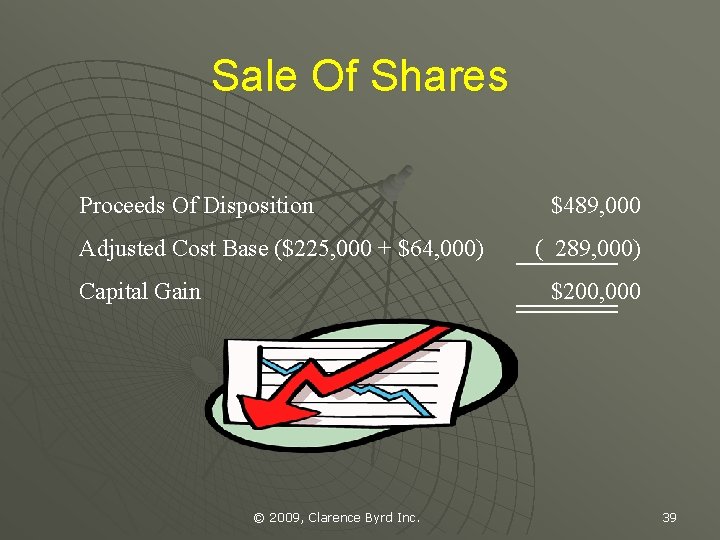
Sale Of Shares Proceeds Of Disposition Adjusted Cost Base ($225, 000 + $64, 000) Capital Gain $489, 000 ( 289, 000) $200, 000 © 2009, Clarence Byrd Inc. 39
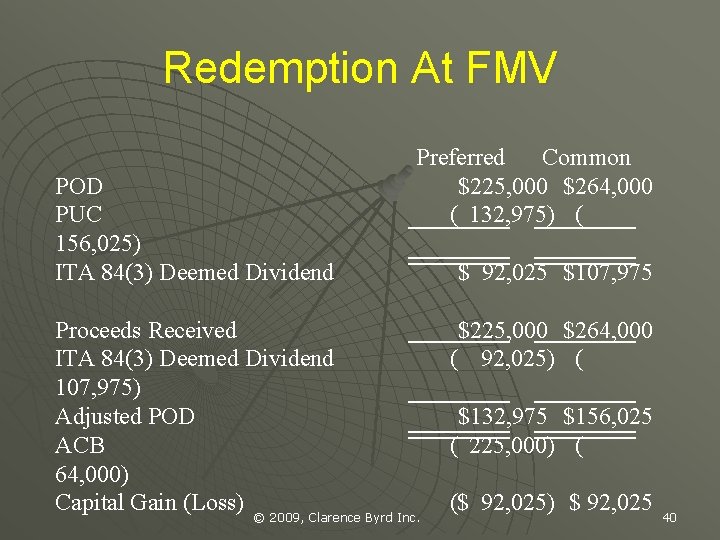
Redemption At FMV POD PUC 156, 025) ITA 84(3) Deemed Dividend Preferred Common $225, 000 $264, 000 ( 132, 975) ( Proceeds Received ITA 84(3) Deemed Dividend 107, 975) Adjusted POD ACB 64, 000) Capital Gain (Loss) © 2009, Clarence Byrd Inc. $ 92, 025 $107, 975 $225, 000 $264, 000 ( 92, 025) ( $132, 975 $156, 025 ( 225, 000) ( ($ 92, 025) $ 92, 025 40
Benefit To Related Person - ITA 85(1)(e. 2) – Example u Property with an ACB of $100, 000 and a FMV of $250, 000, is transferred to a corporation. The transferor elects a value of $100, 000 for the property. The transferor takes back a $100, 000 Note and Preferred Stock that is redeemable at $80, 000 (FMV). © 2009, Clarence Byrd Inc. 41
Benefit To Related Person - ITA 85(1)(e. 2) – Example u If related party holds Common Stock of corporation, than there is a gift of $70, 000 ($250, 000 - $180, 000). Daughter buys common shares for $1, 000. © 2009, Clarence Byrd Inc. 42
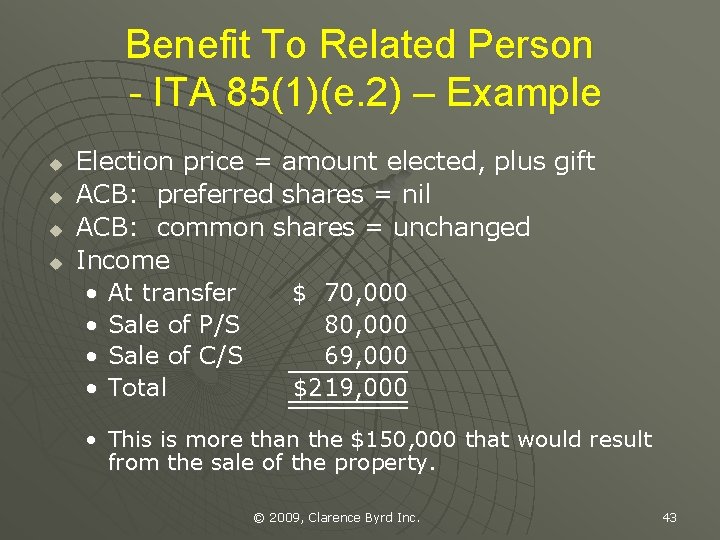
Benefit To Related Person - ITA 85(1)(e. 2) – Example u u Election price = amount elected, plus gift ACB: preferred shares = nil ACB: common shares = unchanged Income • At transfer $ 70, 000 • Sale of P/S 80, 000 • Sale of C/S 69, 000 • Total $219, 000 • This is more than the $150, 000 that would result from the sale of the property. © 2009, Clarence Byrd Inc. 43
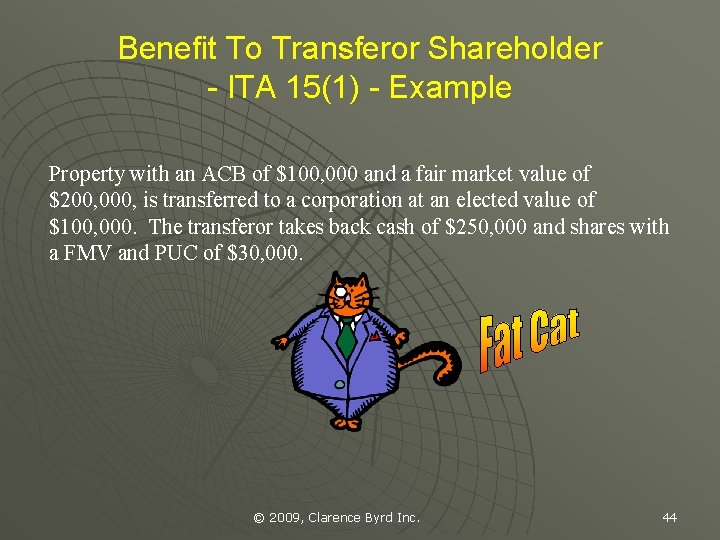
Benefit To Transferor Shareholder - ITA 15(1) - Example Property with an ACB of $100, 000 and a fair market value of $200, 000, is transferred to a corporation at an elected value of $100, 000. The transferor takes back cash of $250, 000 and shares with a FMV and PUC of $30, 000. © 2009, Clarence Byrd Inc. 44
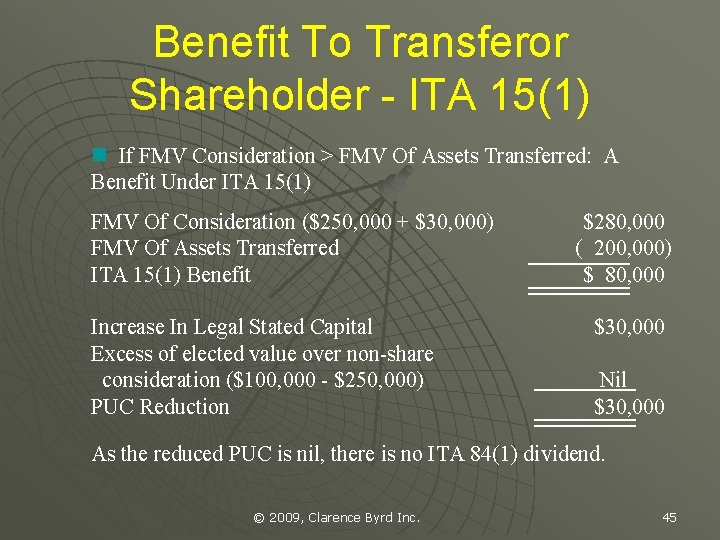
Benefit To Transferor Shareholder - ITA 15(1) n If FMV Consideration > FMV Of Assets Transferred: A Benefit Under ITA 15(1) FMV Of Consideration ($250, 000 + $30, 000) FMV Of Assets Transferred ITA 15(1) Benefit Increase In Legal Stated Capital Excess of elected value over non-share consideration ($100, 000 - $250, 000) PUC Reduction $280, 000 ( 200, 000) $ 80, 000 $30, 000 Nil $30, 000 As the reduced PUC is nil, there is no ITA 84(1) dividend. © 2009, Clarence Byrd Inc. 45
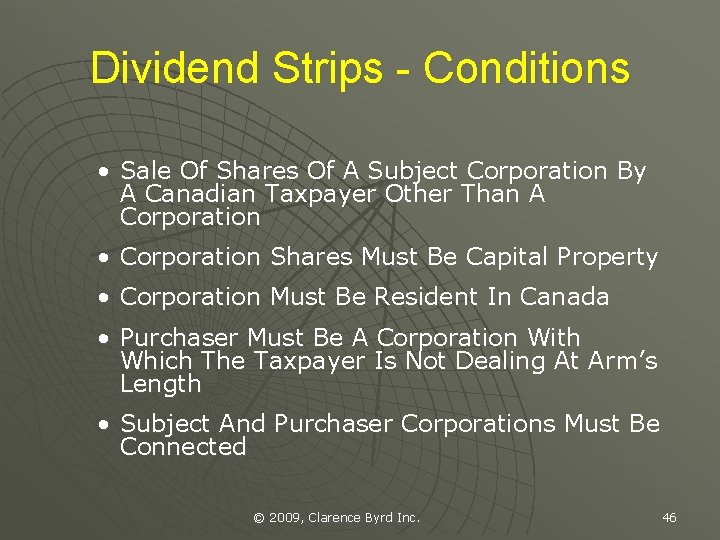
Dividend Strips - Conditions • Sale Of Shares Of A Subject Corporation By A Canadian Taxpayer Other Than A Corporation • Corporation Shares Must Be Capital Property • Corporation Must Be Resident In Canada • Purchaser Must Be A Corporation With Which The Taxpayer Is Not Dealing At Arm’s Length • Subject And Purchaser Corporations Must Be Connected © 2009, Clarence Byrd Inc. 46
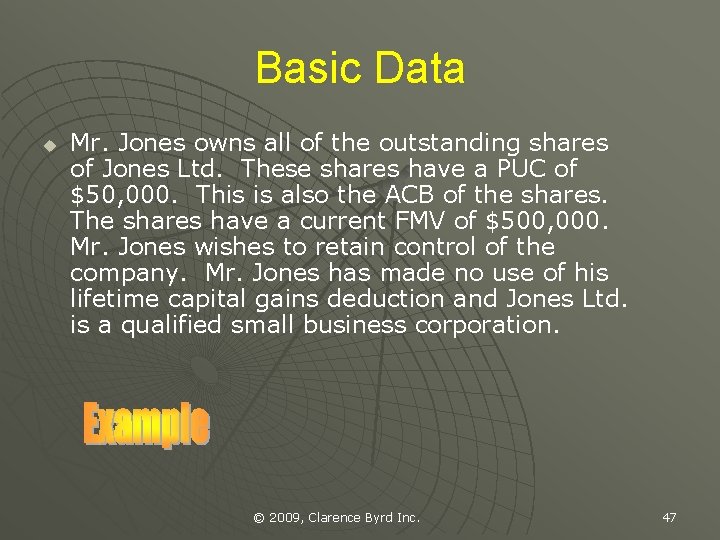
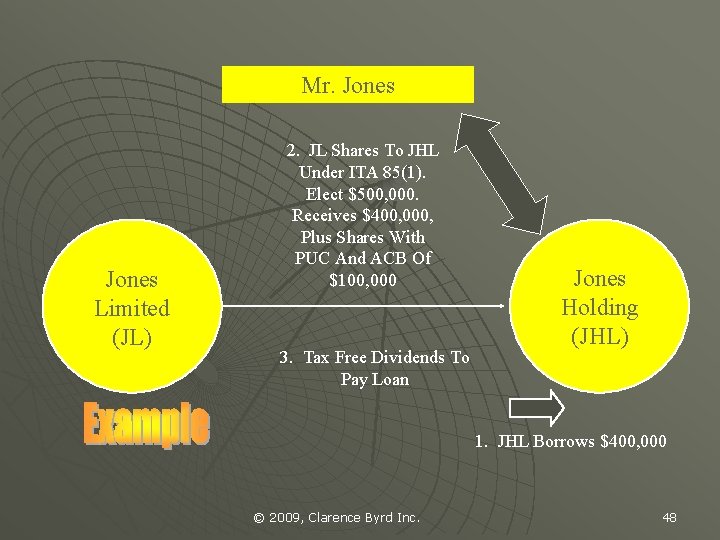
Basic Data u Mr. Jones owns all of the outstanding shares of Jones Ltd. These shares have a PUC of $50, 000. This is also the ACB of the shares. The shares have a current FMV of $500, 000. Mr. Jones wishes to retain control of the company. Mr. Jones has made no use of his lifetime capital gains deduction and Jones Ltd. is a qualified small business corporation. © 2009, Clarence Byrd Inc. 47
Mr. Jones Limited (JL) 2. JL Shares To JHL Under ITA 85(1). Elect $500, 000. Receives $400, 000, Plus Shares With PUC And ACB Of $100, 000 3. Tax Free Dividends To Pay Loan Jones Holding (JHL) 1. JHL Borrows $400, 000 © 2009, Clarence Byrd Inc. 48
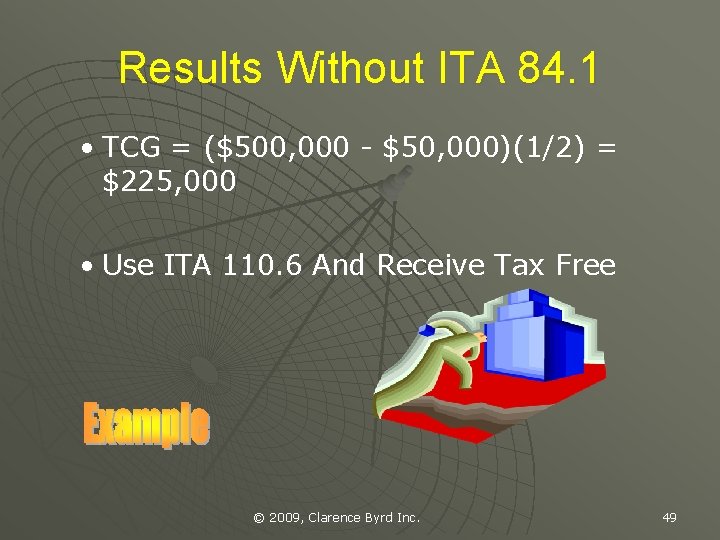
Results Without ITA 84. 1 • TCG = ($500, 000 - $50, 000)(1/2) = $225, 000 • Use ITA 110. 6 And Receive Tax Free © 2009, Clarence Byrd Inc. 49
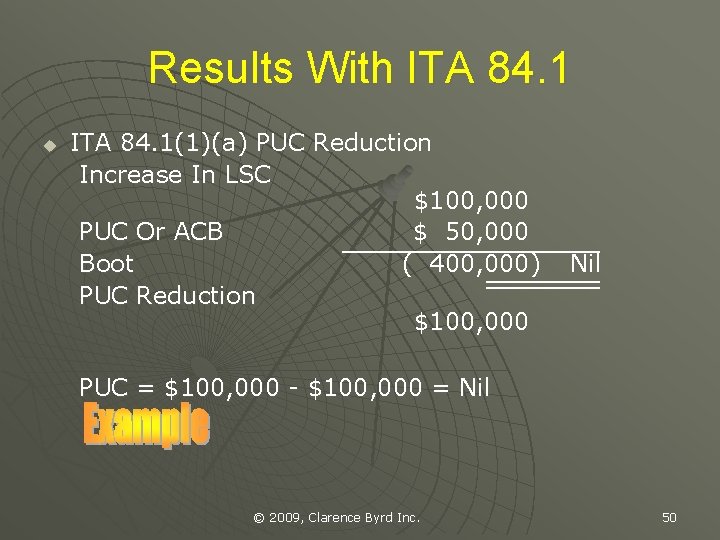
Results With ITA 84. 1 u ITA 84. 1(1)(a) PUC Reduction Increase In LSC $100, 000 PUC Or ACB $ 50, 000 Boot ( 400, 000) PUC Reduction $100, 000 Nil PUC = $100, 000 - $100, 000 = Nil © 2009, Clarence Byrd Inc. 50
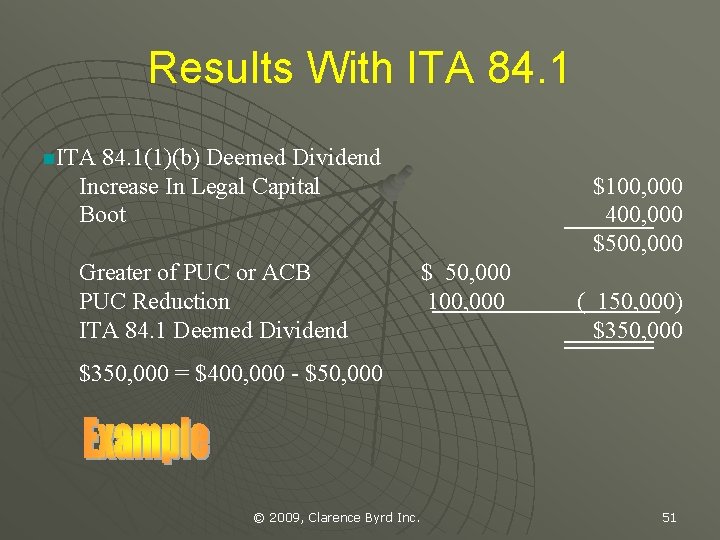
Results With ITA 84. 1 n. ITA 84. 1(1)(b) Deemed Dividend Increase In Legal Capital Boot Greater of PUC or ACB PUC Reduction ITA 84. 1 Deemed Dividend $100, 000 400, 000 $500, 000 $ 50, 000 100, 000 ( 150, 000) $350, 000 = $400, 000 - $50, 000 © 2009, Clarence Byrd Inc. 51
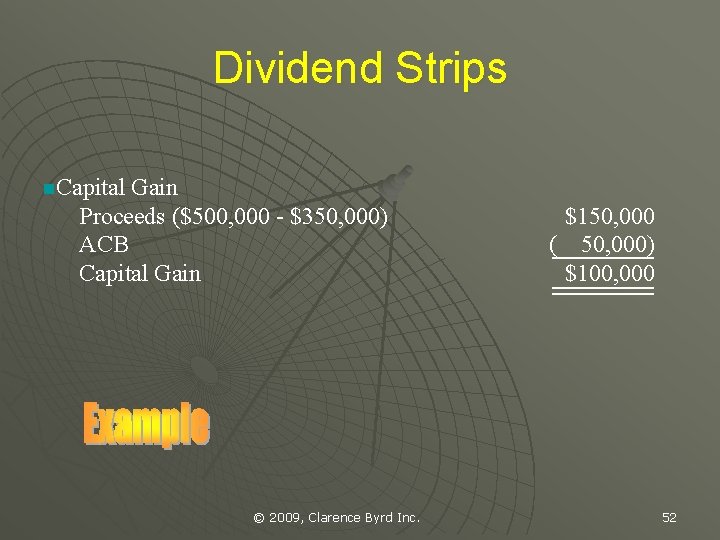
Dividend Strips n. Capital Gain Proceeds ($500, 000 - $350, 000) ACB Capital Gain © 2009, Clarence Byrd Inc. $150, 000 ( 50, 000) $100, 000 52
Capital Gains Strips - Conditions u u Deductible Dividends A Component Of An Arm’s Length Disposition Of Shares Objective To Convert Capital Gain To Dividend © 2009, Clarence Byrd Inc. 53
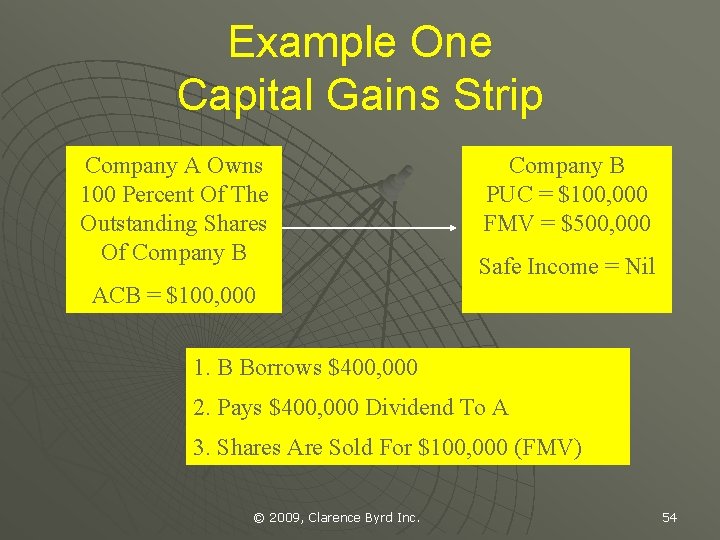
Example One Capital Gains Strip Company A Owns 100 Percent Of The Outstanding Shares Of Company B PUC = $100, 000 FMV = $500, 000 Safe Income = Nil ACB = $100, 000 1. B Borrows $400, 000 2. Pays $400, 000 Dividend To A 3. Shares Are Sold For $100, 000 (FMV) © 2009, Clarence Byrd Inc. 54
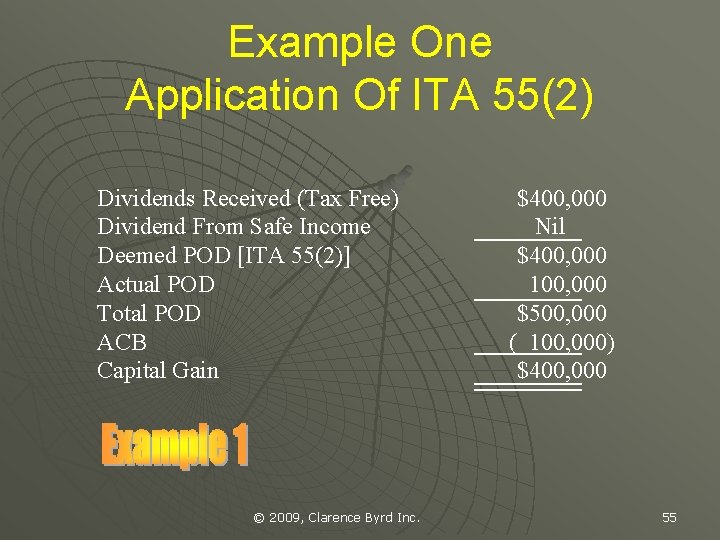
Example One Application Of ITA 55(2) Dividends Received (Tax Free) Dividend From Safe Income Deemed POD [ITA 55(2)] Actual POD Total POD ACB Capital Gain © 2009, Clarence Byrd Inc. $400, 000 Nil $400, 000 100, 000 $500, 000 ( 100, 000) $400, 000 55
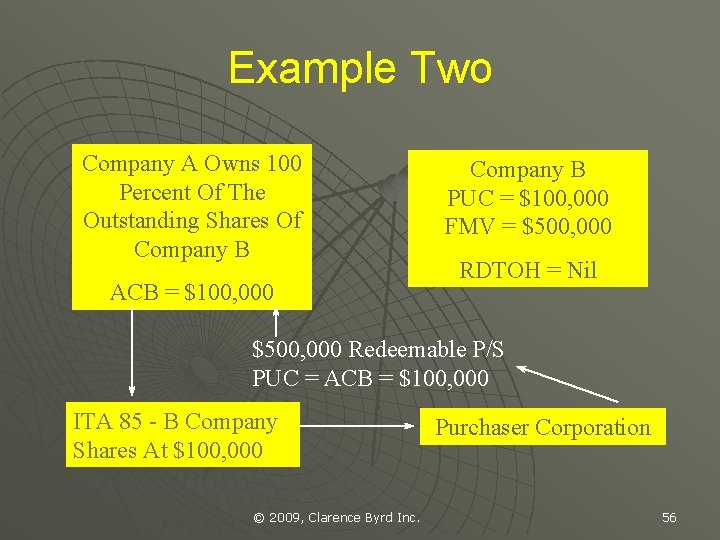
Example Two Company A Owns 100 Percent Of The Outstanding Shares Of Company B ACB = $100, 000 Company B PUC = $100, 000 FMV = $500, 000 RDTOH = Nil $500, 000 Redeemable P/S PUC = ACB = $100, 000 ITA 85 - B Company Shares At $100, 000 © 2009, Clarence Byrd Inc. Purchaser Corporation 56
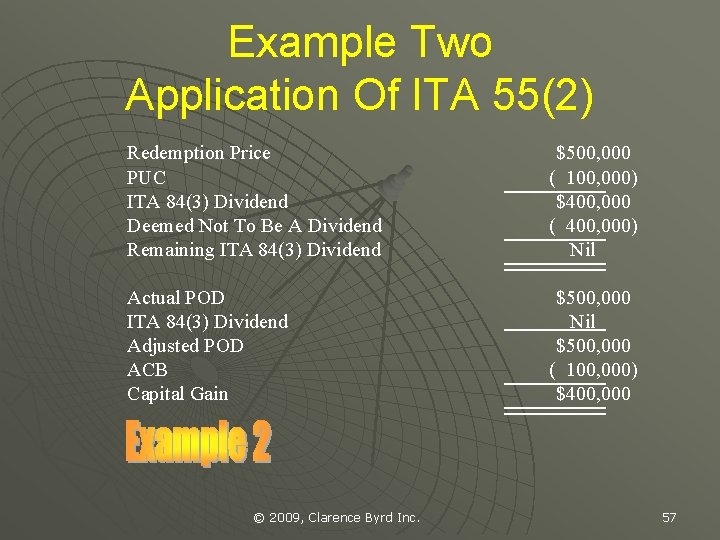
Example Two Application Of ITA 55(2) Redemption Price PUC ITA 84(3) Dividend Deemed Not To Be A Dividend Remaining ITA 84(3) Dividend $500, 000 ( 100, 000) $400, 000 ( 400, 000) Nil Actual POD ITA 84(3) Dividend Adjusted POD ACB Capital Gain $500, 000 Nil $500, 000 ( 100, 000) $400, 000 © 2009, Clarence Byrd Inc. 57
© 2009, Clarence Byrd Inc. 58