Chapter 1 Introduction to Quantitative Analysis To accompany

- Slides: 29
Chapter 1 Introduction to Quantitative Analysis To accompany Quantitative Analysis for Management, Tenth Edition, by Render, Stair, and Hanna Power Point slides created by Jeff Heyl © 2008 Prentice-Hall, Inc. © 2009 Prentice-Hall, Inc.
Introduction n Mathematical tools have been used for thousands of years n Quantitative analysis can be applied to a wide variety of problems n It’s not enough to just know the mathematics of a technique n One must understand the specific applicability of the technique, its limitations, and its assumptions © 2009 Prentice-Hall, Inc. 1– 2
Need for Operations Management n The increased complexity of running a successful business. n Lots of information, but no decisions. n A large nationwide bank is using OM techniques to configure complicated financial instruments for their customers. n A major retail enterprise is using OM methodology for making decisions about customer relationship management (CRM). © 2009 Prentice-Hall, Inc. 1– 3
Examples of Quantitative Analyses n Taco Bell saved over $150 million using forecasting and scheduling quantitative analysis models n NBC television increased revenues by over $200 million by using quantitative analysis to develop better sales plans n Continental Airlines saved over $40 million using quantitative analysis models to quickly recover from weather delays and other disruptions © 2009 Prentice-Hall, Inc. 1– 4
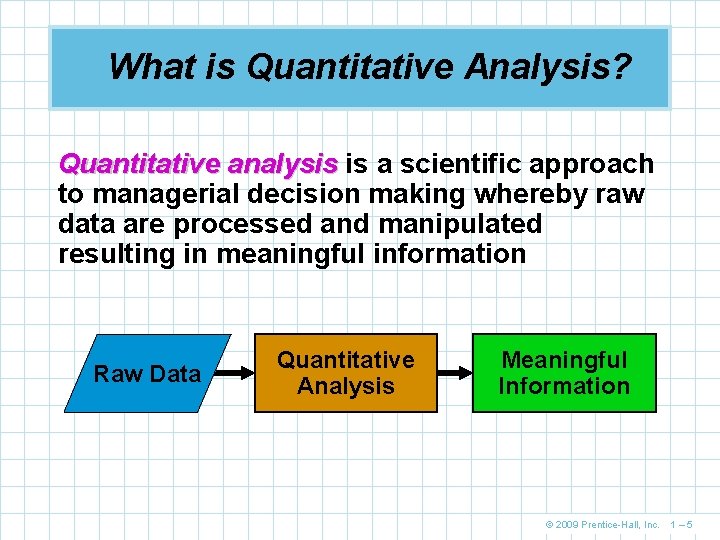
What is Quantitative Analysis? Quantitative analysis is a scientific approach to managerial decision making whereby raw data are processed and manipulated resulting in meaningful information Raw Data Quantitative Analysis Meaningful Information © 2009 Prentice-Hall, Inc. 1– 5
What is Quantitative Analysis? Quantitative factors might be different investment alternatives, interest rates, inventory levels, demand, or labor cost Qualitative factors such as the weather, state and federal legislation, and technology breakthroughs should also be considered n Information may be difficult to quantify but can affect the decision-making process © 2009 Prentice-Hall, Inc. 1– 6
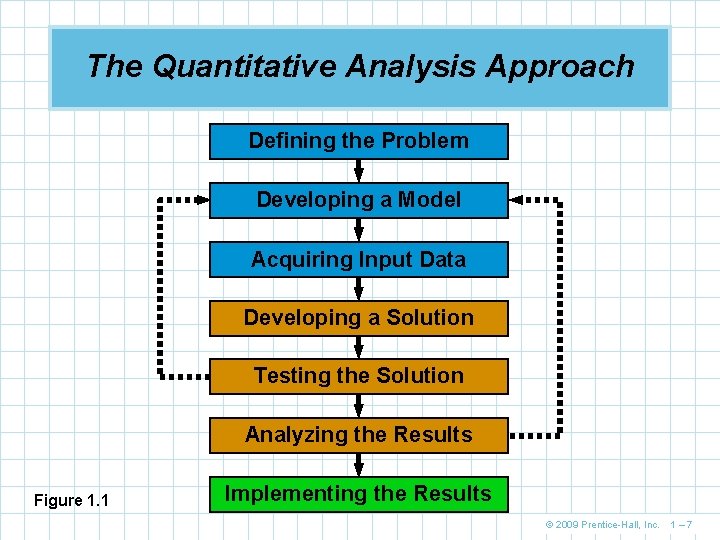
The Quantitative Analysis Approach Defining the Problem Developing a Model Acquiring Input Data Developing a Solution Testing the Solution Analyzing the Results Figure 1. 1 Implementing the Results © 2009 Prentice-Hall, Inc. 1– 7
Defining the Problem Need to develop a clear and concise statement that gives direction and meaning to the following steps n This may be the most important and difficult step n It is essential to go beyond symptoms and identify true causes n May be necessary to concentrate on only a few of the problems – selecting the right problems is very important n Specific and measurable objectives may have to be developed © 2009 Prentice-Hall, Inc. 1– 8
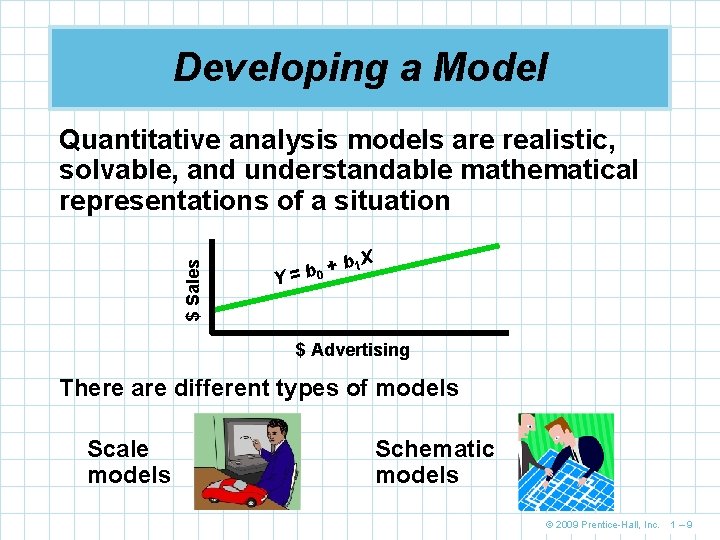
Developing a Model $ Sales Quantitative analysis models are realistic, solvable, and understandable mathematical representations of a situation b 1 X + b 0 Y= $ Advertising There are different types of models Scale models Schematic models © 2009 Prentice-Hall, Inc. 1– 9
Developing a Model n Models generally contain variables (controllable and uncontrollable) and parameters n Controllable variables are generally the decision variables and are generally unknown n Parameters are known quantities that are a part of the problem © 2009 Prentice-Hall, Inc. 1 – 10
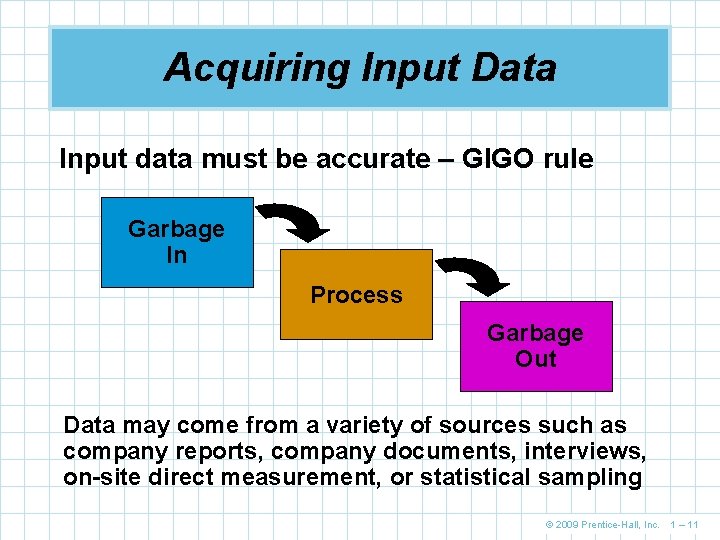
Acquiring Input Data Input data must be accurate – GIGO rule Garbage In Process Garbage Out Data may come from a variety of sources such as company reports, company documents, interviews, on-site direct measurement, or statistical sampling © 2009 Prentice-Hall, Inc. 1 – 11
Developing a Solution n The best (optimal) solution to a problem is found by manipulating the model variables until a solution is found that is practical and can be implemented n Common techniques are n Solving equations n Trial and error – trying various approaches and picking the best result n Complete enumeration – trying all possible values n Using an algorithm – a series of repeating steps to reach a solution © 2009 Prentice-Hall, Inc. 1 – 12
Testing the Solution Both input data and the model should be tested for accuracy before analysis and implementation n New data can be collected to test the model n Results should be logical, consistent, and represent the real situation © 2009 Prentice-Hall, Inc. 1 – 13
Analyzing the Results Determine the implications of the solution n Implementing results often requires change in an organization n The impact of actions or changes needs to be studied and understood before implementation Sensitivity analysis determines how much the results of the analysis will change if the model or input data changes n Sensitive models should be very thoroughly tested © 2009 Prentice-Hall, Inc. 1 – 14
Implementing the Results Implementation incorporates the solution into the company n Implementation can be very difficult n People can resist changes n Many quantitative analysis efforts have failed because a good, workable solution was not properly implemented Changes occur over time, so even successful implementations must be monitored to determine if modifications are necessary © 2009 Prentice-Hall, Inc. 1 – 15
Modeling in the Real World Quantitative analysis models are used extensively by real organizations to solve real problems n In the real world, quantitative analysis models can be complex, expensive, and difficult to sell n Following the steps in the process is an important component of success © 2009 Prentice-Hall, Inc. 1 – 16
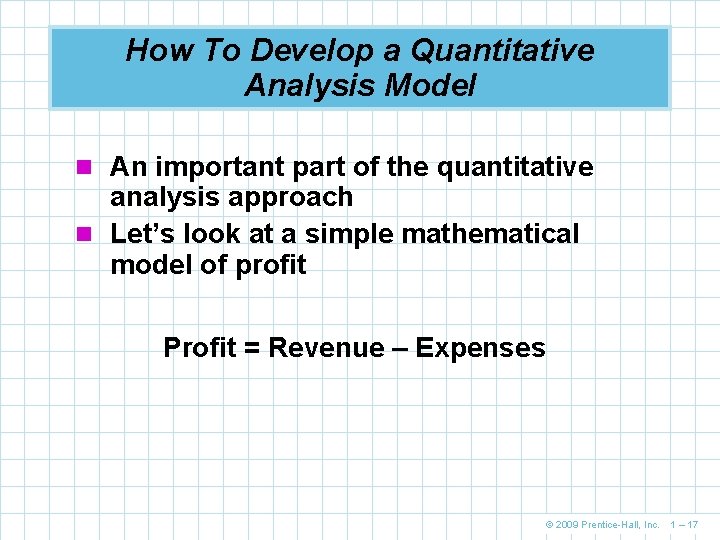
How To Develop a Quantitative Analysis Model n An important part of the quantitative analysis approach n Let’s look at a simple mathematical model of profit Profit = Revenue – Expenses © 2009 Prentice-Hall, Inc. 1 – 17
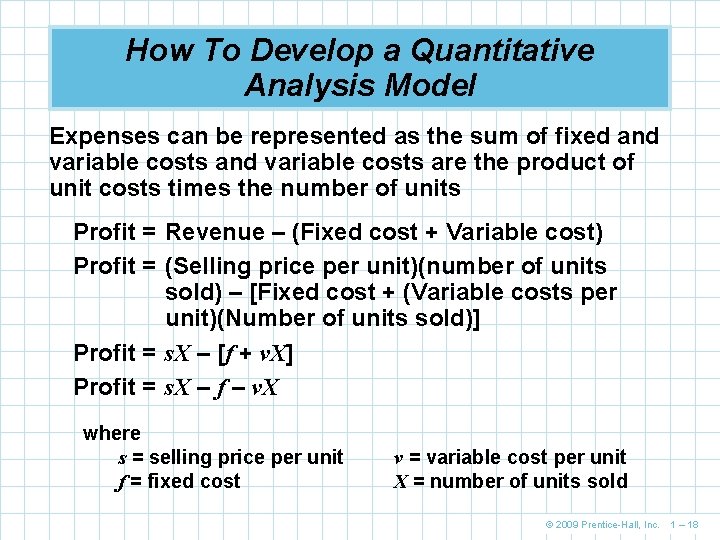
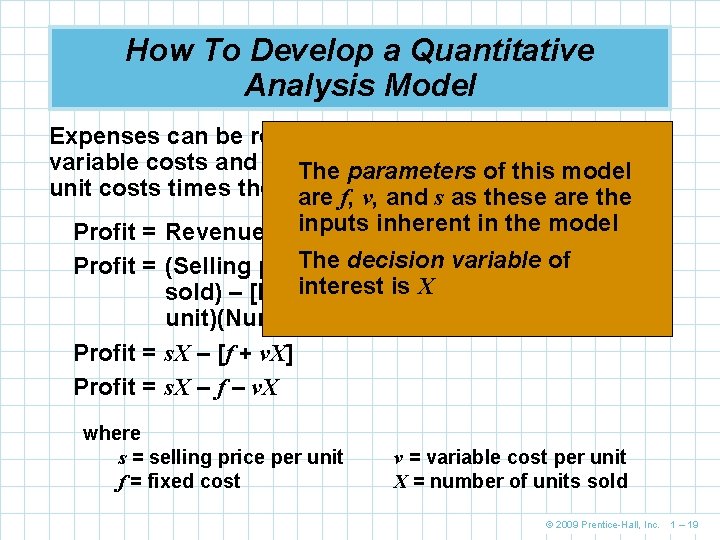
How To Develop a Quantitative Analysis Model Expenses can be represented as the sum of fixed and variable costs are the product of unit costs times the number of units Profit = Revenue – (Fixed cost + Variable cost) Profit = (Selling price per unit)(number of units sold) – [Fixed cost + (Variable costs per unit)(Number of units sold)] Profit = s. X – [f + v. X] Profit = s. X – f – v. X where s = selling price per unit f = fixed cost v = variable cost per unit X = number of units sold © 2009 Prentice-Hall, Inc. 1 – 18
How To Develop a Quantitative Analysis Model Expenses can be represented as the sum of fixed and variable costs are the product of The parameters of this model unit costs times the number units are f, v, of and s as these are the inputscost inherent in the cost) model Profit = Revenue – (Fixed + Variable The decision variable Profit = (Selling price per unit)(number of of units interest X sold) – [Fixed cost +is(Variable costs per unit)(Number of units sold)] Profit = s. X – [f + v. X] Profit = s. X – f – v. X where s = selling price per unit f = fixed cost v = variable cost per unit X = number of units sold © 2009 Prentice-Hall, Inc. 1 – 19
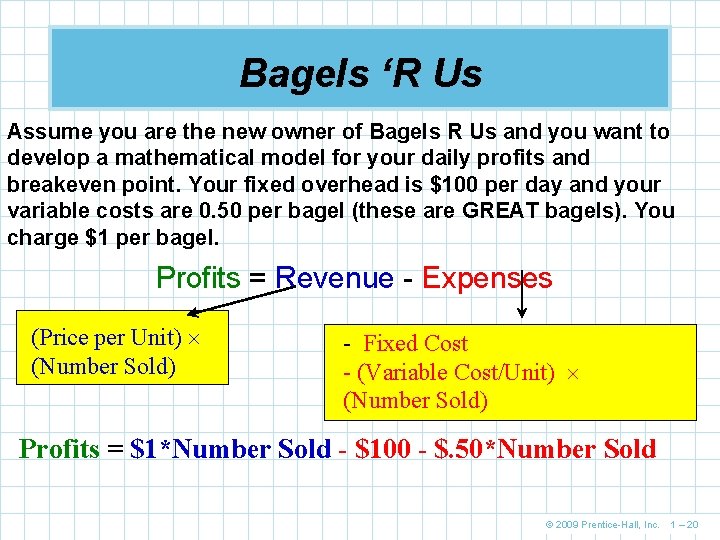
Bagels ‘R Us Assume you are the new owner of Bagels R Us and you want to develop a mathematical model for your daily profits and breakeven point. Your fixed overhead is $100 per day and your variable costs are 0. 50 per bagel (these are GREAT bagels). You charge $1 per bagel. Profits = Revenue - Expenses (Price per Unit) (Number Sold) - Fixed Cost - (Variable Cost/Unit) (Number Sold) Profits = $1*Number Sold - $100 - $. 50*Number Sold © 2009 Prentice-Hall, Inc. 1 – 20
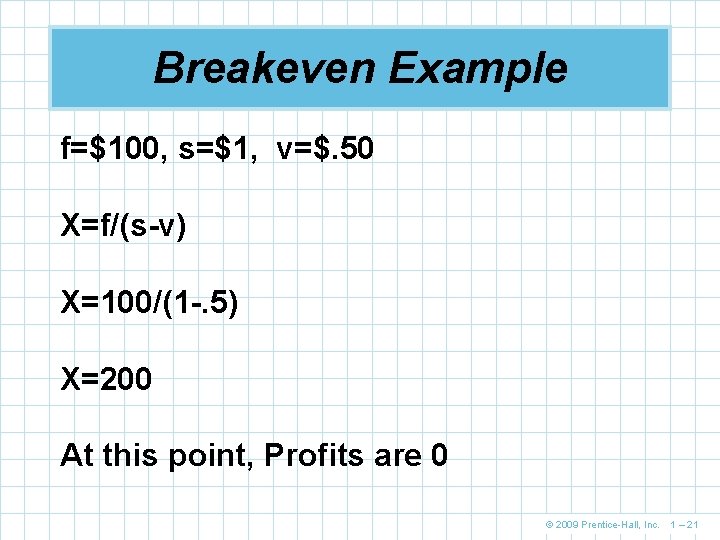
Breakeven Example f=$100, s=$1, v=$. 50 X=f/(s-v) X=100/(1 -. 5) X=200 At this point, Profits are 0 © 2009 Prentice-Hall, Inc. 1 – 21
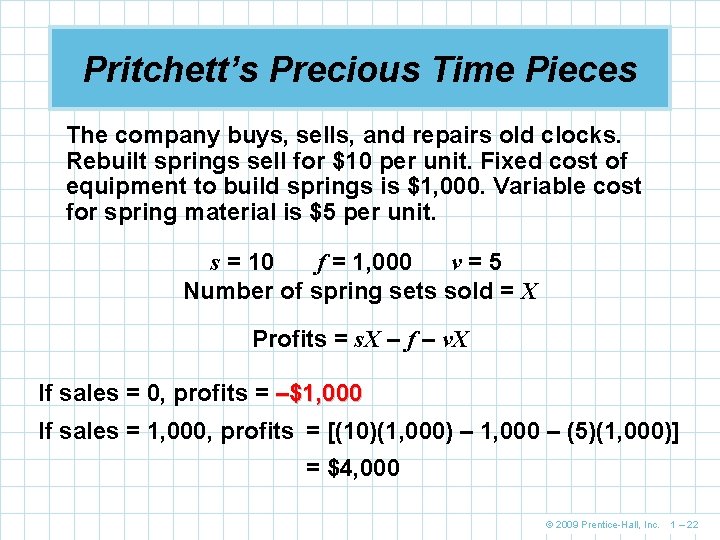
Pritchett’s Precious Time Pieces The company buys, sells, and repairs old clocks. Rebuilt springs sell for $10 per unit. Fixed cost of equipment to build springs is $1, 000. Variable cost for spring material is $5 per unit. s = 10 f = 1, 000 v=5 Number of spring sets sold = X Profits = s. X – f – v. X If sales = 0, profits = –$1, 000 If sales = 1, 000, profits = [(10)(1, 000) – 1, 000 – (5)(1, 000)] = $4, 000 © 2009 Prentice-Hall, Inc. 1 – 22
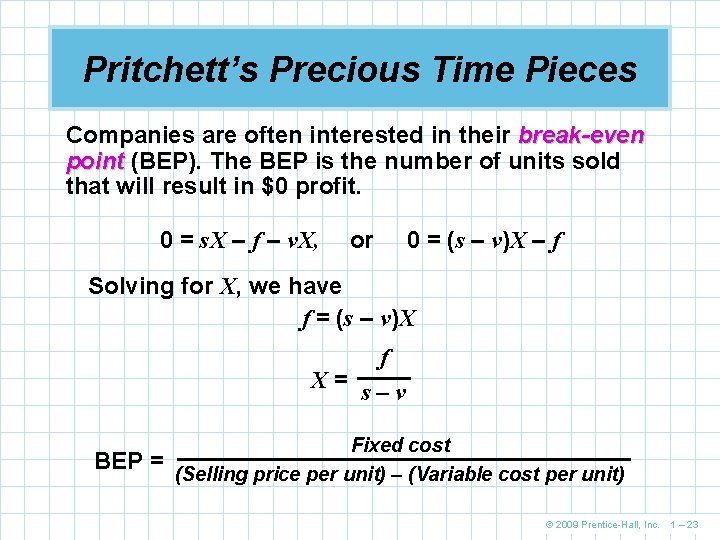
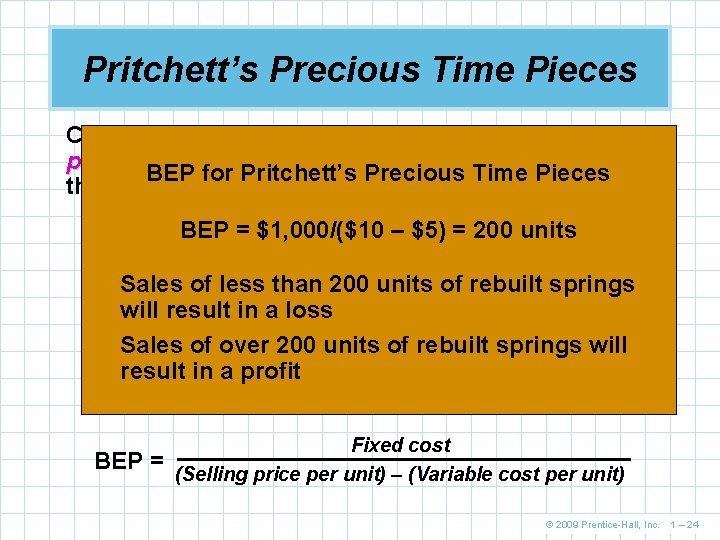
Pritchett’s Precious Time Pieces Companies are often interested in their break-even point (BEP). The BEP is the number of units sold that will result in $0 profit. 0 = s. X – f – v. X, or 0 = (s – v)X – f Solving for X, we have f = (s – v)X f X= s–v BEP = Fixed cost (Selling price per unit) – (Variable cost per unit) © 2009 Prentice-Hall, Inc. 1 – 23
Pritchett’s Precious Time Pieces Companies are often interested in their break-even point (BEP). The BEP is the number of units sold BEP for Pritchett’s Precious Time Pieces that will result in $0 profit. BEP = – 200 0= s. X –= f$1, 000/($10 – v. X, or – 0$5) = (s v)Xunits –f Salesfor of less 200 units of rebuilt springs Solving X, wethan have will result in a loss f = (s – v)X Sales of over 200 units of rebuilt springs will f result in a profit X = s–v BEP = Fixed cost (Selling price per unit) – (Variable cost per unit) © 2009 Prentice-Hall, Inc. 1 – 24
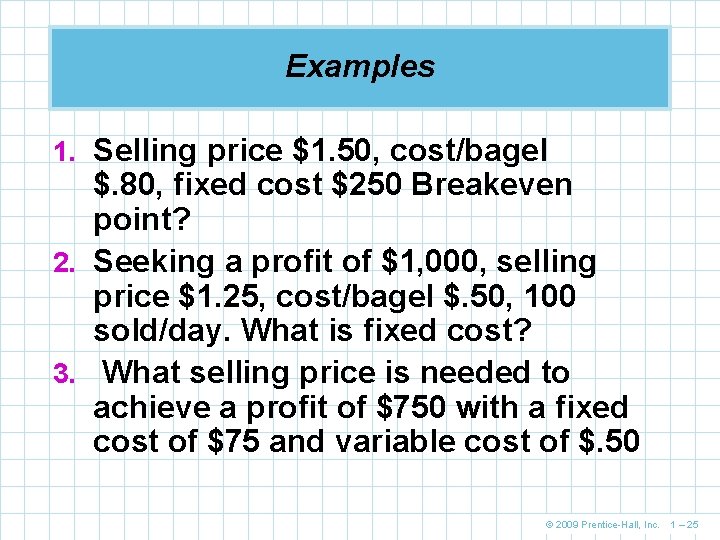
Examples 1. Selling price $1. 50, cost/bagel $. 80, fixed cost $250 Breakeven point? 2. Seeking a profit of $1, 000, selling price $1. 25, cost/bagel $. 50, 100 sold/day. What is fixed cost? 3. What selling price is needed to achieve a profit of $750 with a fixed cost of $75 and variable cost of $. 50 © 2009 Prentice-Hall, Inc. 1 – 25
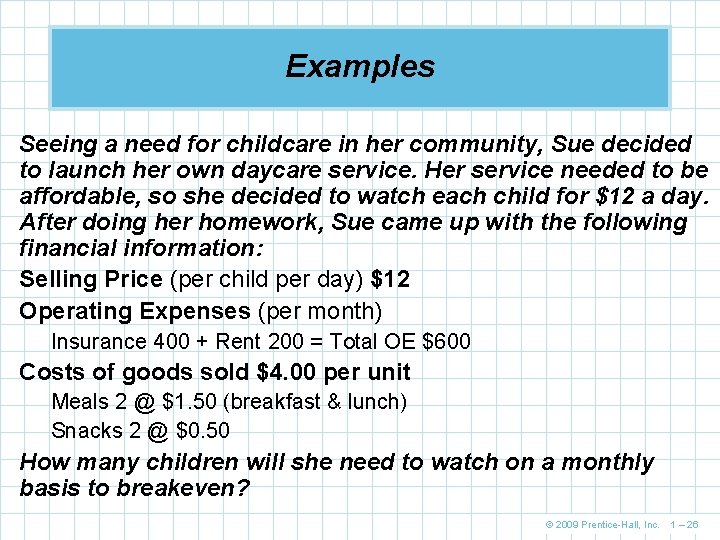
Examples Seeing a need for childcare in her community, Sue decided to launch her own daycare service. Her service needed to be affordable, so she decided to watch each child for $12 a day. After doing her homework, Sue came up with the following financial information: Selling Price (per child per day) $12 Operating Expenses (per month) Insurance 400 + Rent 200 = Total OE $600 Costs of goods sold $4. 00 per unit Meals 2 @ $1. 50 (breakfast & lunch) Snacks 2 @ $0. 50 How many children will she need to watch on a monthly basis to breakeven? © 2009 Prentice-Hall, Inc. 1 – 26
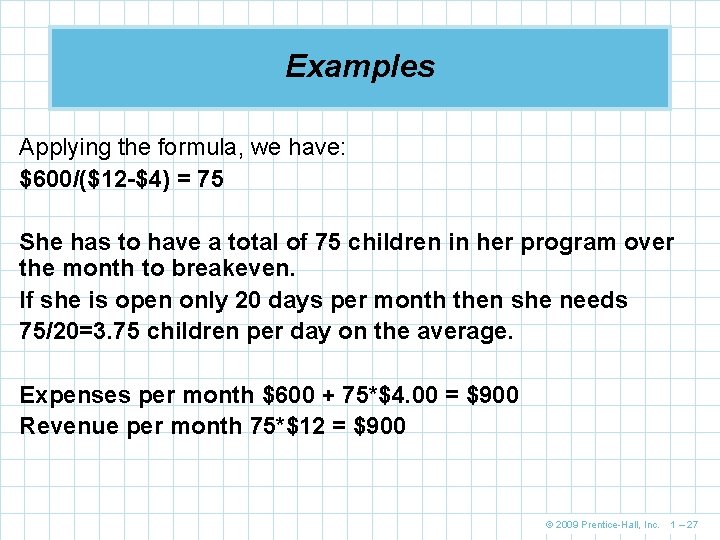
Examples Applying the formula, we have: $600/($12 -$4) = 75 She has to have a total of 75 children in her program over the month to breakeven. If she is open only 20 days per month then she needs 75/20=3. 75 children per day on the average. Expenses per month $600 + 75*$4. 00 = $900 Revenue per month 75*$12 = $900 © 2009 Prentice-Hall, Inc. 1 – 27
Advantages of Mathematical Modeling 1. Models can accurately represent reality 2. Models can help a decision maker 3. 4. 5. 6. formulate problems Models can give us insight and information Models can save time and money in decision making and problem solving A model may be the only way to solve large or complex problems in a timely fashion A model can be used to communicate problems and solutions to others © 2009 Prentice-Hall, Inc. 1 – 28
Models Categorized by Risk n Mathematical models that do not involve risk are called deterministic models n We know all the values used in the model with complete certainty n Mathematical models that involve risk, chance, or uncertainty are called probabilistic models n Values used in the model are estimates based on probabilities © 2009 Prentice-Hall, Inc. 1 – 29