PENSIONS DIVORCE A PRACTICAL GUIDE This is for
- Slides: 37
PENSIONS & DIVORCE A PRACTICAL GUIDE This is for financial adviser use only and shouldn’t be relied upon by any other person.
PENSIONS & DIVORCE OBJECTIVES By the end of this session, attendees will be able to: • Understand the divorce process and the options available for pensions in a divorce settlement • Explain the impact of pension freedoms on pensions and divorce • Consider the issues facing clients and solicitor connections in relation to pensions and divorce. 2
PENSIONS & DIVORCE DISCLAIMERS We will assume: Divorcees are subject to English Law… No conflict of interest One party has the larger pension assets… And that it’s always the bloke’s fault in an opposite sex marriage…
PENSIONS & DIVORCE PART 1 BACKGROUND
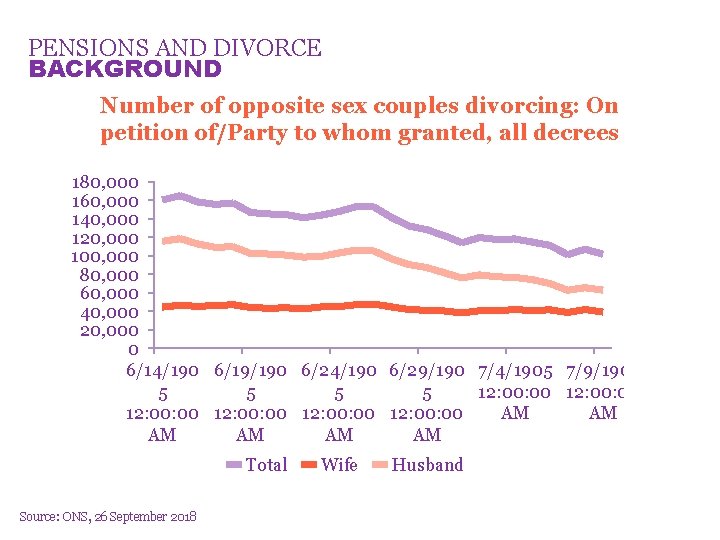
PENSIONS AND DIVORCE BACKGROUND Number of opposite sex couples divorcing: On petition of/Party to whom granted, all decrees 180, 000 160, 000 140, 000 120, 000 100, 000 80, 000 60, 000 40, 000 20, 000 0 6/14/190 6/19/190 6/24/190 6/29/190 7/4/1905 7/9/1905 5 5 12: 00: 00 12: 00: 00 AM AM AM Total Source: ONS, 26 September 2018 Wife Husband
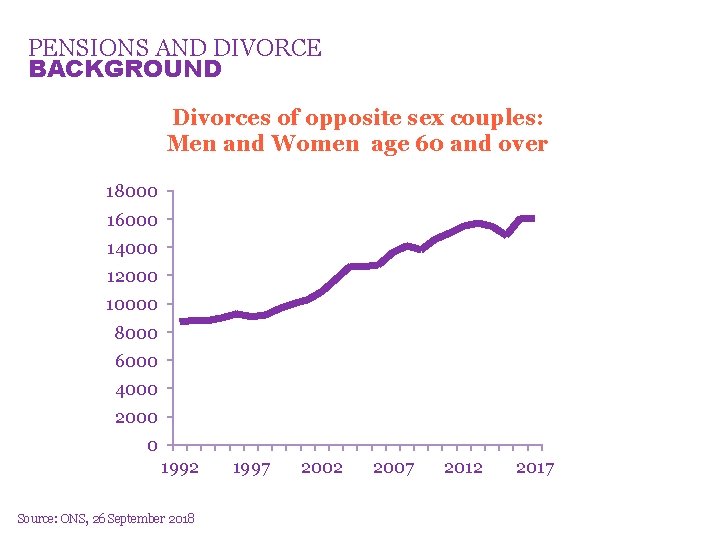
PENSIONS AND DIVORCE BACKGROUND Divorces of opposite sex couples: Men and Women age 60 and over 18000 16000 14000 12000 10000 8000 6000 4000 2000 0 1992 Source: ONS, 26 September 2018 1997 2002 2007 2012 2017
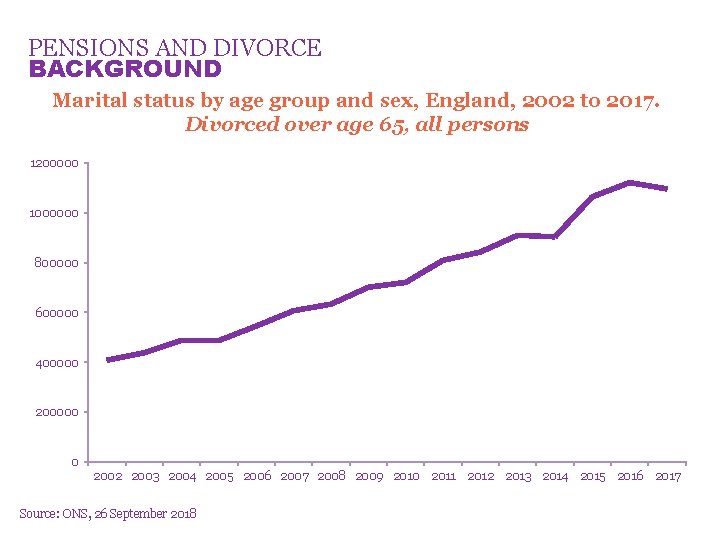
PENSIONS AND DIVORCE BACKGROUND Marital status by age group and sex, England, 2002 to 2017. Divorced over age 65, all persons 1200000 1000000 800000 600000 400000 200000 0 2002 2003 2004 2005 2006 2007 2008 2009 2010 Source: ONS, 26 September 2018 2011 2012 2013 2014 2015 2016 2017
PENSIONS AND DIVORCE BACKGROUND Almost all (92%) of the brides and grooms aged 65 and over in 2014 were Planning Point: divorcees, Make widows widowers, with sure anyor divorcees have reviewed/changed any only 8% getting married nomination for the first time. Source: ONS
PENSIONS AND DIVORCE THE MARKET “Nearly one quarter of a million people face divorce in the UK each year, with the majority needing financial assistance. Yet there are just 42 accredited financial adviser specialists in family law – that’s one adviser for every 5, 000 people. ” Source: Resolution with the Personal Finance Society “Unlock the divorce and separation market”
PENSIONS & DIVORCE BACKGROUND Griffiths v Dawson & Co (1993) • Dawson & Co failed to include Pension Assets • Mrs Griffiths successfully sued her lawyer • Pensions Act 1995 – Pensions must be included when assessing assets
PENSIONS & DIVORCE PART 2 THE LEGAL PROCESS
PENSIONS & DIVORCE THE LEGAL PROCESS Irretrievable breakdown: • 5 criteria: adultery unreasonable behaviour desertion two years separation + consent 5 years separation without consent • The reason for the divorce does not affect the financial settlement • 2 separate legal processes…dissolution and financial remedy
PENSIONS & DIVORCE THE LEGAL PROCESS Dissolution Ø Court order Ø Collaborative Law Ø Mediation Ø Online – does NOT include financial remedy! Financial remedy Ø Kids’ needs first Ø Clean break, 50/50 split preferred
PENSIONS & DIVORCE PART 3 PENSION OPTIONS
PENSIONS & DIVORCE ACTION POINTS 3 stages: 1 2 3 Find the pensions Value the pensions Decide how to split the pensions
PENSIONS & DIVORCE 1. FIND THE PENSIONS Factfind • Assets, liabilities and income for both parties • Can use Form E for voluntary disclosure • Required if full disclosure ordered by the Court 1
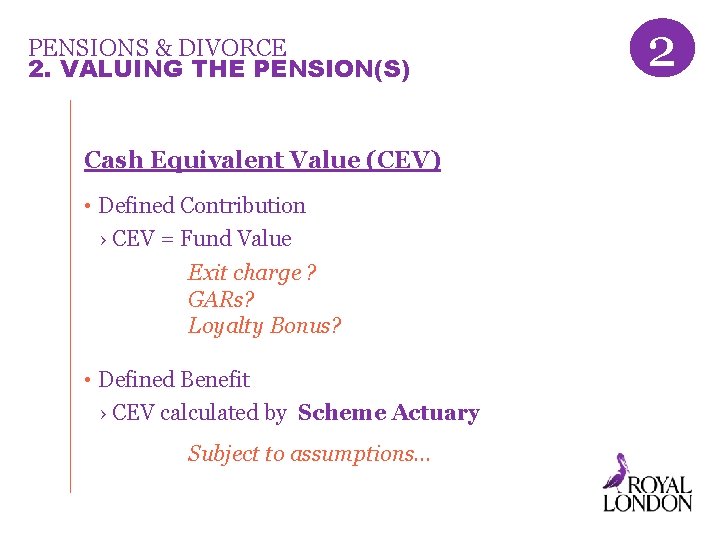
PENSIONS & DIVORCE 2. VALUING THE PENSION(S) Cash Equivalent Value (CEV) • Defined Contribution › CEV = Fund Value Exit charge ? GARs? Loyalty Bonus? • Defined Benefit › CEV calculated by Scheme Actuary Subject to assumptions… 2
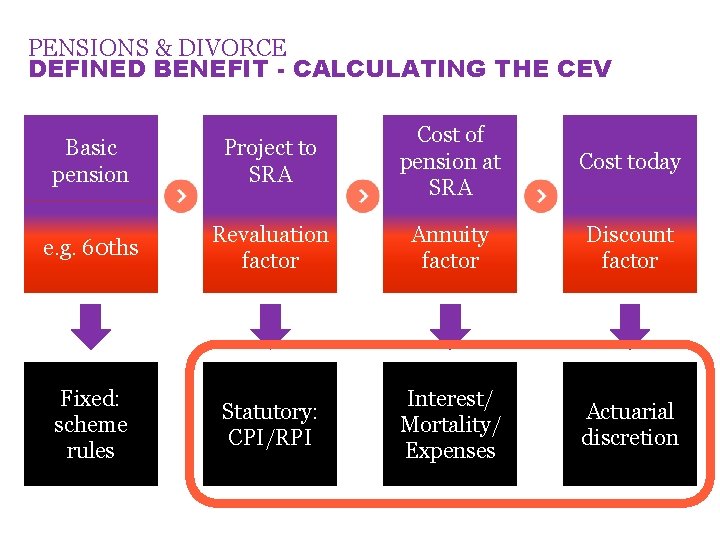
PENSIONS & DIVORCE DEFINED BENEFIT - CALCULATING THE CEV Basic pension Project to SRA Cost of pension at SRA Cost today e. g. 60 ths Revaluation factor Annuity factor Discount factor Fixed: scheme rules Statutory: CPI/RPI Interest/ Mortality/ Expenses Actuarial discretion
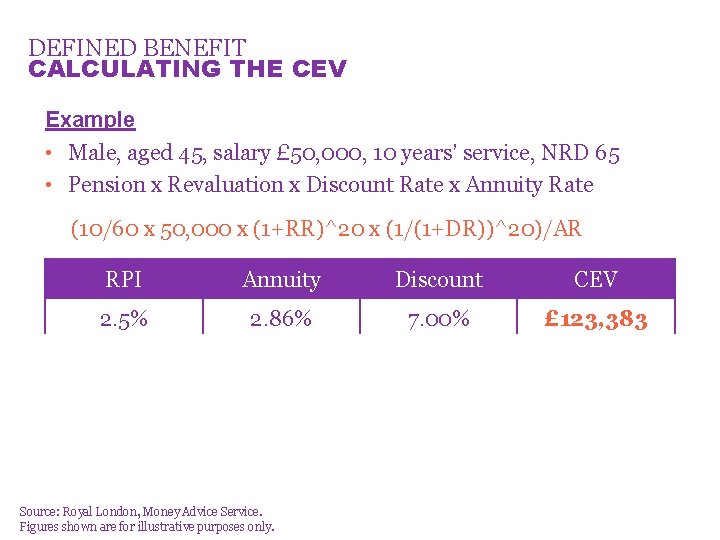
DEFINED BENEFIT CALCULATING THE CEV Example • Male, aged 45, salary £ 50, 000, 10 years’ service, NRD 65 • Pension x Revaluation x Discount Rate x Annuity Rate (10/60 x 50, 000 x (1+RR)^20 x (1/(1+DR))^20)/AR RPI Annuity Discount CEV 2. 5% 2. 86% 7. 00% £ 123, 383 2. 5% 2. 86% 6. 00% £ 148, 872 2. 5% 2. 166% 7. 00% £ 162, 915 2. 5% 2. 166% 6. 00% £ 196, 571 Source: Royal London, Money Advice Service. Figures shown are for illustrative purposes only.
PENSIONS AND DIVORCE UNIFORMED SERVICES & PUBLIC SECTOR Scheme CEV MCCV Difference Police £ 624, 000 £ 2, 125, 000 +240% Armed Forces’ (75) £ 301, 000 £ 587, 000 +95% Teachers’ (in payment) NHS Firefighters’ (in payment) Planning Point: £ 149, 600 £ 244, 000 Always consider independent +63% valuation for Armed Forces/Public £ 273, 300 £ 556, 000 +103% Sector schemes £ 756, 000 £ 1, 240, 000 +64% Source: Bradshaw Dixon & Moore Limited, “Cash Equivalent Values versus Market Consistent Capital Values”. Used with permission
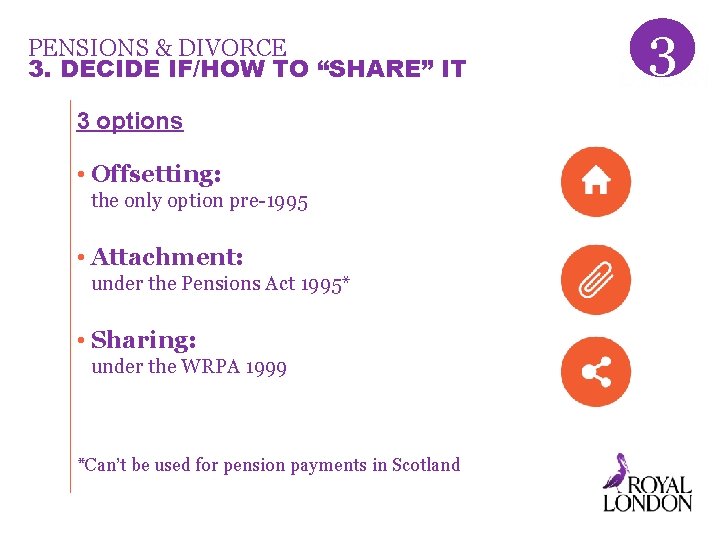
PENSIONS & DIVORCE 3. DECIDE IF/HOW TO “SHARE” IT 3 options • Offsetting: the only option pre-1995 • Attachment: under the Pensions Act 1995* • Sharing: under the WRPA 1999 *Can’t be used for pension payments in Scotland 3
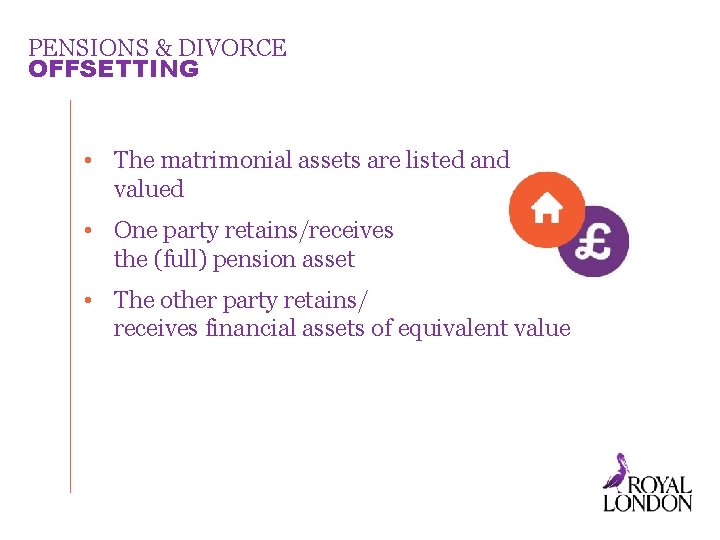
PENSIONS & DIVORCE OFFSETTING • The matrimonial assets are listed and valued • One party retains/receives the (full) pension asset • The other party retains/ receives financial assets of equivalent value
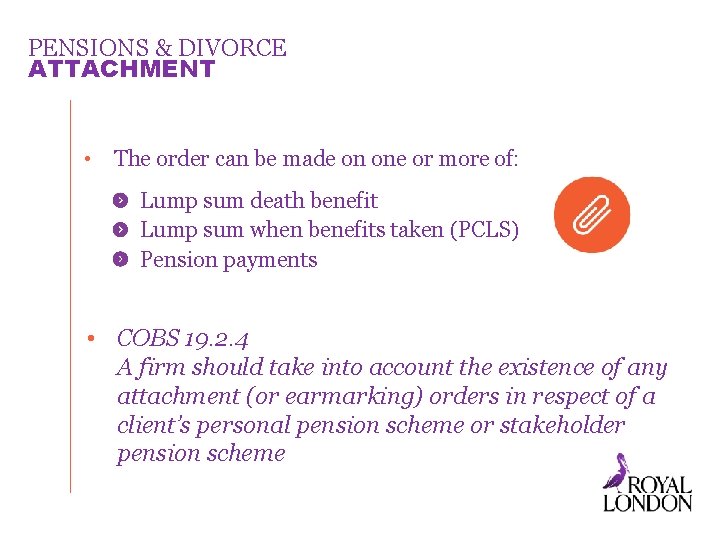
PENSIONS & DIVORCE ATTACHMENT • The order can be made on one or more of: Lump sum death benefit Lump sum when benefits taken (PCLS) Pension payments • COBS 19. 2. 4 A firm should take into account the existence of any attachment (or earmarking) orders in respect of a client’s personal pension scheme or stakeholder pension scheme
PENSIONS & DIVORCE THE EFFECT OF PENSION FREEDOM From 6/4/15 scheme members >55 can take their pension as a cash lump sum • Offsetting Provide ready cash Planning Point: Review any Pressure from spouses? pension attachment orders: Hiding of assets? Pension Freedoms • Attachment Member could cash out Need to revisit order?
PENSIONS & DIVORCE PART 4 PENSION SHARING
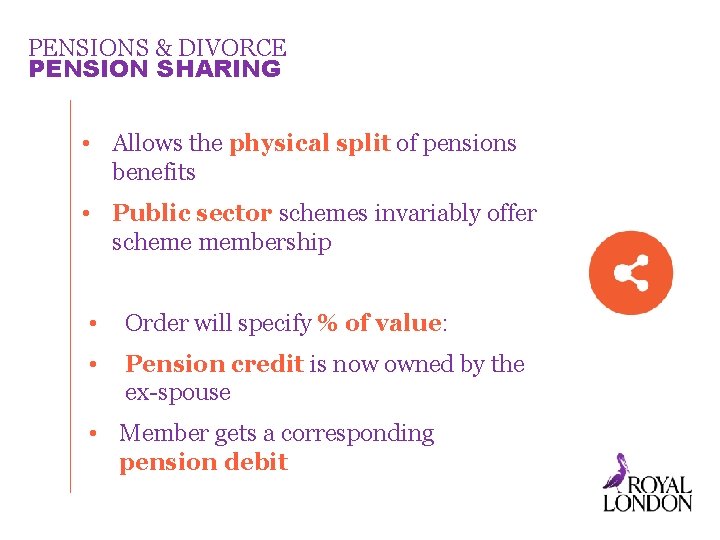
PENSIONS & DIVORCE PENSION SHARING • Allows the physical split of pensions benefits • Public sector schemes invariably offer scheme membership • Order will specify % of value: • Pension credit is now owned by the ex-spouse • Member gets a corresponding pension debit
PENSIONS & DIVORCE TAXATION – PENSION CREDITS Tax Aspect Effect of pension credit LTA Can be enhanced if credit is from pension in payment LTA IP 2014/16 Credit added on for LTA purposes Planning Point: LTA enhanced/FP 12/14/16 Protection lost if new money Where LTA purchase protection applies, scheme make sure the pension credit goes Annual Allowance None Lump sum protection to an existing scheme Only 25% available Pension in payment – No PCLS available: disqualifying pension credit • No UFPLS • Does not trigger MPAA
PENSIONS & DIVORCE PENSION DEBIT: TAXATION Tax Aspect Effect of pension debit LTA primary Primary protection factor reduced LTA IP 2014/16 Personalised LTA reduced LTA enhanced FP 12/14/16 None* Annual Allowance None but watch MPAA Planning Point: Not reduced What’s the most tax-efficient Pension in paymentway of rebuilding Might pay less tax assets? Lump sum protection * Protection will be lost where the member makes contributions or where benefit accrual in DB/cash balance schemes exceeds the ‘relevant percentage’
PENSIONS & DIVORCE PART 5 EXAMPLE CASE STUDIES
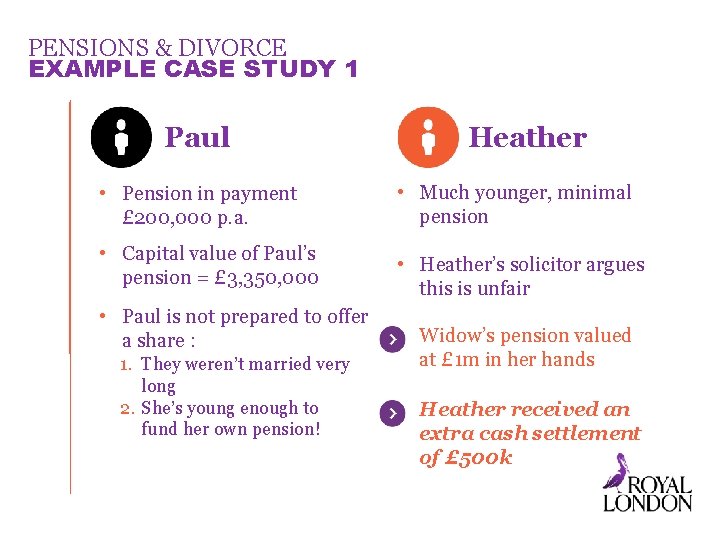
PENSIONS & DIVORCE EXAMPLE CASE STUDY 1 Paul • Pension in payment £ 200, 000 p. a. • Capital value of Paul’s pension = £ 3, 350, 000 • Paul is not prepared to offer a share : 1. They weren’t married very long 2. She’s young enough to fund her own pension! Heather • Much younger, minimal pension • Heather’s solicitor argues this is unfair • Widow’s pension valued at £ 1 m in her hands • Heather received an extra cash settlement of £ 500 k
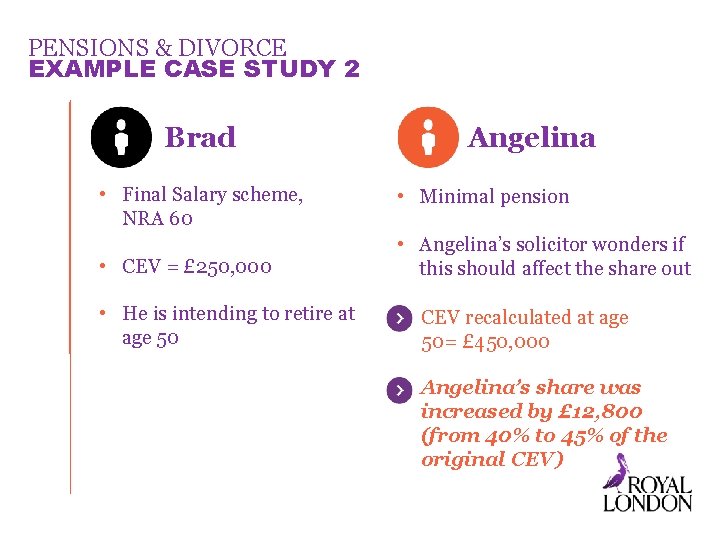
PENSIONS & DIVORCE EXAMPLE CASE STUDY 2 Brad • Final Salary scheme, NRA 60 Angelina • Minimal pension • CEV = £ 250, 000 • Angelina’s solicitor wonders if this should affect the share out • He is intending to retire at age 50 • CEV recalculated at age 50= £ 450, 000 • Angelina’s share was increased by £ 12, 800 (from 40% to 45% of the original CEV)
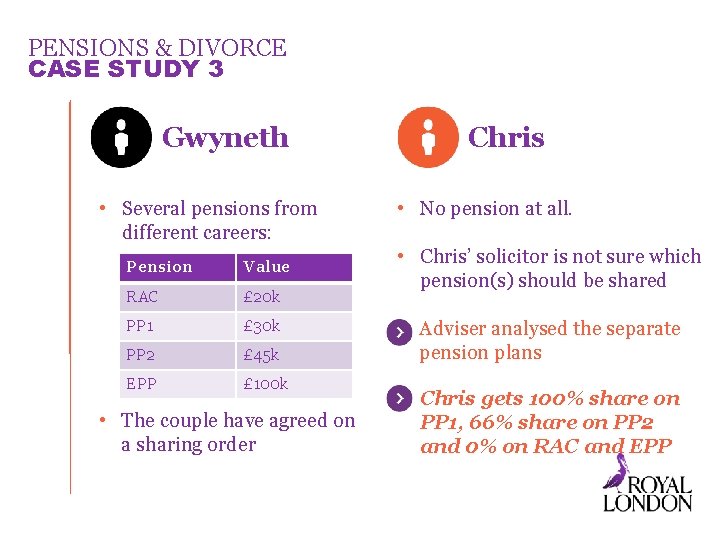
PENSIONS & DIVORCE CASE STUDY 3 Gwyneth • Several pensions from different careers: Pension Value RAC £ 20 k PP 1 £ 30 k PP 2 £ 45 k EPP £ 100 k • The couple have agreed on a sharing order Chris • No pension at all. • Chris’ solicitor is not sure which pension(s) should be shared • Adviser analysed the separate pension plans • Chris gets 100% share on PP 1, 66% share on PP 2 and 0% on RAC and EPP
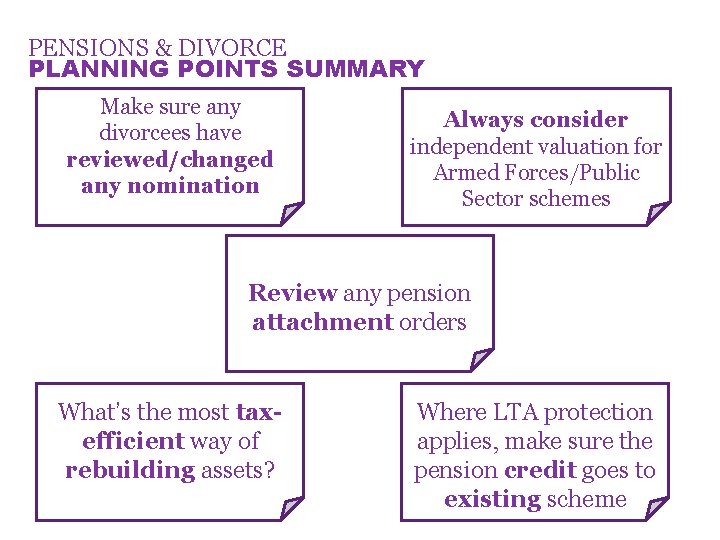
PENSIONS & DIVORCE PLANNING POINTS SUMMARY Make sure any divorcees have reviewed/changed any nomination Always consider independent valuation for Armed Forces/Public Sector schemes Review any pension attachment orders What’s the most taxefficient way of rebuilding assets? Where LTA protection applies, make sure the pension credit goes to existing scheme
PENSIONS AND DIVORCE FURTHER READING • bdm-web. com Independent actuarial valuations “Financial Adviser Specialist Accreditation is open to associate • https: //www. wikivorce. com/divorce members of Resolution who hold a Divorce wiki QCF Level 4 plus AF 3/G 60 and a valid Statement of Professional Standing (SPS). ” • http: //www. resolution. org. uk Organisation of 6, 500 family lawyers and other professionals Source: Resolution with the Personal Finance Society “Unlock the divorce and separation market” http: //www. resolution. org. uk/editorial. asp? page_id=1013
PENSIONS & DIVORCE OBJECTIVES By the end of this session, attendees will be able to: • Understand the divorce process and the options available for pensions in a divorce settlement • Explain the impact of pension freedoms on pensions and divorce • Consider the issues facing clients and solicitor connections in relation to pensions and divorce. 35
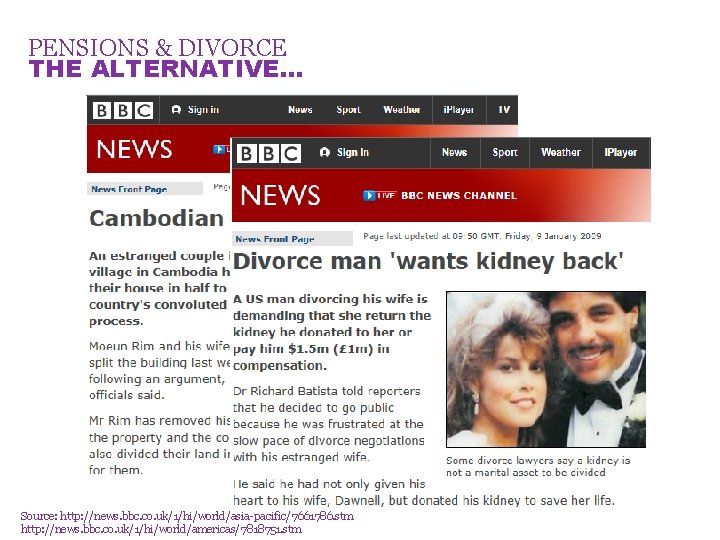
PENSIONS & DIVORCE THE ALTERNATIVE… Source: http: //news. bbc. co. uk/1/hi/world/asia-pacific/7661786. stm http: //news. bbc. co. uk/1/hi/world/americas/7818751. stm
THANK YOU The Royal London Mutual Insurance Society Limited is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. The firm is on the Financial Services Register, registration number 117672. It provides life assurance and pensions and is a member of the Association of British Insurers. Registered in England Wales number 99064. Registered office: 55 Gracechurch Street, London EC 3 V 0 RL. Royal London Marketing Limited is authorised and regulated by the Financial Conduct Authority and introduces Royal London’s customers to other insurance companies. The firm is on the Financial Services Register, registration number 302391. Registered in England Wales number 4414137. Registered office: 55 Gracechurch Street, London EC 3 V 0 RL. Royal London Corporate Pension Services Limited is authorised and regulated by the Financial Conduct Authority and provides pension services. The firm is on the Financial Services Register, registration number 460304. Registered in England Wales number 5817049. Registered office: 55 Gracechurch Street, London EC 3 V 0 RL. November 2018 PR 6 PN 0086