The Impact of Real Property Gains Tax in

- Slides: 25
The Impact of Real Property Gains Tax in Real Estate Secondary Market : A Malaysian Case Study KHUZAIMAH ABDULLAH National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia khuzaimah@inspen. gov. my European Real Estate Society (ERES) Conference 2010 23 – 26 June 2010, Milan, Italy
INTRODUCTION This is a preliminary study, looking into the impact of tax exemption on capital gains (RPGT) in real estate transaction. • In March 2007, Prime Minister announced the exemption of RPGT with effect from April 1, 2007 • The exemption was intended to “inject more excitement and dynamism into both the property and the financial sectors” in boosting the economic activities • The RPGT exemption however was re-imposed in January 1, 2010, following the PM’s announcement on 23 October 2009 National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
BACKGROUND • The first legislation to tax gains from the disposal of real estate was introduced by the enactment of Land Speculation Tax Act 1974 (LST), which came into force on December 6, 1973 • LST was introduced to curb speculative activities in property as such activities were rampant then and has triggered artificial market demand in the real estate market • It was meant more for government policy tool to deter speculation in land-based activities than a revenue raising measures. LST provided for a single tax rate of 50% on chargeable gains in properties disposed within two years from the date of acquisition and if the disposal consideration was more than RM 200, 000. • LST was then repealed in 1975 and replaced by RPGT Act 1976, effective from 7 th November, 1975 National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
BACKGROUND • Choong (2007) observed that the high tax rate under LST has deterred not only speculative activities but also genuine disposal of property. Thus, the RPGT Act was seen as an instrument to correct limitations to LST • RPGT has since then, gone through several amendments since its inception. The amendments to RPGT rates were made to keep abreast of the changes in the economic conditions of the country • In the light to boost the property market following recession period (1986), RPGT rates were dropped by 50%. Whilst during boom time (1994 to 1996), when property prices rose dramatically, RPGT was implemented to stabilize prices and to curtail undue speculation in property dealings National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
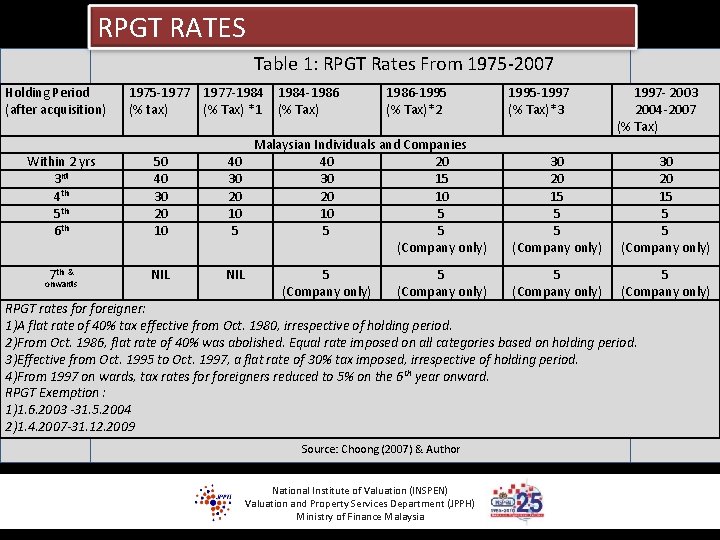
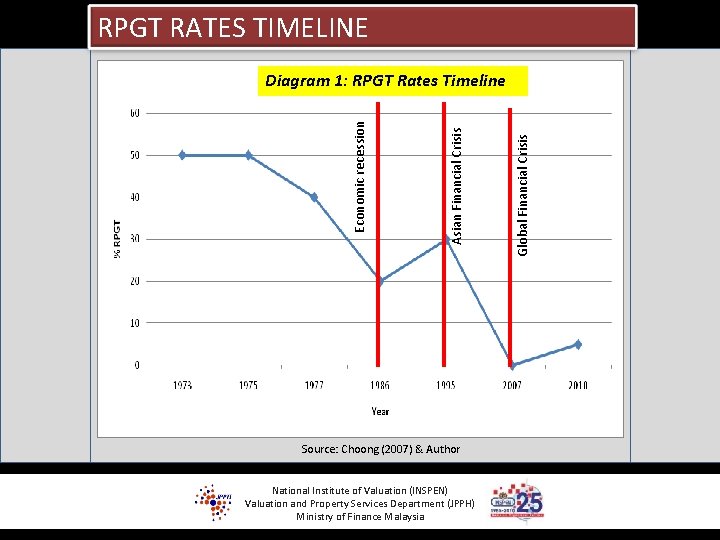
BACKGROUND • The tax rate was then increased by 5% to 10% in 1995 to 1997 • The latest amendment of RPGT rate came into effect from 1 January 2010 with imposition of a flat rate of 5% within 5 years of ownership. The re-imposition was announced during 2010 Budget speech by the Prime Minister on 23 October 2009 • The lifting of exemption was a measure in the efforts to increase government revenue. • Table 1 and Diagram 1 below tracked the changes in the rates of tax. National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
RPGT RATES Table 1: RPGT Rates From 1975 -2007 Holding Period (after acquisition) 1975 -1977 -1984 -1986 (% tax) (% Tax) *1 (% Tax) Within 2 yrs 3 rd 4 th 5 th 6 th 50 40 30 20 10 5 7 th & onwards NIL 1986 -1995 (% Tax)*2 Malaysian Individuals and Companies 40 20 30 15 20 10 10 5 5 5 (Company only) 1995 -1997 (% Tax)*3 1997 - 2003 2004 -2007 (% Tax) 30 30 20 20 15 15 5 (Company only) 5 (Company only) RPGT rates foreigner: 1)A flat rate of 40% tax effective from Oct. 1980, irrespective of holding period. 2)From Oct. 1986, flat rate of 40% was abolished. Equal rate imposed on all categories based on holding period. 3)Effective from Oct. 1995 to Oct. 1997, a flat rate of 30% tax imposed, irrespective of holding period. 4)From 1997 on wards, tax rates foreigners reduced to 5% on the 6 th year onward. RPGT Exemption : 1)1. 6. 2003 -31. 5. 2004 2)1. 4. 2007 -31. 12. 2009 Source: Choong (2007) & Author National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
RPGT RATES TIMELINE Source: Choong (2007) & Author National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia Global Financial Crisis Asian Financial Crisis Economic recession Diagram 1: RPGT Rates Timeline
METHODOLOGY • The research employed a frequency analysis of transactions recorded during the exemption period for the entire country. • Data obtained from Property Market Report produced annually by National Property Information centre (NAPIC). Property data were categorized into five subsectors, namely residential, commercial, industrial, agriculture and development land • The study focuses upon two key research questions: (i)Did the RPGT exemption boost up the property market? (ii)How has the exemption impact upon the property prices? National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
RESEARCH QUESTIONS • Research question (i) focus upon test of change in demand in the specific time , i. e. ‘before , during and after’ exemption period. • Announcement date on the exemption as well as reimposition of RPGT is also imperative to observe due to time lag in property transaction. • Research question (ii) called for tracking of price change. • In tracking the price change resulted from the exemption, ‘matched pair analysis’ were conducted. • The technique employed identifying properties that were transacted before and after the exemption • Repeat sales occurred within five years of ownership form the criteria of samples chosen in the analysis. • The difference in price between the matched pairs were then evaluated to indicate the price change. National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
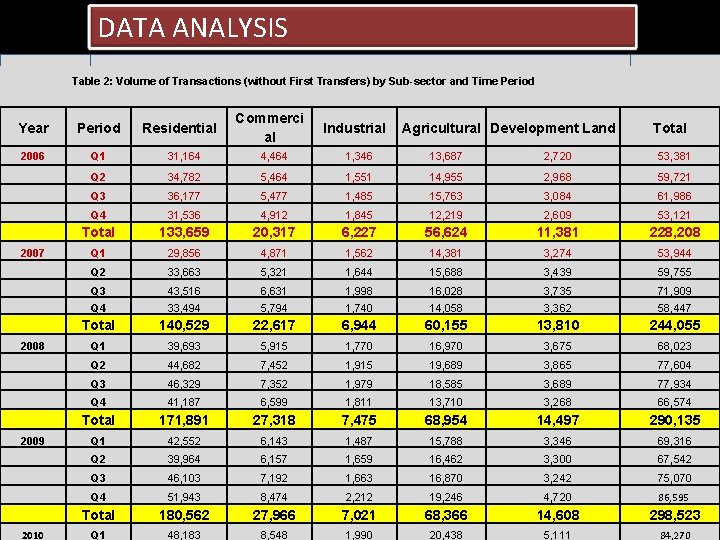
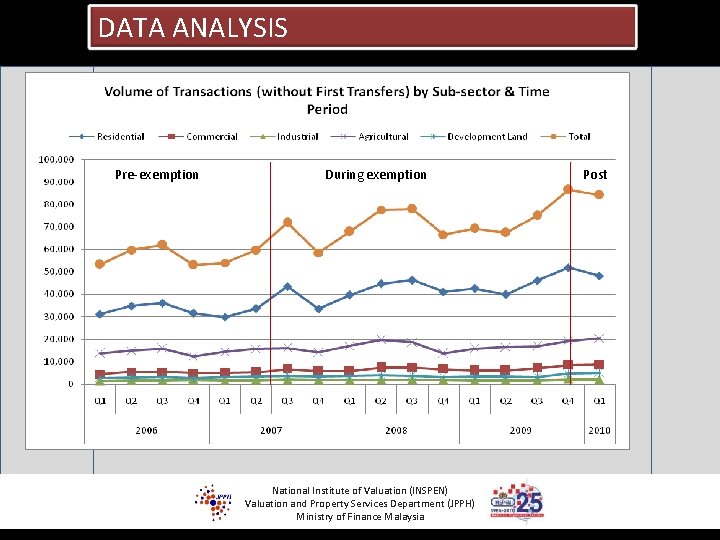
DATA ANALYSIS • SOURCE OF DATA • PROPERTY MARKET REPORT • NATIONAL PROPERTY INFORMATION CENTRE (NAPIC) • DATA ANALYSIS • Impact on Volume of Transaction • Repeat sales data for pre, during and post exemption dates tabulated in Table 2 and the line graph indicating the trend in Diagram 2. National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
DATA ANALYSIS Source: NAPIC & Property Market Report Table 2: Volume of Transactions (without First Transfers) by Sub-sector and Time Period Commerci al Year Period Residential 2006 Q 1 31, 164 4, 464 1, 346 13, 687 2, 720 53, 381 Q 2 34, 782 5, 464 1, 551 14, 955 2, 968 59, 721 Q 3 36, 177 5, 477 1, 485 15, 763 3, 084 61, 986 Q 4 31, 536 4, 912 1, 845 12, 219 2, 609 53, 121 Total 133, 659 20, 317 6, 227 56, 624 11, 381 228, 208 2007 Q 1 29, 856 4, 871 1, 562 14, 381 3, 274 53, 944 Q 2 33, 663 5, 321 1, 644 15, 688 3, 439 59, 755 Q 3 43, 516 6, 631 1, 998 16, 028 3, 735 71, 909 Q 4 33, 494 5, 794 1, 740 14, 058 3, 362 58, 447 Total 140, 529 22, 617 6, 944 60, 155 13, 810 244, 055 2008 Q 1 39, 693 5, 915 1, 770 16, 970 3, 675 68, 023 Q 2 44, 682 7, 452 1, 915 19, 689 3, 865 77, 604 Q 3 46, 329 7, 352 1, 979 18, 585 3, 689 77, 934 Q 4 41, 187 6, 599 1, 811 13, 710 3, 268 66, 574 Total 171, 891 27, 318 7, 475 68, 954 14, 497 290, 135 2009 Q 1 42, 552 6, 143 1, 487 15, 788 3, 346 69, 316 Q 2 39, 964 6, 157 1, 659 16, 462 3, 300 67, 542 Q 3 46, 103 3, 242 75, 070 Q 4 51, 943 4, 720 86, 595 Total 180, 562 2010 Q 1 48, 183 Industrial Agricultural Development Land 7, 192 1, 663 16, 870 National Institute of Valuation (INSPEN) 8, 474 2, 212 19, 246 Valuation and Property Services Department (JPPH) 27, 966 Ministry of Finance Malaysia 7, 021 68, 366 8, 548 1, 990 20, 438 14, 608 5, 111 Total 298, 523 84, 270
DATA ANALYSIS Pre-exemption During exemption National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia Post
DATA ANALYSIS • During the exemption period, which was from Q 2 of 2007 to Q 4 of 2009, the total number of transactions showed a significant increase • The increased occurred despite of the global financial crisis that began to surface in the Q 3 2007. All subsectors were showing the positive impact towards the exemption • The highest number of transaction recorded in Q 4 2009 the government announcement on re-imposition of RPGT that was made in October. • Upon re-imposition of RPGT, transaction of properties declined by almost 3%. National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
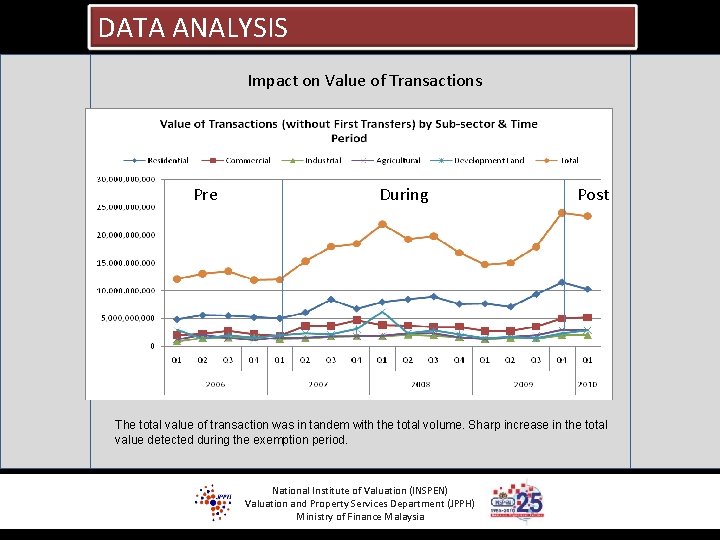
DATA ANALYSIS Impact on Value of Transactions Pre During Post The total value of transaction was in tandem with the total volume. Sharp increase in the total value detected during the exemption period. National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
Contents INTRODUCTION LITERATURE REVIEW METHODOLOGY FINDINGS & DISCUSSION CONCLUSION & RECOMMENDATION • Tracking of Price Change • In tracking the effect of exemption on property price, this study relied on transaction price of properties in Federal Territory of Kuala Lumpur (FTKL) • It was chosen as the case study due to its active market activities and the availability of data. FTKL consisted of five districts and in this case study, transactions in the district of Batu were chosen as sample for the study • Transactions recorded from year 2002 to October 2009 were sorted to get repeat sales National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
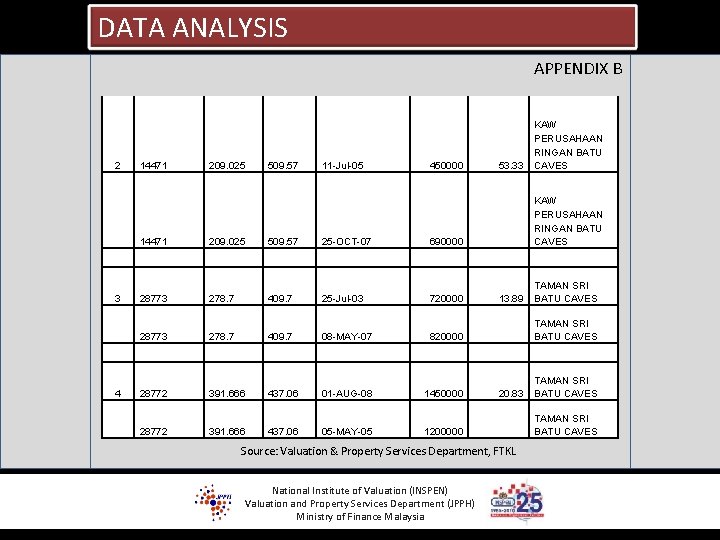
Contents INTRODUCTION LITERATURE REVIEW METHODOLOGY FINDINGS & DISCUSSION CONCLUSION & RECOMMENDATION • There were a total of 10, 835 transaction data from 2002 to 2009 • Samples taken from 20% of the total transaction were analysed and it was observed that less than 5% indicated repeat sales occurred within 5 years of holding period • Results from ‘matched pair analysis’ are shown in Appendix A and B National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
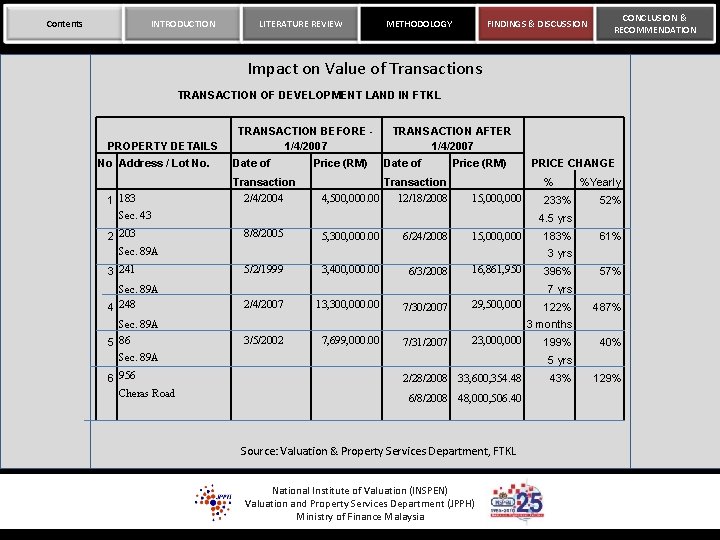
Contents INTRODUCTION LITERATURE REVIEW METHODOLOGY FINDINGS & DISCUSSION CONCLUSION & RECOMMENDATION Impact on Value of Transactions TRANSACTION OF DEVELOPMENT LAND IN FTKL TRANSACTION BEFORE - 1/4/2007 PROPERTY DETAILS No Address / Lot No. Date of Price (RM) Transaction 2/4/2004 1 183 Sec. 43 2 203 Sec. 89 A 3 241 8/8/2005 Sec. 89 A 4 248 5, 300, 000. 00 2/4/2007 13, 300, 000. 00 7, 699, 000. 00 52% 183% 61% 396% 57% 7 yrs 29, 500, 000 122% 487% 3 months 23, 000 7/31/2007 233% 3 yrs 16, 861, 950 7/30/2007 %Yearly 4. 5 yrs 15, 000, 000 6/3/2008 PRICE CHANGE % 3, 400, 000. 00 3/5/2002 Price (RM) 6/24/2008 5/2/1999 Cheras Road Date of Transaction 4, 500, 000. 00 12/18/2008 Sec. 89 A 5 86 Sec. 89 A 6 956 TRANSACTION AFTER 1/4/2007 2/28/2008 33, 600, 354. 48 6/8/2008 48, 000, 506. 40 Source: Valuation & Property Services Department, FTKL National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia 199% 40% 5 yrs 43% 129%
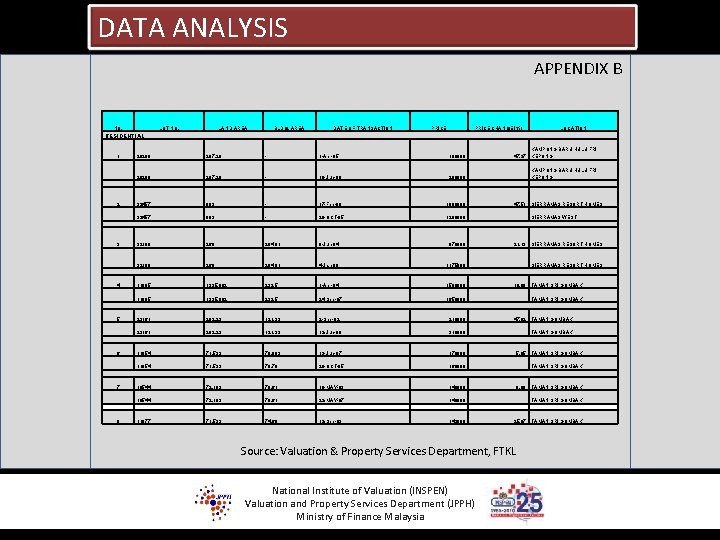
DATA ANALYSIS APPENDIX B NO. LOT NO, RESIDENTIAL LAND AREA BLDG. AREA DATE OF TRANSACTION PRICE CHANGE (%) 1 28298 297. 28 - 1 -Apr-05 190000 28298 297. 28 19 -Jun-09 280000 2 32457 893 - 17 -Feb-09 1900000 32457 893 28 -OCT-05 1288008 3 32190 260 204. 01 8 -Jun-04 32190 260 204. 01 4 -Jan-08 4 11995 1335. 902 232. 5 1 -Apr-04 11995 1335. 902 232. 5 24 -Sep-07 5 23161 282. 23 121. 33 2 -Sep-02 210000 23161 282. 23 121. 33 12 -Jun-08 310000 6 11854 71. 533 79. 893 13 -Jun-07 11854 71. 533 78. 78 28 -OCT-05 7 10544 72. 183 70. 61 19 -MAY-03 140000 10544 72. 183 70. 61 22 -MAY-07 140000 8 11877 71. 533 74. 69 12 -Sep-03 47. 37 1175000 47. 51 1650000 168000 10. 00 47. 62 TAMAN GOMBAK 5. 95 TAMAN SRI GOMBAK 0. 00 TAMAN SRI GOMBAK 25. 87 Source: Valuation & Property Services Department, FTKL National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia TAMAN SRI GOMBAK 143000 SIERRAMAS RESORT HOMES 178000 SIERRAMAS RESORT HOMES SIERRAMAS WEST 21. 13 1500000 KAMPONG BARU HULU FRI KEPONG 970000 LOCATION TAMAN SRI GOMBAK
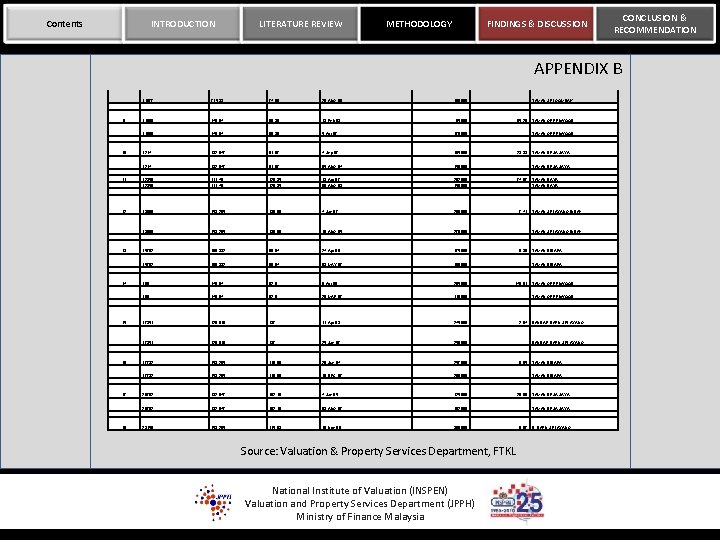
Contents INTRODUCTION LITERATURE REVIEW METHODOLOGY FINDINGS & DISCUSSION CONCLUSION & RECOMMENDATION APPENDIX B 11877 71. 533 74. 69 28 -AUG-08 9 11988 148. 64 80. 36 13 -Feb-03 11988 148. 64 80. 36 5 -Apr-07 10 1214 132. 847 91. 97 4 -Sep-07 185000 1214 132. 847 91. 97 05 -AUG-04 150000 11 12358 111. 48 126. 35 13 -Apr-07 262000 12358 111. 48 126. 35 06 -AUG-03 150000 12 13608 153. 285 138. 98 4 -Jan-07 13608 153. 285 138. 98 19 -AUG-05 13 15762 100. 332 89. 84 24 -Apr-09 175000 15762 100. 332 89. 84 03 -MAY-07 160000 14 169 148. 64 92. 9 8 -Apr-09 265000 169 148. 64 92. 9 20 -MAR-07 110000 15 17351 128. 016 137 11 -Apr-03 17351 128. 016 137 25 -Jan-07 16 17732 153. 285 116. 69 29 -Jun-04 17732 153. 285 116. 69 19 -DEC-07 17 20792 132. 847 102. 19 4 -Jan-05 125000 20792 132. 847 102. 19 03 -AUG-07 162000 23156 153. 285 115. 93 16 -Nov-06 18 180000 TAMAN SRI GOMBAK 95000 176000 85. 26 TAMAN GREENWOOD 23. 33 74. 67 270000 TAMAN DAYA 7. 41 TAMAN SELAYANG INDAH 9. 38 250000 140. 91 TAMAN GREENWOOD 2. 04 257000 280000 TAMAN GREENWOOD BANDAR BARU SELAYANG TAMAN BIDARA 245000 TAMAN SELAYANG INDAH TAMAN DAYA 290000 TAMAN DESA JAYA TAMAN GREENWOOD 8. 95 TAMAN BIDARA 29. 60 TAMAN DESA JAYA 300000 Source: Valuation & Property Services Department, FTKL National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia TAMAN DESA JAYA 6. 67 B. BARU SELAYANG
Contents INTRODUCTION LITERATURE REVIEW METHODOLOGY FINDINGS & DISCUSSION CONCLUSION & RECOMMENDATION APPENDIX B 23156 153. 285 115. 93 20 -MAY-08 320000 19 25749 153. 28 98. 11 10 -Jun-05 238000 25749 153. 28 98. 11 10 -MAY-07 250000 20 16157 163. 318 137. 4 2 -Jul-04 240000 16157 163. 318 137. 4 01 -OCT-07 249000 21 14254 76. 643 91. 6 23 -Nov-07 14254 76. 643 91. 6 17 -AUG-06 22 18894 97. 545 55. 94 21 -Apr-08 18894 97. 545 55. 94 20 -AUG-02 23 27550 174 78. 04 18 -Apr-05 27550 174 78. 04 22 -DEC-08 24 10169 71. 533 70. 61 6 -Feb-09 10169 71. 533 70. 61 25 -AUG-03 25 13404 69. 675 78. 08 23 -Nov-06 13404 69. 675 78. 08 07 -MAR-07 26 13473 69. 675 78. 08 13 -Feb-08 13473 69. 675 78. 08 11 -MAY-05 27 17582 132. 847 81. 57 16 -Sep-05 170000 17582 132. 847 81. 57 18 -Feb-08 215000 B. BARU SELAYANG 5. 04 TAMAN SRI MELATI 3. 75 TAMAN EHSAN 12. 77 TAMAN SAMUDRA 135. 71 TAMAN SRI GOMBAK 70000 170000 71. 43 TAMAN EHSAN 265000 165000 TAMAN SRI GOMBAK 10. 00 TAMAN BUKIT DESA JAYA 187000 TAMAN BUKIT DESA JAYA 190000 1. 06 188000 TAMAN BUKIT DESA JAYA 26. 47 TAMAN DESA JAYA Source: Valuation & Property Services Department, FTKL National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia TAMAN SELAYANG UTAMA 105000 235000 6. 67 150000 180000 TAMAN BIDARA 160000 TAMAN SRI MELATI TAMAN DESA JAYA
Contents INTRODUCTION LITERATURE REVIEW METHODOLOGY FINDINGS & DISCUSSION CONCLUSION & RECOMMENDATION APPENDIX B 28 18433/F-4 -25 85. 747 85. 74 17 -Jan-06 100000 18433/F-4 -25 85. 747 85. 74 24 -MAY-09 130000 29 23501/3 -46 96. 152 96. 15 29 -Jun-06 117520 23501/3 -46 96. 152 96. 15 16 -Sep-08 132000 30 23501/5 -43 96. 152 96. 15 5 -Sep-06 23501/5 -43 96. 152 96. 15 16 -Jul-08 31 23501/6 -35 96. 152 96. 15 16 -Jun-08 135000 23501/6 -35 96. 152 96. 15 29 -MAY-06 119920 COMMERCIAL PROPERTY 30. 00 TAMAN SAMUDRA 12. 32 WANGSA PERMAI 119120 125000 132. 847 237. 5 29 -Apr-04 1424 132. 847 237. 5 3 -Jun-08 2 1507 132. 847 251. 39 14 -Sep-07 430000 1507 132. 847 251. 39 01 -OCT-03 330000 3 28854 139. 35 364. 18 11 -Jun-07 700000 28854 139. 35 364. 18 26 -AUG-03 480000 4 13824 191 652 02 -MAR-09 2150000 13824 191 652 08 -MAY-06 1880000 INDUSTRIAL PROPERTY 1 14437 574. 865 765. 5 18 -Apr-07 14437 574. 865 765. 5 04 -OCT-04 182172 WANGSA PERMAI 70. 22 BANDAR BARU KUNDANG 310085 BANDAR BARU KUNDANG 30. 30 TAMAN DESA JAYA 45. 83 B. BARU SELAYANG 14. 36 TAMAN DESA JAYA 985000 WANGSA PERMAI 12. 58 WANGSA PERMAI 1424 WANGSA PERMAI 4. 94 WANGSA PERMAI 1 TAMAN SAMUDRA 900000 Source: Valuation & Property Services Department, FTKL National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia TAMAN DESA JAYA 9. 44 BATU CAVES
DATA ANALYSIS APPENDIX B 2 14471 209. 025 509. 57 11 -Jul-05 14471 209. 025 509. 57 25 -OCT-07 3 28773 278. 7 409. 7 25 -Jul-03 28773 278. 7 409. 7 08 -MAY-07 450000 690000 53. 33 KAW PERUSAHAAN RINGAN BATU CAVES 720000 820000 4 28772 391. 666 437. 06 01 -AUG-08 1450000 28772 391. 666 437. 06 05 -MAY-05 1200000 KAW PERUSAHAAN RINGAN BATU CAVES 13. 89 TAMAN SRI BATU CAVES 20. 83 Source: Valuation & Property Services Department, FTKL National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia TAMAN SRI BATU CAVES
DISCUSSION • The real estate market responded positively to the exemption of RPGT. Transaction data has shown that volume of transactions and value of all sub-sectors has increased. • The announcement made on 23 October 2009 on re-imposition of RPGT with effect from 1 January, 2010 showed a decline in the value and volume of transaction of properties. National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
FUTURE RESEARCH • Study on implications of RPGT exemption on other financial/revenue resources e. g. income tax, stamp duty. • For price change, to widen the sample size to include nationwide data. National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia
The Impact of Real Property Gains Tax in Real Estate Secondary Market : A Malaysian Case Study QUESTION AND ANSWER European Real Estate Society (ERES) Conference 2010 23 – 26 June 2010, Milan, Italy THANK YOU Comments and feedbacks are welcome. khuzaimah@inspen. gov. my National Institute of Valuation (INSPEN) Valuation and Property Services Department (JPPH) Ministry of Finance Malaysia