State of play of the Customsrelated aspects 21
- Slides: 15
State of play of the Customsrelated aspects 21 st meeting of the VAT Expert Group 11 February 2019
Main changes for low value consignments Ø UCC ü Electronic data transmission will be required for: • safety and security: entry summary declaration (before arrival of the goods) • import: declaration for release for free circulation Ø VAT ü customs declaration for each consignment, including with a value up to 22 €
Date of application: 1/1/2021 New VAT E-commerce rules with customs impact § Abolish import exemption for consignments of a value ≤ EUR 22 Ø All distance sales from third countries to the EU are subject to VAT upon importation § For consignments of a value ≤ EUR 150, the Import One-Stop Shop (IOSS) can be used to declare and pay the VAT § All MS must compile a monthly listing containing: ü The IOSS VAT Id Nos mentioned in import declarations during the month (of any MSI) ü Per IOSS VAT Id No, The total value of imports exempted during the month § Special arrangements, if IOSS is not used 3
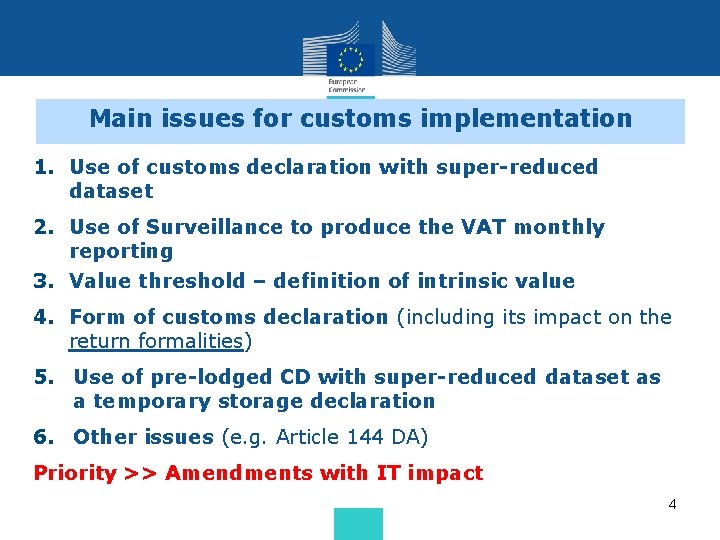
Main issues for customs implementation 1. Use of customs declaration with super-reduced dataset 2. Use of Surveillance to produce the VAT monthly reporting 3. Value threshold – definition of intrinsic value 4. Form of customs declaration (including its impact on the return formalities) 5. Use of pre-lodged CD with super-reduced dataset as a temporary storage declaration 6. Other issues (e. g. Article 144 DA) Priority >> Amendments with IT impact 4
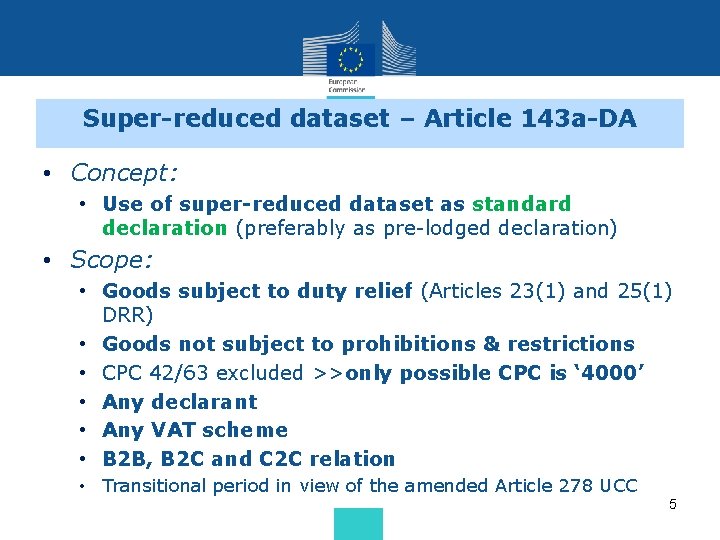
Super-reduced dataset – Article 143 a-DA • Concept: • Use of super-reduced dataset as standard declaration (preferably as pre-lodged declaration) • Scope: • Goods subject to duty relief (Articles 23(1) and 25(1) DRR) • Goods not subject to prohibitions & restrictions • CPC 42/63 excluded >>only possible CPC is ‘ 4000’ • Any declarant • Any VAT scheme • B 2 B, B 2 C and C 2 C relation • Transitional period in view of the amended Article 278 UCC 5
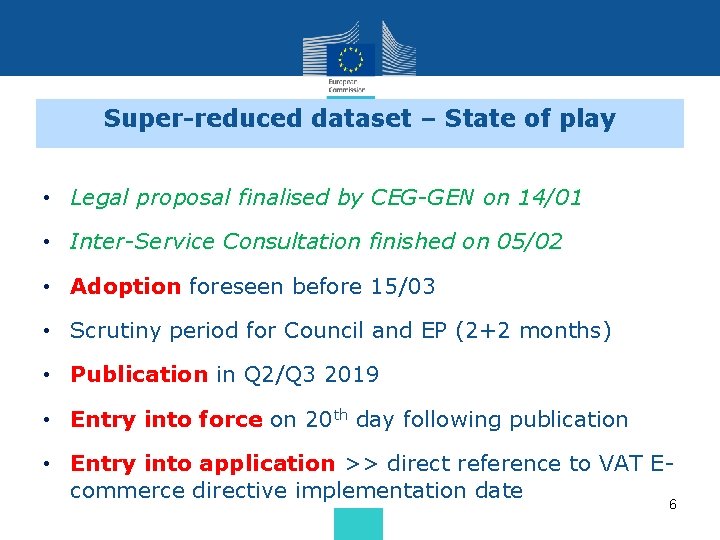
Super-reduced dataset – State of play • Legal proposal finalised by CEG-GEN on 14/01 • Inter-Service Consultation finished on 05/02 • Adoption foreseen before 15/03 • Scrutiny period for Council and EP (2+2 months) • Publication in Q 2/Q 3 2019 • Entry into force on 20 th day following publication • Entry into application >> direct reference to VAT Ecommerce directive implementation date 6
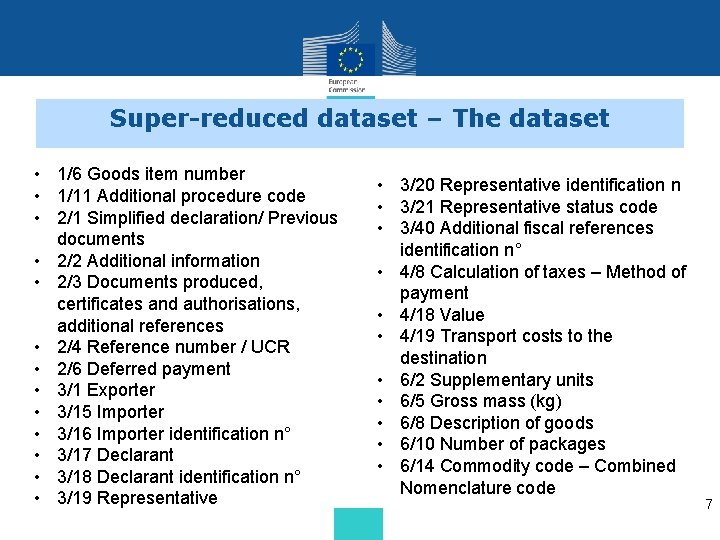
Super-reduced dataset – The dataset • 1/6 Goods item number • 1/11 Additional procedure code • 2/1 Simplified declaration/ Previous documents • 2/2 Additional information • 2/3 Documents produced, certificates and authorisations, additional references • 2/4 Reference number / UCR • 2/6 Deferred payment • 3/1 Exporter • 3/15 Importer • 3/16 Importer identification n° • 3/17 Declarant • 3/18 Declarant identification n° • 3/19 Representative • 3/20 Representative identification n • 3/21 Representative status code • 3/40 Additional fiscal references identification n° • 4/8 Calculation of taxes – Method of payment • 4/18 Value • 4/19 Transport costs to the destination • 6/2 Supplementary units • 6/5 Gross mass (kg) • 6/8 Description of goods • 6/10 Number of packages • 6/14 Commodity code – Combined Nomenclature code 7
Monthly reporting through Surveillance § Obligation laid down in Council Directive (EU) 2017/2455 >> All MS must compile a monthly listing containing: ü The IOSS VAT Id Nos mentioned in import declarations during the month (of any MSI) ü Per IOSS VAT Id No, The total value of imports exempted during the month § Solution: ‘Surveillance – SURVRECAP’ – no legal impediment § Amendments to UCC-IA § Annexes 21 -01 (and 21 -02) – New data elements § D. E. 3/40 (IOSS number) § D. E. 4/4 Tax base § Annex B § Amendments to UCC-DA (Annex B to ensure consistency with IA) 8
Intrinsic value I. § § § Duty Relief Regulation (Regulation No (EU)1186/2009) VAT E-Commerce Directive (Council Directive 2017/2455) No legally binding definition available Compendium on DRR is used as guidance ‘intrinsic value' means the value of goods in themselves, excluding transport and insurance costs, as ascertainable by the customs authorities either from any relevant document or in the light of their experience. § Questions: § Any need to introduce a legally binding definition, if yes what should be the definition used? § How should the intrinsic value be calculated? § Which data element to use for capturing the intrinsic value? 9
Intrinsic value II Main conclusions from CEG-GEN 27 meeting on 14/12/2018 § Broad support for uniform and legally binding definition § Definition should be clear, simple & practicable § Legal solution and definition to be further analysed & discussed § Relevance only for low value consignments § Data element to capture the intrinsic value in the CD with super-reduced dataset: ü (new) D. E. 4/18 Value (Intrinsic value of the goods per item in the invoice currency) 10
Intrinsic value III. – The definition § Definition used in the Compendium: ‘intrinsic value' means the value of goods in themselves, excluding transport and insurance costs, as ascertainable by the customs authorities either from any relevant document or in the light of their experience. § Change in circumstances > boost of e-commerce > transport costs often offered free by online retailers or not separately indicated on the invoice >> new definition proposed: ‘intrinsic value' means the price actually paid or payable for the goods when sold for export to the customs territory of the Union Ø Concept based on the transaction value 11
Intrinsic value IV. – The legal solution Need for clear definition – where? Options: ü Compendium – legally not binding, current content to be improved ü UCC-DA (Delegated Regulation 2015/2446) ü Duty Relief Regulation (EU) 1186/2009) ü Combined Nomenclature (2019 version – in force as of 1. 1. 2020) ü VAT legislation 12
Additional issues I. • Subjects requiring further consideration by PG-LVC • Mainly procedural rules (relating to applicable formalities >> less IT impact) • To be covered by 2019 DA amendment package (Q 4 -2019) • Improved presentation of LVC-related Article(s)
Additional issues II. • Declaration by any other act for IOSS goods • Act of declaration is presentation to customs, using the super-reduced dataset • Solution to be left at MS discretion (potential impact on wording • Under condition that of Article 143 a DA) • • Checking of IOSS number is ensured Annex 21 -01 data sent to Surveillance • Liability of the declarant • Competent customs office • Systematic use of CD in Article 143 a DA as TSD, if prelodged • Returns
DG TAXUD – Unit A 2 E-mail: TAXUD-UNIT-A 2@ec. europa. eu 15