Our Evolving Industry Analysis and Insight Courtney Killion
- Slides: 50
Our Evolving Industry: Analysis and Insight Courtney Killion Market Research Analyst, Cleveland Research
Cleveland Research Company • Sell-side equity research firm started in June 2006 • Cover 4 industries, 15 analysts, 70+ employees Stock Market Research • We do in-depth financial research on publicly traded companies. • Our clients include the 125 largest institutional investors such as Fidelity and T. Rowe Price. What Sets us Apart? • We go to greater lengths than most of our peers to find out what’s new and what is changing with the companies/industries we cover. • We spend a large amount of time talking with retail customers, suppliers, distributors, and competitors. • Our clients find this differentiated and highly value-added versus other sell-side firms.
Agenda • • • Economic overview Industrial activity indicators Industrial distribution trends Expectations for 2014 Changing landscape E-Commerce
Economic Overview
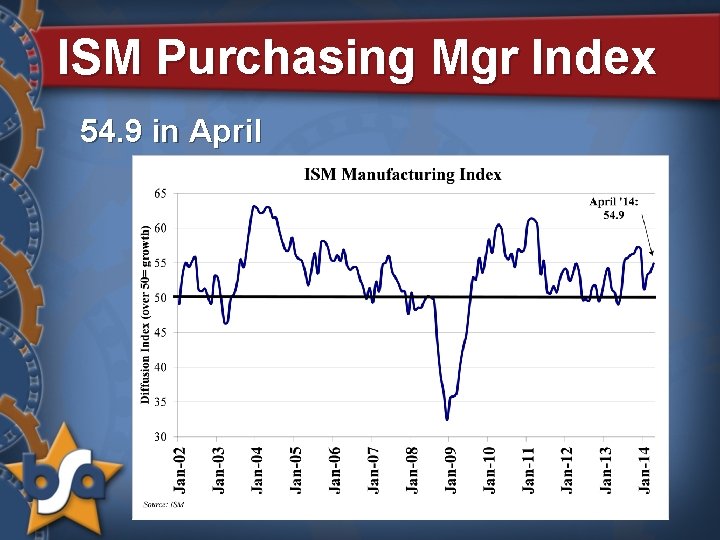
ISM Purchasing Mgr Index 54. 9 in April
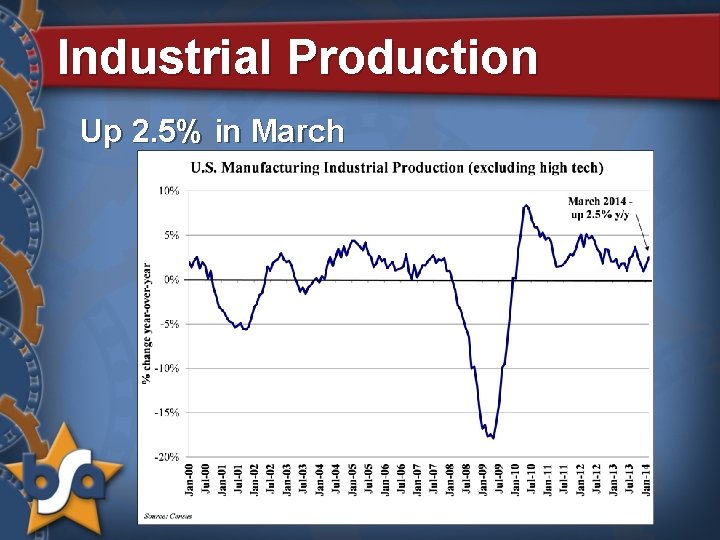
Industrial Production Up 2. 5% in March
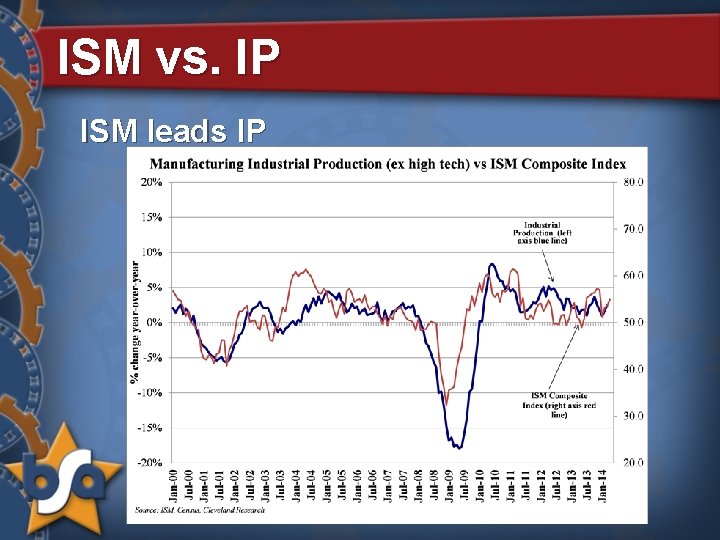
ISM vs. IP ISM leads IP
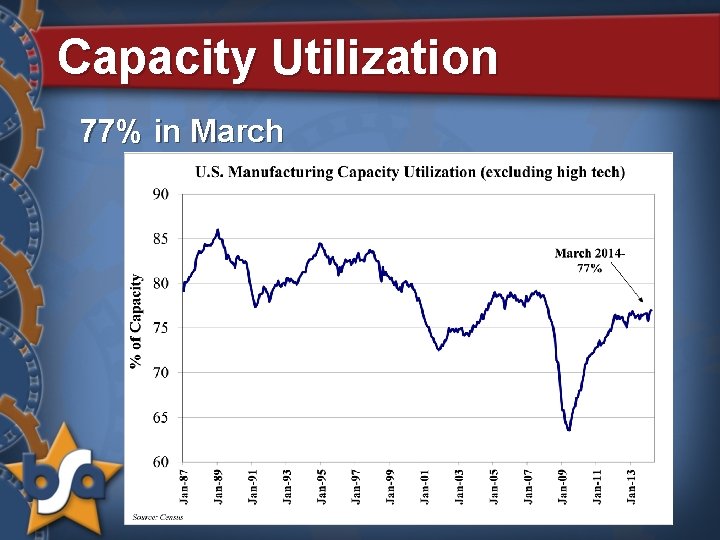
Capacity Utilization 77% in March
Industrial Activity Indicators
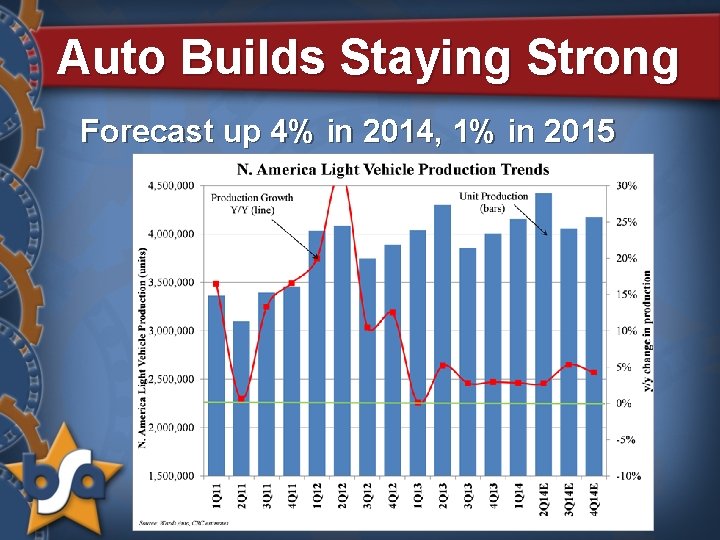
Auto Builds Staying Strong Forecast up 4% in 2014, 1% in 2015
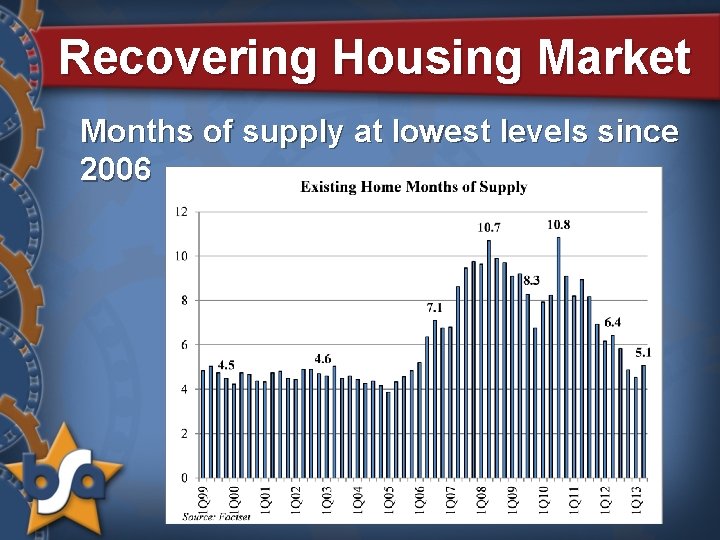
Recovering Housing Market Months of supply at lowest levels since 2006
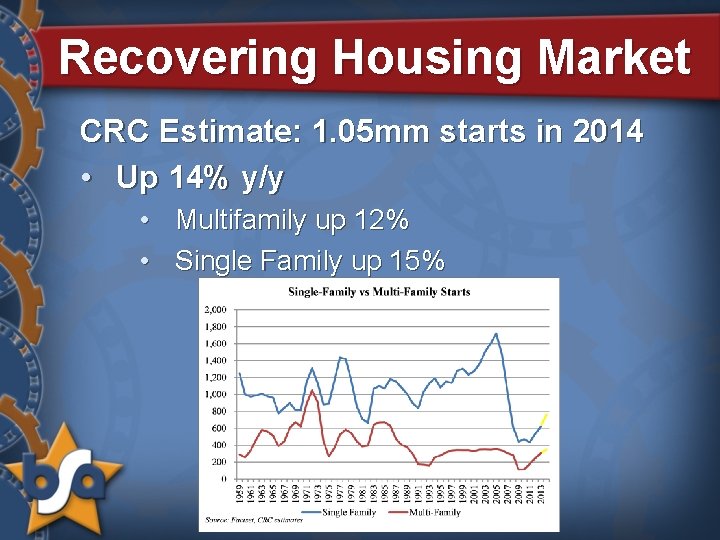
Recovering Housing Market CRC Estimate: 1. 05 mm starts in 2014 • Up 14% y/y • Multifamily up 12% • Single Family up 15%
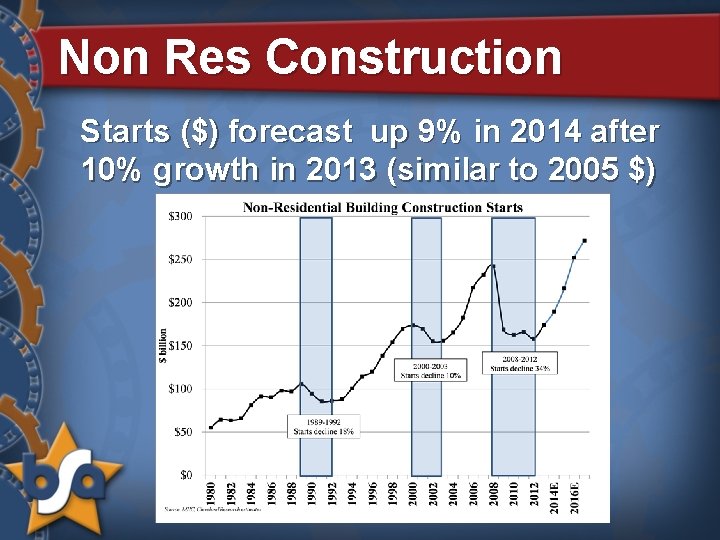
Non Res Construction Starts ($) forecast up 9% in 2014 after 10% growth in 2013 (similar to 2005 $)
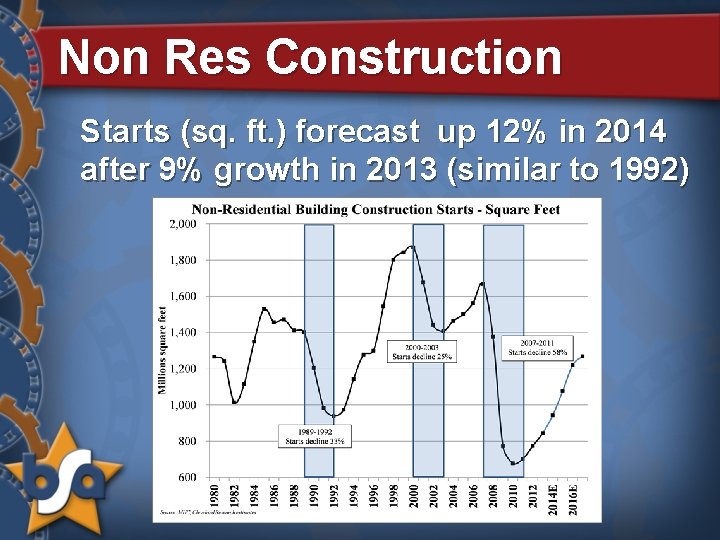
Non Res Construction Starts (sq. ft. ) forecast up 12% in 2014 after 9% growth in 2013 (similar to 1992)
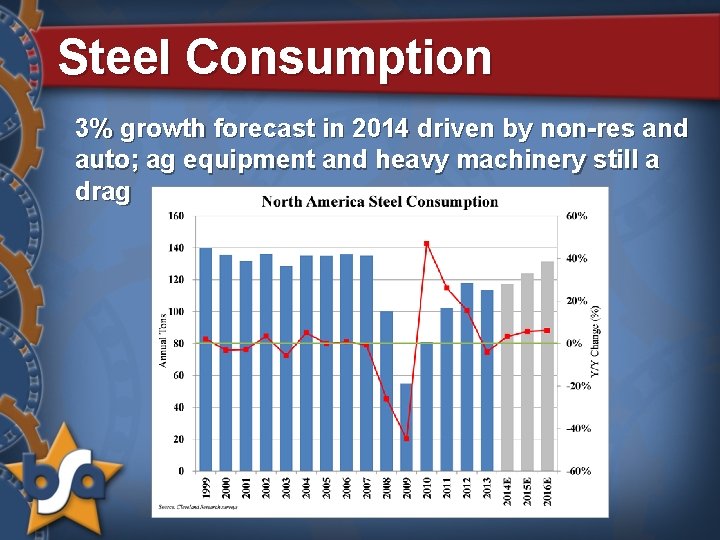
Steel Consumption 3% growth forecast in 2014 driven by non-res and auto; ag equipment and heavy machinery still a drag
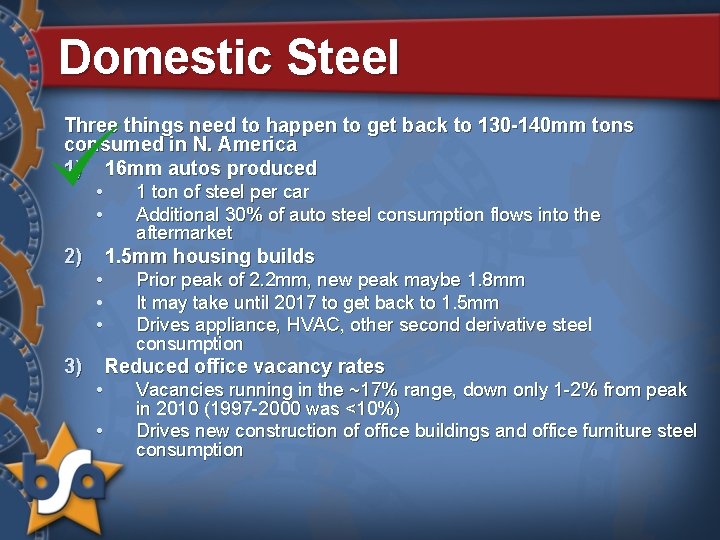
Domestic Steel Three things need to happen to get back to 130 -140 mm tons consumed in N. America 1) 16 mm autos produced • 1 ton of steel per car • Additional 30% of auto steel consumption flows into the aftermarket 2) 1. 5 mm housing builds • • • 3) Prior peak of 2. 2 mm, new peak maybe 1. 8 mm It may take until 2017 to get back to 1. 5 mm Drives appliance, HVAC, other second derivative steel consumption Reduced office vacancy rates • • Vacancies running in the ~17% range, down only 1 -2% from peak in 2010 (1997 -2000 was <10%) Drives new construction of office buildings and office furniture steel consumption
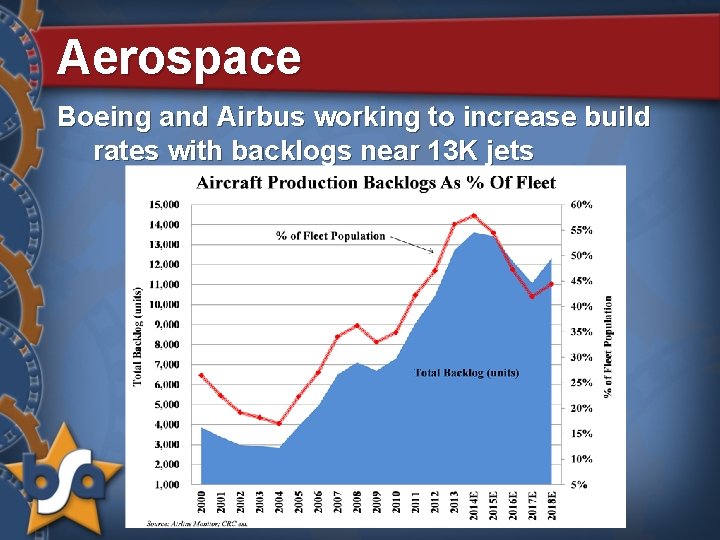
Aerospace Boeing and Airbus working to increase build rates with backlogs near 13 K jets
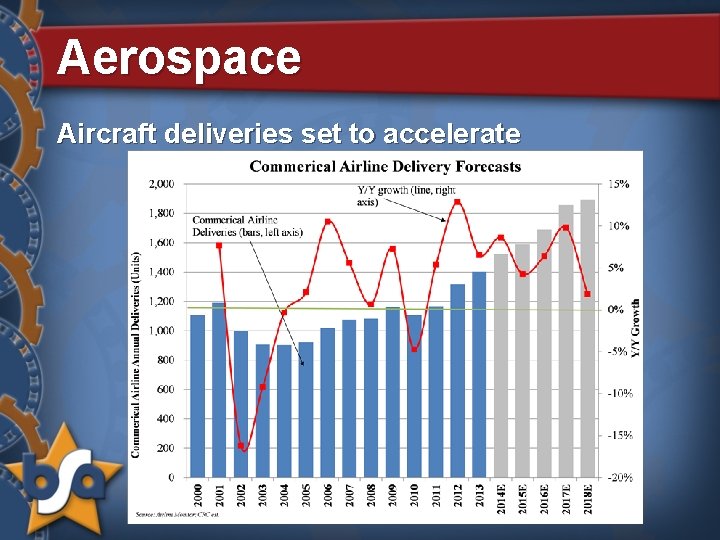
Aerospace Aircraft deliveries set to accelerate
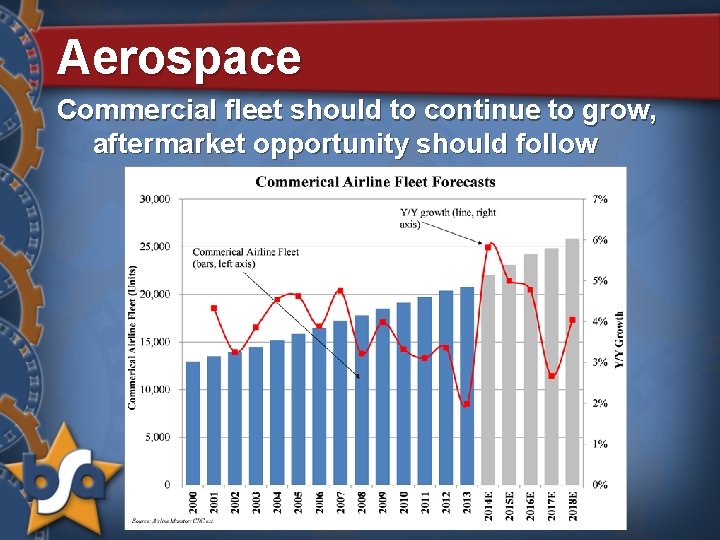
Aerospace Commercial fleet should to continue to grow, aftermarket opportunity should follow
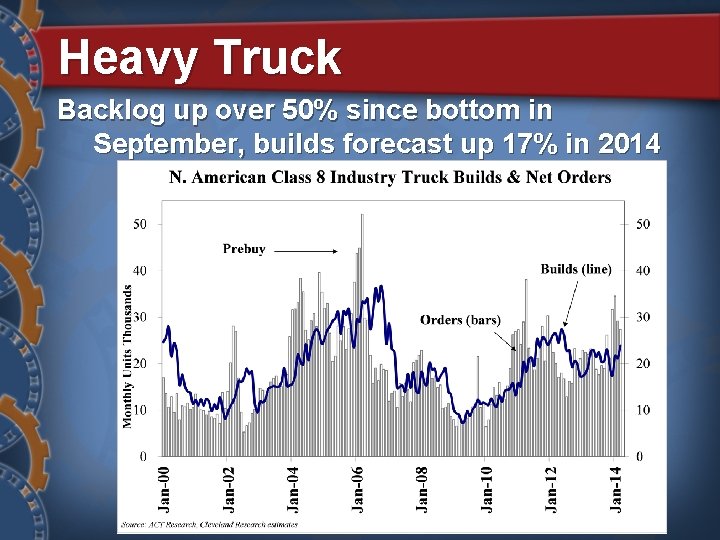
Heavy Truck Backlog up over 50% since bottom in September, builds forecast up 17% in 2014
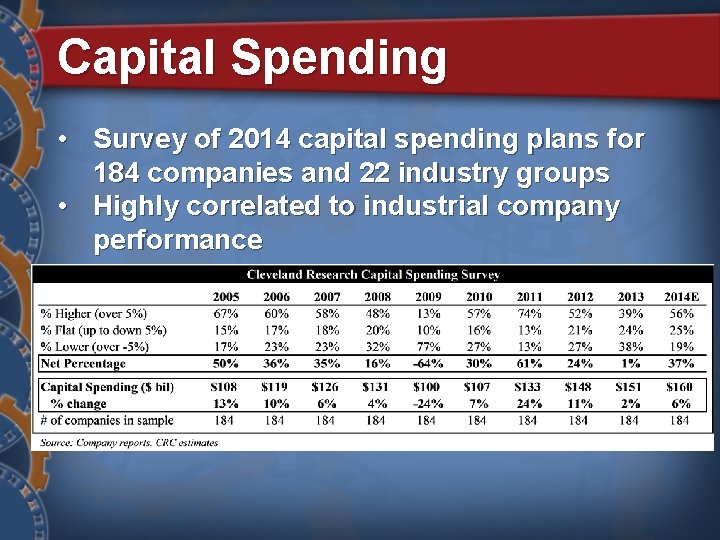
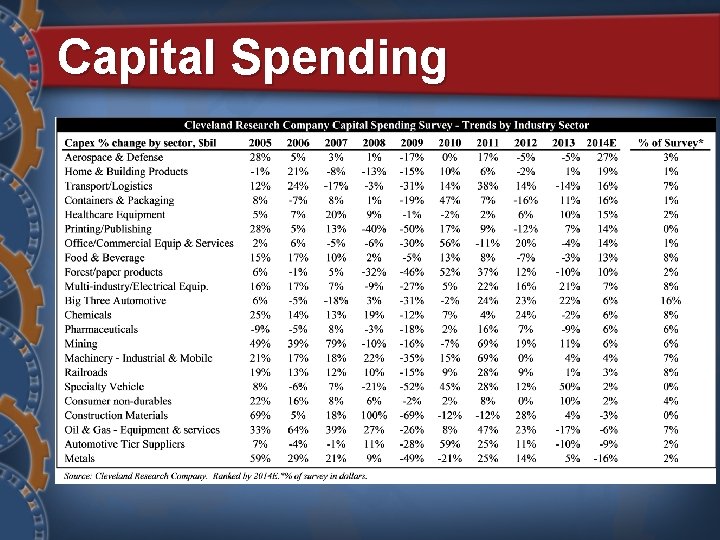
Capital Spending • Survey of 2014 capital spending plans for 184 companies and 22 industry groups • Highly correlated to industrial company performance
Capital Spending
Industrial Distribution Trends
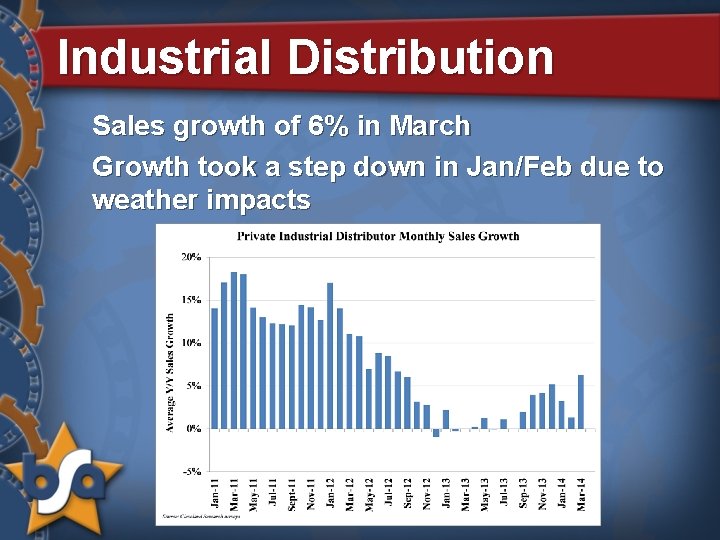
Industrial Distribution Sales growth of 6% in March Growth took a step down in Jan/Feb due to weather impacts
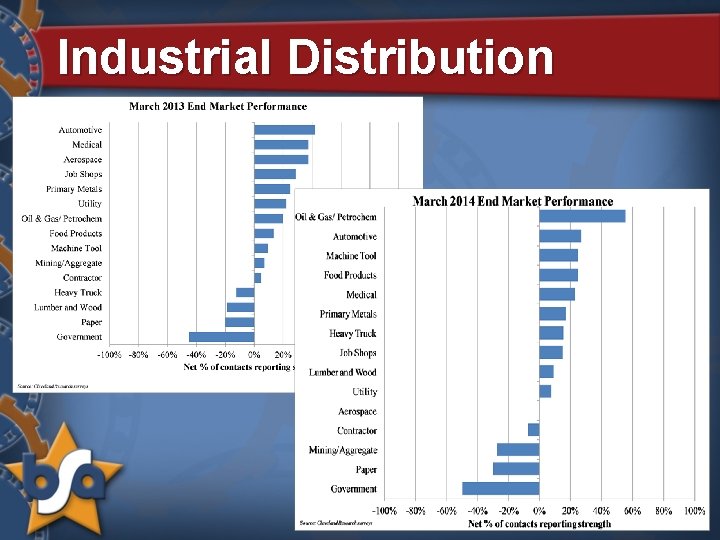
Industrial Distribution
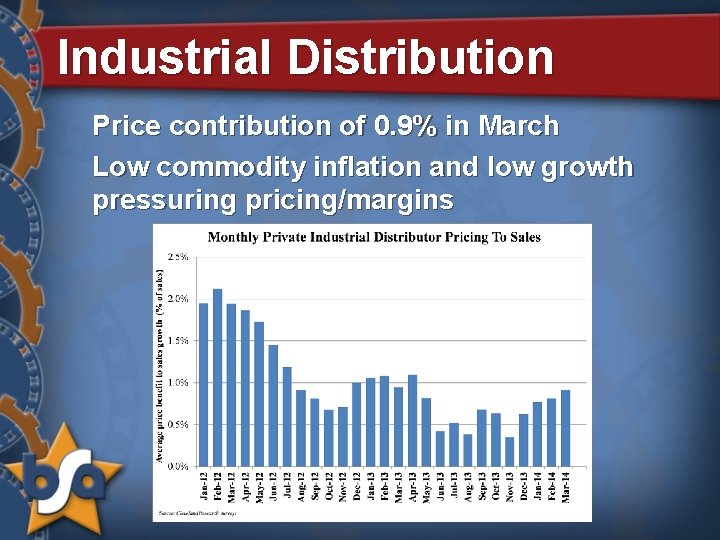
Industrial Distribution Price contribution of 0. 9% in March Low commodity inflation and low growth pressuring pricing/margins
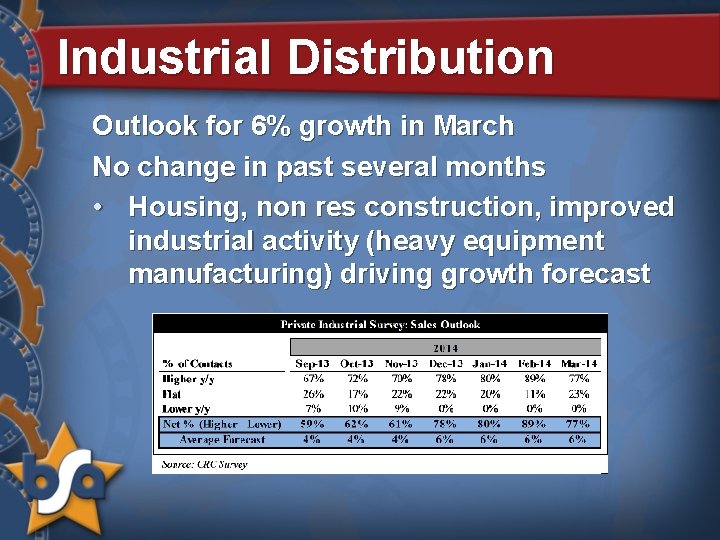
Industrial Distribution Outlook for 6% growth in March No change in past several months • Housing, non res construction, improved industrial activity (heavy equipment manufacturing) driving growth forecast
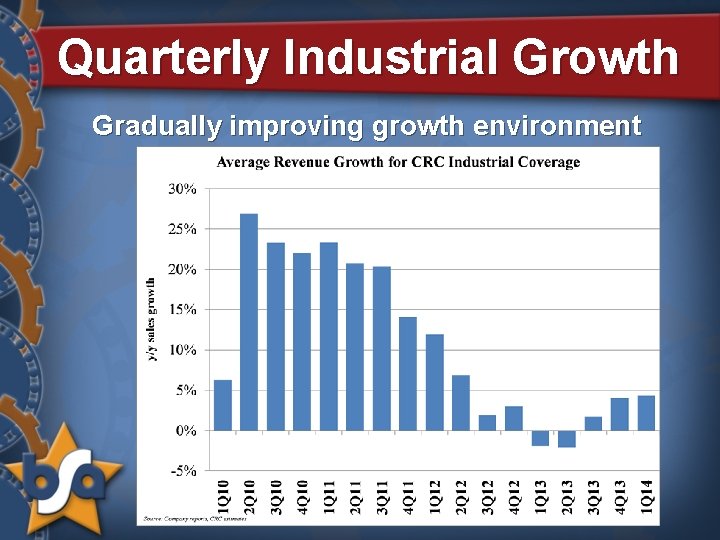
Quarterly Industrial Growth Gradually improving growth environment
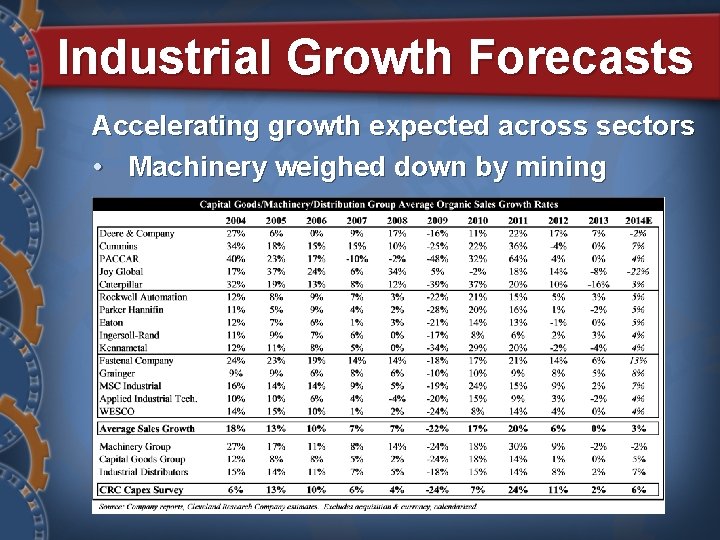
Industrial Growth Forecasts Accelerating growth expected across sectors • Machinery weighed down by mining
Changing Landscape
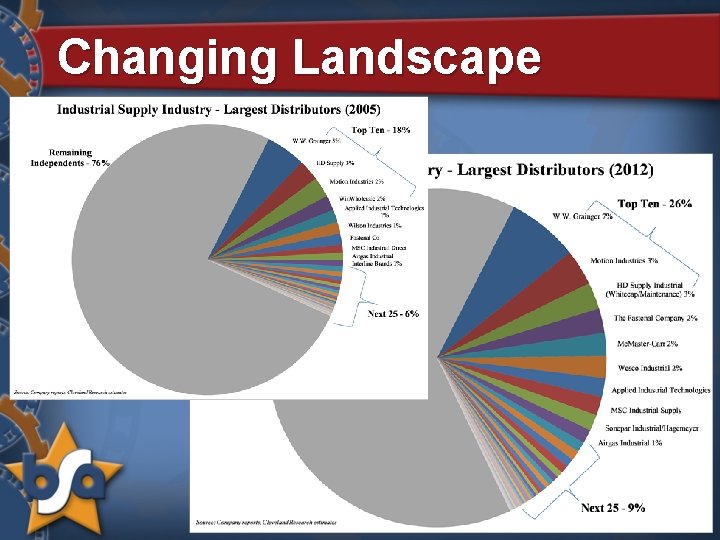
Changing Landscape
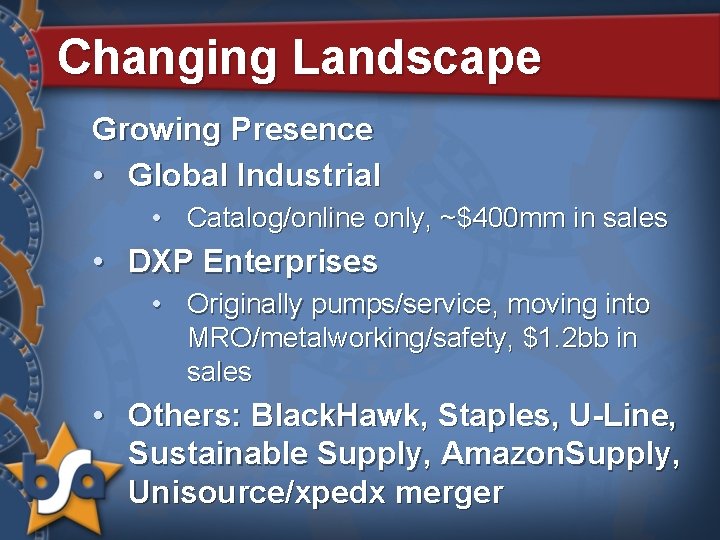
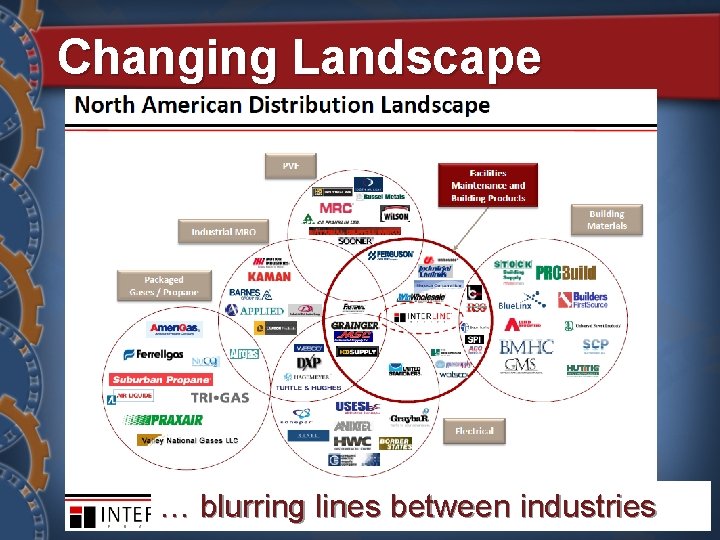
Changing Landscape Growing Presence • Global Industrial • Catalog/online only, ~$400 mm in sales • DXP Enterprises • Originally pumps/service, moving into MRO/metalworking/safety, $1. 2 bb in sales • Others: Black. Hawk, Staples, U-Line, Sustainable Supply, Amazon. Supply, Unisource/xpedx merger
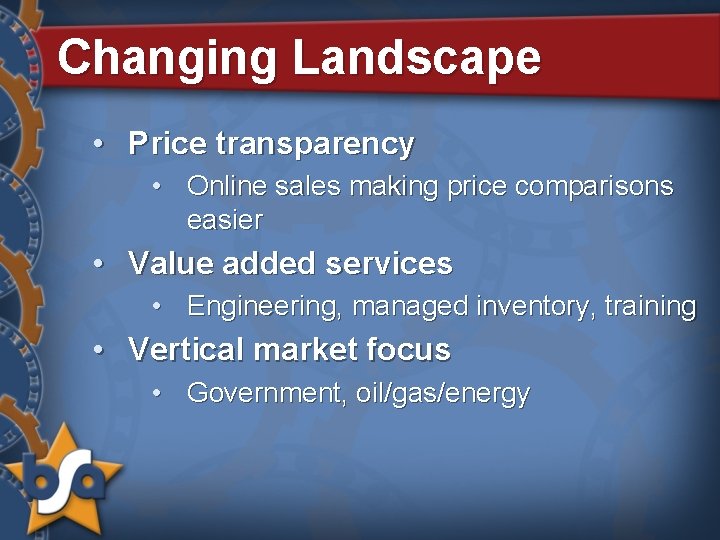
Changing Landscape • Price transparency • Online sales making price comparisons easier • Value added services • Engineering, managed inventory, training • Vertical market focus • Government, oil/gas/energy
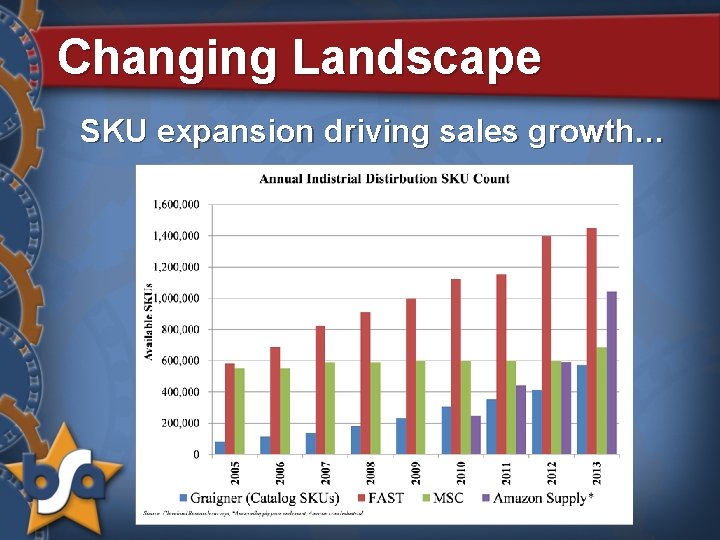
Changing Landscape SKU expansion driving sales growth…
Changing Landscape … blurring lines between industries
E-Commerce
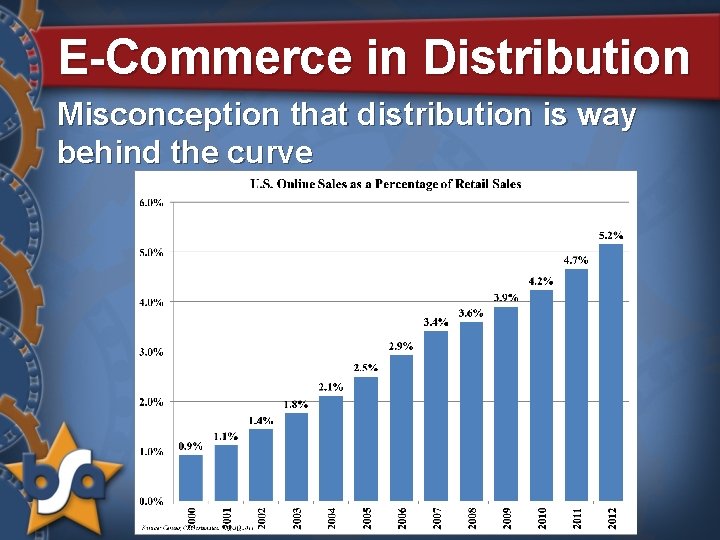
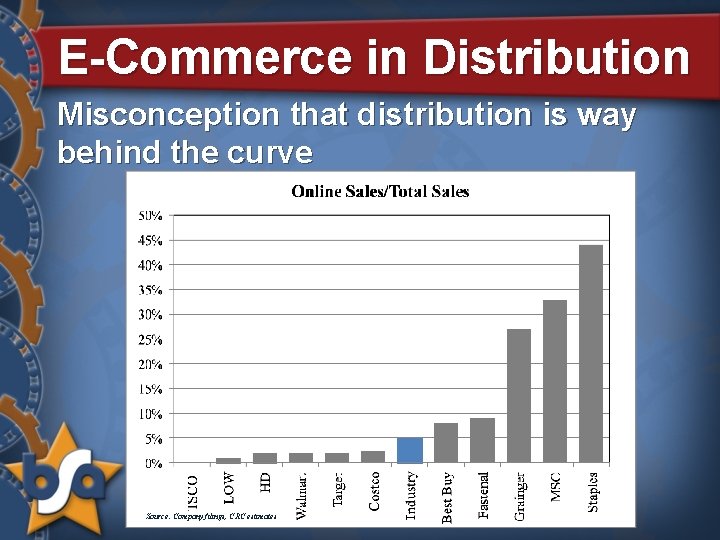
E-Commerce in Distribution Misconception that distribution is way behind the curve
E-Commerce in Distribution Misconception that distribution is way behind the curve Source: Company filings, CRC estimates
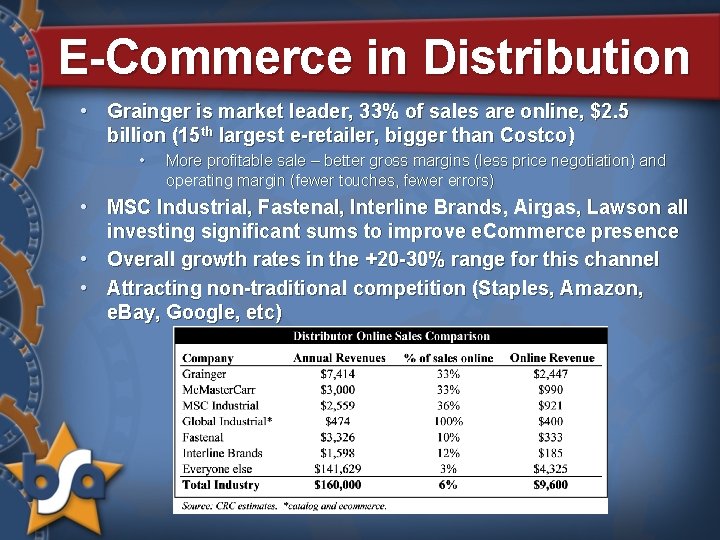
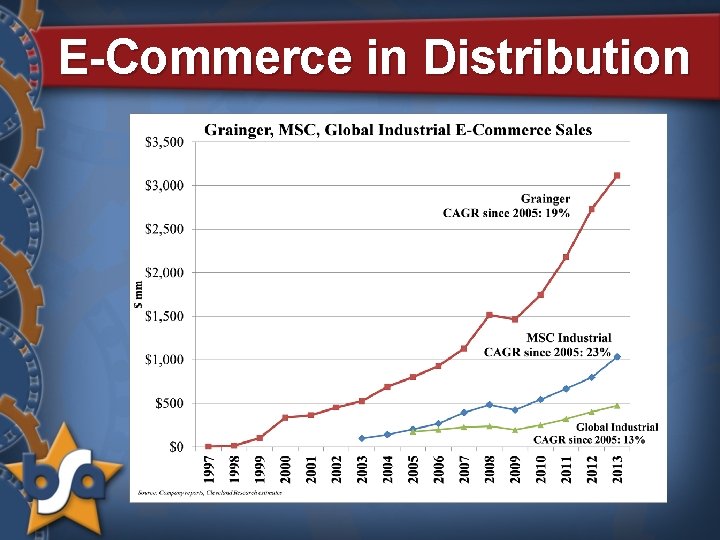
E-Commerce in Distribution • Grainger is market leader, 33% of sales are online, $2. 5 billion (15 th largest e-retailer, bigger than Costco) • More profitable sale – better gross margins (less price negotiation) and operating margin (fewer touches, fewer errors) • MSC Industrial, Fastenal, Interline Brands, Airgas, Lawson all investing significant sums to improve e. Commerce presence • Overall growth rates in the +20 -30% range for this channel • Attracting non-traditional competition (Staples, Amazon, e. Bay, Google, etc)
E-Commerce in Distribution
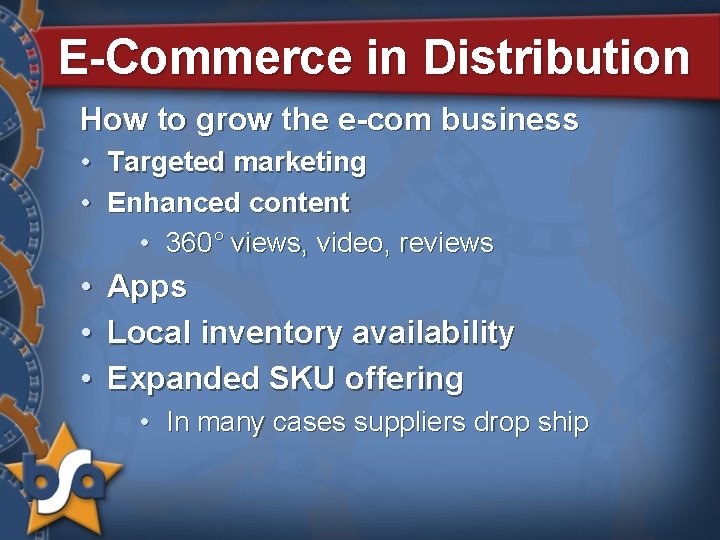
E-Commerce in Distribution How to grow the e-com business • • Targeted marketing Enhanced content • 360° views, video, reviews • • • Apps Local inventory availability Expanded SKU offering • In many cases suppliers drop ship
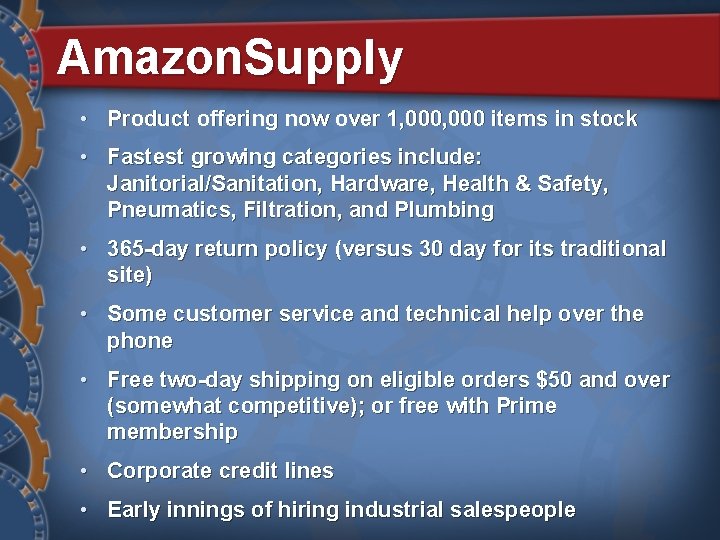
Amazon. Supply • Product offering now over 1, 000 items in stock • Fastest growing categories include: Janitorial/Sanitation, Hardware, Health & Safety, Pneumatics, Filtration, and Plumbing • 365 -day return policy (versus 30 day for its traditional site) • Some customer service and technical help over the phone • Free two-day shipping on eligible orders $50 and over (somewhat competitive); or free with Prime membership • Corporate credit lines • Early innings of hiring industrial salespeople
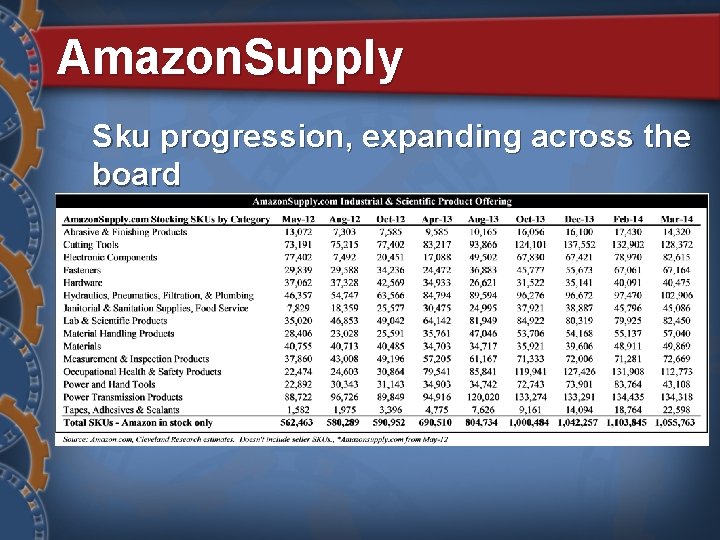
Amazon. Supply Sku progression, expanding across the board
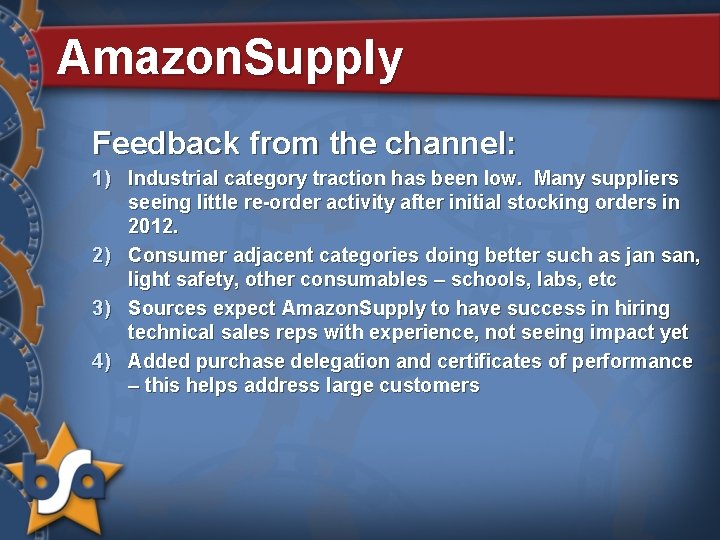
Amazon. Supply Feedback from the channel: 1) Industrial category traction has been low. Many suppliers seeing little re-order activity after initial stocking orders in 2012. 2) Consumer adjacent categories doing better such as jan san, light safety, other consumables – schools, labs, etc 3) Sources expect Amazon. Supply to have success in hiring technical sales reps with experience, not seeing impact yet 4) Added purchase delegation and certificates of performance – this helps address large customers
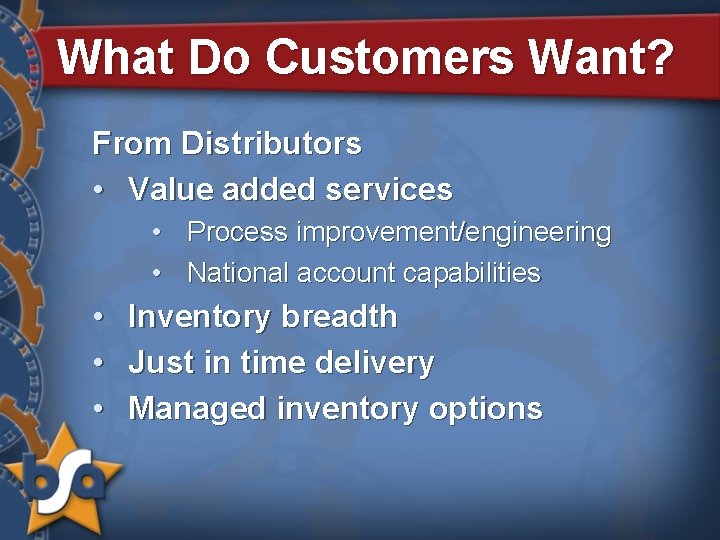
What Do Customers Want? From Distributors • Value added services • Process improvement/engineering • National account capabilities • • • Inventory breadth Just in time delivery Managed inventory options
What Do Customers Want? Vending • Up front 30%+ usage reduction • Accountability for employees and projects, data collecting • Safety • Move product closer to people • Lower overhead costs • Reduced labor for inventory management/distribution
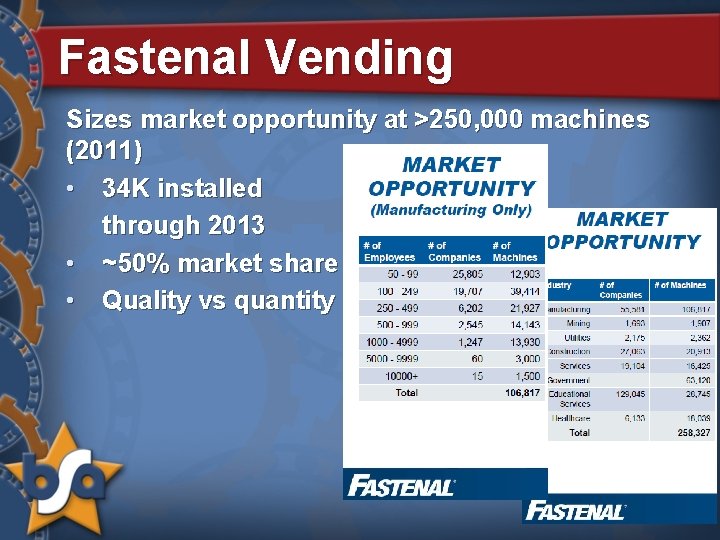
Fastenal Vending Sizes market opportunity at >250, 000 machines (2011) • 34 K installed through 2013 • ~50% market share • Quality vs quantity
What Do Investors Want? • Profitable growth • Organic or through acquisition • Forward looking investments • Salespeople • E-commerce capabilities • Footprint (distribution center or manufacturing)
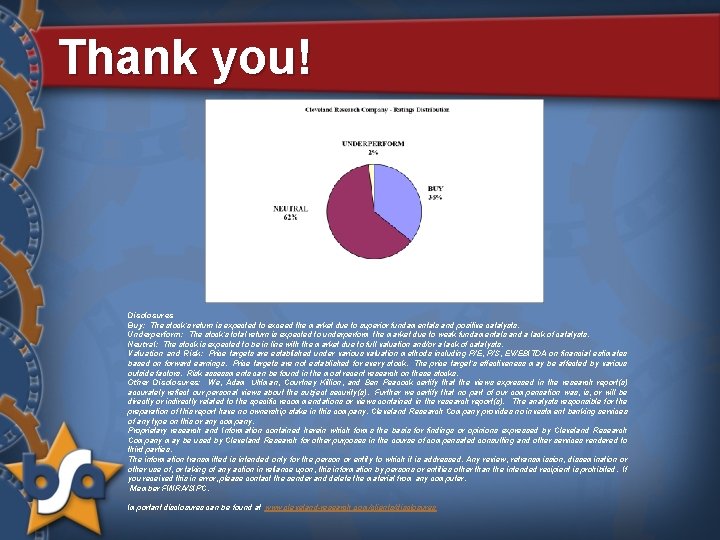
Thank you! Disclosures Buy: The stock’s return is expected to exceed the market due to superior fundamentals and positive catalysts. Underperform: The stock’s total return is expected to underperform the market due to weak fundamentals and a lack of catalysts. Neutral: The stock is expected to be in line with the market due to full valuation and/or a lack of catalysts. Valuation and Risk: Price targets are established under various valuation methods including P/E, P/S, EV/EBITDA on financial estimates based on forward earnings. Price targets are not established for every stock. The price target’s effectiveness may be affected by various outside factors. Risk assessments can be found in the most recent research on these stocks. Other Disclosures: We, Adam Uhlman, Courtney Killion, and Ben Peacock certify that the views expressed in the research report(s) accurately reflect our personal views about the subject security(s). Further we certify that no part of our compensation was, is, or will be directly or indirectly related to the specific recommendations or views contained in the research report(s). The analysts responsible for the preparation of this report have no ownership stake in this company. Cleveland Research Company provides no investment banking services of any type on this or any company. Proprietary research and Information contained herein which forms the basis for findings or opinions expressed by Cleveland Research Company may be used by Cleveland Research for other purposes in the course of compensated consulting and other services rendered to third parties. The information transmitted is intended only for the person or entity to which it is addressed. Any review, retransmission, dissemination or other use of, or taking of any action in reliance upon, this information by persons or entities other than the intended recipient is prohibited. If you received this in error, please contact the sender and delete the material from any computer. Member FINRA/SIPC. Important disclosures can be found at www. cleveland-research. com/clients/disclosures