Modern Auditing Assurance Services and the Integrity of
- Slides: 23
Modern Auditing: Assurance Services and the Integrity of Financial Reporting, 8 th Edition William C. Boynton California Polytechnic State University at San Luis Obispo Raymond N. Johnson Portland State University Chapter 21 – Internal, Operational, and Governmental Auditing
Chapter Overview
Internal Auditing Defined • Internal • Independent and objective • Systematic, disciplined approach • Helps and organization accomplish its objectives
Internal Auditing • Evolution of Internal Auditing • IIA Code of Ethics • IIA Attribute and Performance Standards – Attribute Standards – Performance Standards – Implementation Standards
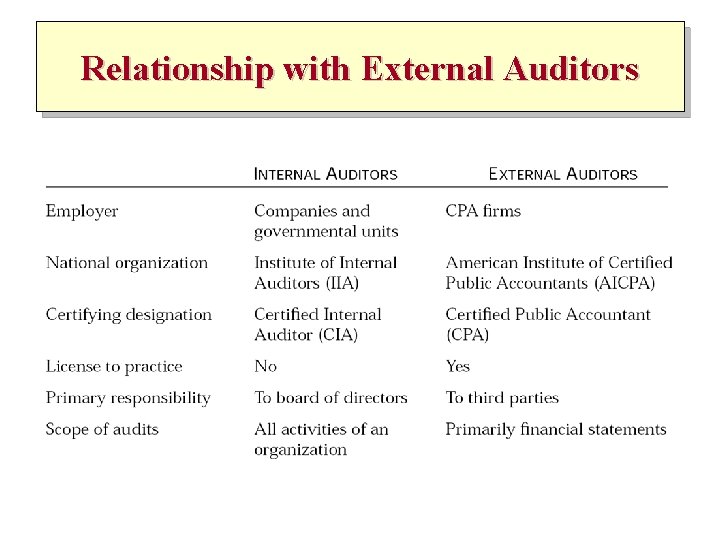
Relationship with External Auditors
Operational Auditing Defined • Systematic process • Evaluating an organization’s operations • Effectiveness, efficiency, and economy of operations • Reporting to appropriate persons • Recommendations for improvement
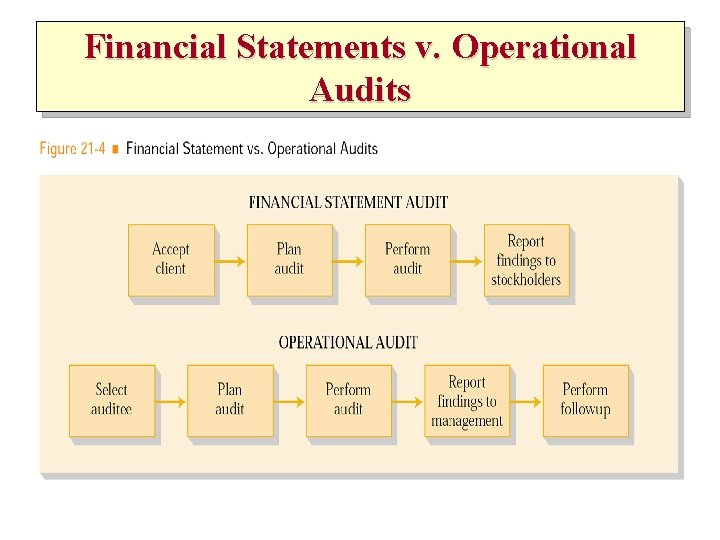
Phases of an Operational Audit • Select Auditee • Plan Audit • Perform Audit • Report Findings • Perform Followup
Financial Statements v. Operational Audits
Study Break 1. This part of the internal auditing definition states the auditor’s judgment has value when it is free of bias. A. B. C. D. Internal Independent and objective Systematic, disciplined approach Helps an organization accomplish its objectives B. Independent and objective
Study Break 2. These IIA Attribute and Performance standards describe the nature of internal audit services and provide quality criteria against which the performance of these services can be measured. A. B. C. D. Attribute Standards Performance Standards Implementation Standards None of the above B. Performance Standards
Study Break 3. Which of the following is not a phase of the operational audit? A. B. C. D. Select auditee Perform audit Report findings to stockholders Perform followup C. Report findings to stockholders
Types of Government Audits • Financial Audits • Attestation Engagements • Performance Audits
Generally Accepted Government Auditing Standards (GAGAS) • General Standards – Independence – Professional judgment – Competence – Quality Control and Assurance
Generally Accepted Government Auditing Standards (GAGAS) • Fieldwork Standards for Financial Audits – Auditor communication – Considering the results of previous audit and attestation engagements – Detecting material misstatements resulting from violations of contract provisions or grant agreements, or from abuse – Developing elements of a finding – Audit documentation
Generally Accepted Government Auditing Standards (GAGAS) • Reporting Standards for Financial Audits – Reporting auditors’ compliance with GAGAS – Reporting on internal control and on compliance with laws, regulations, and provisions of contracts or grant agreements – Reporting deficiencies in internal control, fraud, illegal acts, violations of provisions of contracts or grand agreements, and abuse
Generally Accepted Government Auditing Standards (GAGAS) • Reporting Standards for Financial Audits – Reporting views of responsible officials – Reporting privileged and confidential information – Report issuance and distribution
Generally Accepted Government Auditing Standards (GAGAS) • Reporting on Compliance with Laws and Regulations • Reporting on Internal Control
The Single Audit Act • Objectives of the Act – Improve financial management – Establish uniform requirements for audits – Promote efficient and effective use of audit resources – Ensure reliance and usage of audit work completed
The Single Audit Act • Applicability and Administration – Federal Financial Assistance – Major Programs – Nonmajor Programs – Cognizant Agency
Scope of an Audit Under the Single Audit Act • General – – Financial Statements Internal Controls Compliance Audit Followup • Reporting Requirements – – Opinion on Financial Statements Report on Internal Control Report on Compliance Schedule of Findings and Questioned Costs
Study Break 4. This type of government audit concern examining, reviewing, or performing agreedupon procedures on a subject matter or an assertion about a subject matter and reporting on the results. A. B. C. D. Financial audits Attestation engagements Performance audits Compliance audits B. Attestation engagements
Study Break 5. Within the General Standards of GAGAS, this standard states that staff assigned to perform the audit or attestation should collectively possess adequate professional competence for the tasks required. A. B. C. D. Independence Professional judgment Competence Quality Control and Assurance C. Competence
Study Break 6. This act established the concept of a single organizationwide government audit encompassing both financial and compliance audits. A. B. C. D. Securities Act of 1933 Securities Act of 1934 Single Audit Act None of the above C. Single Audit Act