
Modern Auditing Assurance Services and the Integrity of
- Slides: 26
Modern Auditing: Assurance Services and the Integrity of Financial Reporting, 8 th Edition William C. Boynton California Polytechnic State University at San Luis Obispo Raymond N. Johnson Portland State University Chapter 2 – Auditors’ Responsibilities and Reports
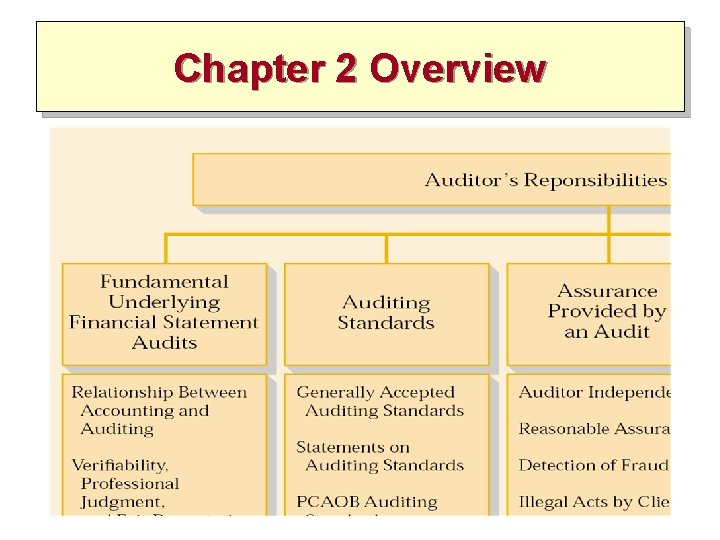
Chapter 2 Overview
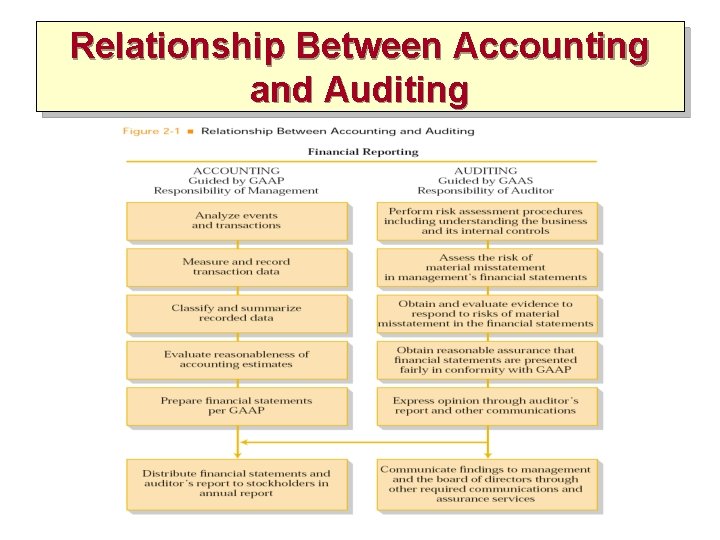
Relationship Between Accounting and Auditing
Important Fundamental Concepts • Verifiability • Fair Presentation • Professional Judgment • Materiality
Independent Auditor Relationships • Management • Board of Directors and Audit Committee • Internal Auditors • Stockholders
Study Break 1. It is the responsibility of management to complete all of the following except: A. Assess the risk of material misstatement in the financial statements B. Measure and record transaction data C. Classify and summarize recorded data D. Prepare financial statements per GAAP A. Assess the risk of material misstatement in the financial statements
Study Break 2. Items that are considered to be _____, are significant to financial statement users. A. Verifiable B. Material C. Fairly Presented D. Recorded B. Material
Generally Accepted Auditing Standards (GAAS) • General Standards • Standards of Field Work • Standards of Reporting
GAAS – General Standards • Adequate Technical Training and Proficiency • Independence in Mental Attitude • Due Professional Care
GAAS – Standards of Field Work • Adequate Planning and Proper Supervision • Understanding the Entity, Environment, and Internal Control • Sufficient Competent Audit Evidence
GAAS – Standards of Reporting • Financial Statements Presented in Accordance with GAAP • Consistency in the Application of GAAP • Adequacy of Informative Disclosures • Expression of Opinion
Additional Standards • Statements on Auditing Standards – AICPA website : Audit and Attest Standards • PCAOB Auditing Standards – Public Companies Accounting Oversight Board website
Study Break 3. General Standards include all of the following except: A. Adequate Training B. Independence C. Understanding the Entity D. Due Professional Care C. Understanding the Entity
Study Break 4. These standards pertain specifically to the conduct of the audit at the entity’s place of business. A. General Standards B. Standards of Field Work C. Standards of Reporting D. Statement on Auditing Standards B. Standards of Field Work
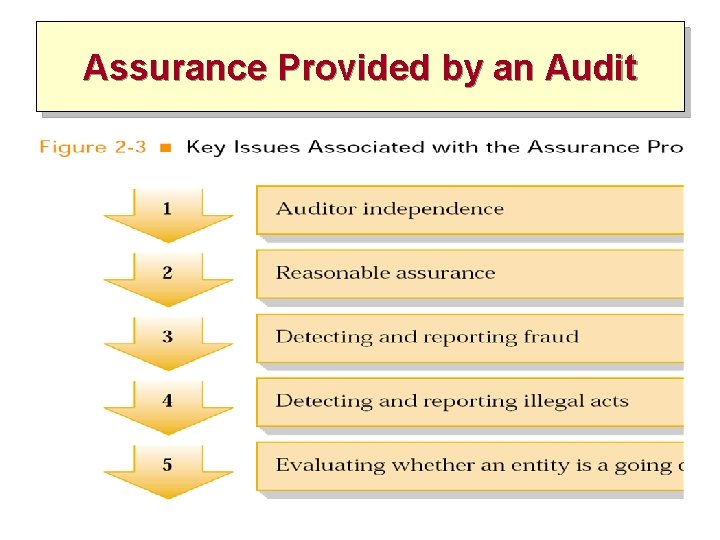
Assurance Provided by an Audit
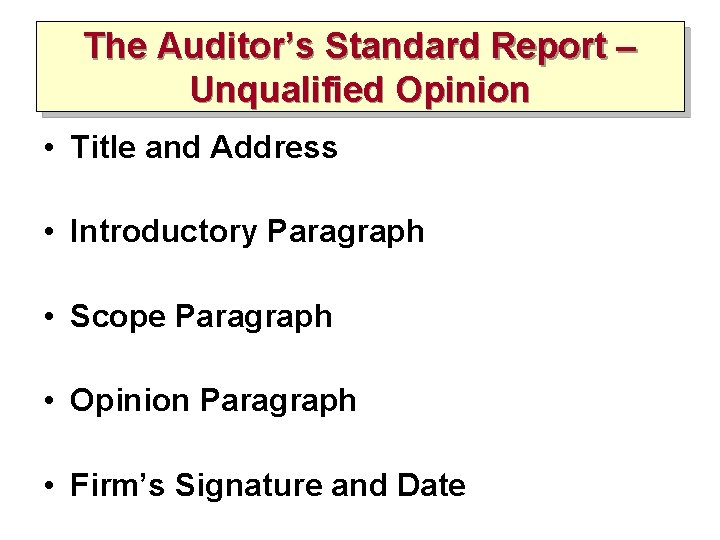
The Auditor’s Standard Report – Unqualified Opinion • Title and Address • Introductory Paragraph • Scope Paragraph • Opinion Paragraph • Firm’s Signature and Date
Departures from the Standard Report • Standard Report with Explanatory Language • Qualified Opinion • Adverse Opinion • Disclaimer of Opinion
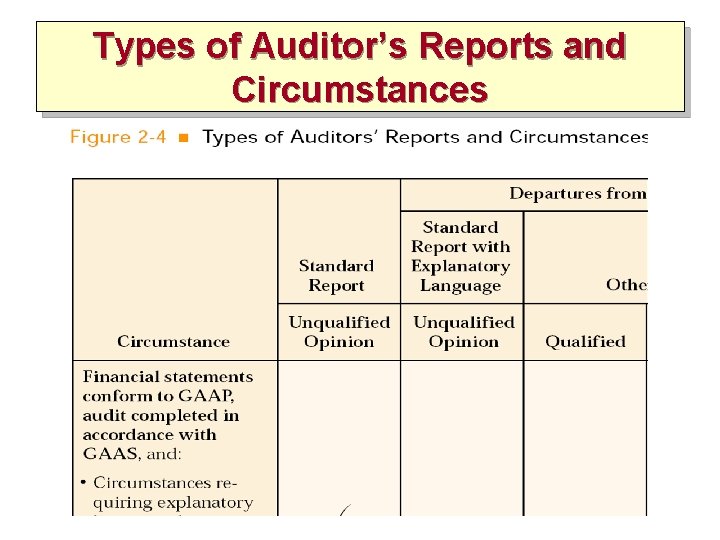
Types of Auditor’s Reports and Circumstances
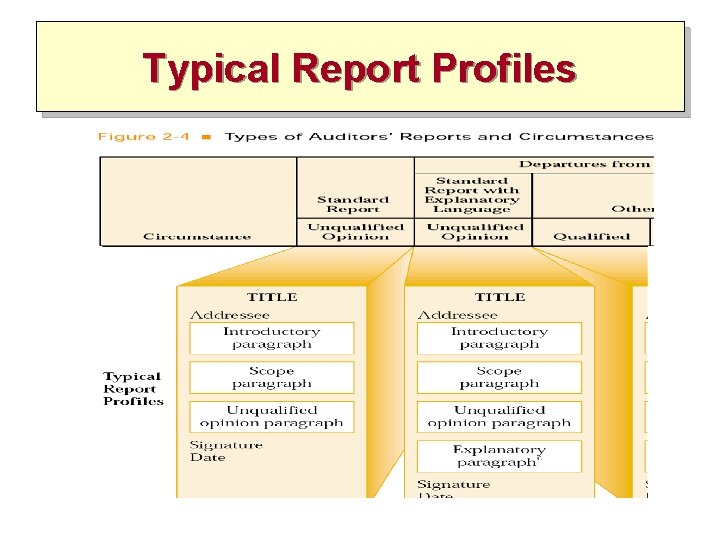
Typical Report Profiles
The Auditor’s Standard Report on Internal Controls • Title and Address • Introductory Paragraph • Scope Paragraph • Definition Paragraph
The Auditor’s Standard Report on Internal Controls (cont. ) • Inherent Limitations Paragraph • Opinion Paragraph • Explanatory Paragraph • Firm’s Signature and Date
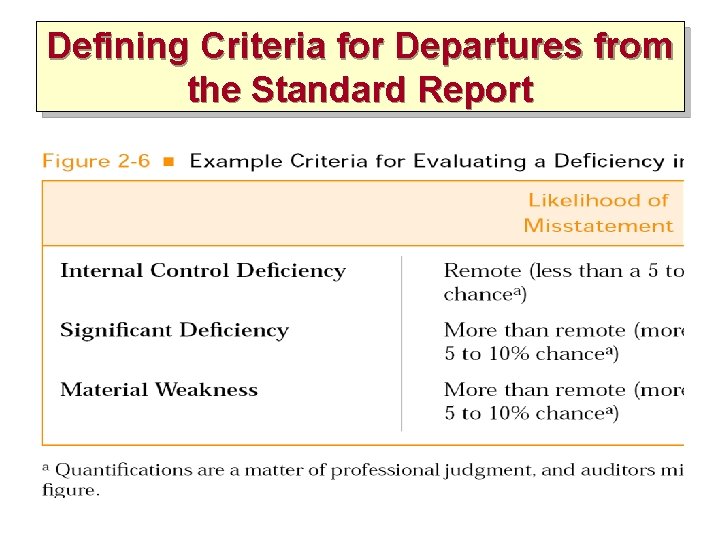
Defining Criteria for Departures from the Standard Report
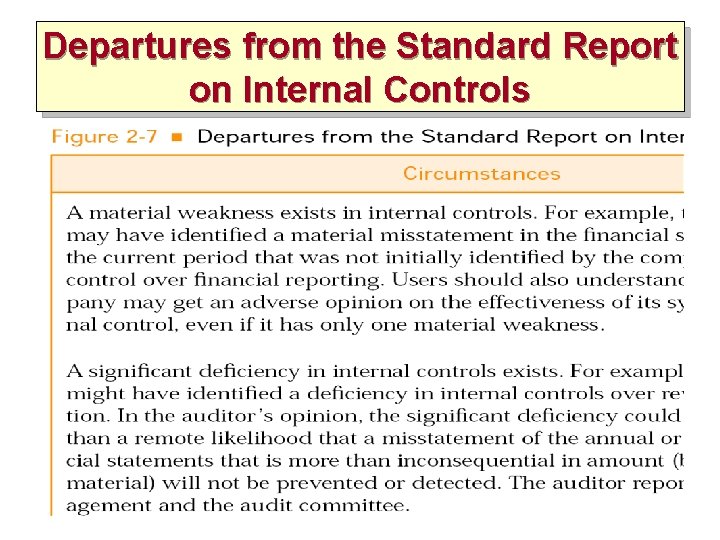
Departures from the Standard Report on Internal Controls
Study Break 5. All of the following are components of assurance provided by an audit except: A. Auditor independence B. Reasonable assurance C. Detecting and reporting illegal acts D. Guaranteed accuracy of financial statements
Study Break 6. The standard report includes all of the following except: A. Introductory Paragraph B. Scope Paragraph C. Explanatory Language Paragraph D. Opinion Paragraph C. Explanatory Language Paragraph
Study Break 7. This opinion states that the auditor does not express and opinion on the financial statements. A. Unqualified Opinion B. Qualified Opinion C. Adverse Opinion D. Disclaimer of Opinion