Insert Picture Here Customer Centricity Driving Growth in
- Slides: 30
<Insert Picture Here> Customer Centricity - Driving Growth in Today's Leading Banks • Larry Dalus • Senior Solutions Consultant, Financial Services Industry • Oracle Corporation
Safe Harbor Statement The following is intended to outline our general product direction. It is intended for information purposes only, and may not be incorporated into any contract. It is not a commitment to deliver any material, code, or functionality, and should not be relied upon in making purchasing decision. The development, release, and timing of any features or functionality described for Oracle’s products remains at the sole discretion of Oracle. 2
Customer Service – A Sustainable Competitive Differentiator? “The customer should only have to ask once” “Leveraging the service profit chain” “Our mission is to be a Premier Bank in the Asia-Pacific region, committed to providing Quality Products and Excellent Customer Service. ” “Understanding and responding to our customer needs is fundamental to the way we do business” “Fundamentally, we our improved performance to a customer-centric approach that puts customers at the core of our business strategy” “We listen to our customers and understand their needs” “Reaching Out To You” “Helping You Get On With Life” 3
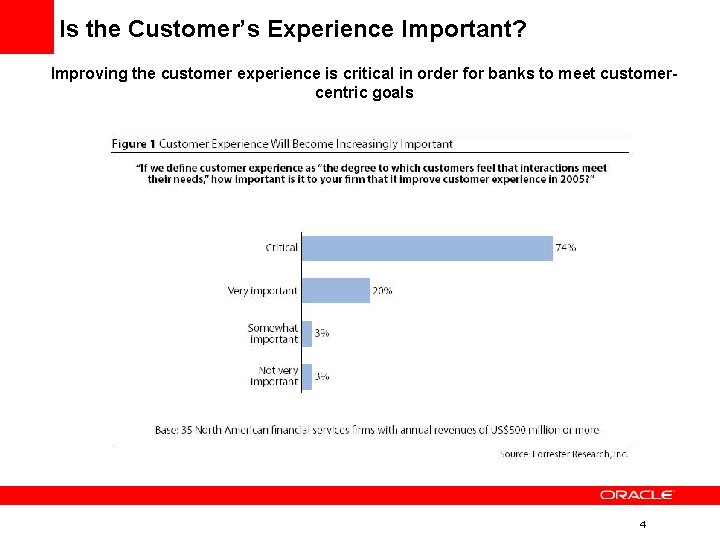
Is the Customer’s Experience Important? Improving the customer experience is critical in order for banks to meet customercentric goals 4
What is an Exceptional Customer Experience? • Every customer interaction is a “moment of truth” – a point in time where the customer will form a view of the Bank and their willingness to continue the relationship • Ingredients of an exceptional customer experience includes: – Know your customer – Anticipate and understand their needs, up-servicing the customer – Being a customer advocate and trust advisor – Leveraging existing customer and interaction data – Only ask for customer for specific information once, but capture for future use – Address issue promptly removing any non-value added processes – Regularly update and realign to changing customer needs and feedback 5
Challenges to Delivering an Exceptional Customer Experience FACTOR CHALLENGE Customer Recognition Bank’s are required to scale relationships across millions of customers Blended Sales & Service >80% of customer interactions are purely service transactions Consultative Selling Agents and sales reps focus on selling the most familiar products Follow Up Leads Customer requests not fulfilled at the point of communication Multi-Channel Capabilities Customer interactions typically span multiple channels 6
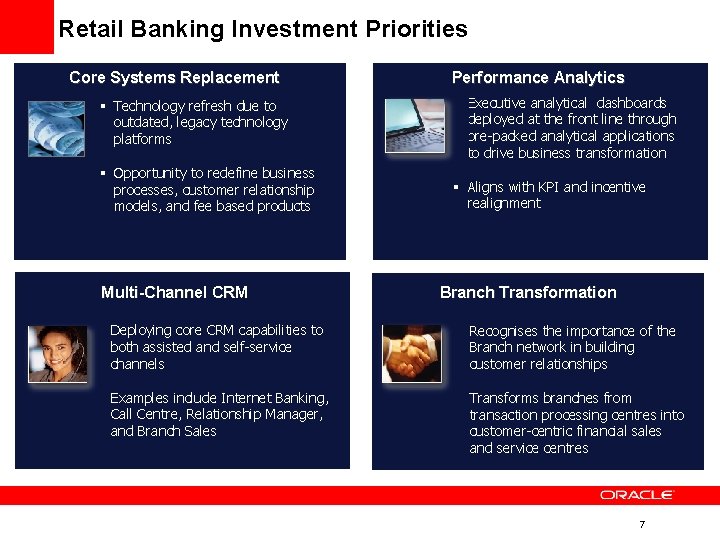
Retail Banking Investment Priorities Core Systems Replacement Performance Analytics § Technology refresh due to outdated, legacy technology platforms § Executive analytical dashboards deployed at the front line through pre-packed analytical applications to drive business transformation § Opportunity to redefine business processes, customer relationship models, and fee based products § Aligns with KPI and incentive realignment Multi-Channel CRM Branch Transformation § Deploying core CRM capabilities to both assisted and self-service channels § Recognises the importance of the Branch network in building customer relationships § Examples include Internet Banking, Call Centre, Relationship Manager, and Branch Sales § Transforms branches from transaction processing centres into customer-centric financial sales and service centres 7
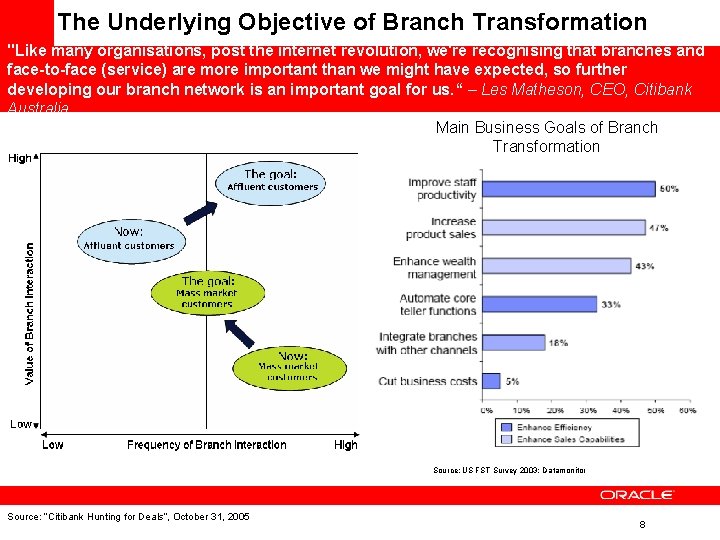
The Underlying Objective of Branch Transformation "Like many organisations, post the internet revolution, we're recognising that branches and face-to-face (service) are more important than we might have expected, so further developing our branch network is an important goal for us. “ – Les Matheson, CEO, Citibank Australia Main Business Goals of Branch Transformation Source: US FST Survey 2003; Datamonitor Source: “Citibank Hunting for Deals”, October 31, 2005 8
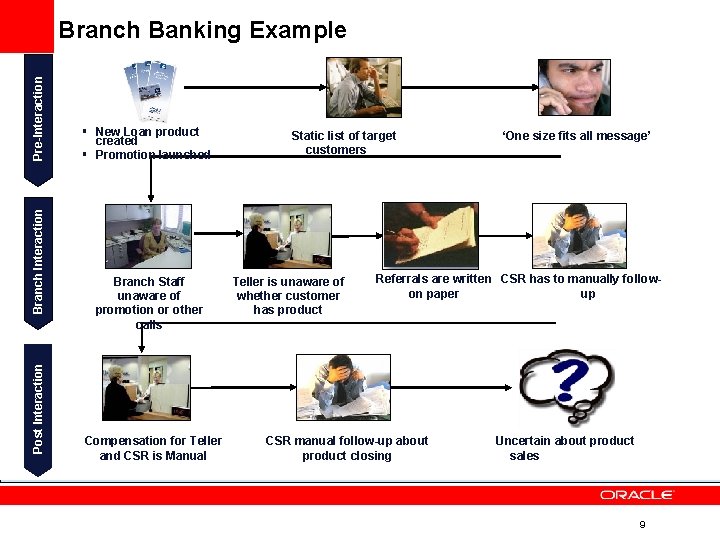
Post Interaction Branch Interaction Pre-Interaction Branch Banking Example § New Loan product created § Promotion launched Branch Staff unaware of promotion or other calls Compensation for Teller and CSR is Manual Static list of target customers Teller is unaware of whether customer has product ‘One size fits all message’ Referrals are written CSR has to manually followon paper up CSR manual follow-up about product closing Uncertain about product sales 9
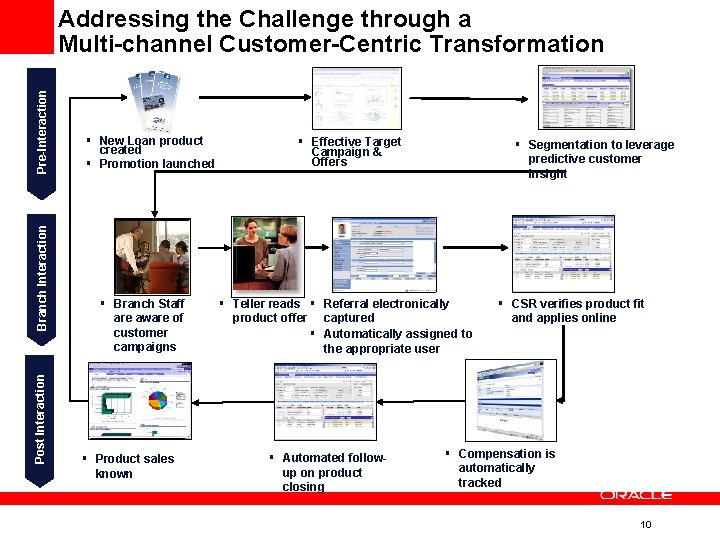
Post Interaction Branch Interaction Pre-Interaction Addressing the Challenge through a Multi-channel Customer-Centric Transformation § New Loan product created § Promotion launched § Branch Staff are aware of customer campaigns § Product sales known § Effective Target Campaign & Offers § Segmentation to leverage predictive customer insight § Teller reads § Referral electronically product offer captured § Automatically assigned to the appropriate user § Automated followup on product closing § CSR verifies product fit and applies online § Compensation is automatically tracked 10
Siebel CRM 8 – Transformational CRM Empower Users – Provide proactive, real time insight at the moment of customer interaction through a flexible, role-based user interface Enable Business Responsiveness – Enable the business to respond to ongoing business process changes and to directly improve the customer experience Ensure Value – Provide choice by supporting multiple deployment options and ease of integration at the lowest cost 11
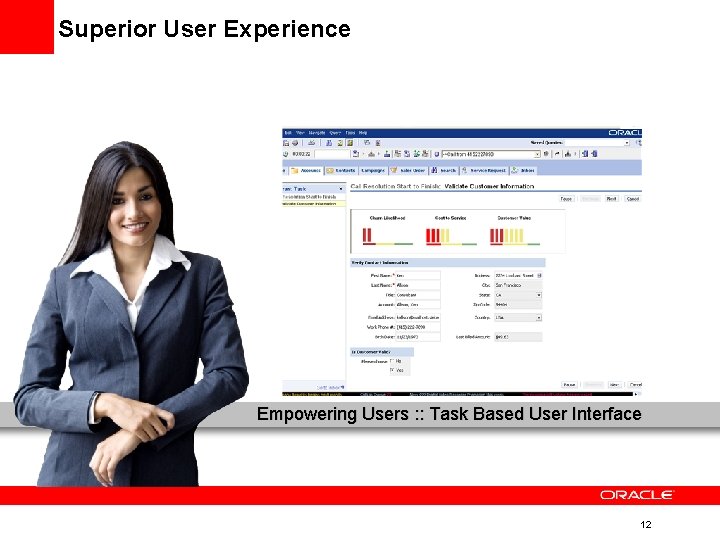
Superior User Experience Empowering Users : : Task Based User Interface 12
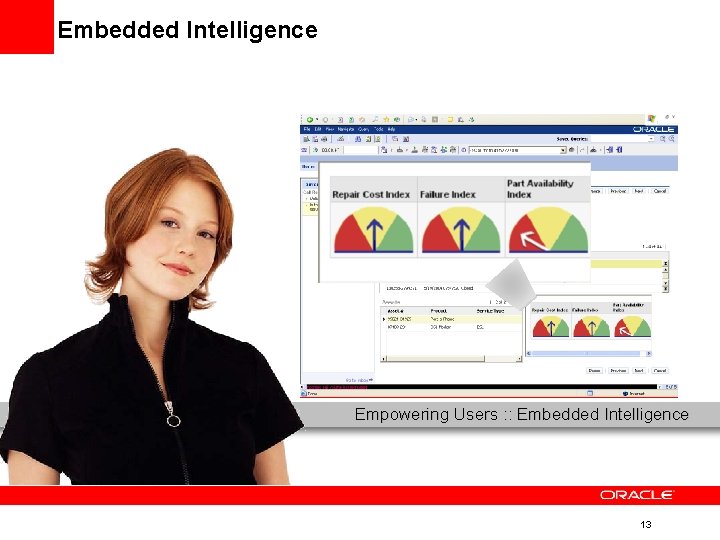
Embedded Intelligence Empowering Users : : Embedded Intelligence 13
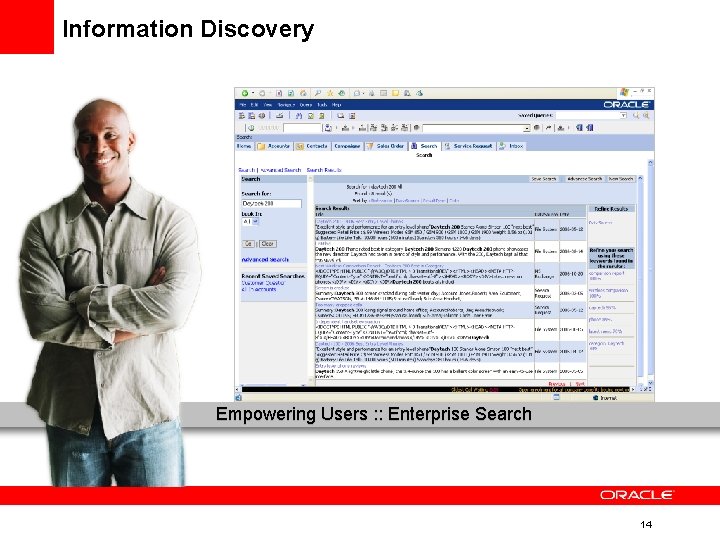
Information Discovery Empowering Users : : Enterprise Search 14
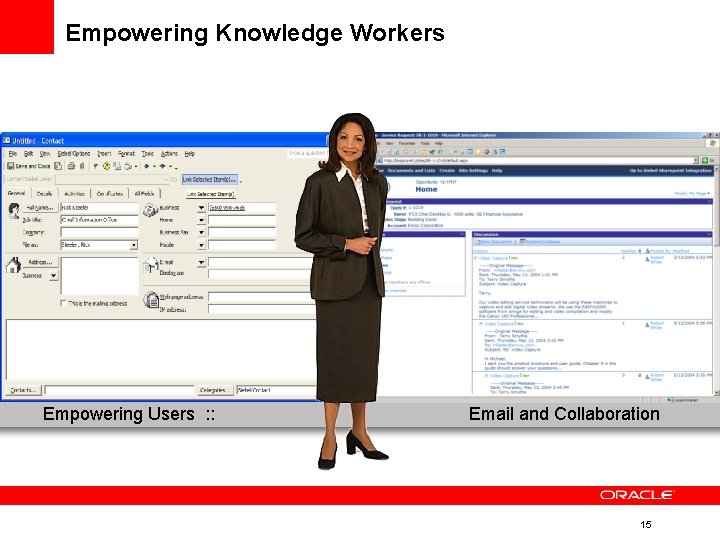
Empowering Knowledge Workers Empowering Users : : Email and Collaboration 15
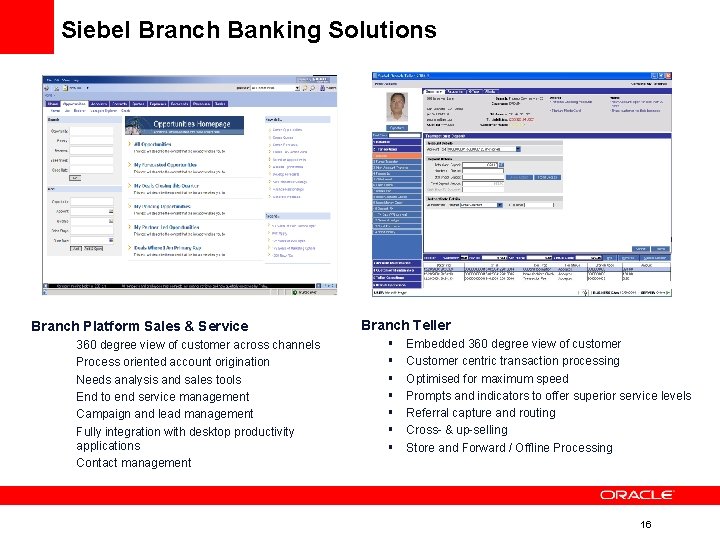
Siebel Branch Banking Solutions Branch Platform Sales & Service § § § § 360 degree view of customer across channels Process oriented account origination Needs analysis and sales tools End to end service management Campaign and lead management Fully integration with desktop productivity applications Contact management Branch Teller § § § § Embedded 360 degree view of customer Customer centric transaction processing Optimised for maximum speed Prompts and indicators to offer superior service levels Referral capture and routing Cross- & up-selling Store and Forward / Offline Processing 16
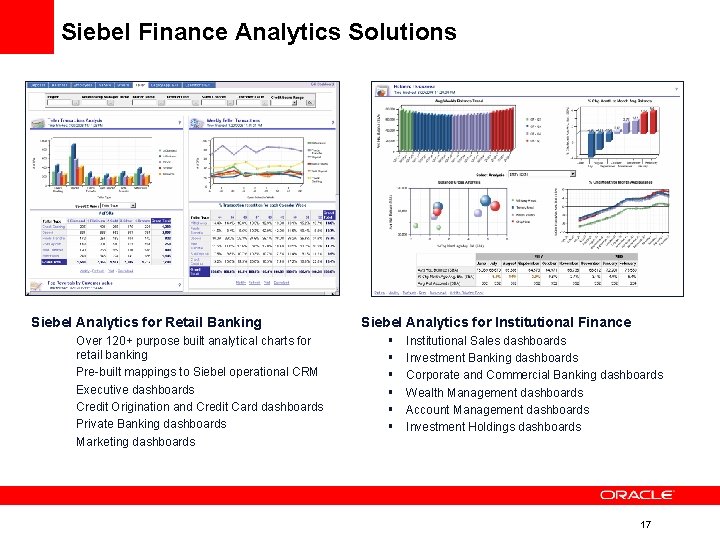
Siebel Finance Analytics Solutions Siebel Analytics for Retail Banking § Over 120+ purpose built analytical charts for retail banking § Pre-built mappings to Siebel operational CRM § Executive dashboards § Credit Origination and Credit Card dashboards § Private Banking dashboards § Marketing dashboards Siebel Analytics for Institutional Finance § § § Institutional Sales dashboards Investment Banking dashboards Corporate and Commercial Banking dashboards Wealth Management dashboards Account Management dashboards Investment Holdings dashboards 17
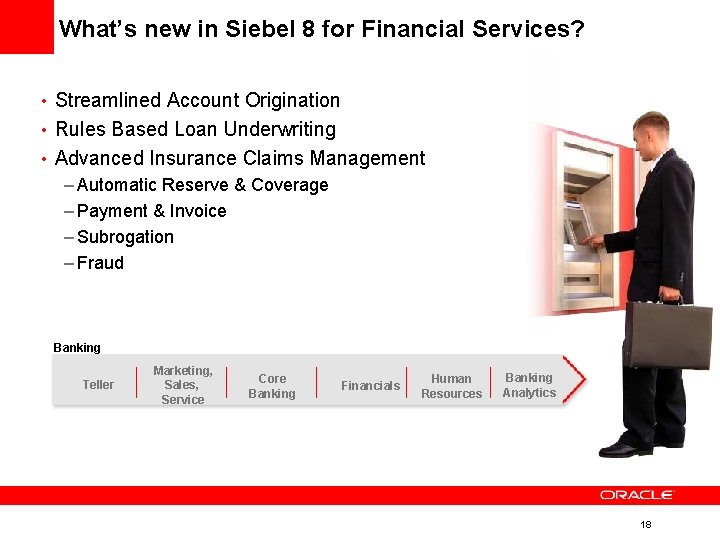
What’s new in Siebel 8 for Financial Services? • Streamlined Account Origination • Rules Based Loan Underwriting • Advanced Insurance Claims Management – Automatic Reserve & Coverage – Payment & Invoice – Subrogation – Fraud Banking Teller Marketing, Sales, Service Core Banking Financials Human Resources Banking Analytics 18
The Global Leader in Front Office Solutions for Retail Banking 19
Westpac Banking Corporation • As of September 30, 2005 Westpac had: – 27, 000 Employees – Global assets of $260 billion AUD – Net profit after income tax was $2, 818 million • Westpac is ranked in the top 10 listed companies by market capitalisation on the Australian Stock Exchange Limited (ASX) • Westpac serves 8. 3 million customers, through key business areas of: – Business and Consumer Banking – Wealth Management – Institutional Banking 20
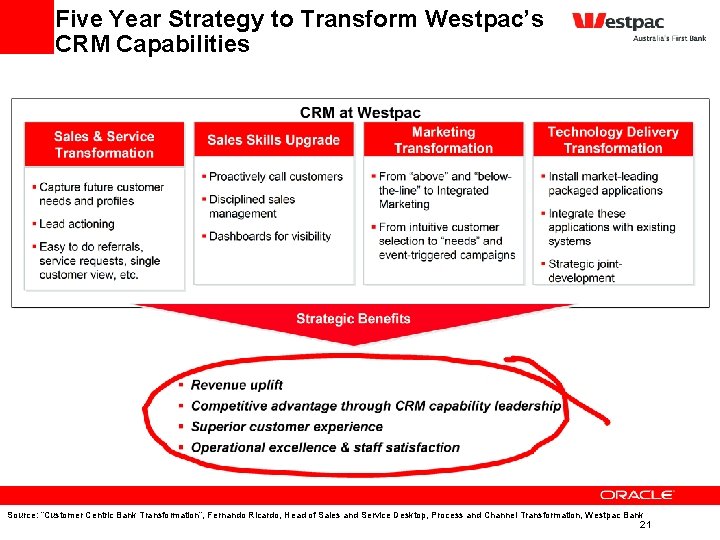
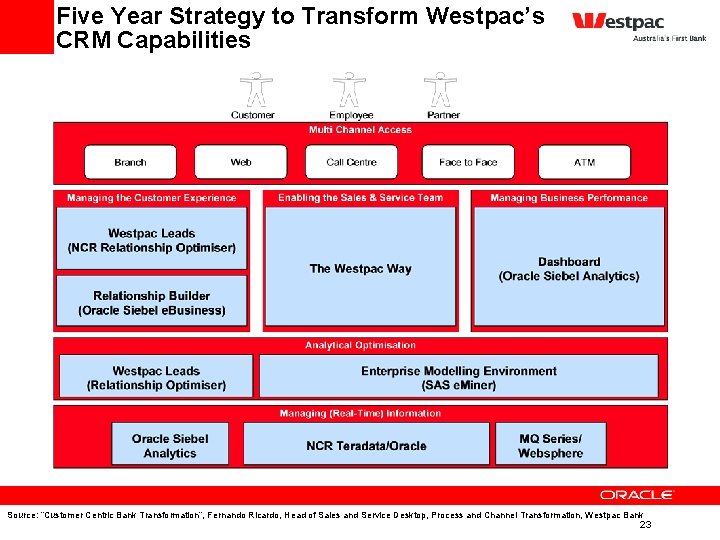
Five Year Strategy to Transform Westpac’s CRM Capabilities Source: “Customer Centric Bank Transformation”, Fernando Ricardo, Head of Sales and Service Desktop, Process and Channel Transformation, Westpac Bank 21
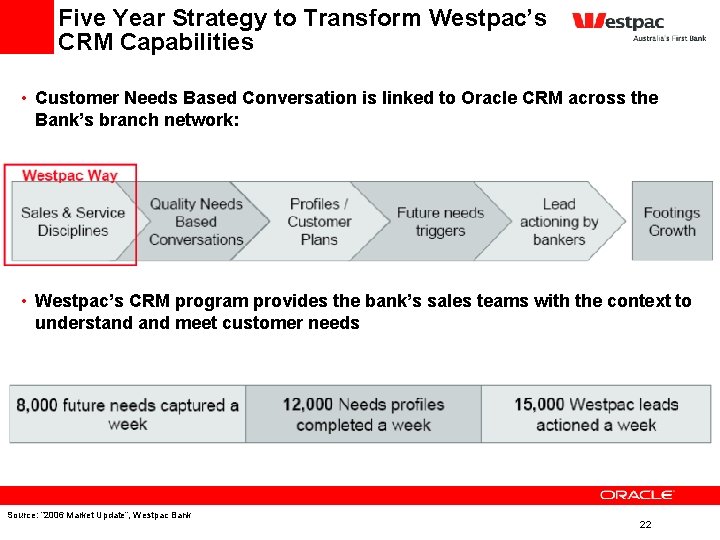
Five Year Strategy to Transform Westpac’s CRM Capabilities • Customer Needs Based Conversation is linked to Oracle CRM across the Bank’s branch network: • Westpac’s CRM program provides the bank’s sales teams with the context to understand meet customer needs Source: “ 2006 Market Update”, Westpac Bank 22
Five Year Strategy to Transform Westpac’s CRM Capabilities Source: “Customer Centric Bank Transformation”, Fernando Ricardo, Head of Sales and Service Desktop, Process and Channel Transformation, Westpac Bank 23
Five Year Strategy to Transform Westpac’s CRM Capabilities Source: “Customer Centric Bank Transformation”, Fernando Ricardo, Head of Sales and Service Desktop, Process and Channel Transformation, Westpac Bank 24
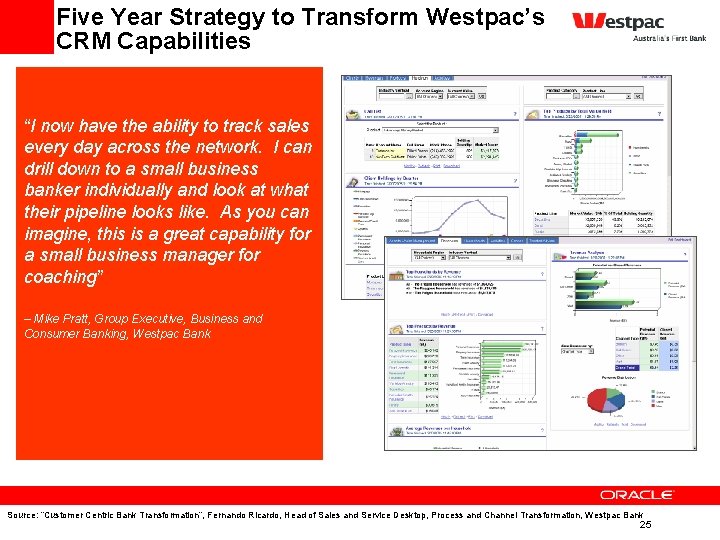
Five Year Strategy to Transform Westpac’s CRM Capabilities “I now have the ability to track sales every day across the network. I can drill down to a small business banker individually and look at what their pipeline looks like. As you can imagine, this is a great capability for a small business manager for coaching” – Mike Pratt, Group Executive, Business and Consumer Banking, Westpac Bank Source: “Customer Centric Bank Transformation”, Fernando Ricardo, Head of Sales and Service Desktop, Process and Channel Transformation, Westpac Bank 25
• 155 Year Old Bank of the Philippine Islands – 11, 000 Employees – 890 Branches – Assets of over $10 Billion USD – Headquartered in Manila • Significant Market Share: – 2. 6 Million Customers – Second largest commercial bank • For years, international publications and rating agencies have given annual awards to BPI as one of the best banks in the region. • Among these are the Far Eastern Economic Review, The Banker, Euromoney, Asiamoney, Business. Week, The Asset, Global Finance, Finance Asia, and The Asian Banker. 26
• BPI recognised the need to constantly look for ways to maintain its market leading position, viewing technology as vital to supporting their business strategy • In 2001, BPI became the first bank in the Philippines to implement a Customer Relationship Management (CRM) system. This was to address: – No centralised sales system – RM’s using different application or manual paper files to locate customer information – RM’s managed their time and client data using paper calendars and notebooks – No automated method of monitoring sales campaign responses, gleaming knowledge from sales data, or targeting campaigns to specific customer segments • “Our vision was to become a customer centric organisation, delivering personalised service and superior products. But even at the branch level we had no standard way of managing customer relationships or leveraging cross-sell opportunities” - Arlene S. Dayrit, Assistant Vice President, CRM, Bank of the Philippine Islands 27
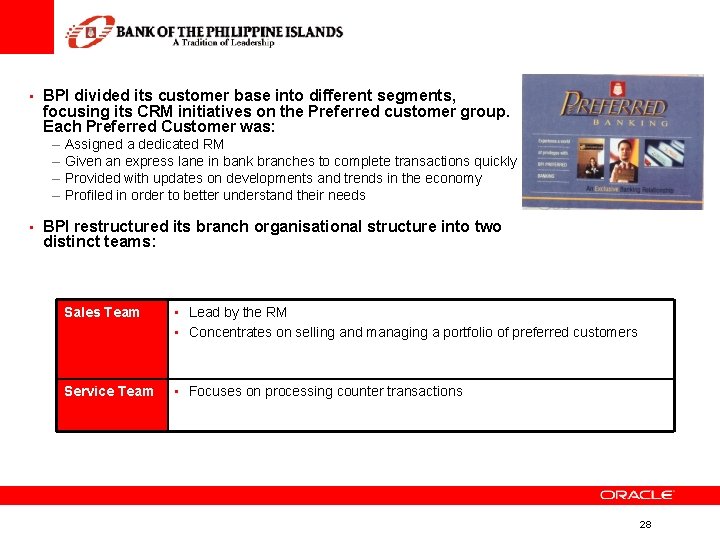
• BPI divided its customer base into different segments, focusing its CRM initiatives on the Preferred customer group. Each Preferred Customer was: – – Assigned a dedicated RM Given an express lane in bank branches to complete transactions quickly Provided with updates on developments and trends in the economy Profiled in order to better understand their needs • BPI restructured its branch organisational structure into two distinct teams: Sales Team • Lead by the RM • Concentrates on selling and managing a portfolio of preferred customers Service Team • Focuses on processing counter transactions 28
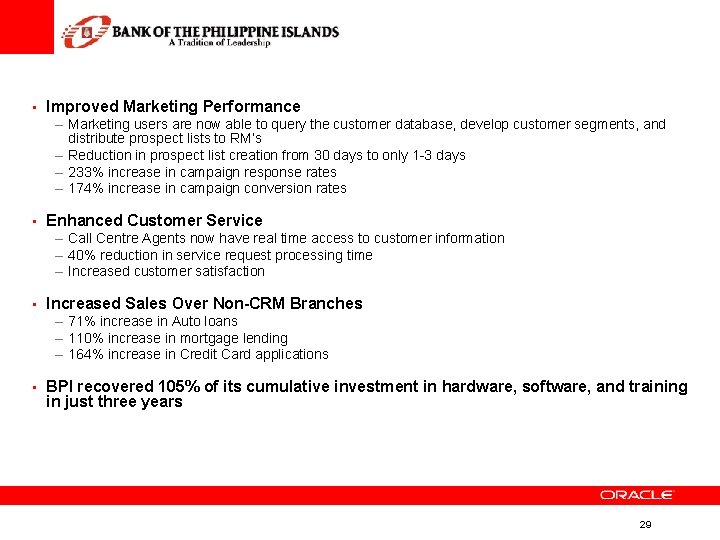
• Improved Marketing Performance – Marketing users are now able to query the customer database, develop customer segments, and distribute prospect lists to RM’s – Reduction in prospect list creation from 30 days to only 1 -3 days – 233% increase in campaign response rates – 174% increase in campaign conversion rates • Enhanced Customer Service – Call Centre Agents now have real time access to customer information – 40% reduction in service request processing time – Increased customer satisfaction • Increased Sales Over Non-CRM Branches – 71% increase in Auto loans – 110% increase in mortgage lending – 164% increase in Credit Card applications • BPI recovered 105% of its cumulative investment in hardware, software, and training in just three years 29
<Insert Picture Here> Customer Centricity - Driving Growth in Today's Leading Banks Oracle | Siebel CRM 8