India the Italcementi experience Rodolfo Danielli Chief Operating
- Slides: 15
India: the Italcementi experience Rodolfo Danielli Chief Operating Officer Milano, February 23 rd , 2006 0
Index Italcementi Group The Indian Market Indian Presence 1
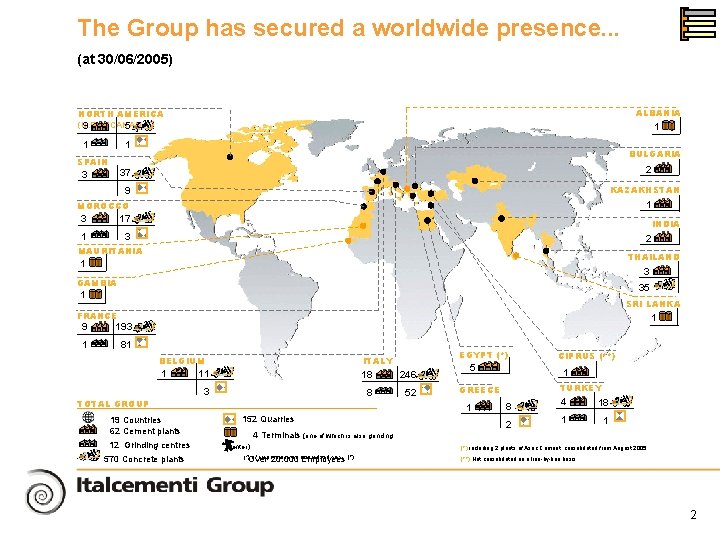
The Group has secured a worldwide presence. . . (at 30/06/2005) ALBANIA NORTH AMERICA (U. S. A. /CANADA) 9 5 1 1 1 SPAIN BULGARIA 2 37 3 KAZAKHSTAN 9 1 MOROCCO 3 17 1 3 INDIA 2 MAURITANIA THAILAND 1 3 GAMBIA 35 1 SRI LANKA FRANCE 9 193 1 81 1 BELGIUM 1 11 18 3 8 TOTAL GROUP 19 Countries 62 Cement plants 12 Grinding centres 570 Concrete plants EGYPT (*) ITALY 246 52 5 152 Quarries 4 Terminals (one of which is also grinding center) (*) N° employees in the consolidated area Over 20. 000 Employees (*) 1 TURKEY GREECE 1 CIPRUS (**) 8 4 18 2 1 1 (*) including 2 plants of Asec Cement, consolidated from August 2005 (**) Not consolidated on a line-by-line basis 2
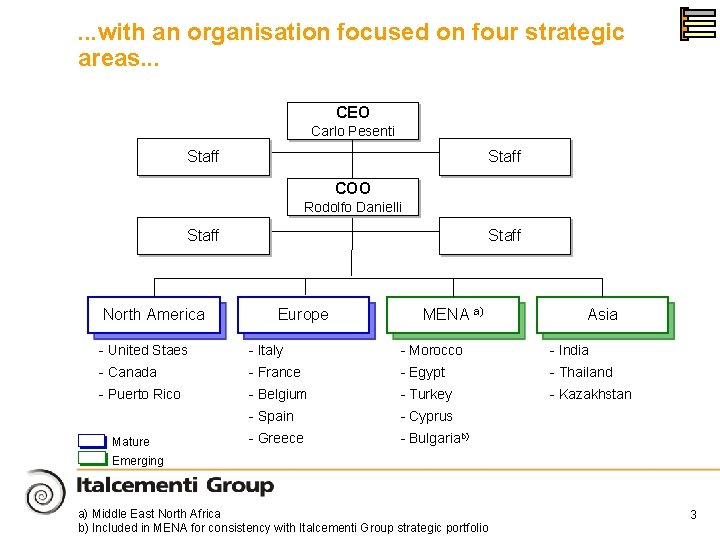
. . . with an organisation focused on four strategic areas. . . CEO Carlo Pesenti Staff COO Rodolfo Danielli Staff North America Europe MENA a) Asia - United Staes - Italy - Morocco - India - Canada - France - Egypt - Thailand - Puerto Rico - Belgium - Turkey - Kazakhstan - Spain - Cyprus - Greece - Bulgariab) Mature Emerging a) Middle East North Africa b) Included in MENA for consistency with Italcementi Group strategic portfolio 3
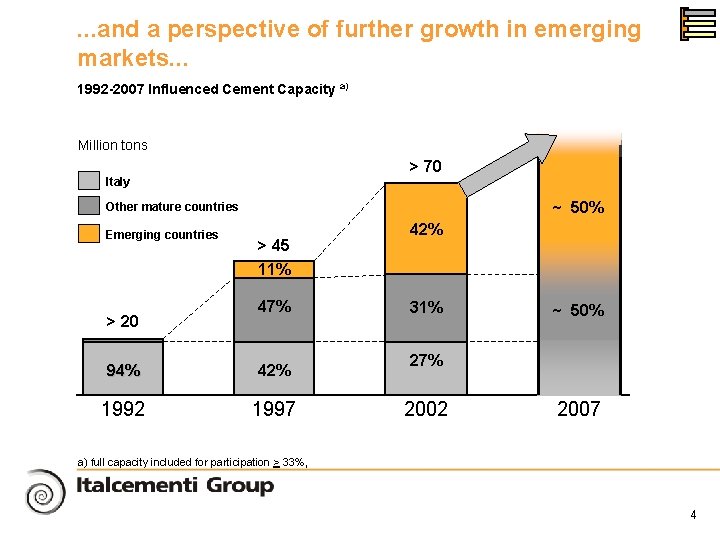
. . . and a perspective of further growth in emerging markets. . . 1992 -2007 Influenced Cement Capacity a) Million tons > 70 Italy ~ 50% Other mature countries Emerging countries > 45 42% 11% > 20 47% 94% 42% 1992 1997 31% ~ 50% 27% 2002 2007 a) full capacity included for participation > 33%, 4
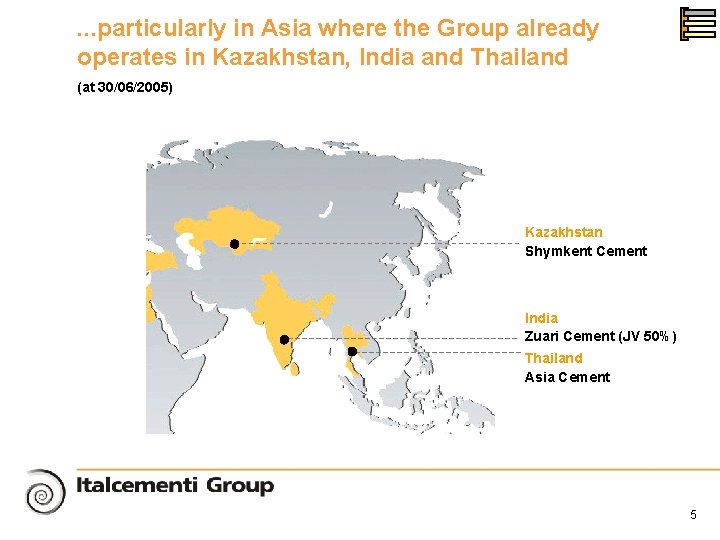
. . . particularly in Asia where the Group already operates in Kazakhstan, India and Thailand (at 30/06/2005) Kazakhstan Shymkent Cement India Zuari Cement (JV 50%) Thailand Asia Cement 5
Index Italcementi Group The Indian Market Indian Presence 6
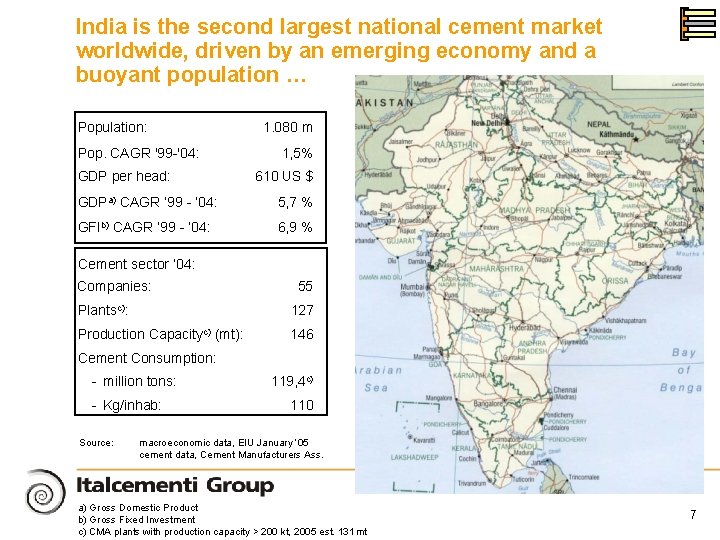
India is the second largest national cement market worldwide, driven by an emerging economy and a buoyant population … Population: Pop. CAGR '99 -'04: GDP per head: 1. 080 m 1, 5% 610 US $ GDPa) CAGR ’ 99 - ’ 04: 5, 7 % GFIb) CAGR ’ 99 - ’ 04: 6, 9 % Cement sector ‘ 04: Companies: 55 Plantsc): 127 Production Capacityc) (mt): 146 Cement Consumption: - million tons: - Kg/inhab: Source: 119, 4 c) 110 macroeconomic data, EIU January ’ 05 cement data, Cement Manufacturers Ass. a) Gross Domestic Product b) Gross Fixed Investment c) CMA plants with production capacity > 200 kt, 2005 est. 131 mt 7
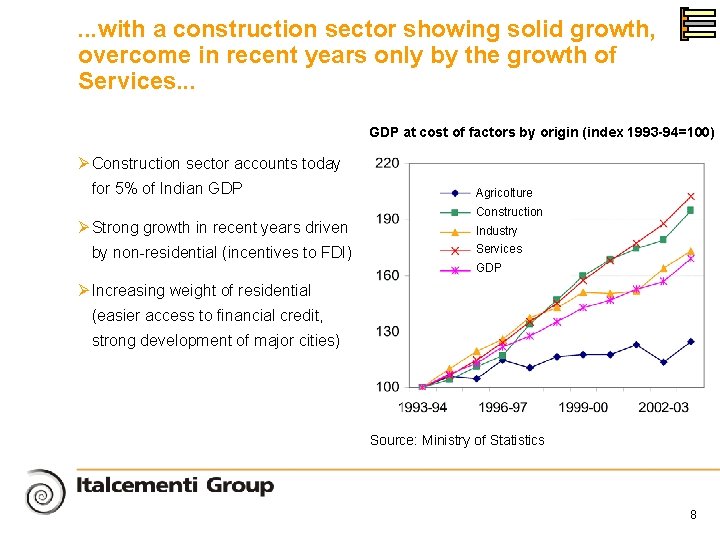
. . . with a construction sector showing solid growth, overcome in recent years only by the growth of Services. . . GDP at cost of factors by origin (index 1993 -94=100) Ø Construction sector accounts today for 5% of Indian GDP Ø Strong growth in recent years driven by non-residential (incentives to FDI) Agricolture Construction Industry Services GDP Ø Increasing weight of residential (easier access to financial credit, strong development of major cities) Source: Ministry of Statistics 8
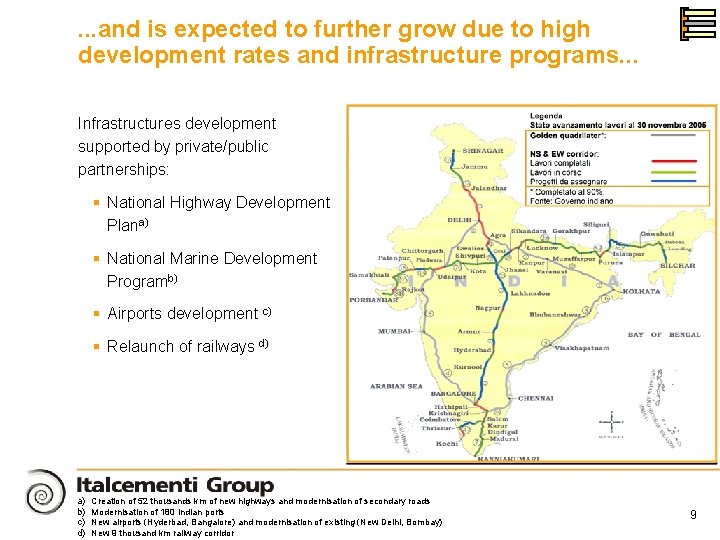
. . . and is expected to further grow due to high development rates and infrastructure programs. . . Infrastructures development supported by private/public partnerships: § National Highway Development Plana) § National Marine Development Programb) § Airports development c) § Relaunch of railways d) a) b) c) d) Creation of 52 thousands km of new highways and modernisation of secondary roads Modernisation of 180 Indian ports New airports (Hyderbad, Bangalore) and modernisation of existing (New Delhi, Bombay) New 9 thousand km railway corridor 9
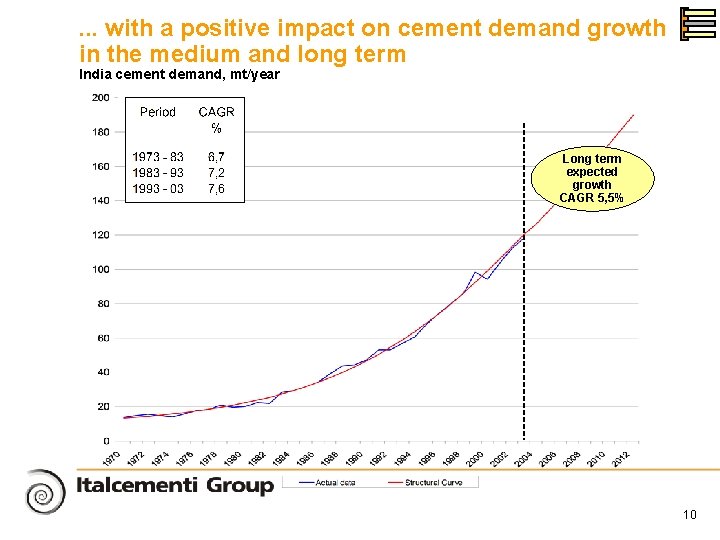
. . . with a positive impact on cement demand growth in the medium and long term India cement demand, mt/year Long term expected growth CAGR 5, 5% 10
Index Italcementi Group The Indian Market Indian Presence 11
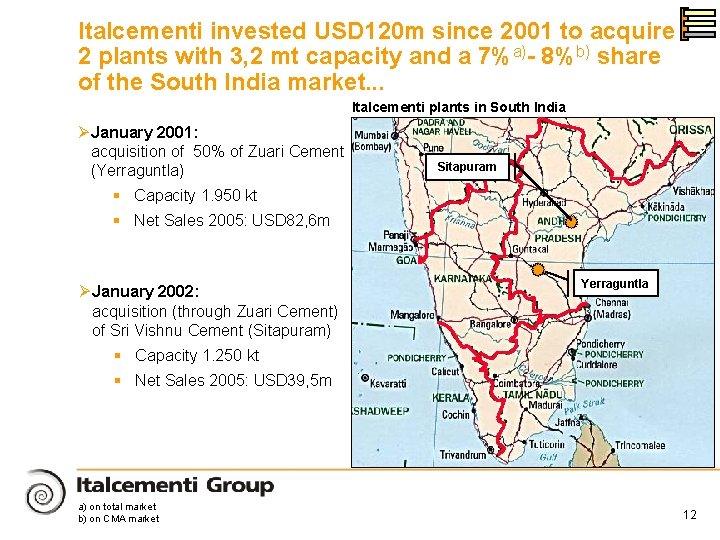
Italcementi invested USD 120 m since 2001 to acquire 2 plants with 3, 2 mt capacity and a 7%a)- 8%b) share of the South India market. . . Italcementi plants in South India Ø January 2001: acquisition of 50% of Zuari Cement (Yerraguntla) Sitapuram § Capacity 1. 950 kt § Net Sales 2005: USD 82, 6 m Ø January 2002: acquisition (through Zuari Cement) of Sri Vishnu Cement (Sitapuram) Yerraguntla § Capacity 1. 250 kt § Net Sales 2005: USD 39, 5 m a) on total market b) on CMA market 12
. . . with the aim to further develop its presence in the country Ø It has taken time to fully assimilate the complexities of operating in the country (challenging cement market, strong price pressure, changing fiscal environment) Ø The high expertise of local human resources allows today to maintain only one expatriate as General Manager in the organisation, and various plans are underway to capitalise Groupwide on Indian resources Ø Several important industrial investments are underway: - 40 MW steam coal power plant - second clinker line in Yerraguntla - grinding centre in Chennai Ø The Group is continuosly seeking opportunities for further growth in the Country through acquisitions 13
India: a successful integration and an increasingly bright future 14