Financial and Managerial Accounting Wild Shaw and Chiappetta

- Slides: 47
Financial and Managerial Accounting Wild, Shaw, and Chiappetta Fourth Edition Mc. Graw-Hill/Irwin Copyright © 2011 by The Mc. Graw-Hill Companies, Inc. All rights reserved.
Chapter 5 Inventories and Cost of Sales
Conceptual Chapter Objectives C 1: Identify the items making up merchandise inventory. C 2: Identify the costs of merchandise inventory. 5 -3
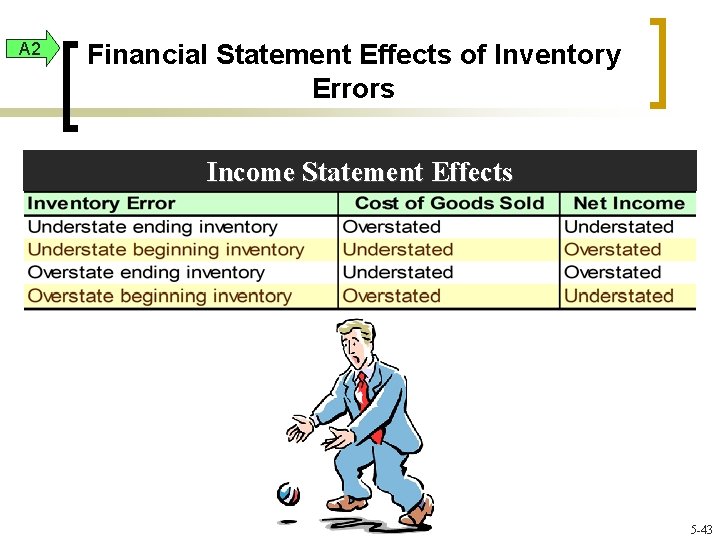
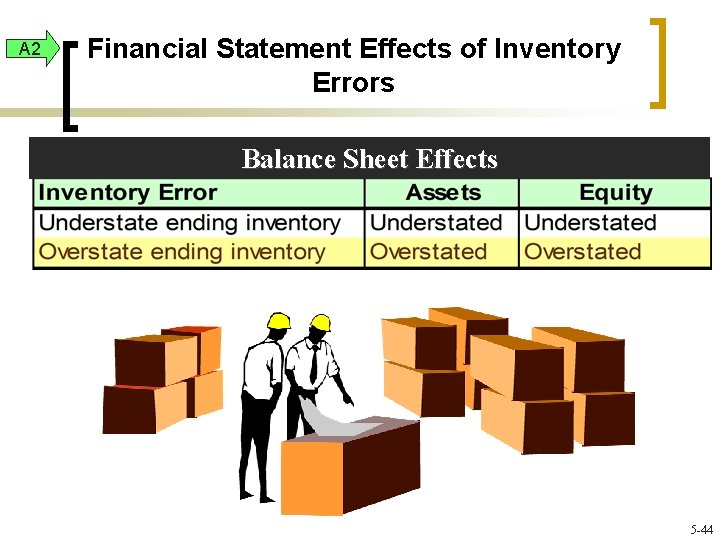
Analytical Chapter Objectives A 1: Analyze the effects of inventory methods for both financial and tax reporting. A 2: Analyze the effects of inventory errors on current and future financial statements. A 3: Assess inventory management using both inventory turnover and days’ sales in inventory. 5 -4
Procedural Chapter Objectives P 1: Compute inventory in a perpetual system using the methods of specific identification, FIFO, LIFO, and weighted average. P 2: Compute the lower of cost or market amount of inventory. P 3: Appendix 5 A – Compute inventory in a periodic system using the methods of specific identification, FIFO, LIFO, and weighted average (see text for details). P 4: Appendix 5 B – Apply both the retail inventory and gross profit methods to estimate inventory (see text for details). 5 -5
C 1 Determining Inventory Items Merchandise inventory includes all goods that a company owns and holds for sale, regardless of where the goods are located when inventory is counted. Items requiring special attention include: Goods in Transit Goods on Consignment Goods Damaged or Obsolete 5 -6
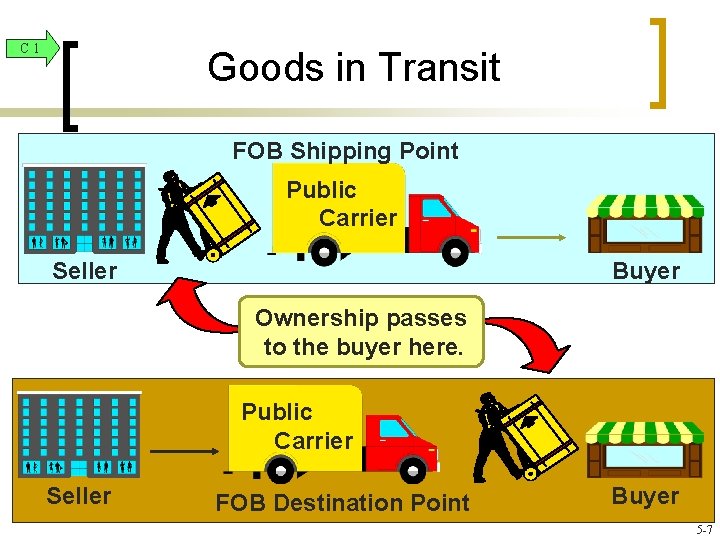
C 1 Goods in Transit FOB Shipping Point Public Carrier Seller Buyer Ownership passes to the buyer here. Public Carrier Seller FOB Destination Point Buyer 5 -7
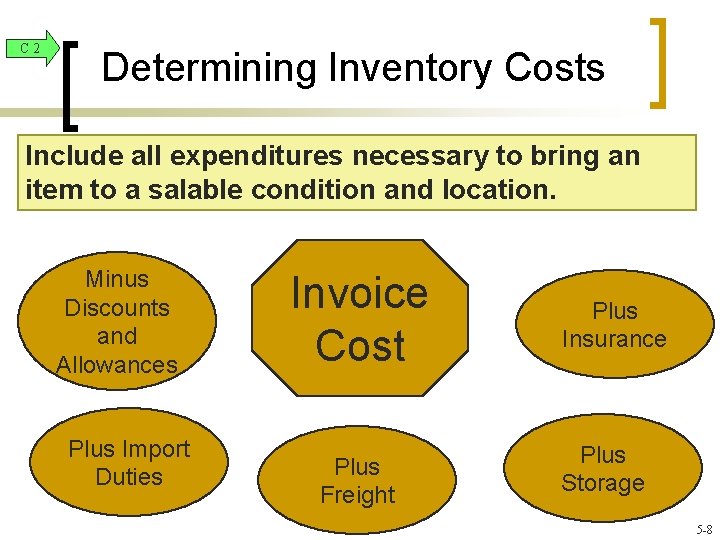
C 2 Determining Inventory Costs Include all expenditures necessary to bring an item to a salable condition and location. Minus Discounts and Allowances Plus Import Duties Invoice Cost Plus Freight Plus Insurance Plus Storage 5 -8
C 2 Internal Controls and Taking a Physical Count Ø Most companies take a physical count of inventory at least once each year. Ø When the physical count does not match the Merchandise Inventory account, an adjustment must be made. Inv e Cou ntory nt Tag Qua n Cou tity nte d_ Cou __ n t e by ___ d ___ _ 5 -9
P 1 Inventory Costing Under a Perpetual System Accounting for inventory requires several decisions. . . Ø Costing Method l Specific Identification, FIFO, LIFO, or Weighted Average Ø Inventory System l Perpetual or Periodic 5 -10
P 1 Frequency in Use of Inventory Methods 5 -11
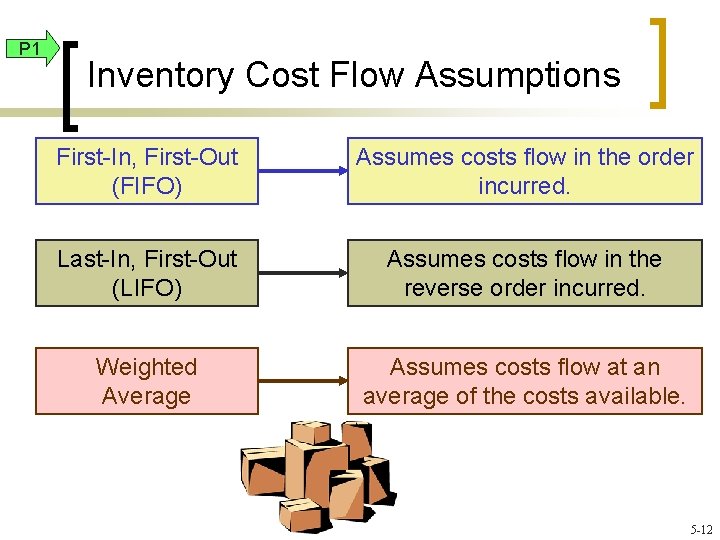
P 1 Inventory Cost Flow Assumptions First-In, First-Out (FIFO) Assumes costs flow in the order incurred. Last-In, First-Out (LIFO) Assumes costs flow in the reverse order incurred. Weighted Average Assumes costs flow at an average of the costs available. 5 -12
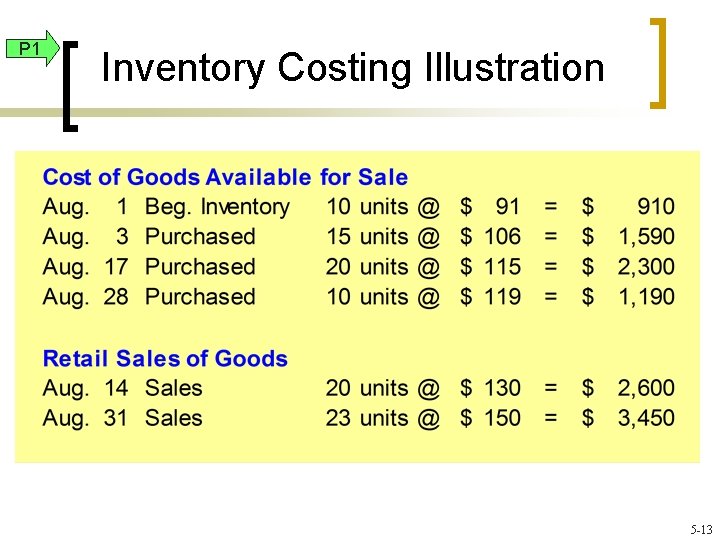
P 1 Inventory Costing Illustration 5 -13
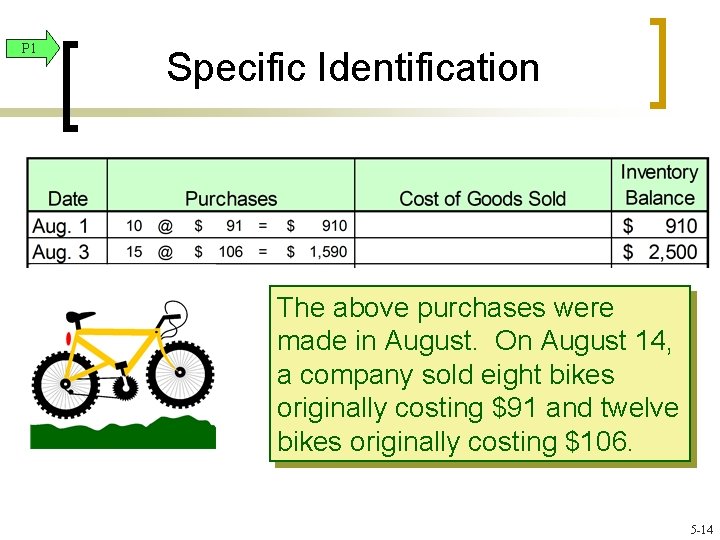
P 1 Specific Identification The above purchases were made in August. On August 14, a company sold eight bikes originally costing $91 and twelve bikes originally costing $106. 5 -14
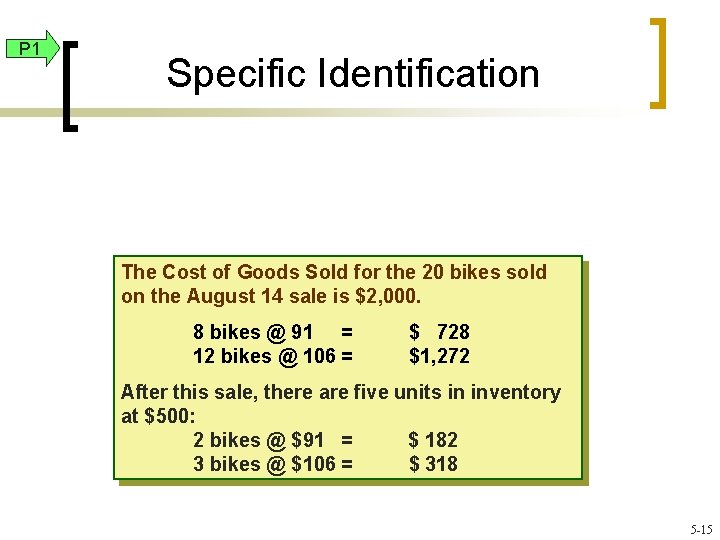
P 1 Specific Identification The Cost of Goods Sold for the 20 bikes sold on the August 14 sale is $2, 000. 8 bikes @ 91 = 12 bikes @ 106 = $ 728 $1, 272 After this sale, there are five units in inventory at $500: 2 bikes @ $91 = $ 182 3 bikes @ $106 = $ 318 5 -15
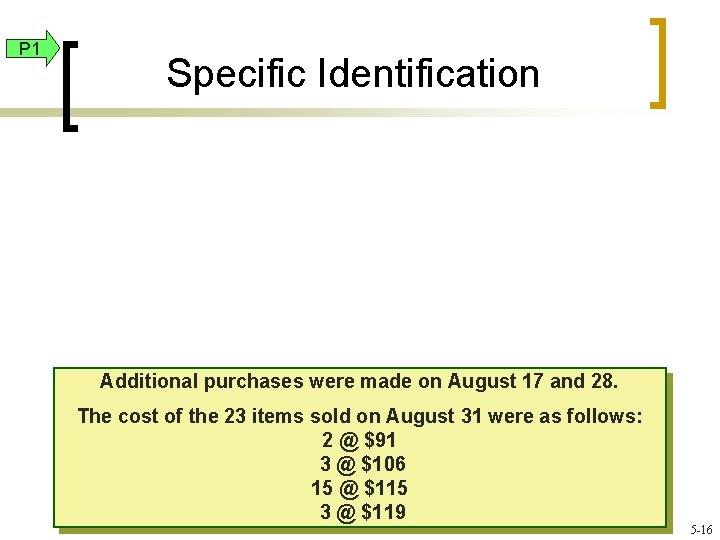
P 1 Specific Identification Additional purchases were made on August 17 and 28. The cost of the 23 items sold on August 31 were as follows: 2 @ $91 3 @ $106 15 @ $115 3 @ $119 5 -16
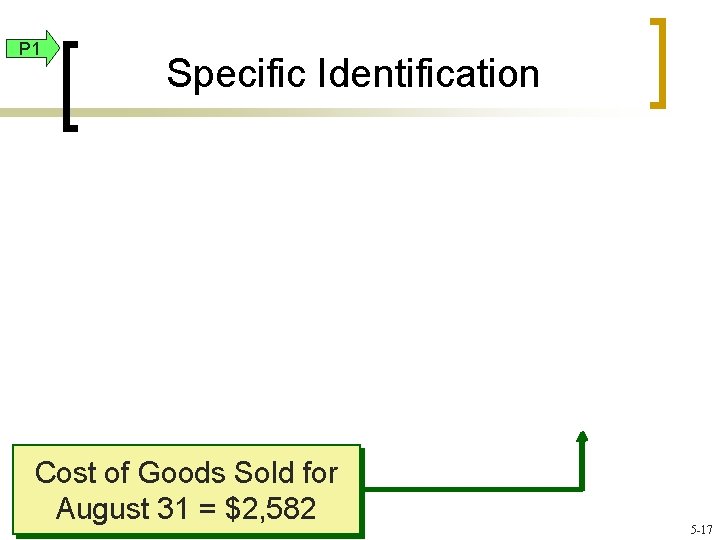
P 1 Specific Identification Cost of Goods Sold for August 31 = $2, 582 5 -17
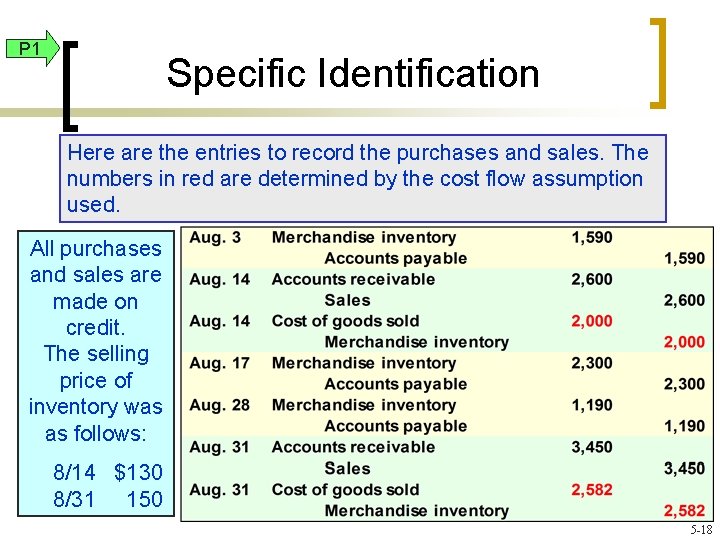
P 1 Specific Identification Here are the entries to record the purchases and sales. The numbers in red are determined by the cost flow assumption used. All purchases and sales are made on credit. The selling price of inventory was as follows: 8/14 $130 8/31 150 5 -18
P 1 First-In, First-Out (FIFO) The above purchases were made in August. On August 14, the company sold 20 bikes. 5 -19
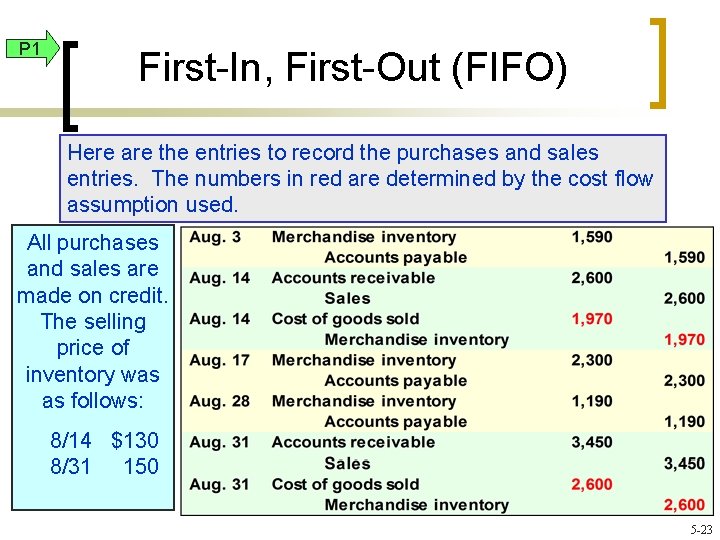
P 1 First-In, First-Out (FIFO) The Cost of Goods Sold for the August 14 sale is $1, 970. After this sale, there are five units in inventory at $530: 5 @ $106 5 -20
P 1 First-In, First-Out (FIFO) Cost of Goods Sold for August 31 = $2, 600 5 -21
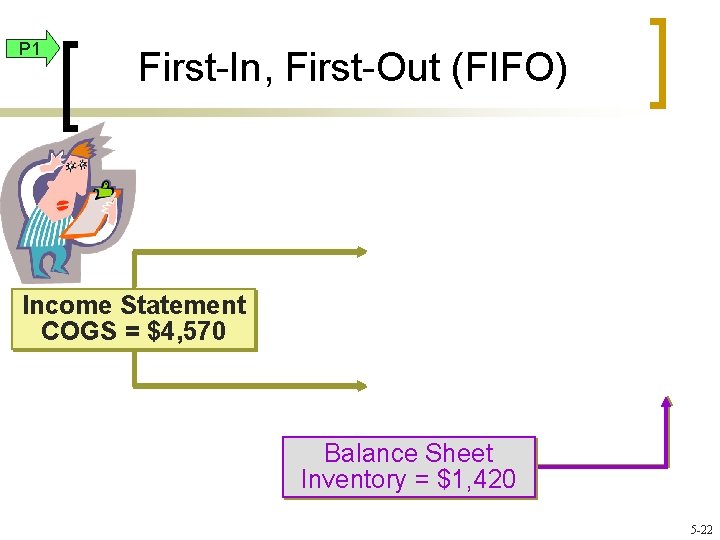
P 1 First-In, First-Out (FIFO) Income Statement COGS = $4, 570 Balance Sheet Inventory = $1, 420 5 -22
P 1 First-In, First-Out (FIFO) Here are the entries to record the purchases and sales entries. The numbers in red are determined by the cost flow assumption used. All purchases and sales are made on credit. The selling price of inventory was as follows: 8/14 $130 8/31 150 5 -23
P 1 Last-In, First-Out (LIFO) The above purchases were made in August. On August 14, the company sold 20 bikes. 5 -24
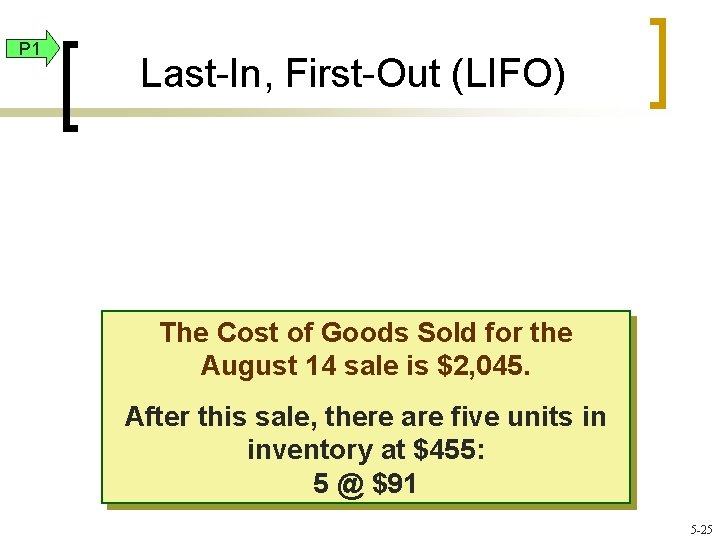
P 1 Last-In, First-Out (LIFO) The Cost of Goods Sold for the August 14 sale is $2, 045. After this sale, there are five units in inventory at $455: 5 @ $91 5 -25
P 1 Last-In, First-Out (LIFO) Cost of Goods Sold for August 31 = $2, 685 5 -26
P 1 Last-In, First-Out (LIFO) Income Statement COGS = $4, 730 Balance Sheet Inventory = $1, 260 5 -27
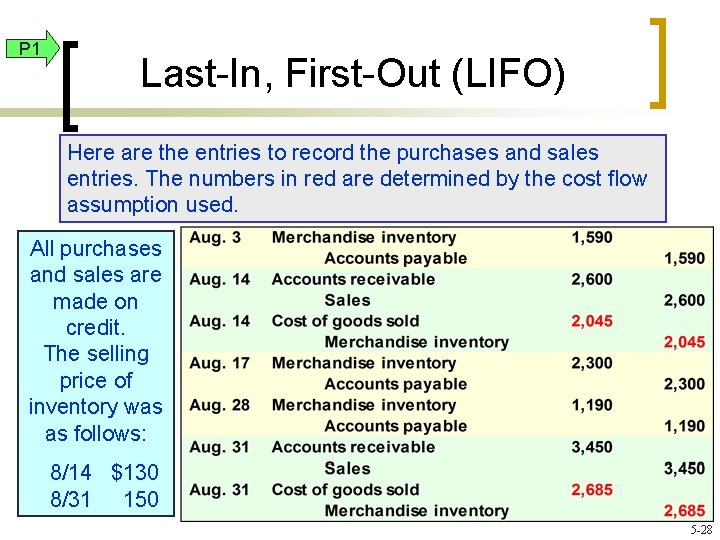
P 1 Last-In, First-Out (LIFO) Here are the entries to record the purchases and sales entries. The numbers in red are determined by the cost flow assumption used. All purchases and sales are made on credit. The selling price of inventory was as follows: 8/14 $130 8/31 150 5 -28
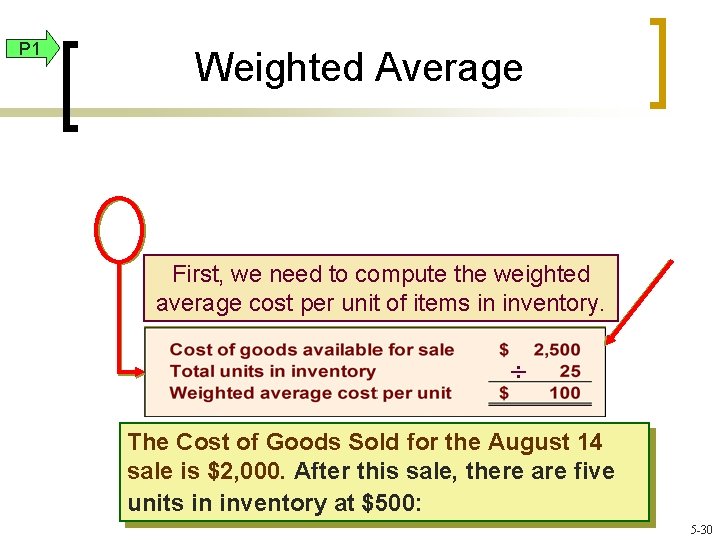
P 1 Weighted Average When a unit is sold, the average cost of each unit in inventory is assigned to cost of goods sold. Cost of Goods Units on hand Available for ÷ on the date of Sale sale 5 -29
P 1 Weighted Average First, we need to compute the weighted average cost per unit of items in inventory. ÷ The Cost of Goods Sold for the August 14 sale is $2, 000. After this sale, there are five units in inventory at $500: 5 -30
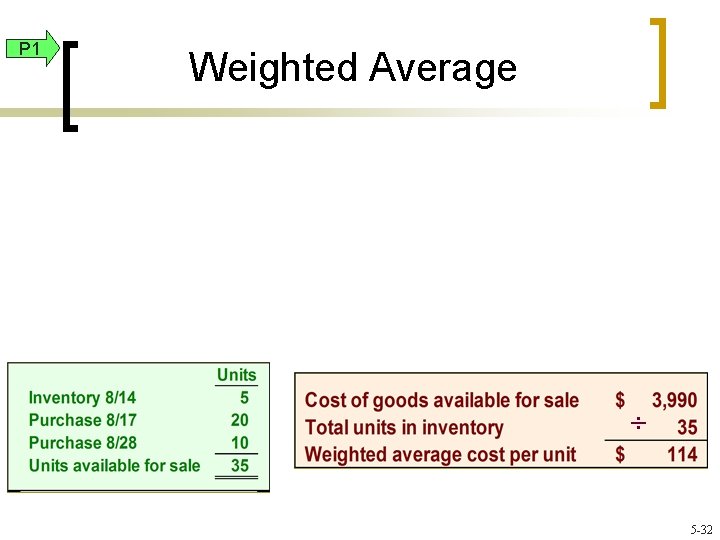
P 1 Weighted Average Additional purchases were made on August 17 and 28. Twenty-three bikes were sold on August 31. What is the weighted average cost per unit of items in inventory? 5 -31
P 1 Weighted Average ÷ 5 -32
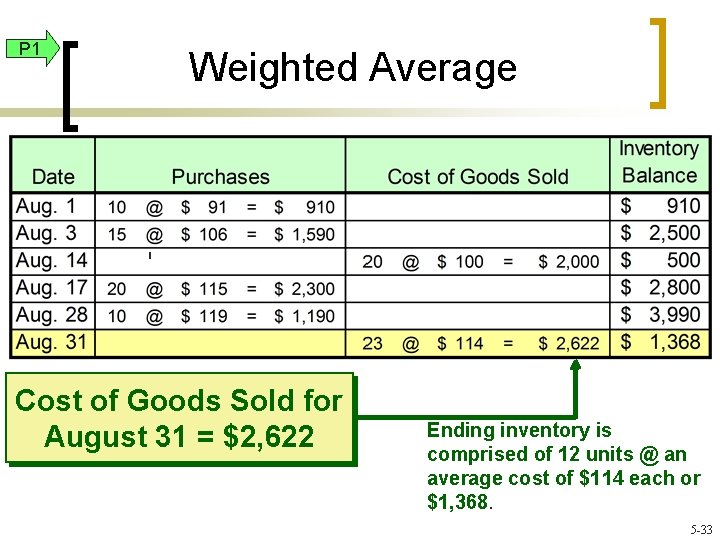
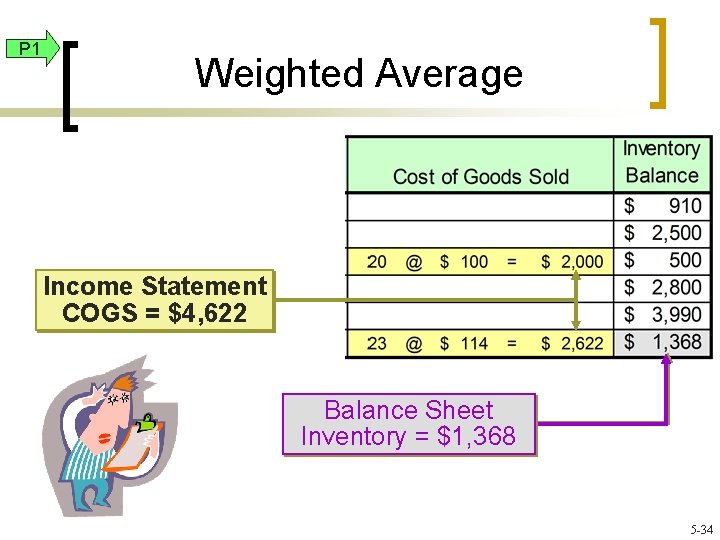
P 1 Weighted Average Cost of Goods Sold for August 31 = $2, 622 Ending inventory is comprised of 12 units @ an average cost of $114 each or $1, 368. 5 -33
P 1 Weighted Average Income Statement COGS = $4, 622 Balance Sheet Inventory = $1, 368 5 -34
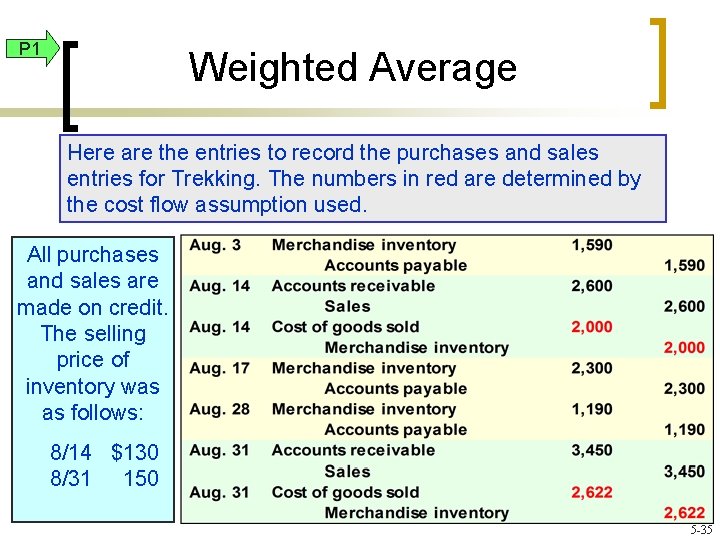
P 1 Weighted Average Here are the entries to record the purchases and sales entries for Trekking. The numbers in red are determined by the cost flow assumption used. All purchases and sales are made on credit. The selling price of inventory was as follows: 8/14 $130 8/31 150 5 -35
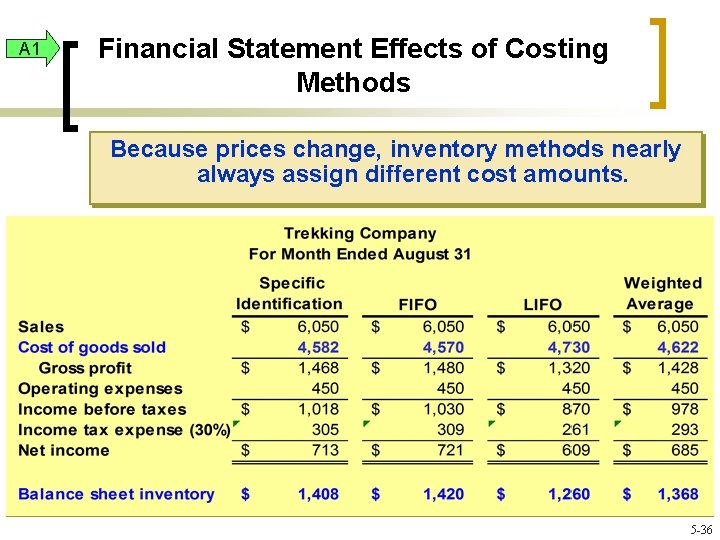
A 1 Financial Statement Effects of Costing Methods Because prices change, inventory methods nearly always assign different cost amounts. 5 -36
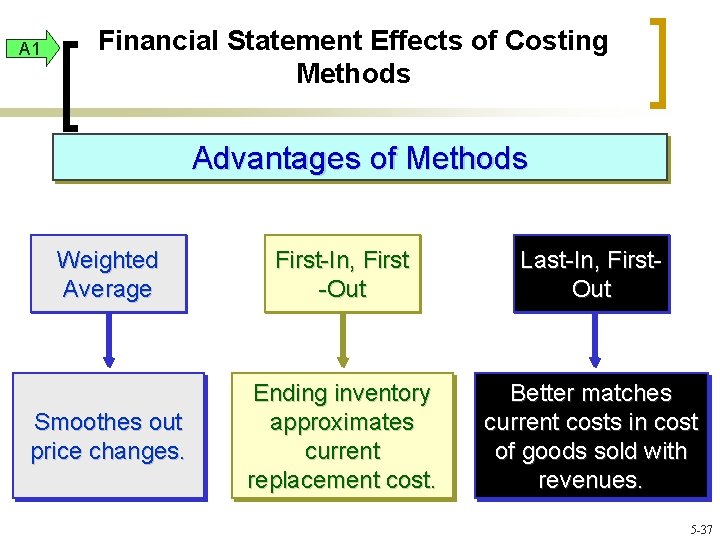
A 1 Financial Statement Effects of Costing Methods Advantages of Methods Weighted Average First-In, First -Out Last-In, First. Out Smoothes out price changes. Ending inventory approximates current replacement cost. Better matches current costs in cost of goods sold with revenues. 5 -37
A 1 Tax Effects of Costing Methods The Internal Revenue Service (IRS) identifies several acceptable methods for inventory costing for reporting taxable income. If LIFO is used for tax purposes, the IRS requires it be used in financial statements. 5 -38
A 1 Consistency in Using Costing Methods The consistency concept requires a company to use the same accounting methods period after period so that financial statements are comparable across periods. 5 -39
P 2 Lower of Cost or Market Inventory must be reported at market value when market is lower than cost. Defined as current replacement cost (not sales price). Consistent with the conservatism principle. Can be applied three ways: (1) (2) (3) separately to each individual item. to major categories of assets. to the whole inventory. 5 -40
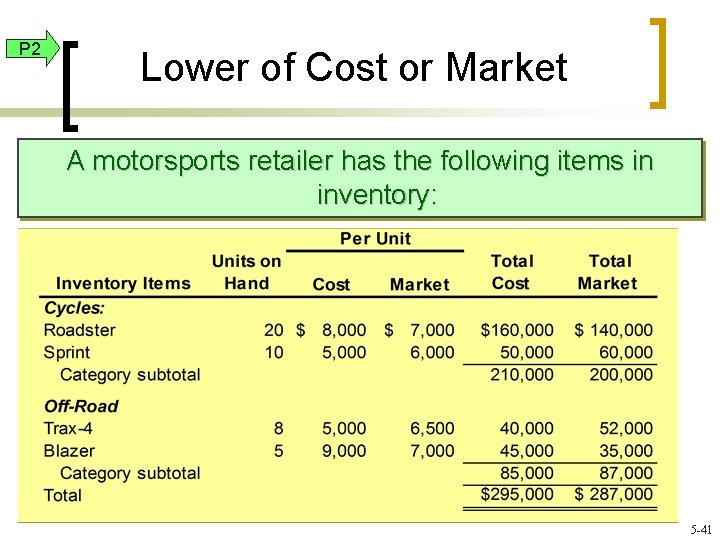
P 2 Lower of Cost or Market A motorsports retailer has the following items in inventory: 5 -41
P 2 Lower of Cost or Market Here is how to compute lower of cost or market for individual inventory items. 5 -42
A 2 Financial Statement Effects of Inventory Errors Income Statement Effects 5 -43
A 2 Financial Statement Effects of Inventory Errors Balance Sheet Effects 5 -44
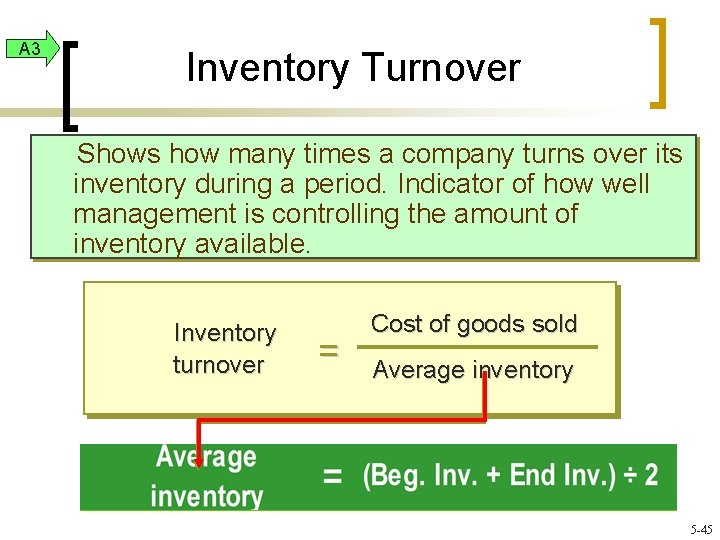
A 3 Inventory Turnover Shows how many times a company turns over its inventory during a period. Indicator of how well management is controlling the amount of inventory available. Inventory turnover = Cost of goods sold Average inventory 5 -45
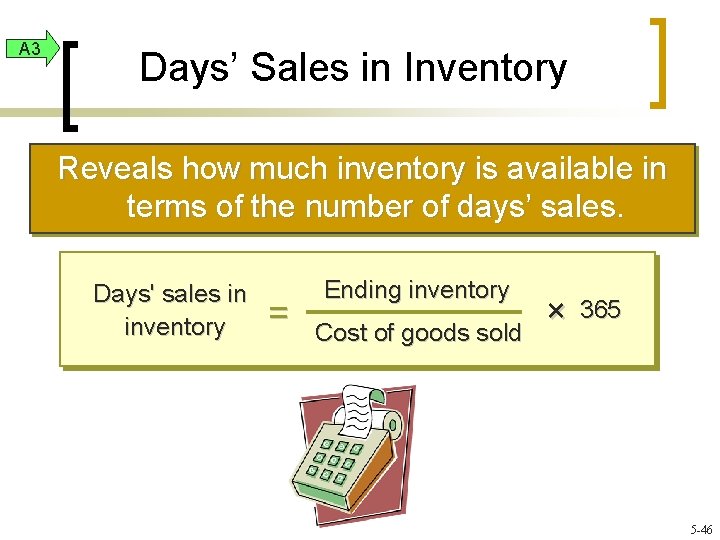
A 3 Days’ Sales in Inventory Reveals how much inventory is available in terms of the number of days’ sales. Days' sales in inventory = Ending inventory Cost of goods sold × 365 5 -46
End of Chapter 5 5 -47