CHARITIES RECENT DEVELOPMENTS UNDER I T ACT 1961
- Slides: 26
CHARITIES – RECENT DEVELOPMENTS UNDER I T ACT, 1961 CA V RAMNATH, B COM, FCA COIMBATORE ramnath@ksp. co. in
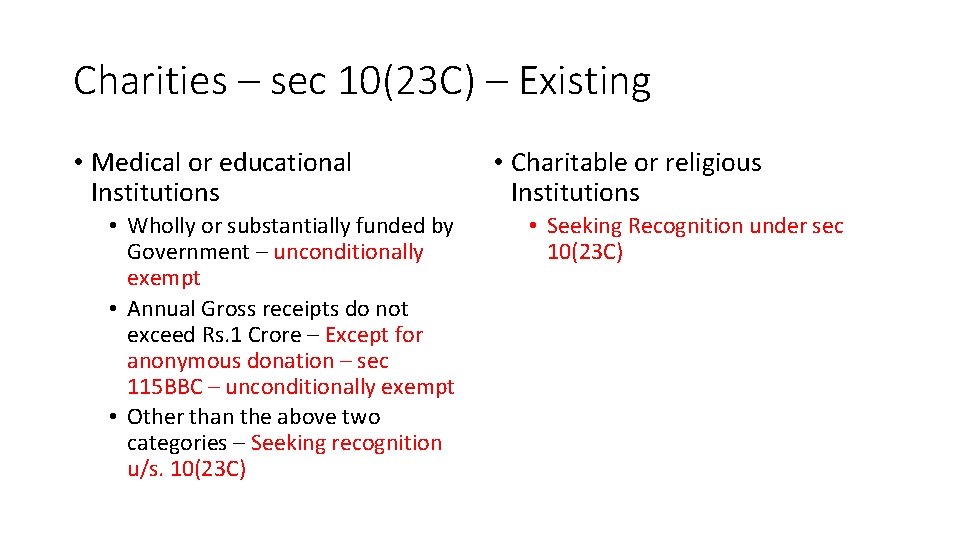
Charities – sec 10(23 C) – Existing • Medical or educational Institutions • Wholly or substantially funded by Government – unconditionally exempt • Annual Gross receipts do not exceed Rs. 1 Crore – Except for anonymous donation – sec 115 BBC – unconditionally exempt • Other than the above two categories – Seeking recognition u/s. 10(23 C) • Charitable or religious Institutions • Seeking Recognition under sec 10(23 C)
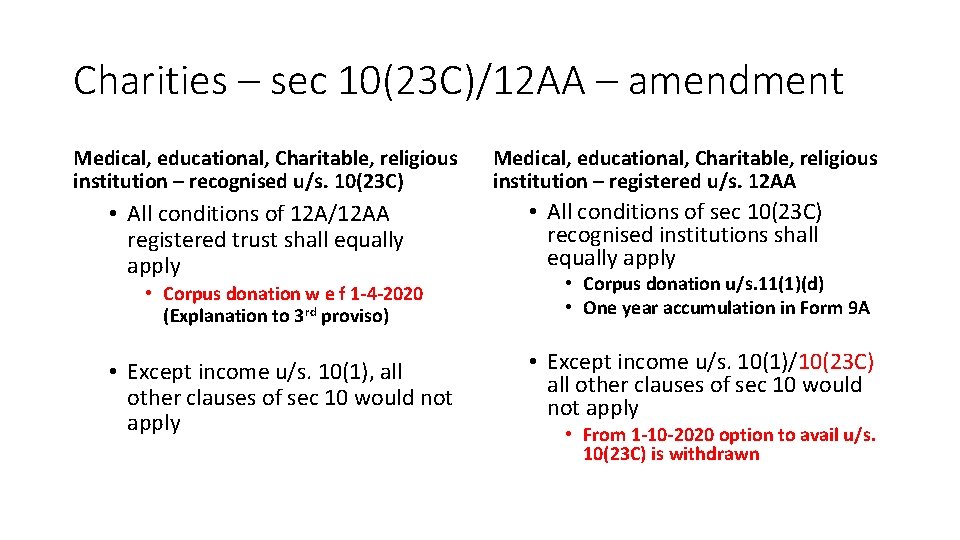
Charities – sec 10(23 C)/12 AA – amendment Medical, educational, Charitable, religious institution – recognised u/s. 10(23 C) • All conditions of 12 A/12 AA registered trust shall equally apply • Corpus donation w e f 1 -4 -2020 (Explanation to 3 rd proviso) • Except income u/s. 10(1), all other clauses of sec 10 would not apply Medical, educational, Charitable, religious institution – registered u/s. 12 AA • All conditions of sec 10(23 C) recognised institutions shall equally apply • Corpus donation u/s. 11(1)(d) • One year accumulation in Form 9 A • Except income u/s. 10(1)/10(23 C) all other clauses of sec 10 would not apply • From 1 -10 -2020 option to avail u/s. 10(23 C) is withdrawn
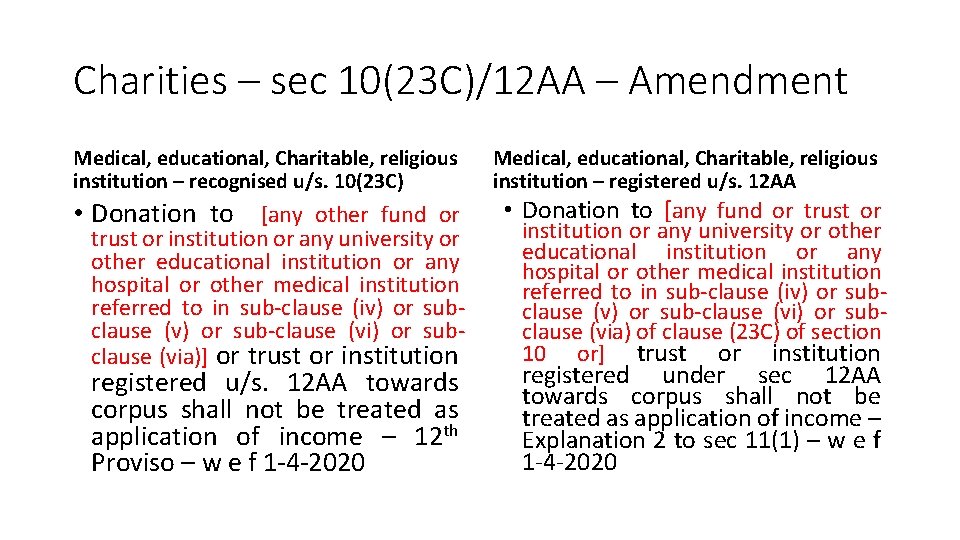
Charities – sec 10(23 C)/12 AA – Amendment Medical, educational, Charitable, religious institution – recognised u/s. 10(23 C) Medical, educational, Charitable, religious institution – registered u/s. 12 AA • Donation to [any other fund or • Donation to [any fund or trust or registered u/s. 12 AA towards corpus shall not be treated as application of income – 12 th Proviso – w e f 1 -4 -2020 registered under sec 12 AA towards corpus shall not be treated as application of income – Explanation 2 to sec 11(1) – w e f 1 -4 -2020 trust or institution or any university or other educational institution or any hospital or other medical institution referred to in sub-clause (iv) or subclause (v) or sub-clause (vi) or subclause (via)] or trust or institution or any university or other educational institution or any hospital or other medical institution referred to in sub-clause (iv) or subclause (v) or sub-clause (vi) or subclause (via) of clause (23 C) of section 10 or] trust or institution
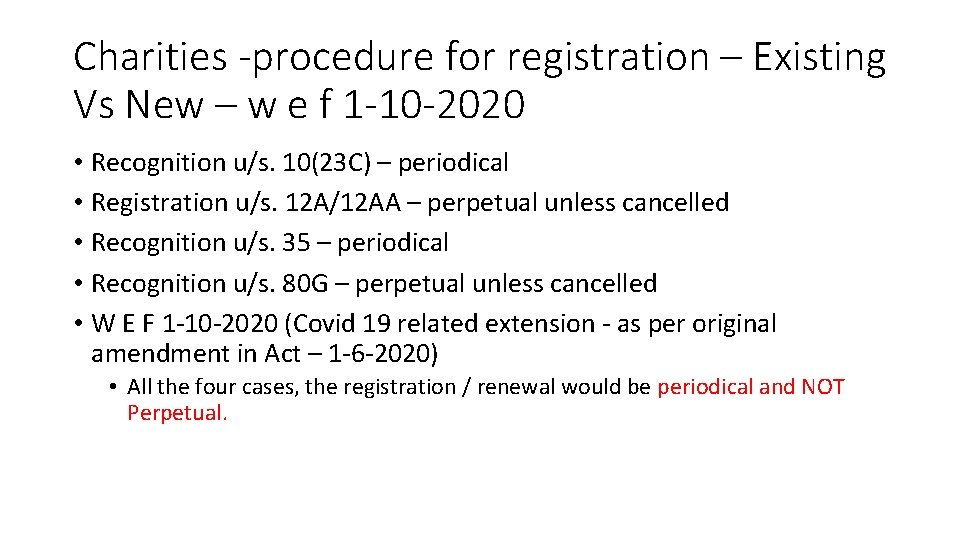
Charities -procedure for registration – Existing Vs New – w e f 1 -10 -2020 • Recognition u/s. 10(23 C) – periodical • Registration u/s. 12 A/12 AA – perpetual unless cancelled • Recognition u/s. 35 – periodical • Recognition u/s. 80 G – perpetual unless cancelled • W E F 1 -10 -2020 (Covid 19 related extension - as per original amendment in Act – 1 -6 -2020) • All the four cases, the registration / renewal would be periodical and NOT Perpetual.
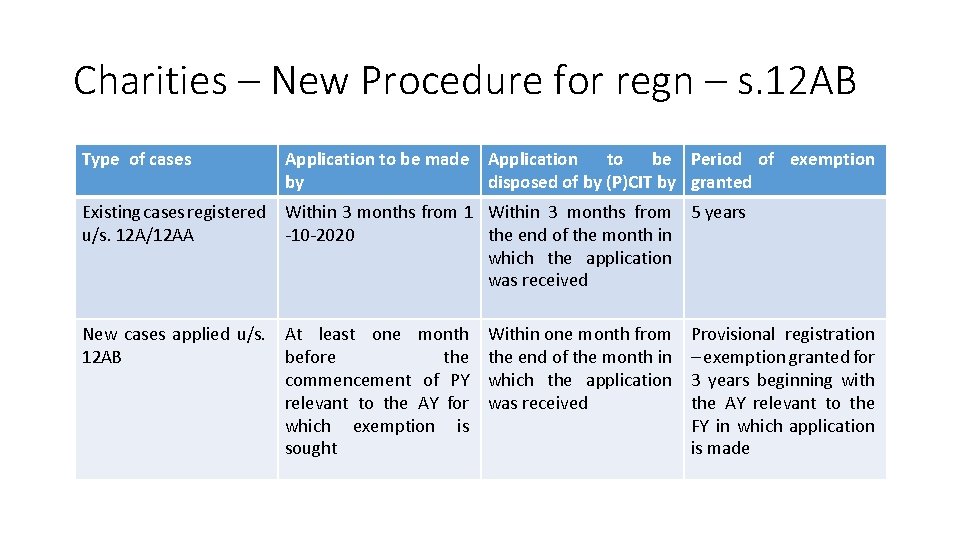
Charities – New Procedure for regn – s. 12 AB Type of cases Application to be made Application to be Period of exemption by disposed of by (P)CIT by granted Existing cases registered Within 3 months from 1 Within 3 months from 5 years u/s. 12 A/12 AA -10 -2020 the end of the month in which the application was received New cases applied u/s. At least one month 12 AB before the commencement of PY relevant to the AY for which exemption is sought Within one month from the end of the month in which the application was received Provisional registration – exemption granted for 3 years beginning with the AY relevant to the FY in which application is made
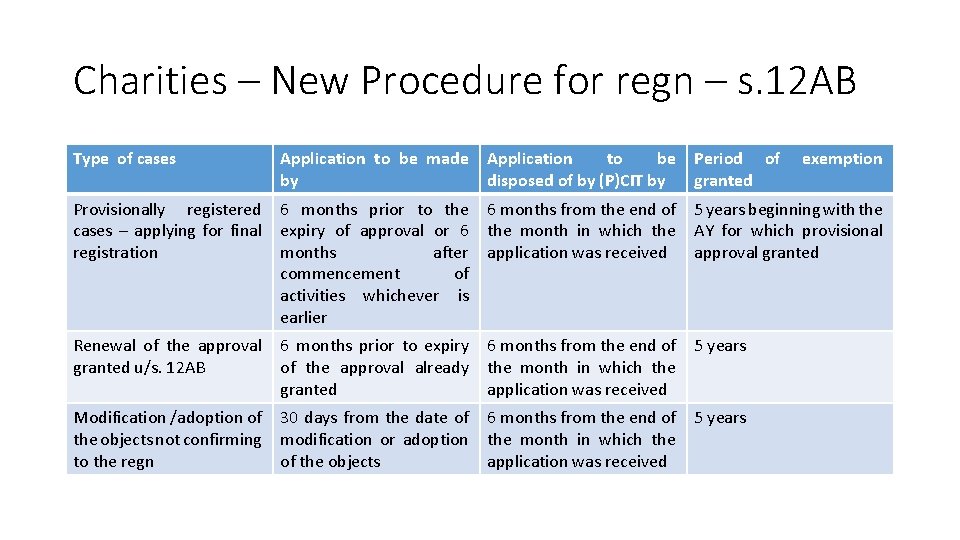
Charities – New Procedure for regn – s. 12 AB Type of cases Application to be made by Application to be disposed of by (P)CIT by Period of granted exemption Provisionally registered 6 months prior to the 6 months from the end of 5 years beginning with the cases – applying for final expiry of approval or 6 the month in which the AY for which provisional registration months after application was received approval granted commencement of activities whichever is earlier Renewal of the approval 6 months prior to expiry 6 months from the end of 5 years granted u/s. 12 AB of the approval already the month in which the granted application was received Modification /adoption of 30 days from the date of 6 months from the end of 5 years the objects not confirming modification or adoption the month in which the to the regn of the objects application was received
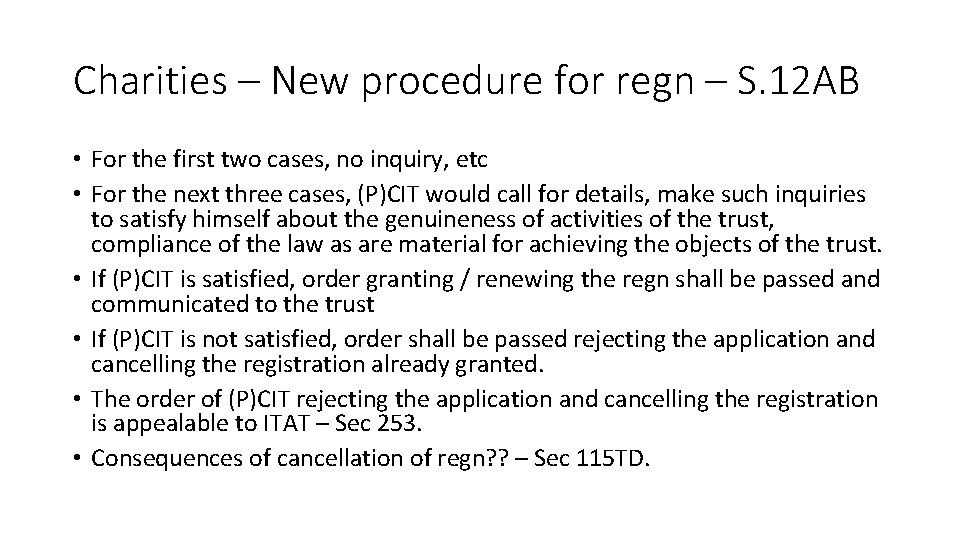
Charities – New procedure for regn – S. 12 AB • For the first two cases, no inquiry, etc • For the next three cases, (P)CIT would call for details, make such inquiries to satisfy himself about the genuineness of activities of the trust, compliance of the law as are material for achieving the objects of the trust. • If (P)CIT is satisfied, order granting / renewing the regn shall be passed and communicated to the trust • If (P)CIT is not satisfied, order shall be passed rejecting the application and cancelling the registration already granted. • The order of (P)CIT rejecting the application and cancelling the registration is appealable to ITAT – Sec 253. • Consequences of cancellation of regn? ? – Sec 115 TD.
Charities – sec 10(23 C), 35, 80 G • The procedure mentioned for trust covered u/s. 12 A/12 AB would equally apply for the institutions seeking recognition u/s. 10(23 C), 35, 80 G. • Institutions recognised u/s. 35/ 80 G/80 GGA shall • furnish the statement in the prescribed form periodically giving the details of donation received • Issue certificate to the donors within the time prescribed • Failure to file the statement, issue certificate would invite • Fees payable u/s. 234 G @ Rs. 200 per day of default (max – donation received) • Penalty u/s. 271 K – Rs. 10000 to Rs. 1 lakhs • Donor would get deduction based on the statement filed by the donee - 80 G/80 GGA • Cash donation u/s. 80 GGA reduced to 2 K from 10 K
Tax on accredited Income – sec 115 TD • Sec 115 TD would apply, if the trust • Converts into another form not eligible for registration u/s. 12 AA/12 AB • Merges into another trust which does not have • similar objects and • registration u/s. 12 AA/12 AB • Upon dissolution, fails to transfer all its assets, within twelve months from the end of the month of dissolution, to another trust having registration u/s. 12 AA/12 AB or recognition u/s. 10(23 C) • Consequences – tax on accredited income @ MMR (42. 74%)
Tax on Accredited Income – sec 115 TD • Meaning of conversion into • Instances leading to cancellation another form not eligible for of registration u/s. 12 AA/12 AB • Activities are not genuine • Registration u/s. 12 AA/12 AB cancelled • Adopted / undertaken modification of objects which do not confirm to the conditions of registration and • Not applied for fresh registration in the previous year of change OR • Fresh application is rejected • Activities are not carried out in accordance with the objects • Activities are carried out so as to invite operation of sec 13(1) • Activities are carried out not complying with any other law which is material for achieving the object of the trust
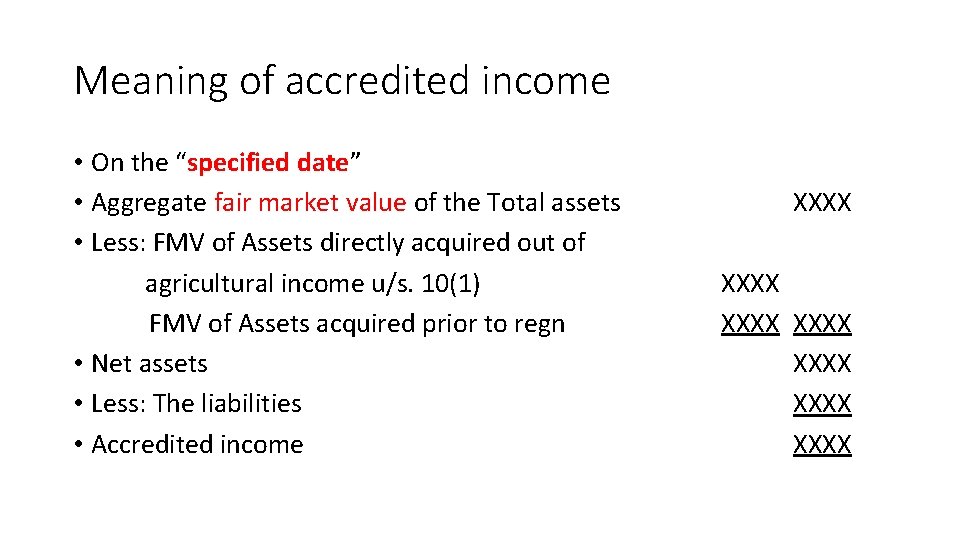
Meaning of accredited income • On the “specified date” • Aggregate fair market value of the Total assets • Less: FMV of Assets directly acquired out of agricultural income u/s. 10(1) FMV of Assets acquired prior to regn • Net assets • Less: The liabilities • Accredited income XXXX XXXX
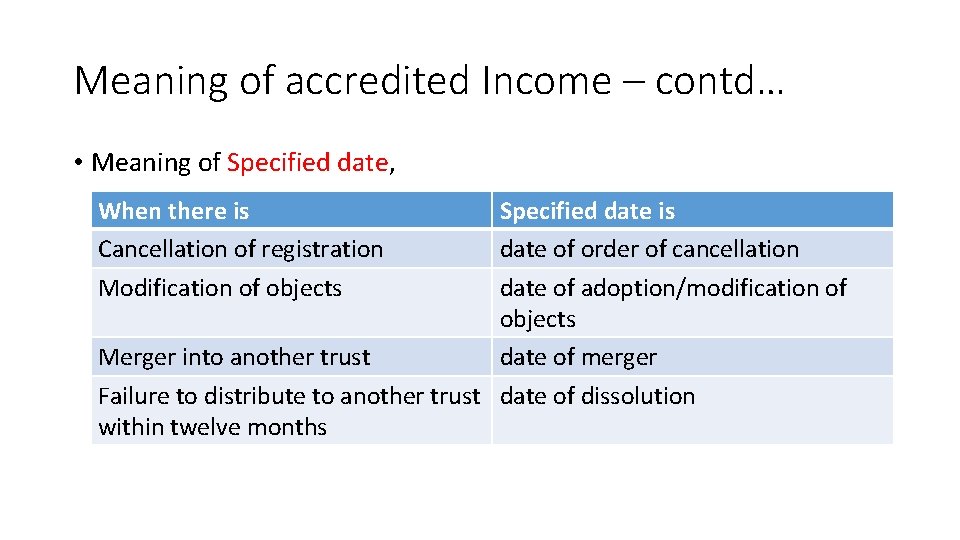
Meaning of accredited Income – contd… • Meaning of Specified date, When there is Cancellation of registration Modification of objects Specified date is date of order of cancellation date of adoption/modification of objects Merger into another trust date of merger Failure to distribute to another trust date of dissolution within twelve months
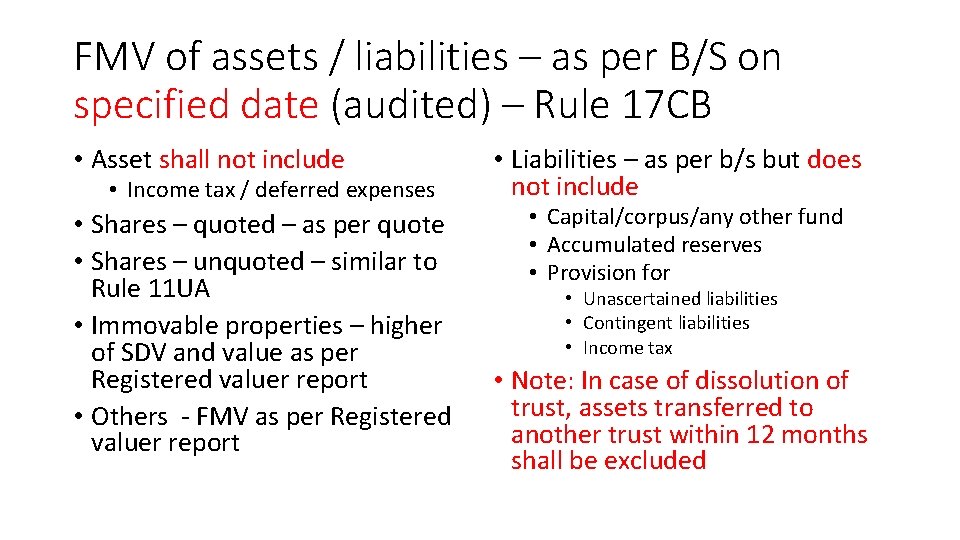
FMV of assets / liabilities – as per B/S on specified date (audited) – Rule 17 CB • Asset shall not include • Income tax / deferred expenses • Shares – quoted – as per quote • Shares – unquoted – similar to Rule 11 UA • Immovable properties – higher of SDV and value as per Registered valuer report • Others - FMV as per Registered valuer report • Liabilities – as per b/s but does not include • Capital/corpus/any other fund • Accumulated reserves • Provision for • Unascertained liabilities • Contingent liabilities • Income tax • Note: In case of dissolution of trust, assets transferred to another trust within 12 months shall be excluded
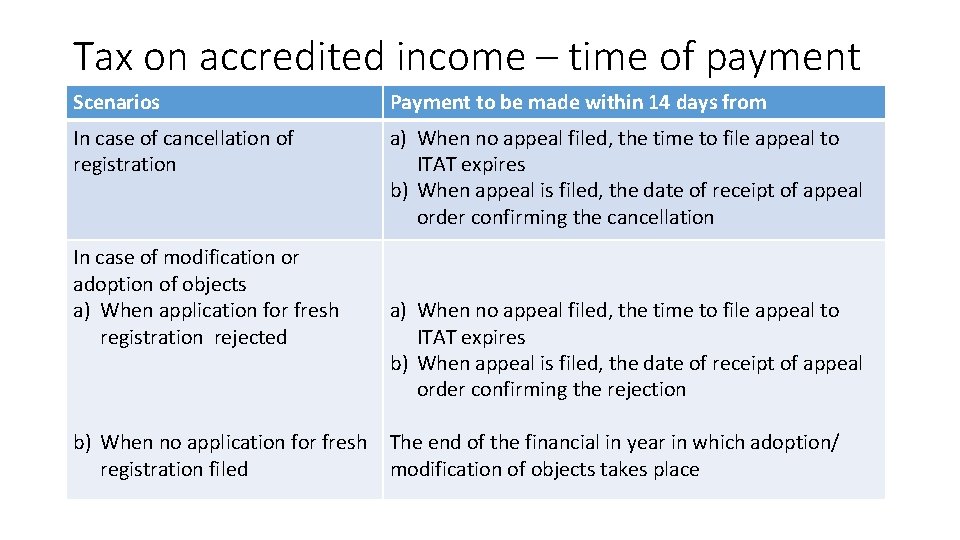
Tax on accredited income – time of payment Scenarios Payment to be made within 14 days from In case of cancellation of registration a) When no appeal filed, the time to file appeal to ITAT expires b) When appeal is filed, the date of receipt of appeal order confirming the cancellation In case of modification or adoption of objects a) When application for fresh registration rejected a) When no appeal filed, the time to file appeal to ITAT expires b) When appeal is filed, the date of receipt of appeal order confirming the rejection b) When no application for fresh The end of the financial in year in which adoption/ registration filed modification of objects takes place
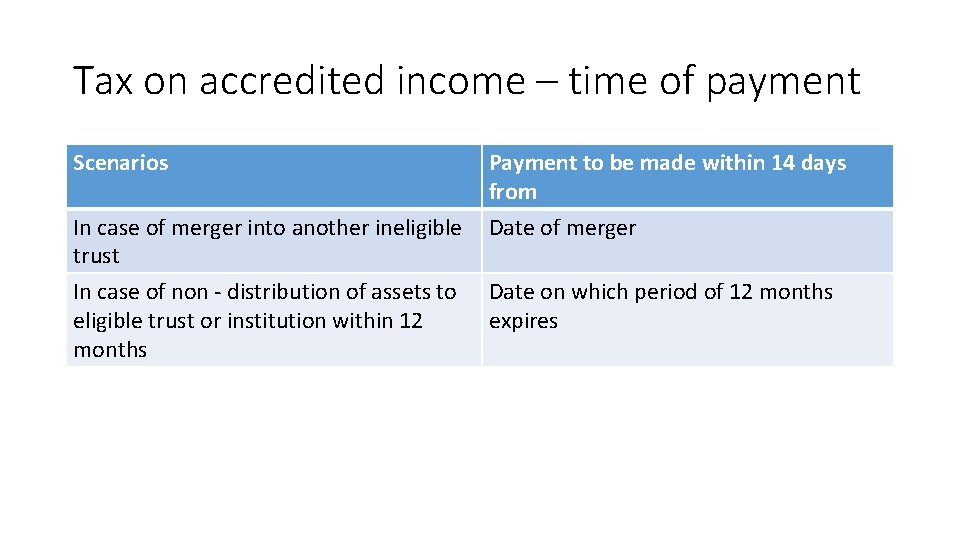
Tax on accredited income – time of payment Scenarios Payment to be made within 14 days from In case of merger into another ineligible Date of merger trust In case of non - distribution of assets to Date on which period of 12 months eligible trust or institution within 12 expires months
Tax on accredited income – Other points • Notwithstanding that no income tax payable by trust, tax on Accredited Income is payable • Tax on Accredited Income is final payment and credit shall not be given for such tax payment to the trust or any other person • No deduction shall be allowed under any other provisions of the Act to the trust or any other person • In respect of income computed (AI) OR • Tax thereon • Delayed payment of tax invites interest @ 1% pm or part thereof – sec 115 TE • Non payment – Principal officer – AID – Asset transferred – Recipient trust is AID to the extent of asset received – Sec 115 TF
New requirements in ROI – Trust – AY 20 -21 • Details about fresh application for renewal to be provided • Whether Application for registration is made as per New Provisions • Section under which registration is applied • Date on which the application for registration/approval as per New provisions is made • Section of Exemption opted for under the New provisions • Corpus donation to another trust shall not be application of income • Tax and interest u/s. 115 TD/115 TE to be specified
Modification/ change in objects • Sec 92 of Civil procedure code 1908 • Ss(3) - Alteration of original purposes in specified circumstances • No power to delete – Sakthi Charities – Mad HC • Sec 26 of the Specific Relief Act 1963 • Rectification of the mistake in the instrument – when the real intention is not expressed – when settlors alive • Sec 7 of Charitable and Religious trust Act 1920 • Trustee may apply seeking opinion/advise/direction of the court, relating to administration of the trust property or management (when no petition u/s. 92 of CPC 1908 pending)
Charitable/religious trust – certain decisions • CIT (E ) cannot insist for activities to be carried out, to satisfy about is genuineness, when the trust is in its initial stages • M/S. Ananda Social And Educational Trust – 2020 (2) TMI 1293 (SC) • Sanjhi Sikhiya Foundation – 2020 (4) TMI 683 (Amrsr ITAT) • CIT (E ) can inquire into the genuineness of the activities before granting registration • Markandashwar Shivji Education Trust – 2020 (6) TMI 131 ITAT Chandigarh • Benefit of registration – eligible for the earlier years – the year for which appeal pending on the date of registration also would qualify • Institute Management Committee (IMC) – 2020 (6) TMI 506 ITAT Bang
Charitable/religious trust – certain decisions • Application for registration filed - no order is passed within 6 months – registration is deemed to be granted • from the date of expiry of 6 months from date of application • Society For Promn. Of Edn. , Allahabad 2016 (2) TMI (SC) • ST. ANN’S Education Society – 2020 (6) TMI 199 Kar HC • Cancellation of registration u/s. 12 AA cannot be retrospective • Auro Lab 411 ITR 308 (Mad) (HC) • In the absence of registration u/s. 12 AA, only net income is taxable • Shree Jyoti Education & Management Trust – 2020 (6) TMI 296 ITAT CUTTACK
Charitable/religious trust – certain decisions • Virtual class rooms imparting education is also charitable u/s. 2(15) • NIIT Foundation – 2020 (5) TMI 628 ITAT Del • Catering service/hostel run by school is also part of imparting education – income from such activities exempt • Wood stock school – 175 ITD 722 (DEL) • Shree Deshi Lohana - 2020 (7) TMI 42 ITAT AMHD • Harish Chand Ram Kali Charitable Trust – 2020 (5) TMI 555 ITAT Del • Pharmacy store run by hospital is also part of medical service – income is exempt • National Health & Education Society – 2020 (3) TMI 505 (Bom HC)
Charitable/religious trust – certain decisions • Executing the job of cleaning the railway coaches by employing poor persons – not a charity • Mahatma Gandhi Charitable Society. 415 ITR 27 (Ker) (HC) • Providing midday meals to poor people by collecting money from govt agencies – not a charity • M/S. Annadan Trust – 2018 (8) TMI 518 (Ker HC) • Interest earned on corpus donation – when there is specific direction from the donors – is also corpus donation – exempt u/s. 11(1)(d) • M/S Mata Amrithanandamayi Math – 2017 (9) TMI 1232 Ker HC
Charitable/religious trust – certain decisions • Rental income of trust – no std deduction of 30% allowable • Nandlal Tolani Charitable trust – 176 ITD 769 (Mum ITAT) • When the application is more than income, 15% is not allowable • Shree Surat Jilla Leuva Patidar Samaj Trust - 176 ITD 69 (Surat) (Trib. ) • Reasonable rent paid to trustees – not bar to claim exemption • Bholaram Education Society – 260 Taxman 369 (Guj HC)
Charitable/religious trust – certain issues • Applicability of sec 40(a)(ia)/40 A(3) in computing the income of the trust – rate of tax on such disallowances • Interest free loans given to another trust having similar objectives • Asset purchased by trust - used by the trustees for trust activities – element of personal use – consequences • Post amendment – allowability of depreciation on the cost of assets claimed as application of income prior to amendment • Meaning of compliance of any other law – PF, ESI, contractual obligations
THANK YOU