CH 12 Sales Agency Accounts Cash receipts and
- Slides: 55
CH 12
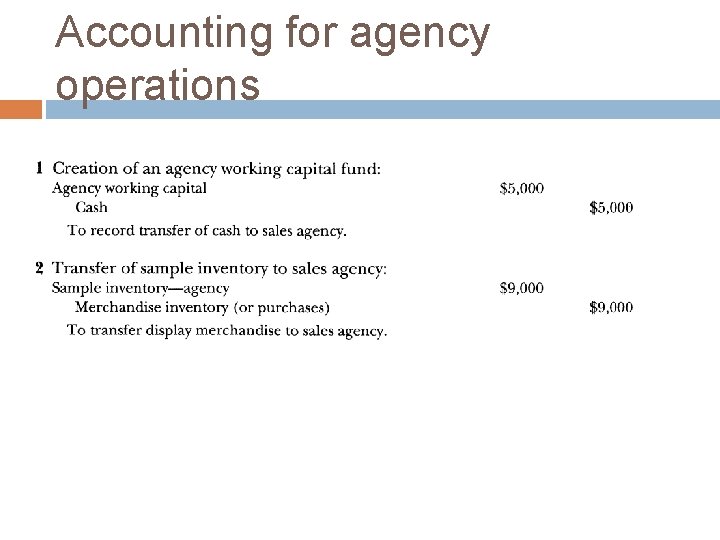
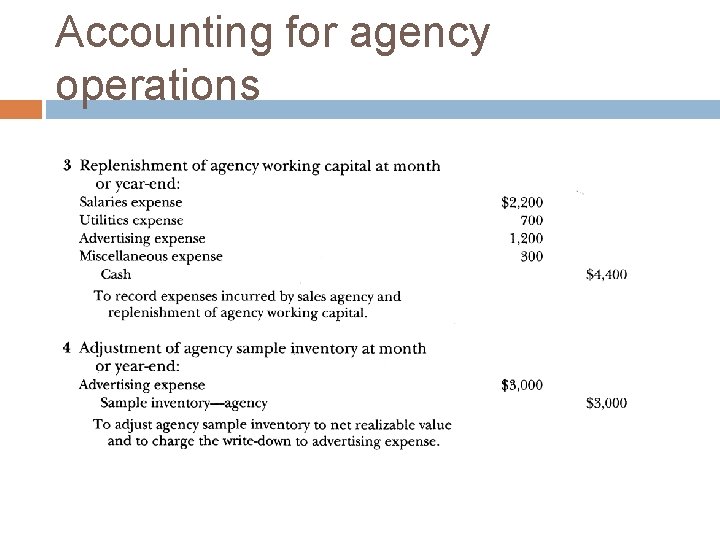
Sales Agency Accounts 銷售代理之會計記錄 Cash receipts and disbursements records are sufficient for accounting at agency locations. Records for sales agency operations must be maintained in the central accounting system of the enterprise.
Accounting for agency operations
Accounting for agency operations
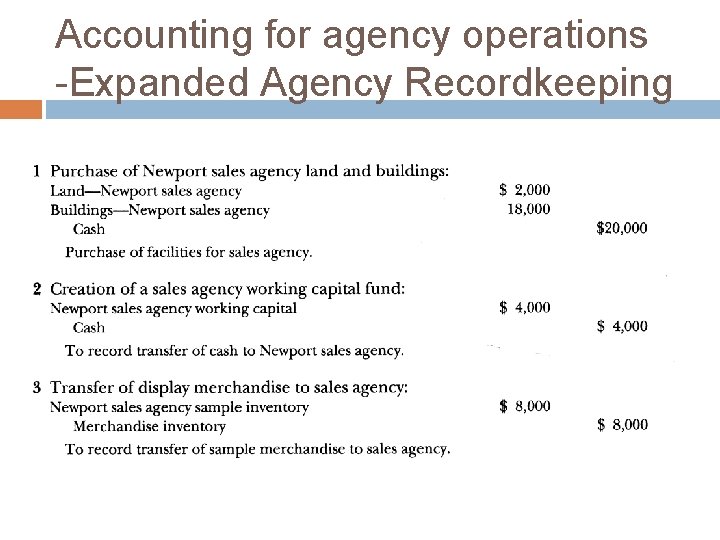
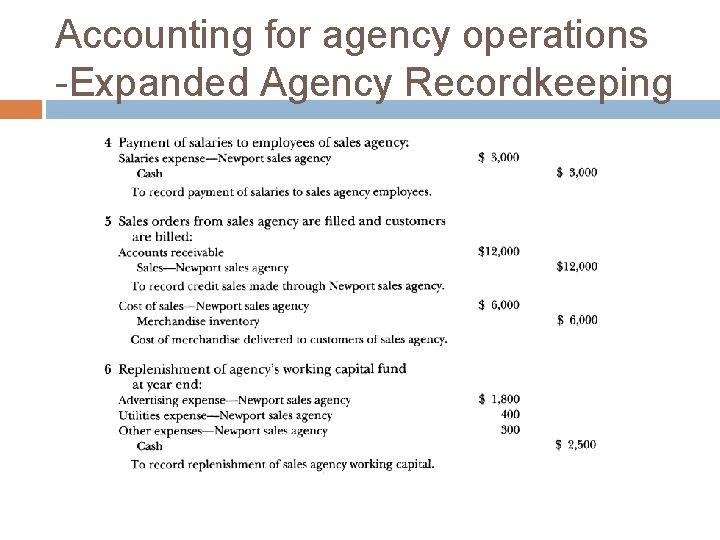
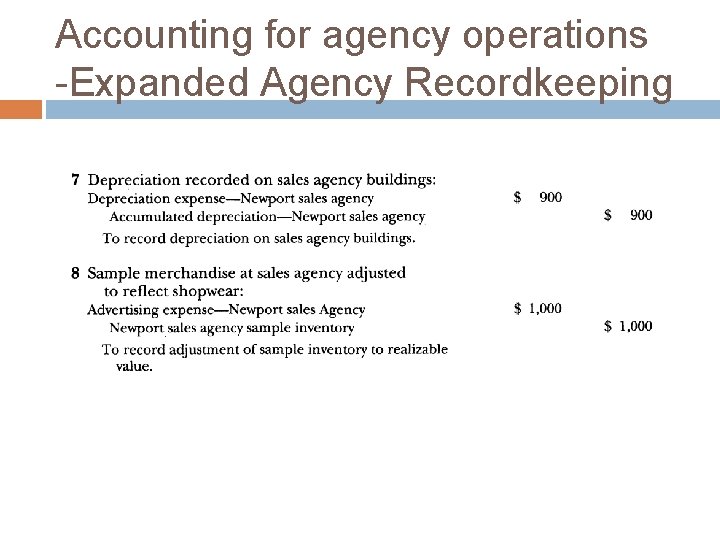
Accounting for agency operations -Expanded Agency Recordkeeping
Accounting for agency operations -Expanded Agency Recordkeeping
Accounting for agency operations -Expanded Agency Recordkeeping
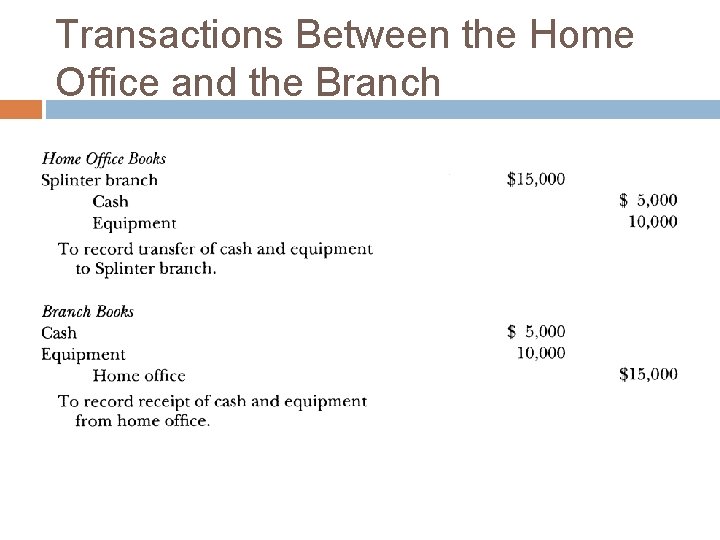
Transactions Between the Home Office and the Branch
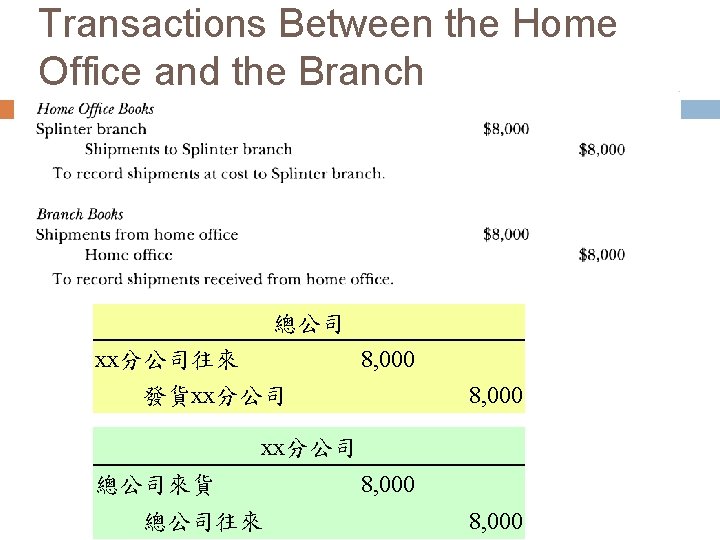
Transactions Between the Home Office and the Branch 總公司 xx分公司往來 8, 000 發貨xx分公司 總公司來貨 總公司往來 8, 000
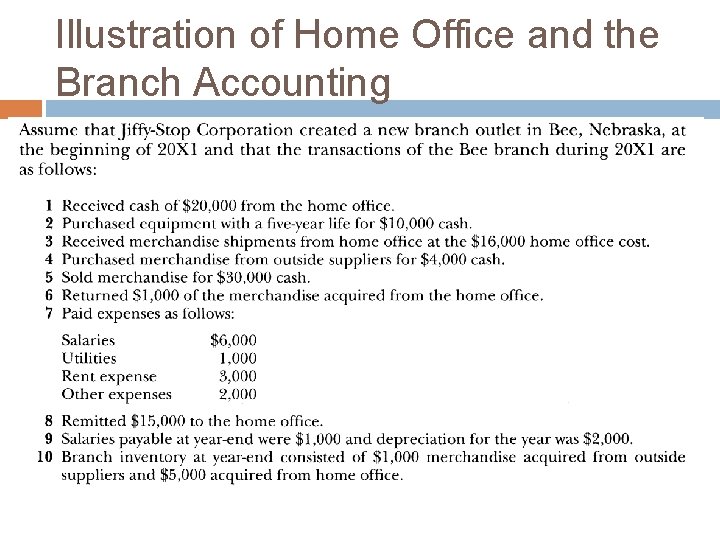
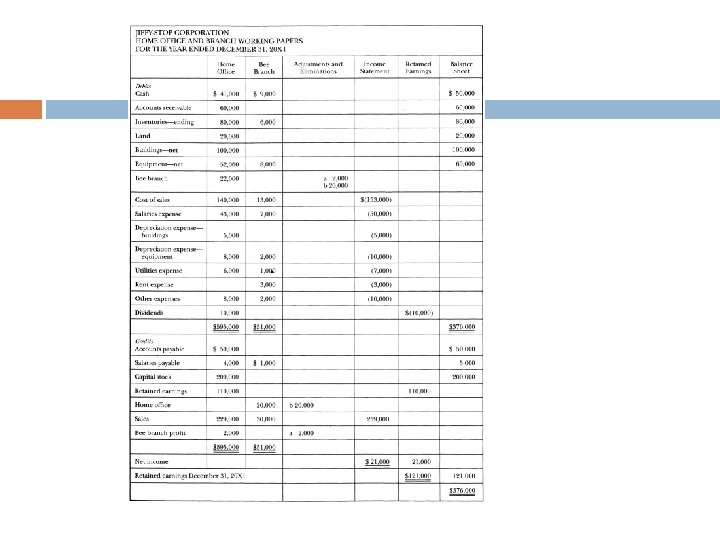
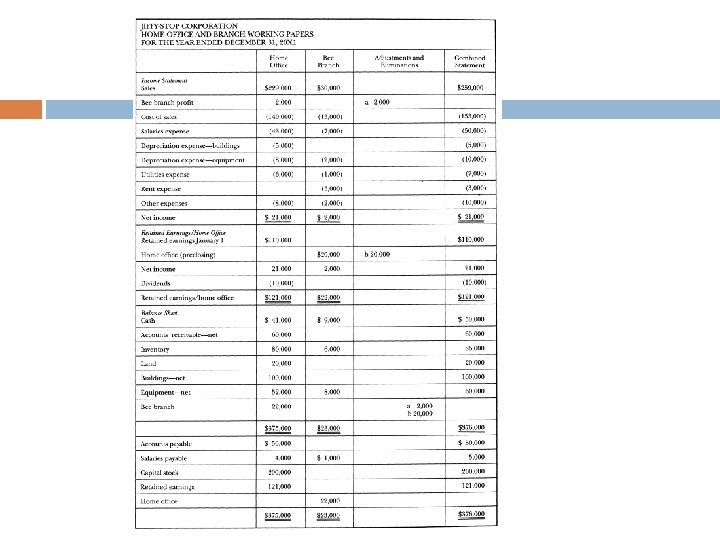
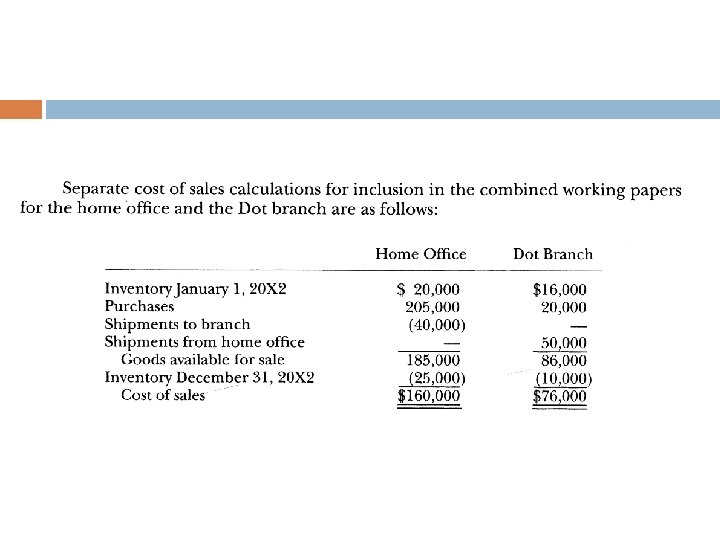
Illustration of Home Office and the Branch Accounting
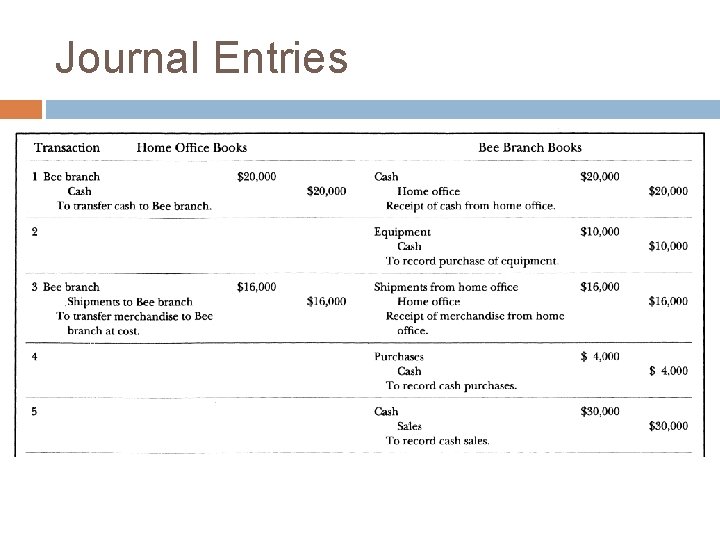
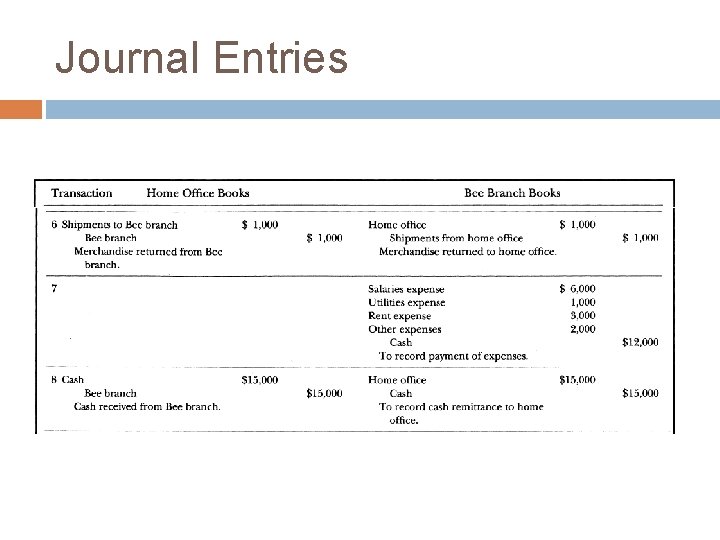
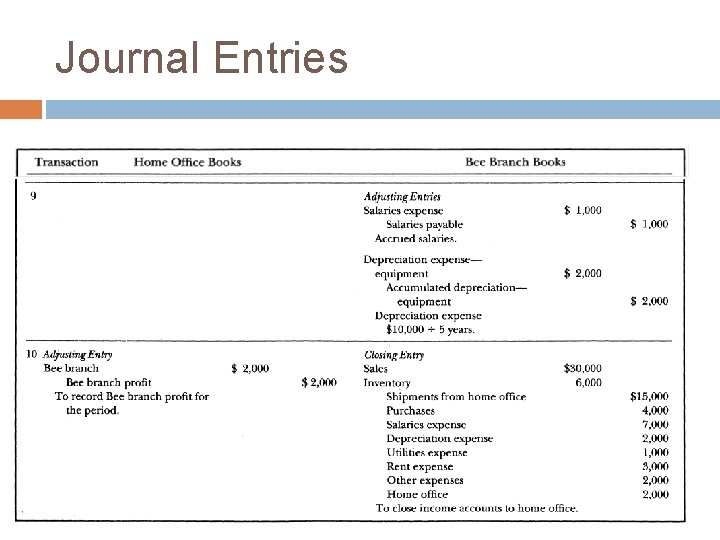
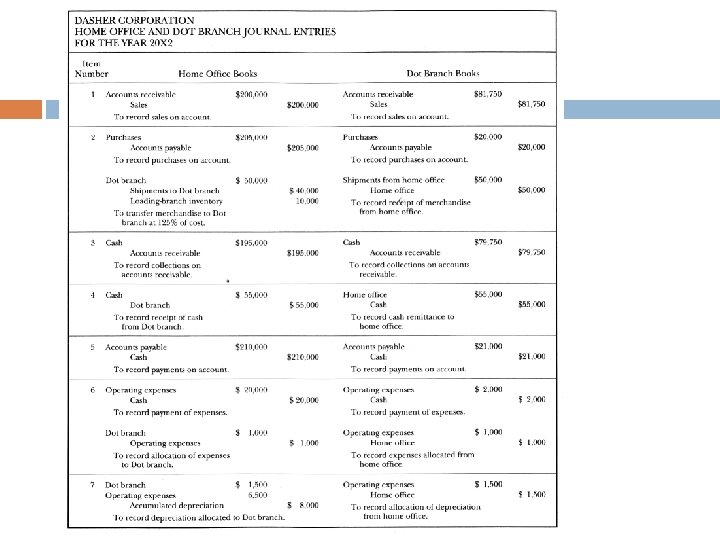
Journal Entries
Journal Entries
Journal Entries
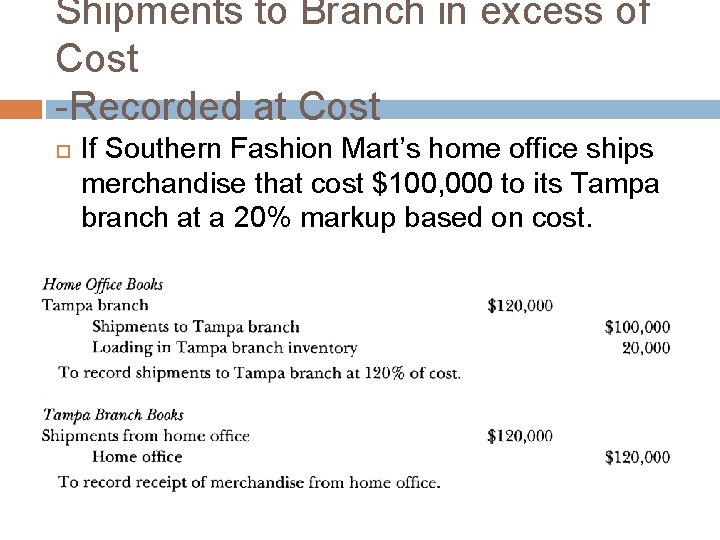
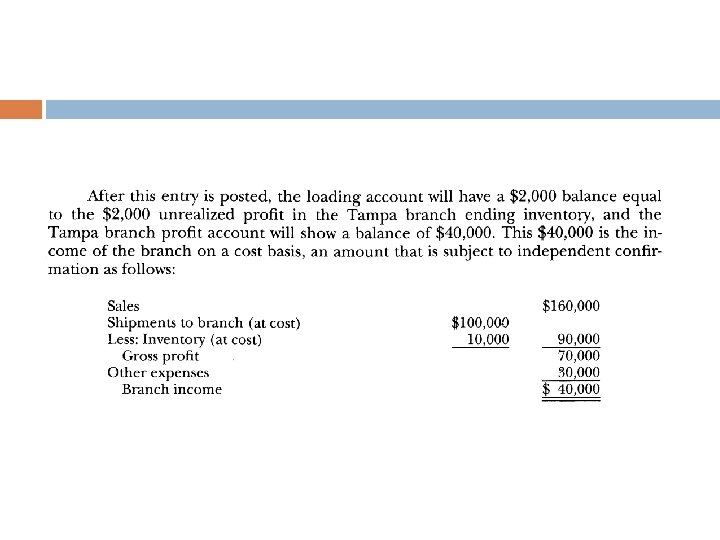
Shipments to Branch in excess of Cost -Recorded at Cost If Southern Fashion Mart’s home office ships merchandise that cost $100, 000 to its Tampa branch at a 20% markup based on cost.
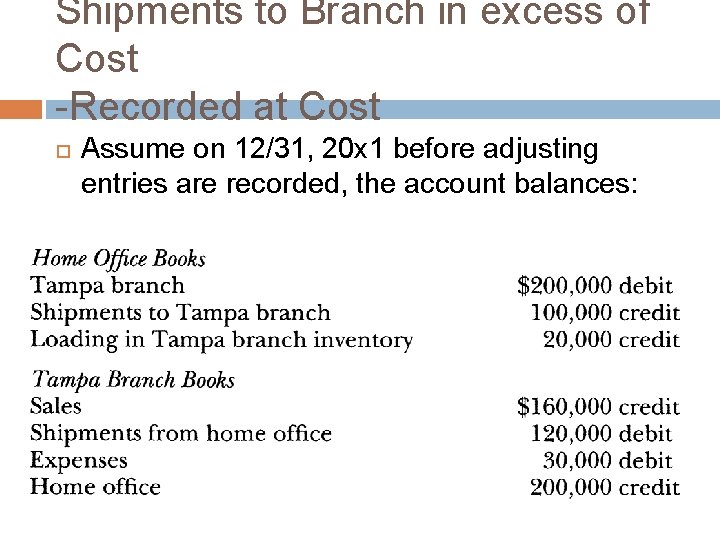
Shipments to Branch in excess of Cost -Recorded at Cost Assume on 12/31, 20 x 1 before adjusting entries are recorded, the account balances:
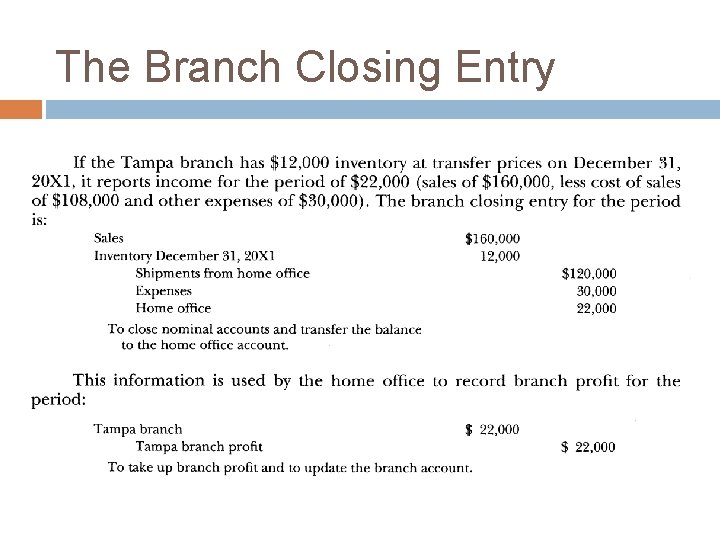
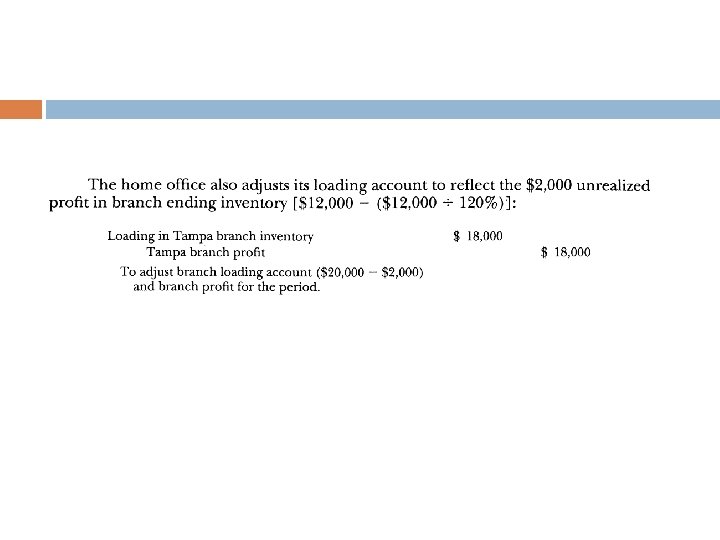
The Branch Closing Entry
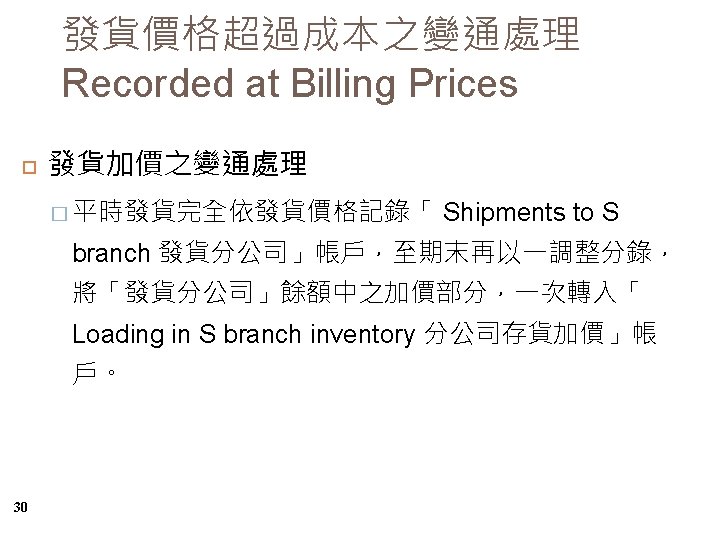
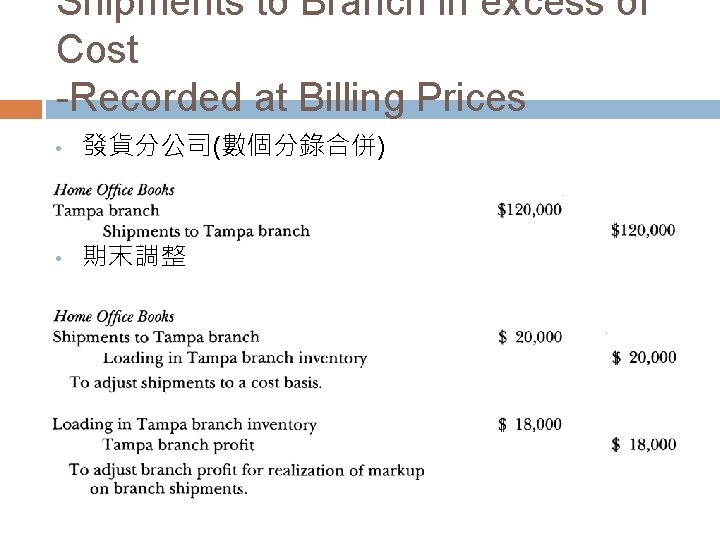
Shipments to Branch in excess of Cost -Recorded at Billing Prices • 發貨分公司(數個分錄合併) • 期末調整
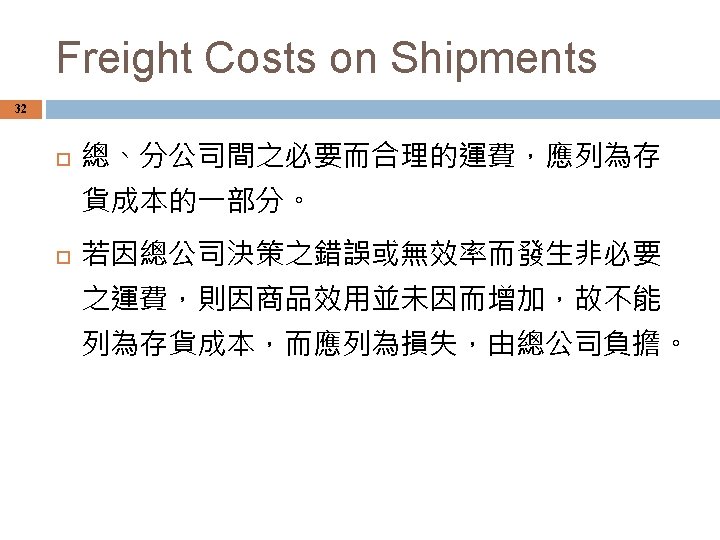
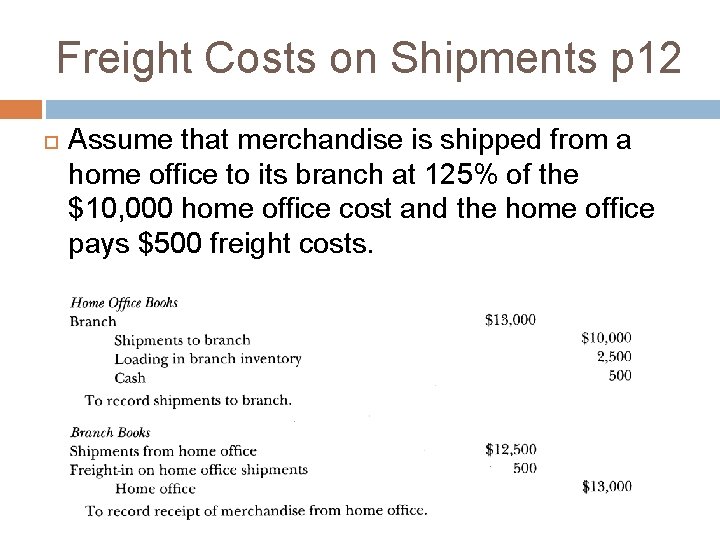
Freight Costs on Shipments p 12 Assume that merchandise is shipped from a home office to its branch at 125% of the $10, 000 home office cost and the home office pays $500 freight costs.
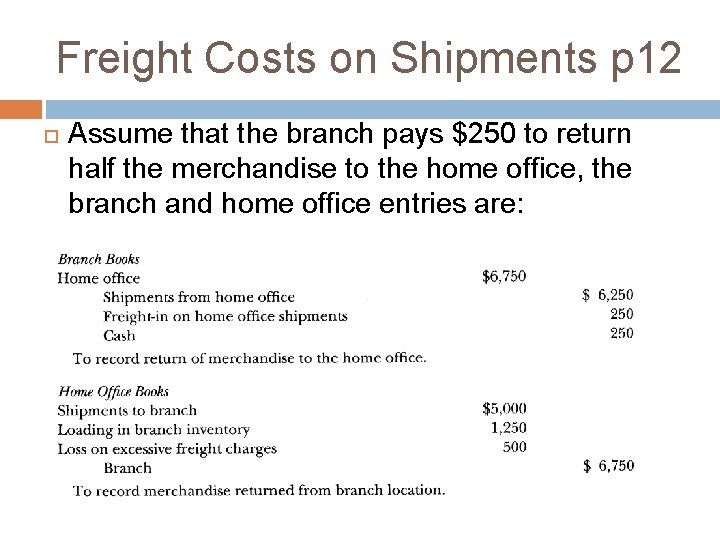
Freight Costs on Shipments p 12 Assume that the branch pays $250 to return half the merchandise to the home office, the branch and home office entries are:
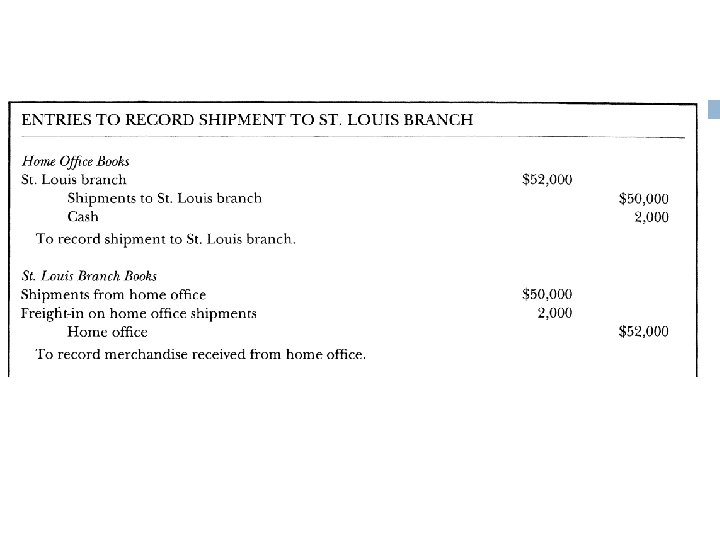
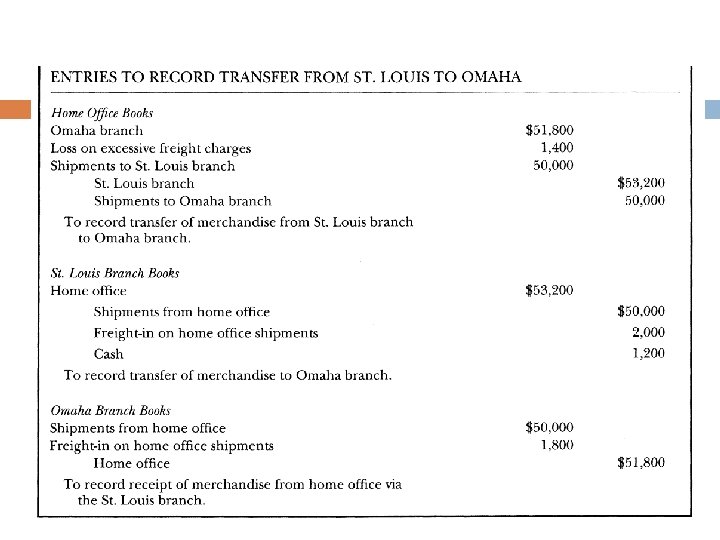
Freight Costs on Shipments p 12 Assume that the home office of Maxwell industries ships merchandise at its $50, 000 cost form Chicago to its St. Louis branch, and it pays $2, 000 freight charges on the merchandise. A few days later, the Omaha branch experiences a merchandise shortage and the merchandise is transferred from St. Louis to Omaha at a $1, 200 cost paid by the St. Louis branch. The cost of shipping the merchandise from Chicago to Omaha would have been $1, 800.
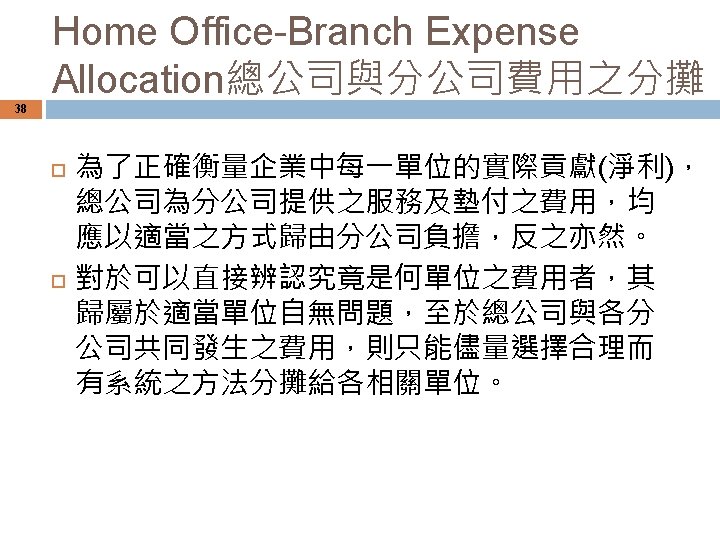
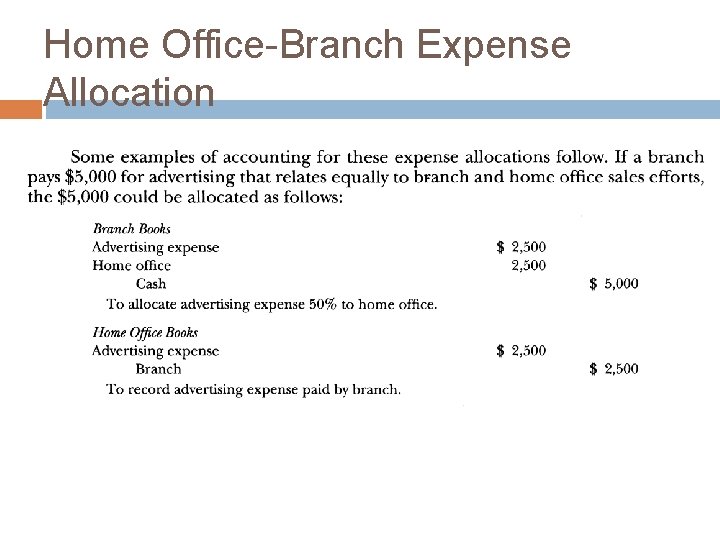
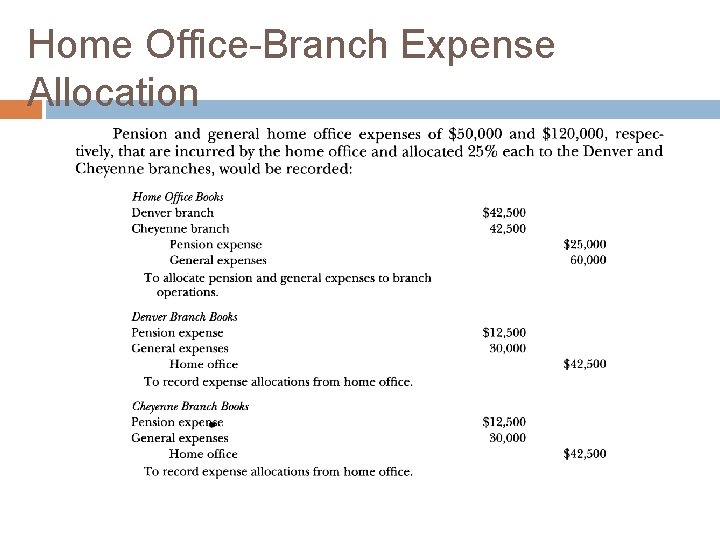
Home Office-Branch Expense Allocation
Home Office-Branch Expense Allocation
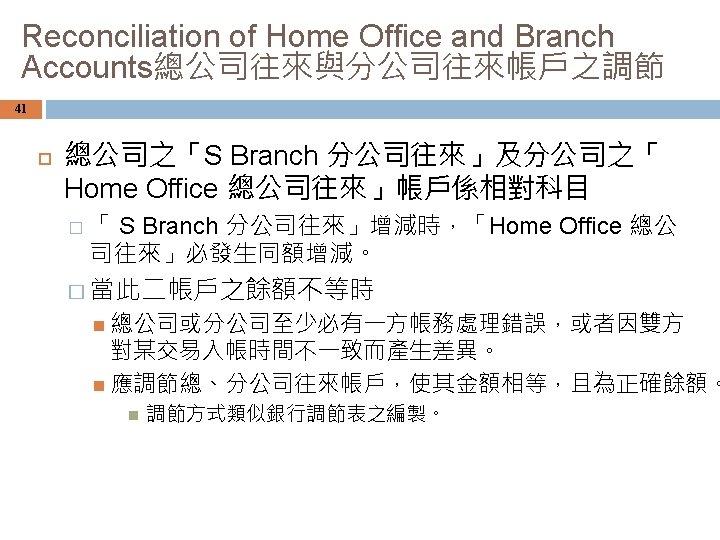
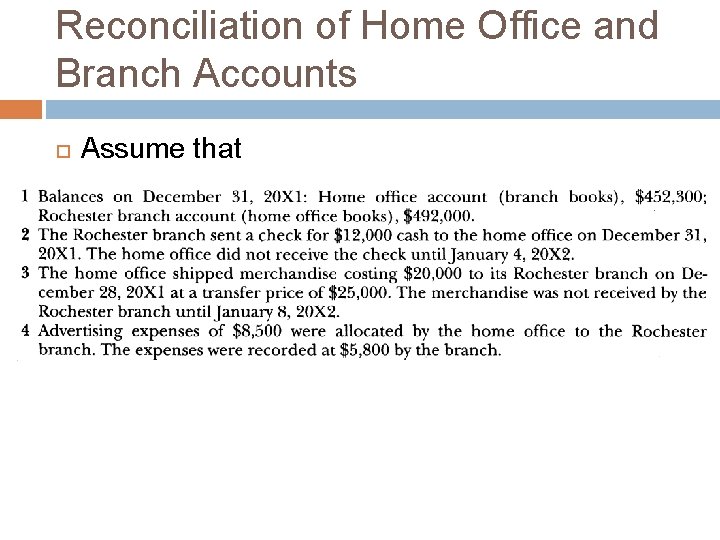
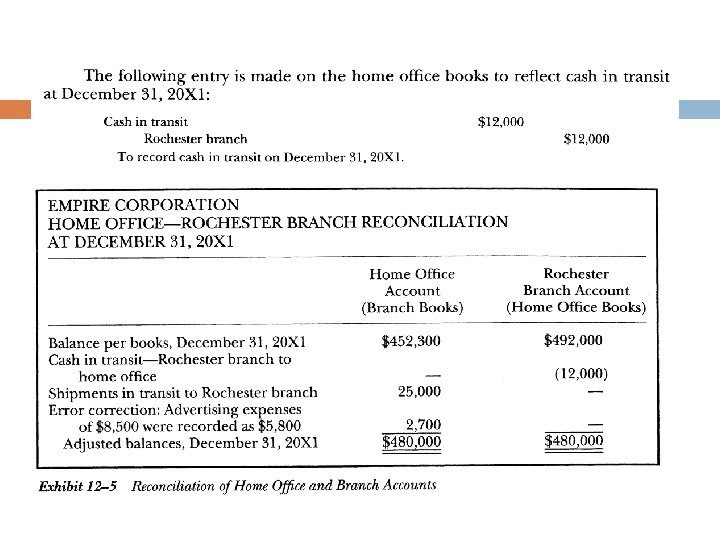
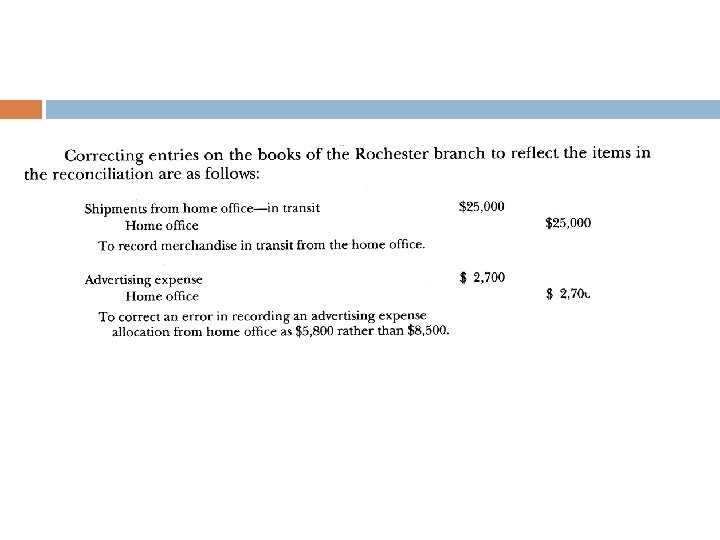
Reconciliation of Home Office and Branch Accounts Assume that
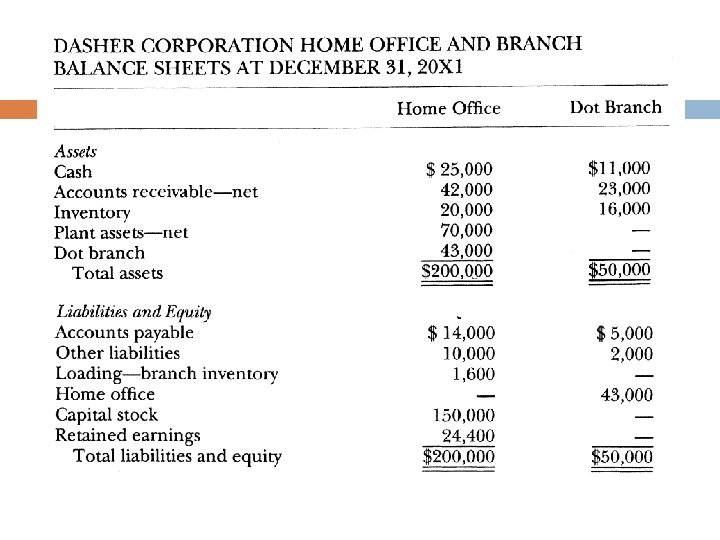
Illustration
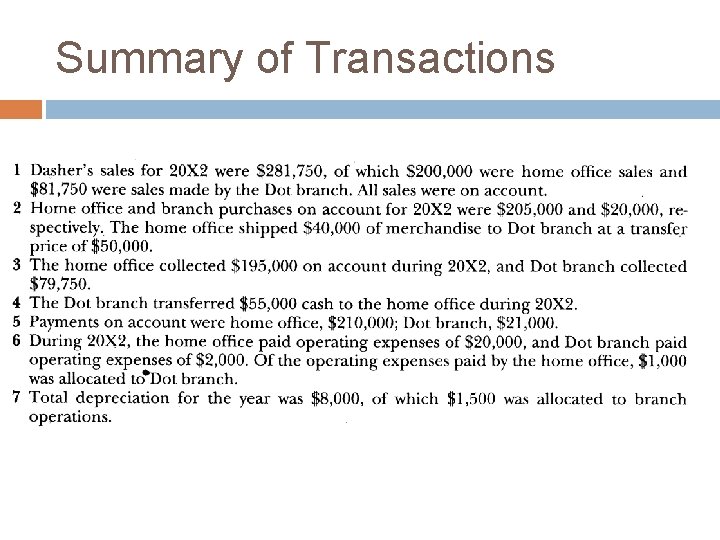
Summary of Transactions
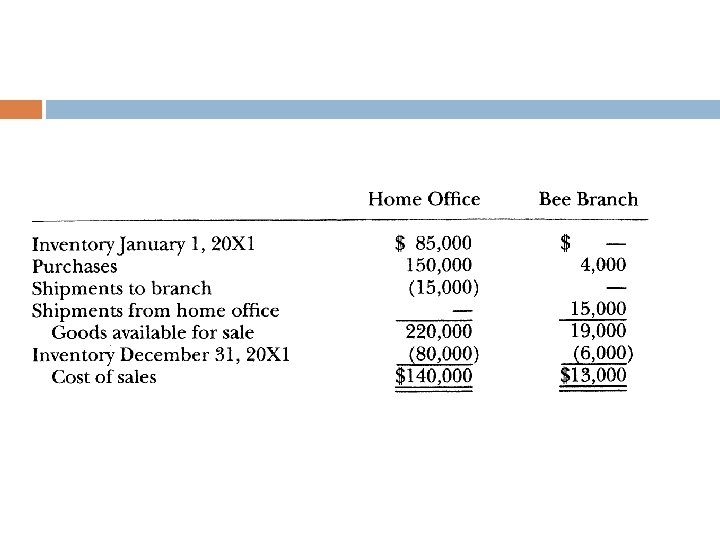
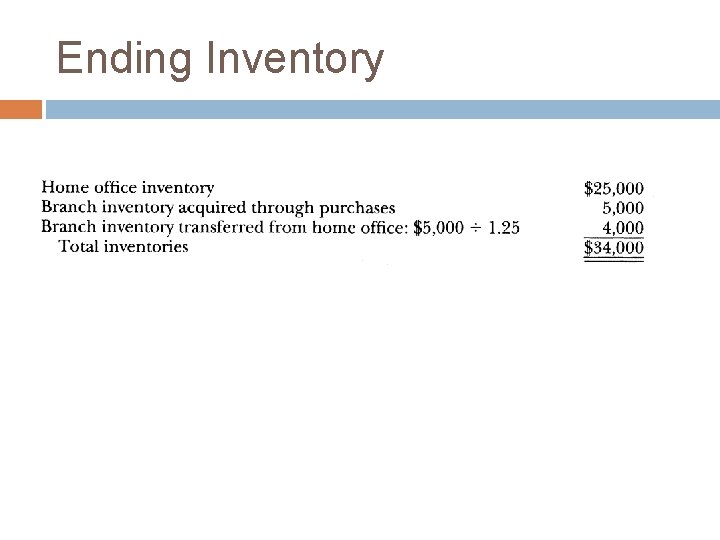
Ending Inventory
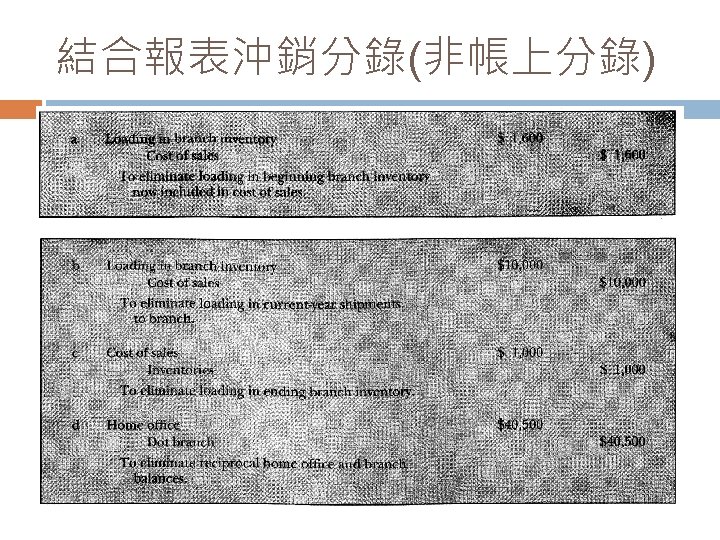
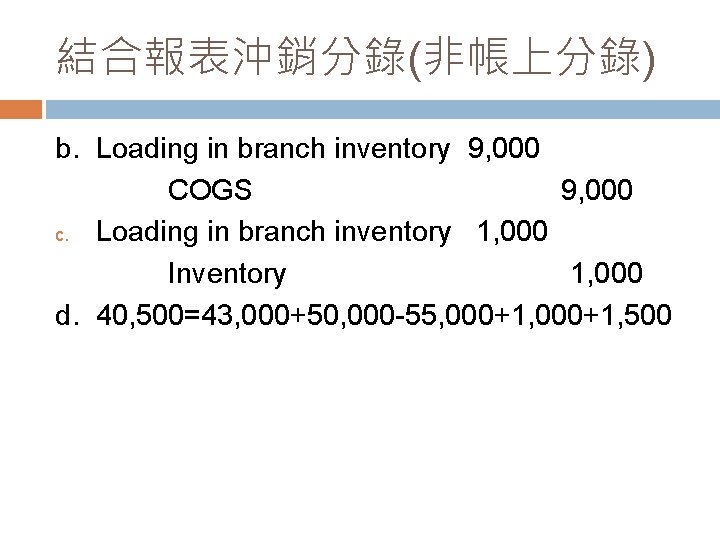
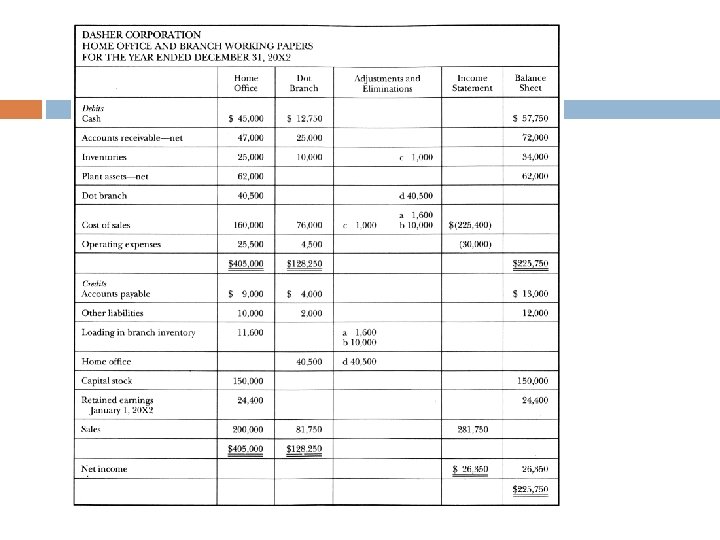
結合報表沖銷分錄(非帳上分錄) b. Loading in branch inventory 9, 000 COGS 9, 000 c. Loading in branch inventory 1, 000 Inventory 1, 000 d. 40, 500=43, 000+50, 000 -55, 000+1, 500
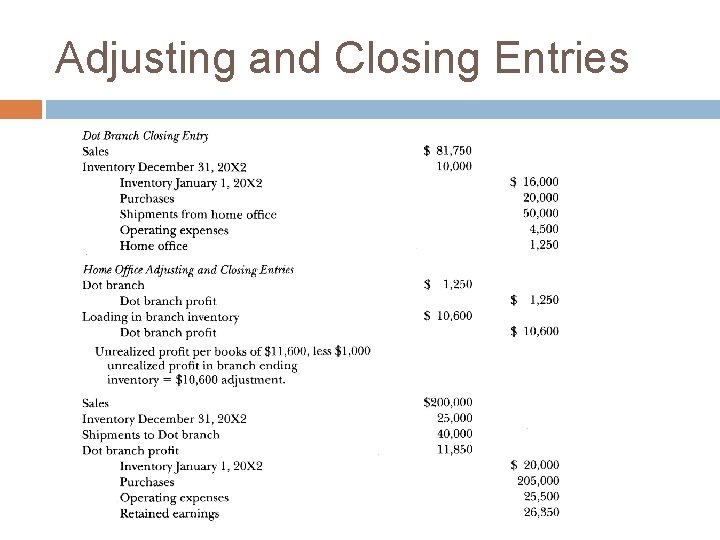
Adjusting and Closing Entries