15 1 Mortgage Payments n Find the monthly
- Slides: 29
15. 1 Mortgage Payments n Find the monthly mortgage payment n Find the total interest on a mortgage and the PITI (Principal, Interest, Taxes, and Insurance) Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Key Terms n A home is a type of “real” property. Real estate or real property is land plus any permanent improvements to the land. n Improvements include: ¡ Water or sewage systems ¡ Homes or commercial buildings ¡ Any other type of structure Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Key Terms n Mortgage: a loan in which real property is used to secure the debt. n Collateral: the property that is held as security on a mortgage. n Equity: the difference between the expected selling price and the balance owed on the property. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Key Terms n Market value: the expected selling price of a property. n First mortgage: the primary mortgage on a property. n Conventional mortgage: a mortgage that is not insured by a government program. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Conventional mortgages n Two types include: ¡ Fixed-rate mortgage: the rate of interest on the loan remains the same for the life of the mortgage. ¡ Adjustable-rate mortgage: the rate of interest may fluctuate during the life of the loan depending on the prime lending rate of most banks. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Mortgage payments n 15 -year and 30 -year loans are the most common. n Payments can be made monthly or on a biweekly plan, resulting in 26 payments. n The biweekly plan builds equity more quickly than the monthly plan. n An equity line of credit, or second mortgage, allows a homeowner to borrow against the equity in the home. It is in addition to the first mortgage. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
15. 1. 1 Find the Monthly Mortgage Payment n The repayment of a loan in equal installments that are applied to principal and interest over a period of time is called the amortization of a loan. n To calculate the monthly mortgage payment, it is customary to use a table. (See Figure 15. 1 in your text) Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
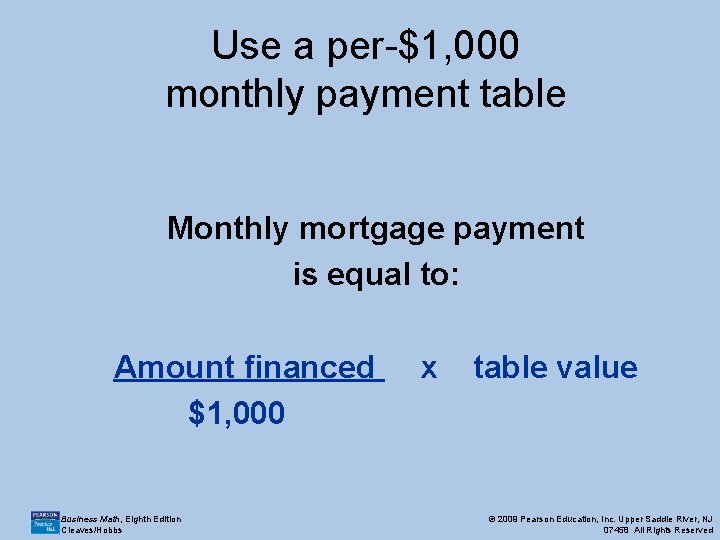
Use a per-$1, 000 monthly payment table Monthly mortgage payment is equal to: Amount financed $1, 000 Business Math, Eighth Edition Cleaves/Hobbs x table value © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
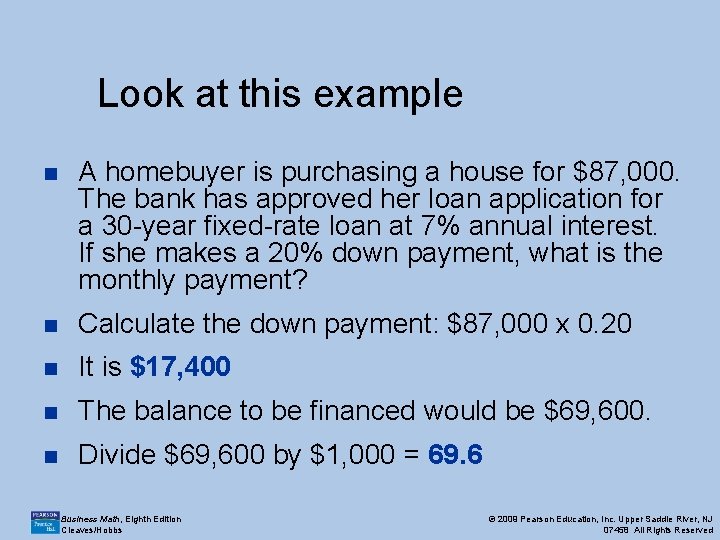
Look at this example n A homebuyer is purchasing a house for $87, 000. The bank has approved her loan application for a 30 -year fixed-rate loan at 7% annual interest. If she makes a 20% down payment, what is the monthly payment? n Calculate the down payment: $87, 000 x 0. 20 n It is $17, 400 n The balance to be financed would be $69, 600. n Divide $69, 600 by $1, 000 = 69. 6 Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
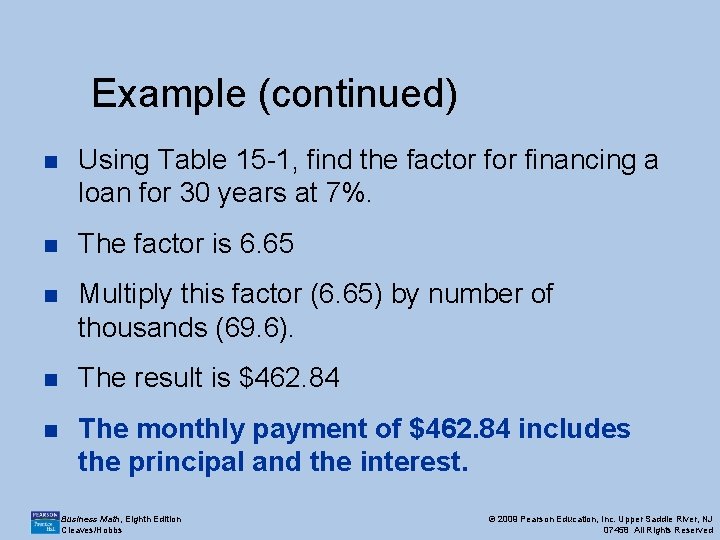
Example (continued) n Using Table 15 -1, find the factor financing a loan for 30 years at 7%. n The factor is 6. 65 n Multiply this factor (6. 65) by number of thousands (69. 6). n The result is $462. 84 n The monthly payment of $462. 84 includes the principal and the interest. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
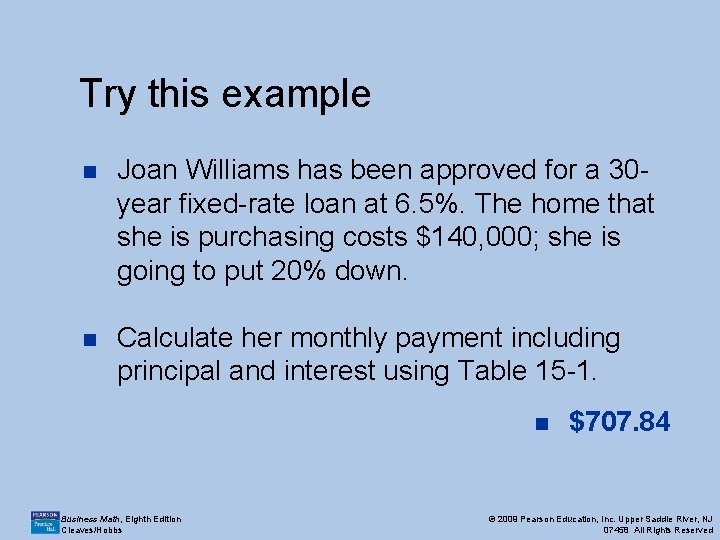
Try this example n Joan Williams has been approved for a 30 year fixed-rate loan at 6. 5%. The home that she is purchasing costs $140, 000; she is going to put 20% down. n Calculate her monthly payment including principal and interest using Table 15 -1. n Business Math, Eighth Edition Cleaves/Hobbs $707. 84 © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
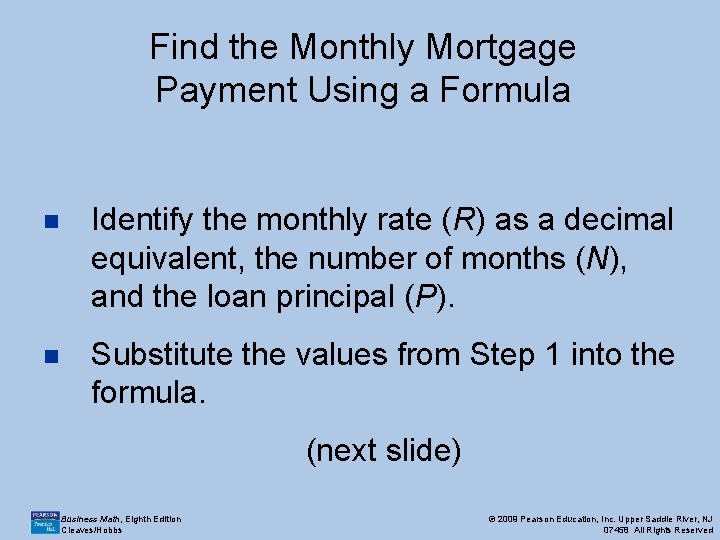
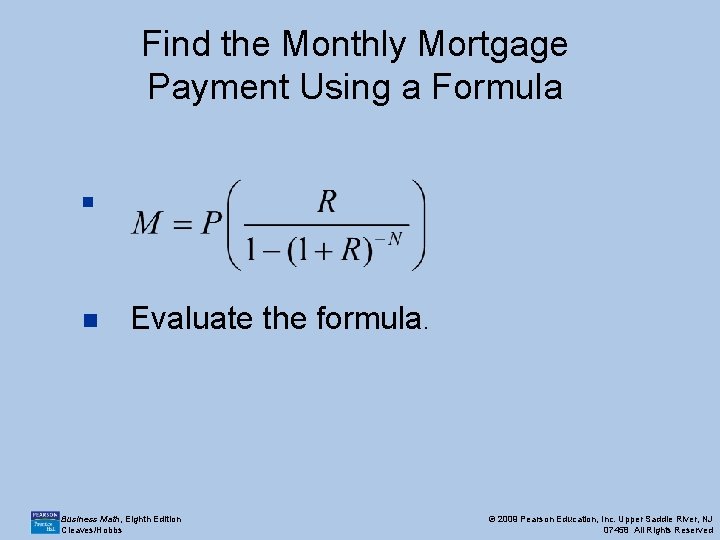
Find the Monthly Mortgage Payment Using a Formula n Identify the monthly rate (R) as a decimal equivalent, the number of months (N), and the loan principal (P). n Substitute the values from Step 1 into the formula. (next slide) Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Find the Monthly Mortgage Payment Using a Formula n n Evaluate the formula. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
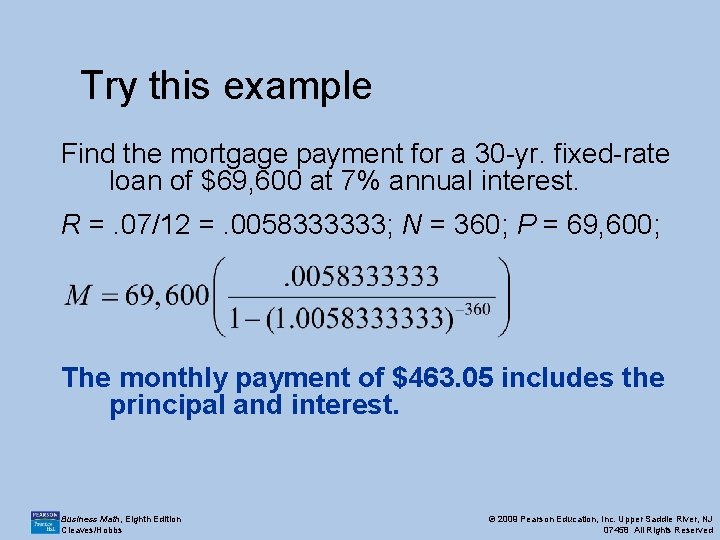
Try this example Find the mortgage payment for a 30 -yr. fixed-rate loan of $69, 600 at 7% annual interest. R =. 07/12 =. 0058333333; N = 360; P = 69, 600; The monthly payment of $463. 05 includes the principal and interest. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
15. 1. 2 Find the Total Interest on a Mortgage and the PITI n Find the total number of payments: multiply the number of payments by the amount of the payment. n Subtract the amount financed from the total of the payments. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Look at this example n In the example on Slide 11, the monthly payment of the principal and interest is $462. 84. The buyer has a 30 -year fixed mortgage. n Total interest = number of payments x amount of payment – amount financed. n TI = 30 x 12 x $462. 84 - $69, 600 n TI = $166, 622. 40 - $69, 600 n The total interest on this loan is $97, 022. 40 Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Try this example n Joan Williams’ monthly mortgage payment is $707. 84. Find the total interest on her 30 year mortgage. The amount financed is $112, 000. Find the total interest on the mortgage. n Business Math, Eighth Edition Cleaves/Hobbs $142, 822. 40 © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
Key Terms n Other costs involved in securing a mortgage include: points, attorney fees, and sales commissions among others. These are called closing costs, and are paid when the loan is made. n Points: a one-time payment to the lender that is a percent of the total loan. n Escrow: an account for holding the part of a monthly payment that is used to pay taxes and insurance. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
PITI n The adjusted monthly payment that includes the principal, interest, taxes and insurance is abbreviated “PITI. ” n The monthly mortgage payment that the borrower will make will include all four elements. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
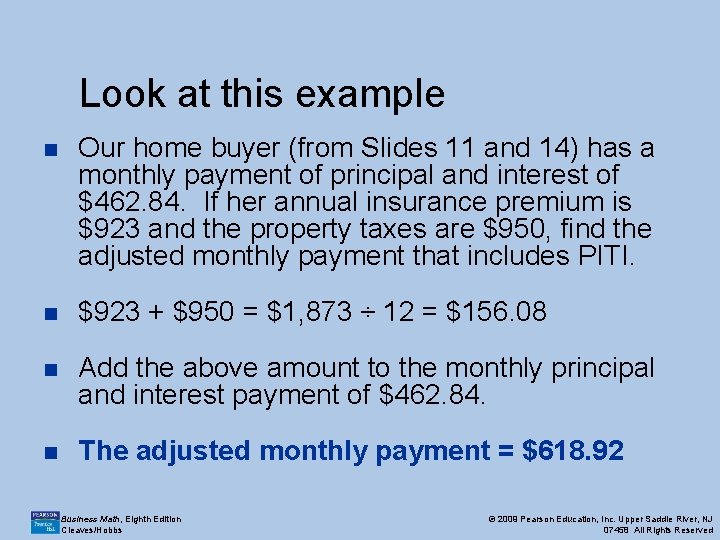
Look at this example n Our home buyer (from Slides 11 and 14) has a monthly payment of principal and interest of $462. 84. If her annual insurance premium is $923 and the property taxes are $950, find the adjusted monthly payment that includes PITI. n $923 + $950 = $1, 873 ÷ 12 = $156. 08 n Add the above amount to the monthly principal and interest payment of $462. 84. n The adjusted monthly payment = $618. 92 Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
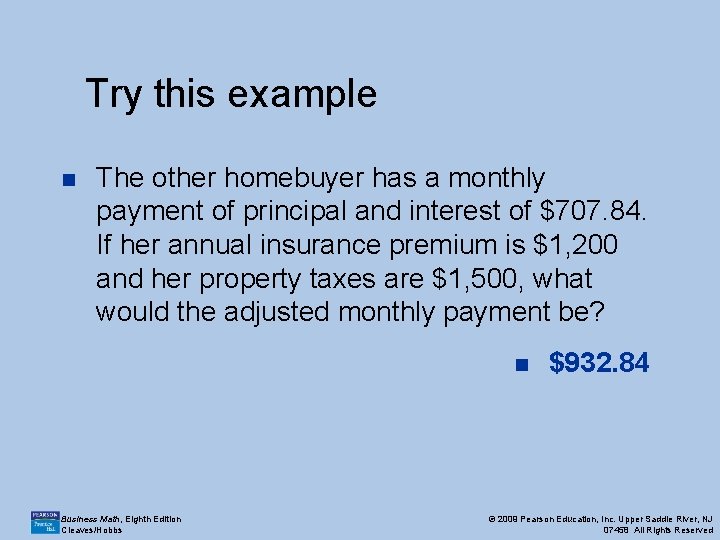
Try this example n The other homebuyer has a monthly payment of principal and interest of $707. 84. If her annual insurance premium is $1, 200 and her property taxes are $1, 500, what would the adjusted monthly payment be? n Business Math, Eighth Edition Cleaves/Hobbs $932. 84 © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
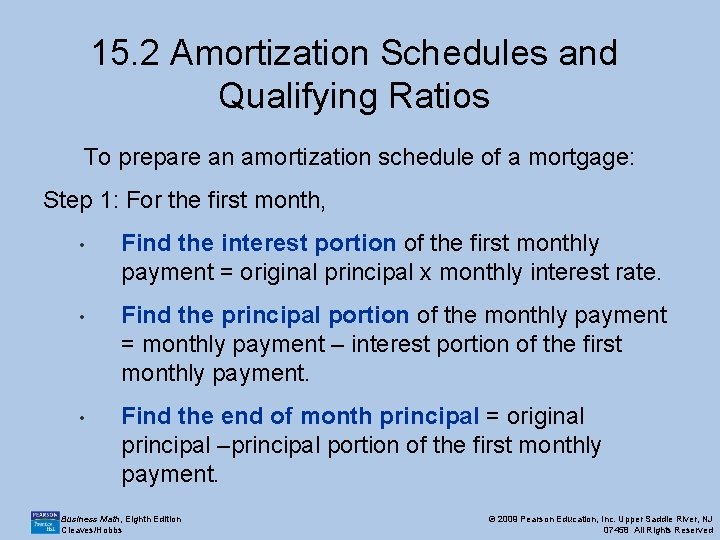
15. 2 Amortization Schedules and Qualifying Ratios To prepare an amortization schedule of a mortgage: Step 1: For the first month, • Find the interest portion of the first monthly payment = original principal x monthly interest rate. • Find the principal portion of the monthly payment = monthly payment – interest portion of the first monthly payment. • Find the end of month principal = original principal –principal portion of the first monthly payment. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
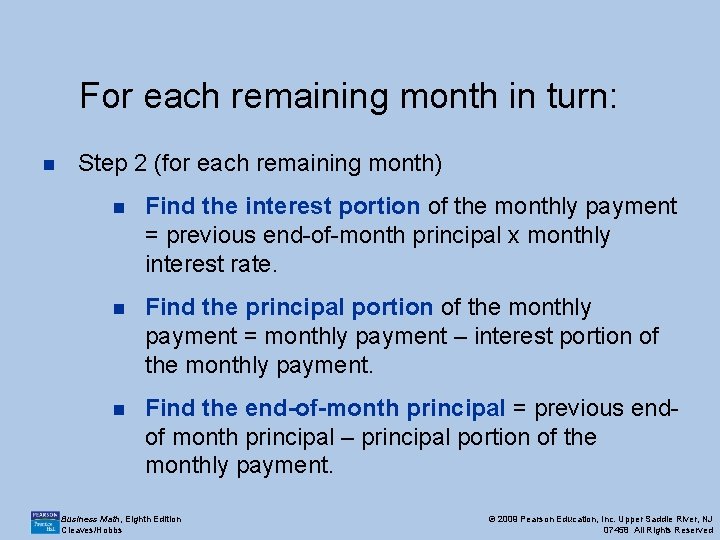
For each remaining month in turn: n Step 2 (for each remaining month) n Find the interest portion of the monthly payment = previous end-of-month principal x monthly interest rate. n Find the principal portion of the monthly payment = monthly payment – interest portion of the monthly payment. n Find the end-of-month principal = previous endof month principal – principal portion of the monthly payment. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
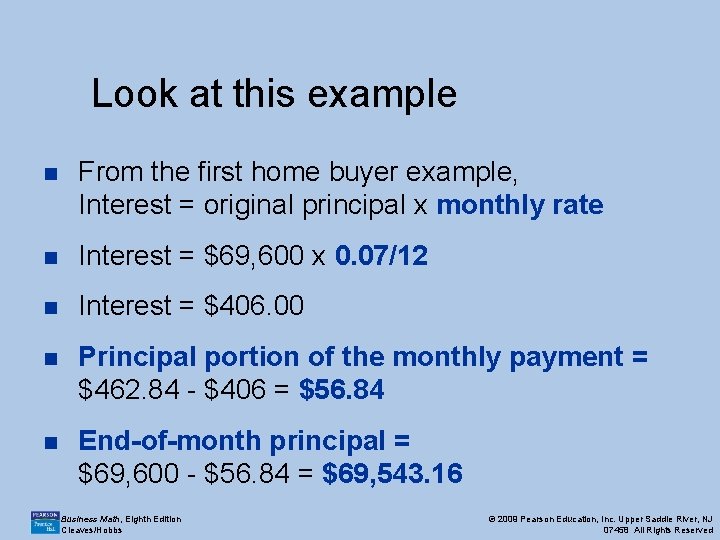
Look at this example n From the first home buyer example, Interest = original principal x monthly rate n Interest = $69, 600 x 0. 07/12 n Interest = $406. 00 n Principal portion of the monthly payment = $462. 84 - $406 = $56. 84 n End-of-month principal = $69, 600 - $56. 84 = $69, 543. 16 Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
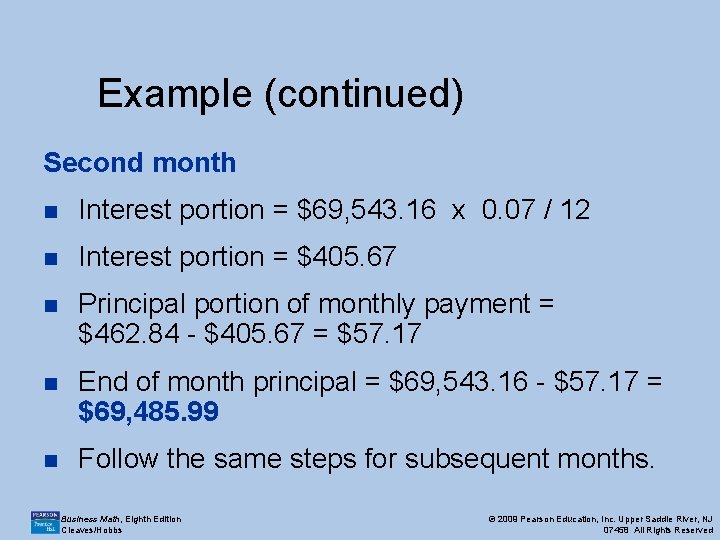
Example (continued) Second month n Interest portion = $69, 543. 16 x 0. 07 / 12 n Interest portion = $405. 67 n Principal portion of monthly payment = $462. 84 - $405. 67 = $57. 17 n End of month principal = $69, 543. 16 - $57. 17 = $69, 485. 99 n Follow the same steps for subsequent months. Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
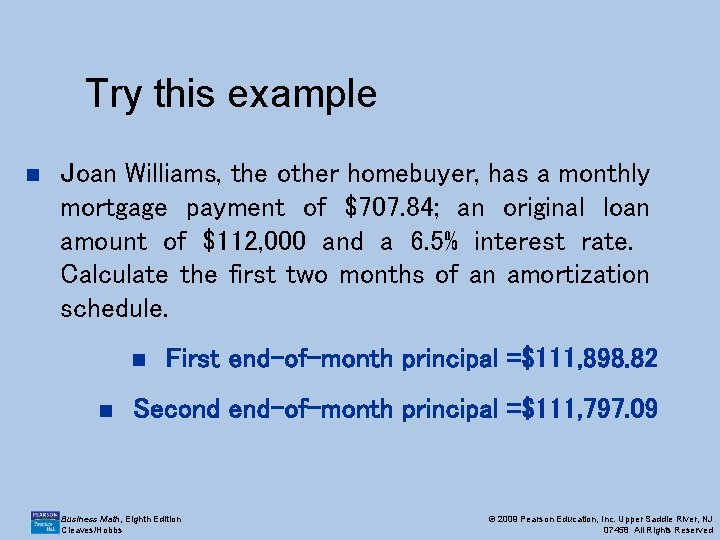
Try this example n Joan Williams, the other homebuyer, has a monthly mortgage payment of $707. 84; an original loan amount of $112, 000 and a 6. 5% interest rate. Calculate the first two months of an amortization schedule. n n First end-of-month principal =$111, 898. 82 Second end-of-month principal =$111, 797. 09 Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
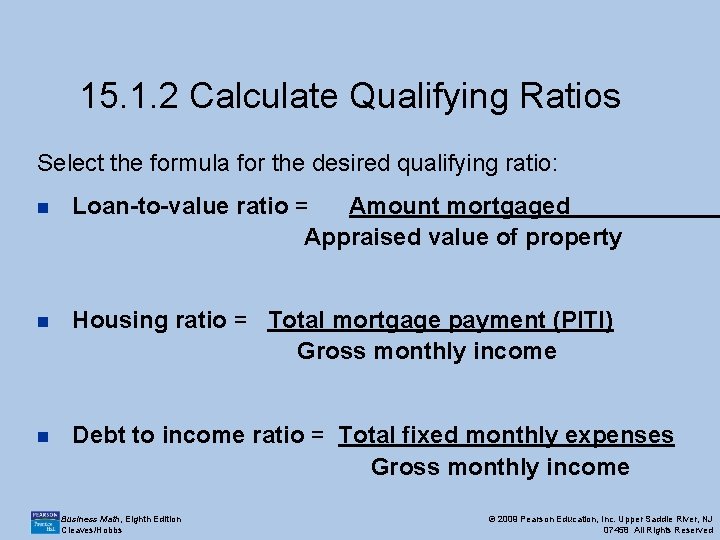
15. 1. 2 Calculate Qualifying Ratios Select the formula for the desired qualifying ratio: n Loan-to-value ratio = Amount mortgaged Appraised value of property n Housing ratio = Total mortgage payment (PITI) Gross monthly income n Debt to income ratio = Total fixed monthly expenses Gross monthly income Business Math, Eighth Edition Cleaves/Hobbs © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved
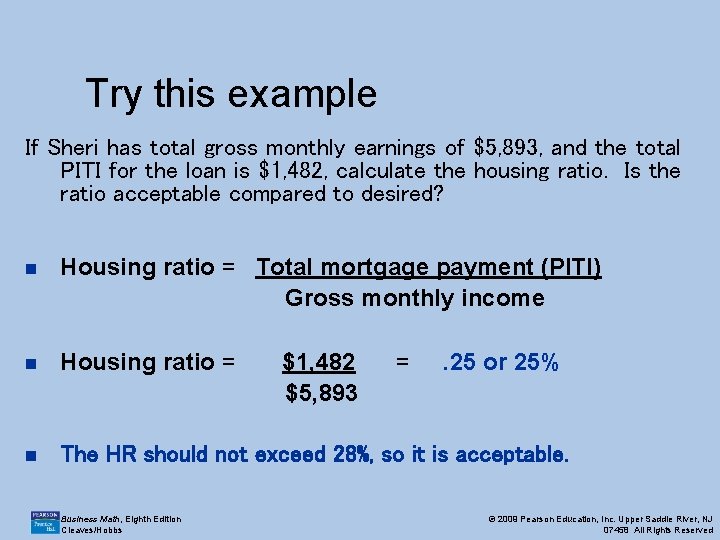
Try this example If Sheri has total gross monthly earnings of $5, 893, and the total PITI for the loan is $1, 482, calculate the housing ratio. Is the ratio acceptable compared to desired? n Housing ratio = Total mortgage payment (PITI) Gross monthly income n Housing ratio = n The HR should not exceed 28%, so it is acceptable. Business Math, Eighth Edition Cleaves/Hobbs $1, 482 $5, 893 = . 25 or 25% © 2009 Pearson Education, Inc. Upper Saddle River, NJ 07458 All Rights Reserved