
WHAT THE HECM RMS AGENT DEVELOPMENT 5 Star
- Slides: 31
WHAT THE HECM? RMS AGENT DEVELOPMENT 5 Star Conference // Dallas, TX September 15, 2015
REO Management Solutions (REOMS) is a wholly-owned subsidiary of Reverse Mortgage Solutions, Inc. (RMS) that specializes in asset management and liquidating bank-owned properties on behalf of investors. Walters Investment Corporation Sister companies with : Ditech/Greentree, Everbank, MA Systems RMS specializes in: Ø liquidating reverse mortgage/HECM REOs Ø maximizing return of HUD insurance process Ø diminishing investor exposure to loss 2 Q 4 2014 For Mortgage Professionals Only
HECM Home Equity Conversion Mortgage Industry term is a Reverse Mortgage 3 Q 4 2014 For Mortgage Professionals Only
HECM Product Overview Tool to allow seniors the opportunity to remain in their homes and to supplement income. Borrower Requirements You must: Be 62 years of age or older Own the property outright or paid-down a considerable amount Occupy the property as your principal residence Not be delinquent on any federal debt Participate in a consumer information session given by a HUD- approved HECM counselor Property Requirements Meet all FHA property standards and flood requirements: Single family home or 2 -4 unit home with one unit occupied by the borrower HUD-approved condominium project Manufactured home that meets FHA requirements Financial Requirements Income, assets, monthly living expenses, and credit history will be verified. Timely payment of real estate taxes, hazard and flood insurance premiums will be verified For Mortgage Professionals Only 4 Q 4 2014
HECM Product Overview But what does this mean to for me as an agent…. Future Inventory 5 Q 4 2014 For Mortgage Professionals Only
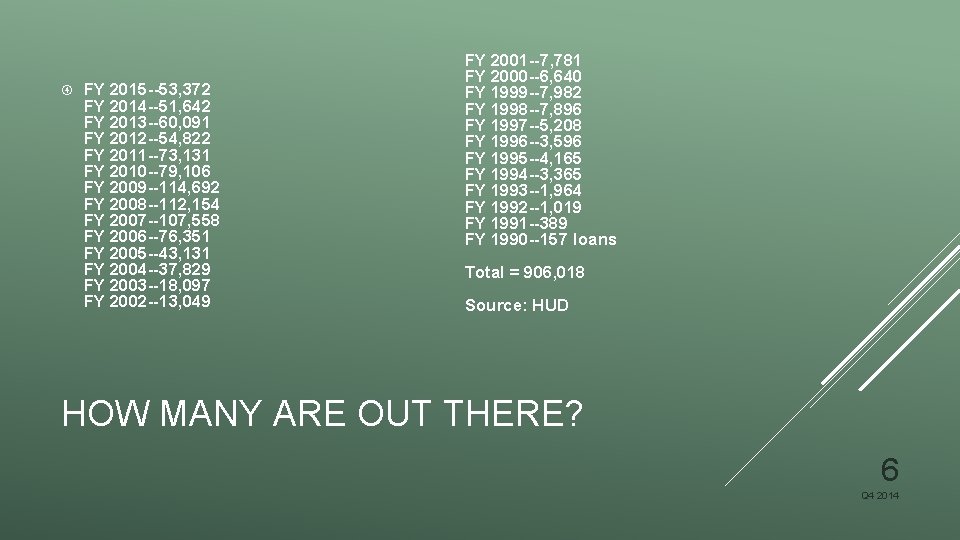
FY 2015 --53, 372 FY 2014 --51, 642 FY 2013 --60, 091 FY 2012 --54, 822 FY 2011 --73, 131 FY 2010 --79, 106 FY 2009 --114, 692 FY 2008 --112, 154 FY 2007 --107, 558 FY 2006 --76, 351 FY 2005 --43, 131 FY 2004 --37, 829 FY 2003 --18, 097 FY 2002 --13, 049 FY 2001 --7, 781 FY 2000 --6, 640 FY 1999 --7, 982 FY 1998 --7, 896 FY 1997 --5, 208 FY 1996 --3, 596 FY 1995 --4, 165 FY 1994 --3, 365 FY 1993 --1, 964 FY 1992 --1, 019 FY 1991 --389 FY 1990 --157 loans Total = 906, 018 Source: HUD HOW MANY ARE OUT THERE? 6 Q 4 2014
HECM Product Overview All reverse mortgages by nature are designed to default. You are giving seniors the ability to stay in their homes with no obligation to pay off the debt. But inevitably default happens… 1. 2. 3. 4. Death of borrowers Tax and Insurance Failure to repair property as a condition of the loan Occupancy 7 Q 4 2014 For Mortgage Professionals Only
HECM Product Overview Default- now what? Borrower or borrower’s heir can redeem the loan. • 6 month timeframe with 2 optional 90 day extensions - House can sit for a year before going to FC. Some of these sit for even longer as we wait for the courts to process the legal steps Short sales and DILs are an option for the estate. 8 Q 4 2014 For Mortgage Professionals Only
HECM Product Overview Key Points for HUD marketing requirements following Foreclosure • Insured loan back to the original investor. • Must sell at the current valid FHA appraised value. * approval to 95% may be granted by HUD as a condition • Sold “as is” no utilities no repairs unless for health and safety or require by local laws. • All valid preservation expenses and curative expenses will be reimbursed to the investor as long as they incurred during the insured period. 9 Q 4 2014 For Mortgage Professionals Only
HECM Product Overview Preservation rules ML 2010 -18 Exb B – Schedule of allowances • $2500 from noncompliance and/or default • Most of the time this money has been spent. • The process to get more money is called a 50002. It’s an over-allowable request for more money. Probably biggest frustration from an agent’s point of view. Not much visibility to the process. Must be submitted by the servicer and coordinated back through local preservation. 10 Q 4 2014 For Mortgage Professionals Only
HECM Product Overview Occupied Assets 6 types 1. Former Borrower 2. Non Borrowing spouse 3. Tenants 4. Heirs 5. Unauthorized Occupants- Squatters 6. Personal Property HUD does not offer Cash For Keys- non-reimbursable investor expense 11 Q 4 2014 For Mortgage Professionals Only
Marketable Title Established Ø The marketable title date (MT) is determined by the most recent of the following three dates: 1. Vacant date 2. Foreclosure Deed recorded date 3. Expiration of Redemption, Ratification or Confirmation *including IRS redemption rights 6 month clock starts upon latest event 12 Q 4 2014 For Mortgage Professionals Only
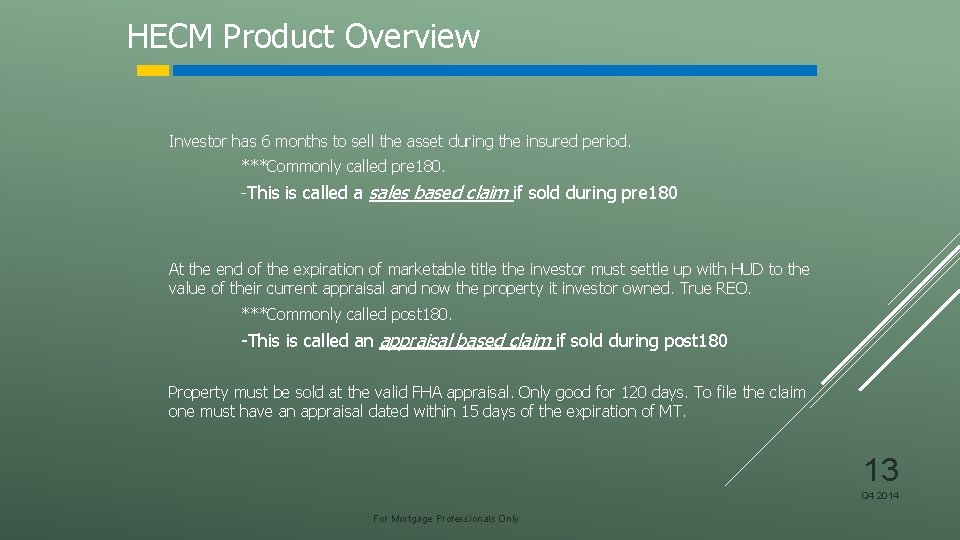
HECM Product Overview Investor has 6 months to sell the asset during the insured period. ***Commonly called pre 180. -This is called a sales based claim if sold during pre 180 At the end of the expiration of marketable title the investor must settle up with HUD to the value of their current appraisal and now the property it investor owned. True REO. ***Commonly called post 180. -This is called an appraisal based claim if sold during post 180 Property must be sold at the valid FHA appraisal. Only good for 120 days. To file the claim one must have an appraisal dated within 15 days of the expiration of MT. 13 Q 4 2014 For Mortgage Professionals Only
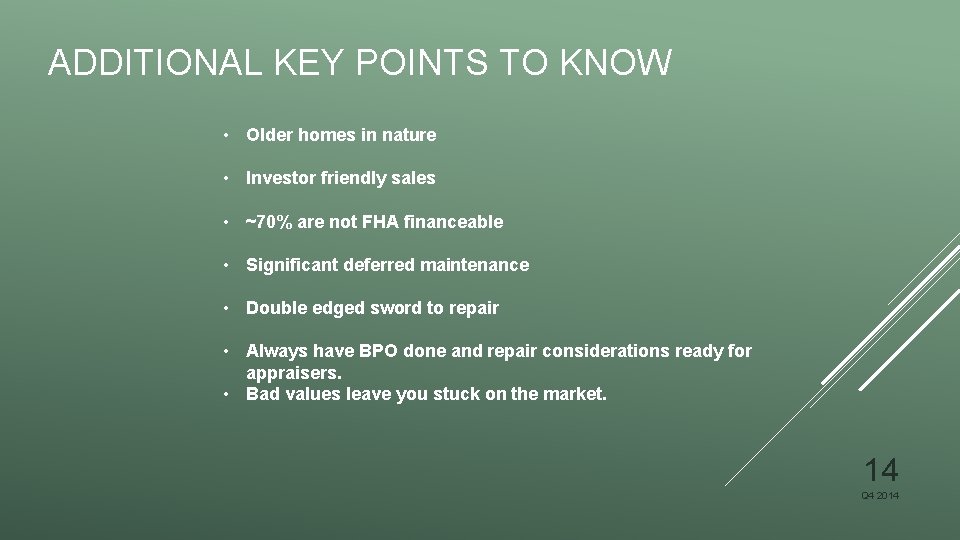
ADDITIONAL KEY POINTS TO KNOW • Older homes in nature • Investor friendly sales • ~70% are not FHA financeable • Significant deferred maintenance • Double edged sword to repair • Always have BPO done and repair considerations ready for appraisers. • Bad values leave you stuck on the market. 14 Q 4 2014
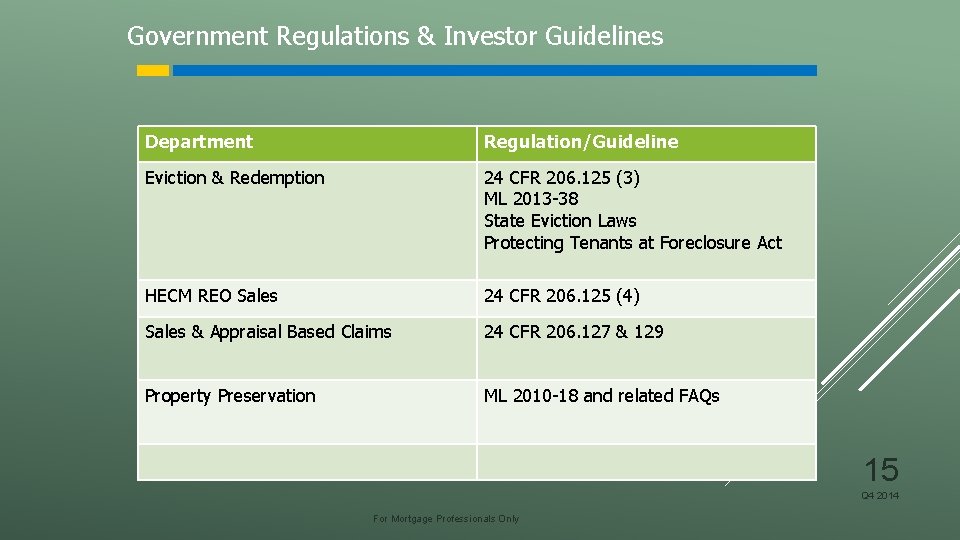
Government Regulations & Investor Guidelines Department Regulation/Guideline Eviction & Redemption 24 CFR 206. 125 (3) ML 2013 -38 State Eviction Laws Protecting Tenants at Foreclosure Act HECM REO Sales 24 CFR 206. 125 (4) Sales & Appraisal Based Claims 24 CFR 206. 127 & 129 Property Preservation ML 2010 -18 and related FAQs 15 Q 4 2014 For Mortgage Professionals Only
What does the future at RMS look like?
RMS CLIENT MATRIX (8188) ENT Federal Credit Union (7022) Random Properties Acquisition, Corp. III (8115) Random Properties Acquisition-HECM (7087) Transcendent Investments Management (7056) Wells-Riverview 2007 -1 (7067) Wells-Riverview 2007 -2 (7058) Wells-Riverview 2007 -3 (7020) World Alliance Financial Group o Total commission is 6% of sale price, of which 1% is to be paid to RMS. o There is no minimum commission offered. o Client will consider a sales price of 95% of the appraised value
RMS CLIENT MATRIX (cont. ) (7271) RMS-RBS-Greenwich (7299) RMS-Owned (7394) RMS-Goldman (7416) RMS-FNMA Repurchase (7418) RMS-GNMA o o o Total commission is 6% to be equally split between LA/SA. Minimum Commission of $2, 000 applies if the total commission payout is < or = $2, 000. The $2, 000 minimum commission is to be equally divided between LA/SA. 1% referral fee does not apply. Client will consider a sales price of 95% of the appraised value
RMS CLIENT MATRIX (cont. ) (7392) RMS-MECA 2010 Trust o Total commission is 6% of sale price, of which 1% is to be paid to RMS o Client will consider a sales price of 95% of the appraised value (7945) US Bank N. A. as Trustee for MECA 2011 -1 o Total commission is 6%. o 1% referral fee does not apply. o Minimum commission is granted on a case by case basis, and determined by the client. o Client will consider a sales price of 95% of the appraised value
RMS CLIENT MATRIX (cont. ) (7091) BAML (8619) Bank of America, N. A (8797) BAML 002 (113234) BAML 2 REO Transfer o o o Total commission is 6% of sales price of which 1% is to be paid to RMS. Minimum Commission of $2, 000 applies if the total commission payout is < or = $2, 000. The $2, 000 minimum commission is to be equally divided between LA/SA. Client will consider a sales price of 95% of the appraised value Transfer assets are boarded 1 x month and may be assigned to previous listing agent.
RMS CLIENT MATRIX (cont. ) (8763) RMS-BOA-UNIS o o o Total commission is 6% of sales price of which 1% is to be paid to RMS. Minimum Commission of $2, 000 applies if the total commission payout is < or = $2, 000. The $2, 000 minimum commission is to be equally divided between LA/SA. List Price will be determined by the BPO/Appraised value Agents may be required to provide bids for repairs and debris removal Marketable Title does not apply
RMS CLIENT MATRIX (cont. ) (8285) Seattle Bank (9067) RML Trust 2013 -1 (9069) RMS Trust 2013 -2 o Total commission is 6% of sales price. o 1% referral fee does not apply. o Client will consider a sales price of 95% of the appraised value
RMS CLIENT MATRIX (cont. ) (8289) Reverse Mortgage Loan Trust 2008 -1 (8583) GTE Federal Credit Union (9069) RMS Trust 2013 -2 o o Total commission is 6% of sales price of which 1% is to be paid to RMS. Minimum Commission of $2, 000 applies if the total commission payout is < or = $2, 000. The $2, 000 minimum commission is to be equally divided between LA/SA. Client will consider a sales price of 95% of the appraised value
RMS CLIENT MATRIX (cont. ) (8237) Chetco Federal Credit Union (28393) American National Bank (300093345) Black Reef Trust – HECM (300079407) Black Reef Trust – Proprietary (109921) TRM – Proprietary *Properties not yet boarded o Total commission is 6% of sales price of which 1% is to be paid to RMS. o Client will consider a sales price of 95% of the appraised value
RMS CLIENT MATRIX (cont. ) (8187) Urban Financial of America, LLC o o o o o Total commission is 6% of sales price of which 1% is to be paid to RMS. Minimum Commission of $2, 000 applies if the total commission payout is < or = $2, 000. The $2, 000 minimum commission is to be equally divided between LA/SA. Client will consider a sales price of 95% of the appraised value 60 Day property look back Broker Marketing Questionnaire Weekly property inspections during vacancy UFA appraisal review prior to listing Agent proximity to properties: - 5 miles Urban - 15 miles Suburban - 25 miles Rural
RMS CLIENT MATRIX (cont. ) (7488) Fannie Mae o Transfer Timeline: - New/Redemption/Occupied: Transferred on 9/10/15 - Pre-Marketing &Weekly Post 180: 9/17/15 - Weekly Post 180: 9/24/15 - Listed & Weekly Post 180: 10/1/15 - Pending offer: 10/8/15 o Contract Extensions in November will only be extended on a case by case basis.
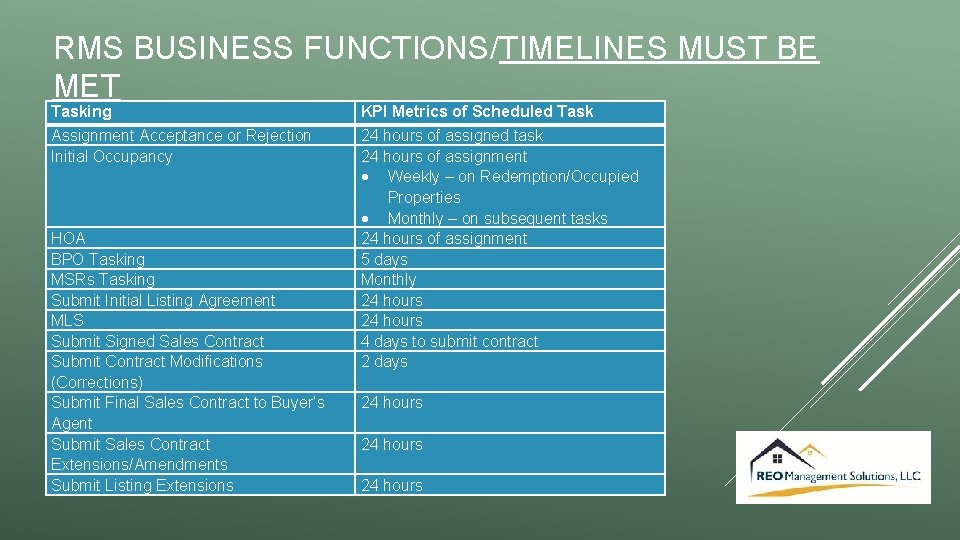
RMS BUSINESS FUNCTIONS/TIMELINES MUST BE MET Tasking KPI Metrics of Scheduled Task Assignment Acceptance or Rejection Initial Occupancy 24 hours of assigned task 24 hours of assignment Weekly – on Redemption/Occupied Properties Monthly – on subsequent tasks 24 hours of assignment 5 days Monthly 24 hours 4 days to submit contract 2 days HOA BPO Tasking MSRs Tasking Submit Initial Listing Agreement MLS Submit Signed Sales Contract Submit Contract Modifications (Corrections) Submit Final Sales Contract to Buyer’s Agent Submit Sales Contract Extensions/Amendments Submit Listing Extensions 24 hours
No Offers? No Help? GOODBYE!
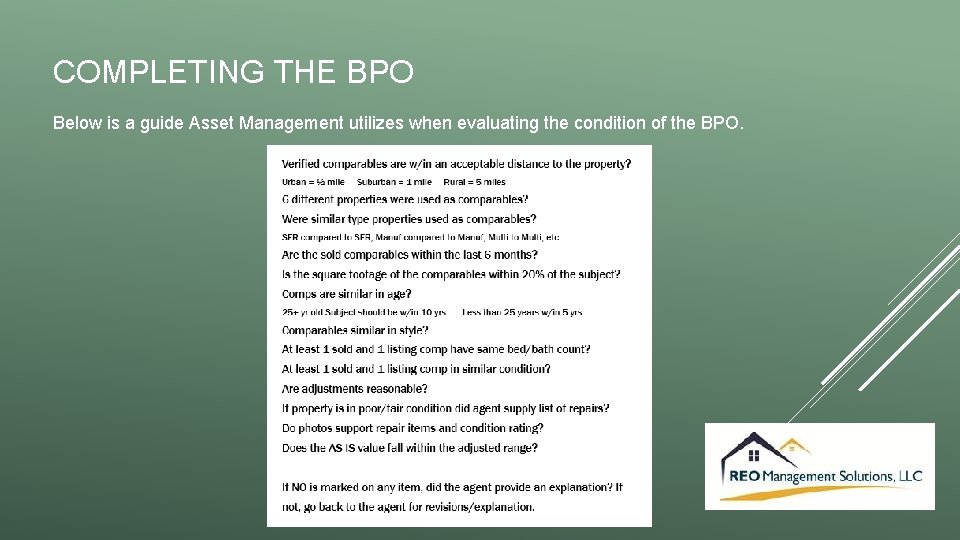
COMPLETING THE BPO Below is a guide Asset Management utilizes when evaluating the condition of the BPO.
ETHICS & PROFESSIONALISM o We expect you to adhere to your local state laws regarding real estate practice. o We expect you to remain professional at all times in your communication with RMS vendors, buyers agents, and buyers. o A few things to consider when handling RMS properties: - Property MUST be listed in your local MLS for 3 days / 5 days on BOA assets - Listing Agents are not permitted to purchase Fannie Mae assets - Not disclosing personal interest in property or the purchasing entity
REOCentral Updates o RMS Exclusive Right to sell Listing Agreement. o RMS Real Estate Purchase Addendum (REPA) 2016