INTERNAL AUDIT REPORT Pradhan Mantri Awaas Yojana Gramin
- Slides: 34
INTERNAL AUDIT REPORT Pradhan Mantri Awaas Yojana (Gramin) Previously known as Indira Awaas Yojana (IAY) Of the O/o Project Director (IAY) 2015 -16 to 2017 -18 and upto date Members of Audit Team Shri Satish Chand Jain (Auditor) Shri kaushalendra Jha (Trainee) Shri Vijay Kumar (Trainee)
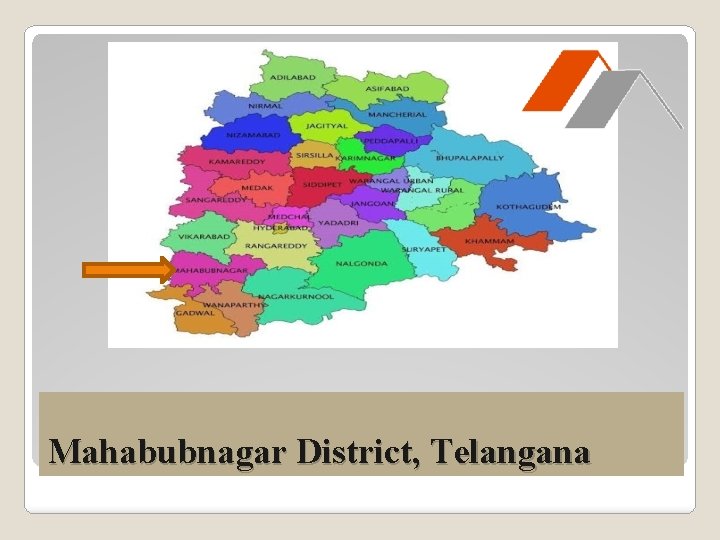
Mahabubnagar District, Telangana
Report on Internal Audit of PMAY-G in Mahabubnagar District, Telangana �A s of 31 st March 2016 Indira Awas Yojana (IAY) was going on with an aim to address h o u s i n g n e e d s o f t h e B e l o w P o v e r t y L i n e ( B P L ) households. With effect from 1 st April 2016 Government of India reconstructed IAY into Pradhan Mantri Awas Yojana-Gramin (PMAYG) . The objective of the programme was to provide a pucca house in rural areas with basic amenities to all houseless households and households living in kuchha and dilapidated h o u s e b y 2 0 2 2. T h e p r o g r a m m e w a s a l s o t e r m e d as Housing for all.
Difference between IAY & PMAY-G �The main changes in the programme were increase in size of house from 20 sqr mtr to 25 sqr mtr, including a dedicated area for hygienic cooking. Besides, there was provision of assistance of Rs 12, 000 for construction of toilet, 90/95 person days unskilled labour wage, facilities of drinking water , electricity, clean and efficient cooking fuel, treatment of solid and liquid waste etc. through convergence of Go. I’s other ongoing programmes/schemes etc. Viz. Swacha Bharat Mission (SBM), Mahatma Gandhi National Rural Employment Guarantee Scheme (MNREGS), Unnat Jyoti by Affordable LEDs and Appliances for all (UJALA) etc.
Financial Status �Financial assistance was also increased from Rs 70, 000 to Rs 1. 20 lakh in plain areas and further, if needed by the beneficiaries, facilitation of loan up to Rs 70, 000 from Financial Institutions were also provided. Now the beneficiaries were to be selected from the list of Socio Economic Caste Census (SECC) 2011 in place of BPL list. Physical and financial progress was required to be put by the States in online Management Information System platform named Awaas. Soft developed for monitoring of the programme. �Contd…. .
�In the first phase ( 2016 -19) , Go. I fixed target for providing 51 lakh houses in the country out of which for Telangana State it was 70, 674 for the year 201618 and communicated (June 2016) to Go. TS. After attending Empowered Committee (EC)’s meeting Go. I released (March 2017) Rs 142. 63 crore a part of 1 st installment and remaining amount of Rs 48. 12 crore in April 2017. Thus, Go. I released total Rs 190. 79 crore. Go. I released (July 2017) target for the year 2017 -18.
Objective of the Audit �a) To ensure compliance of rules/guideline relating to (PMAY) Scheme under Rural Development. �b) To safeguard the interests of Government and ensure value for money. �c) To test check the progress of the construction of dwelling units under the scheme. �d) To ensure that whether in scheme implementing Authority provided facility to the beneficiary by conversing other scheme/programme. �e) To ensure that the payment is being made to the beneficiaries of the scheme through their banks.
Scope of Audit a) b) c) d) e) To track the flow of funds from the Ministry to the Implementing Agency and from Implementing Agency to ultimate beneficiaries. Checking of the records such as Bank Statement and Cash Book & other records and Bank Passbook/statement of the beneficiary and implementing agency. To evaluate compliance with the provisions of various rules and regulations in incurring expenditure. Checking of the compiled accounts duly audited by the Chartered Accountant. To bring out recommendations for improving risk Management.
Audit Methodology: A. B. C. D. E. F. The audit was conducted on the basis of objectives, provisions of the scheme, flow of funds, specific rules and laws governing the execution of programme etc. along with compendium of operational guidelines and circulars. Entry conference was done with the Project Director on first day. Audit Team also visited the villages and checked the houses constructed/under construction under the scheme. Interaction with the beneficiaries of the Scheme to inquire about the payment of the installments of the houses. Exit conference was done with the Project Director where major audit findings were discussed with him. On the basis of gravity of irregularities, Para has been graded as high and moderate for low risk Para.
Scheme Implementation Procedure �The District Collector was the scheme Implementing Authority. He pointed a Nodal Officer for implementing the scheme in the district. �Actual execution was done by the Project Director of Telangana State Housing Corporation Ltd (TSHCL) at Mahboobnagar. �Commissioner, Weaker section and Housing department was State Nodal Authority who transferred funds to the MD, TSHCL, Hyderabad. �Payments under IAY to beneficiaries were made from State level by the MD , TSHCL, Hyderabad in beneficiaries’ bank accounts.
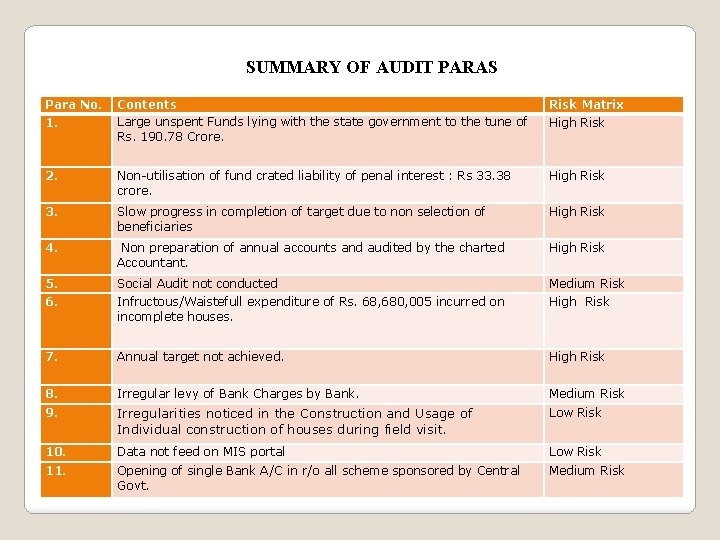
SUMMARY OF AUDIT PARAS Para No. Contents Large unspent Funds lying with the state government to the tune of Rs. 190. 78 Crore. Risk Matrix 2. Non-utilisation of fund crated liability of penal interest : Rs 33. 38 crore. High Risk 3. Slow progress in completion of target due to non selection of beneficiaries High Risk 4. Non preparation of annual accounts and audited by the charted Accountant. High Risk 5. Social Audit not conducted Medium Risk 6. Infructous/Waistefull expenditure of Rs. 68, 680, 005 incurred on incomplete houses. High Risk 7. Annual target not achieved. High Risk 8. Irregular levy of Bank Charges by Bank. Medium Risk 9. Irregularities noticed in the Construction and Usage of Individual construction of houses during field visit. Low Risk 10. Data not feed on MIS portal Low Risk 11. Opening of single Bank A/C in r/o all scheme sponsored by Central Govt. Medium Risk 1. High Risk
Huge unspent G 0 I Funds lying with the State Government: Rs. 190. 78 Crore. � As per financial rules, the fund received during the year is to be utilized during the same financial year and for the purpose for which it is received from the Government. � Scrutiny revealed that under PMAY –G State Government received central funds of Rs 190. 79 crore during 2016 -17 but State did not allot funds to districts. It is lying with the State Government, because the State had their own scheme named 2 BHK Housing Programme for BPL category of people and State wants relaxations in conditions from Go. I. As such District is unable to utilize the grants properly on the construction of houses in the rural areas in the PMAY-G scheme. � Recommendation : (1) State Govt. may look into the aspect and unutilized amount lying with them may be refund to the Central Govt. transferred/adjusted in future grants. (2) Withholding the grants received from Mo. RD, New Delhi and it’s not utilization fully and properly means failure of the purpose of the scheme for which grants were released.
Non deposit of penal interest due to non-utilization of fund : Rs 33. 38 crore. As per the guidelines of PMAY-G central fund released to State should be transferred to State Nodal Account within 15 days from date of receipt of fund failing which State have to deposit a penal interest at the rate of 12 percent . The state will provide a certificate regarding deposition of penal interest at the time of release of next installment of fund failing which the same will be deducted from its central share. � Audit observed that under PMAY-G programme 1 st installment of funds of Rs 190. 79 crore were released by Go. I to Go. TS by April 2017. Go. TS dovetailed PMAY-G with 2 BHK programme and grounded 20, 608 units out of Mo. RD’s target of 70, 674 for this State. • ◦ Contd…. .
� The Managing Director, Telangana State Housing Corporation Limited (TSHCL) did not receive funds from Go. TS to release in districts. TSHCL record did not reveal availability of central fund for housing for all. The district nodal office also stated non availability of Go. I fund of PMAYG under 2 BHK housing programme. Minutes (October 2018) of Empowered Committee (Mo. RD)’s meeting revealed that Go. TS had not returned the funds. There was decision of EC , Mo. RD to this effect but Communication to Go. TS to return of funds was also not on record. � Thus, funds keeping undisbursed to implementing agency attracts penal interest at the rate of 12 percent per annum from 15 th May 2017 to Oct 2018 amounting to Rs 33. 38 crore payable to Go. I. � Mo. RD should direct the Go. TS to refund the unutilized fund with interest.
Show Progress in completion of target due to non selection of Benefeciary As per para 9. 4 0 f PMAY-G guidelines of Go. I out of the total available funds and physical targets under the scheme in a district 60 percent may be utilized for SC/ST BPL households and 40 percent from non SC/ST BPL households. In the case of non- availability of beneficiaries in a particular category beneficiaries from other category may be selected subject to certification to this effect by the Zila Parishad/DRDA concerned. � Para 9, 7. 1 of the guidelines, further, states that moving from BPL list all the houseless and households living in zero, one or two room houses with katcha wall and katcha roof as per Socio Economic Cast Census (SECC) data may be selected. As per the guidelines of Go. TS for sanction of 2 BHk housing in the case of Urban area guidelines issued under Housing for all by Go. I shall be followed wherever funds are dovetailed with Housing for all scheme funds. The District Collector shall finalize list of beneficiaries. Go. TS prescribed (July 2015 ) that selected eligible beneficiaries from BPL list and shall be checked with the SECC data to ensure beneficiaries eligibility. � �Contd……
Government of Telangana State(Go. TS) sanctioned(September, 2015) 24, 000 2 BHK House for Urban area in the State at unit cost of Rs 5. 30 lakh for which Go. I subsidy from Housing for all at the rate of rupees one lakh per unit was decided to be given. Besides 36000 2 -BHK houses for Rural areas were sanctioned( September 2015) with subsidy of Rs 0. 35 lakh from IAY. In addition to that Go. TS sanctioned(GO Ms No 6 for 2016 -17)for construction of two lakh 2 BHK houses with State fund itself. Out of the total 2, 60, 000 houses in Maboobnagar construction for 1794 houses were started , of which only 20 were completed as of 15 October 2018 and total expenditure of Rs 49. 08 crore only could be spent. But selection of beneficiaries could not be held as of date. This resulted in non allotment of completed houses and slow progress of scheme. Though , selection of beneficiaries and grounding of houses was parallel activity. Nodal officer could not provide records pertaining to selection of beneficiaries. The District Collector should make a fresh list of common beneficiaries in list of BPL and SECC list as well on priority basis first from same locality irrespective of caste composition in allotment of house in the same locality . Thereafter adjust such other conmmon and eager beneficiaries from other possible locality . So that houses may not be remain un allotted and not unnecessary be remain un-allotted and expenditure become infructuous.
Non Preparation of Annual Accounts and audited by the Charted Accountant � As per PMAY-G guidelines (Para 9. 11. 4 ) the state will ensure that the accounts at all levels are audited by a charted accountant selected from a panel approved by the C&AG the audit should be completed before 31 August of the next financial year. � Nodal Officer of the scheme stated that no accounts are maintained at district level as all the payments are made through Nodal Bank Account opened and maintained at state level . Therefore , annual accounts of Mehabubnagar district. have not been prepared. � Non- preparation of annual accounts and non- issuing the utilization certificate by the implementing officer district wise status of project in financial and physical terms could not be visualized. � PMU in-charge Mehabubnagar may look into it and get the accounts prepared and audited by the Chartered Accountant empanelled by C&AG . The compliance may be reported to IAW( Mo. RD).
Social Audit not conducted � Social audit units setup by State government under MANREGA may be utilised to conduct of social audit of PMAY-G. Social audit is continues ongoing process involving public vigilance and verification of implementation of the scheme. Formal social audit is to be conducted in every Gram Panchayat. Nodal Officer stated that no social audit was conducted by the SHG/Competent Authority so far. Thus provisions of guidelines of IAY/PMAY-G was not complied. � As such the implementing authority was not aware with the actual status of the scheme implemented and/ or being implemented. � District Collector , Mahabubnagar may look into it and get the social audit done at least once in a year to fulfill the optimum achievement of the scheme.
In fructuous / Wasteful expenditure on incomplete houses : Rs. 6. 87 crore � In terms of para 9. 7. 2 clause of the IAY scheme guidelines construction of the house should be competed in the 12 months from the date of sanction. � Scrutiny revealed that during the 2015 -16 total 3749 houses under IAY were sanctioned. Out of that only 3442 houses were taken for construction but only 307 houses were completed, after incurring total expenditure of 9. 02 crore . The expenditure of Rs 2. 15 crore was on 307 completed houses at the rate of Rs 70, 000 per unit as prescribed in the guidelines, and Rs. 6. 87 crore on the rest of the houses which could not be completed so far after expiry of three years and provision of scheme was not complied. � Non completion of the houses has resulted into wasteful expenditure since these houses are not habitable for the villagers and the purpose of the government to provide houses to the rural homeless is defeated. � District Collector , Mahabubnagar may look into for earlier completion of the houses completed in order to desired benefit to the beneficiaries.
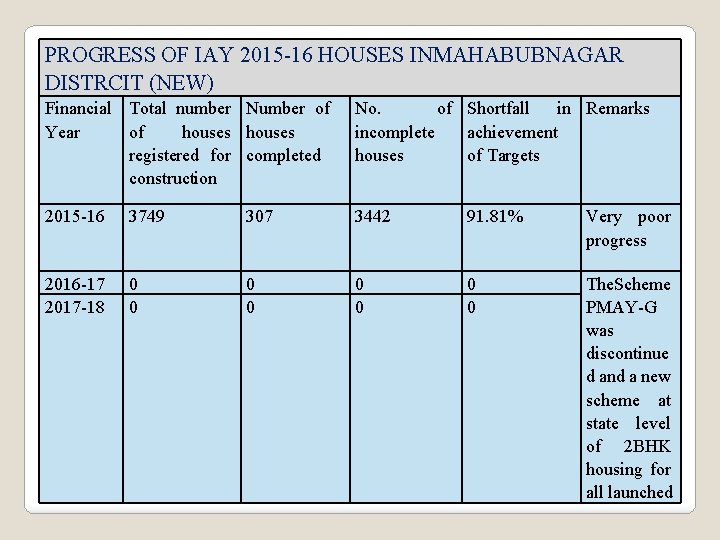
Little achievement of Annual target � In terms of Para 9. 5. 2 of PMAY-G the state should prepare annual action plan (AAP) for implementation of PMAY-G. The plan would inter alia, include the road-map for time bond completion of the houses sanctioned and ensure convergence with other schemes. The AAP should contain the district-wise plan highlighting the strategy that is to be adopted for saturating priority households. � On scrutiny of Records regarding targets and achievement it was noticed that against target for construction of total number of 3749 houses in district the achievement was construction of only 307 (8, 20 %) houses. . � Non achievement of the targets fixed by the annual action plan Committee is a serious laps in functioning of the scheme at District and Block level. � District Collector , Mahabubnagar may look into it and get the houses completed on priority for the beneficiary and make the scheme successful.
PROGRESS OF IAY 2015 -16 HOUSES INMAHABUBNAGAR DISTRCIT (NEW) Financial Total number Number of No. of Shortfall in Remarks Year of houses incomplete achievement registered for completed houses of Targets construction 2015 -16 3749 307 3442 91. 81% Very poor progress 2016 -17 2017 -18 0 0 0 0 The Scheme PMAY-G was discontinue d and a new scheme at state level of 2 BHK housing for all launched
Irregular levy of Bank Charges by Bank. � As per the policy, banks should not charge any commission on clearing/collection of Govt. transactions as per normal practice. � Telangana State Housing Corporation Ltd. is maintaining the Nodal bank Account for all the scheme in one account in SBH 62346389592 bearing account number for making benefit to the beneficiary. As per the annual accounts of 2015 -16 it was noticed that bank charges for Rs. 33159 were shown in their financial statement. � Levying of Bank charges on various Govt. transactions is against the policies and loss to the Govt. exchequer. � All such cases should be reviewed by MD, TSHCL, Hyderabad and matter may be taken up with banks for waiving Bank charges on all such transactions and to credit back the amount in the Government account. Action taken in this regard may be intimated to the IAW, M/o Rural Development.
Irregularities noticed in the Construction and Usage of Individual construction of houses during field visit. � As per Para 9. 7. 2 regarding construction of the house under the scheme IAY/PMAY-G the beneficiary selected for house will be registered after the proper verification of the bank accounts and other formalities. Distinct PMAY-G Id Code. House shall be registered jointly in the name of husband wife except in case of widow or single women of the family. The construction of the house should be completed within one year from the date of the issue of sanction. � The houses should be completed with the basic facilities of household toilets, electric connection, LPG connection, support of 90/95 person days of unskilled labour works access to save drinking water and management of solid liquid waste etc. �Contd……
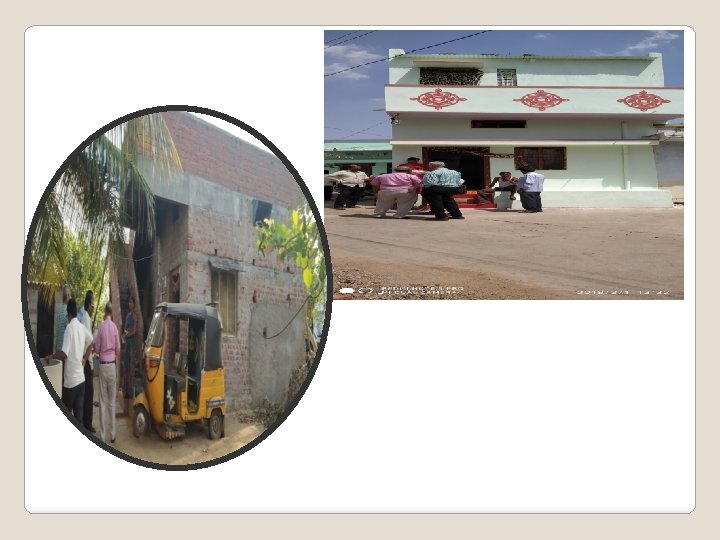
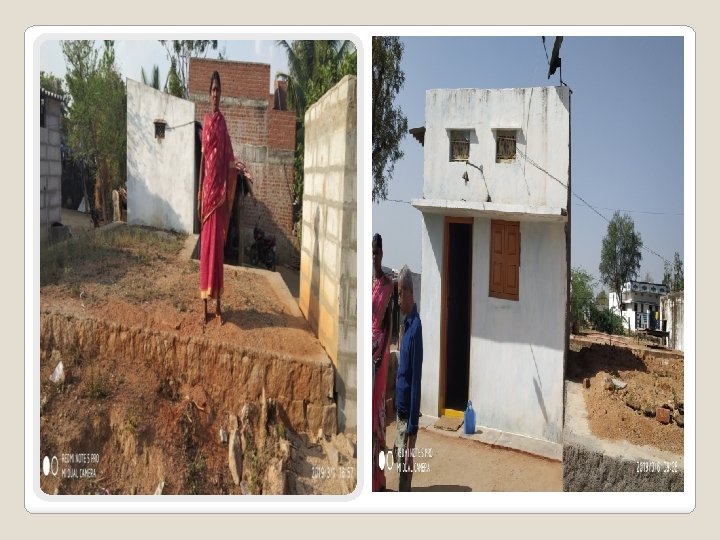
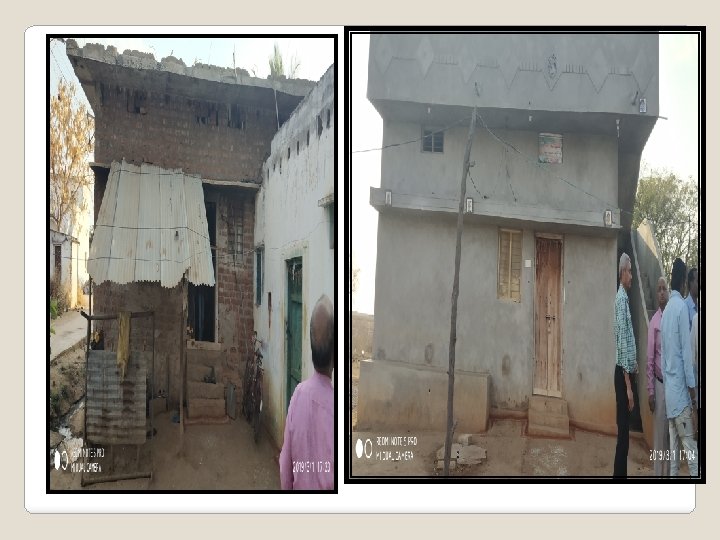
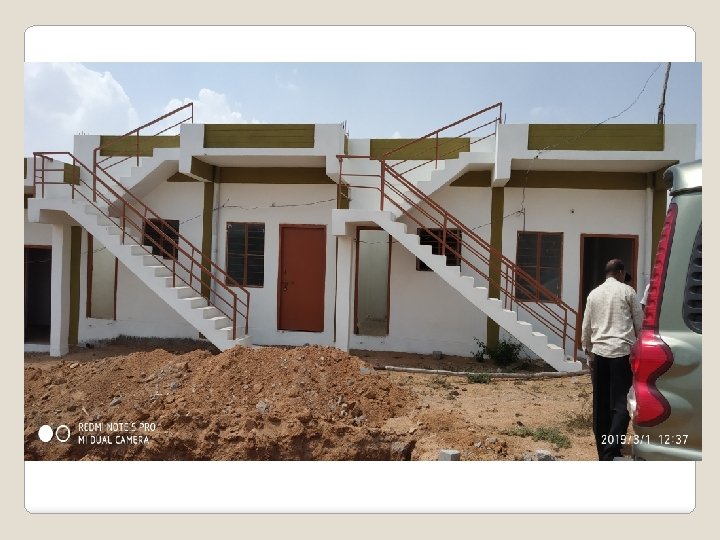
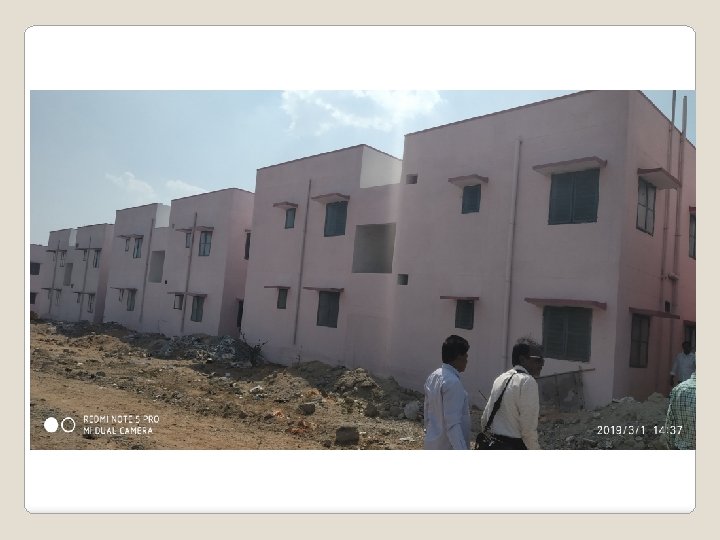
�The audit team visited four test checked villages in two blocks in order to see how the IAY/PMAY-G guidelines of the scheme were followed and also to find out whether the houses constructed under IAY/PMAY-G are put to use as envisaged in the scheme. �Audit observed that 6 out of 7 houses were incomplete. �Distt. Collector may make efforts to get the incomplete houses completed so that beneficiary can get the benefit of the scheme.
Data not feed in MIS reports � In term of para 9. 6. 4. of fund management of the scheme, the state shall maintain single savings account in a schedule commercial bank at state level reffered as SNA (State Nodal Account) and the account details shall also be registered in Aawas Soft and with PFMS. Further as per 9. 1. 4. EGovernance in PMAY-G the programme implementation and monitoring shall be executed though on end to end E-Governance model i. e. : The PMAY-G MIS-Awassoft &The PMAY-G Mobile application-Awassoft. � On scrutiny of MIS reports on Awassoft regarding the financial and physical target and achievement it was observed that no data was uploaded in the software as per the procedure laid down in the above said guidelines of the scheme. � Non Compliance codal provisions of IAY/PMAY-G. � In absence of requisit information the management may not be aware of the facts about the progress of the scheme for their future planning etc. Moreover the information may also not available in the public domain as a transparency of the scheme. � District Collector , Mahabubnagar may look into it and arrange to get it uploaded in the software every month so that the management may be apprised of the progress of the scheme.
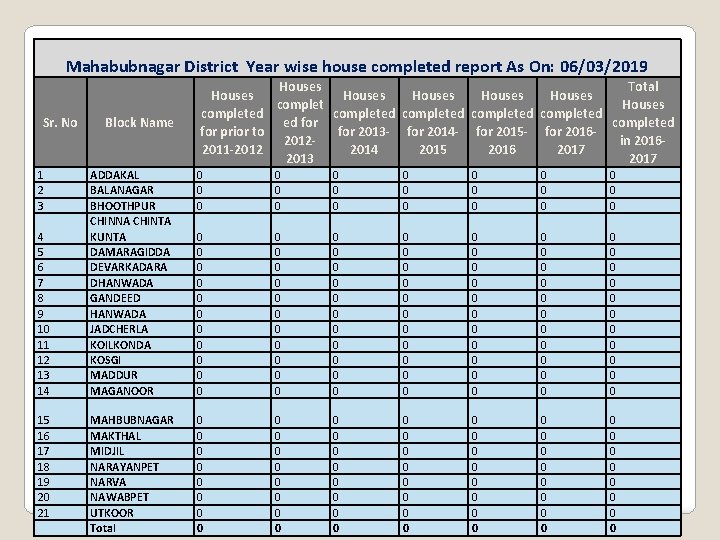
Mahabubnagar District Year wise house completed report As On: 06/03/2019 Sr. No 1 2 3 Block Name Houses Total Houses Houses completed completed ed for completed for prior to for 2013 - for 2014 - for 2015 - for 20162012 in 20162011 -2012 2014 2015 2016 2017 2013 2017 0 0 0 0 0 0 4 5 6 7 8 9 10 11 12 13 14 ADDAKAL BALANAGAR BHOOTHPUR CHINNA CHINTA KUNTA DAMARAGIDDA DEVARKADARA DHANWADA GANDEED HANWADA JADCHERLA KOILKONDA KOSGI MADDUR MAGANOOR 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 0 15 16 17 18 19 20 21 MAHBUBNAGAR MAKTHAL MIDJIL NARAYANPET NARVA NAWABPET UTKOOR Total 0 0 0 0 0 0 0 0 0 0 0 0 0 0
Non maintenance of separate bank accounts for each scheme of Go. I In term of para 9. 6. 4 regarding basic principle in fund management of the scheme, the funds under IAY/PMAY-G will be released by Mo. RD to State Govt. Accounts as per directions of M/o Finance. The State Govt. shall release the fund to Saving account in a scheduled commercial bank at state level and referred as SNA (State Nodal Accounts) and also registered in the Awasssoft and with PFMS. Hence for each scheme there should be a separate Bank account. � Scrutiny of Bank statement furnished by Telangana State Housing Corporation Ltd. revealed that there was a single bank account ( State Nodal Account) bearing number SBH-62346389592 maintained for all the schemes implemented in the state. Since all transaction made for all the schemes were entered in one account as a result of which it is difficult to have the scheme wise financial status. Though during 2014 -18 total Rs. 107. 25 c rore was received as interest. � It is violation of Govt. India orders/Guidelines of IAY/PMAY-G as stipulated above. Besides, interest earned on unspent balances of the different schemes during the financial year also could not be ascertained in order to assess the requirement of amount for next installment under a particular scheme. � The State Government should ensure maintenance of bank account as per guidelines of scheme. �
THANKS