Inflow uncertainty in a hydropower market Petter Vegard
- Slides: 16
Inflow uncertainty in a hydropower market Petter Vegard Hansen Statistics Norway
The aim of this paper is • to enhance our understanding of whether, and under what conditions, market power is affected by the stochastic of water inflow. • to pin point in more detail the impact of uncertainty.
The literature • Hydropower, certainty: – – Førsund (2007), Crampes and Moreaux (2001) Bushnell (2003) Mathiesen et al. (2003) • Hydropower, uncertainty: – Johnsen (2001) – Garcia et al. (2001) – Centeno et al. (2007) • Non-renewable resources – Kemp (1976) – Cairns (1990) • Prudence – Menegatti (2001)
Assumptions • • • Two period model with reservoir Short-term variable cost equal to zero Water inflow are stochastic No spilling Identical demand functions
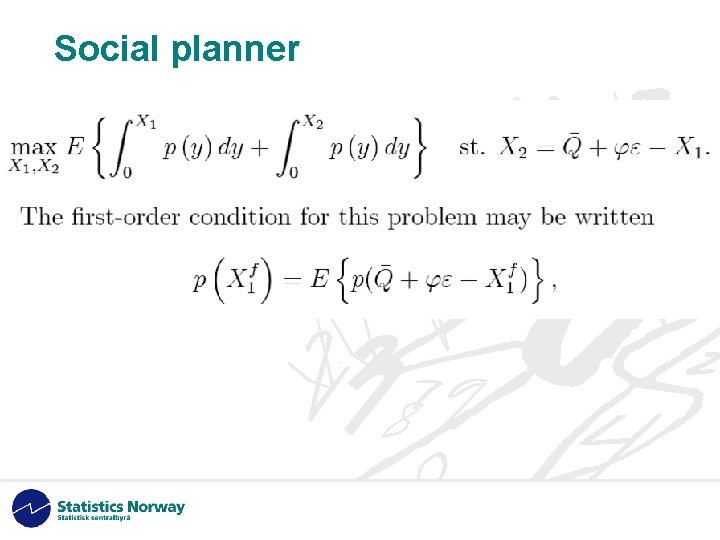
Social planner
Optimal resource allocation
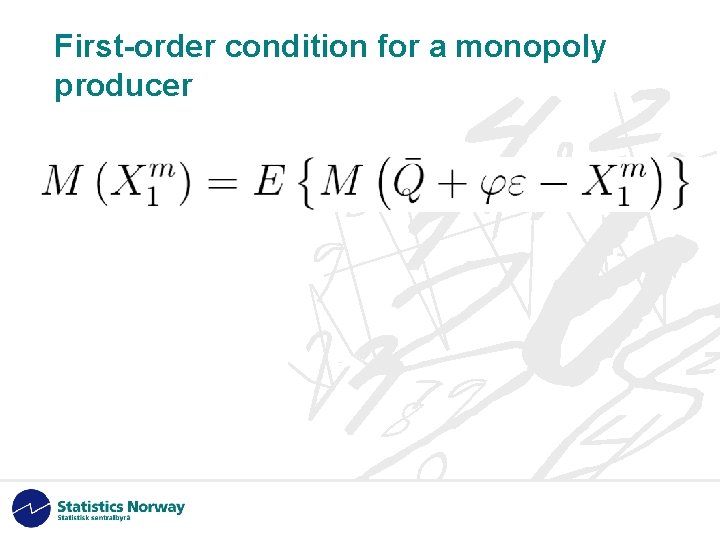
First-order condition for a monopoly producer
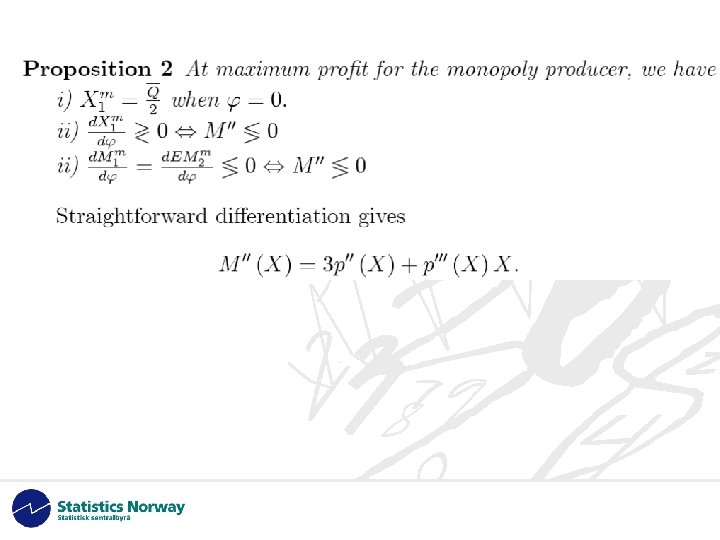
Illustration of monopoly producer
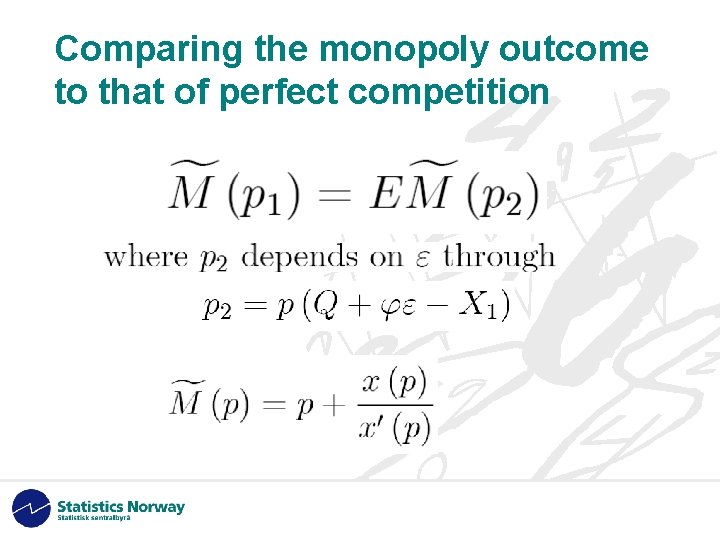
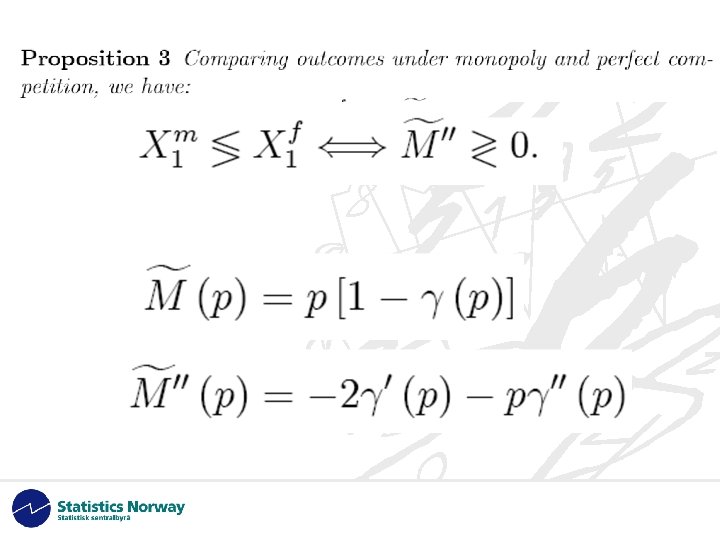
Comparing the monopoly outcome to that of perfect competition
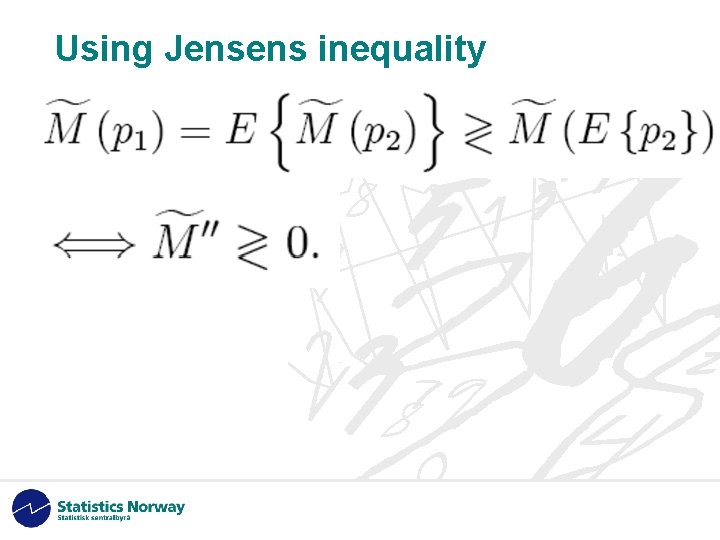
Using Jensens inequality
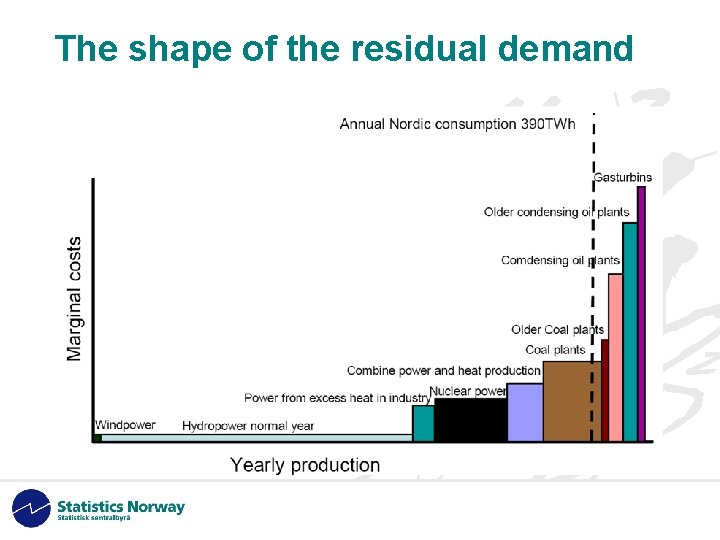
The shape of the residual demand
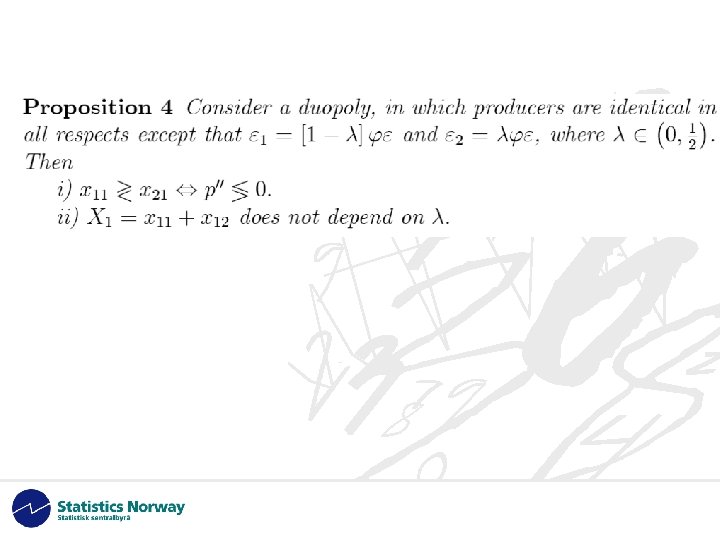
Conclusion • Allocation of water depends on the shape of the • • • demand Convex demand function – prudent consumers -implies saving Residual demand – Nordic market –implies saving Market power – prudent and increase in prudence Suggest that a monopolist does not save enough Duopoly market – the distribution of uncertainty among firms does not effect market output