CTC 475 Review Gradient Series Find P given
- Slides: 24
CTC 475 Review Gradient Series – Find P given G – Find A given G Rules: 1. P occurs two periods before the first G 2. n equals the number of cash flows + 1 3. First cash flow is G
CTC 475 Review Geometric Series – Find P given A 1, i and j – Find F given A 1, i and j Rules: 1. P occurs one period before A 1 2. F occurs the same time as the last cash flow 3. n equals the number of cash flows 4. First cash flow is A 1
CTC 475 Interest/equity, Changing interest rates and Effective interest rates
Objectives • Know how to determine equity (principal) and interest on borrowed money • Know how to recognize and solve problems when interest rates change • Know how to calculate effective interest rates
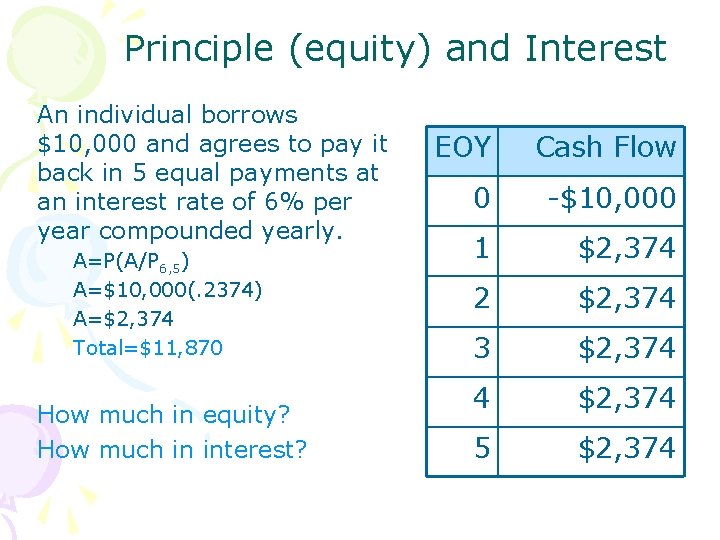
Principle (equity) and Interest An individual borrows $10, 000 and agrees to pay it back in 5 equal payments at an interest rate of 6% per year compounded yearly. A=P(A/P 6, 5) A=$10, 000(. 2374) A=$2, 374 Total=$11, 870 How much in equity? How much in interest? EOY Cash Flow 0 -$10, 000 1 $2, 374 2 $2, 374 3 $2, 374 4 $2, 374 5 $2, 374
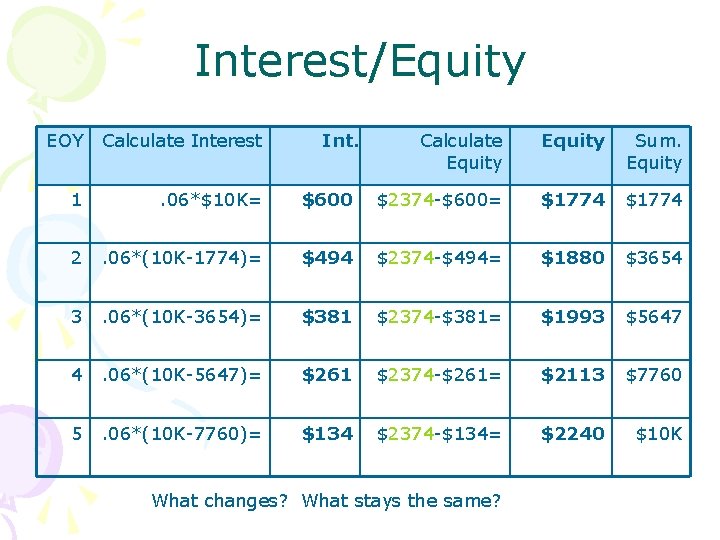
Interest/Equity EOY Calculate Interest 1 . 06*$10 K= 2 Int. Calculate Equity Sum. Equity $600 $2374 -$600= $1774 . 06*(10 K-1774)= $494 $2374 -$494= $1880 $3654 3 . 06*(10 K-3654)= $381 $2374 -$381= $1993 $5647 4 . 06*(10 K-5647)= $261 $2374 -$261= $2113 $7760 5 . 06*(10 K-7760)= $134 $2374 -$134= $2240 $10 K What changes? What stays the same?
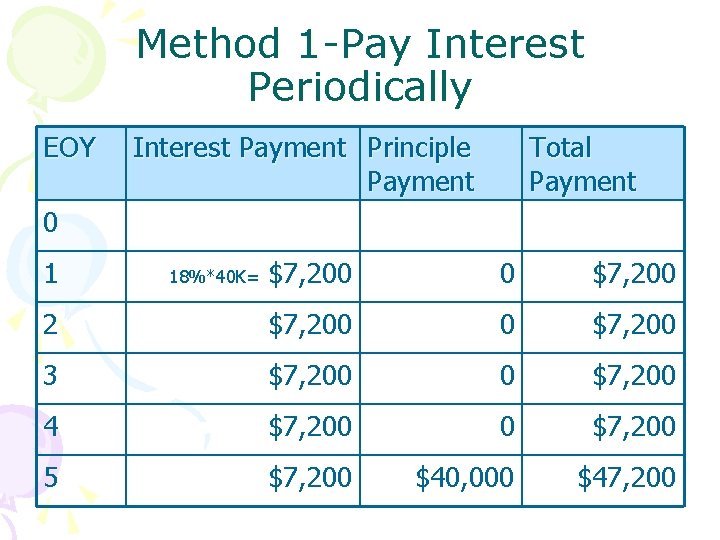
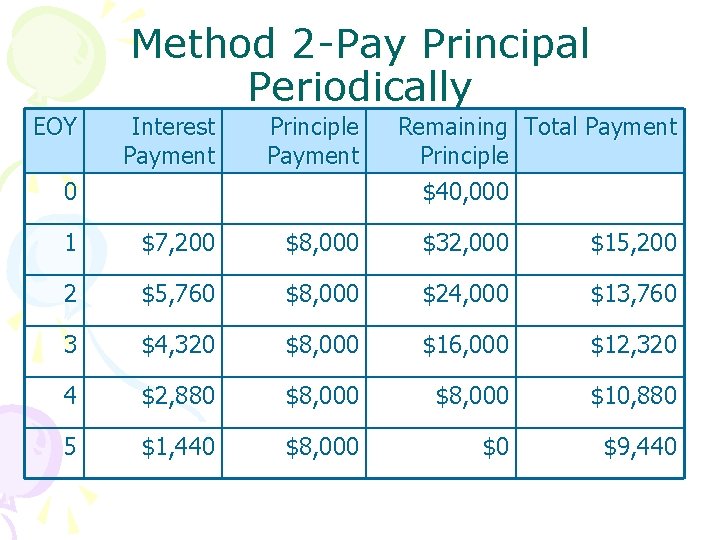
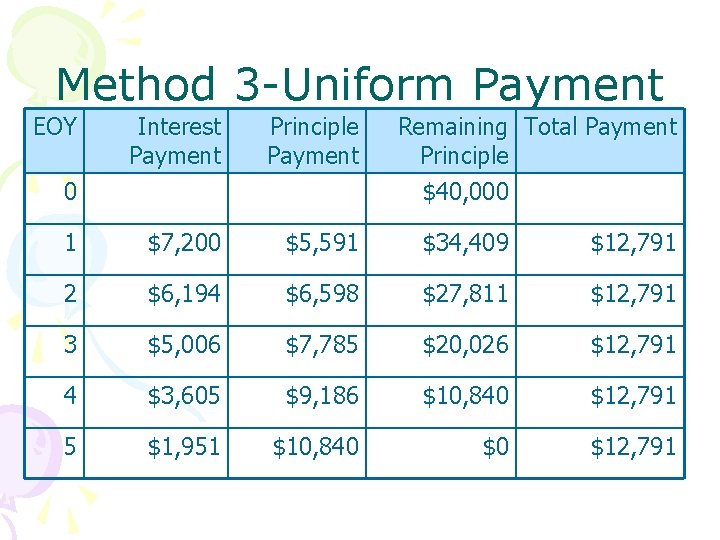
Methods for borrowing money 1. Periodic payment of interest with all principle being repaid at end of repayment period. 2. Uniform payment of principle. 3. Uniform payment (principle and interest). 4. Pay nothing until end of repayment period.
Example Problem Method 1 -4 • Borrowed amount = $40 K • 18% per year compounded annually • Repayment period-5 years
Method 1 -Pay Interest Periodically EOY Interest Payment Principle Payment Total Payment 0 1 $7, 200 0 $7, 200 2 $7, 200 0 $7, 200 3 $7, 200 0 $7, 200 4 $7, 200 0 $7, 200 5 $7, 200 $40, 000 $47, 200 18%*40 K=
Method 2 -Pay Principal Periodically EOY Interest Payment Principle Payment 1 $7, 200 $8, 000 $32, 000 $15, 200 2 $5, 760 $8, 000 $24, 000 $13, 760 3 $4, 320 $8, 000 $16, 000 $12, 320 4 $2, 880 $8, 000 $10, 880 5 $1, 440 $8, 000 $0 $9, 440 0 Remaining Total Payment Principle $40, 000
Method 3 -Uniform Payment EOY Interest Payment Principle Payment 1 $7, 200 $5, 591 $34, 409 $12, 791 2 $6, 194 $6, 598 $27, 811 $12, 791 3 $5, 006 $7, 785 $20, 026 $12, 791 4 $3, 605 $9, 186 $10, 840 $12, 791 5 $1, 951 $10, 840 $0 $12, 791 0 Remaining Total Payment Principle $40, 000
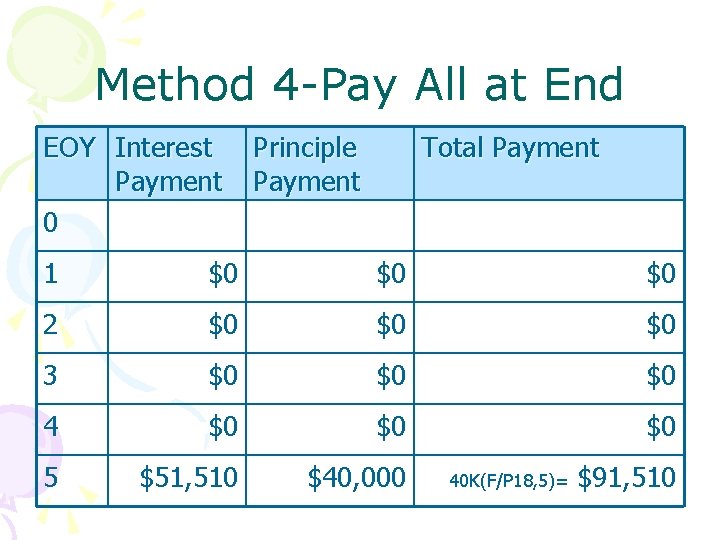
Method 4 -Pay All at End EOY Interest Payment 0 Principle Payment Total Payment 1 $0 $0 $0 2 $0 $0 $0 3 $0 $0 $0 4 $0 $0 $0 5 $51, 510 $40, 000 40 K(F/P 18, 5)= $91, 510
New Topic What if interest rates change?
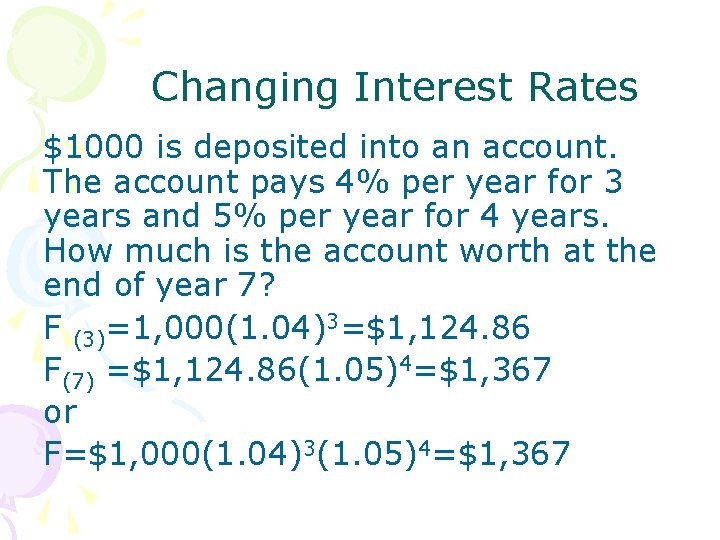
Changing Interest Rates $1000 is deposited into an account. The account pays 4% per year for 3 years and 5% per year for 4 years. How much is the account worth at the end of year 7? F (3)=1, 000(1. 04)3=$1, 124. 86 F(7) =$1, 124. 86(1. 05)4=$1, 367 or F=$1, 000(1. 04)3(1. 05)4=$1, 367
New Topics Multiple Compounding Nominal interest rate
Multiple Compounding Periods in a Year • 12% compounded quarterly is equivalent to 3% every 3 months • 12% is the nominal interest rate (r-mixed) • 3% is the interest rate per interest period (i-not mixed) • 3 months is the duration period • m is the number of compounding periods per year (m=4 quarters per year) • i = r/m =12%/4=3%
Remember Can only use tools if all periods match 3% per quarter compounded quarterly for 20 quarters
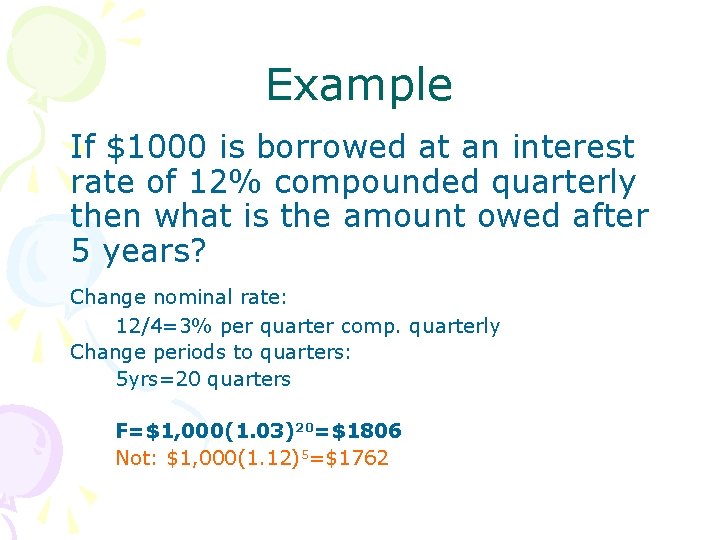
Example If $1000 is borrowed at an interest rate of 12% compounded quarterly then what is the amount owed after 5 years? Change nominal rate: 12/4=3% per quarter comp. quarterly Change periods to quarters: 5 yrs=20 quarters F=$1, 000(1. 03)20=$1806 Not: $1, 000(1. 12)5=$1762
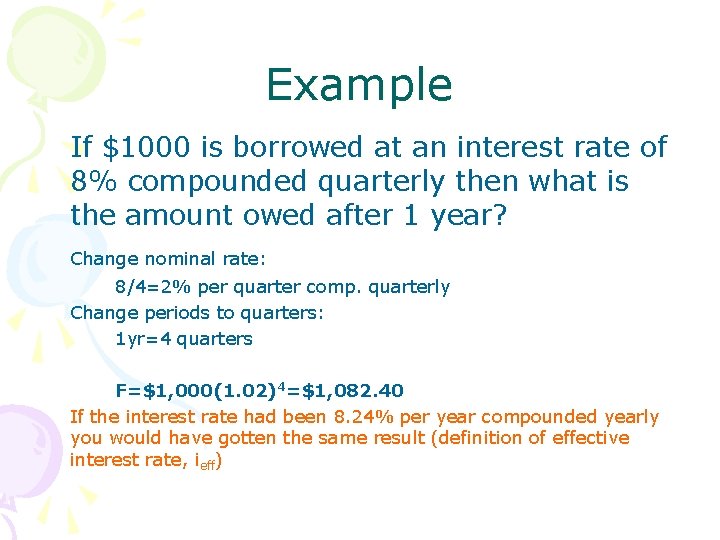
Example If $1000 is borrowed at an interest rate of 8% compounded quarterly then what is the amount owed after 1 year? Change nominal rate: 8/4=2% per quarter comp. quarterly Change periods to quarters: 1 yr=4 quarters F=$1, 000(1. 02)4=$1, 082. 40 If the interest rate had been 8. 24% per year compounded yearly you would have gotten the same result (definition of effective interest rate, ieff)
New Topic Effective (or equivalent) interest rate
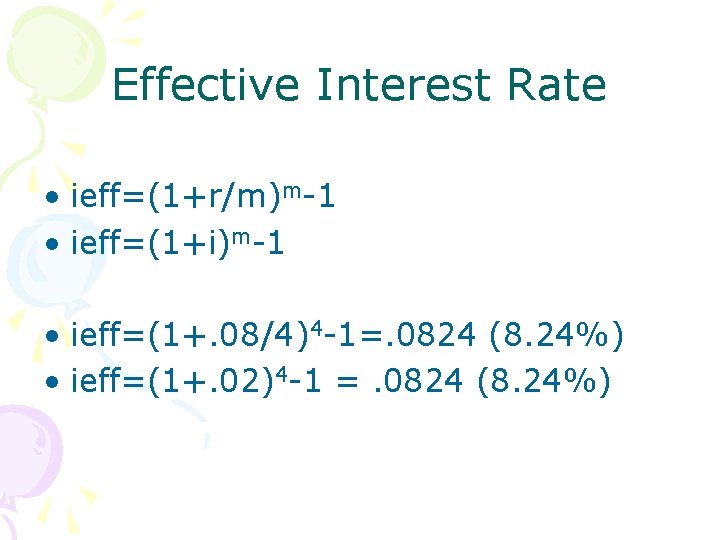
Effective Interest Rate • ieff=(1+r/m)m-1 • ieff=(1+i)m-1 • ieff=(1+. 08/4)4 -1=. 0824 (8. 24%) • ieff=(1+. 02)4 -1 =. 0824 (8. 24%)
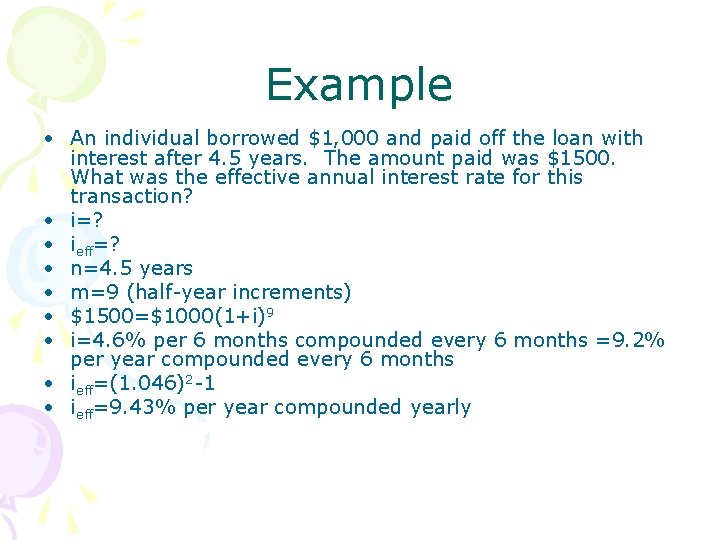
Example • An individual borrowed $1, 000 and paid off the loan with interest after 4. 5 years. The amount paid was $1500. What was the effective annual interest rate for this transaction? • i=? • ieff=? • n=4. 5 years • m=9 (half-year increments) • $1500=$1000(1+i)9 • i=4. 6% per 6 months compounded every 6 months =9. 2% per year compounded every 6 months • ieff=(1. 046)2 -1 • ieff=9. 43% per year compounded yearly
Next lecture • What to do when your cash flow interval doesn’t occur at the same time as the compound interval • 3% per yr compounded qtrly; cash flows are monthly
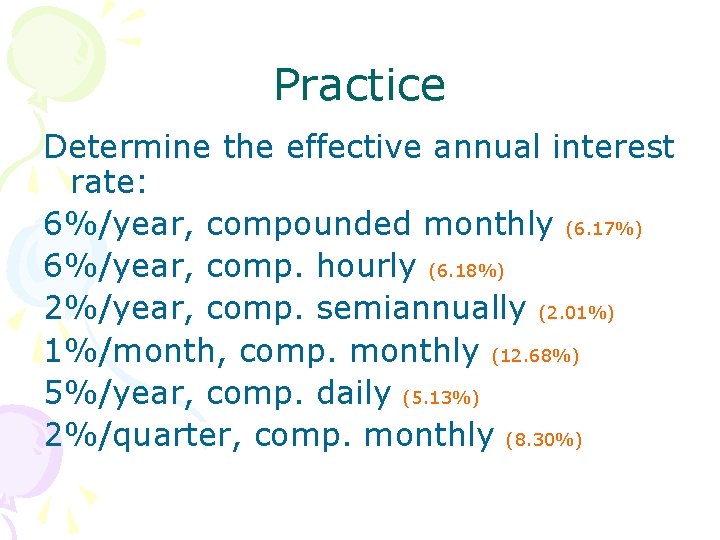
Practice Determine the effective annual interest rate: 6%/year, compounded monthly (6. 17%) 6%/year, comp. hourly (6. 18%) 2%/year, comp. semiannually (2. 01%) 1%/month, comp. monthly (12. 68%) 5%/year, comp. daily (5. 13%) 2%/quarter, comp. monthly (8. 30%)