Chapter M 10 Power Notes Cost Allocation and
- Slides: 29
Chapter M 10 Power Notes Cost Allocation and Activity-Based Costing Learning Objectives 1. Product Costing Allocation Methods 2. Single Plantwide Factory Overhead Rate Method 3. Multiple Production Department Factory Overhead Rate Method C 10 4. Activity-Based Costing Method 5. Activity-Based Costing for Selling and Administrative Expenses 6. Activity-Based Costing in Service Businesses C 23 - 1
Chapter M 10 Power Notes Cost Allocation and Activity-Based Costing Slide # Power Note Topics 3 10 20 Product Costing Allocation Methods Activity-Based Costing in Service Businesses Note: To select a topic, type the slide # and press Enter. C 23 - 2
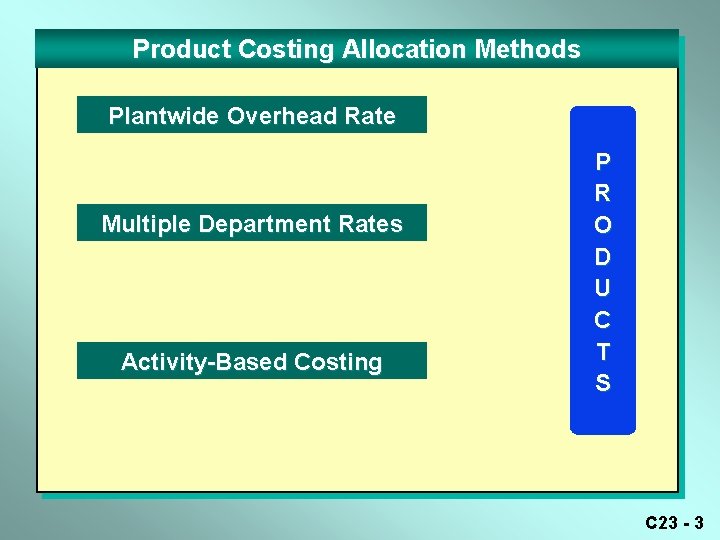
Product Costing Allocation Methods Plantwide Overhead Rate Multiple Department Rates Activity-Based Costing P R O D U C T S C 23 - 3
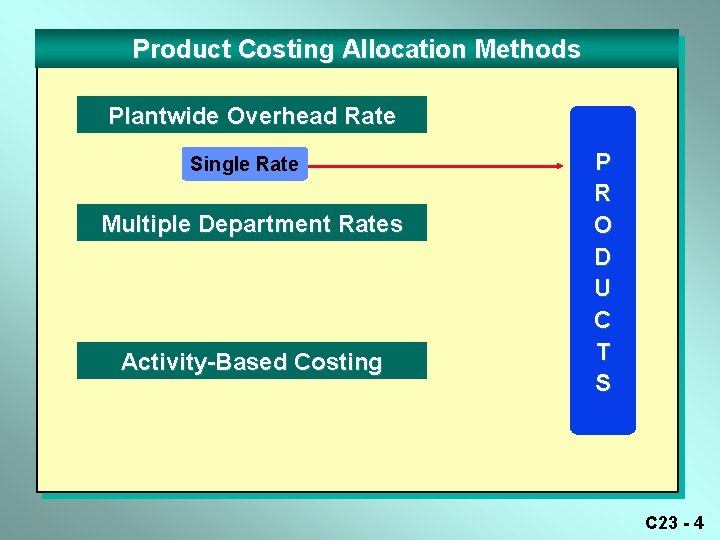
Product Costing Allocation Methods Plantwide Overhead Rate Single Rate Multiple Department Rates Activity-Based Costing P R O D U C T S C 23 - 4
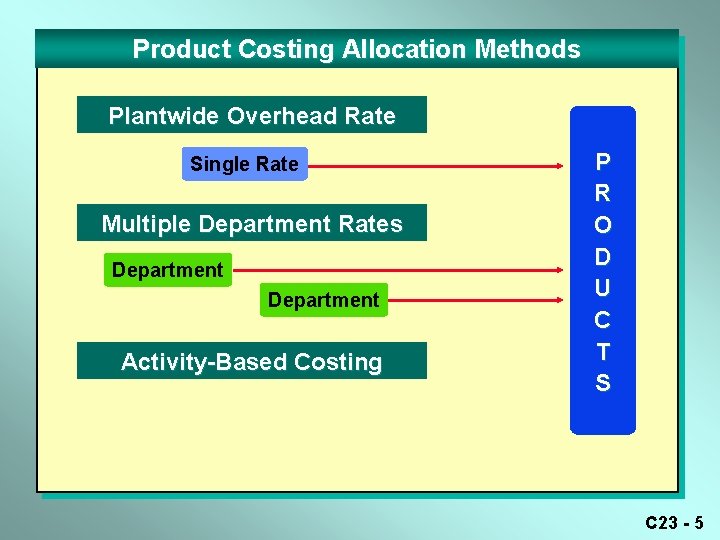
Product Costing Allocation Methods Plantwide Overhead Rate Single Rate Multiple Department Rates Department Activity-Based Costing P R O D U C T S C 23 - 5
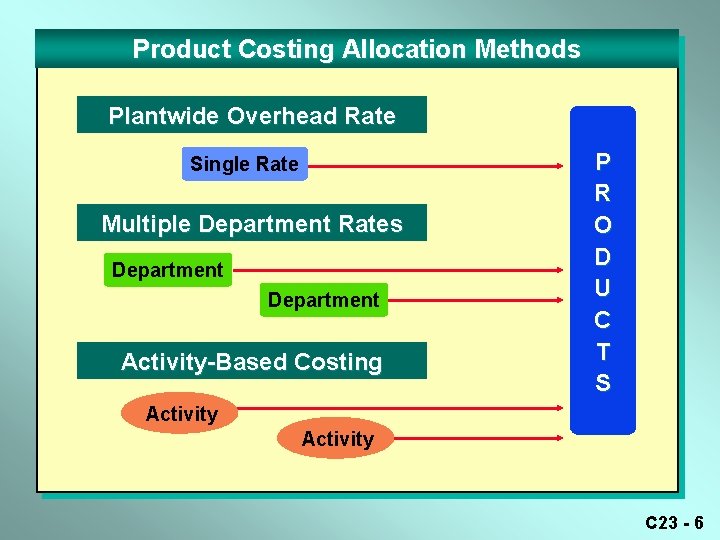
Product Costing Allocation Methods Plantwide Overhead Rate Single Rate Multiple Department Rates Department Activity-Based Costing P R O D U C T S Activity C 23 - 6
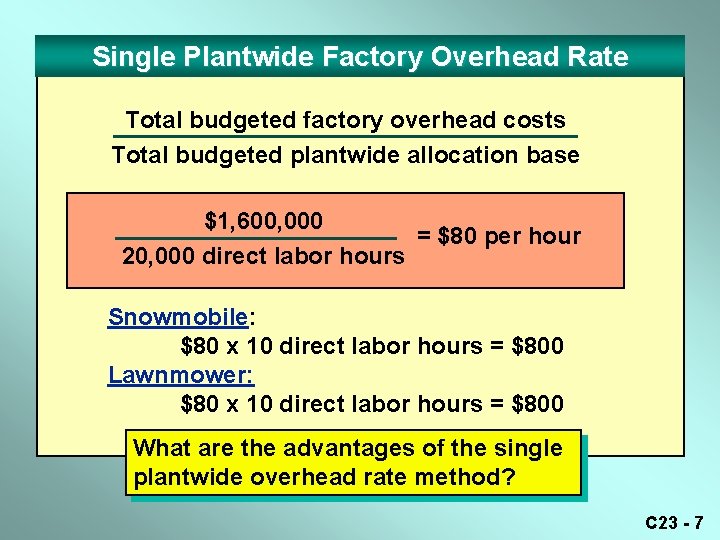
Single Plantwide Factory Overhead Rate Total budgeted factory overhead costs Total budgeted plantwide allocation base $1, 600, 000 = $80 per hour 20, 000 direct labor hours Snowmobile: $80 x 10 direct labor hours = $800 Lawnmower: $80 x 10 direct labor hours = $800 What are the advantages of the single plantwide overhead rate method? C 23 - 7
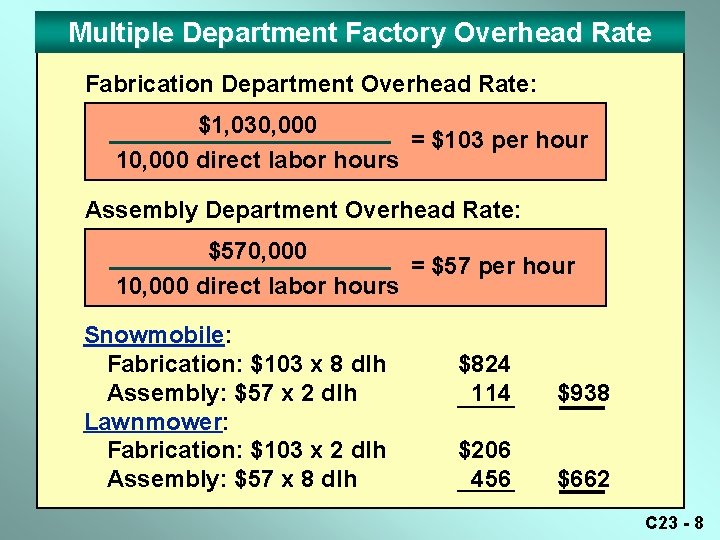
Multiple Department Factory Overhead Rate Fabrication Department Overhead Rate: $1, 030, 000 = $103 per hour 10, 000 direct labor hours Assembly Department Overhead Rate: $570, 000 = $57 per hour 10, 000 direct labor hours Snowmobile: Fabrication: $103 x 8 dlh Assembly: $57 x 2 dlh Lawnmower: Fabrication: $103 x 2 dlh Assembly: $57 x 8 dlh $824 114 $938 $206 456 $662 C 23 - 8
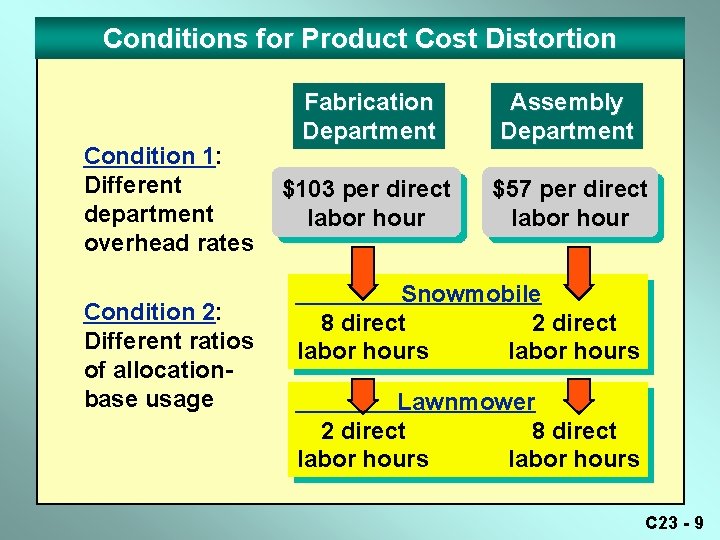
Conditions for Product Cost Distortion Condition 1: Different department overhead rates Condition 2: Different ratios of allocationbase usage Fabrication Department Assembly Department $103 per direct labor hour $57 per direct labor hour Snowmobile 8 direct 2 direct labor hours Lawnmower 2 direct 8 direct labor hours C 23 - 9
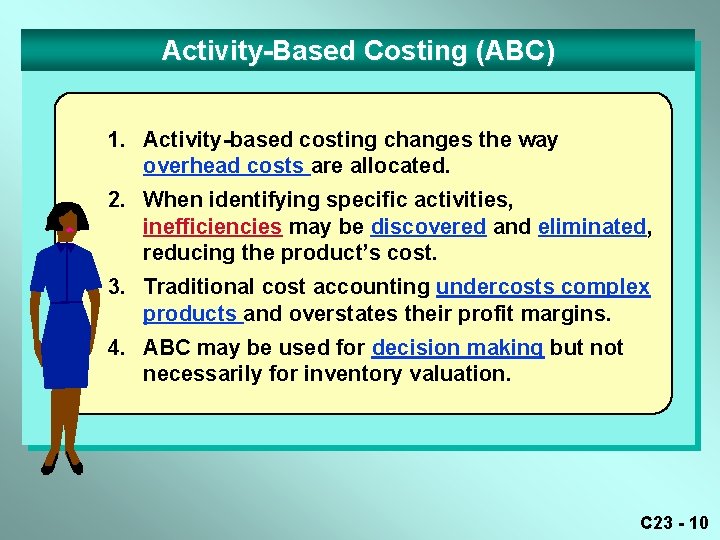
Activity-Based Costing (ABC) 1. Activity-based costing changes the way overhead costs are allocated. 2. When identifying specific activities, inefficiencies may be discovered and eliminated, reducing the product’s cost. 3. Traditional cost accounting undercosts complex products and overstates their profit margins. 4. ABC may be used for decision making but not necessarily for inventory valuation. C 23 - 10
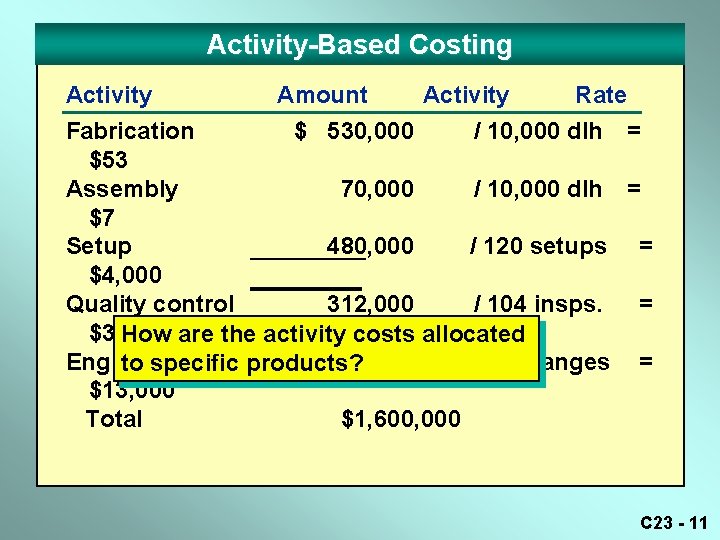
Activity-Based Costing Activity Amount Activity Rate Fabrication $ 530, 000 / 10, 000 dlh = $53 Assembly 70, 000 / 10, 000 dlh = $7 Setup 480, 000 / 120 setups = $4, 000 Quality control 312, 000 / 104 insps. = $3, 000 How are the activity costs allocated Engineering 208, 000 / 16 changes = to specific products? $13, 000 Total $1, 600, 000 C 23 - 11
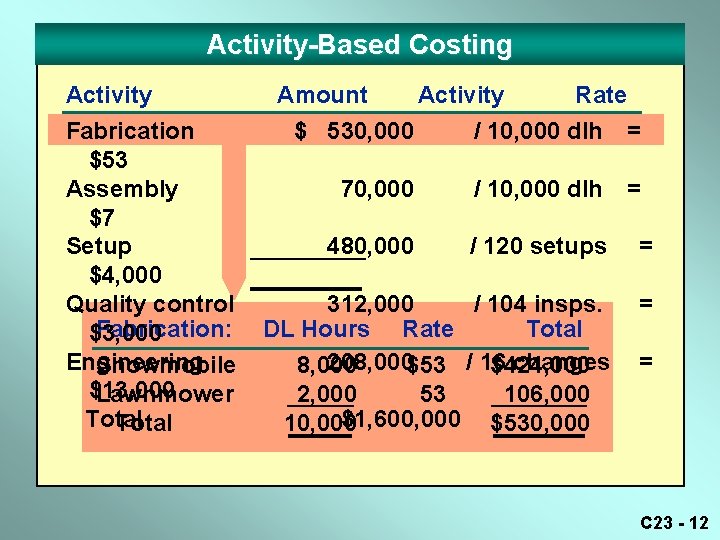
Activity-Based Costing Activity Fabrication $53 Assembly $7 Setup $4, 000 Quality control Fabrication: $3, 000 Engineering Snowmobile $13, 000 Lawnmower Total Amount Activity Rate $ 530, 000 / 10, 000 dlh = 70, 000 / 10, 000 dlh = 480, 000 / 120 setups = 312, 000 / 104 insps. DL Hours Rate Total 208, 000$53 / 16 changes 8, 000 $424, 000 2, 000 53 106, 000 $1, 600, 000 $530, 000 10, 000 = = C 23 - 12
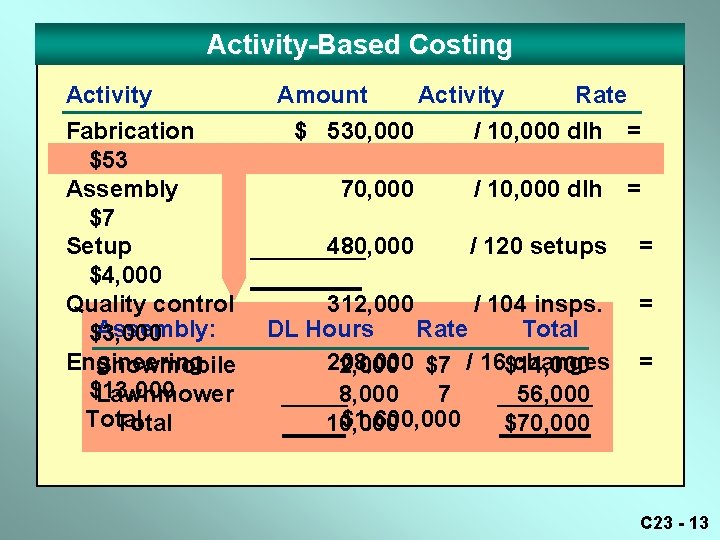
Activity-Based Costing Activity Fabrication $53 Assembly $7 Setup $4, 000 Quality control Assembly: $3, 000 Engineering Snowmobile $13, 000 Lawnmower Total Amount Activity Rate $ 530, 000 / 10, 000 dlh = 70, 000 / 10, 000 dlh = 480, 000 / 120 setups = 312, 000 / 104 insps. DL Hours Rate Total 208, 000 changes 2, 000 $7 / 16$14, 000 8, 000 7 56, 000 $1, 600, 000 10, 000 $70, 000 = = C 23 - 13
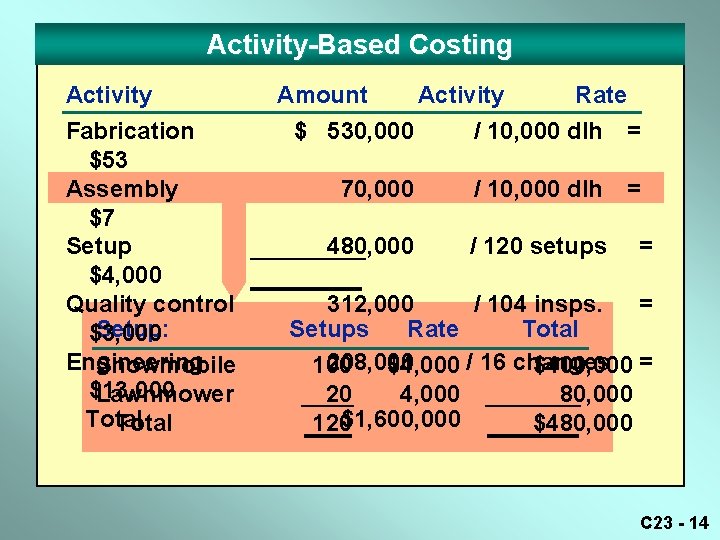
Activity-Based Costing Activity Fabrication $53 Assembly $7 Setup $4, 000 Quality control Setup: $3, 000 Engineering Snowmobile $13, 000 Lawnmower Total Amount Activity Rate $ 530, 000 / 10, 000 dlh = 70, 000 / 10, 000 dlh 480, 000 / 120 setups = = 312, 000 / 104 insps. = Setups Rate Total 208, 000 100 $4, 000 / 16 changes $400, 000 = 20 4, 000 80, 000 120$1, 600, 000 $480, 000 C 23 - 14
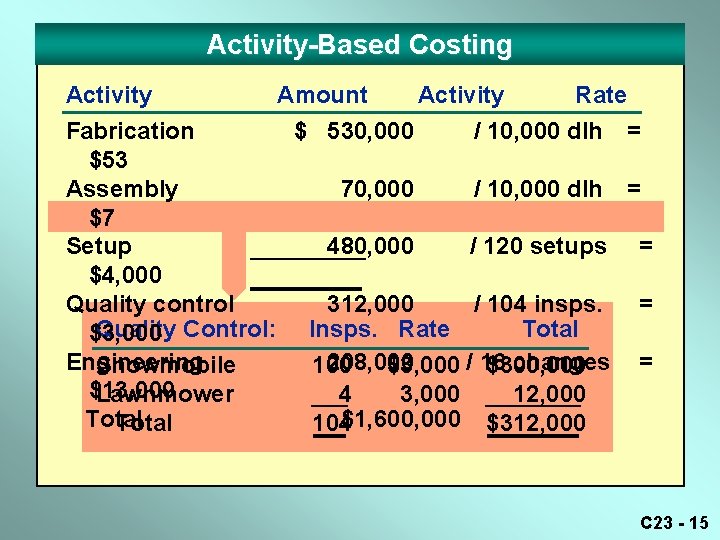
Activity-Based Costing Activity Amount Activity Rate Fabrication $ 530, 000 / 10, 000 dlh = $53 Assembly 70, 000 / 10, 000 dlh = $7 Setup 480, 000 / 120 setups = $4, 000 Quality control 312, 000 / 104 insps. = Quality Control: Insps. Rate Total $3, 000 Engineering 208, 000 changes = Snowmobile 100 $3, 000 / 16 $300, 000 $13, 000 Lawnmower 4 3, 000 12, 000 Total 104$1, 600, 000 $312, 000 C 23 - 15
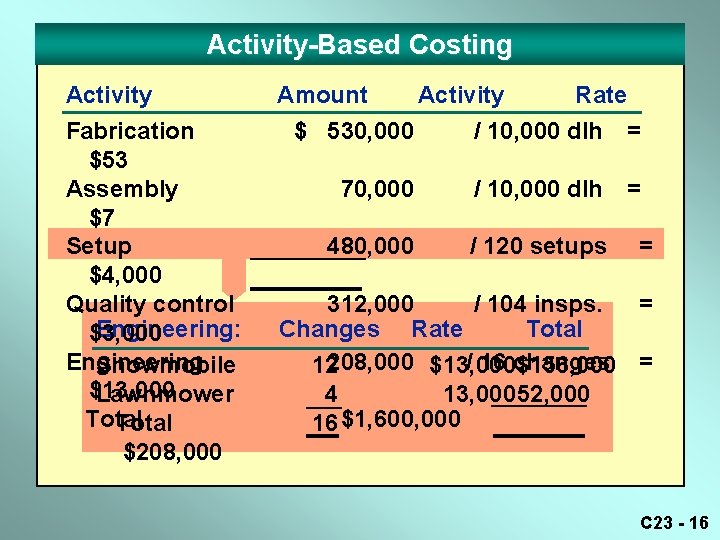
Activity-Based Costing Activity Fabrication $53 Assembly $7 Setup $4, 000 Quality control Engineering: $3, 000 Engineering Snowmobile $13, 000 Lawnmower Total $208, 000 Amount Activity Rate $ 530, 000 / 10, 000 dlh = 70, 000 / 10, 000 dlh 480, 000 / 120 setups = = 312, 000 / 104 insps. = Changes Rate Total / 16 changes = 12208, 000 $13, 000$156, 000 4 13, 00052, 000 16 $1, 600, 000 C 23 - 16
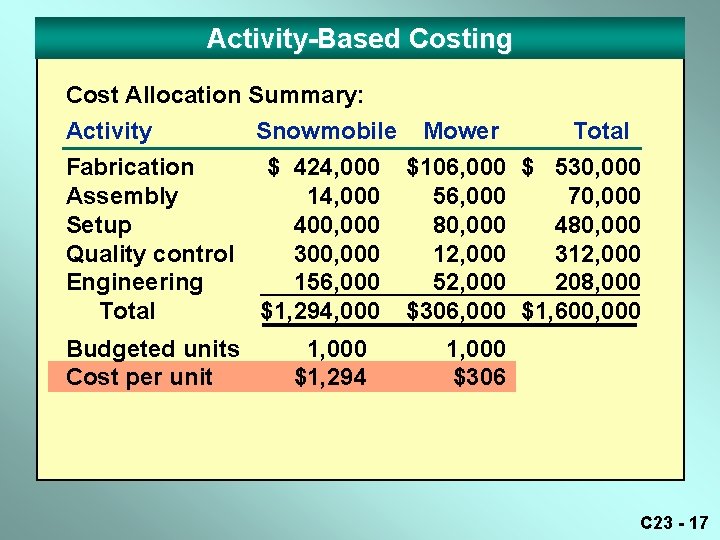
Activity-Based Costing Cost Allocation Summary: Activity Snowmobile Mower Total Fabrication $ 424, 000 $106, 000 $ 530, 000 Assembly 14, 000 56, 000 70, 000 Setup 400, 000 80, 000 480, 000 Quality control 300, 000 12, 000 312, 000 Engineering 156, 000 52, 000 208, 000 Total $1, 294, 000 $306, 000 $1, 600, 000 Budgeted units Cost per unit 1, 000 $1, 294 1, 000 $306 C 23 - 17
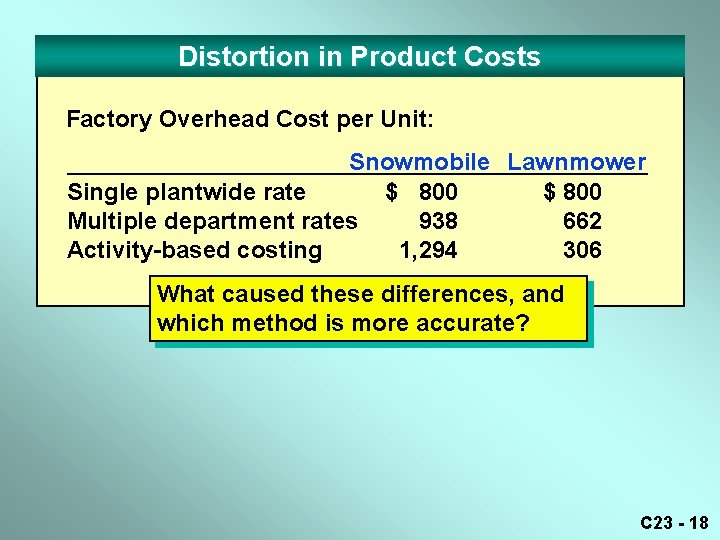
Distortion in Product Costs Factory Overhead Cost per Unit: Snowmobile Lawnmower Single plantwide rate $ 800 Multiple department rates 938 662 Activity-based costing 1, 294 306 What caused these differences, and which method is more accurate? C 23 - 18
Selling and Administrative Activities Selling and administrative activities may include: 1. 2. 3. 4. 5. 6. 7. 8. Post-sale technical support Order writing Promotional support Order entry Customer return processing Shipping document preparation Shipping and handling Field service C 23 - 19
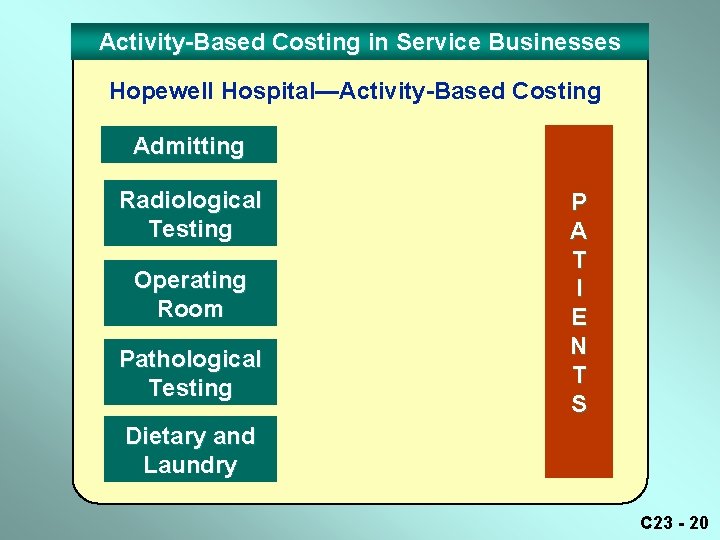
Activity-Based Costing in Service Businesses Hopewell Hospital—Activity-Based Costing Admitting Radiological Testing Operating Room Pathological Testing P A T I E N T S Dietary and Laundry C 23 - 20
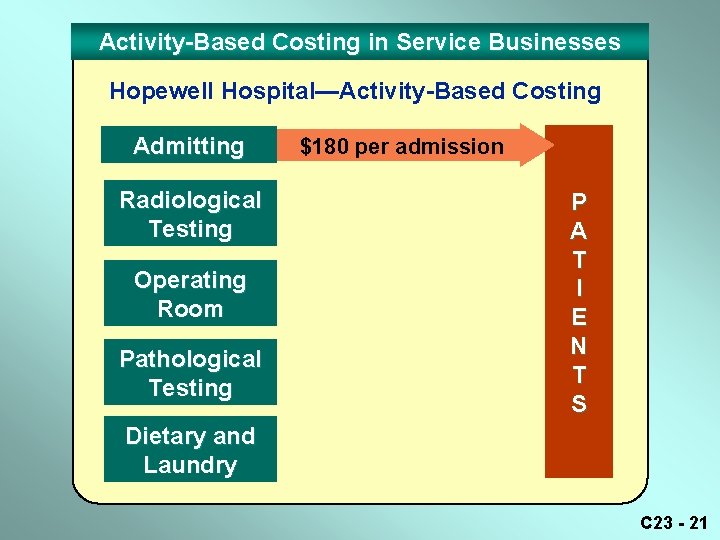
Activity-Based Costing in Service Businesses Hopewell Hospital—Activity-Based Costing Admitting Radiological Testing Operating Room Pathological Testing $180 per admission P A T I E N T S Dietary and Laundry C 23 - 21
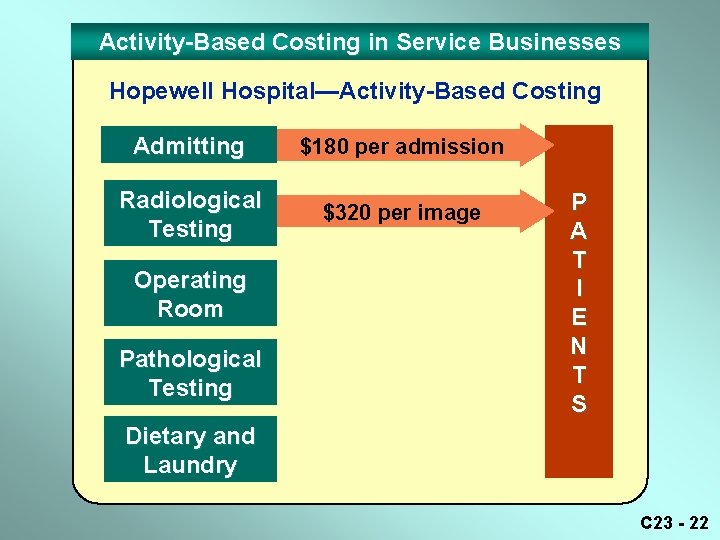
Activity-Based Costing in Service Businesses Hopewell Hospital—Activity-Based Costing Admitting $180 per admission Radiological Testing $320 per image Operating Room Pathological Testing P A T I E N T S Dietary and Laundry C 23 - 22
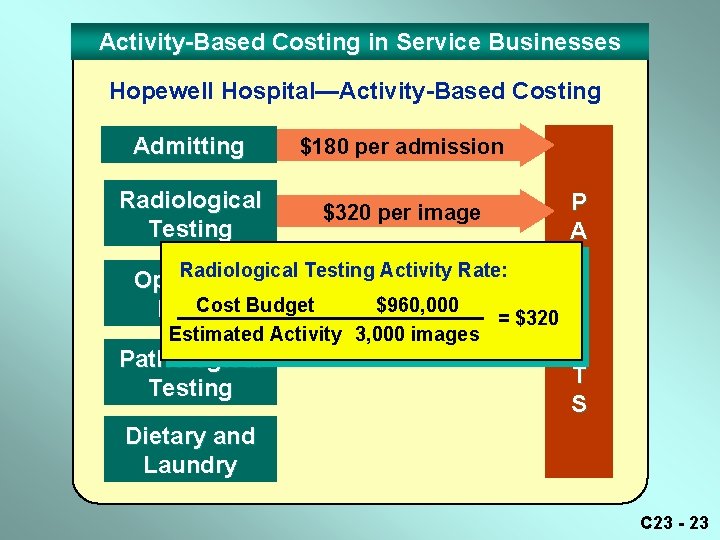
Activity-Based Costing in Service Businesses Hopewell Hospital—Activity-Based Costing Admitting $180 per admission Radiological Testing $320 per image P A T Radiological Testing Activity Rate: Operating I Cost Budget $960, 000 Room = $320 E Estimated Activity 3, 000 images N Pathological T Testing S Dietary and Laundry C 23 - 23
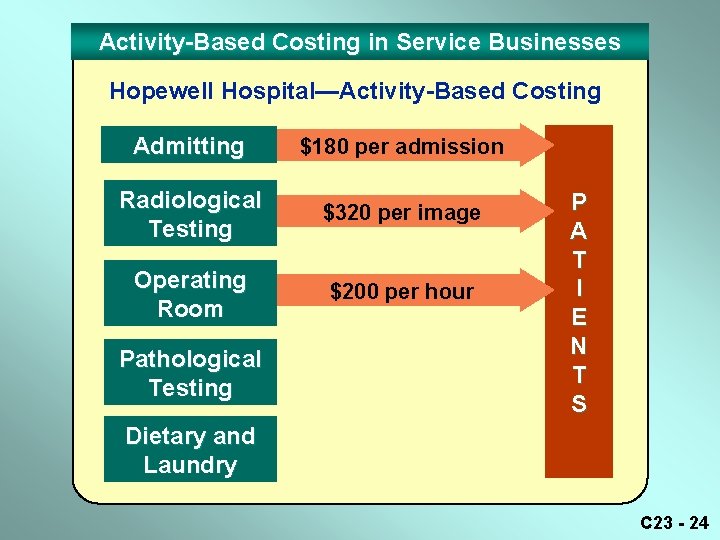
Activity-Based Costing in Service Businesses Hopewell Hospital—Activity-Based Costing Admitting $180 per admission Radiological Testing $320 per image Operating Room $200 per hour Pathological Testing P A T I E N T S Dietary and Laundry C 23 - 24
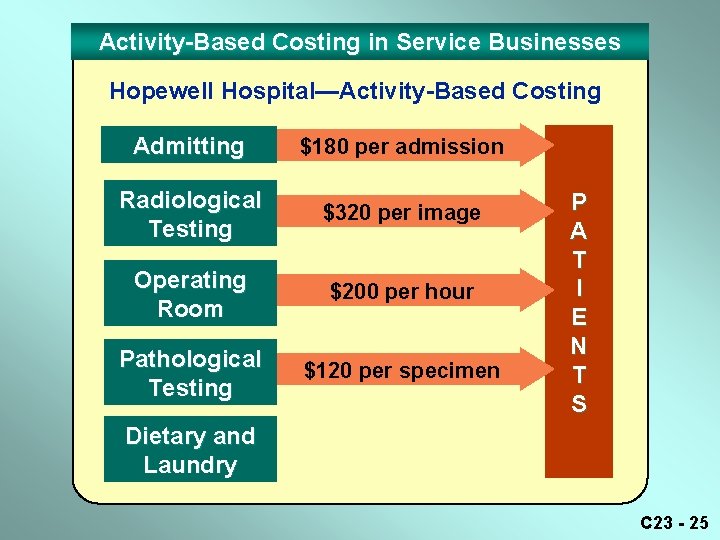
Activity-Based Costing in Service Businesses Hopewell Hospital—Activity-Based Costing Admitting $180 per admission Radiological Testing $320 per image Operating Room $200 per hour Pathological Testing $120 per specimen P A T I E N T S Dietary and Laundry C 23 - 25
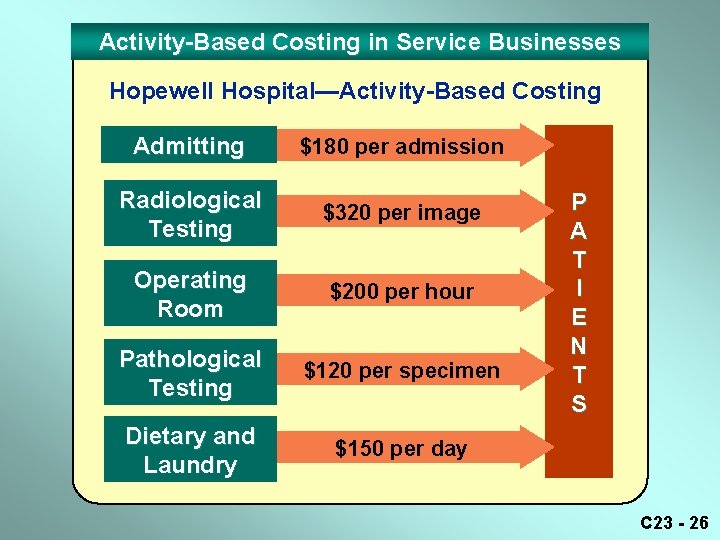
Activity-Based Costing in Service Businesses Hopewell Hospital—Activity-Based Costing Admitting $180 per admission Radiological Testing $320 per image Operating Room $200 per hour Pathological Testing $120 per specimen Dietary and Laundry $150 per day P A T I E N T S C 23 - 26
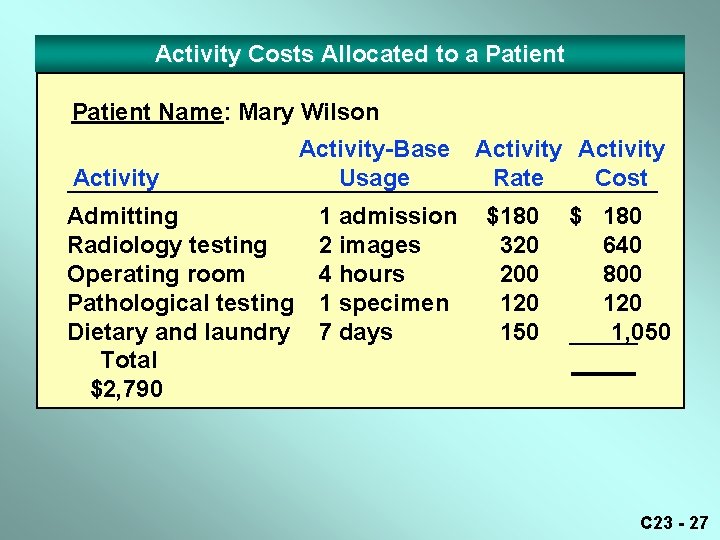
Activity Costs Allocated to a Patient Name: Mary Wilson Activity Admitting Radiology testing Operating room Pathological testing Dietary and laundry Total $2, 790 Activity-Base Usage 1 admission 2 images 4 hours 1 specimen 7 days Activity Rate Cost $180 320 200 120 150 $ 180 640 800 120 1, 050 C 23 - 27
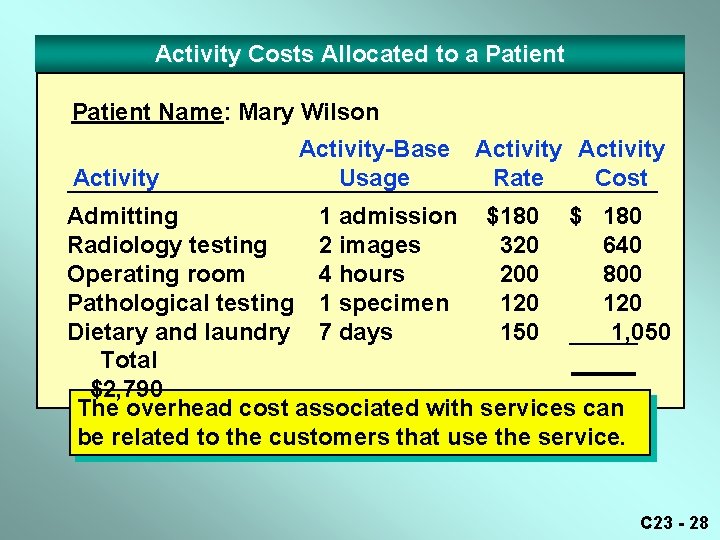
Activity Costs Allocated to a Patient Name: Mary Wilson Activity-Base Usage Activity Rate Cost Admitting 1 admission $180 $ 180 Radiology testing 2 images 320 640 Operating room 4 hours 200 800 Pathological testing 1 specimen 120 Dietary and laundry 7 days 150 1, 050 Total $2, 790 The overhead cost associated with services can be related to the customers that use the service. C 23 - 28
Chapter M 10 Power Notes Cost Allocation and Activity-Based Costing This is the last slide in Chapter M 10. Note: To see the first slide, type 1 and press Enter. C 23 - 29