Chapter 18 FOUNDATIONS OF CONTROL 2003 Pearson Education
- Slides: 29
Chapter 18 FOUNDATIONS OF CONTROL © 2003 Pearson Education Canada Inc. 18. 1
LEARNING OBJECTIVES • You should be able to: – Define control – Describe three approaches to control – Explain why control is important – Describe the control process – Distinguish among the three types of control – Describe the qualities of an effective control system © 2003 Pearson Education Canada Inc. 18. 2
LEARNING OBJECTIVES (continued) • You should be able to: – Discuss the contingency factors that influence the design of an organization’s control system – Identify how controls need to be adjusted for cultural differences – Explain how three contemporary issues workplace privacy, employee theft, and workplace violence - affect control © 2003 Pearson Education Canada Inc. 18. 3
WHAT IS CONTROL? • Control – – The process of monitoring activities to ensure that they are being accomplished as planned and of correcting significant deviations Control systems are judged in terms of how well they facilitate goal achievement • Three basic approaches to control – Market control - emphasizes the use of external market mechanisms to establish standards of performance © 2003 Pearson Education Canada Inc. 18. 4
WHAT IS CONTROL? (continued) • Three basic approaches to control (continued) – – Bureaucratic control - emphasizes organizational authority and relies on administrative rules and procedures Clan control - behaviour regulated by shared values, traditions, and other aspects of organizational culture © 2003 Pearson Education Canada Inc. 18. 5
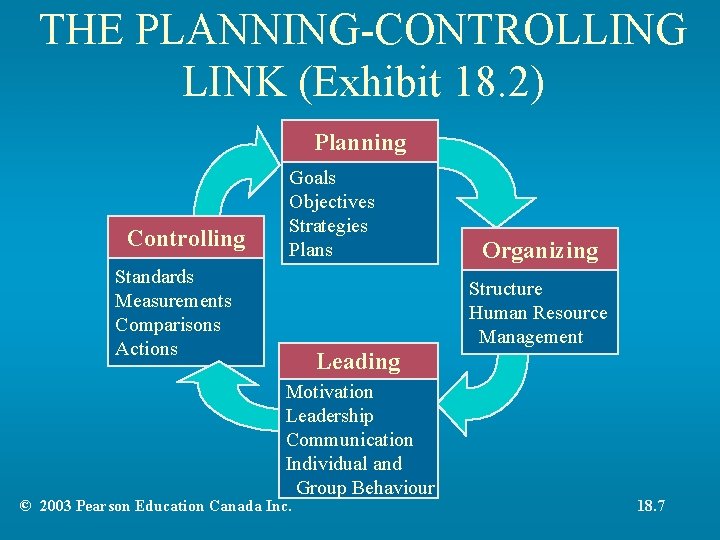
WHY IS CONTROL IMPORTANT? • Control is the Final Link in the Management Process – – Provides the critical link back to planning Only way managers know whether organizational goals are being met • Permits delegation of authority – – Fear that employees will do something wrong for which the manager will be held responsible Provides information and feedback on employee performance © 2003 Pearson Education Canada Inc. 18. 6
THE PLANNING-CONTROLLING LINK (Exhibit 18. 2) Planning Controlling Goals Objectives Strategies Plans Standards Measurements Comparisons Actions Organizing Structure Human Resource Management Leading Motivation Leadership Communication Individual and Group Behaviour © 2003 Pearson Education Canada Inc. 18. 7
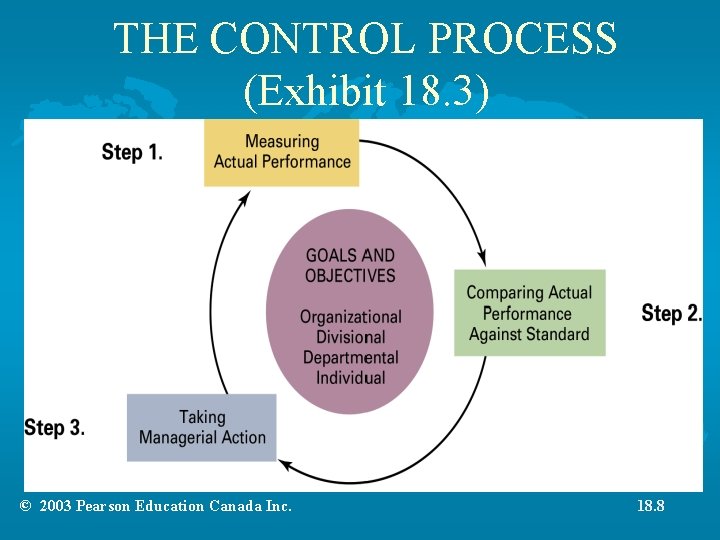
THE CONTROL PROCESS (Exhibit 18. 3) © 2003 Pearson Education Canada Inc. 18. 8
THE CONTROL PROCESS • Controlling is a three-step process • Assumes that performance standards already exist – specific goals are created in the planning process • Measuring – How We Measure • personal observation - permits intensive coverage – Management By Walking Around (MBWA) – drawbacks - subject to personal biases © 2003 Pearson Education Canada Inc. 18. 9
THE CONTROL PROCESS (continued) • Measuring (continued) – How We Measure (continued) • statistical reports - numerical data are easy to visualize and effective for showing relationships – drawbacks - not all operations can be measured • oral reports - includes meetings, telephone calls – may be best way to control work in a virtual environment – technology permits creation of written record from oral report – drawbacks - filtering of information © 2003 Pearson Education Canada Inc. 18. 10
THE CONTROL PROCESS (continued) • Measuring (continued) – How We Measure (continued) – written reports - often more comprehensive and concise than oral reports • usually easy to file and retrieve – comprehensive control efforts should use all four approaches © 2003 Pearson Education Canada Inc. 18. 11
THE CONTROL PROCESS (continued) • Measuring (continued) – What We Measure • what we measure more critical than how we measure • control criteria applicable to any management situation: – employee satisfaction, absenteeism, and turnover – keeping costs within budgets – – Control system needs to recognize the diversity of activities Some activities difficult to measure in quantifiable terms © 2003 Pearson Education Canada Inc. 18. 12
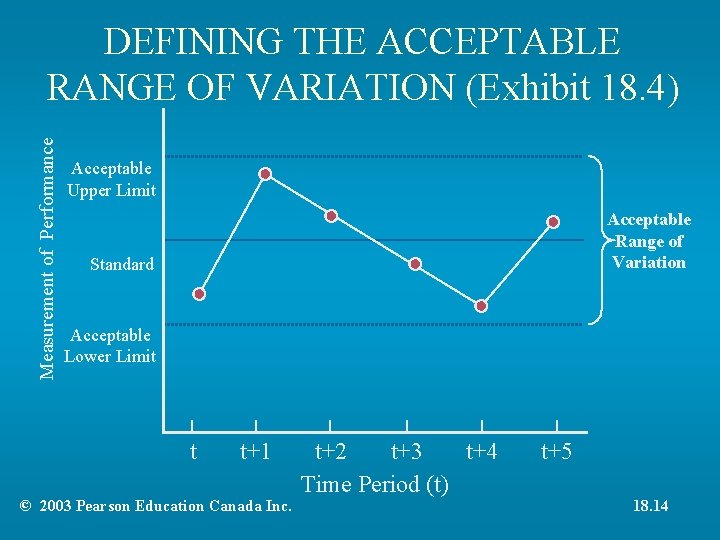
THE CONTROL PROCESS (continued) • Comparing – Determines the degree of variation between actual performance and standard – Acceptable range of variation - deviations that exceed this range become significant © 2003 Pearson Education Canada Inc. 18. 13
Measurement of Performance DEFINING THE ACCEPTABLE RANGE OF VARIATION (Exhibit 18. 4) Acceptable Upper Limit Acceptable Range of Variation Standard Acceptable Lower Limit t t+1 © 2003 Pearson Education Canada Inc. t+2 t+3 t+4 Time Period (t) t+5 18. 14
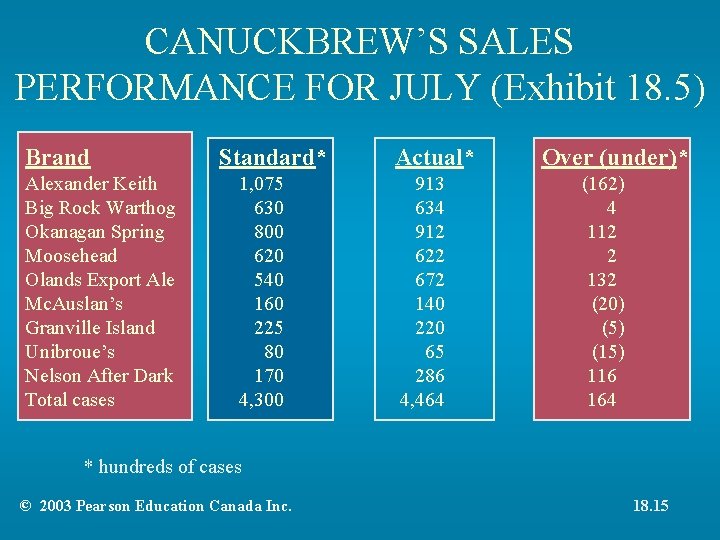
CANUCKBREW’S SALES PERFORMANCE FOR JULY (Exhibit 18. 5) Brand Alexander Keith Big Rock Warthog Okanagan Spring Moosehead Olands Export Ale Mc. Auslan’s Granville Island Unibroue’s Nelson After Dark Total cases Standard* 1, 075 630 800 620 540 160 225 80 170 4, 300 Actual* 913 634 912 622 672 140 220 65 286 4, 464 Over (under)* (162) 4 112 2 132 (20) (5) (15) 116 164 * hundreds of cases © 2003 Pearson Education Canada Inc. 18. 15
THE CONTROL PROCESS (continued) • Taking Managerial Action – Correct Actual Performance - action taken when the performance variation is unsatisfactory • immediate corrective action - corrects problems at once to get performance back on track • basic corrective action - identifies reason for performance variation – Revise the Standard - variance results from an unrealistic standard • standard, not performance, needs correction © 2003 Pearson Education Canada Inc. 18. 16
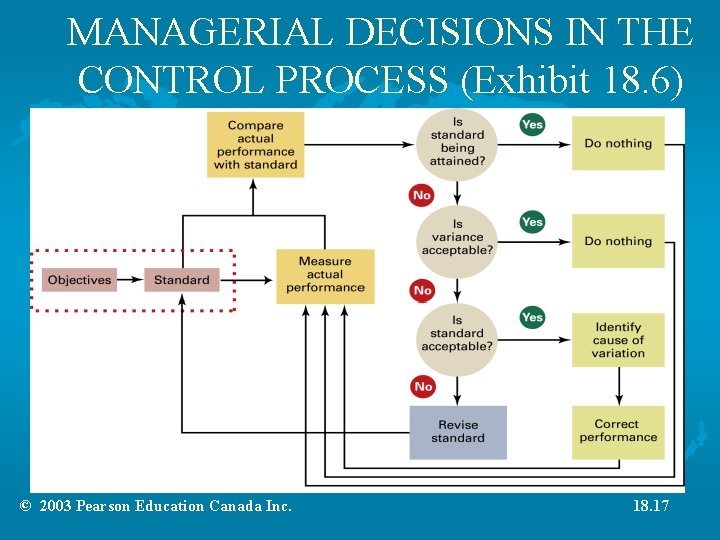
MANAGERIAL DECISIONS IN THE CONTROL PROCESS (Exhibit 18. 6) © 2003 Pearson Education Canada Inc. 18. 17
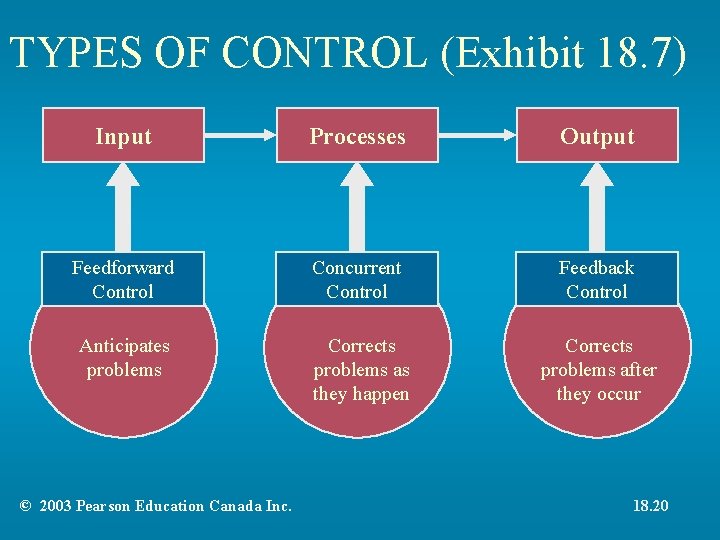
TYPES OF CONTROL • Feedforward Control – prevents anticipated problems – most desirable type of control – requires timely and accurate information that often is difficult to get • Concurrent Control – takes place while activity is in progress – corrects problem before it becomes too costly – best-known form is direct supervision © 2003 Pearson Education Canada Inc. 18. 18
TYPES OF CONTROL (continued) • Feedback Control – – Takes place after the activity is done Problems may already have caused damage or waste The most popular type of control Feedback has two advantages • provides meaningful information on the effectiveness of planning • can enhance employee motivation © 2003 Pearson Education Canada Inc. 18. 19
TYPES OF CONTROL (Exhibit 18. 7) Input Processes Output Feedforward Control Concurrent Control Feedback Control Anticipates problems Corrects problems as they happen Corrects problems after they occur © 2003 Pearson Education Canada Inc. 18. 20
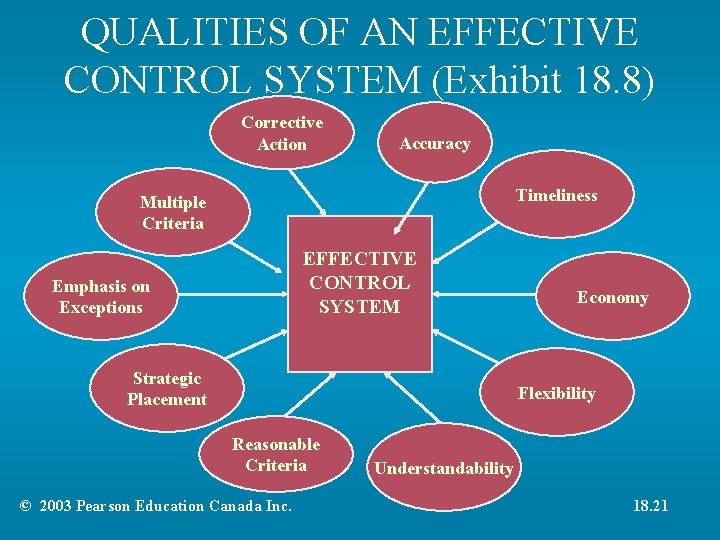
QUALITIES OF AN EFFECTIVE CONTROL SYSTEM (Exhibit 18. 8) Corrective Action Accuracy Timeliness Multiple Criteria EFFECTIVE CONTROL SYSTEM Emphasis on Exceptions Strategic Placement Economy Flexibility Reasonable Criteria © 2003 Pearson Education Canada Inc. Understandability 18. 21
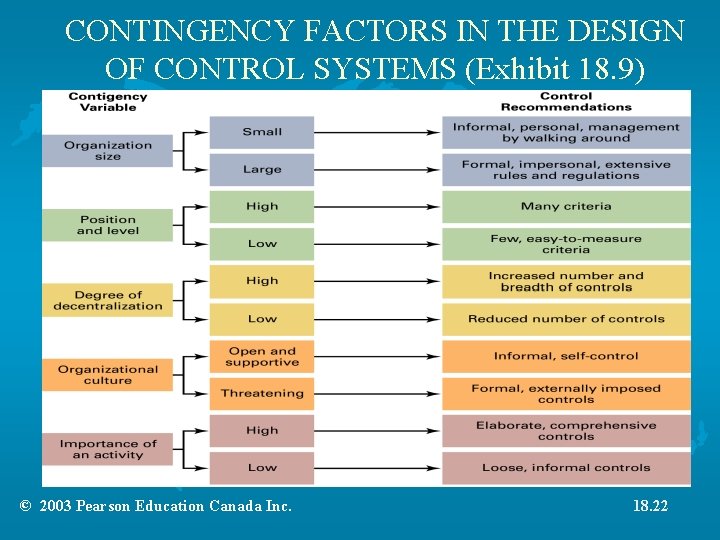
CONTINGENCY FACTORS IN THE DESIGN OF CONTROL SYSTEMS (Exhibit 18. 9) © 2003 Pearson Education Canada Inc. 18. 22
IMPLICATIONS FOR MANAGERS • Adjusting Controls for Cultural Differences – – – Methods of controlling people and work can be quite different in other countries In technologically advanced nations, controls are indirect In less technologically advanced nations, controls are more direct Laws in different countries provide different constraints on corrective action Data used for controlling may not be comparable in different countries © 2003 Pearson Education Canada Inc. 18. 23
CONTEMPORARY ISSUES IN CONTROL • Workplace Privacy – – Employers have the right to monitor employee communications, examine employee computers and files, and use surveillance cameras Reasons for monitoring include prevention of: • recreational on-the-job Web surfing • creation of hostile work environments with e-mail • security leaks of critical information © 2003 Pearson Education Canada Inc. 18. 24
CONTEMPORARY ISSUES IN CONTROL (continued) • Workplace Privacy (continued) – Companies are developing and enforcing workplace monitoring policies • develop unambiguous computer usage policy • inform employees that computers may be monitored • provide clear guidelines on acceptable use of company e-mail system and the Web © 2003 Pearson Education Canada Inc. 18. 25
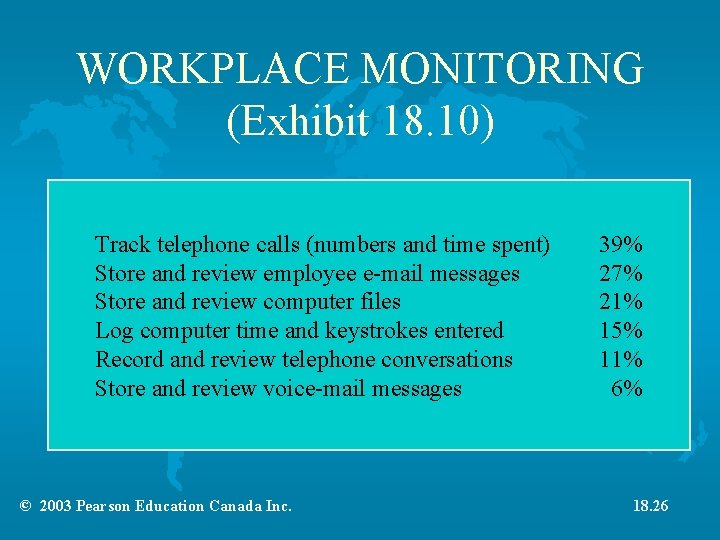
WORKPLACE MONITORING (Exhibit 18. 10) Track telephone calls (numbers and time spent) Store and review employee e-mail messages Store and review computer files Log computer time and keystrokes entered Record and review telephone conversations Store and review voice-mail messages © 2003 Pearson Education Canada Inc. 39% 27% 21% 15% 11% 6% 18. 26
CONTEMPORARY ISSUES IN CONTROL (continued) • Employee Theft – – – Unauthorized taking of company property by employees for their personal use Is an escalating problem in all types of organizations Different proposals to explain employee theft © 2003 Pearson Education Canada Inc. 18. 27
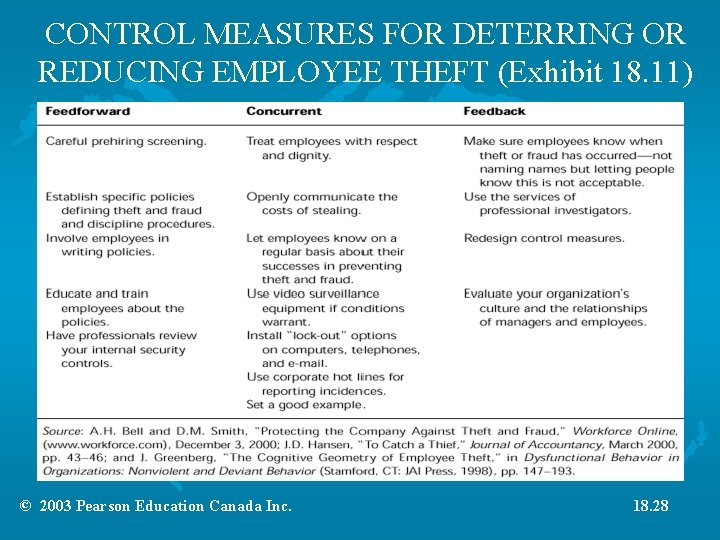
CONTROL MEASURES FOR DETERRING OR REDUCING EMPLOYEE THEFT (Exhibit 18. 11) © 2003 Pearson Education Canada Inc. 18. 28
CONTEMPORARY ISSUES IN CONTROL (continued) • Workplace Violence – Many factors contribute to workplace violence including: • • • employee work driven by time, numbers, and crises rapid and unpredictable change destructive communication style of manager authoritarian leadership defensive attitude double standards unresolved grievances emotionally troubled employees repetitive, boring work © 2003 Pearson Education Canada Inc. 18. 29