Annuities Chapter 11 Annuities n n Equal Cash
- Slides: 16
Annuities Chapter 11
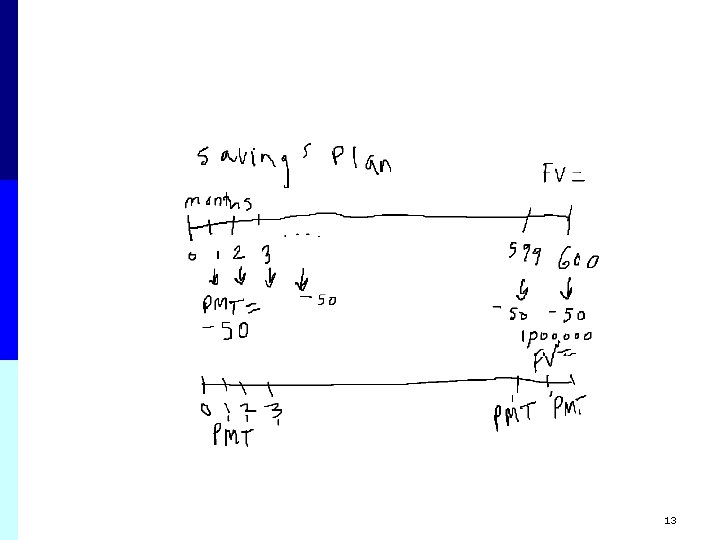
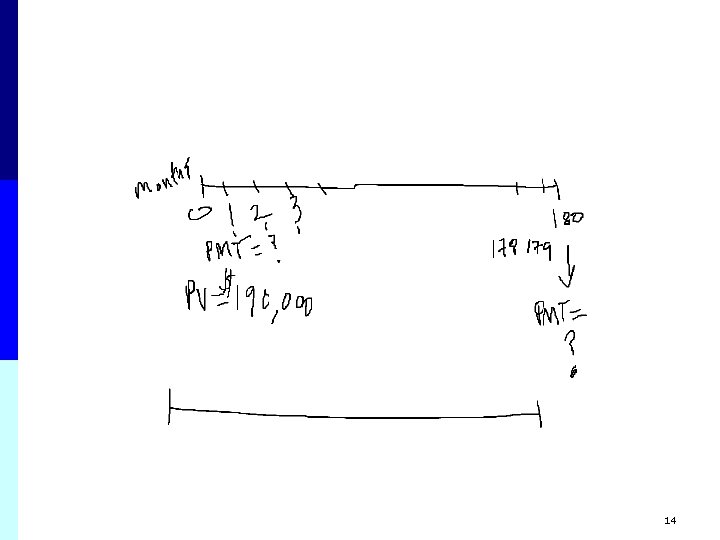
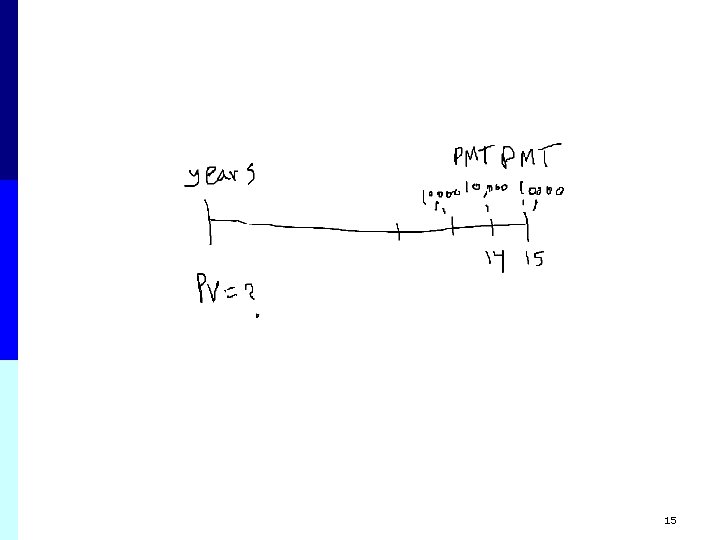
Annuities n n Equal Cash Flows at Equal Time Intervals Ordinary Annuity (End): Cash Flow At End Of Each Period Annuity Due (Begin): Cash Flow At Beginning Of Each Period Examples: n Savings Plan: Save $50 at the end of each month n Savings Plan: How Much Do I have to put in bank each month for 35 years to become a millionaire? n Borrow Money: What is my monthly payment if I borrow $190, 000? n Asset Valuation: How much should I pay for a machine if it will yield Cash Flow of $10, 000 at the each of each year for the next 15 years? 2
Annuities n Annuity Definition: n A level steam of cash flows for a fixed period of time n n Each payment is for the same amount Payments are referred to as: PMT The time between PMT is always the same Timing for annuities: n Ordinary Annuity (Savings Plans, Mortgage contracts) n n n PMT are made at the end of each period The day you sign the contract, you do not make a PMT Annuity due (Lease contracts) n PMT are made at the beginning of each period 3
Types of Annuities n Savings plan: n n Future value of future cash flows valuation: n n If I want to be a millionaire, how much do I have to put in the bank at the end of each month. What is the PMTFV? Loan (DEBT) periodic payment: n n If I put $50 (PMT) in the bank at the end of each month for 50 years, how much will I have when I retire? What is the future value? If I take out a loan for $190, 000, what is the monthly payment amount paid at the end of each month (PMT)? What is the PMTPV? Present value of future cash flows valuation n If I know the asset will give me $10, 000 (PMT) at the end of each year for the next 15 years, what should I pay for this asset today? What is the present value? 4
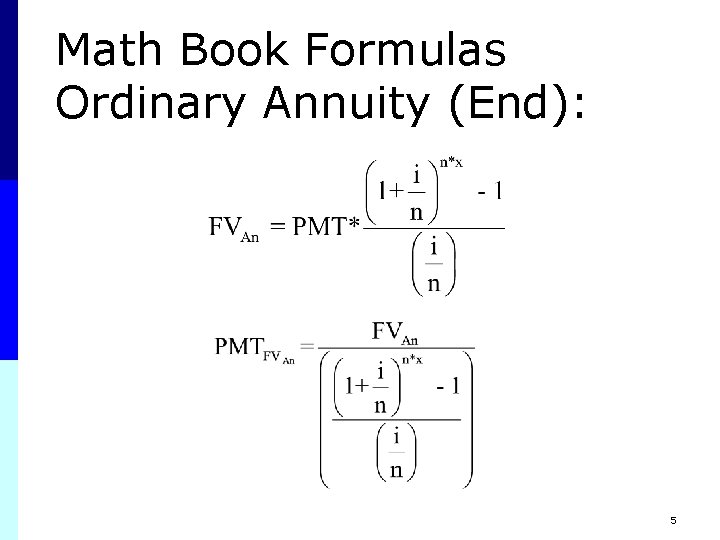
Math Book Formulas Ordinary Annuity (End): 5
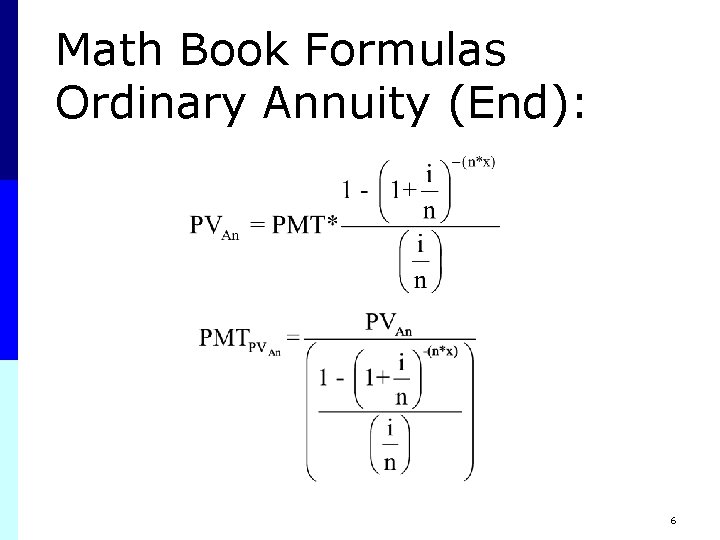
Math Book Formulas Ordinary Annuity (End): 6
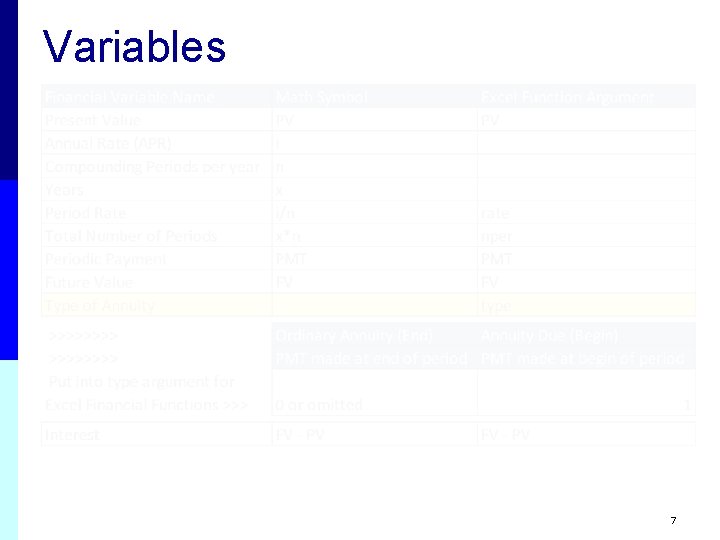
Variables 7
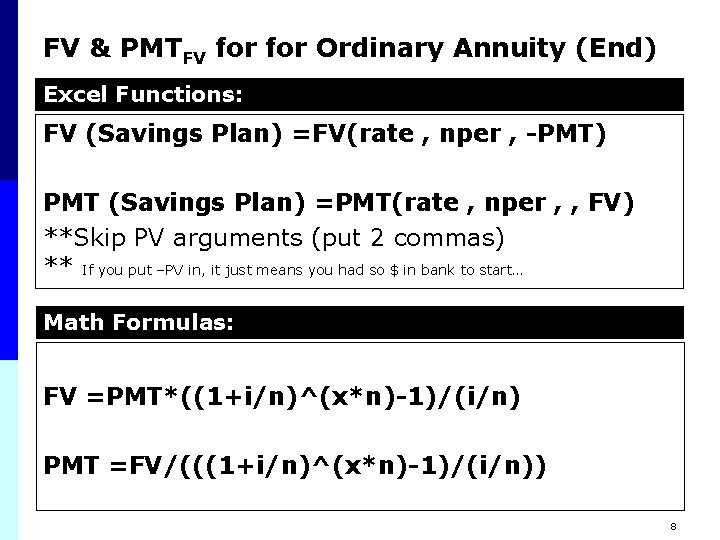
FV & PMTFV for Ordinary Annuity (End) Excel Functions: FV (Savings Plan) =FV(rate , nper , -PMT) PMT (Savings Plan) =PMT(rate , nper , , FV) **Skip PV arguments (put 2 commas) ** If you put –PV in, it just means you had so $ in bank to start… Math Formulas: FV =PMT*((1+i/n)^(x*n)-1)/(i/n) PMT =FV/(((1+i/n)^(x*n)-1)/(i/n)) 8
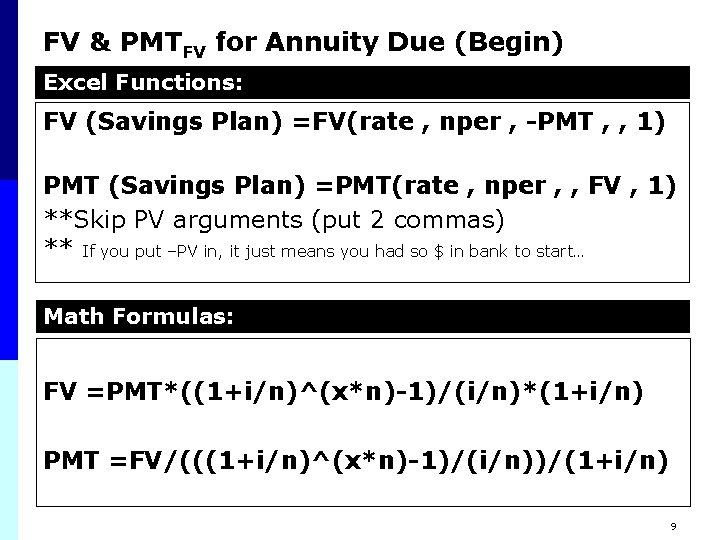
FV & PMTFV for Annuity Due (Begin) Excel Functions: FV (Savings Plan) =FV(rate , nper , -PMT , , 1) PMT (Savings Plan) =PMT(rate , nper , , FV , 1) **Skip PV arguments (put 2 commas) ** If you put –PV in, it just means you had so $ in bank to start… Math Formulas: FV =PMT*((1+i/n)^(x*n)-1)/(i/n)*(1+i/n) PMT =FV/(((1+i/n)^(x*n)-1)/(i/n))/(1+i/n) 9
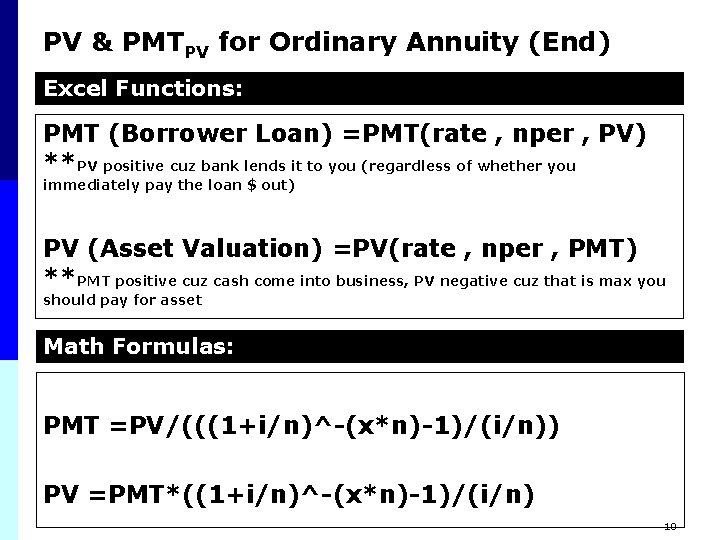
PV & PMTPV for Ordinary Annuity (End) Excel Functions: PMT (Borrower Loan) =PMT(rate , nper , PV) **PV positive cuz bank lends it to you (regardless of whether you immediately pay the loan $ out) PV (Asset Valuation) =PV(rate , nper , PMT) **PMT positive cuz cash come into business, PV negative cuz that is max you should pay for asset Math Formulas: PMT =PV/(((1+i/n)^-(x*n)-1)/(i/n)) PV =PMT*((1+i/n)^-(x*n)-1)/(i/n) 10
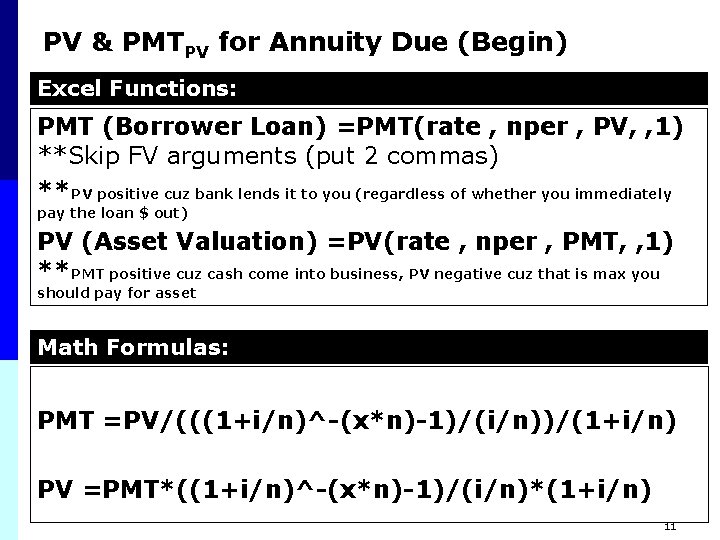
PV & PMTPV for Annuity Due (Begin) Excel Functions: PMT (Borrower Loan) =PMT(rate , nper , PV, , 1) **Skip FV arguments (put 2 commas) **PV positive cuz bank lends it to you (regardless of whether you immediately pay the loan $ out) PV (Asset Valuation) =PV(rate , nper , PMT, , 1) **PMT positive cuz cash come into business, PV negative cuz that is max you should pay for asset Math Formulas: PMT =PV/(((1+i/n)^-(x*n)-1)/(i/n))/(1+i/n) PV =PMT*((1+i/n)^-(x*n)-1)/(i/n)*(1+i/n) 11
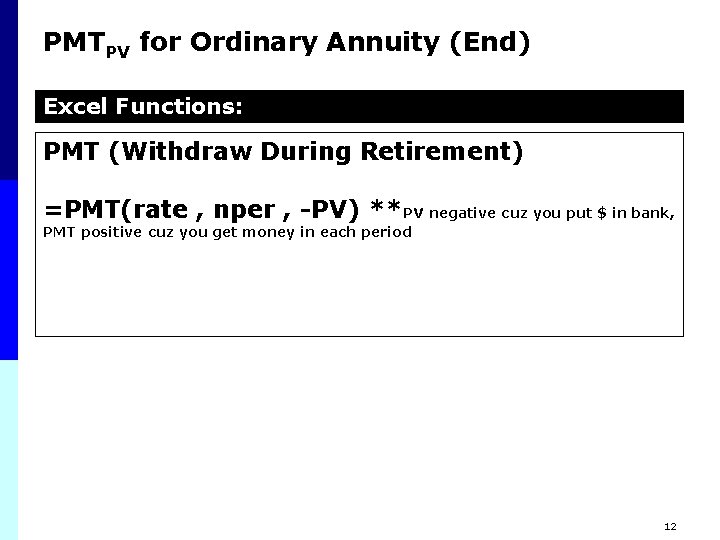
PMTPV for Ordinary Annuity (End) Excel Functions: PMT (Withdraw During Retirement) =PMT(rate , nper , -PV) **PV negative cuz you put $ in bank, PMT positive cuz you get money in each period 12
13
14
15
16