Warehouse Finance providing wider access to Securitisation Alex
- Slides: 17
Warehouse Finance – providing wider access to Securitisation Alex Medlock Head of Origination, VTB Europe Asset Securitisation in Russia and CIS Frankfurt 21 -22 June 2007
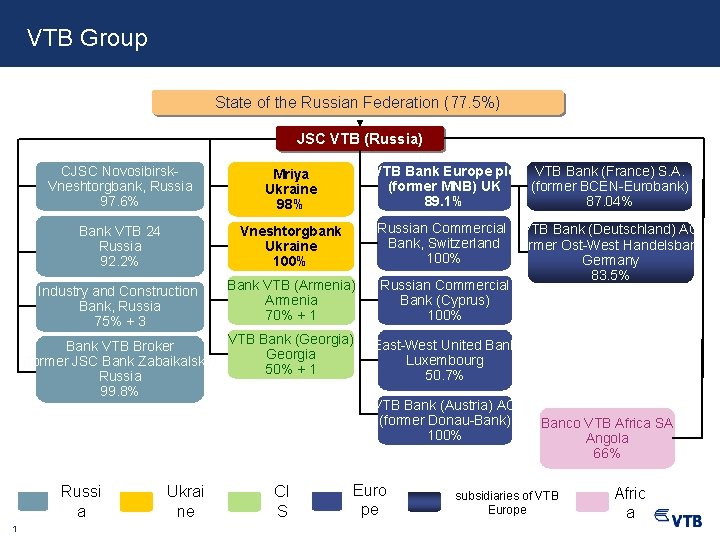
VTB Group State of the Russian Federation (77. 5%) JSC VTB (Russia) CJSC Novosibirsk. Vneshtorgbank, Russia 97. 6% Mriya Ukraine 98% Bank VTB 24 Russia 92. 2% Vneshtorgbank Ukraine 100% Industry and Construction Bank, Russia 75% + 3 Bank VTB (Armenia) Armenia 70% + 1 Bank VTB Broker (former JSC Bank Zabaikalsky) Russia 99. 8% Russi a 1 Ukrai ne VTB Bank Europe plc (former MNB) UK 89. 1% VTB Bank (Georgia) Georgia 50% + 1 Russian Commercial VTB Bank (Deutschland) AG Bank, Switzerland (former Ost-West Handelsbank) 100% Germany 83. 5% Russian Commercial Bank (Cyprus) 100% East-West United Bank Luxembourg 50. 7% VTB Bank (Austria) AG (former Donau-Bank) 100% CI S VTB Bank (France) S. A. (former BCEN-Eurobank) 87. 04% Euro pe Banco VTB Africa SA Angola 66% subsidiaries of VTB Europe Afric a
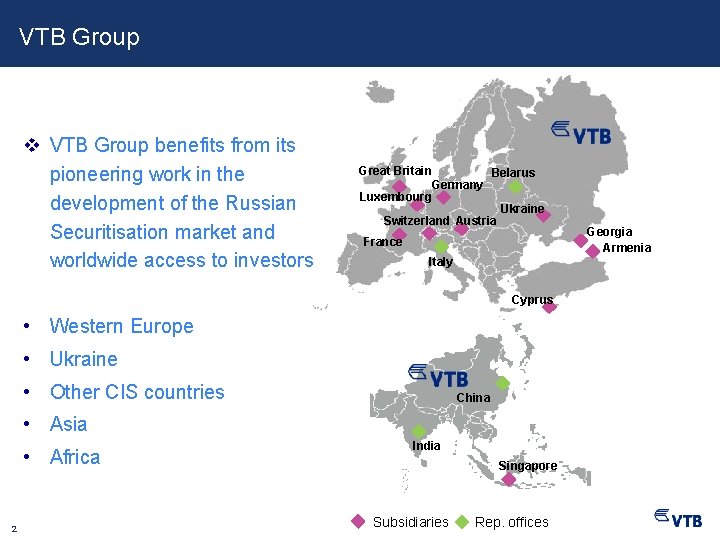
VTB Group v VTB Group benefits from its pioneering work in the development of the Russian Securitisation market and worldwide access to investors Great Britain Belarus Germany Luxembourg Ukraine Switzerland Austria France Italy Cyprus • Western Europe • Ukraine • Other CIS countries China • Asia • Africa 2 India Singapore Subsidiaries Rep. offices Georgia Armenia
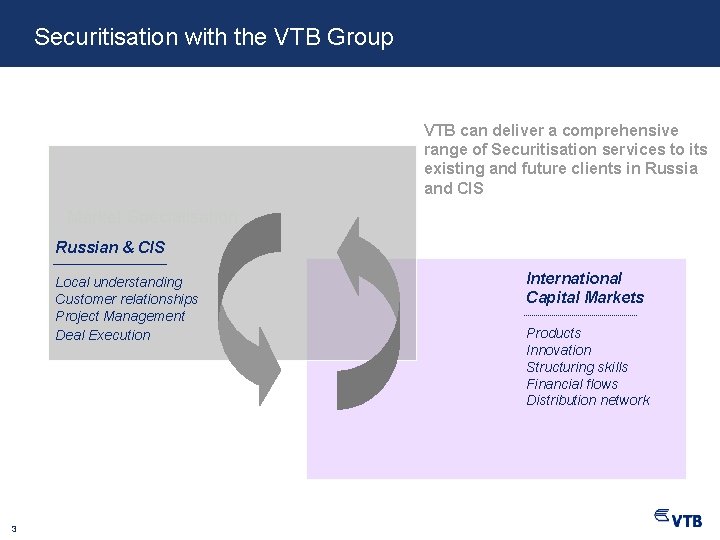
Securitisation with the VTB Group VTB can deliver a comprehensive range of Securitisation services to its existing and future clients in Russia and CIS Market Specialisation Russian & CIS Local understanding Customer relationships Project Management Deal Execution 3 International Capital Markets Products Innovation Structuring skills Financial flows Distribution network
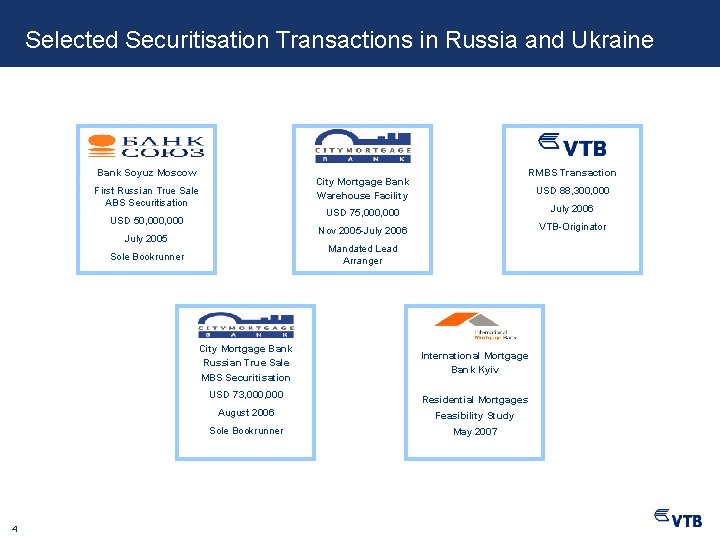
Selected Securitisation Transactions in Russia and Ukraine Bank Soyuz Moscow First Russian True Sale ABS Securitisation USD 50, 000 July 2005 USD 88, 300, 000 USD 75, 000 July 2006 Nov 2005 -July 2006 VTB-Originator Mandated Lead Arranger Sole Bookrunner City Mortgage Bank Russian True Sale MBS Securitisation USD 73, 000 4 RMBS Transaction City Mortgage Bank Warehouse Facility International Mortgage Bank Kyiv Residential Mortgages August 2006 Feasibility Study Sole Bookrunner May 2007
Warehouse Facility – Purpose 5 • The purpose of the Warehouse Facility is to provide financing to the Originator in order to accumulate a portfolio of receivables sufficient in size to permit a marketable and economic ABS/MBS offering to investors • The Originator sells portfolios to the Warehouse during the “Ramp Up” period • Once the Warehouse has been refinanced through securitisation it may be reused for another cycle • May be structured as a “true sale” or “limited recourse financing” depending on the objectives of the Originator
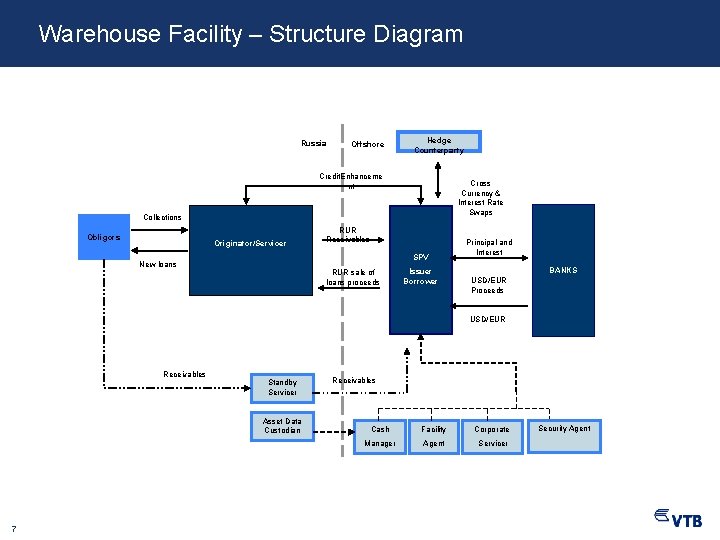
Warehouse Facility - Structure 6 • Typical cross-border true sale securitisation structure with SPV in tax efficient domicile e. g. Netherlands/Luxembourg (Russia), UK, (Ukraine) • Originator continues to service the portfolio and earns servicing fee and or excess spread • Public rating not necessary, but often “Initial Assessment” which focuses on portfolio characteristics • Senior/subordinate structure to provide credit enhancement for senior tranche/loan
Warehouse Facility – Structure Diagram Russia Offshore Hedge Counterparty Credit. Enhanceme nt Cross Currency & Interest Rate Swaps Collections Obligors Originator/Servicer RUR Receivables SPV New loans RUR sale of loans proceeds Issuer Borrower Principal and Interest BANKS USD/EUR Proceeds USD/EUR Receivables Standby Servicer Asset Data Custodian 7 Receivables Cash Facility Corporate Manager Agent Servicer Security Agent
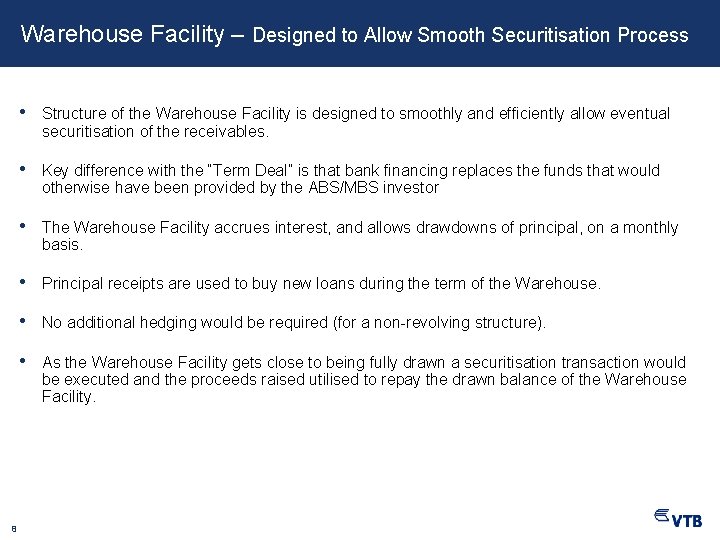
Warehouse Facility – Designed to Allow Smooth Securitisation Process 8 • Structure of the Warehouse Facility is designed to smoothly and efficiently allow eventual securitisation of the receivables. • Key difference with the “Term Deal” is that bank financing replaces the funds that would otherwise have been provided by the ABS/MBS investor • The Warehouse Facility accrues interest, and allows drawdowns of principal, on a monthly basis. • Principal receipts are used to buy new loans during the term of the Warehouse. • No additional hedging would be required (for a non-revolving structure). • As the Warehouse Facility gets close to being fully drawn a securitisation transaction would be executed and the proceeds raised utilised to repay the drawn balance of the Warehouse Facility.
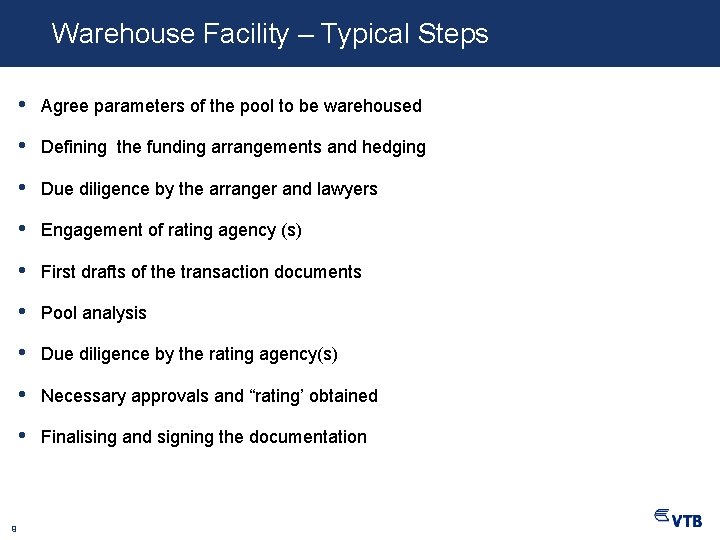
Warehouse Facility – Typical Steps 9 • Agree parameters of the pool to be warehoused • Defining the funding arrangements and hedging • Due diligence by the arranger and lawyers • Engagement of rating agency (s) • First drafts of the transaction documents • Pool analysis • Due diligence by the rating agency(s) • Necessary approvals and “rating’ obtained • Finalising and signing the documentation
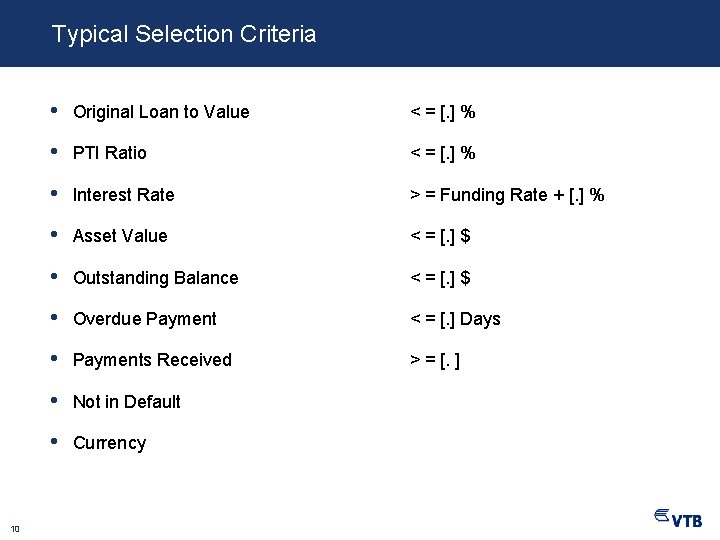
Typical Selection Criteria 10 • Original Loan to Value < = [. ] % • PTI Ratio < = [. ] % • Interest Rate > = Funding Rate + [. ] % • Asset Value < = [. ] $ • Outstanding Balance < = [. ] $ • Overdue Payment < = [. ] Days • Payments Received > = [. ] • Not in Default • Currency
Ongoing Portfolio Characteristics 11 • Product Types < = [. ] % • Weighted Average Seasoning > =. months • Weighted Average remaining term < = [. ] months • Weighted average interest rate > = funding rate + [. ] % • Weighted average LTV < = [. ] % • Regional Concentration < = [. ] % • Aggregate jumbo loans < = [. ] % • Delinquent loans < = [. ]%
Originator Buy Back/Repurchase Obligation 12 • Untrue or incorrect Originator representations and warranties • Change in Loan Terms outside Eligibility Criteria • Assets remaining in Warehouse following Securitisation • Defaulted Loans • Structure of Buy Back obligation will depend on the Originator’s objectives during Warehouse stage.
Hedging required for Warehousing and ABS/MBS issuance 13 • To access the ABS/MBS investor universe efficiently it is essential to offer ABS/MBS which offer a floating rate of interest. Although a fixed rate ABS/MBS market does exist, it generaly prefers bonds that offer a bullet maturity or a guaranteed amortisation schedule. • To address the mismatch between a RUR fixed rate of interest received and the floating rate of interest on the USD/EUR denominated bonds, a USD/EUR basis or a cross currency swap is required. • The incorporation of a swap is complicated by the fact that the notional amount of the collateral is uncertain at any given point in the future. • The swap must therefore be “balance guaranteed” meaning that the swap provider references the notional amount of the collateral outstanding, or a specific tranche such as the Senior Notes, in order to determine the notional amount of the swap. • Rating agencies and investors are familiar with this type of hedging structure.
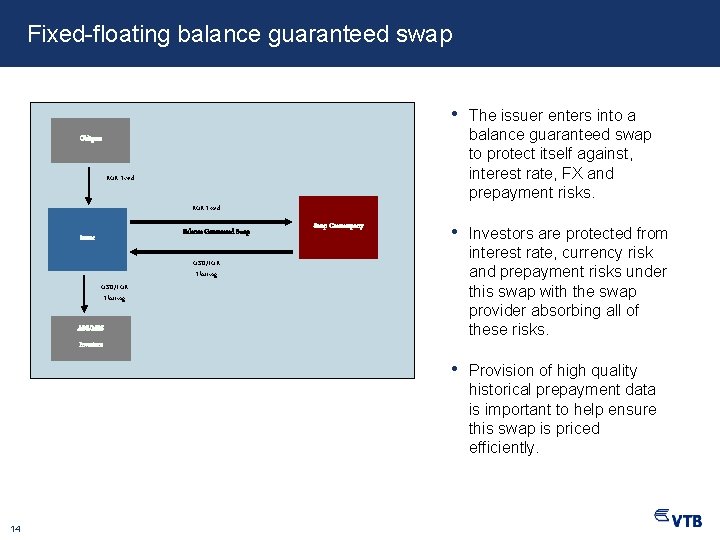
Fixed-floating balance guaranteed swap • The issuer enters into a balance guaranteed swap to protect itself against, interest rate, FX and prepayment risks. • Investors are protected from interest rate, currency risk and prepayment risks under this swap with the swap provider absorbing all of these risks. • Provision of high quality historical prepayment data is important to help ensure this swap is priced efficiently. Obligors RUR Fixed Balance Guaranteed Swap Issuer Swap Counterparty USD/EUR Floating ABS/MBS Investors 14
Contact details Alex Medlock Head of Origination VTB Bank Europe plc 81 King Williams street London EC 4 N 7 BG Tel: + 44 20 7815 9254 Fax: + 44 20 7929 2534 Email: alex. medlock@vtbeurope. com Visit us @ www. vtb. com 15
Disclaimer This document has been prepared for information or discussion purposes only and does not constitute an offer, an invitation to offer, or a recommendation to enter into any transaction, nor is it an official or unofficial confirmation of terms. We have sent you this document in our capacity as a potential counterparty acting at arm’s length. We are not acting as your financial advisor or in a fiduciary capacity in respect of any transaction with you unless otherwise expressly agreed by us in writing. Before entering into any transaction you should take steps to ensure that you understand the transaction and have made an independent assessment of the appropriateness of the transaction in light of your own objectives and circumstances, including the possible risks and benefits of entering into such a transaction. You should also consider seeking advice from your advisors in making this assessment. Reference must be made to the official offering documents for definitive information with respect to any offering. VTB Europe Capital Markets is a division of VTB Bank Europe plc, authorised and regulated by the Financial Services Authority. No part of this report may be reproduced or distributed in any manner without permission of VTB Bank Europe plc. 16