Rizky Fadhila Hanief Dina Mustika Putri Irviansyah Pradana
- Slides: 21
Rizky Fadhila Hanief Dina Mustika Putri Irviansyah Pradana Gustian Maulidi Abdul Haris Azri
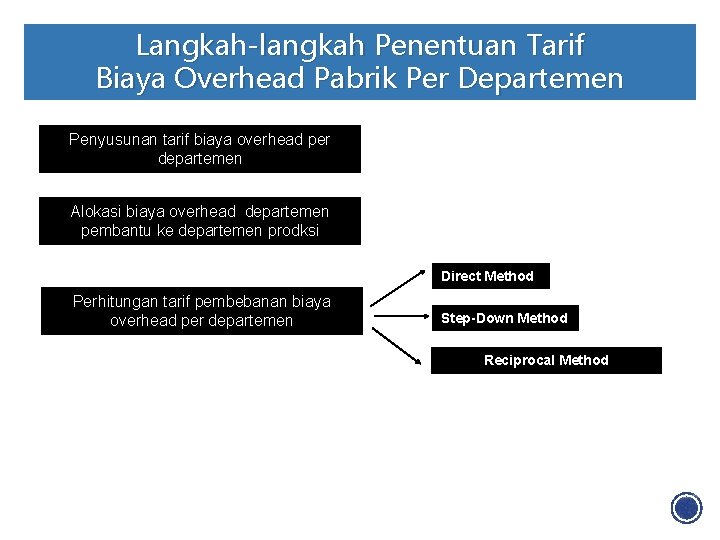
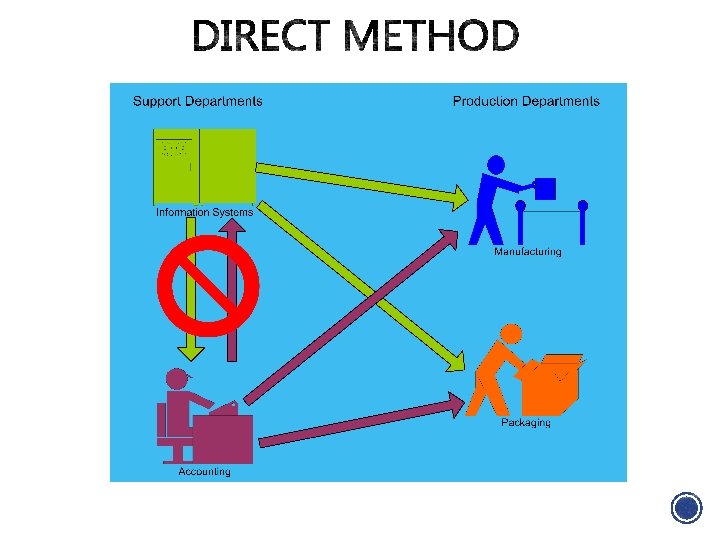
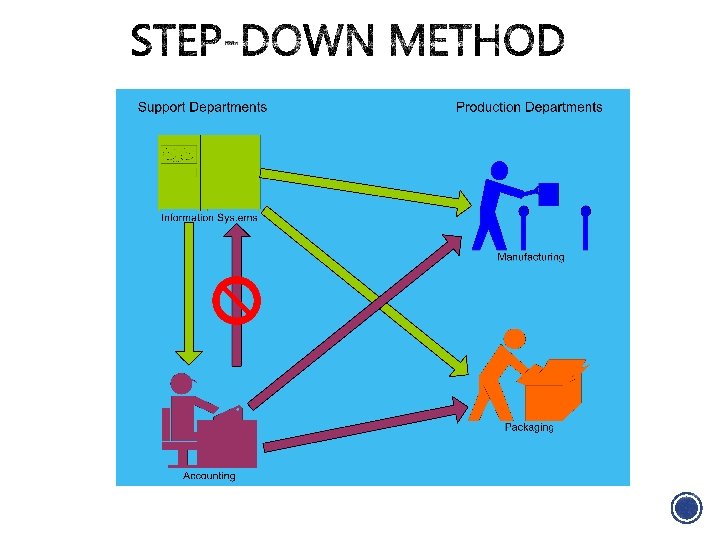
Langkah-langkah Penentuan Tarif Biaya Overhead Pabrik Per Departemen Penyusunan tarif biaya overhead per departemen Alokasi biaya overhead departemen pembantu ke departemen prodksi Direct Method Perhitungan tarif pembebanan biaya overhead per departemen Step-Down Method Reciprocal Method
§ Departemen produksi : departemen yang melakukan proses produksi dgn mengubah SDA menjadi suatu material atau dll § Departemen pelayanan : departemen yang membantu kelancaran dari suatu proses produksi yang terjadi di departemen produksi
§ Departementalization of Factory overhead means dividing the plant into segments, called departements, to which overhead costs are changed. For accounting purposes : - Improved product costing - Promotes responsible control of FOH
§ Penyusunan anggaran BOP per departemen baik departemen produksi maupun pelayanan § Alokasi BOP departemen pelayanan § Perhitungan tarif BOP per departemen produksi § Pembebanan BOP
§ Supervision, indirect labor, overtime § Labor fringe benefits § Indirect materials, supplies § repairs, and maintenance § Equipment depreciation § Machine in insurance
§ Building rent § Property tax § Depreciation-building § Fire insurance § Building repairs
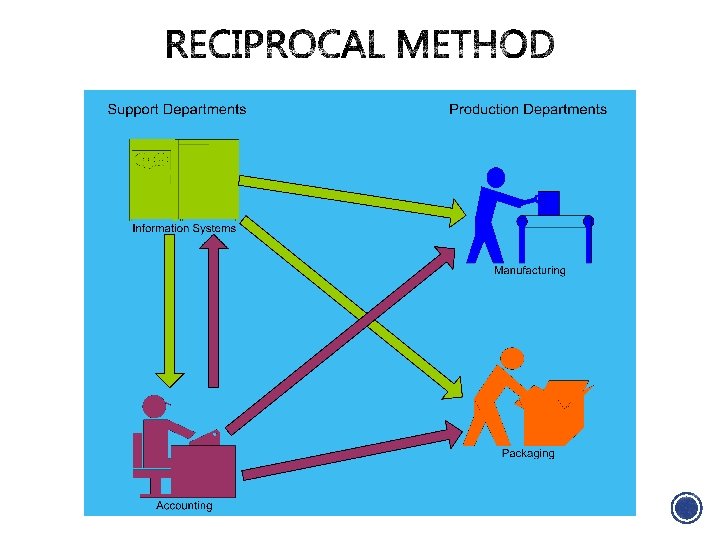
§ Direct § Step-down § Reciprocal/simultaneous/algebraic
• Metode Reciprocal paling akurat • Metode Direct langsung dan Step-Down lebih sederhana dan mudah
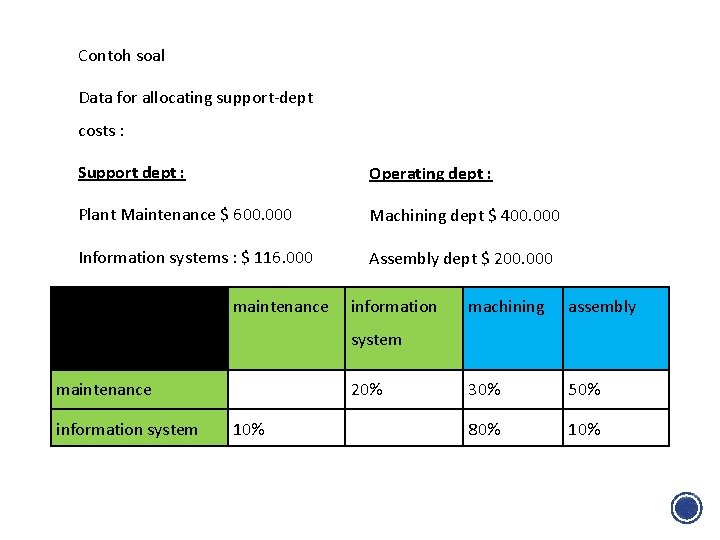
Contoh soal Data for allocating support-dept costs : Support dept : Operating dept : Plant Maintenance $ 600. 000 Machining dept $ 400. 000 Information systems : $ 116. 000 Assembly dept $ 200. 000 maintenance information machining assembly system maintenance 20% 30% 50% information system 10% 80% 10%
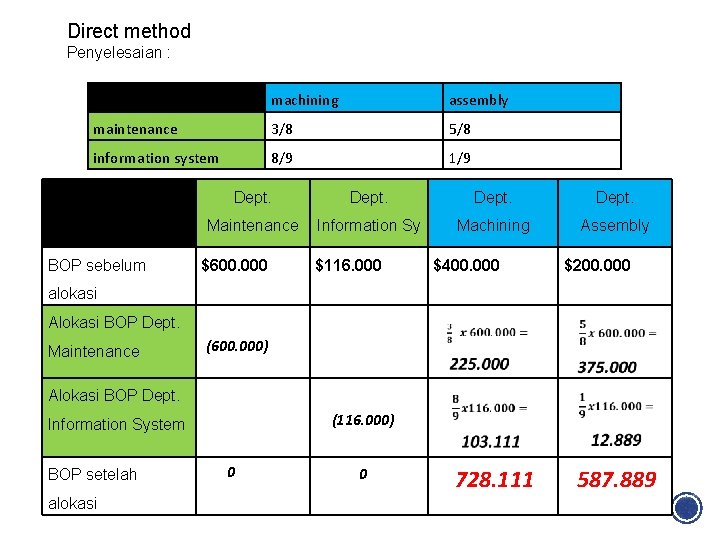
Direct method Penyelesaian : machining assembly maintenance 3/8 5/8 information system 8/9 1/9 BOP sebelum Dept. Maintenance Information Sy Machining Assembly $600. 000 $116. 000 $400. 000 $200. 000 alokasi Alokasi BOP Dept. (600. 000) Maintenance Alokasi BOP Dept. alokasi (116. 000) Information System BOP setelah 0 0 728. 111 587. 889
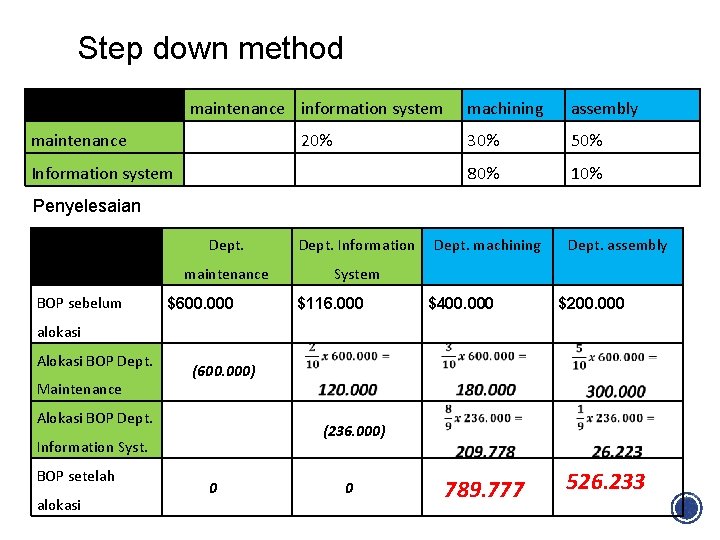
Step down method maintenance information system machining assembly maintenance 20% 30% 50% 80% 10% Information system Penyelesaian Dept. Information Dept. machining maintenance BOP sebelum $600. 000 alokasi Alokasi BOP Dept. Maintenance $116. 000 $400. 000 $200. 000 (600. 000) (236. 000) Information Syst. alokasi System Alokasi BOP Dept. BOP setelah Dept. assembly 0 0 789. 777 526. 233
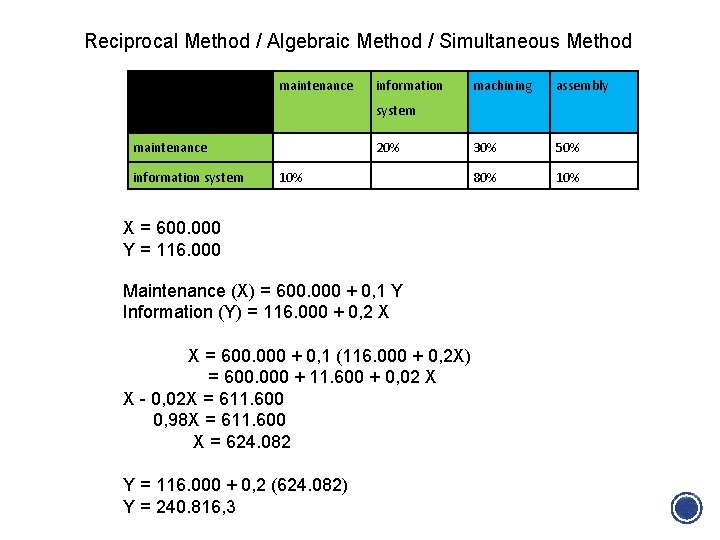
Reciprocal Method / Algebraic Method / Simultaneous Method maintenance information machining assembly system maintenance 20% 30% 50% information system 10% 80% 10% X = 600. 000 Y = 116. 000 Maintenance (X) = 600. 000 + 0, 1 Y Information (Y) = 116. 000 + 0, 2 X X = 600. 000 + 0, 1 (116. 000 + 0, 2 X) = 600. 000 + 11. 600 + 0, 02 X X - 0, 02 X = 611. 600 0, 98 X = 611. 600 X = 624. 082 Y = 116. 000 + 0, 2 (624. 082) Y = 240. 816, 3
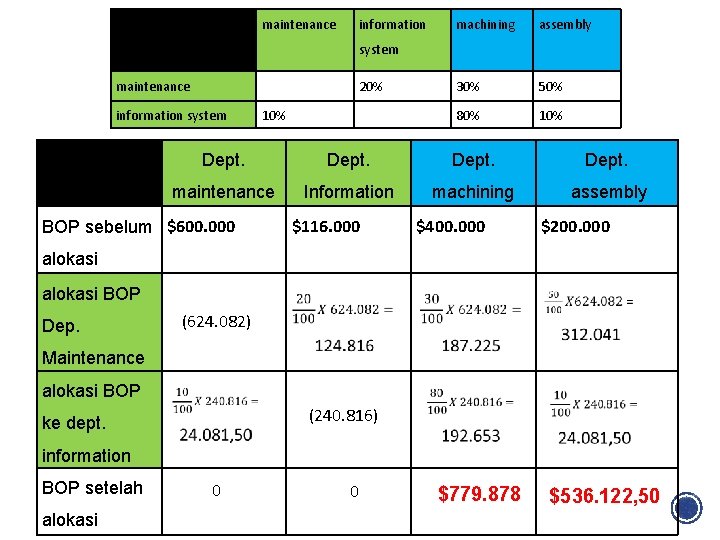
maintenance information machining assembly system maintenance 20% 30% 50% information system 10% 80% 10% Dept. maintenance Information machining assembly BOP sebelum $600. 000 $116. 000 $400. 000 $200. 000 alokasi BOP Dep. (624. 082) Maintenance alokasi BOP (240. 816) ke dept. information BOP setelah alokasi 0 0 $779. 878 $536. 122, 50
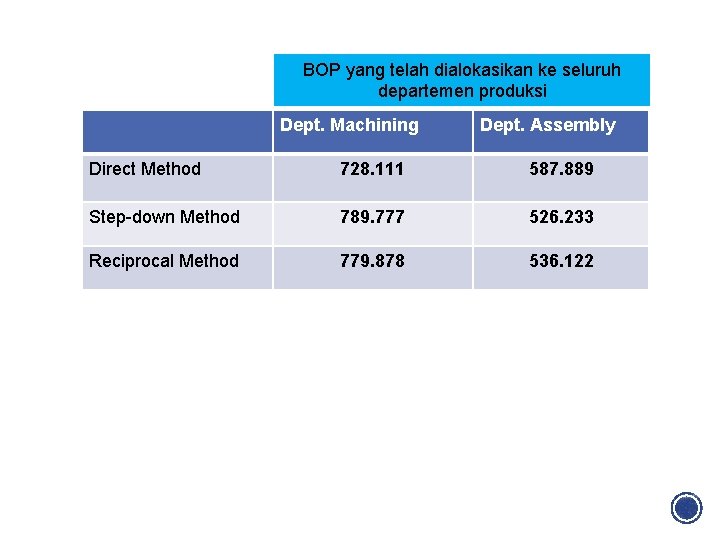
BOP yang telah dialokasikan ke seluruh departemen produksi Dept. Machining Dept. Assembly Direct Method 728. 111 587. 889 Step-down Method 789. 777 526. 233 Reciprocal Method 779. 878 536. 122
TERIMAKASIH THANK YOU HATUR NUHUN
§ Raka 1. angka persentase awal yag 80&