RISK ALLOCATION IN A MULTI ASSET FRAMEWORK ISOVOLATILITY
- Slides: 27
RISK ALLOCATION IN A MULTI -ASSET FRAMEWORK ISOVOLATILITY Tarek ISSAOUI, Head of Flexible Solutions & Overlay London, 3 October 2017 FOR PROFESSIONAL INVESTORS MARKETING COMMUNICATION
1 VOLATILITY LANDSCAPE & RISK ALLOCATION 03/10/2020 2
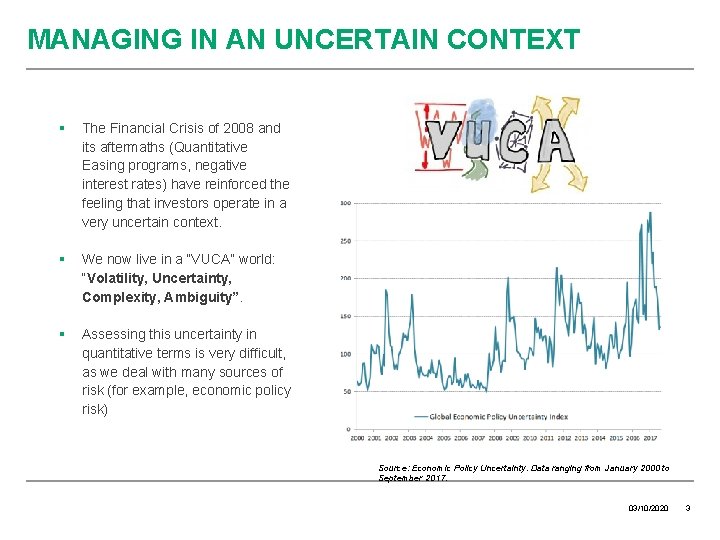
MANAGING IN AN UNCERTAIN CONTEXT The Financial Crisis of 2008 and its aftermaths (Quantitative Easing programs, negative interest rates) have reinforced the feeling that investors operate in a very uncertain context. We now live in a “VUCA” world: “Volatility, Uncertainty, Complexity, Ambiguity”. Assessing this uncertainty in quantitative terms is very difficult, as we deal with many sources of risk (for example, economic policy risk) Source: Economic Policy Uncertainty. Data ranging from January 2000 to September 2017. 03/10/2020 3
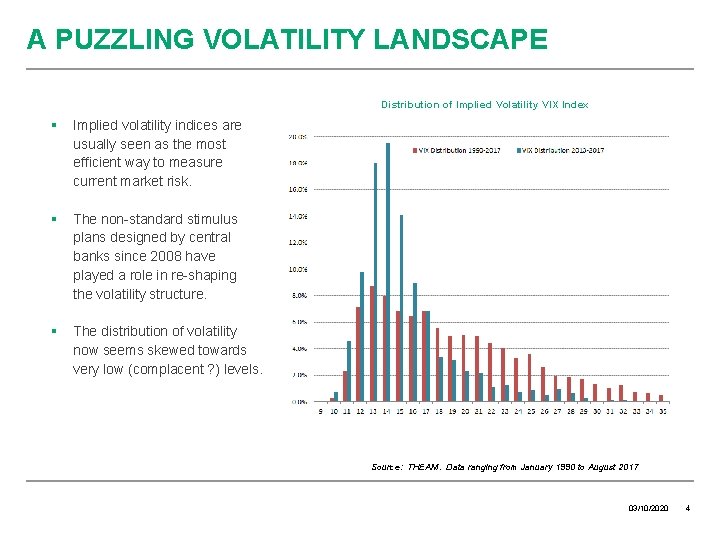
A PUZZLING VOLATILITY LANDSCAPE Distribution of Implied Volatility VIX Index Implied volatility indices are usually seen as the most efficient way to measure current market risk. The non-standard stimulus plans designed by central banks since 2008 have played a role in re-shaping the volatility structure. The distribution of volatility now seems skewed towards very low (complacent ? ) levels. Source: THEAM. Data ranging from January 1990 to August 2017 03/10/2020 4
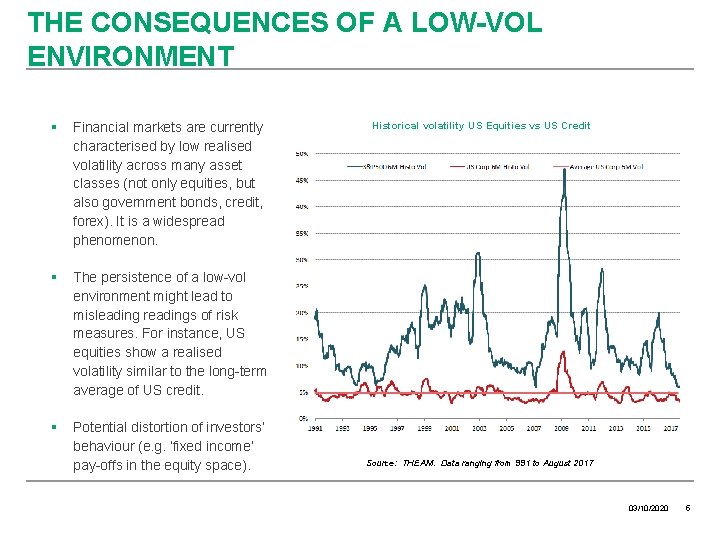
THE CONSEQUENCES OF A LOW-VOL ENVIRONMENT Financial markets are currently characterised by low realised volatility across many asset classes (not only equities, but also government bonds, credit, forex). It is a widespread phenomenon. The persistence of a low-vol environment might lead to misleading readings of risk measures. For instance, US equities show a realised volatility similar to the long-term average of US credit. Potential distortion of investors’ behaviour (e. g. ‘fixed income’ pay-offs in the equity space). Historical volatility US Equities vs US Credit Source: THEAM. Data ranging from 991 to August 2017 03/10/2020 5
UP AND DOWN FORCES ON VOLATILITY Central banks’ activity, moral hazard & forward guidance Coming normalisation of central banks’ nonstandard measures Low realised macroeconomic volatility (growth & inflation) Hunt for ‘short vol’ pay-offs (e. g. autocalls) in a low rate environment Rising corporate leverage & high debt/GDP ratios create cash-flow vulnerability Pro-cyclical behaviour of investors (herding) Geopolitical risk Share buy-backs High sector dispersion intra -market, capping index moves More “known unknowns” in recent years (e. g: elections) 03/10/2020 6
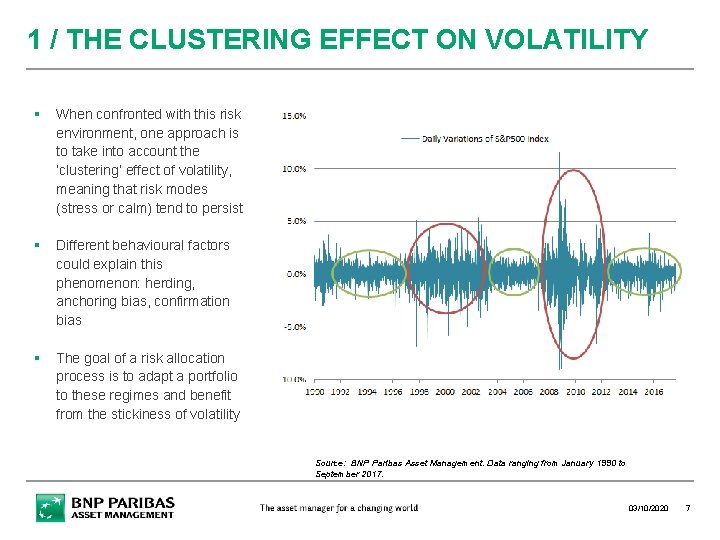
1 / THE CLUSTERING EFFECT ON VOLATILITY When confronted with this risk environment, one approach is to take into account the ‘clustering’ effect of volatility, meaning that risk modes (stress or calm) tend to persist Different behavioural factors could explain this phenomenon: herding, anchoring bias, confirmation bias The goal of a risk allocation process is to adapt a portfolio to these regimes and benefit from the stickiness of volatility Source: BNP Paribas Asset Management. Data ranging from January 1990 to September 2017. 03/10/2020 7
BENEFITS CONFIRMED BY ACADEMIC RESEARCH BNPP AM’s Financial Engineering team has worked extensively on a risk budgeting methodology, highlighting the consequences of volatility clustering Our academic research shows that stabilising the volatility profile of a diversified portfolio reduces maximum drawdowns and increases the Sharpe ratio (performance vs. risk) Publication of BNP Paribas AM’s own research: Predicting the success of volatility targeting strategies: Application to equities and other asset classes Romain Perchet, Raul Leote de Carvalho, Thomas Heckel, Pierre Moulin The Journal of Alternative Investments, Hiver 2016, Vol. 18, Issue 3 Inter-temporal risk parity: a constant volatility framework for factor investing Romain Perchet, Raul Leote de Carvalho, Pierre Moulin Journal of Investment Strategies, 2014 Parvest Diversified Dynamic 02/06/2017 8
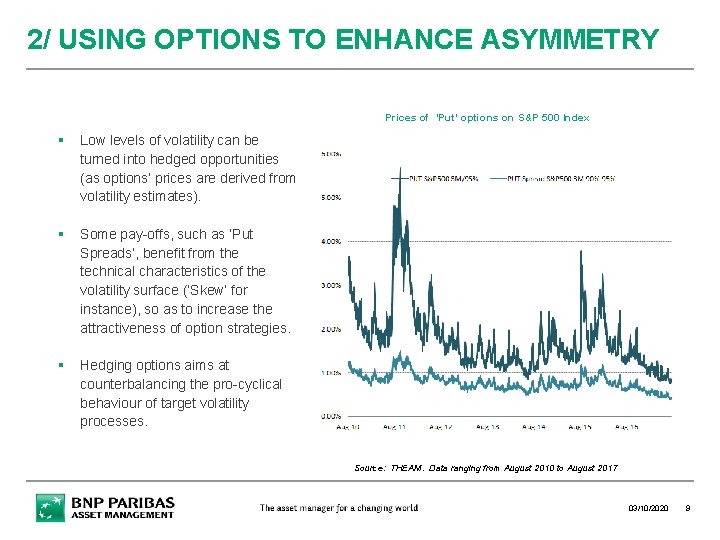
2/ USING OPTIONS TO ENHANCE ASYMMETRY Prices of ’Put’ options on S&P 500 Index Low levels of volatility can be turned into hedged opportunities (as options’ prices are derived from volatility estimates). Some pay-offs, such as ‘Put Spreads’, benefit from the technical characteristics of the volatility surface (‘Skew’ for instance), so as to increase the attractiveness of option strategies. Hedging options aims at counterbalancing the pro-cyclical behaviour of target volatility processes. Source: THEAM. Data ranging from August 2010 to August 2017 03/10/2020 9
2 FOCUS ON PARVEST DIVERSIFIED DYNAMIC 03/10/2020 10
HOW TO STABILISE PORTFOLIO RISK At the end of 2009, we introduced an innovative investment process, named ISOVOL, which is designed to stabilise the volatility of a diversified portfolio The concept is simple and intuitive: we adapt each asset’s exposure according to market dynamics. The lower the expected volatility, the higher the exposure, and vice versa. Light winds = full sail High winds = head sail adjusted 03/10/2020 11
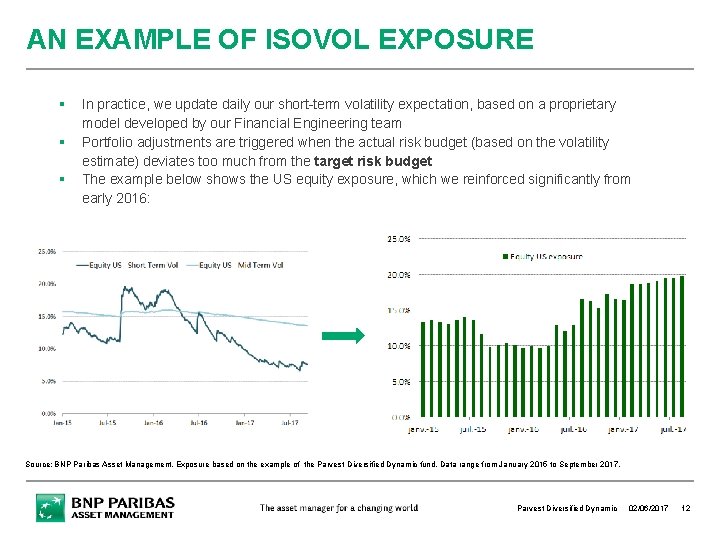
AN EXAMPLE OF ISOVOL EXPOSURE In practice, we update daily our short-term volatility expectation, based on a proprietary model developed by our Financial Engineering team Portfolio adjustments are triggered when the actual risk budget (based on the volatility estimate) deviates too much from the target risk budget The example below shows the US equity exposure, which we reinforced significantly from early 2016: Source: BNP Paribas Asset Management. Exposure based on the example of the Parvest Diversified Dynamic fund. Data range from January 2015 to September 2017. Parvest Diversified Dynamic 02/06/2017 12
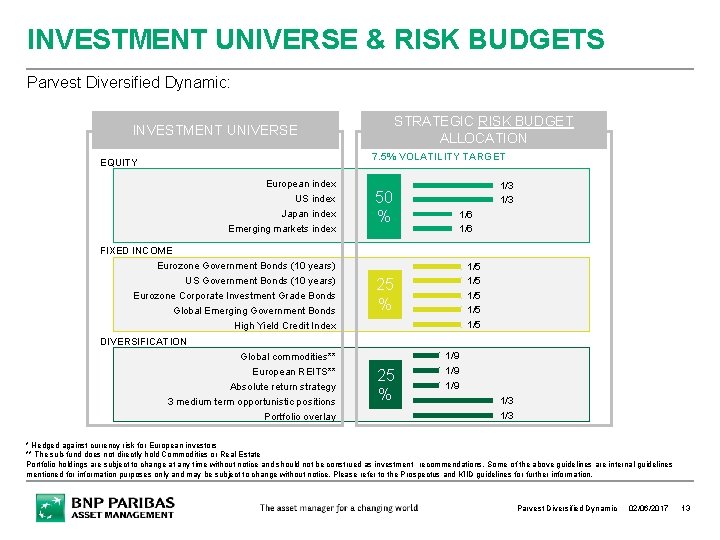
INVESTMENT UNIVERSE & RISK BUDGETS Parvest Diversified Dynamic: STRATEGIC RISK BUDGET ALLOCATION INVESTMENT UNIVERSE 7. 5% VOLATILITY TARGET EQUITY European index US index Japan index Emerging markets index 50 % 1/3 1/6 FIXED INCOME Eurozone Government Bonds (10 years) US Government Bonds (10 years) Eurozone Corporate Investment Grade Bonds Global Emerging Government Bonds High Yield Credit Index 1/5 1/5 1/5 25 % DIVERSIFICATION 1/9 Global commodities** European REITS** Absolute return strategy 3 medium term opportunistic positions Portfolio overlay 25 % 1/9 1/3 * Hedged against currency risk for European investors ** The sub-fund does not directly hold Commodities or Real Estate Portfolio holdings are subject to change at any time without notice and should not be construed as investment recommendations. Some of the above guidelines are internal guidelines mentioned for information purposes only and may be subject to change without notice. Please refer to the Prospectus and KIID guidelines for further information. Parvest Diversified Dynamic 02/06/2017 13
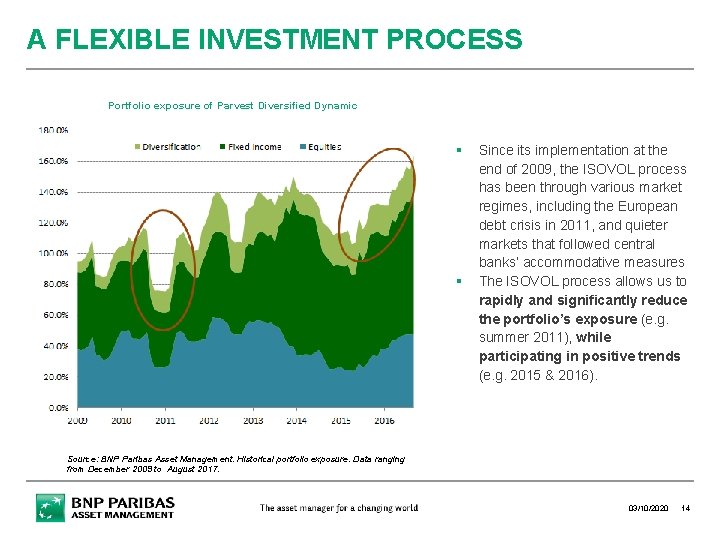
A FLEXIBLE INVESTMENT PROCESS Portfolio exposure of Parvest Diversified Dynamic Since its implementation at the end of 2009, the ISOVOL process has been through various market regimes, including the European debt crisis in 2011, and quieter markets that followed central banks’ accommodative measures The ISOVOL process allows us to rapidly and significantly reduce the portfolio’s exposure (e. g. summer 2011), while participating in positive trends (e. g. 2015 & 2016). Source: BNP Paribas Asset Management. Historical portfolio exposure. Data ranging from December 2009 to August 2017. 03/10/2020 14
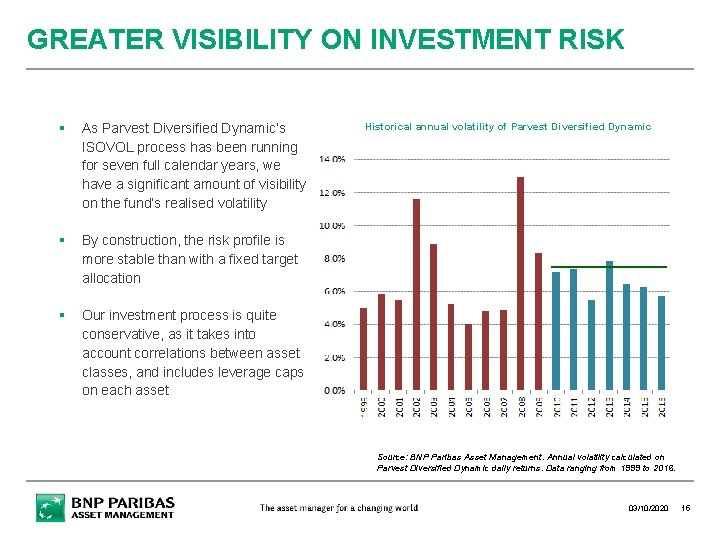
GREATER VISIBILITY ON INVESTMENT RISK As Parvest Diversified Dynamic’s ISOVOL process has been running for seven full calendar years, we have a significant amount of visibility on the fund’s realised volatility By construction, the risk profile is more stable than with a fixed target allocation Historical annual volatility of Parvest Diversified Dynamic Our investment process is quite conservative, as it takes into account correlations between asset classes, and includes leverage caps on each asset Source: BNP Paribas Asset Management. Annual volatility calculated on Parvest Diversified Dynamic daily returns. Data ranging from 1999 to 2016. 03/10/2020 15
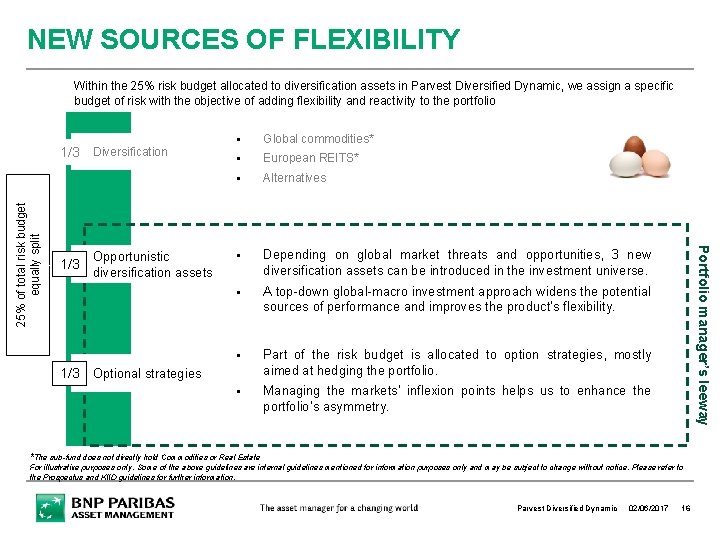
NEW SOURCES OF FLEXIBILITY Within the 25% risk budget allocated to diversification assets in Parvest Diversified Dynamic, we assign a specific budget of risk with the objective of adding flexibility and reactivity to the portfolio 1/3 Opportunistic diversification assets Global commodities* European REITS* Alternatives Depending on global market threats and opportunities, 3 new diversification assets can be introduced in the investment universe. A top-down global-macro investment approach widens the potential sources of performance and improves the product’s flexibility. Part of the risk budget is allocated to option strategies, mostly aimed at hedging the portfolio. Managing the markets’ inflexion points helps us to enhance the portfolio’s asymmetry. 1/3 Optional strategies Portfolio manager’s leeway 25% of total risk budget equally split 1/3 Diversification *The sub-fund does not directly hold Commodities or Real Estate For illustrative purposes only. Some of the above guidelines are internal guidelines mentioned for information purposes only and may be subject to change without notice. Please refer to the Prospectus and KIID guidelines for further information. Parvest Diversified Dynamic 02/06/2017 16
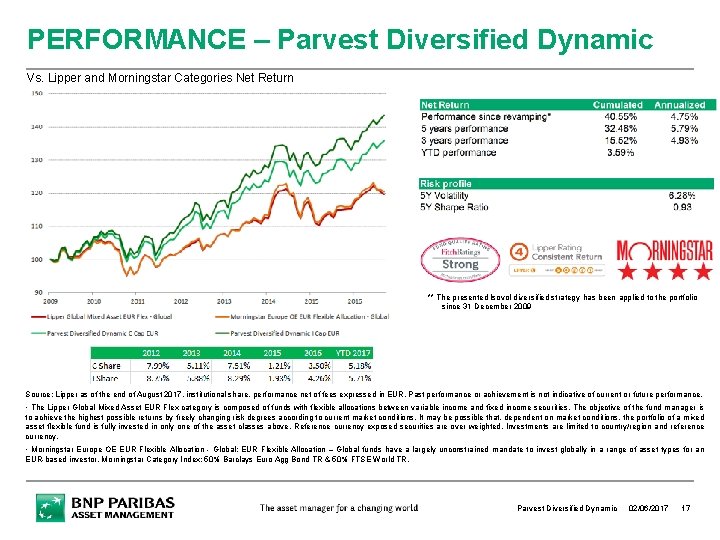
PERFORMANCE – Parvest Diversified Dynamic Vs. Lipper and Morningstar Categories Net Return ** The presented Isovol diversified strategy has been applied to the portfolio since 31 December 2009 Source: Lipper as of the end of August 2017, institutional share, performance net of fees expressed in EUR. Past performance or achievement is not indicative of current or future performance. • The Lipper Global Mixed Asset EUR Flex category is composed of funds with flexible allocations between variable income and fixed income securities. The objective of the fund manager is to achieve the highest possible returns by freely changing risk degrees according to current market conditions. It may be possible that, dependent on market conditions, the portfolio of a mixed asset flexible fund is fully invested in only one of the asset classes above. Reference currency exposed securities are over weighted. Investments are limited to country/region and reference currency. • Morningstar Europe OE EUR Flexible Allocation - Global: EUR Flexible Allocation – Global funds have a largely unconstrained mandate to invest globally in a range of asset types for an EUR-based investor. Morningstar Category Index: 50% Barclays Euro Agg Bond TR & 50% FTSE World TR. Parvest Diversified Dynamic 02/06/2017 17
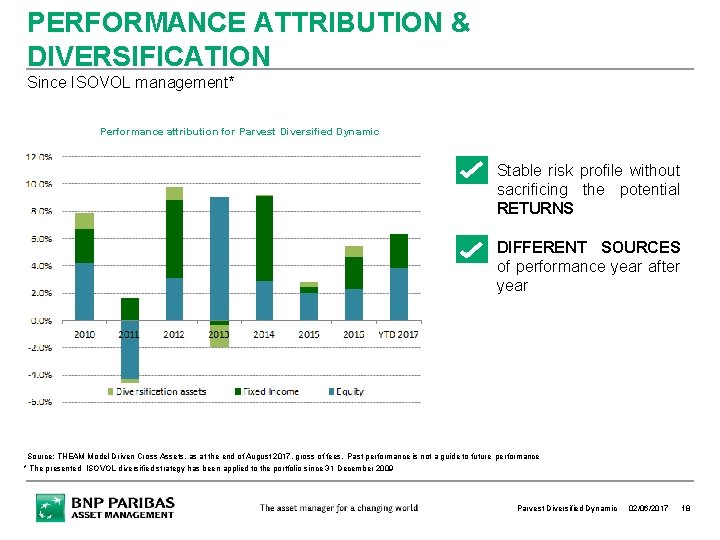
PERFORMANCE ATTRIBUTION & DIVERSIFICATION Since ISOVOL management* Performance attribution for Parvest Diversified Dynamic • Stable risk profile without sacrificing the potential RETURNS • DIFFERENT SOURCES of performance year after year Source: THEAM Model Driven Cross Assets, as at the end of August 2017, gross of fees. Past performance is not a guide to future performance * The presented ISOVOL diversified strategy has been applied to the portfolio since 31 December 2009 Parvest Diversified Dynamic 02/06/2017 18
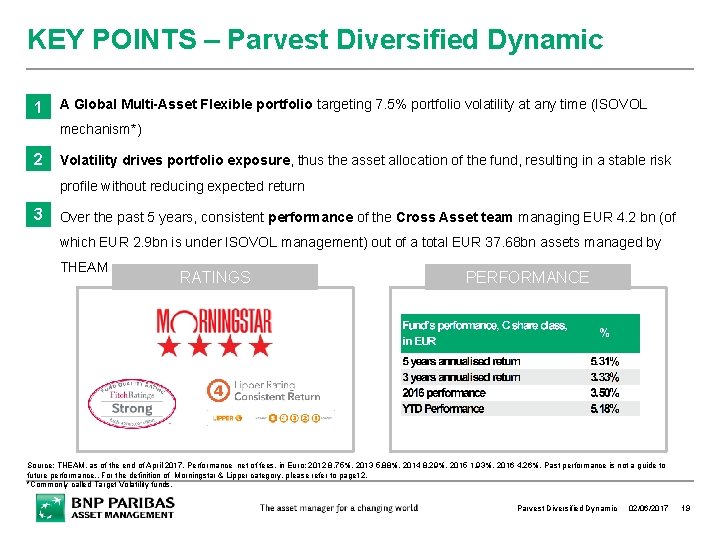
KEY POINTS – Parvest Diversified Dynamic 1 A Global Multi-Asset Flexible portfolio targeting 7. 5% portfolio volatility at any time (ISOVOL mechanism*) 2 Volatility drives portfolio exposure, thus the asset allocation of the fund, resulting in a stable risk profile without reducing expected return 3 Over the past 5 years, consistent performance of the Cross Asset team managing EUR 4. 2 bn (of which EUR 2. 9 bn is under ISOVOL management) out of a total EUR 37. 68 bn assets managed by THEAM RATINGS PERFORMANCE Source: THEAM, as of the end of April 2017. Performance net of fees, in Euro: 2012 8. 75%, 2013 5. 88%, 2014 8. 29%, 2015 1. 93%, 2016 4. 26%. Past performance is not a guide to future performance. . For the definition of Morningstar & Lipper category, please refer to page 12. *Commonly called Target Volatility funds. Parvest Diversified Dynamic 02/06/2017 19
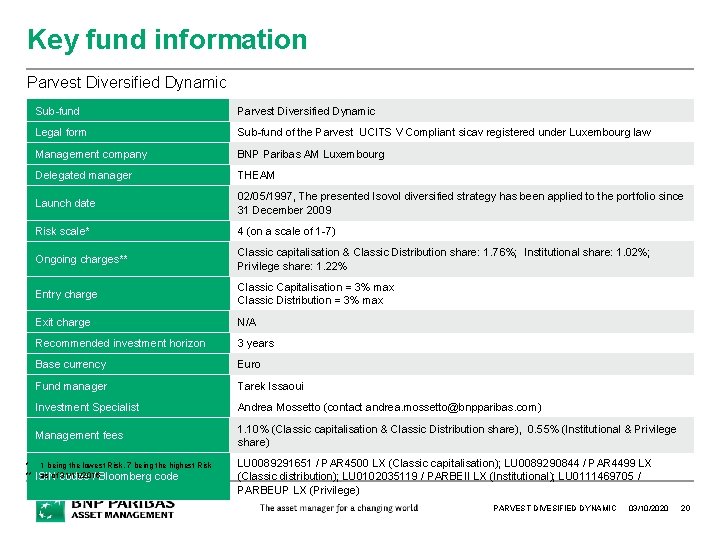
Key fund information Parvest Diversified Dynamic * ** Sub-fund Parvest Diversified Dynamic Legal form Sub-fund of the Parvest UCITS V Compliant sicav registered under Luxembourg law Management company BNP Paribas AM Luxembourg Delegated manager THEAM Launch date 02/05/1997, The presented Isovol diversified strategy has been applied to the portfolio since 31 December 2009 Risk scale* 4 (on a scale of 1 -7) Ongoing charges** Classic capitalisation & Classic Distribution share: 1. 76%; Institutional share: 1. 02%; Privilege share: 1. 22% Entry charge Classic Capitalisation = 3% max Classic Distribution = 3% max Exit charge N/A Recommended investment horizon 3 years Base currency Euro Fund manager Tarek Issaoui Investment Specialist Andrea Mossetto (contact andrea. mossetto@bnpparibas. com) Management fees 1. 10% (Classic capitalisation & Classic Distribution share), 0. 55% (Institutional & Privilege share) 1 being the lowest Risk, 7 being the highest Risk as of 31/11/2016 ISIN codes / Bloomberg code LU 0089291651 / PAR 4500 LX (Classic capitalisation); LU 0089290844 / PAR 4499 LX (Classic distribution); LU 0102035119 / PARBEII LX (Institutional); LU 0111469705 / PARBEUP LX (Privilege) PARVEST DIVESIFIED DYNAMIC 03/10/2020 20
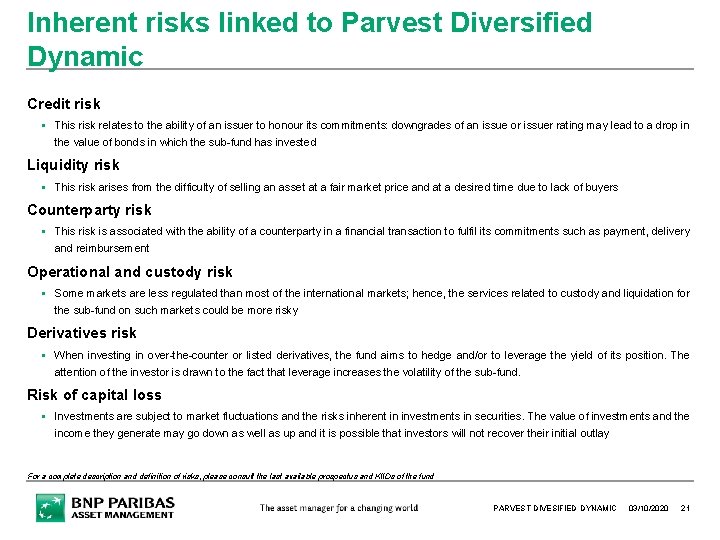
Inherent risks linked to Parvest Diversified Dynamic Credit risk This risk relates to the ability of an issuer to honour its commitments: downgrades of an issue or issuer rating may lead to a drop in the value of bonds in which the sub-fund has invested Liquidity risk This risk arises from the difficulty of selling an asset at a fair market price and at a desired time due to lack of buyers Counterparty risk This risk is associated with the ability of a counterparty in a financial transaction to fulfil its commitments such as payment, delivery and reimbursement Operational and custody risk Some markets are less regulated than most of the international markets; hence, the services related to custody and liquidation for the sub-fund on such markets could be more risky Derivatives risk When investing in over-the-counter or listed derivatives, the fund aims to hedge and/or to leverage the yield of its position. The attention of the investor is drawn to the fact that leverage increases the volatility of the sub-fund. Risk of capital loss Investments are subject to market fluctuations and the risks inherent in investments in securities. The value of investments and the income they generate may go down as well as up and it is possible that investors will not recover their initial outlay For a complete description and definition of risks, please consult the last available prospectus and KIIDs of the fund PARVEST DIVESIFIED DYNAMIC 03/10/2020 21
Contacts IF YOU HAVE ANY QUESTIONS, RECOMMANDATIONS OR WANT MORE DETAILS ON OUR FUND RANGE… PLEASE FEEL FREE TO CONTACT THEAM INVESTMENT SPECIALISTS TEAM Andrea MOSSETTO Senior Investment Specialist THEAM Model Driven Cross Asset, Paris : @Amossetto : andrea. mossetto@bnpparibas. com : Andrea Mossetto THEAM Investment Specialists Team THEAM, Paris : @ B N P P I P _ C O M : theam. investmentspecialists@bnpparibas. com : THEAM PARVEST DIVESIFIED DYNAMIC 03/10/2020 22
3 APPENDIX 03/10/2020 23
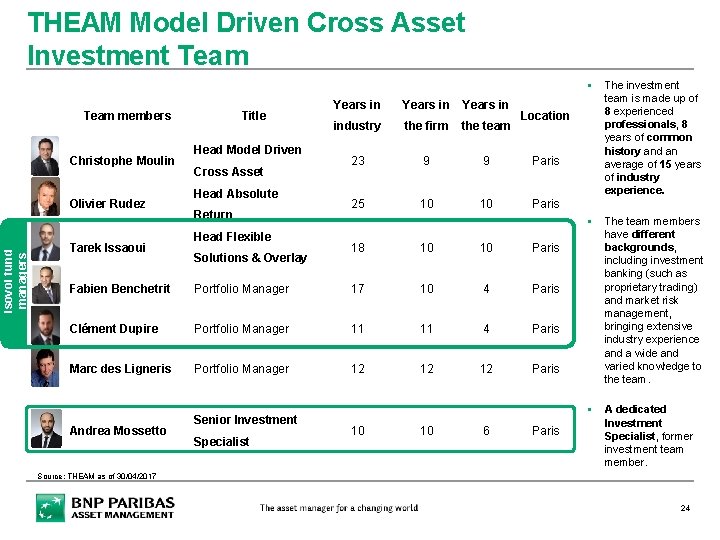
THEAM Model Driven Cross Asset Investment Team members Christophe Moulin Isovol fund managers Olivier Rudez Tarek Issaoui Title Head Model Driven Cross Asset Head Absolute Return Head Flexible Solutions & Overlay Years in industry the firm the team 23 9 9 Paris 25 10 10 Paris 18 10 10 Paris Portfolio Manager 17 10 4 Paris Clément Dupire Portfolio Manager 11 11 4 Paris Marc des Ligneris Portfolio Manager 12 12 12 Paris Andrea Mossetto Specialist 10 10 6 The investment team is made up of 8 experienced professionals, 8 years of common history and an average of 15 years of industry experience. The team members have different backgrounds, including investment banking (such as proprietary trading) and market risk management, bringing extensive industry experience and a wide and varied knowledge to the team. A dedicated Investment Specialist, former investment team member. Location Fabien Benchetrit Senior Investment Paris Source: THEAM as of 30/04/2017 24
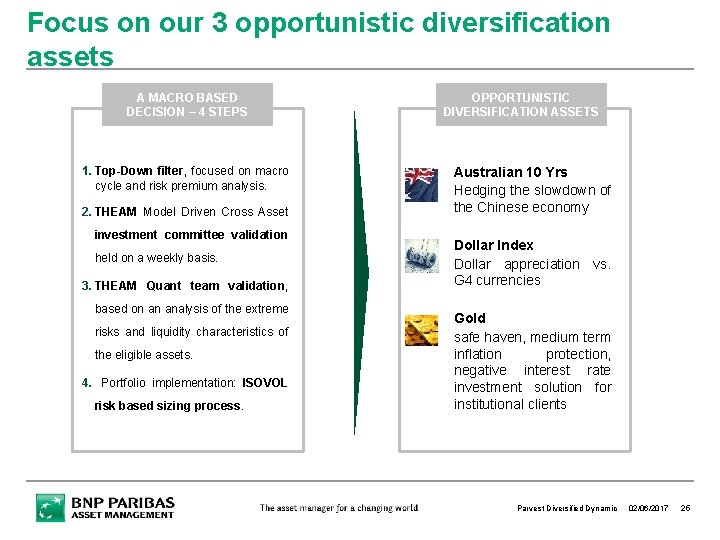
Focus on our 3 opportunistic diversification assets A MACRO BASED DECISION – 4 STEPS 1. Top-Down filter, focused on macro cycle and risk premium analysis. 2. THEAM Model Driven Cross Asset investment committee validation held on a weekly basis. 3. THEAM Quant team validation, based on an analysis of the extreme risks and liquidity characteristics of the eligible assets. 4. Portfolio implementation: ISOVOL risk based sizing process. OPPORTUNISTIC DIVERSIFICATION ASSETS Australian 10 Yrs Hedging the slowdown of the Chinese economy Dollar Index Dollar appreciation vs. G 4 currencies Gold safe haven, medium term inflation protection, negative interest rate investment solution for institutional clients Parvest Diversified Dynamic 02/06/2017 25
Disclaimers BNP PARIBAS ASSET MANAGEMENT UK Limited, “the investment company”, is authorised and regulated by the Financial Conduct Authority. Registered in England No: 02474627, registered office: 5 Aldermanbury Square, London, England, EC 2 V 7 BP, United Kingdom. This material is produced for information purposes only and does not constitute: 1. 2. an offer to buy nor a solicitation to sell, nor shall it form the basis of or be relied upon in connection with any contract or commitment whatsoever or investment advice. This material makes reference to certain financial instruments authorised and regulated in their jurisdiction(s) of incorporation. No action has been taken which would permit the public offering of the financial instrument(s) in any other jurisdiction, except as indicated in the most recent prospectus and the Key Investor Information Document (KIID) of the relevant financial instrument(s) where such action would be required, in particular, in the United States, to US persons (as such term is defined in Regulation S of the United States Securities Act of 1933). Prior to any subscription in a country in which such financial instrument(s) is/are registered, investors should verify any legal constraints or restrictions there may be in connection with the subscription, purchase, possession or sale of the financial instrument(s). Investors considering subscribing to the financial instrument(s) should read carefully the most recent prospectus and Key Investor Information Document (KIID) and consult the financial instrument(s’) most recent financial reports. These documents are available on the website. Opinions included in this material constitute the judgement of the investment management company at the time specified and may be subject to change without notice. The investment management company is not obliged to update or alter the information or opinions contained within this material. Investors should consult their own legal and tax advisors in respect of legal, accounting, domicile and tax advice prior to investing in the financial instrument(s) in order to make an independent determination of the suitability and consequences of an investment therein, if permitted. Please note that different types of investments, if contained within this material, involve varying degrees of risk and there can be no assurance that any specific investment may either be suitable, appropriate or profitable for an investor’s investment portfolio. Given the economic and market risks, there can be no assurance that the financial instrument(s) will achieve its/their investment objectives. Returns may be affected by, amongst other things, investment strategies or objectives of the financial instrument(s) and material market and economic conditions, including interest rates, market terms and general market conditions. The different strategies applied to financial instruments may have a significant effect on the results presented in this material. Past performance is not a guide to future performance and the value of the investments in financial instrument(s) may go down as well as up. Investors may not get back the amount they originally invested. The performance data, as applicable, reflected in this material, do not take into account the commissions, costs incurred on the issue and redemption and taxes. This document is directed only at person(s) who have professional experience in matters relating to investments (“relevant persons”). Any investment or investment activity to which this document relates is available only to and will be engaged in only with Professional Clients as defined in the rules of the Financial Conduct Authority. Any person who is not a relevant person should not act or rely on this document or any of its contents. All information referred to in the present document is available on www. bnpparibas-am. com PARVEST DIVESIFIED DYNAMIC 03/10/2020 26
Disclaimers Data Source - © 2017 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. Past performance is no guarantee of future results. Morningstars rank from 1 to 5, with the top ranking being 5 stars. All Morningstar ratings shown in this document are for Classic capitalizing shares, as of June 30, 2017. (to adapt) Lipper Ratings do not constitute and are not intended to constitute investment advice or an offer to sell or the solicitation of an offer to buy any security of any entity in any jurisdiction. As a result, you should not make an investment decision on the basis of this information. Rather, you should use Lipper Ratings for informational purposes only. Lipper is not responsible for the accuracy, reliability or completeness of the information that you obtain from Lipper. In addition, Lipper will not be liable for any loss or damage resulting from information obtained from Lipper or any of its affiliates. © Thomson Reuters 2017. All rights reserved. Lipper ratings range from 1 to 5, with 5 corresponding to ‘Leader’. PARVEST DIVESIFIED DYNAMIC 03/10/2020 27