Presentation of financial statements The auditors review Presented
- Slides: 20
Presentation of financial statements The auditor’s review Presented by: Tahmeen Ahmad (ACA)
Purpose of Financial Statements • Financial statements are: “Structured representation of the financial position and financial performance of an entity. ” • Objective: To provide information about: – the financial position, – financial performance, and – cash flows of an entity that is useful to a wide range of users in making economic decisions.
The Framework • The International Financial Reporting Standards (IFRS), in particular guidance on presentation and disclosure • Local statutory requirements – The Companies’ Ordinance, 1984, in particular the Fourth/ Fifth Schedule for presentation purposes – Directives of the regulatory bodies – Industry specific legislation – Generally accepted accounting principles
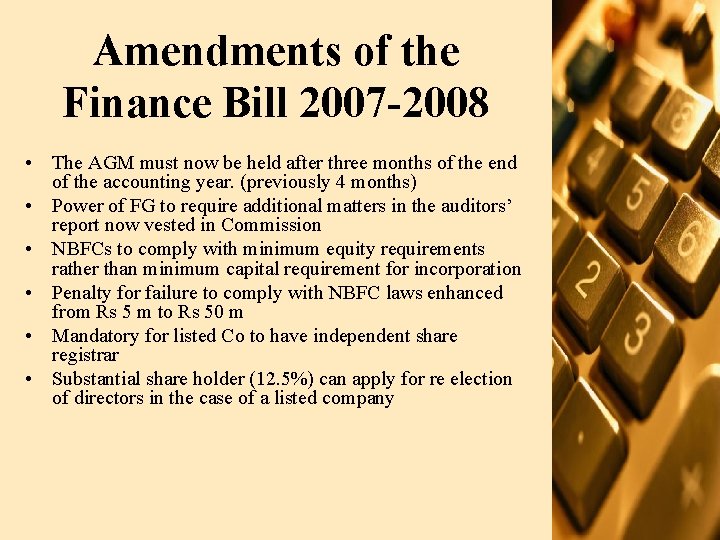
Amendments of the Finance Bill 2007 -2008 • The AGM must now be held after three months of the end of the accounting year. (previously 4 months) • Power of FG to require additional matters in the auditors’ report now vested in Commission • NBFCs to comply with minimum equity requirements rather than minimum capital requirement for incorporation • Penalty for failure to comply with NBFC laws enhanced from Rs 5 m to Rs 50 m • Mandatory for listed Co to have independent share registrar • Substantial share holder (12. 5%) can apply for re election of directors in the case of a listed company
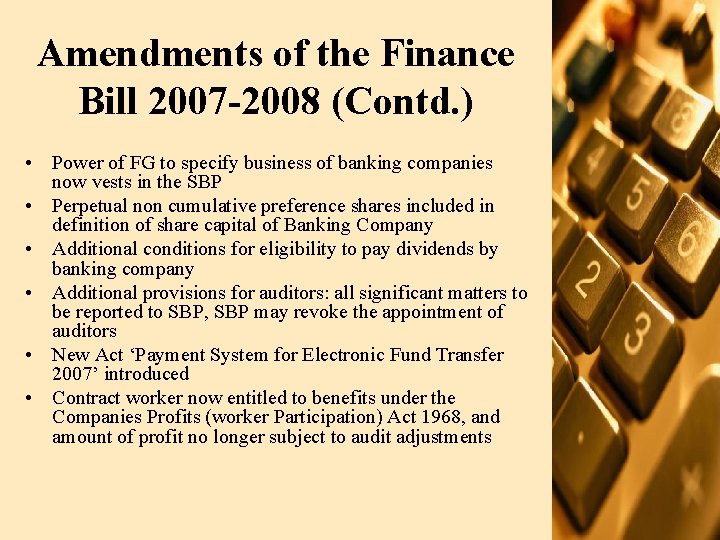
Amendments of the Finance Bill 2007 -2008 (Contd. ) • Power of FG to specify business of banking companies now vests in the SBP • Perpetual non cumulative preference shares included in definition of share capital of Banking Company • Additional conditions for eligibility to pay dividends by banking company • Additional provisions for auditors: all significant matters to be reported to SBP, SBP may revoke the appointment of auditors • New Act ‘Payment System for Electronic Fund Transfer 2007’ introduced • Contract worker now entitled to benefits under the Companies Profits (worker Participation) Act 1968, and amount of profit no longer subject to audit adjustments
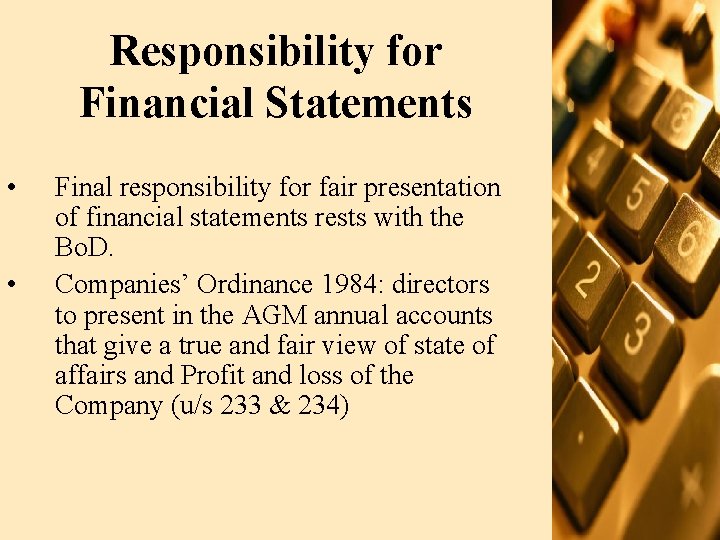
Responsibility for Financial Statements • • Final responsibility for fair presentation of financial statements rests with the Bo. D. Companies’ Ordinance 1984: directors to present in the AGM annual accounts that give a true and fair view of state of affairs and Profit and loss of the Company (u/s 233 & 234)
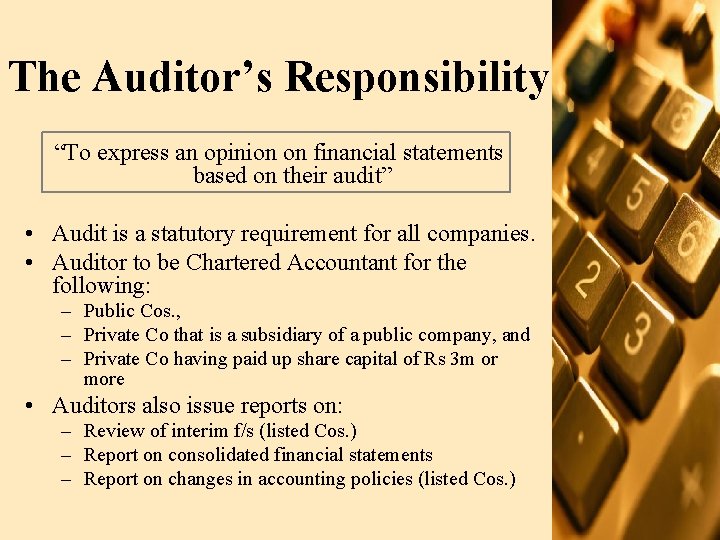
The Auditor’s Responsibility “To express an opinion on financial statements based on their audit” • Audit is a statutory requirement for all companies. • Auditor to be Chartered Accountant for the following: – Public Cos. , – Private Co that is a subsidiary of a public company, and – Private Co having paid up share capital of Rs 3 m or more • Auditors also issue reports on: – Review of interim f/s (listed Cos. ) – Report on consolidated financial statements – Report on changes in accounting policies (listed Cos. )
The Auditor’s Responsibility (contd. ) – Review of compliance with Best Practices of Code of Corporate Governance (Listed Cos. ) – Assets, liabilities, profits and losses, share capital and its breakup value for prospectus (Schedule II) – Certification of financial information in statutory report (for Co limited by shares etc) – Significant issues identified during audits (listed Cos) – Industry specific reports (basel II, profit rate verification, credit review reports etc)
Components of Financial Statements • General purpose financial statements comprise of: – Balance Sheet – Profit and loss account – Statement of changes in equity – Cash flow statement – Notes to the financial statements
Components of Financial Statements (contd. ) Listed Cos. – Balance sheet – Profit and loss – Statement of changes in equity – Cash flow – Notes • 4 th schedule applies • This includes private companies and public non-listed companies that are subsidiaries of listed companies Non Listed Cos. – Balance sheet – Profit and loss – Notes • 5 th schedule applies
The Annual Report – other information – Other information includes the following: TYPE OF REPORT REQUIREMENT OF: Director’s report Companies’ Ordinance 1984 Statement of Compliance with Code of corporate governance Listing regulations Company information including financial progress reports, management structure etc – The auditor may review the information in relation to the accounts under audit
Review of the Financial Statements • Variation in presentation may arise from difference in: – – Nature of business of the entity Type of Company (listed, non-listed public, private) Consolidated or unconsolidated accounts Management judgement on matters not specified by statute / standards
Review of the Financial Statements (Contd. ) • • • Identification of each f/s component Name of reporting entity Specified if accounts related to group entity Balance sheet date/period of account Presentation currency Level of rounding used in presenting amounts Comparatives F/s amounts supported by adequate notes Each F/s component signed by director and chief executive.
Review of Balance Sheet Presentation • Please review the sample balance sheet: • Our discussion will follow the line items: ASSETS • Fixed Assets • Long term investments • Long term loans and advances • Long term deposits and prepayments • Current assets – – – – – Stores and spares Stock in trade Trade debts Loans and advances Trade deposits, prepayments Interest accrued Other receivables Financial assets Tax refunds Cash and bank balances
Balance Sheet (Contd. ) SHARE CAPITAL & RESERVES ● Share capital ● Capital reserves ● Revenue reserves ● Surplus on revaluation of fixed assets NON CURRENT LIABILITIES ● Long term financing ● Debentures ● Liabilities against assets subject to finance lease ● Long term Murabaha ● Long term Deposits ● Deferred Liabilities
Balance Sheet (Contd. ) CURRENT LIABILITIES • • • Trade and other payables Interest, profit, markup accrued Short term borrowings Current portion of long term murabaha Provisions for taxation CONTINGENCIES AND COMMITMENTS
Review of Income Statement Presentation • Please review the sample profit and loss account • Line wise discussion follows: TURNOVER EXPENSES • Cost of sales • Distribution cost • Administrative expenses • Other operating expenses • Finance cost OTHER OPERATING INCOME • Income from financial assets • Income from investments/debts of related parties • Income from assets other than financial assets
Review of Cash Flow Presentation • Please review sample cash flow statements • Cash flows may be prepared under the indirect or direct method. • These methods affect the method of arriving at operating cash flows only • Discussion will follow the line items of the sample cash flow: – – from operating activities from investing activities from financing activities cash& equivalents • Cash flows are prepared in accordance with the requirements of IAS 7
Review of Statement of Changes in Equity • Please review sample statements of changes in equity • Statement may either show: – All changes in equity – Changes other than transactions with equity holders
Variations for Industries • Variations can be seen in presentation & disclosures of f/s for different industries, eg: – – – – Banking Companies Manufacturing companies Telecom industry Petroleum exploration and production Funds Insurance companies Leasing Companies and other NBFCs