Part I An overview of Chocolate Confectionery Industry
- Slides: 15
Part I: • An overview of Chocolate & Confectionery Industry of Pakistan Part II: • Practical aspects of sales & distribution of FMCG
Branded Chocolate and Confectionery Industry of Pakistan 2009 www. saifdewan. wordpress. com Via Google - Chocolate and Confectionery Pakistan
Chocolate & Confectionery - Pakistan • Chocolate and Confectionery Industry – An overview • Close estimates of sales turnover- major players • Characteristics, Distribution & Selling Strategy • Channels’ Margin • Popular Brands and Price points • Drivers, Challenges and trends
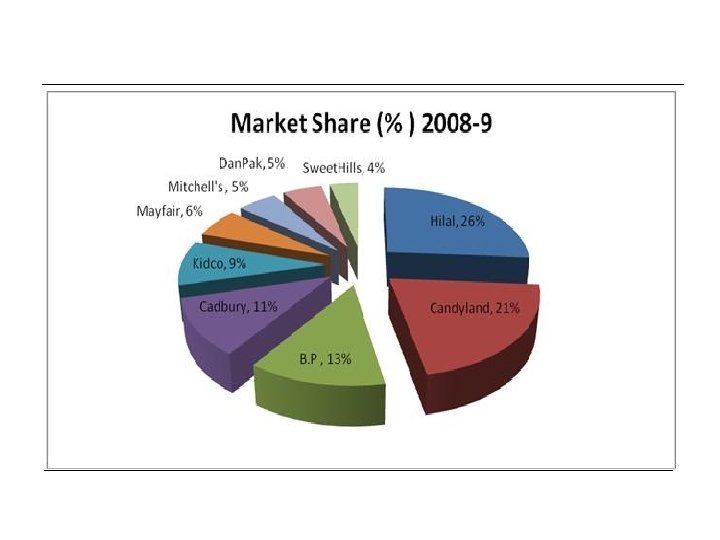
Overview of Industry • Enjoyed an emerging and growing trend in recent past • Yet its size and growth pattern is inconsequential to Asia-pacific region • Average annual growth rate 6. 5% to 7. 5% during 20022008. • Domestic brands dominates accounting for more than 85% market share. • Split into organized (branded) sector and un-organized (generic) sector. • Branded sector – monopolistic in nature , with 9 -10 prominent and active players • 80% industry share – being enjoyed by 5 players
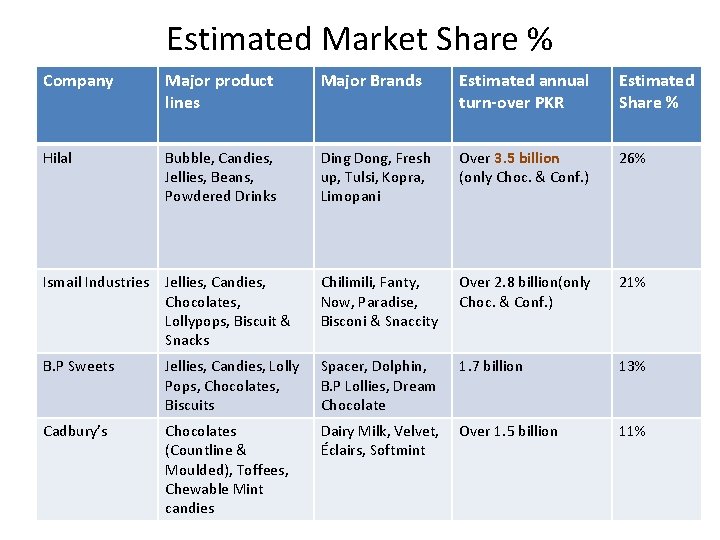
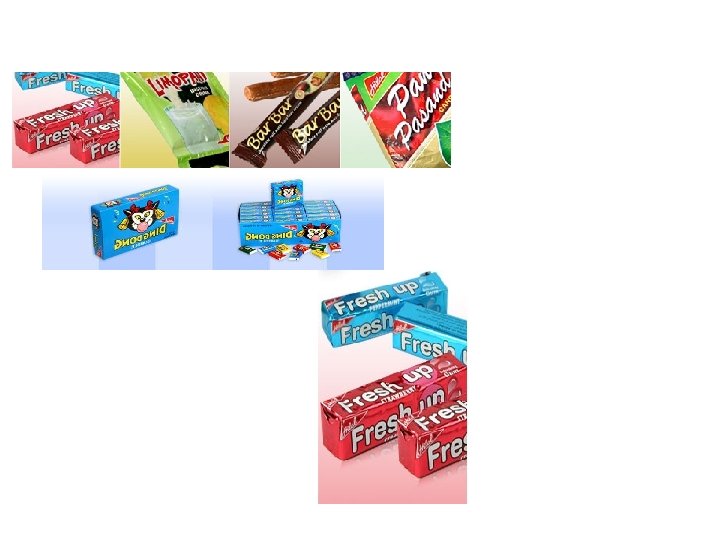
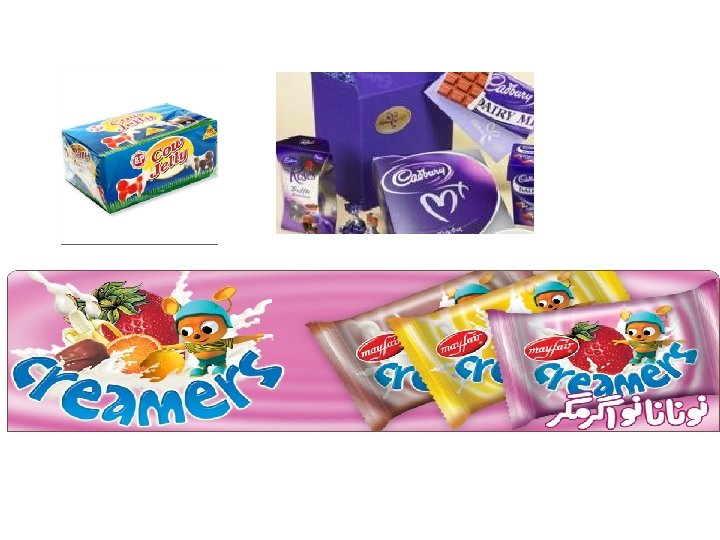
Estimated Market Share % Company Major product lines Major Brands Estimated annual turn-over PKR Estimated Share % Hilal Bubble, Candies, Jellies, Beans, Powdered Drinks Ding Dong, Fresh up, Tulsi, Kopra, Limopani Over 3. 5 billion (only Choc. & Conf. ) 26% Ismail Industries Jellies, Candies, Chocolates, Lollypops, Biscuit & Snacks Chilimili, Fanty, Now, Paradise, Bisconi & Snaccity Over 2. 8 billion(only Choc. & Conf. ) 21% B. P Sweets Jellies, Candies, Lolly Pops, Chocolates, Biscuits Spacer, Dolphin, B. P Lollies, Dream Chocolate 1. 7 billion 13% Cadbury’s Chocolates (Countline & Moulded), Toffees, Chewable Mint candies Dairy Milk, Velvet, Éclairs, Softmint Over 1. 5 billion 11%
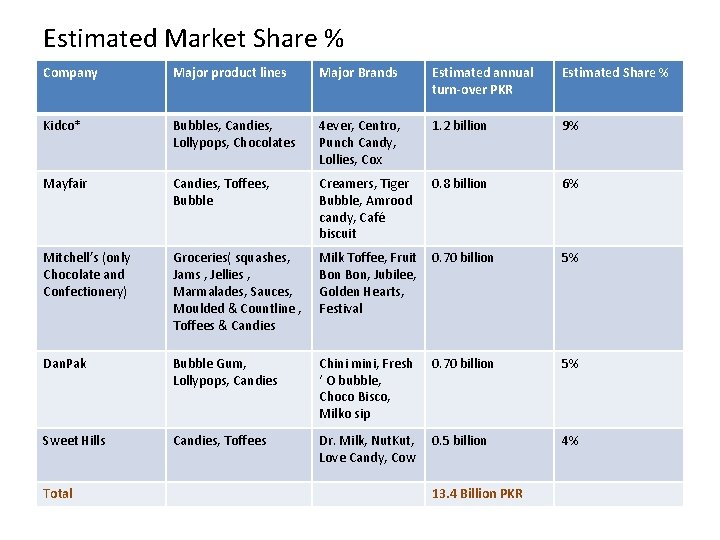
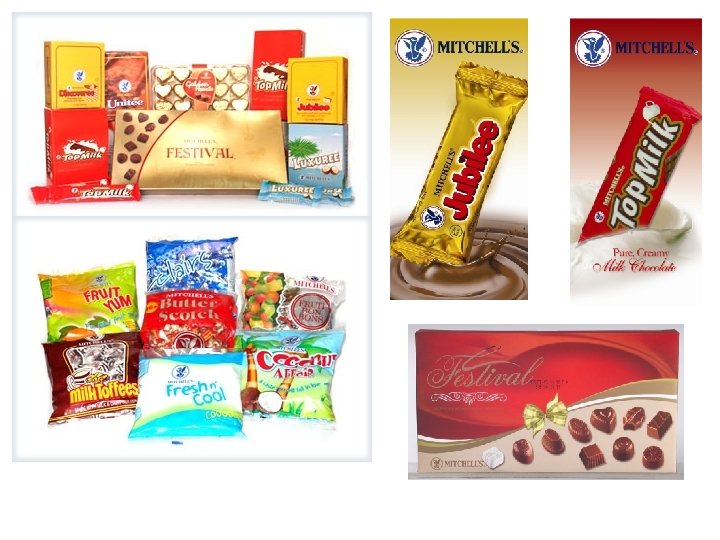
Estimated Market Share % Company Major product lines Major Brands Estimated annual turn-over PKR Estimated Share % Kidco* Bubbles, Candies, Lollypops, Chocolates 4 ever, Centro, Punch Candy, Lollies, Cox 1. 2 billion 9% Mayfair Candies, Toffees, Bubble Creamers, Tiger Bubble, Amrood candy, Café biscuit 0. 8 billion 6% Mitchell’s (only Chocolate and Confectionery) Groceries( squashes, Jams , Jellies , Marmalades, Sauces, Moulded & Countline , Toffees & Candies Milk Toffee, Fruit Bon, Jubilee, Golden Hearts, Festival 0. 70 billion 5% Dan. Pak Bubble Gum, Lollypops, Candies Chini mini, Fresh ‘ O bubble, Choco Bisco, Milko sip 0. 70 billion 5% Sweet Hills Candies, Toffees Dr. Milk, Nut. Kut, Love Candy, Cow 0. 5 billion 4% Total 13. 4 Billion PKR
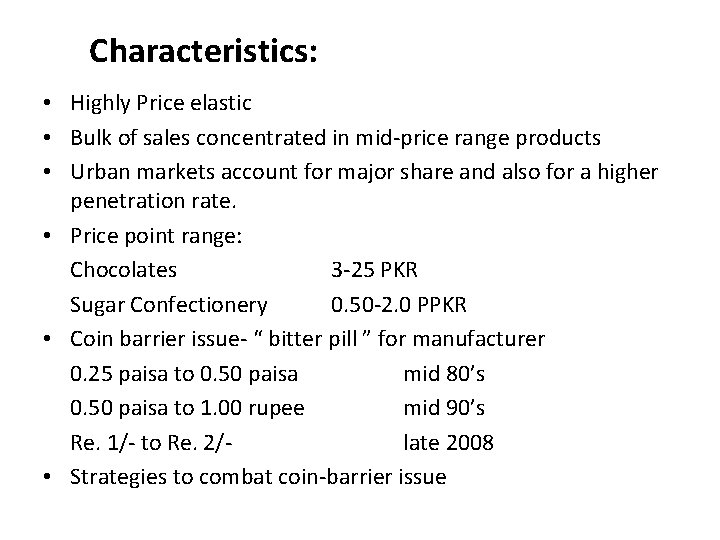
Characteristics: • Highly Price elastic • Bulk of sales concentrated in mid-price range products • Urban markets account for major share and also for a higher penetration rate. • Price point range: Chocolates 3 -25 PKR Sugar Confectionery 0. 50 -2. 0 PPKR • Coin barrier issue- “ bitter pill ” for manufacturer 0. 25 paisa to 0. 50 paisa mid 80’s 0. 50 paisa to 1. 00 rupee mid 90’s Re. 1/- to Re. 2/late 2008 • Strategies to combat coin-barrier issue
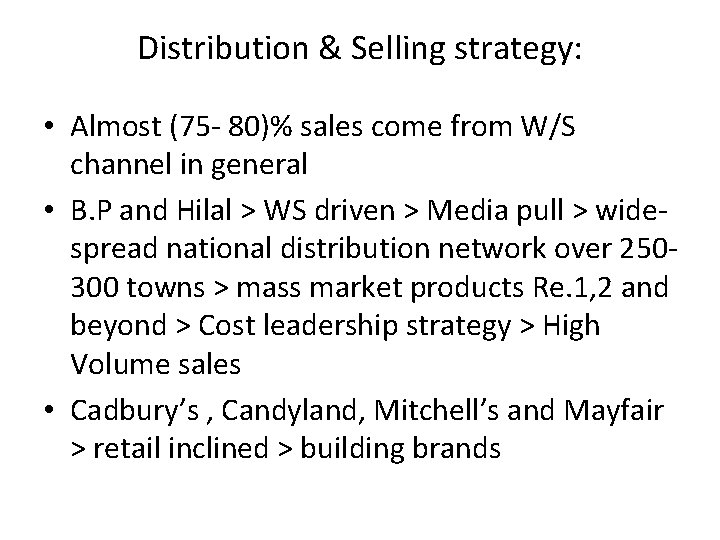
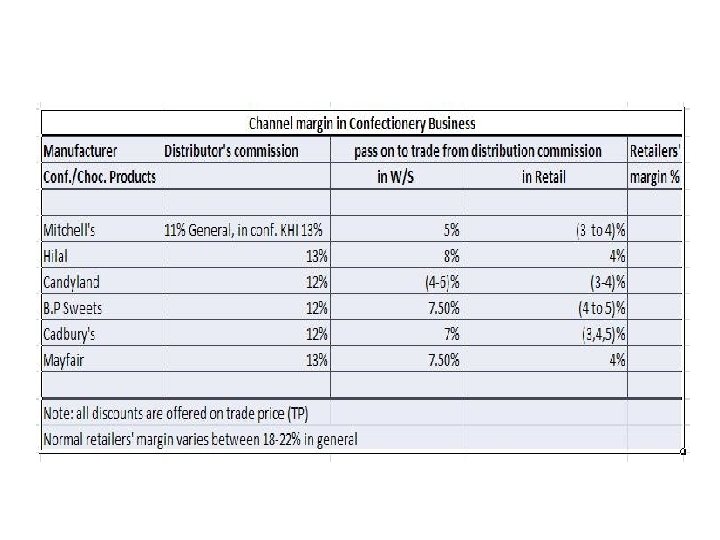
Distribution & Selling strategy: • Almost (75 - 80)% sales come from W/S channel in general • B. P and Hilal > WS driven > Media pull > widespread national distribution network over 250300 towns > mass market products Re. 1, 2 and beyond > Cost leadership strategy > High Volume sales • Cadbury’s , Candyland, Mitchell’s and Mayfair > retail inclined > building brands
Drivers, Challenges & Trend • Drivers: