HOW TO DESIGN INNOVATIVE RETIREMENT PRODUCTS FOR ACCUMULATION
- Slides: 19
HOW TO DESIGN INNOVATIVE RETIREMENT PRODUCTS FOR ACCUMULATION PERIOD Ansgar Lürwer 17. 11. 2017 / Amsterdam
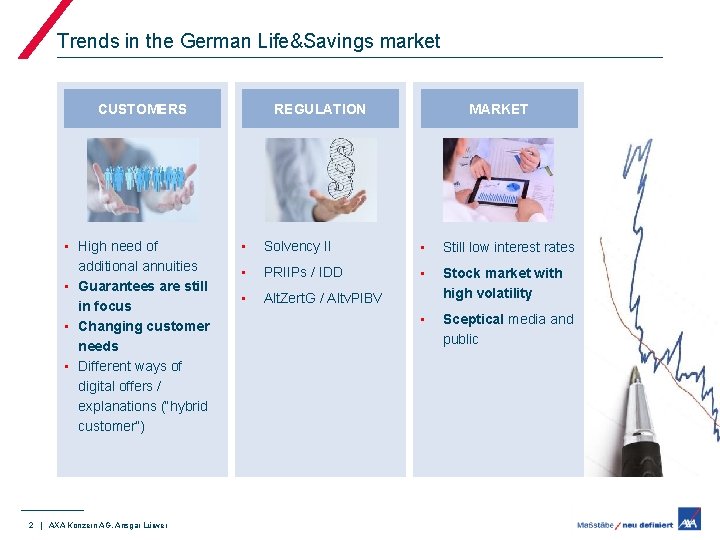
Trends in the German Life&Savings market • High need of additional annuities • Guarantees are still in focus • Changing customer needs • Different ways of digital offers / explanations (“hybrid customer“) 2 | AXA Konzern AG, Ansgar Lürwer MARKET REGULATION CUSTOMERS • Solvency II • Still low interest rates • PRIIPs / IDD • • Alt. Zert. G / Altv. PIBV Stock market with high volatility • Sceptical media and public
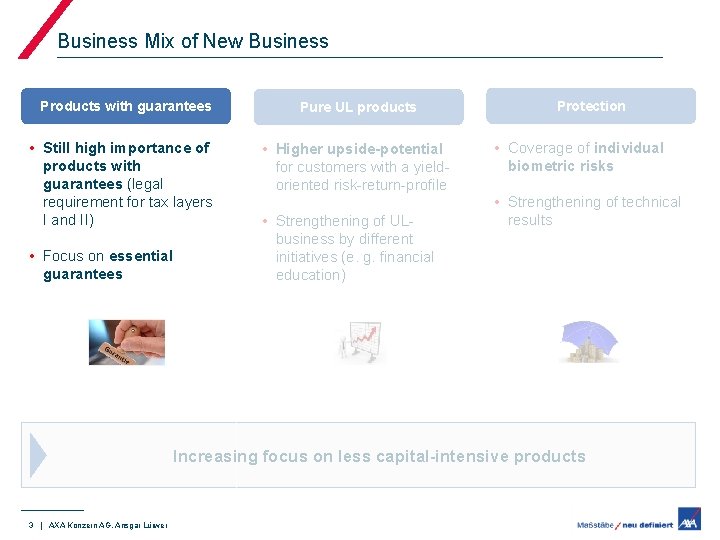
Business Mix of New Business Products with guarantees • Still high importance of products with guarantees (legal requirement for tax layers I and II) • Focus on essential guarantees Pure UL products • Higher upside-potential for customers with a yieldoriented risk-return-profile • Strengthening of ULbusiness by different initiatives (e. g. financial education) Protection • Coverage of individual biometric risks • Strengthening of technical results Increasing focus on less capital-intensive products 3 | AXA Konzern AG, Ansgar Lürwer
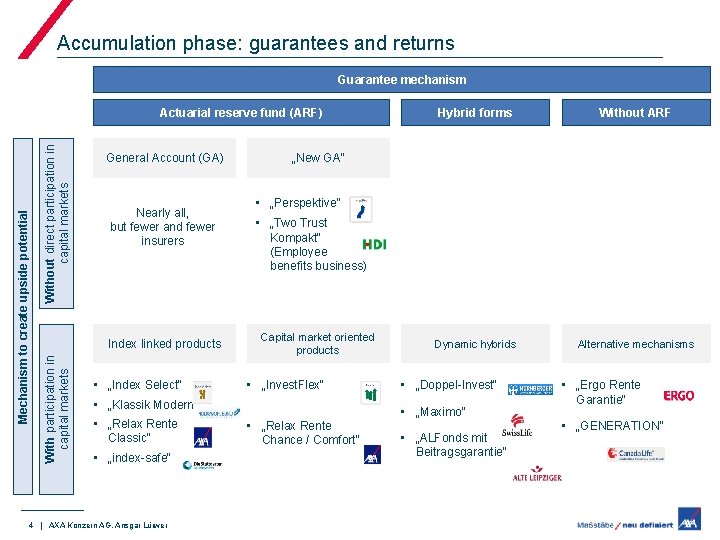
Accumulation phase: guarantees and returns Guarantee mechanism Without direct participation in capital markets General Account (GA) Nearly all, but fewer and fewer insurers Index linked products With participation in capital markets Mechanism to create upside potential Actuarial reserve fund (ARF) • „Index Select“ • „index-safe“ 4 | AXA Konzern AG, Ansgar Lürwer Without ARF Dynamic hybrids Alternative mechanisms „New GA“ • „Perspektive“ • „Two Trust Kompakt“ (Employee benefits business) Capital market oriented products • „Invest. Flex“ • „Klassik Modern“ • „Relax Rente Classic“ Hybrid forms • „Doppel-Invest“ • „Maximo“ • „Relax Rente Chance / Comfort“ • „ALFonds mit Beitragsgarantie“ • „Ergo Rente Garantie“ • „GENERATION“
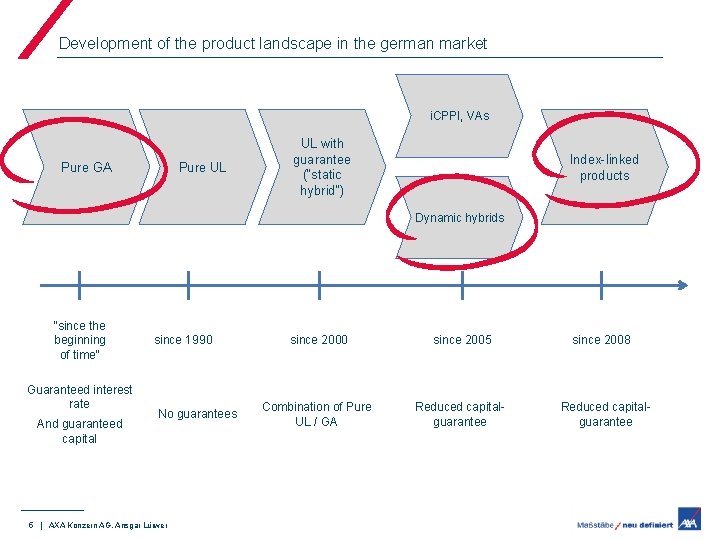
Development of the product landscape in the german market i. CPPI, VAs Pure GA Pure UL UL with guarantee (“static hybrid“) Index-linked products Dynamic hybrids “since the beginning of time“ Guaranteed interest rate And guaranteed capital since 1990 No guarantees 5 | AXA Konzern AG, Ansgar Lürwer since 2000 since 2005 Combination of Pure UL / GA Reduced capitalguarantee since 2008 Reduced capitalguarantee
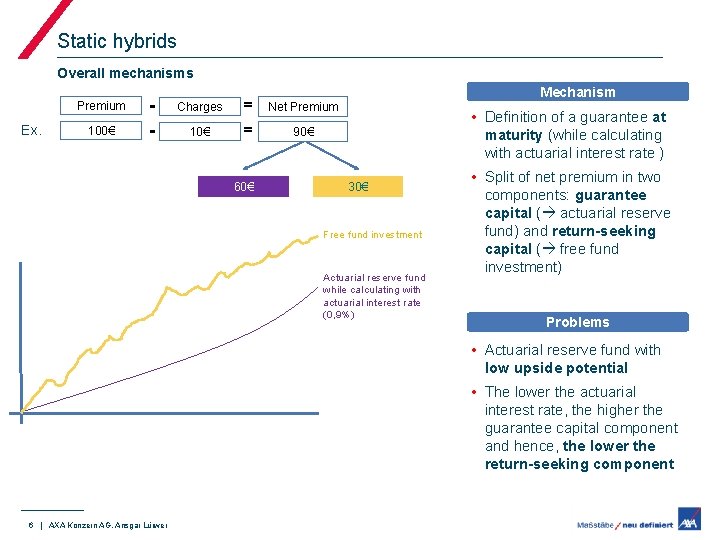
Static hybrids Overall mechanisms Premium Ex. 100€ - Mechanism Charges = Net Premium 10€ = 90€ 60€ • Definition of a guarantee at maturity (while calculating with actuarial interest rate ) 30€ Free fund investment Actuarial reserve fund while calculating with actuarial interest rate (0, 9%) • Split of net premium in two components: guarantee capital ( actuarial reserve fund) and return-seeking capital ( free fund investment) Problems • Actuarial reserve fund with low upside potential • The lower the actuarial interest rate, the higher the guarantee capital component and hence, the lower the return-seeking component 6 | AXA Konzern AG, Ansgar Lürwer
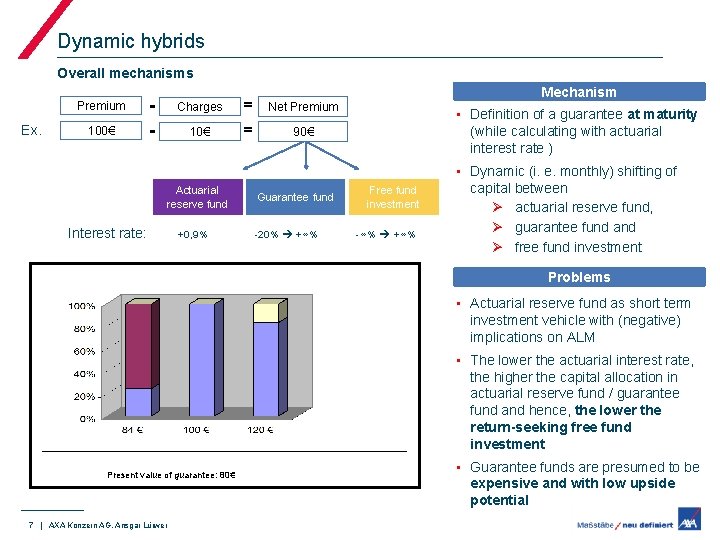
Dynamic hybrids Overall mechanisms Premium Ex. 100€ - = Net Premium 10€ = 90€ Actuarial reserve fund Interest rate: Mechanism Charges +0, 9% Guarantee fund -20% +∞% • Definition of a guarantee at maturity (while calculating with actuarial interest rate ) Free fund investment -∞% +∞% • Dynamic (i. e. monthly) shifting of capital between Ø actuarial reserve fund, Ø guarantee fund and Ø free fund investment Problems • Actuarial reserve fund as short term investment vehicle with (negative) implications on ALM • The lower the actuarial interest rate, the higher the capital allocation in actuarial reserve fund / guarantee fund and hence, the lower the return-seeking free fund investment Present value of guarantee: 80€ 7 | AXA Konzern AG, Ansgar Lürwer • Guarantee funds are presumed to be expensive and with low upside potential
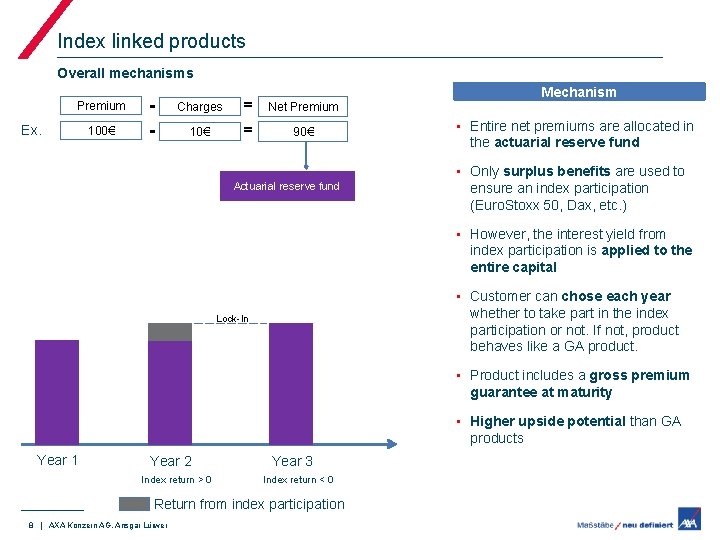
Index linked products Overall mechanisms Premium Ex. 100€ - Mechanism Charges = Net Premium 10€ = 90€ Actuarial reserve fund • Entire net premiums are allocated in the actuarial reserve fund • Only surplus benefits are used to ensure an index participation (Euro. Stoxx 50, Dax, etc. ) • However, the interest yield from index participation is applied to the entire capital • Customer can chose each year whether to take part in the index participation or not. If not, product behaves like a GA product. Lock-In • Product includes a gross premium guarantee at maturity • Higher upside potential than GA products Year 1 Year 2 Index return > 0 Year 3 Index return < 0 Return from index participation 8 | AXA Konzern AG, Ansgar Lürwer
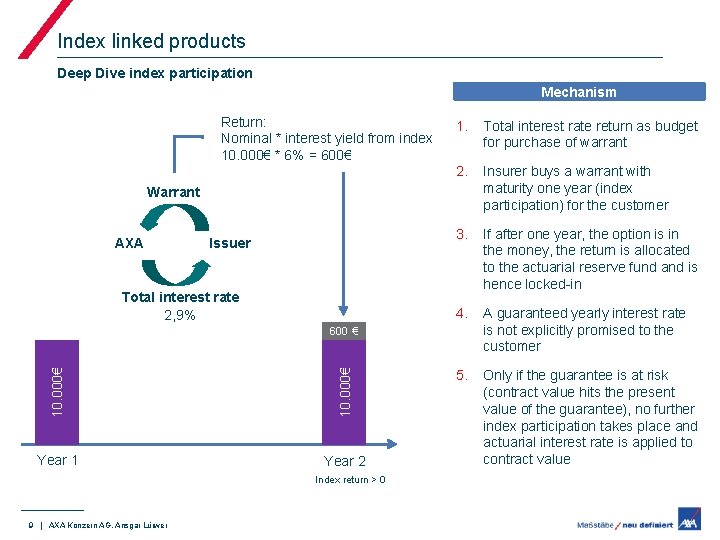
Index linked products Deep Dive index participation Mechanism Return: Nominal * interest yield from index 10. 000€ * 6% = 600€ 1. Total interest rate return as budget for purchase of warrant 2. Insurer buys a warrant with maturity one year (index participation) for the customer 3. If after one year, the option is in the money, the return is allocated to the actuarial reserve fund and is hence locked-in 4. A guaranteed yearly interest rate is not explicitly promised to the customer 5. Only if the guarantee is at risk (contract value hits the present value of the guarantee), no further index participation takes place and actuarial interest rate is applied to contract value Warrant AXA Issuer Total interest rate 2, 9% 10. 000€ 600 € Year 1 Year 2 Index return > 0 9 | AXA Konzern AG, Ansgar Lürwer
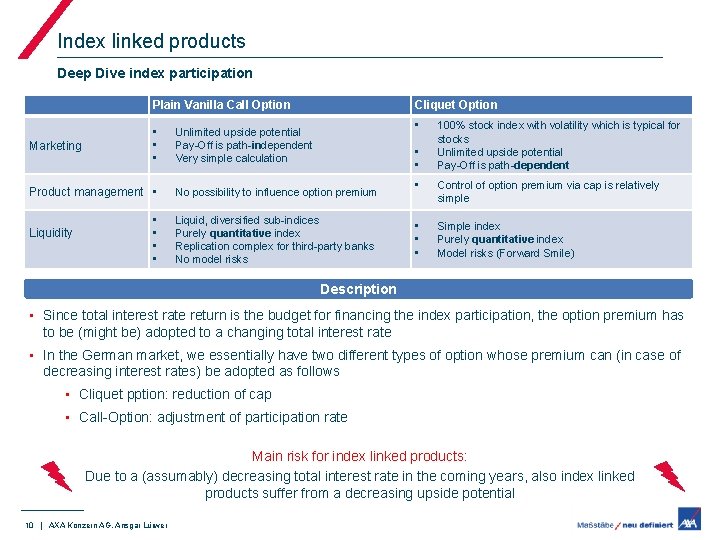
Index linked products Deep Dive index participation Plain Vanilla Call Option Marketing • • • Product management • Liquidity • • Cliquet Option • Unlimited upside potential Pay-Off is path-independent Very simple calculation • • No possibility to influence option premium Liquid, diversified sub-indices Purely quantitative index Replication complex for third-party banks No model risks 100% stock index with volatility which is typical for stocks Unlimited upside potential Pay-Off is path-dependent • Control of option premium via cap is relatively simple • • • Simple index Purely quantitative index Model risks (Forward Smile) Description • Since total interest rate return is the budget for financing the index participation, the option premium has to be (might be) adopted to a changing total interest rate • In the German market, we essentially have two different types of option whose premium can (in case of decreasing interest rates) be adopted as follows • Cliquet pption: reduction of cap • Call-Option: adjustment of participation rate Main risk for index linked products: Due to a (assumably) decreasing total interest rate in the coming years, also index linked products suffer from a decreasing upside potential 10 | AXA Konzern AG, Ansgar Lürwer
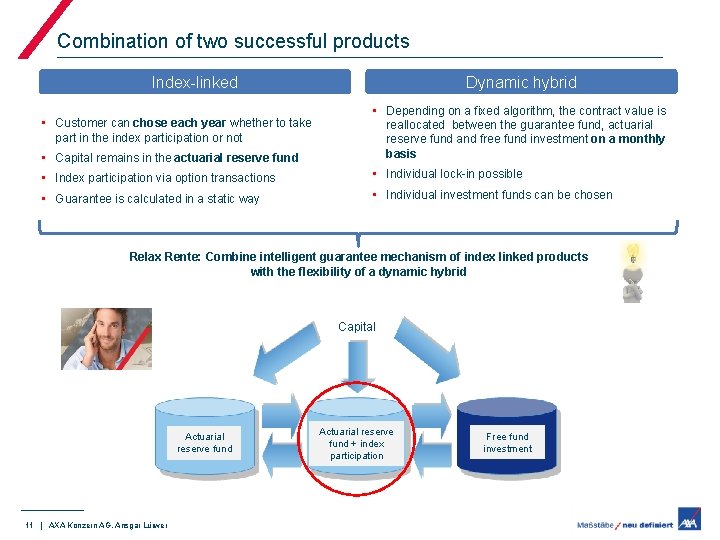
Combination of two successful products Index-linked Dynamic hybrid • Capital remains in the actuarial reserve fund • Depending on a fixed algorithm, the contract value is reallocated between the guarantee fund, actuarial reserve fund and free fund investment on a monthly basis • Index participation via option transactions • Individual lock-in possible • Guarantee is calculated in a static way • Individual investment funds can be chosen • Customer can chose each year whether to take part in the index participation or not Relax Rente: Combine intelligent guarantee mechanism of index linked products with the flexibility of a dynamic hybrid Capital Actuarial reserve fund 11 | AXA Konzern AG, Ansgar Lürwer Actuarial reserve fund + index participation Free fund investment
Next steps in differentiation from competitors: the decumulation phase
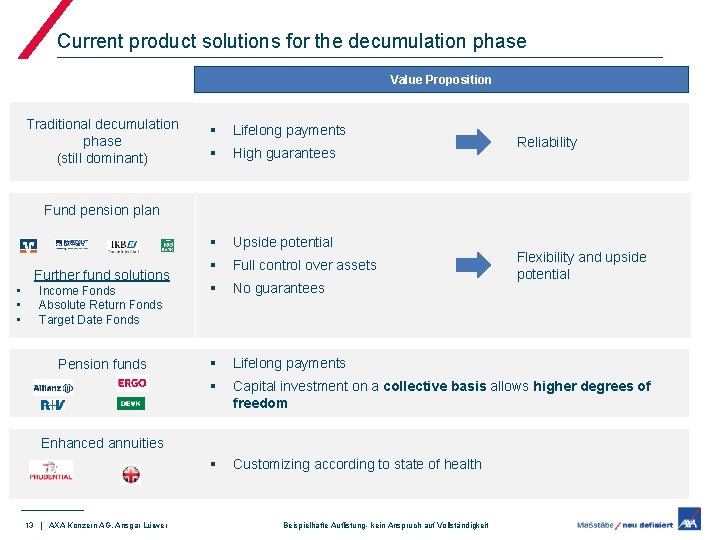
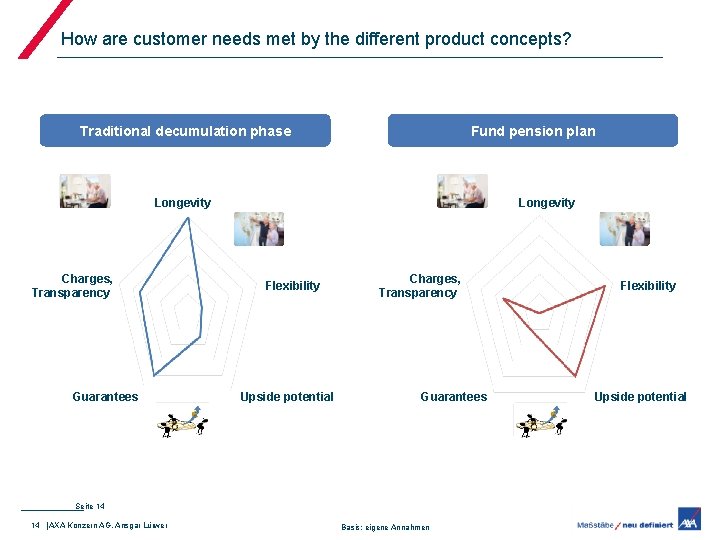
Current product solutions for the decumulation phase Value Proposition Traditional decumulation phase (still dominant) § Lifelong payments § High guarantees § Upside potential § Full control over assets Income Fonds Absolute Return Fonds Target Date Fonds § No guarantees Pension funds § Lifelong payments § Capital investment on a collective basis allows higher degrees of freedom § Customizing according to state of health Reliability Fund pension plan Further fund solutions • • • Enhanced annuities 13 | AXA Konzern AG, Ansgar Lürwer Beispielhafte Auflistung- kein Anspruch auf Vollständigkeit Flexibility and upside potential
How are customer needs met by the different product concepts? Traditional decumulation phase Fund pension plan Longevity Charges, Transparency Guarantees Longevity Flexibility Upside potential Charges, Transparency Guarantees Seite 14 14 | AXA Konzern AG, Ansgar Lürwer Basis: eigene Annahmen Flexibility Upside potential
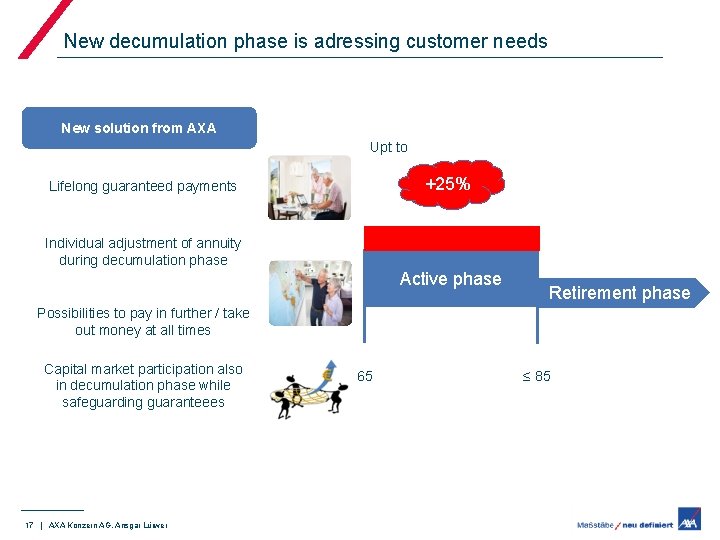
New decumulation phase is adressing customer needs New solution from AXA Upt to +25% Lifelong guaranteed payments Individual adjustment of annuity during decumulation phase Active phase Retirement phase Possibilities to pay in further / take out money at all times Capital market participation also in decumulation phase while safeguarding guaranteees 17 | AXA Konzern AG, Ansgar Lürwer 65 ≤ 85
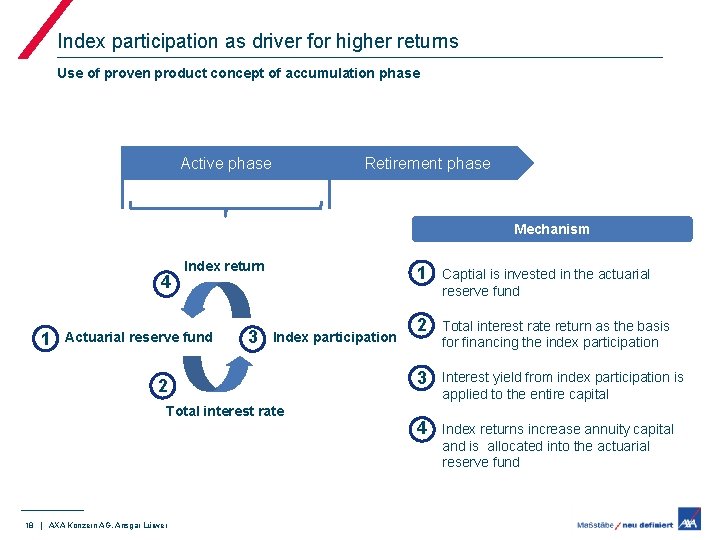
Index participation as driver for higher returns Use of proven product concept of accumulation phase Active phase Retirement phase Mechanism 4 1 Index return Actuarial reserve fund 3 Index participation 2 Total interest rate 18 | AXA Konzern AG, Ansgar Lürwer 1 1. Captial is invested in the actuarial reserve fund 2. 2 Total interest rate return as the basis for financing the index participation 3. 3 Interest yield from index participation is applied to the entire capital 4. 4 Index returns increase annuity capital and is allocated into the actuarial reserve fund
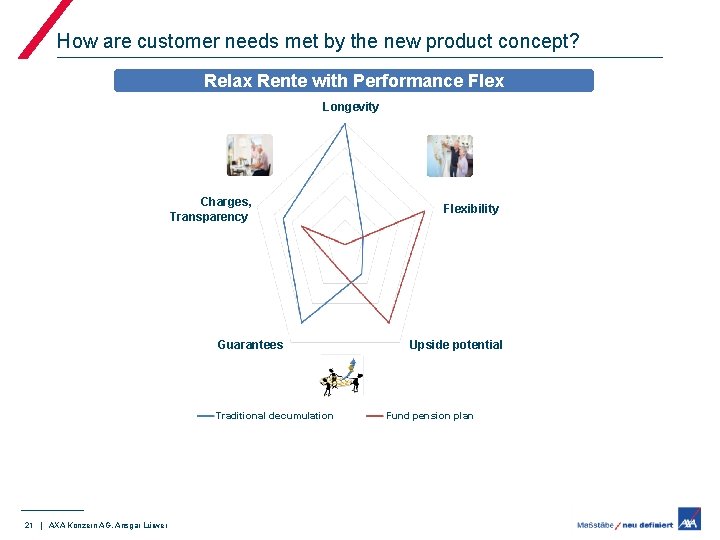
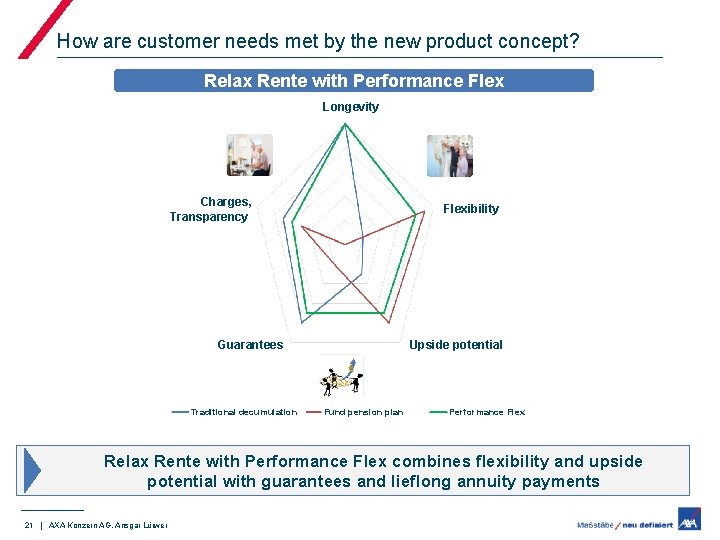
How are customer needs met by the new product concept? Relax Rente with Performance Flex Longevity Charges, Transparency Guarantees Traditional decumulation 21 | AXA Konzern AG, Ansgar Lürwer Flexibility Upside potential Fund pension plan
How are customer needs met by the new product concept? Relax Rente with Performance Flex Longevity Charges, Transparency Flexibility Guarantees Traditional decumulation Upside potential Fund pension plan Performance Flex Relax Rente with Performance Flex combines flexibility and upside potential with guarantees and lieflong annuity payments 21 | AXA Konzern AG, Ansgar Lürwer
Thank you! Datum / Ort