Church Accounting Standards A guide to compliance with
- Slides: 15
Church Accounting Standards A guide to compliance with new requirements
Overview 1. Public Benefit Entity Accounting Standards: Key Points 2. Reporting Requirements ◦ - Non-financial information ◦ - Financial Information 3. Summary and Q and A 2
1. PBE Accounting - Key Points 1. Under the Financial Reporting Act 2013, churches are defined as Public Benefit Entities and have to: - complete annual reports to PBE standards - post report on charities register within six months of balance date 2. Most churches will be either Tier 3 or Tier 4 PBE’s, measured in annual operating expense: - Tier 3: expense over $125 k, less than $2 m - Tier 4: expense less than $125, 000 pa 3
3. Churches have to consolidate controlled Trusts and associated activities 4. Tier 3 requires accrual accounting; Tier 4 requires cash accounting 5. Churches who qualify for Tier 4 may opt for Tier 3 reporting standard 6. Accounts may be consolidated with national or regional church accounts – seek advice from denomination National Office 4
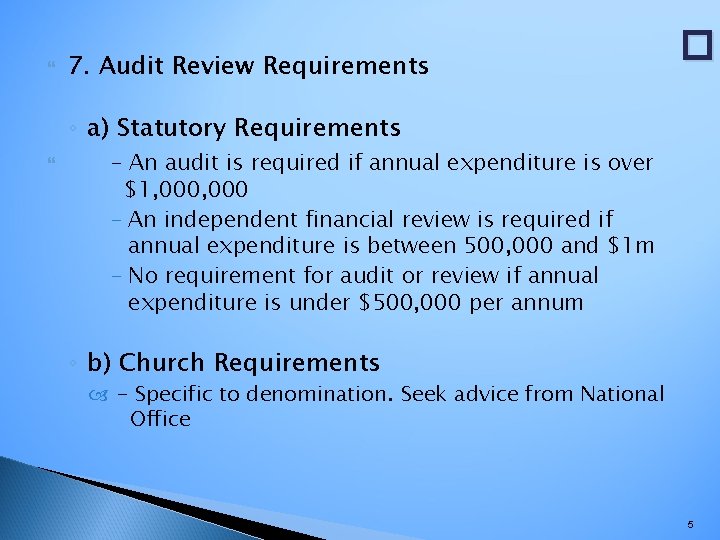
7. Audit Review Requirements � ◦ a) Statutory Requirements - An audit is required if annual expenditure is over $1, 000 - An independent financial review is required if annual expenditure is between 500, 000 and $1 m - No requirement for audit or review if annual expenditure is under $500, 000 per annum ◦ b) Church Requirements - Specific to denomination. Seek advice from National Office 5
2. Reporting Requirements Non Financial Reports – All churches - Entity Information - Statement of Service Performance 6
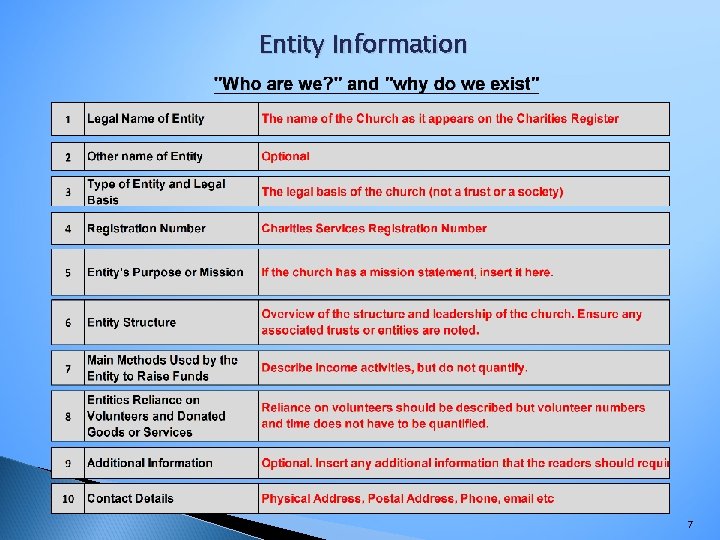
Entity Information 7
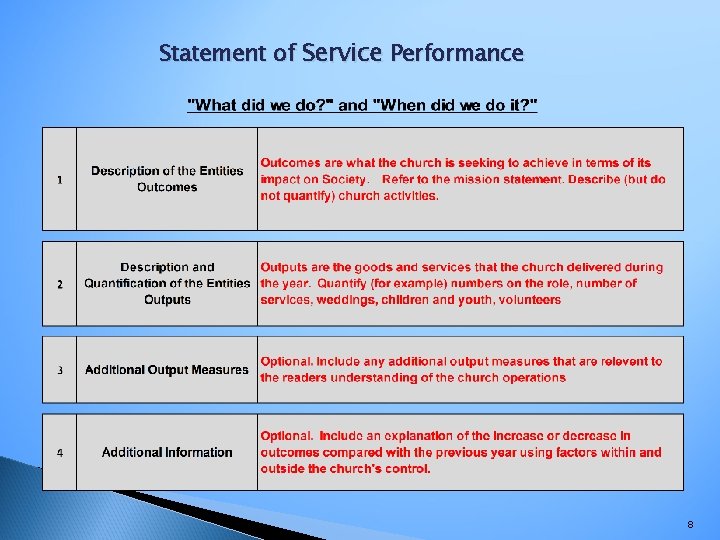
Statement of Service Performance 8
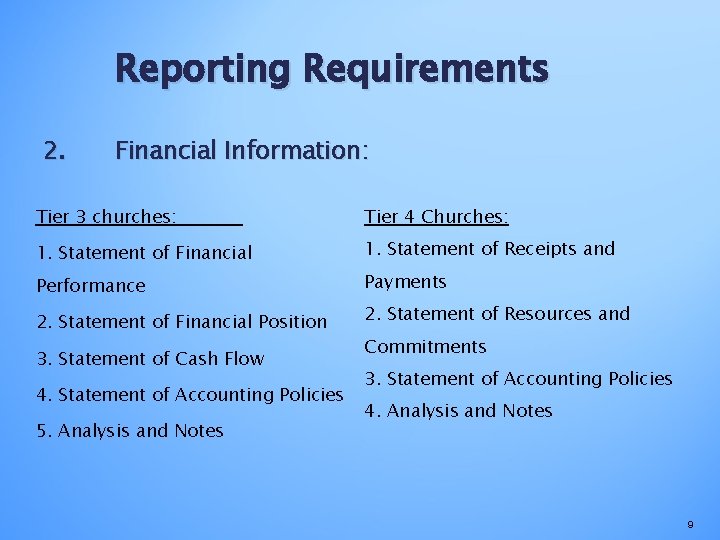
Reporting Requirements 2. Financial Information: Tier 3 churches: Tier 4 Churches: 1. Statement of Financial 1. Statement of Receipts and Performance Payments 2. Statement of Financial Position 2. Statement of Resources and 3. Statement of Cash Flow 4. Statement of Accounting Policies 5. Analysis and Notes Commitments 3. Statement of Accounting Policies 4. Analysis and Notes 9
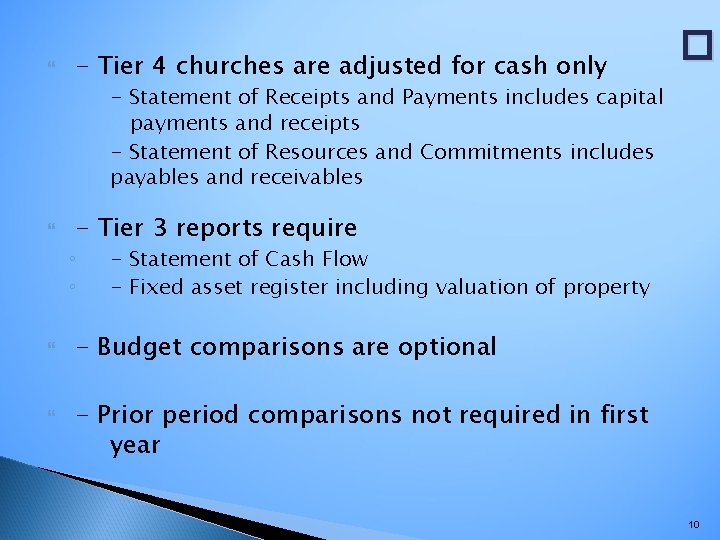
- Tier 4 churches are adjusted for cash only � - Statement of Receipts and Payments includes capital payments and receipts - Statement of Resources and Commitments includes payables and receivables - Tier 3 reports require ◦ ◦ - Statement of Cash Flow - Fixed asset register including valuation of property - Budget comparisons are optional - Prior period comparisons not required in first year 10
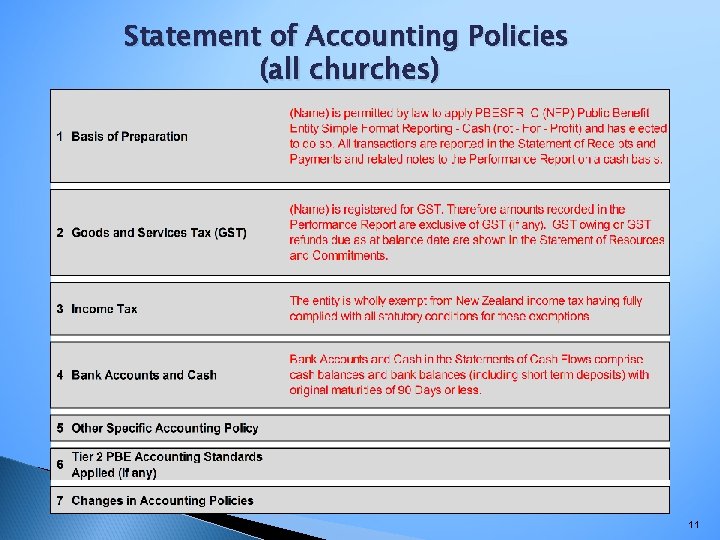
Statement of Accounting Policies (all churches) 11
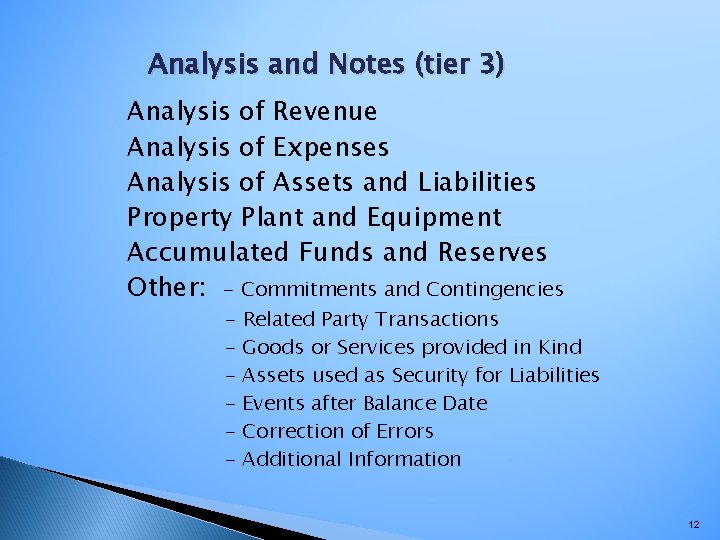
Analysis and Notes (tier 3) Analysis of Revenue Analysis of Expenses Analysis of Assets and Liabilities Property Plant and Equipment Accumulated Funds and Reserves Other: - Commitments and Contingencies - Related Party Transactions Goods or Services provided in Kind Assets used as Security for Liabilities Events after Balance Date Correction of Errors Additional Information 12
Analysis and Notes (tier 4) Analysis of Receipts Analysis of Payments Capital Receipts and Payments Other - Correction of Errors - Related Party transactions - Events after Balance Date - Additional Notes 13
Further Information presbyterian. org. nz (find something fast/treasurers information) icbnz. org charities. govt. nz laurenson. co. nz 14
Summary - Consider: What Tier does my church come under? What other trusts or joint ventures does the church have or control? What do I do about non financial transactions – donated goods; volunteers, church membership, measurement of activities, donations of assets? Financial Information – what reporting fields are mandatory / voluntary? Do I have to report prior period comparisons? I have to report budgets? Do the accounts have to be reviewed or audited? How do I post accounts on Charities Register? 15