Accounting Standards RTI Jaipur 1 Session overview Every
- Slides: 24
Accounting Standards RTI, Jaipur 1
Session overview Every profession develops a body of knowledge consisting of principles, which are considered as standard to be attained. Accounting is no exception. In India, the Institute of Chartered Accountants of India has developed Accounting Standards; based on the ‘generally accepted accounting standards’ to be used in preparation of financial statements. RTI, Jaipur 2
Session coverage During this session, we will learn: the importance of the accounting standards in preparation of financial statements; and ·application of AS 1 relating to ‘Disclosure of Accounting Policies’, and ·application of AS 4 relating to ‘Events Occurring After the Balance Sheet Date’ for preparation of financial statements. RTI, Jaipur 3
Learning Objective At the end of the session, the learner will be able to state the importance of Accounting Standards in the preparation of financial statements and application of AS 1 relating to ‘Disclosure of Accounting Policies’ and AS 4 relating to ‘Events Occurring After the Balance Sheet Date’ in the preparation of Financial Statements. RTI, Jaipur 4
Importance of Accounting Standards The users of the financial statements need an assurance that the entities preparing their financial statements follow the accepted standards while presenting their financial information in the financial statements. RTI, Jaipur 5
LIST OF ACCOUNTING STANDARDS ISSUED SO FAR Institute of Chartered Accountants of India has so far issued 29 Accounting Standards on the advise of the accounting Standards Board RTI, Jaipur 6
LIST OF ACCOUNTING STANDARDS ISSUED SO FAR AS 1 -Disclosure of Accounting Policies AS 2 -Valuation of Inventories AS 3 -Cash flow Statements AS 4 -Contingencies and Events Occurring After the Balance Sheet Date AS 5 -Net Profit or Loss for the Period, Prior Period Items and Changes in Accounting Policies AS 6 -Depreciation Accounting RTI, Jaipur 7
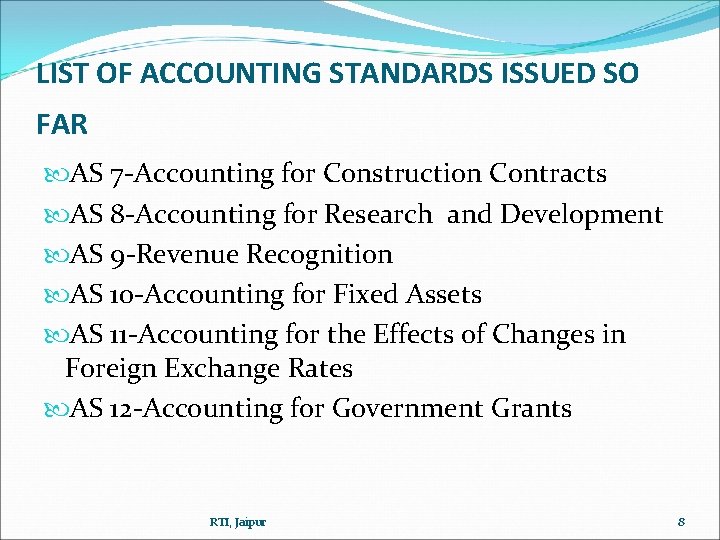
LIST OF ACCOUNTING STANDARDS ISSUED SO FAR AS 7 -Accounting for Construction Contracts AS 8 -Accounting for Research and Development AS 9 -Revenue Recognition AS 10 -Accounting for Fixed Assets AS 11 -Accounting for the Effects of Changes in Foreign Exchange Rates AS 12 -Accounting for Government Grants RTI, Jaipur 8
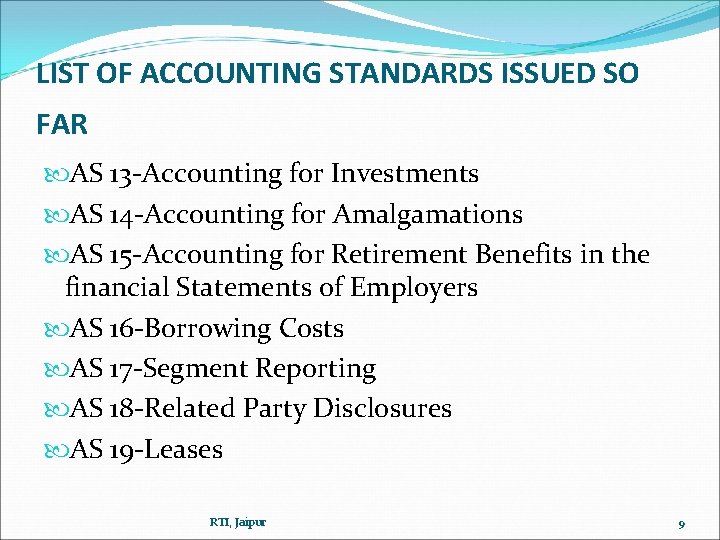
LIST OF ACCOUNTING STANDARDS ISSUED SO FAR AS 13 -Accounting for Investments AS 14 -Accounting for Amalgamations AS 15 -Accounting for Retirement Benefits in the financial Statements of Employers AS 16 -Borrowing Costs AS 17 -Segment Reporting AS 18 -Related Party Disclosures AS 19 -Leases RTI, Jaipur 9
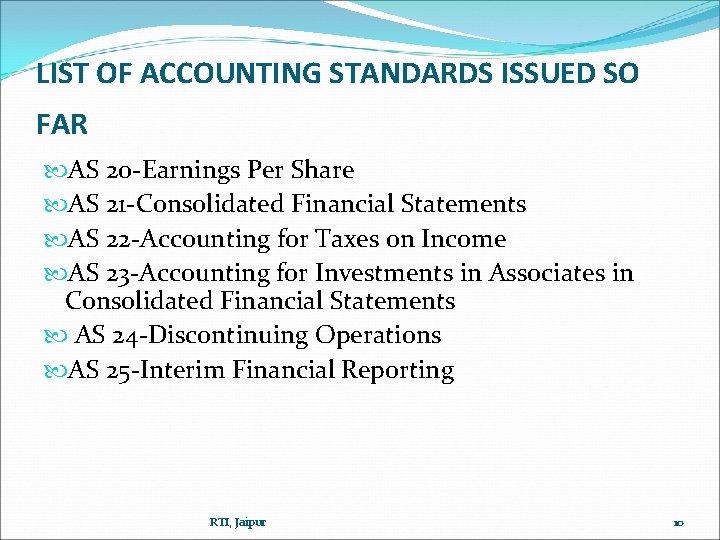
LIST OF ACCOUNTING STANDARDS ISSUED SO FAR AS 20 -Earnings Per Share AS 21 -Consolidated Financial Statements AS 22 -Accounting for Taxes on Income AS 23 -Accounting for Investments in Associates in Consolidated Financial Statements AS 24 -Discontinuing Operations AS 25 -Interim Financial Reporting RTI, Jaipur 10
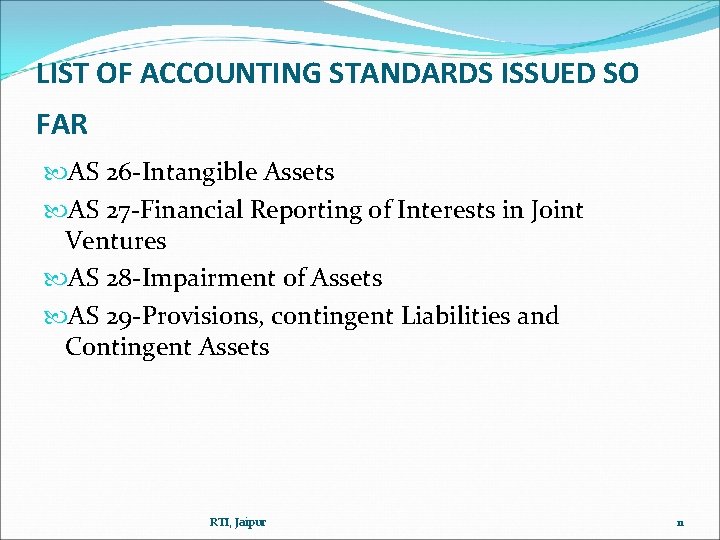
LIST OF ACCOUNTING STANDARDS ISSUED SO FAR AS 26 -Intangible Assets AS 27 -Financial Reporting of Interests in Joint Ventures AS 28 -Impairment of Assets AS 29 -Provisions, contingent Liabilities and Contingent Assets RTI, Jaipur 11
Accounting Standard (AS 1) – Disclosure of Accounting Policies RTI, Jaipur 12
AS 1 – Disclosure of Accounting Policies Fundamental Accounting Assumptions Accounting Policies RTI, Jaipur 13
Fundamental Accounting Assumptions Going concern Consistency Accrual RTI, Jaipur 14
Areas in which differing accounting Policies are encountered Ø Methods of depreciation, depletion and amortization; Ø Treatment of expenditure during construction; Ø Conversion or translation of foreign currency items; RTI, Jaipur 15
Areas in which differing accounting Policies are encountered Ø Valuation of inventories; Ø Treatment of goodwill; Ø Valuation of investments; Ø Treatment of retirement benefits; RTI, Jaipur 16
Areas in which differing accounting Policies are encountered Ø Recognition of profit on long-term contracts; Ø Valuation of fixed assets; Ø Treatment of contingent liabilities. RTI, Jaipur 17
Considerations in the selection of Accounting Policies ü Prudence ü Substance over form ü Materiality RTI, Jaipur 18
Accounting Standard-1 ·All significant accounting policies adopted in preparation and presentation of financial statements should be disclosed. ·The disclosure of significant accounting policies as such should form part of the financial statement and the significant accounting policies should normally be disclosed in one place. RTI, Jaipur 19
Accounting Standard-1 · If the fundamental accounting assumptions, viz. , going concern, consistency and accrual are followed in financial statements, specific disclosure is not required. If a fundamental accounting assumption is not followed, the fact should be disclosed. RTI, Jaipur 20
Accounting Standard (AS) 4 Contingencies and Events Occurring After the Balance Sheet Date RTI, Jaipur 21
Accounting Standard-4 This standard deals with treatment in financial statements of: ü Contingencies; and ü Events occurring after the balance sheet date. RTI, Jaipur 22
Accounting Standard-4 Does not apply to: (a) Liabilities of life assurance and general insurance enterprises arising from policies issued; (b) Obligations under retirement benefit plans; and © Commitments arising from long-term lease contracts. RTI, Jaipur 23
Definitions A contingency is a condition or situation, the ultimate outcome of which, gain or loss, will be known or determined only on the occurrence or nonoccurrence of one or more uncertain future events. RTI, Jaipur Events after the balance sheet date are those significant events, both favourable and unfavourable, that occur between the balance sheet date and the date on which the financial statements are approved by the Board of Directors represent material changes and commitments affecting the financial position of the enterprise 24