Accounting Information Systems Accounting Information System 9 th
- Slides: 25
ﺑﺴﻢ ﺍﻟﻠﻪ ﺍﻟﺮﺣﻤﻦ ﺍﻟﺮﺣﻴﻢ Accounting Information Systems ﻧﻈﻢ ﺍﻟﻤﻌﻠﻮﻣﺎﺕ ﺍﻟﻤﺤﺎﺳﺒﻴﺔ : ﺗﺮﺟﻤﺔ ﻭﺇﻋﺪﺍﺩ ﻣﺤﻤﻮﺩ ﻋﻤﺮ ﻣﺤﻤﻮﺩ ﺍﻟﻄﺒﺮﻱ. ﺩ : ﻣﻦ ﻛﺘﺎﺏ Accounting Information System, 9 th ed. , Romney/Steinbart ﺃﻬﻼ ﻭﻣﺮﺣﺒ ﺑﺎﻟﺠﻤﻴﻊ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 1 -1
ﺑﺴﻢ ﺍﻟﻠﻪ ﺍﻟﺮﺣﻤﻦ ﺍﻟﺮﺣﻴﻢ Chapter 1: Accounting Information Systems (AIS): An Overview : ﺍﻟﻔﺼﻞ ﺍﻷﻮﻝ ﻣﺮﺍﺟﻌﺔ : ﻧﻈﻢ ﺍﻟﻤﻌﻠﻮﻣﺎﺕ ﺍﻟﻤﺤﺎﺳﺒﻴﺔ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 1 -2
The American Institute of Certified Public Accountants (AICPA) ﻣﻨﻈﻤﺔ ﺍﻟﻤﺤﺎﺳﺒﻴﻴﻦ ﺍﻟﻘﺎﻧﻮﻧﻴﻴﻦ ﺍﻻﻣﺮﻳﻜﻴﻴﻦ “The American Institute of Certified Public Accountants (AICPA) has projected that two of the top technology issues facing the accounting profession during the first several years of the 21 st century are: ﺍﻻﻣﺮﻳﻜﻴﻴﻦ ﺃﻦ ﺃﻬﻢ ﺃﻤﺮﺍﻥ ﻓﻲ ﺍﻟﺘﻜﻨﻮﻟﻮﺟﻴﺎ ﺳﻴﻮﺍﺟﻬﺎﻥ ﻣﻬﻨﺔ ﺍﻟﻤﺤﺎﺳﺒﺔ ﻓﻲ ﺗﺴﺘﻘﺮﺀ ﻣﻨﻈﻤﺔ ﺍﻟﻤﺤﺎﺳﺒﻴﻴﻦ ﺍﻟﻘﺎﻧﻮﻧﻴﻴﻦ ¢ : ﺍﻷﻮﻟﻰ ﻣﻦ ﺍﻟﻘﺮﻥ ﺍﻟﺤﺎﺩﻱ ﻭﺍﻟﻌﺸﺮﻳﻦ ﻫﻤﺎ ﺍﻟﺴﻨﻮﺍﺕ l Information security and controls within information systems, and ﺍﻷﻤﻦ ﻭﺍﻟﺘﺤﻜﻢ ﺑﺎﻟﻤﻌﻠﻮﻣﺎﺕ ﻣﻦ ﺩﺍﺧﻞ ﺃﻨﻈﻤﺔ ﺍﻟﻤﻌﻠﻮﻣﺎﺕ l l Electronic commerce ﺍﻹﻟﻜﺘﺮﻭﻧﻴﺔ ﻭ ﺍﻟﺘﺠﺎﺭﺓ l ¢ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 5
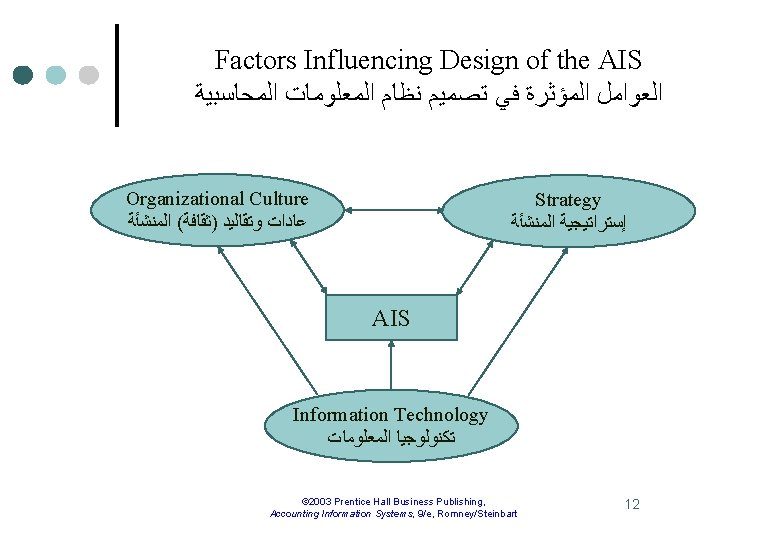
Factors Influencing Design of the AIS ﺍﻟﻌﻮﺍﻣﻞ ﺍﻟﻤﺆﺜﺮﺓ ﻓﻲ ﺗﺼﻤﻴﻢ ﻧﻈﺎﻡ ﺍﻟﻤﻌﻠﻮﻣﺎﺕ ﺍﻟﻤﺤﺎﺳﺒﻴﺔ Organizational Culture ﻋﺎﺩﺍﺕ ﻭﺗﻘﺎﻟﻴﺪ )ﺛﻘﺎﻓﺔ( ﺍﻟﻤﻨﺸﺄﺔ Strategy ﺇﺳﺘﺮﺍﺗﻴﺠﻴﺔ ﺍﻟﻤﻨﺸﺄﺔ AIS Information Technology ﺗﻜﻨﻮﻟﻮﺟﻴﺎ ﺍﻟﻤﻌﻠﻮﻣﺎﺕ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 12
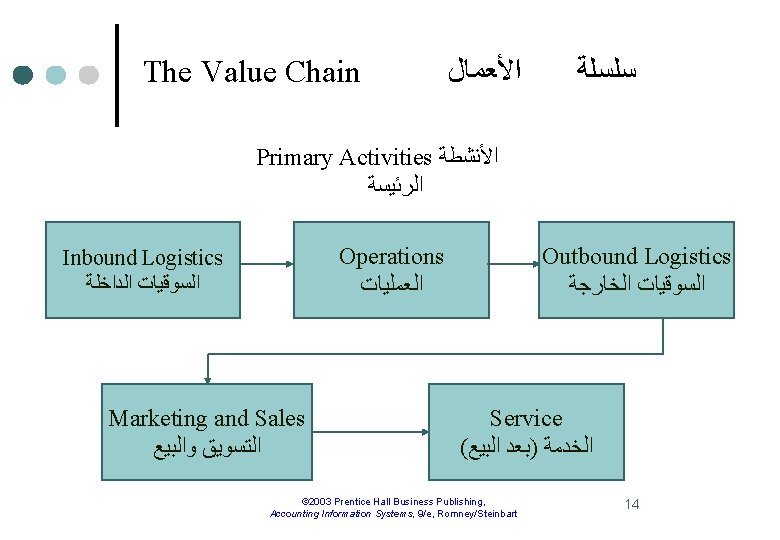
The Value Chain ﺍﻷﻌﻤﺎﻝ ﺳﻠﺴﻠﺔ Primary Activities ﺍﻷﻨﺸﻄﺔ ﺍﻟﺮﺋﻴﺴﺔ Operations ﺍﻟﻌﻤﻠﻴﺎﺕ Inbound Logistics ﺍﻟﺴﻮﻗﻴﺎﺕ ﺍﻟﺪﺍﺧﻠﺔ Marketing and Sales ﺍﻟﺘﺴﻮﻳﻖ ﻭﺍﻟﺒﻴﻊ Outbound Logistics ﺍﻟﺴﻮﻗﻴﺎﺕ ﺍﻟﺨﺎﺭﺟﺔ Service ( ﺍﻟﺨﺪﻣﺔ )ﺑﻌﺪ ﺍﻟﺒﻴﻊ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 14
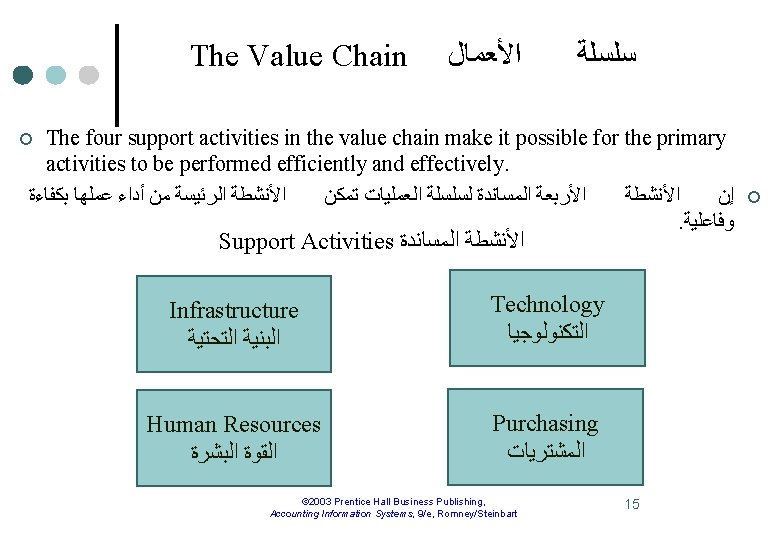
The Value Chain ﺍﻷﻌﻤﺎﻝ ﺳﻠﺴﻠﺔ The four support activities in the value chain make it possible for the primary activities to be performed efficiently and effectively. ﺍﻷﻨﺸﻄﺔ ﺍﻟﺮﺋﻴﺴﺔ ﻣﻦ ﺃﺪﺍﺀ ﻋﻤﻠﻬﺎ ﺑﻜﻔﺎﺀﺓ ﺍﻷﺮﺑﻌﺔ ﺍﻟﻤﺴﺎﻧﺪﺓ ﻟﺴﻠﺴﻠﺔ ﺍﻟﻌﻤﻠﻴﺎﺕ ﺗﻤﻜﻦ ﺍﻷﻨﺸﻄﺔ ﺇﻥ . ﻭﻓﺎﻋﻠﻴﺔ ¢ Support Activities ﺍﻷﻨﺸﻄﺔ ﺍﻟﻤﺴﺎﻧﺪﺓ Infrastructure ﺍﻟﺒﻨﻴﺔ ﺍﻟﺘﺤﺘﻴﺔ Technology ﺍﻟﺘﻜﻨﻮﻟﻮﺟﻴﺎ Human Resources ﺍﻟﻘﻮﺓ ﺍﻟﺒﺸﺮﺓ Purchasing ﺍﻟﻤﺸﺘﺮﻳﺎﺕ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 15 ¢
The Value System ﻗﻴﻤﺔ ﺍﻟﻨﻈﺎﻡ ¢ ¢ The value chain concept can be extended by recognizing that organizations must interact with suppliers, distributors, and customers. . ﻭﺍﻟﻌﻤﻼﺀ ﺍﻷﻌﻤﺎﻝ ﻳﻤﻜﻦ ﺃﻦ ﺗﻤﺘﺪ ﻟﺘﺸﻤﻞ ﺍﻟﺘﻔﺎﻋﻞ ﻣﻊ ﺍﻟﻤﻮﺭﺩﻳﻦ ﻭﺍﻟﻤﻮﺯﻋﻴﻦ ﺇﻥ ﺳﻠﺴﻠﺔ ¢ An organization’s value chain and the value chains of its suppliers, distributors, and customers collectively form a value system. ﻭﺍﻟﻌﻤﻼﺀ ﻣﺠﺘﻤﻌﺔ ﺗﺸﻜﻞ ﻣﺎ ﻭﺳﻠﺴﻠﺔ ﺃﻌﻤﺎﻝ ﺍﻟﻤﻮﺭﺩﻳﻦ ﻭﺍﻟﻤﻮﺯﻋﻴﻦ ، ﺍﻷﻌﻤﺎﻝ ﻟﻠﻤﻨﺸﺔ ﺇﻥ ﺳﻠﺴﻠﺔ ¢. ﻳﺴﻤﻰ ﻗﻴﻤﺔ ﺍﻟﻨﻈﺎﻡ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 16
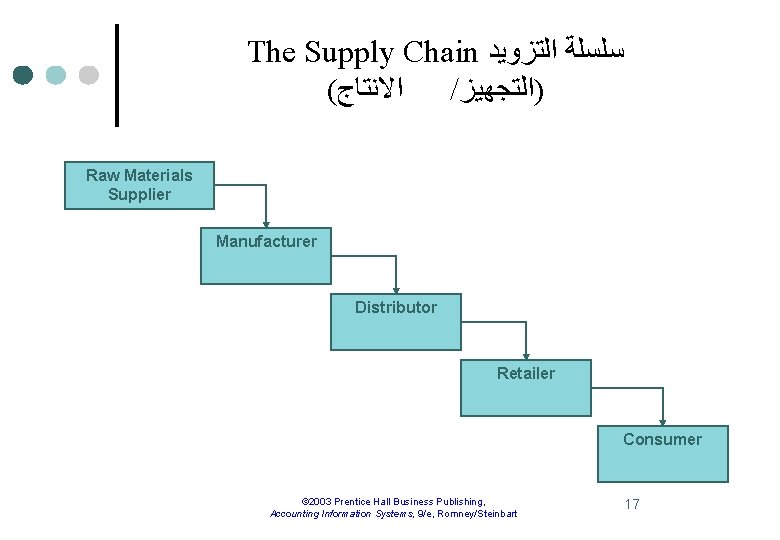
The Supply Chain ﺳﻠﺴﻠﺔ ﺍﻟﺘﺰﻭﻳﺪ ( ﺍﻻﻧﺘﺎﺝ / )ﺍﻟﺘﺠﻬﻴﺰ Raw Materials Supplier Manufacturer Distributor Retailer Consumer © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 17
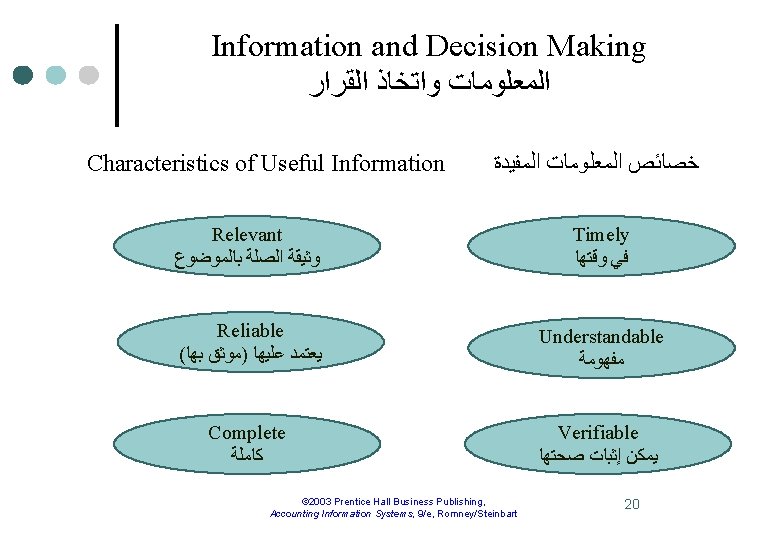
Information and Decision Making ﺍﻟﻤﻌﻠﻮﻣﺎﺕ ﻭﺍﺗﺨﺎﺫ ﺍﻟﻘﺮﺍﺭ Characteristics of Useful Information ﺧﺼﺎﺋﺺ ﺍﻟﻤﻌﻠﻮﻣﺎﺕ ﺍﻟﻤﻔﻴﺪﺓ Relevant ﻭﺛﻴﻘﺔ ﺍﻟﺼﻠﺔ ﺑﺎﻟﻤﻮﺿﻮﻉ Timely ﻓﻲ ﻭﻗﺘﻬﺎ Reliable ( ﻳﻌﺘﻤﺪ ﻋﻠﻴﻬﺎ )ﻣﻮﺛﻖ ﺑﻬﺎ Understandable ﻣﻔﻬﻮﻣﺔ Complete ﻛﺎﻣﻠﺔ Verifiable ﻳﻤﻜﻦ ﺇﺛﺒﺎﺕ ﺻﺤﺘﻬﺎ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 20
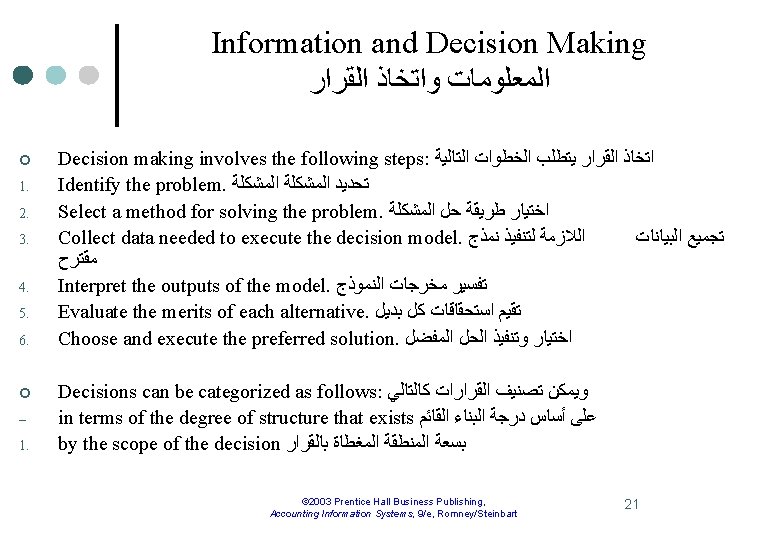
Information and Decision Making ﺍﻟﻤﻌﻠﻮﻣﺎﺕ ﻭﺍﺗﺨﺎﺫ ﺍﻟﻘﺮﺍﺭ ¢ 1. 2. 3. 4. 5. 6. ¢ – 1. Decision making involves the following steps: ﺍﺗﺨﺎﺫ ﺍﻟﻘﺮﺍﺭ ﻳﺘﻄﻠﺐ ﺍﻟﺨﻄﻮﺍﺕ ﺍﻟﺘﺎﻟﻴﺔ Identify the problem. ﺗﺤﺪﻳﺪ ﺍﻟﻤﺸﻜﻠﺔ Select a method for solving the problem. ﺍﺧﺘﻴﺎﺭ ﻃﺮﻳﻘﺔ ﺣﻞ ﺍﻟﻤﺸﻜﻠﺔ Collect data needed to execute the decision model. ﺍﻟﻼﺯﻣﺔ ﻟﺘﻨﻔﻴﺬ ﻧﻤﺬﺝ ﺗﺠﻤﻴﻊ ﺍﻟﺒﻴﺎﻧﺎﺕ ﻣﻘﺘﺮﺡ Interpret the outputs of the model. ﺗﻔﺴﻴﺮ ﻣﺨﺮﺟﺎﺕ ﺍﻟﻨﻤﻮﺫﺝ Evaluate the merits of each alternative. ﺗﻘﻴﻢ ﺍﺳﺘﺤﻘﺎﻗﺎﺕ ﻛﻞ ﺑﺪﻳﻞ Choose and execute the preferred solution. ﺍﺧﺘﻴﺎﺭ ﻭﺗﻨﻔﻴﺬ ﺍﻟﺤﻞ ﺍﻟﻤﻔﻀﻞ Decisions can be categorized as follows: ﻭﻳﻤﻜﻦ ﺗﺼﻨﻴﻒ ﺍﻟﻘﺮﺍﺭﺍﺕ ﻛﺎﻟﺘﺎﻟﻲ in terms of the degree of structure that exists ﻋﻠﻰ ﺃﺴﺎﺱ ﺩﺭﺟﺔ ﺍﻟﺒﻨﺎﺀ ﺍﻟﻘﺎﺋﻢ by the scope of the decision ﺑﺴﻌﺔ ﺍﻟﻤﻨﻄﻘﺔ ﺍﻟﻤﻐﻄﺎﺓ ﺑﺎﻟﻘﺮﺍﺭ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 21
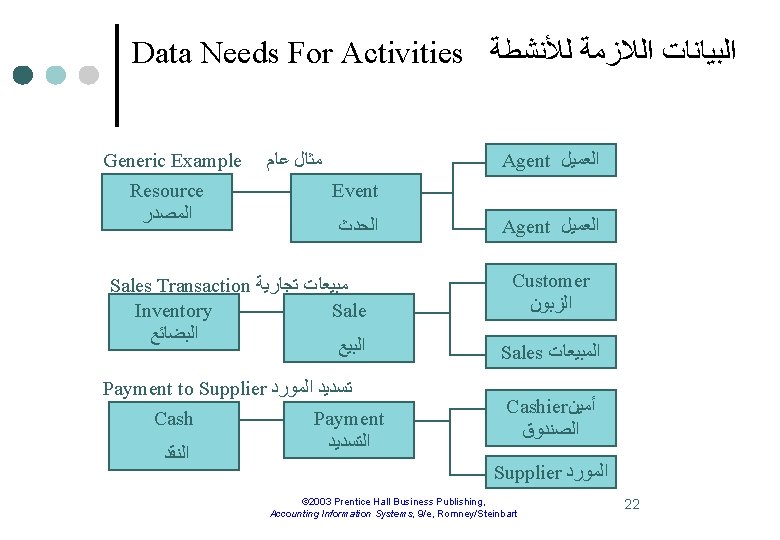
Data Needs For Activities ﺍﻟﺒﻴﺎﻧﺎﺕ ﺍﻟﻼﺯﻣﺔ ﻟﻸﻨﺸﻄﺔ Generic Example Resource ﺍﻟﻤﺼﺪﺭ ﻣﺜﺎﻝ ﻋﺎﻡ Agent ﺍﻟﻌﻤﻴﻞ Event ﺍﻟﺤﺪﺙ Sales Transaction ﻣﺒﻴﻌﺎﺕ ﺗﺠﺎﺭﻳﺔ Inventory Sale ﺍﻟﺒﻀﺎﺋﻊ ﺍﻟﺒﻴﻊ Payment to Supplier ﺗﺴﺪﻳﺪ ﺍﻟﻤﻮﺭﺩ Cash Payment ﺍﻟﺘﺴﺪﻳﺪ ﺍﻟﻨﻘﺪ Agent ﺍﻟﻌﻤﻴﻞ Customer ﺍﻟﺰﺑﻮﻥ Sales ﺍﻟﻤﺒﻴﻌﺎﺕ Cashier ﺃﻤﻴﻦ ﺍﻟﺼﻨﺪﻭﻕ Supplier ﺍﻟﻤﻮﺭﺩ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 22
Decision Scope ﺍﻟﻨﻈﺮﺓ ﻟﻠﻘﺮﺍﺭ Decisions vary in terms of the scope of their effect: ﻳﻤﻜﻦ ﺍﻟﻘﻮﻝ ﺃﻦ ، ﻟﺬﺍ. ﺗﺨﺘﻠﻒ ﺍﻟﻘﺮﺍﺭﺍﺕ ﻋﻠﻰ ﺍﺳﺎﺱ ﺍﻟﻨﻈﺮﺓ ﻷﺜﺮﻫﺎ ¢ Operational control is concerned with the effective and efficient performance of specific tasks. . ﺍﻟﺴﻴﻄﺮﺓ )ﺍﻟﻀﺒﻂ( ﺍﻟﺘﺸﻐﻴﻠﻲ ﻣﻌﻨﻲ ﺑﺎﻷﺪﺍﺀ ﺍﻟﻔﻌﺎﻝ ﻭﺍﻟﻜﻔﺆ ﻟﻤﻬﺎﻡ ﻣﺤﺪﺩﺓ ¢ Management control is concerned with the effective and efficient use of resources for accomplishing organizational objectives. . ﺍﻟﺴﻴﻄﺮﺓ )ﺍﻟﻀﺒﻂ( ﺍﻹﺩﺍﺭﻱ ﻣﻌﻨﻲ ﺑﺎﻻﺳﺘﺨﺪﺍﻡ ﺍﻟﻔﻌﺎﻝ ﻭﺍﻟﻜﻔﺆ ﻟﻠﻤﻮﺍﺭﺩ ﻹﻧﺠﺎﺯ ﺃﻬﺪﺍﻑ ﺍﻟﻤﻨﺸﺄﺔ ¢ ¢ ¢ Strategic planning is concerned with establishing organizational objectives and policies for accomplishing those objectives. . ﺍﻟﺘﺨﻄﻴﻂ ﺍﻻﺳﺘﺮﺍﺗﻴﺠﻲ ﻣﻌﻨﻲ ﺑﺘﺄﺴﻴﺲ ﺃﻬﺪﺍﻑ ﺍﻟﻤﻨﺸﺄﺔ ﻭﺍﻟﺨﻄﻂ ﻹﻧﺠﺎﺯ ﻫﺬﻩ ﺍﻷﻬﺪﺍﻑ © 2003 Prentice Hall Business Publishing, Accounting Information Systems, 9/e, Romney/Steinbart 24 ¢