YEAREND ACCOUNTING PROCEDURES Other Adjustments Grade 10 Accounting
- Slides: 13
YEAR–END ACCOUNTING PROCEDURES Other Adjustments Grade 10 Accounting Module 10 Lesson 7
OTHER ADJUSTMENTS �Some adjustments that occur throughout the year and are not year-end adjustments have been covered in previous modules. �It may, however, be necessary to record them at yearend to ensure accuracy
1. Bad Debts �Adjustment Further bad debts must be written off �Entry in the General Journal Debit Bad Debts; Credit Debtors Control �Effect in the Post-Adjustment Trial Balance Bad Debts (expense) increases; Debtors Control decreases �Effect on Accounting equation Assets decrease; Expense increase (Owners’ Equity decreases)
2. Bad Debts Recovered �Adjustment Received a cheque from a debtor. His account had previously been written off �Entry in the Cash Receipts Journal Debit Bank; Credit Bad Debts Recovered �Effect in the Post-Adjustment Trial Balance Bank increases; Bad Debts Recovered (income) increases �Effect on Accounting equation Assets increase; Income increase (Owners’ Equity increases)
3. Insolvencies �Adjustment A debtor who owed R 500 was declared insolvent. His state paid a dividend of 20 cents in the Rand. The balance of his account must be written off. No entries had been made. �Entry in the General Journal Debit Bank R 100; Credit Debtors Control R 100 Debit Bad Debts R 400; Credit Debtors Control R 400 �Effect in the Post-Adjustment Trial Balance Bank increases R 100; Debtors Control decreases R 100 Bad Debts increases R 100; Debtors Control decreases R 400 �Effect on Accounting equation Assets increase R 100; Assets decrease R 100 Assets decrease R 400; Expenses increase (Owners’ Equity decreases) R 400
4. Interest on overdue Debtors �Adjustment A debtor owes R 1 200. His account is overdue. Charged him R 40 interest. �Entry in the General Journal Debit Debtors Control R 40; Credit Interest on Overdue account R 40 �Effect in the Post-Adjustment Trial Balance Debtors Control increases R 40; Interest on overdue account (income) increases R 40 �Effect on Accounting equation Assets increase R 40; Income increase (Owners’ Equity increases) R 40
5. Interest on overdue Creditors �Adjustment A creditor charges us R 140 interest on our overdue account. �Entry in the General Journal Debit Interest expense R 140; Creditors Control R 140 �Effect in the Post-Adjustment Trial Balance Interest expense increases R 140; Creditors Control increases R 140 �Effect on Accounting equation Expenses increase (Owners’ Equity decreases) R 140; Liabilities increase R 140
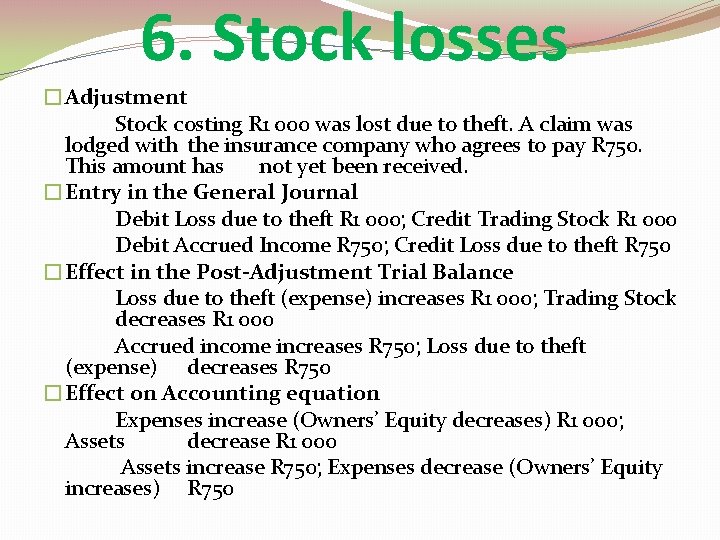
6. Stock losses �Adjustment Stock costing R 1 000 was lost due to theft. A claim was lodged with the insurance company who agrees to pay R 750. This amount has not yet been received. �Entry in the General Journal Debit Loss due to theft R 1 000; Credit Trading Stock R 1 000 Debit Accrued Income R 750; Credit Loss due to theft R 750 �Effect in the Post-Adjustment Trial Balance Loss due to theft (expense) increases R 1 000; Trading Stock decreases R 1 000 Accrued income increases R 750; Loss due to theft (expense) decreases R 750 �Effect on Accounting equation Expenses increase (Owners’ Equity decreases) R 1 000; Assets decrease R 1 000 Assets increase R 750; Expenses decrease (Owners’ Equity increases) R 750
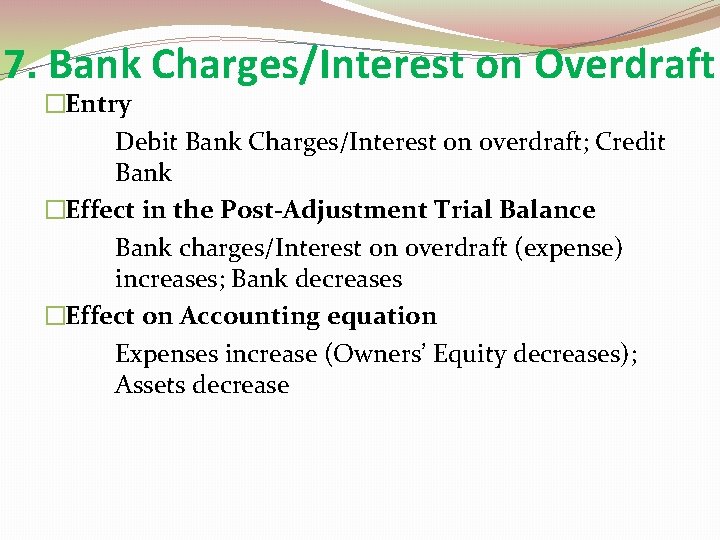
7. Bank Charges/Interest on Overdraft �Entry Debit Bank Charges/Interest on overdraft; Credit Bank �Effect in the Post-Adjustment Trial Balance Bank charges/Interest on overdraft (expense) increases; Bank decreases �Effect on Accounting equation Expenses increase (Owners’ Equity decreases); Assets decrease
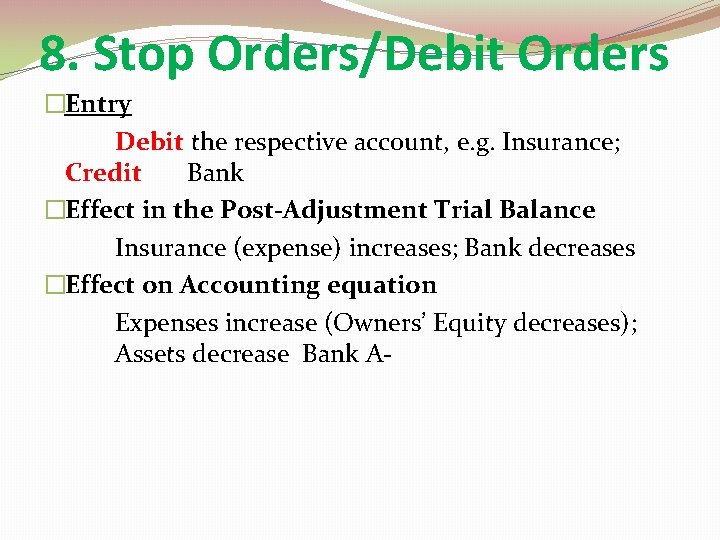
8. Stop Orders/Debit Orders �Entry Debit the respective account, e. g. Insurance; Credit Bank �Effect in the Post-Adjustment Trial Balance Insurance (expense) increases; Bank decreases �Effect on Accounting equation Expenses increase (Owners’ Equity decreases); Assets decrease Bank A-
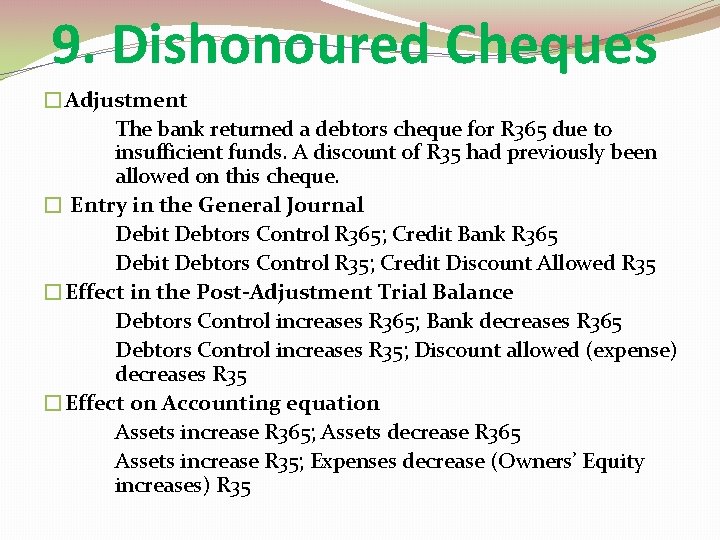
9. Dishonoured Cheques �Adjustment The bank returned a debtors cheque for R 365 due to insufficient funds. A discount of R 35 had previously been allowed on this cheque. � Entry in the General Journal Debit Debtors Control R 365; Credit Bank R 365 Debit Debtors Control R 35; Credit Discount Allowed R 35 �Effect in the Post-Adjustment Trial Balance Debtors Control increases R 365; Bank decreases R 365 Debtors Control increases R 35; Discount allowed (expense) decreases R 35 �Effect on Accounting equation Assets increase R 365; Assets decrease R 365 Assets increase R 35; Expenses decrease (Owners’ Equity increases) R 35
10. Correction of errors The usual procedure is followed in respect of correction of errors and the necessary adjustments are made to the post-adjustment figures. 1. . Look at the error. What did you Debit & Credit? 2. Did you record the correct amounts? 3. Ask yourself what must you record to cancel the error? 4. Record the correction of the error which should result in both rectifying the error and recording the correct outcome. TIP If entry too Small the record on the Same side. If entry too BIG then record on the opposite sides.
11. Drawings Debit Drawings Credit “whatever the owner took” Trading Stock taken for drawings always recorded at cost price