The Impact of Missing Trader IntraCommunity Fraud on
- Slides: 21
The Impact of Missing Trader Intra-Community Fraud on Trade Statistics Sandra Tudor Head of Statistics and Analysis of Trade Unit
Missing Trader Intra-Community Fraud • Increasing problem since the introduction • • of the single market Takes advantage of VAT system, where goods are zero rated on transactions between EU Member States Missing traders charge for VAT on sales but do not pay the tax to government
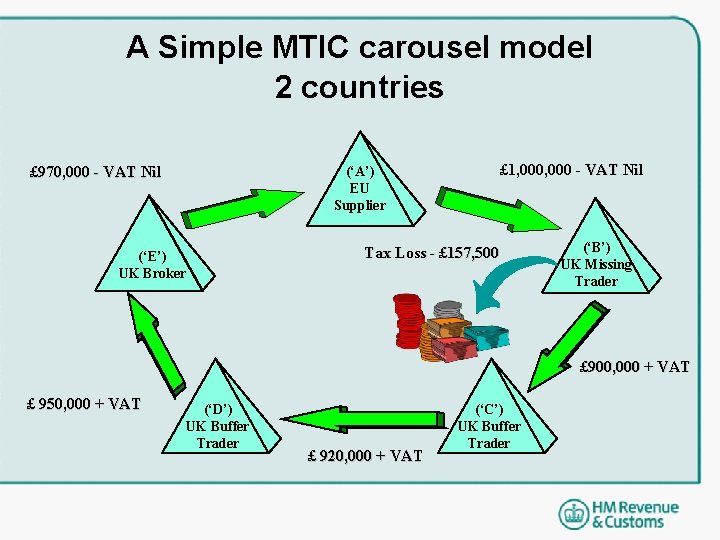
A Simple MTIC carousel model 2 countries £ 970, 000 - VAT Nil (‘A’) EU Supplier £ 1, 000 - VAT Nil Tax Loss - £ 157, 500 (‘E’) UK Broker (‘B’) UK Missing Trader £ 900, 000 + VAT £ 950, 000 + VAT (‘D’) UK Buffer Trader £ 920, 000 + VAT (‘C’) UK Buffer Trader
Media headlines, 2002 -2003 p u d se i v e r h t w s o r k g n i r h UK s t i c i f e d as 2 c 200 FT De Tw £ 8 o a 0 m rre VA sted Tf fo ra r ud BB C Fraud ca ses up, financia l losses down The Reg ister, July 2003 Se pt 2 00 3
Original work for Balance of Payments 2002 - July 2003
Impact on Trade Statistics • Effect on Intrastat data collection • • – Exports are captured, Imports are not Correct treatment is to increase imports Increasing imports worsens – Balance of Trade – Current Account deficit Goods are usually high value/low mass No estimate of acquisition fraud
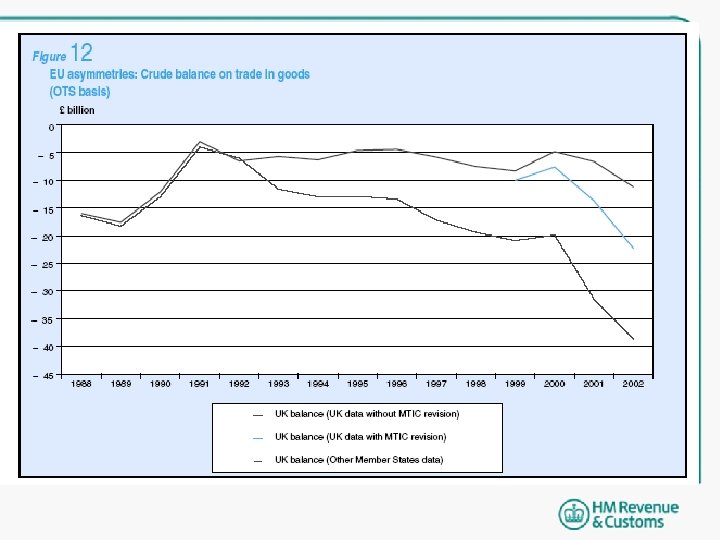
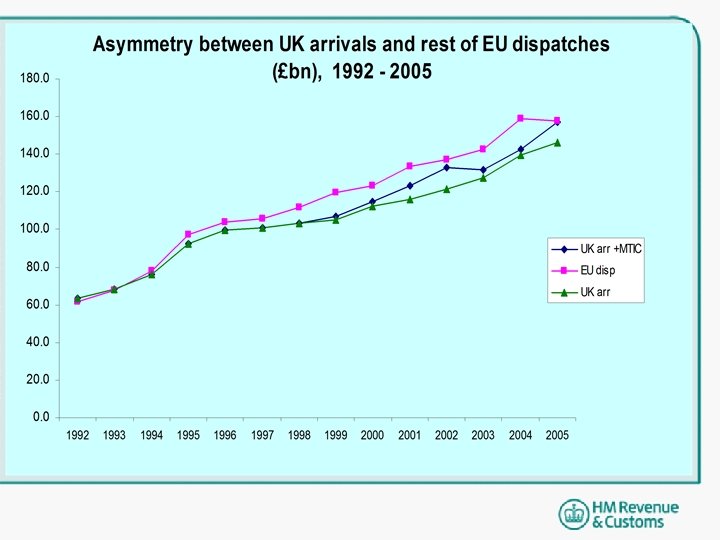
The adjustments • UK’s methodology includes information uncovered by Customs operational activity • The estimates were corroborated by: – national estimates of VAT loss – reduced EU trade asymmetries – smaller imbalances in the relevant products in the ONS annual supply and use analysis
Next Steps August 2003 to Feb 2005
Project 2 • Reviewed methodology • Looked at Acquisition Fraud • Arranged to include the estimates in the Overseas Trade Statistics • Compared data sources: – Arrivals, ESL purchases, VAT declarations – Dispatches, ESL sales, VAT declarations
Project 2 • Investigated how best to incorporate the adjustments for 1999 – 2004 into HMRC’s Overseas Trade Statistics – Uses 3 month rolling average • Second joint article published Feb 2005
Further developments Non-EU trade
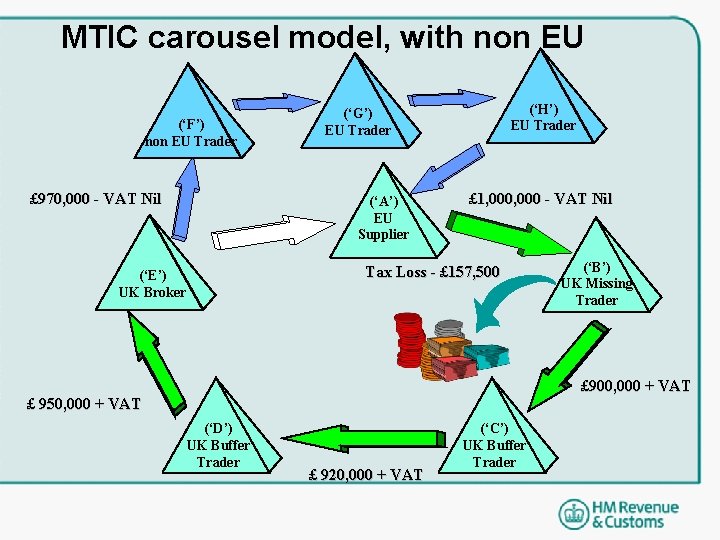
MTIC carousel model, with non EU (‘F’) non EU Trader £ 970, 000 - VAT Nil (‘H’) EU Trader (‘G’) EU Trader (‘A’) EU Supplier £ 1, 000 - VAT Nil Tax Loss - £ 157, 500 (‘E’) UK Broker (‘B’) UK Missing Trader £ 900, 000 + VAT £ 950, 000 + VAT (‘D’) UK Buffer Trader £ 920, 000 + VAT (‘C’) UK Buffer Trader
Third Project
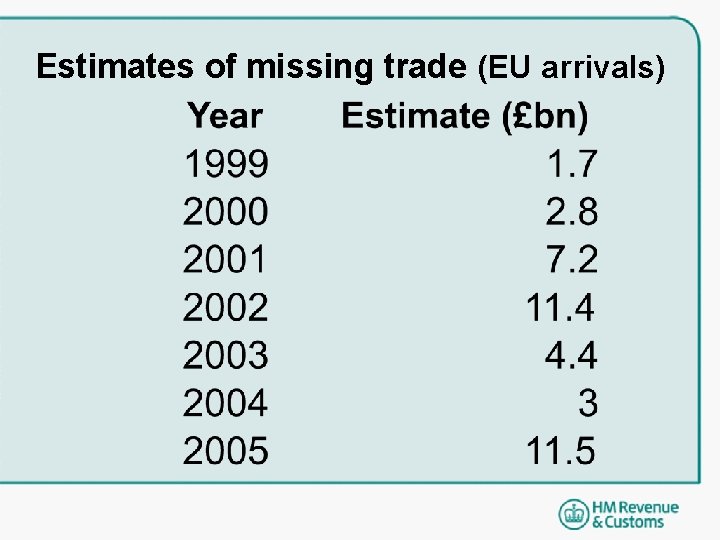
Estimates of missing trade (EU arrivals)
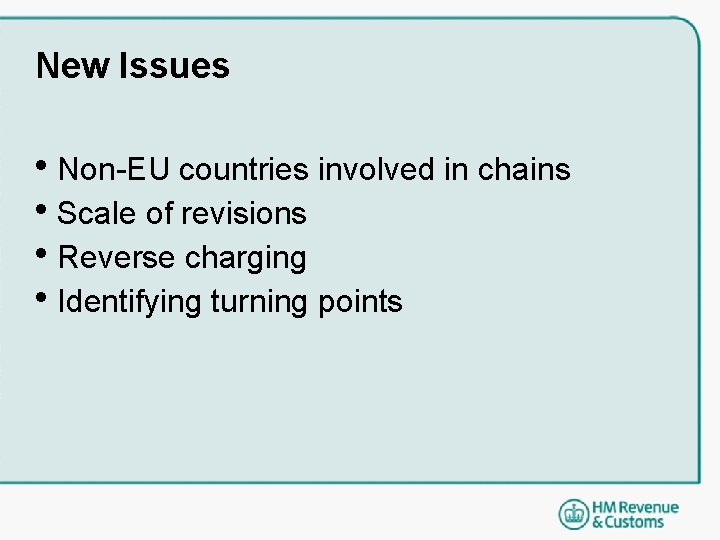
New Issues • Non-EU countries involved in chains • Scale of revisions • Reverse charging • Identifying turning points
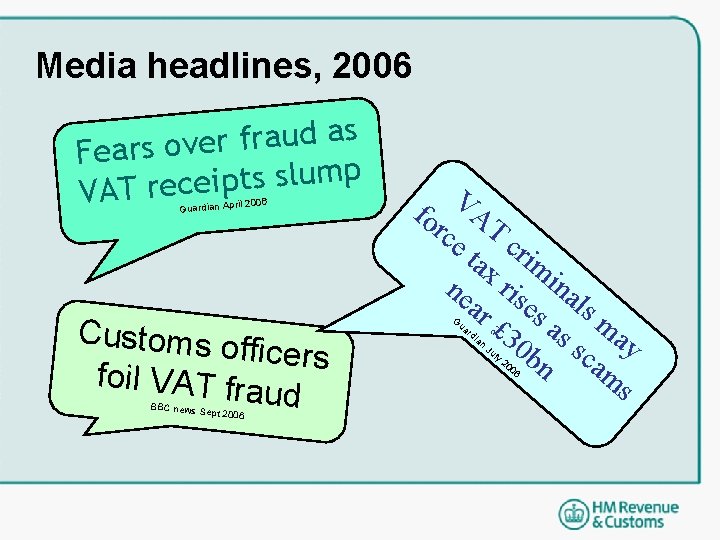
Media headlines, 2006 s a d u a r f r e v Fears o p m u l s s t p i e c VAT re Guardian Apr il 2006 Customs of ficers foil VAT fra ud BBC news Sept 2006 fo VAT rc e t cr ax im ne ris ina ar es ls £ 3 as ma 0 b sc y n am s G ua rd i an Ju ly 20 0 6
Ongoing work • We continue to produce monthly estimates of the impact of the fraud for the OTS, Bo. P and Eurostat trade data • We monitor changes in the pattern of trade – commodity – country
Lessons Learnt • Need to continually monitor changes • Close links between SATU and Customs important • Conflicting requirements • Use of a range of data
If you want more information please contact: sandra. tudor@hmrc. gsi. gov. uk andrew. kochen@hmrc. gsi. gov. uk