Tax accounting Introduction contents Definition Purposes of Taxation
- Slides: 18
Tax accounting Introduction
contents: • Definition • Purposes of Taxation • Major types of tax • Development of the Egyptian income tax • Law 91/2005
Definition Tax : a cash levy collected by the state from individuals and establishments in accordance with determined rules with the aim of financing public expenditures
Purposes of Taxation : 1. Financing government spending 2. Reduce gap between rich and poor (Progressive tax system) 3. Reduce consumption of demerit Goods (Examples include cigarette tax) 4. Control Inflation 5. Balance of payments (increasing the tariffs will cause a fall in demand for the imported goods. ) 6. Protecting local industries
Major types of tax 1. Direct and indirect 2. Qualitative and unified 3. Personal and in-kind taxes 4. Proportional and progressive 5. Taxes paid directly by tax payer to tax department and taxes deducted at source
Major types of tax Direct and indirect : Direct tax : § tax in which the person who bears the tax is the one who pays the tax § as tax on salaries Indirect tax : tax in which the tax is transferred to another person as sales tax
Major types of tax Qualitative and unified : Qualitative tax : Tax imposed on each kind of income separately Unified tax : Tax imposed on total incomes regarding their sources
Major types of tax Personal and in-kind taxes : Personal tax : tax that considers the family charge exemption § As salaries tax § In-kind tax : tax that don’t consider the family charge exemption As sales tax
Major types of tax Taxes paid directly by tax payer to tax department and taxes deducted at source : § Taxes paid directly by tax payer to tax department : As commercial tax and non commercial tax § taxes deducted at source : As tax on salaries
Development of the Egyptian income tax 5 stages for the Egyptian income tax development : § Stage 1 : law 14/1939 § Stage 2 : law 99/1949 § Stage 3 : law 157/1981 § Stage 4 : law 187/1993 § Stage 5 : law 91/2005
Law 91/2005 • This new law is intended to follow the best taxation bases and practices. • It is intended to play the role of the primary axis of taxation , administration and reform , meanwhile simplifying procedures.
Law 91/2005 The most significant features of this law : tax legislation Mutual trust developing Tax administration Tax justice Balancing various objective
Mistrust cases Simplifying procedures Widening the tax exemption Eliminating family burden Law 91/2005 The new law is dependent on number of principals :
Law 91/2005 - features • Eliminating family burden : A. The reduction of tax price to 20% B. Raising the limit of exemption to 5000 L. E to the benefit of natural persons C. Simplifying tax treatment D. 5 years exemption for the projects financed by the social fund E. 4000 L. E personal exemption for salaries and wages
Law 91/2005 - features • Widening the tax exemption : For the projects outside official scope by setting disputes in a sound manner
Law 91/2005 - features • Simplifying procedures : A. Authorizing citizen declaration as the basis of tax declaration B. Optional in advance payment to allow tax payers to pay in advance till treatment is being settled at the end of the year C. maintaining the cancelled exemption for the projects set up before the new law is applied
Law 91/2005 - features • Mistrust cases : To encourage taxpayers to cooperate with the tax authority: A. Setting up independent appeals committees B. Determining the taxpayer’s rights and extent of tax authority
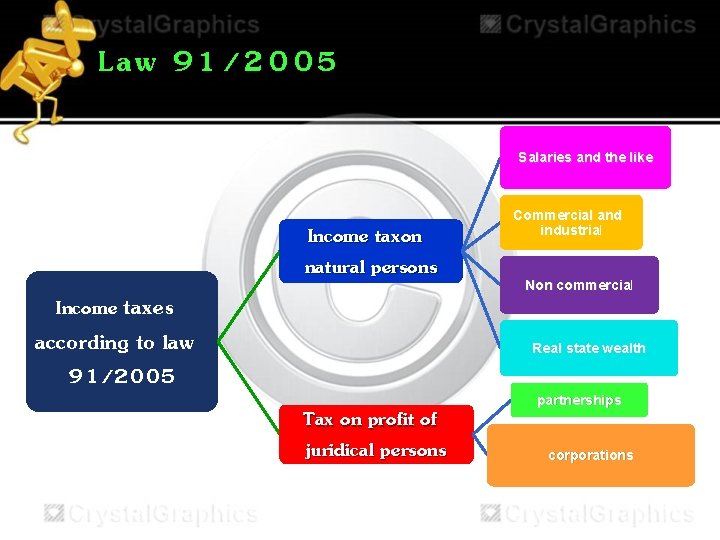
Law 91/2005 Salaries and the like Income taxon natural persons Income taxes according to law 91/2005 Commercial and industrial Non commercial Real state wealth Tax on profit of juridical persons partnerships corporations