QPS Evaluation Services Group Retirement Savings Plan RRSP
- Slides: 31
QPS Evaluation Services Group Retirement Savings Plan (RRSP) & Deferred Profit Sharing Plan (DPSP)
Agenda § Introduce Manulife Financial § Review plan details § How to make an informed investment decision Introduce you to the Steps Retirement Program § Enrolling into the new QPS Evaluation Services Group RSP & DPSP § Tools to manage your account § Advantage of the plan § What’s next § Questions
Manulife’s Role… § Provide the Company with administration and recordkeeping services § Provides QPS Evaluation Service employees with… » Communication services » Online Retirement Planning tools » Semi-annual member statements » Tax receipts (annually in Jan and March) § Ongoing service and support to members Toll-free Customer Service (8 am – 6 pm EST) Internet and IVR access 24/7
QPS Evaluation Services Group RRSP & DPSP A review of your plan design and provisions
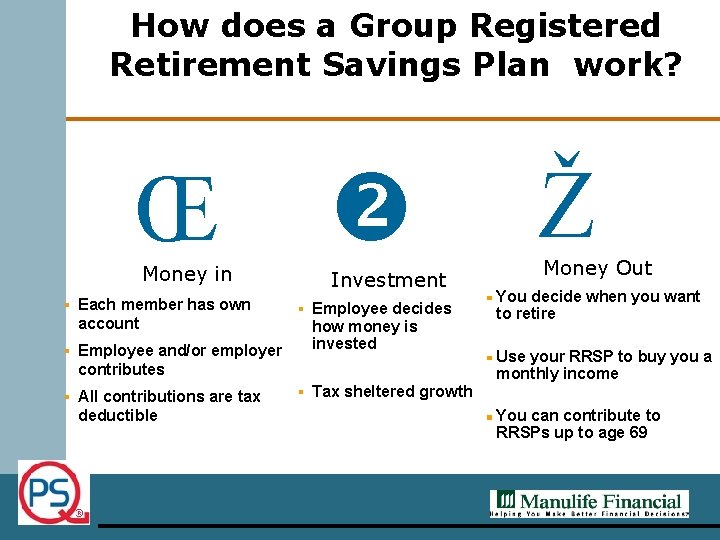
How does a Group Registered Retirement Savings Plan work? Œ Money in § Each member has own account § Employee and/or employer contributes § All contributions are tax deductible Investment § § Employee decides how money is invested Ž Money Out You decide when you want to retire Use your RRSP to buy you a monthly income Tax sheltered growth You can contribute to RRSPs up to age 69
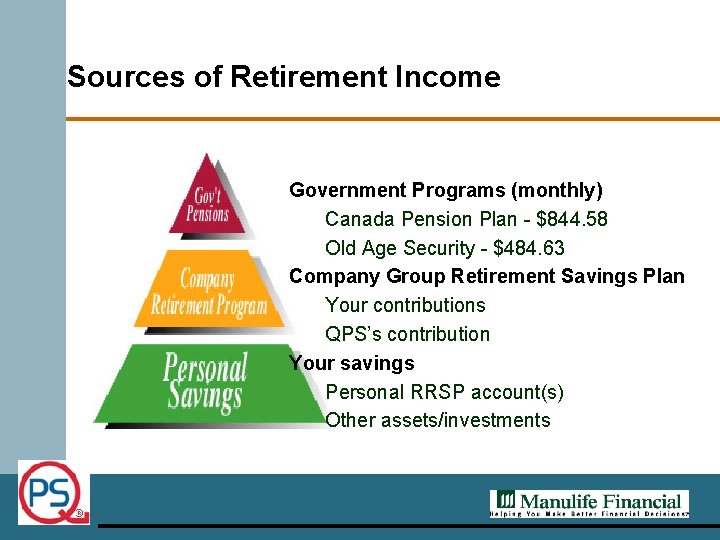
Sources of Retirement Income Government Programs (monthly) Canada Pension Plan - $844. 58 Old Age Security - $484. 63 Company Group Retirement Savings Plan Your contributions QPS’s contribution Your savings Personal RRSP account(s) Other assets/investments
Plan details Effective date § August 2006 Eligibility § All full time are eligible to join the plan after 3 months of continuous service
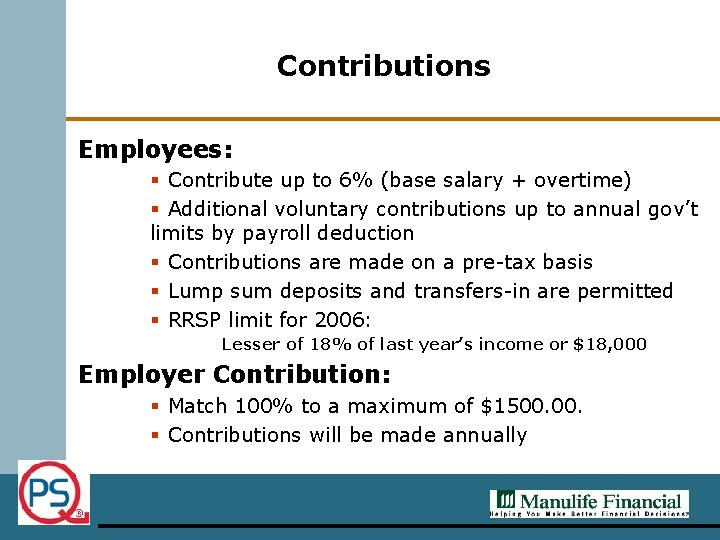
Contributions Employees: § Contribute up to 6% (base salary + overtime) § Additional voluntary contributions up to annual gov’t limits by payroll deduction § Contributions are made on a pre-tax basis § Lump sum deposits and transfers-in are permitted § RRSP limit for 2006: Lesser of 18% of last year’s income or $18, 000 Employer Contribution: § Match 100% to a maximum of $1500. § Contributions will be made annually
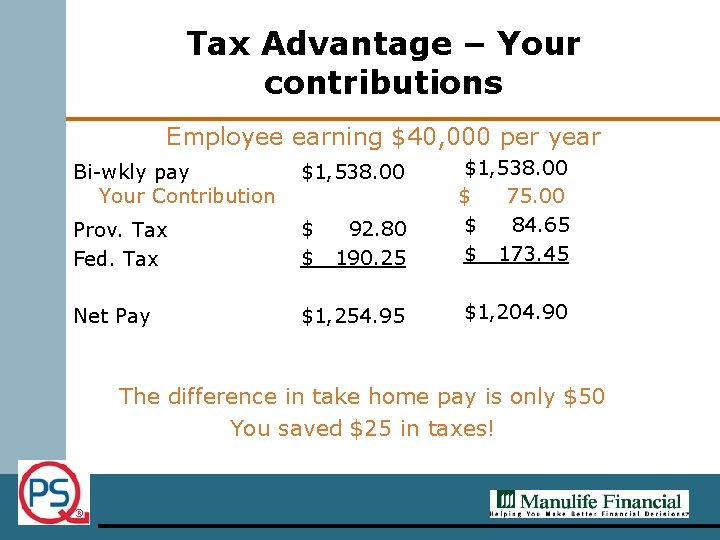
Tax Advantage – Your contributions Employee earning $40, 000 per year Bi-wkly pay Your Contribution $1, 538. 00 Prov. Tax Fed. Tax $ $ 92. 80 190. 25 $1, 538. 00 $ 75. 00 $ 84. 65 $ 173. 45 Net Pay $1, 254. 95 $1, 204. 90 The difference in take home pay is only $50 You saved $25 in taxes!
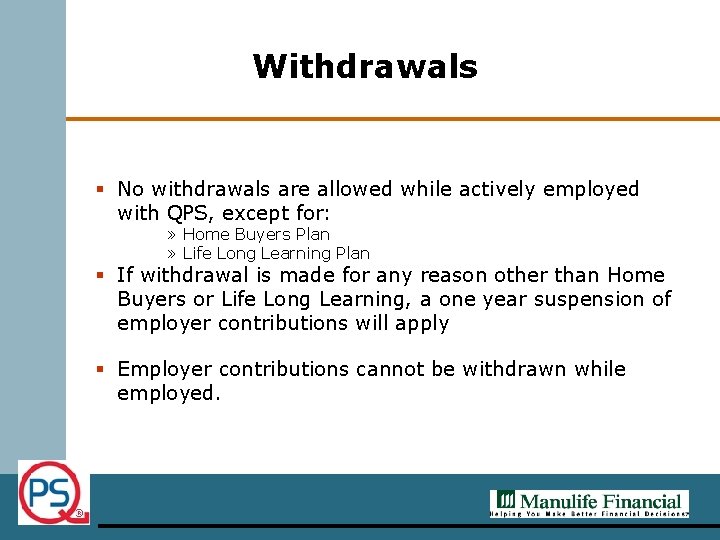
Withdrawals § No withdrawals are allowed while actively employed with QPS, except for: » Home Buyers Plan » Life Long Learning Plan § If withdrawal is made for any reason other than Home Buyers or Life Long Learning, a one year suspension of employer contributions will apply § Employer contributions cannot be withdrawn while employed.
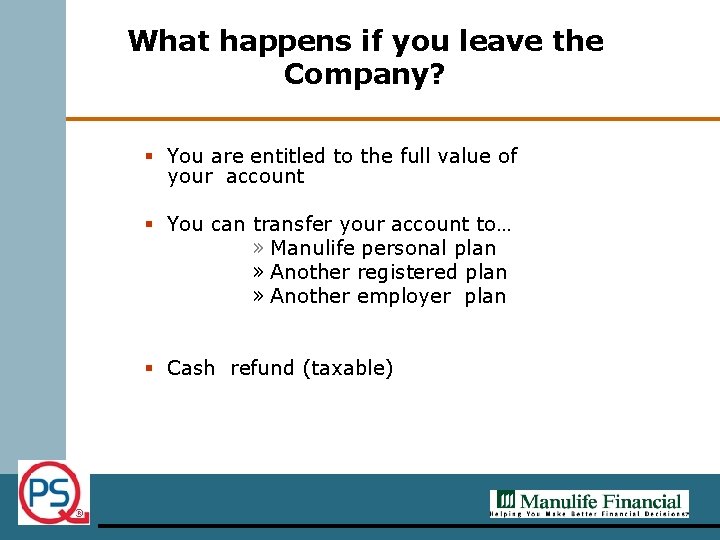
What happens if you leave the Company? § You are entitled to the full value of your account § You can transfer your account to… » Manulife personal plan » Another registered plan » Another employer plan § Cash refund (taxable)
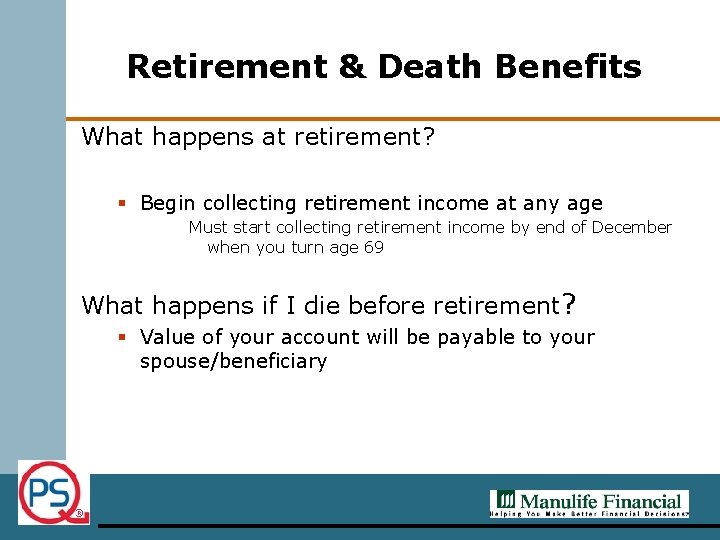
Retirement & Death Benefits What happens at retirement? § Begin collecting retirement income at any age Must start collecting retirement income by end of December when you turn age 69 What happens if I die before retirement? § Value of your account will be payable to your spouse/beneficiary
Selecting investments for your Group RRSP/DPSP Providing you with the power to make choices about your retirement
Which investments are best for me?
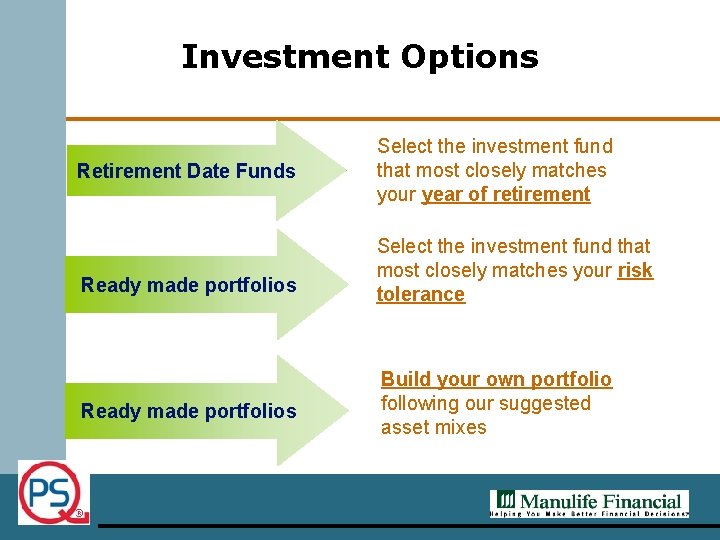
Investment Options Retirement Date Funds Ready made portfolios Select the investment fund that most closely matches your year of retirement Select the investment fund that most closely matches your risk tolerance Build your own portfolio following our suggested asset mixes
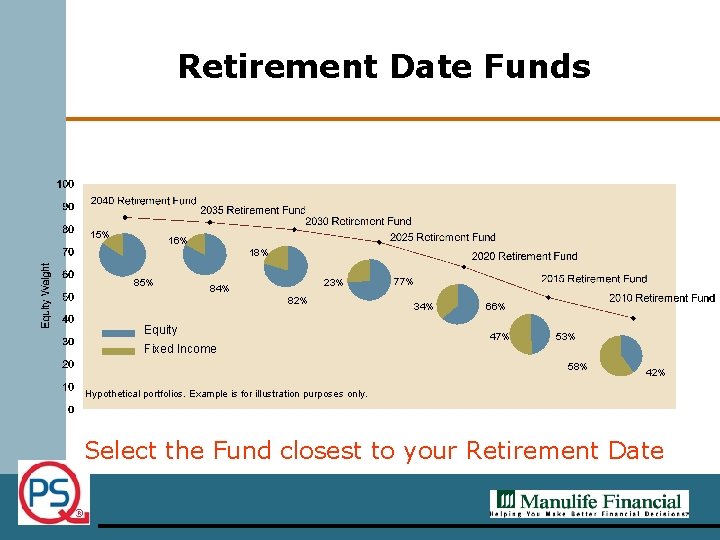
Retirement Date Funds § (7) Choices § Well balanced portfolio inside a single fund § Each fund represents a future retirement date § Balance of the funds changes as you near retirement
Retirement Date Funds 15% 16% 18% 85% 23% 84% 82% Equity 77% 34% 66% 47% 53% Fixed Income 58% 42% Hypothetical portfolios. Example is for illustration purposes only. Select the Fund closest to your Retirement Date
What are Asset Allocation Funds? Ready-made portfolios in a single fund 1. Simple and easy – little homework 2. Diversified by asset class, style, manager 3. Manulife is responsible for monitoring and rebalancing periodically
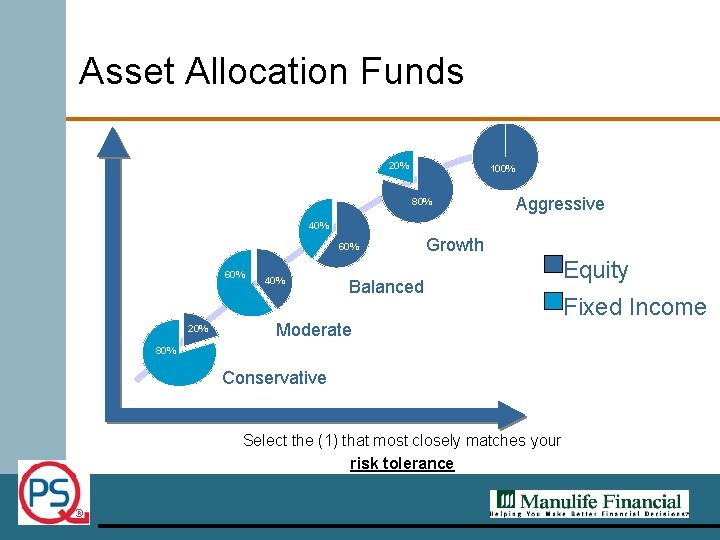
Asset Allocation Funds 20% 100% 80% Aggressive 40% 60% 20% 40% Growth Balanced Moderate 80% Conservative Select the (1) that most closely matches your risk tolerance Equity Fixed Income
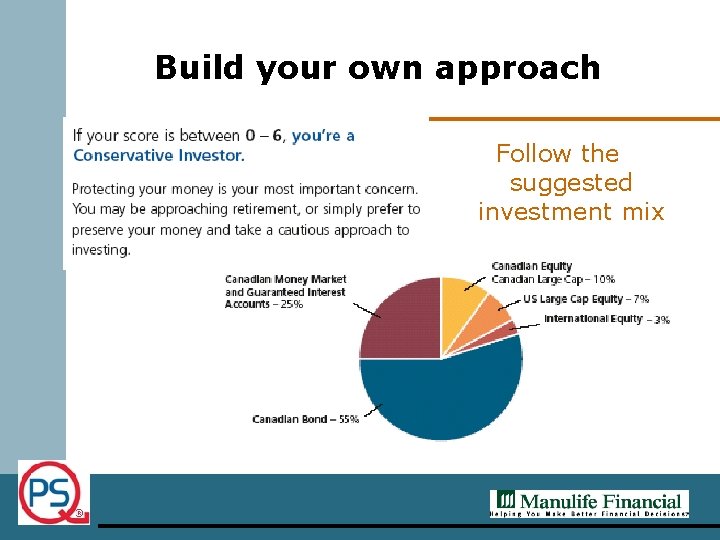
Build your own approach Follow the suggested investment mix
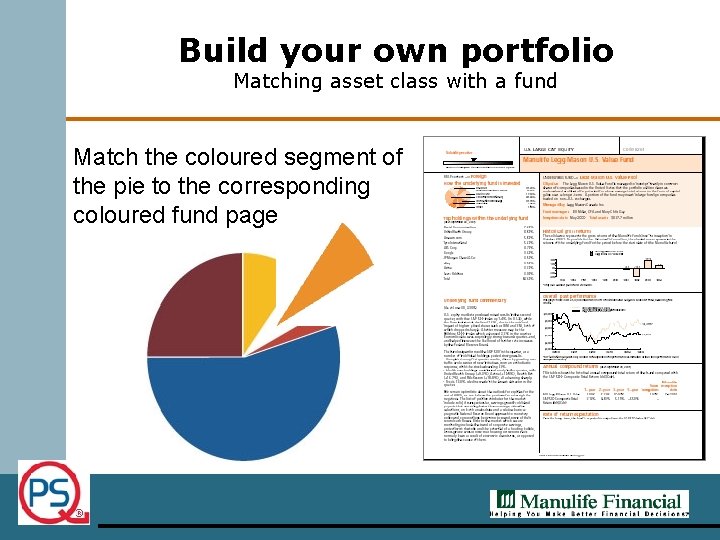
Build your own portfolio Matching asset class with a fund Match the coloured segment of the pie to the corresponding coloured fund page
Investment Fees § On average, retail investment management fees; ie banks, range between 2. 00 and 5. 00% § There are no sales charges, transaction fees, front/back-end loads associated with the investment options
Management Fee Comparison Royal Balanced Fund CIBC Balanced TD Balanced Bank of Montreal Asset Allocation 3. 00% 3. 35% 3. 20% 3. 13% MLI Mc. Lean Budden Balanced Fund 2. 80%
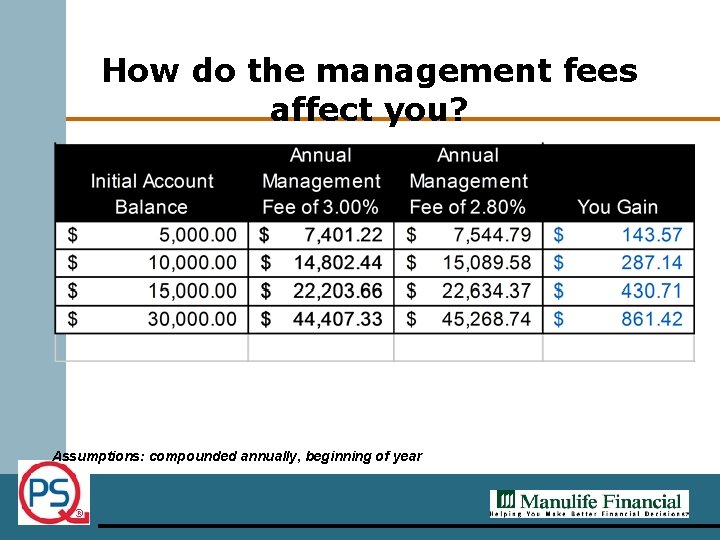
How do the management fees affect you? Assumptions: compounded annually, beginning of year
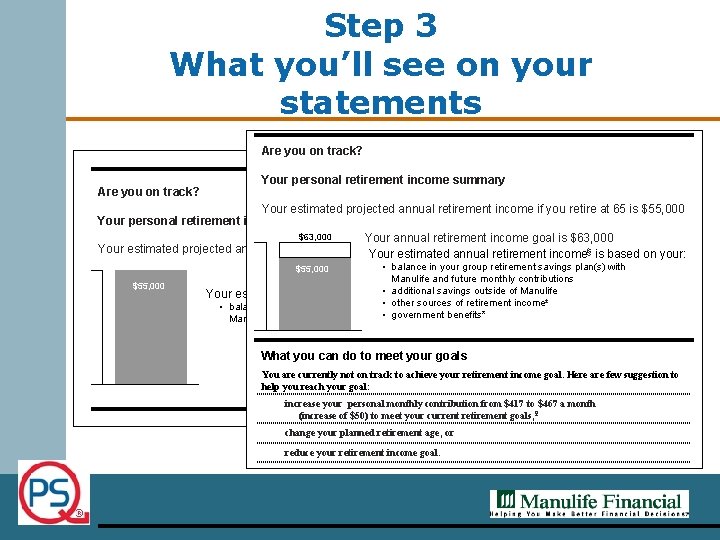
Step 3 What you’ll see on your statements Are you on track? Your personal retirement income summary Are you on track? Your estimated projected annual retirement income if you retire at 65 is $55, 000 Your personal retirement income summary $63, 000 Your annual retirement income goal is $63, 000 Your estimated projected annual retirement income. Your if youestimated retire at 65 is $55, 000 annual retirement income§ is based on your: • balance in your group retirement savings plan(s) with Manulife and future monthly contributions • additional savings of Manulife § is Your estimated annual retirement income basedoutside on your: • other sources of retirement income± • balance in your group retirement savings plan(s) with • government benefits* Manulife and future monthly contributions $55, 000 What you can do to meet your goals You are currently not on track to achieve your retirement income goal. Here are few suggestion to help you reach your goal: increase your personal monthly contribution from $417 to $467 a month (increase of $50) to meet your current retirement goals, ¥ change your planned retirement age, or reduce your retirement income goal.
Getting started with Manulife
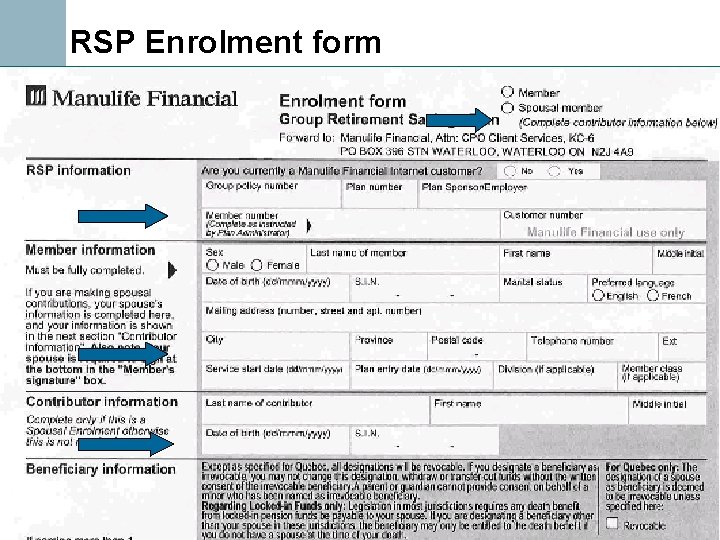
RSP Enrolment form
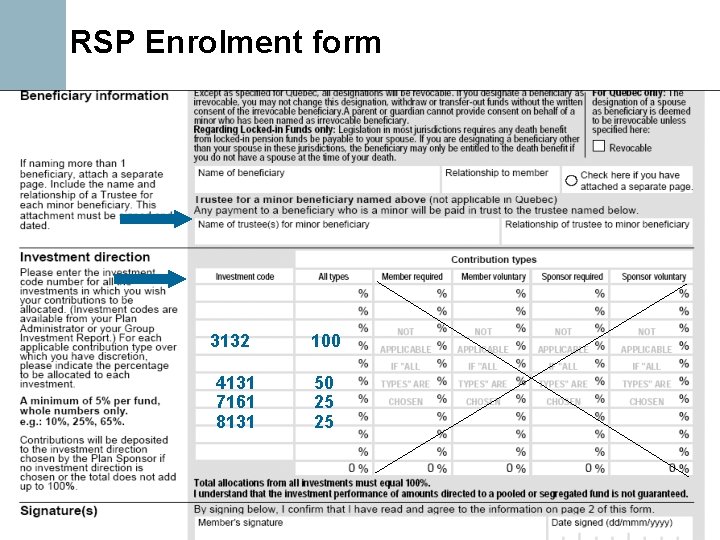
RSP Enrolment form 3132 4131 7161 8131 100 50 25 25
Default investment option If you do not complete the investment section, your contributions will be invested in the plan default until otherwise instructed by you. The plan default is the Manulife Money Market Fund
Benefits of your plan • Immediate tax savings • Wide array of investment options • Easy access to your account information • Make investment changes at any time • Manage and monitor your account easily • Wholesale investment management fees