LESSON 12 1 Capital Stock Transactions CENTURY 21
- Slides: 9
LESSON 12 -1 Capital Stock Transactions CENTURY 21 ACCOUNTING © Thomson/South-Western
2 Capital Stock Transactions n As a corporation grows, it may require additional capital to finance its expansion n Articles of incorporation are usually written to permit a corporation to issue more shares of stock than it sold to initial investors n The corporation may issue stock: n At par value n Above par value n Below par value n For assets other than cash CENTURY 21 ACCOUNTING © Thomson/South-Western LESSON 12 -1
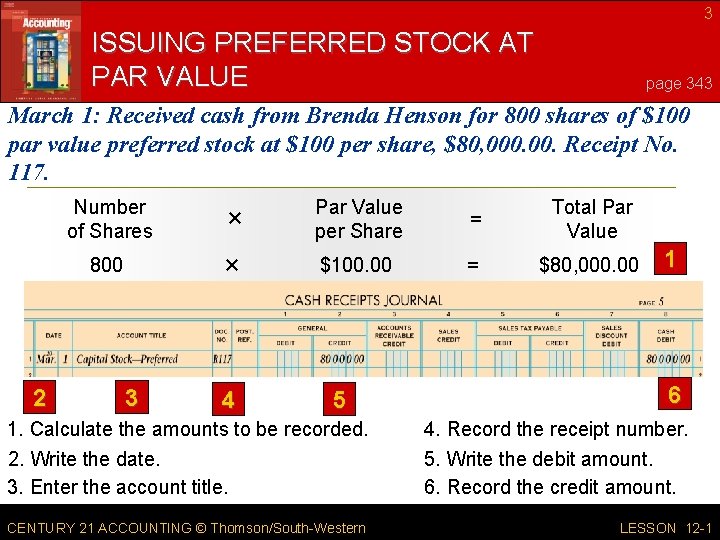
3 ISSUING PREFERRED STOCK AT PAR VALUE page 343 March 1: Received cash from Brenda Henson for 800 shares of $100 par value preferred stock at $100 per share, $80, 000. Receipt No. 117. 2 Number of Shares × Par Value per Share = Total Par Value 800 × $100. 00 = $80, 000. 00 3 4 5 1 6 1. Calculate the amounts to be recorded. 4. Record the receipt number. 2. Write the date. 3. Enter the account title. 5. Write the debit amount. 6. Record the credit amount. CENTURY 21 ACCOUNTING © Thomson/South-Western LESSON 12 -1
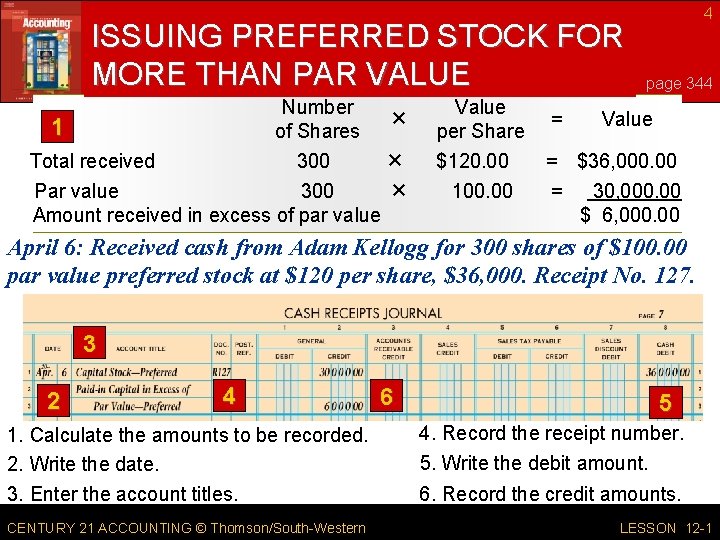
ISSUING PREFERRED STOCK FOR MORE THAN PAR VALUE Number of Shares 300 1 Total received × Par value 300 Amount received in excess of par value × × Value per Share $120. 00 100. 00 = 4 page 344 Value = $36, 000. 00 = 30, 000. 00 $ 6, 000. 00 April 6: Received cash from Adam Kellogg for 300 shares of $100. 00 par value preferred stock at $120 per share, $36, 000. Receipt No. 127. 3 2 4 1. Calculate the amounts to be recorded. 2. Write the date. 3. Enter the account titles. CENTURY 21 ACCOUNTING © Thomson/South-Western 6 5 4. Record the receipt number. 5. Write the debit amount. 6. Record the credit amounts. LESSON 12 -1
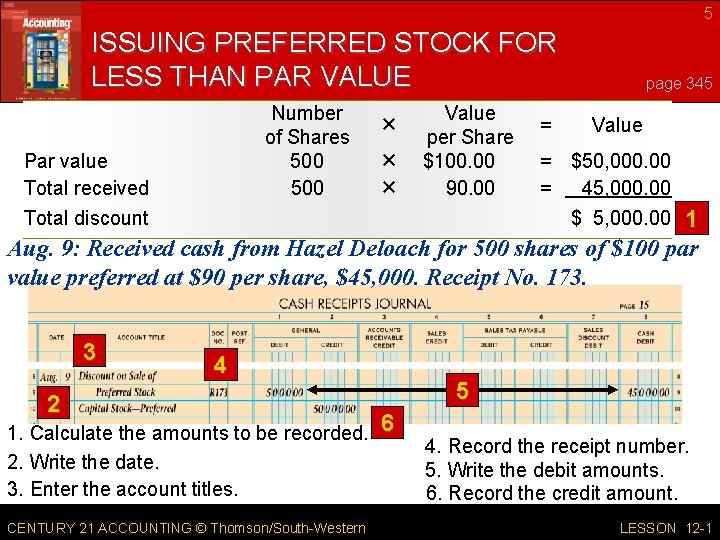
5 ISSUING PREFERRED STOCK FOR LESS THAN PAR VALUE Number of Shares 500 Par value Total received Total discount × × × Value per Share $100. 00 90. 00 = page 345 Value = $50, 000. 00 = 45, 000. 00 $ 5, 000. 00 1 Aug. 9: Received cash from Hazel Deloach for 500 shares of $100 par value preferred at $90 per share, $45, 000. Receipt No. 173. 3 4 2 1. Calculate the amounts to be recorded. 2. Write the date. 3. Enter the account titles. CENTURY 21 ACCOUNTING © Thomson/South-Western 5 6 4. Record the receipt number. 5. Write the debit amounts. 6. Record the credit amount. LESSON 12 -1
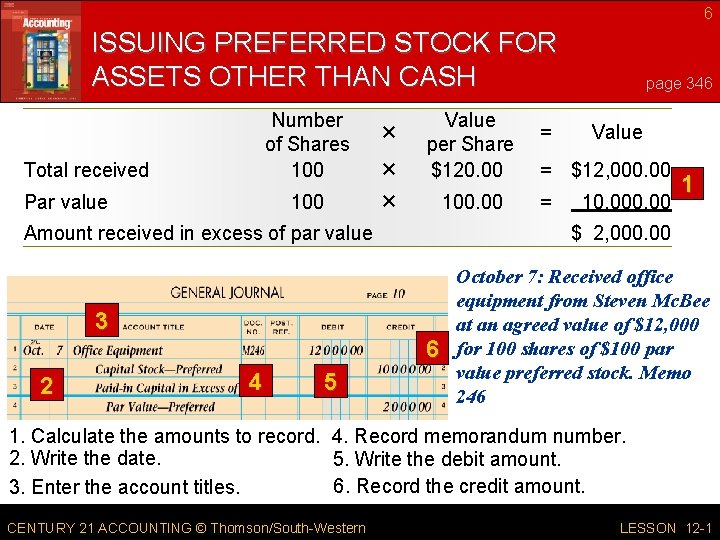
6 ISSUING PREFERRED STOCK FOR ASSETS OTHER THAN CASH Number of Shares 100 Total received Par value 100 × × × Value per Share $120. 00 100. 00 Amount received in excess of par value 6 4 5 Value = $12, 000. 00 = 10, 000. 00 1 $ 2, 000. 00 3 2 = page 346 October 7: Received office equipment from Steven Mc. Bee at an agreed value of $12, 000 for 100 shares of $100 par value preferred stock. Memo 246 1. Calculate the amounts to record. 4. Record memorandum number. 2. Write the date. 5. Write the debit amount. 6. Record the credit amount. 3. Enter the account titles. CENTURY 21 ACCOUNTING © Thomson/South-Western LESSON 12 -1
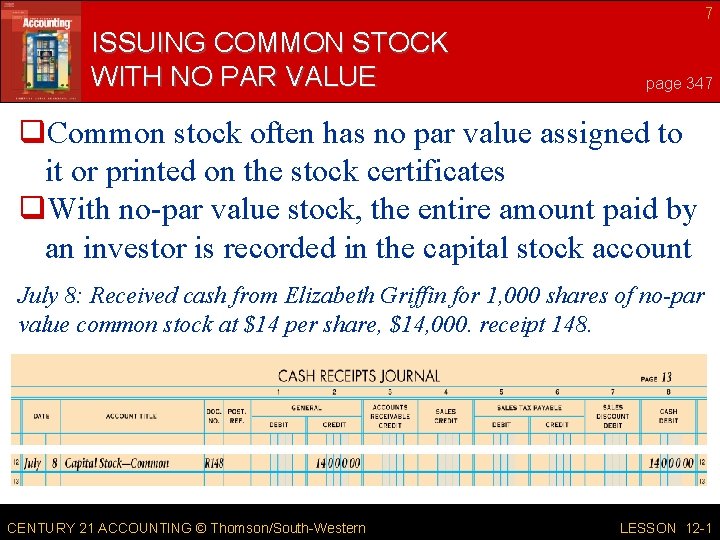
7 ISSUING COMMON STOCK WITH NO PAR VALUE page 347 q. Common stock often has no par value assigned to it or printed on the stock certificates q. With no-par value stock, the entire amount paid by an investor is recorded in the capital stock account July 8: Received cash from Elizabeth Griffin for 1, 000 shares of no-par value common stock at $14 per share, $14, 000. receipt 148. CENTURY 21 ACCOUNTING © Thomson/South-Western LESSON 12 -1
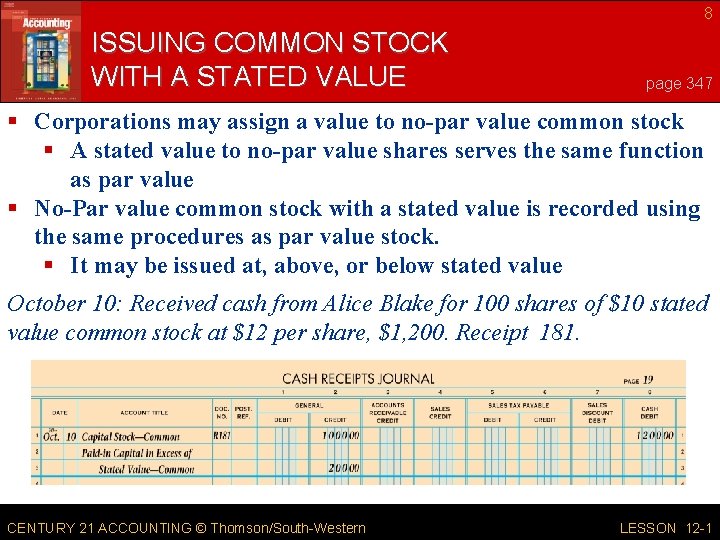
8 ISSUING COMMON STOCK WITH A STATED VALUE page 347 § Corporations may assign a value to no-par value common stock § A stated value to no-par value shares serves the same function as par value § No-Par value common stock with a stated value is recorded using the same procedures as par value stock. § It may be issued at, above, or below stated value October 10: Received cash from Alice Blake for 100 shares of $10 stated value common stock at $12 per share, $1, 200. Receipt 181. CENTURY 21 ACCOUNTING © Thomson/South-Western LESSON 12 -1
9 TERM REVIEW page 348 n discount on capital stock CENTURY 21 ACCOUNTING © Thomson/South-Western LESSON 12 -1