Speaking with you today Stanley Porter Deloitte Consulting
- Slides: 3
Speaking with you today Stanley Porter Deloitte Consulting LLP Shemin V. Proctor Andrews Kurth Pamela Tsang Morgan Lewis Andrea Wang Lucan K&L Gates Grace C. Yeh Exxon Mobil Corporation 1 Copyright © 2015 Deloitte Development LLC. All rights reserved.
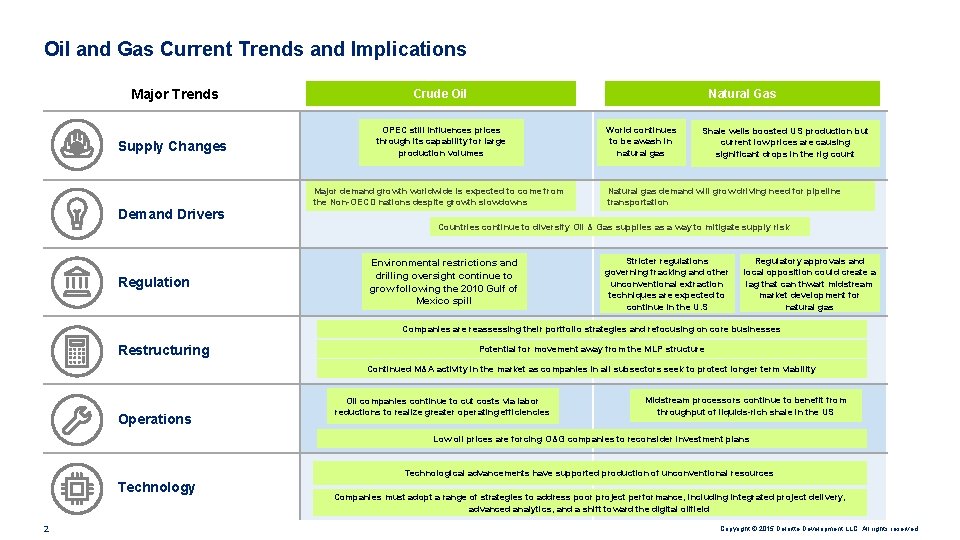
Oil and Gas Current Trends and Implications Major Trends Crude Oil Supply Changes OPEC still influences prices through its capability for large production volumes Demand Drivers Regulation Natural Gas Major demand growth worldwide is expected to come from the Non-OECD nations despite growth slowdowns World continues to be awash in natural gas Shale wells boosted US production but current low prices are causing significant drops in the rig count Natural gas demand will grow driving need for pipeline transportation Countries continue to diversify Oil & Gas supplies as a way to mitigate supply risk Environmental restrictions and drilling oversight continue to grow following the 2010 Gulf of Mexico spill Stricter regulations governing fracking and other unconventional extraction techniques are expected to continue in the U. S Regulatory approvals and local opposition could create a lag that can thwart midstream market development for natural gas Companies are reassessing their portfolio strategies and refocusing on core businesses Restructuring Potential for movement away from the MLP structure Continued M&A activity in the market as companies in all subsectors seek to protect longer term viability Operations Oil companies continue to cut costs via labor reductions to realize greater operating efficiencies Midstream processors continue to benefit from throughput of liquids-rich shale in the US Low oil prices are forcing O&G companies to reconsider investment plans Technological advancements have supported production of unconventional resources Technology 2 Companies must adopt a range of strategies to address poor project performance, including integrated project delivery, advanced analytics, and a shift toward the digital oilfield Copyright © 2015 Deloitte Development LLC. All rights reserved.
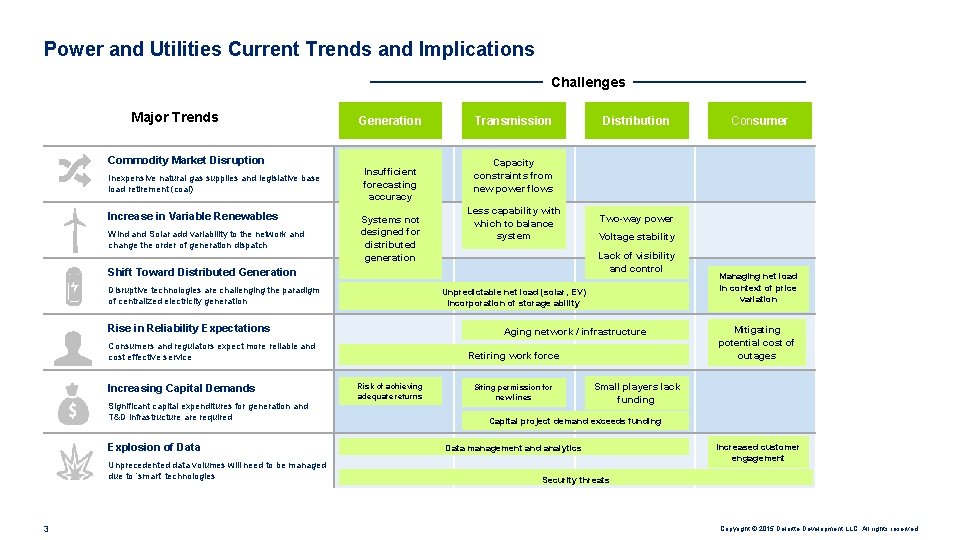
Power and Utilities Current Trends and Implications Challenges Major Trends Commodity Market Disruption Inexpensive natural gas supplies and legislative base load retirement (coal) Increase in Variable Renewables Wind and Solar add variability to the network and change the order of generation dispatch Generation Insufficient forecasting accuracy Systems not designed for distributed generation Transmission Less capability with which to balance system Significant capital expenditures for generation and T&D infrastructure are required Explosion of Data Unprecedented data volumes will need to be managed due to ‘smart’ technologies 3 Voltage stability Lack of visibility and control Aging network / infrastructure Consumers and regulators expect more reliable and cost effective service Increasing Capital Demands Two-way power Unpredictable net load (solar, EV) Incorporation of storage ability Rise in Reliability Expectations Retiring work force Risk of achieving adequate returns Consumer Capacity constraints from new power flows Shift Toward Distributed Generation Disruptive technologies are challenging the paradigm of centralized electricity generation Distribution Siting permission for new lines Managing net load in context of price variation Mitigating potential cost of outages Small players lack funding Capital project demand exceeds funding Data management and analytics Increased customer engagement Security threats Copyright © 2015 Deloitte Development LLC. All rights reserved.