Ministry of Finance of Georgia State Treasury of

- Slides: 9
Ministry of Finance of Georgia State Treasury of Georgia Performance Measurement and Monitoring PEMPAL Tirana May 2018
Strategic Documents • Key Country Development Areas and Indicators (BDD); • Public Finance Management Strategy; • Annual PFM Action Plan; • Program-based Budget; • Anticorruption Strategy.
Goals and Priorities • Introduction of IPSAS-based accrual accounting; • Developing a unified public finance management information system; • Finance management reform.
Key Performance Indicators • All IPSAS standards (IPSAS 18, IPSAS 20, IPSAS 25, IPSAS 26, IPSAS 32) mentioned in action plans have been implemented in all budget institutions; • Guidelines have been drafted for further (2019) implementation of IPSAS standards mentioned in action plans; • As a result of workshops and working meetings held, local government officials are aware of IPSAS standards; • Analytical data have been prepared on revenue accrual accounting in the unified treasury book; • E-treasury Finance Management Module has been upgraded; • Accounting and reporting are continuously being improved in terms of information capacity, timeliness and transparency.
Tools Used for Performance Monitoring • PFM Working Group; • Budget users’ report on programs and sub-programs; • Quarterly Report; • Anticorruption Working Group; • Self-assessment based on PEFA indicators.
Expenditure Arrears Assessment • Payments and debt accounting are regulated by the following documents: – – – Georgia’s Budget Code; Annual Budget; Guidelines on Payments; Guidelines on Accounting; Contract terms (number of days from arrival of documents, количество дней с момента прибытия документов, guaranteed custody); – Expert Evaluation Bureau’s Conclusion; • The State Treasury has information on commitments registered in the IT system; • Institutions provide information on expenditure arrears in reference articles of their financial statements. • Indicator 22. 1. score - «A» .
Expenditure Arrears Monitoring • The Treasury receives data on expenditure arrears annually upon completion of each fiscal year; • Debt repayment rule is an effective arrears monitoring mechanism; • Indicator 22. 2. score - «С» ; • Within the framework of on-going reforms, on January 1, 2018, an Invoice Module providing real-time information on expenditure arrears was launched.
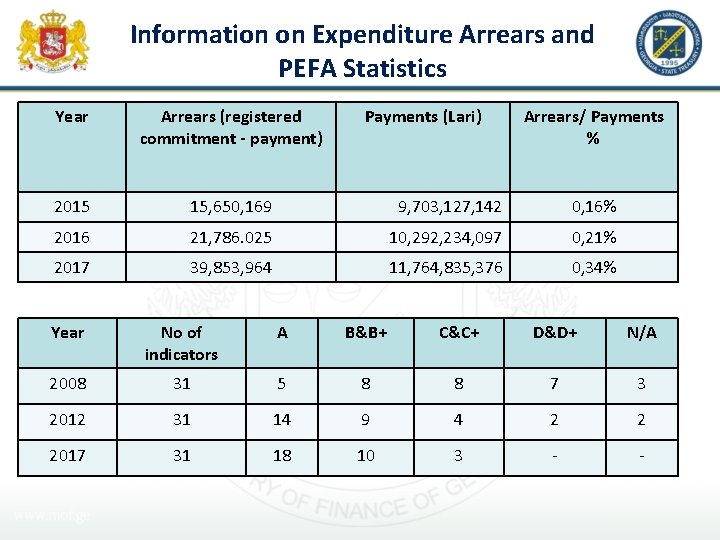
Information on Expenditure Arrears and PEFA Statistics Year Arrears (registered commitment - payment) Payments (Lari) Arrears/ Payments % 2015 15, 650, 169 9, 703, 127, 142 0, 16% 2016 21, 786. 025 10, 292, 234, 097 0, 21% 2017 39, 853, 964 11, 764, 835, 376 0, 34% Year No of indicators A B&B+ C&C+ D&D+ N/A 2008 31 5 8 8 7 3 2012 31 14 9 4 2 2 2017 31 18 10 3 - -
Treasury of Georgia Performance Measurement and Monitoring Thank you for your attention! www. mof. ge www. treasury. gov. ge May, 2018