Comparing Merchandising and Manufacturing Activities Merchandisers Manufacturers v
- Slides: 14
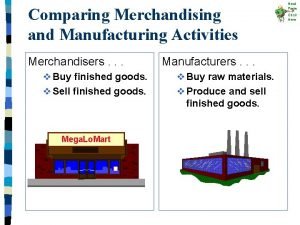
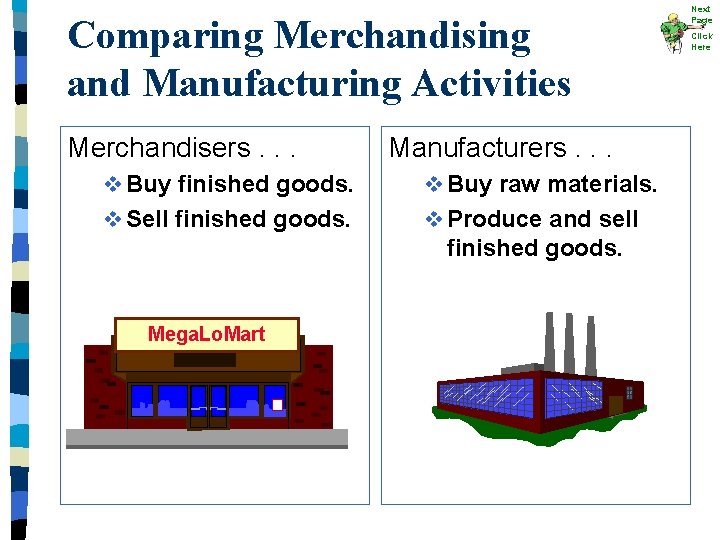
Comparing Merchandising and Manufacturing Activities Merchandisers. . . Manufacturers. . . v Buy finished goods. v Buy raw materials. v Sell finished goods. v Produce and sell finished goods. Mega. Lo. Mart Next Page Click Here
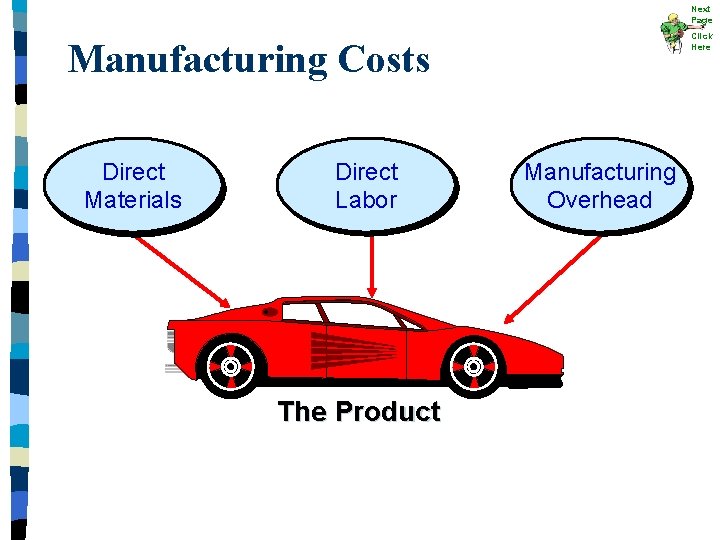
Next Page Click Here Manufacturing Costs Direct Materials Direct Labor The Product Manufacturing Overhead
Next Page Direct Materials Those materials that become an integral part of the product and that can be conveniently traced directly to it. Example: A radio installed in an automobile Click Here
Next Page Direct Labor Those labor costs that can be easily traced to individual units of product. Example: Wages paid to automobile assembly workers Click Here
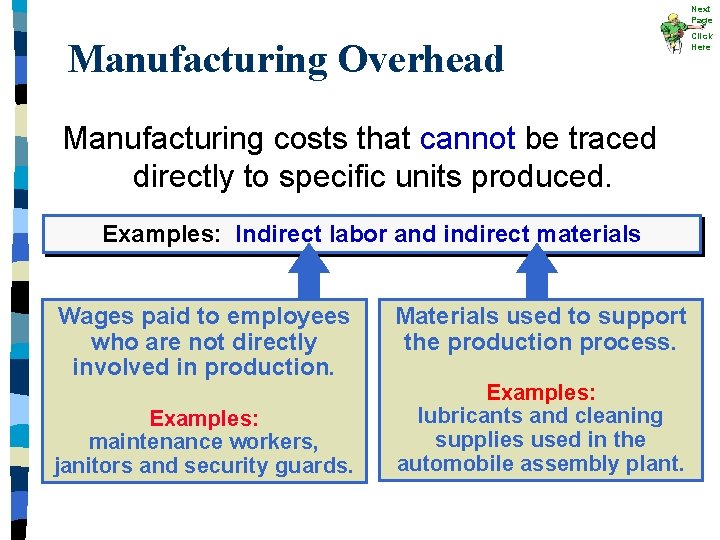
Next Page Manufacturing Overhead Manufacturing costs that cannot be traced directly to specific units produced. Examples: Indirect labor and indirect materials Wages paid to employees who are not directly involved in production. Examples: maintenance workers, janitors and security guards. Materials used to support the production process. Examples: lubricants and cleaning supplies used in the automobile assembly plant. Click Here
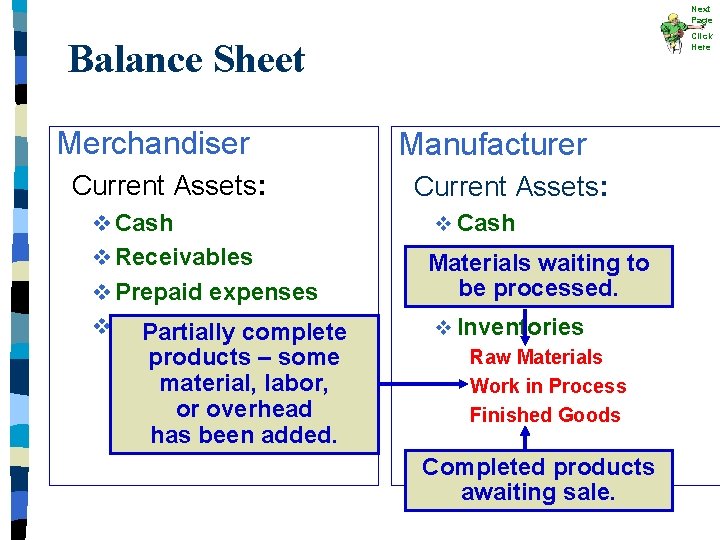
Next Page Click Here Balance Sheet Merchandiser Current Assets: v Cash v Receivables v Prepaid expenses v Merchandise Partially complete inventory products – some material, labor, or overhead has been added. Manufacturer Current Assets: v Cash v Receivables Materials waiting to be processed. v Prepaid Expenses v Inventories Raw Materials Work in Process Finished Goods Completed products awaiting sale.
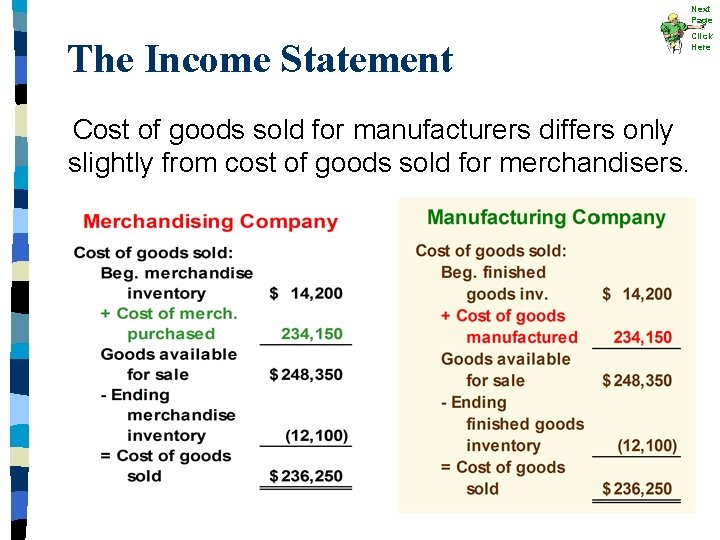
Next Page The Income Statement Cost of goods sold for manufacturers differs only slightly from cost of goods sold for merchandisers. Click Here
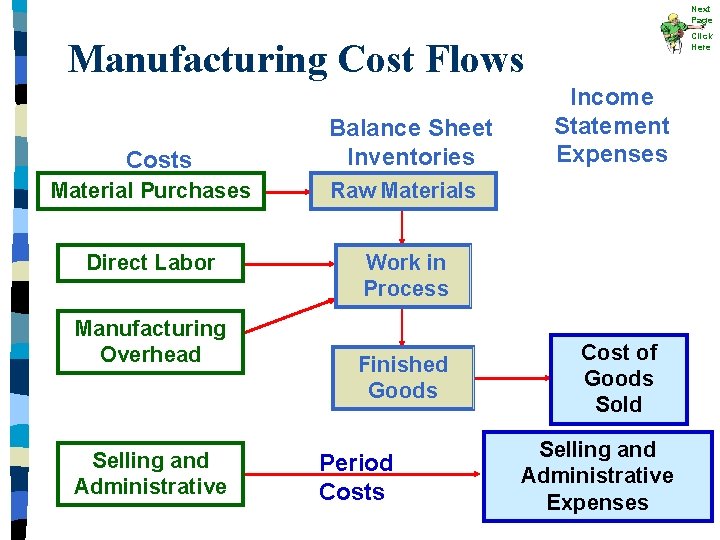
Next Page Click Here Manufacturing Cost Flows Costs Balance Sheet Inventories Material Purchases Raw Materials Direct Labor Work in Process Manufacturing Overhead Selling and Administrative Finished Goods Period Costs Income Statement Expenses Cost of Goods Sold Selling and Administrative Expenses
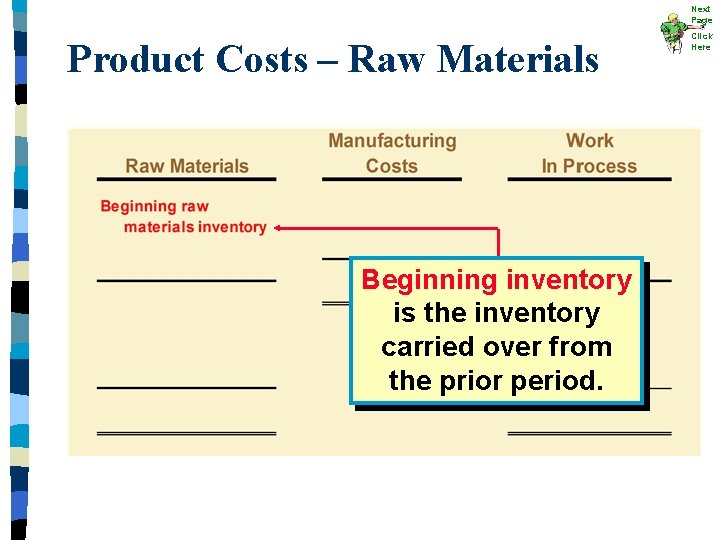
Next Page Product Costs – Raw Materials Beginning inventory is the inventory carried over from the prior period. Click Here
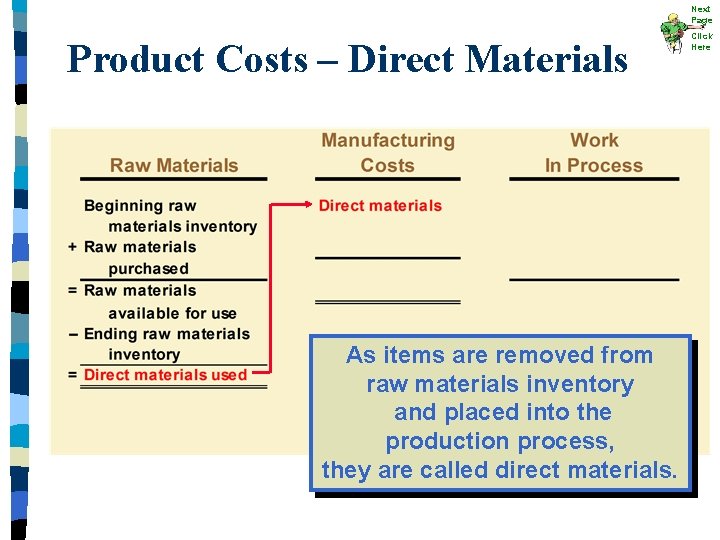
Next Page Product Costs – Direct Materials As items are removed from raw materials inventory and placed into the production process, they are called direct materials. Click Here
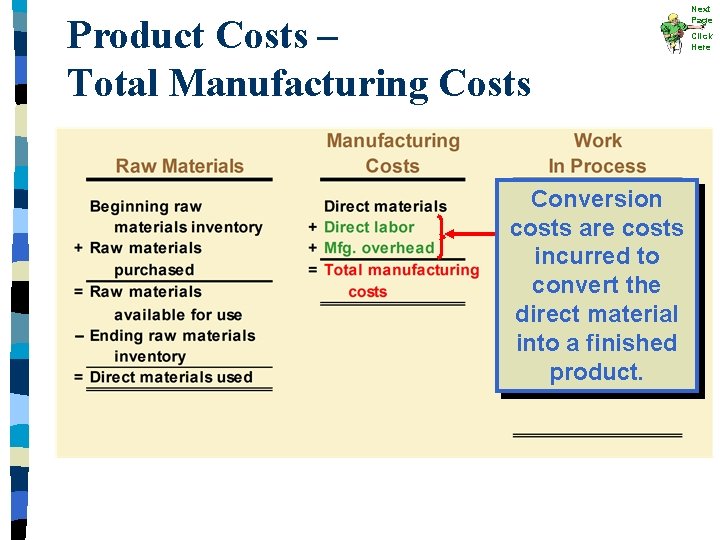
Product Costs – Total Manufacturing Costs Conversion costs are costs incurred to convert the direct material into a finished product. Next Page Click Here
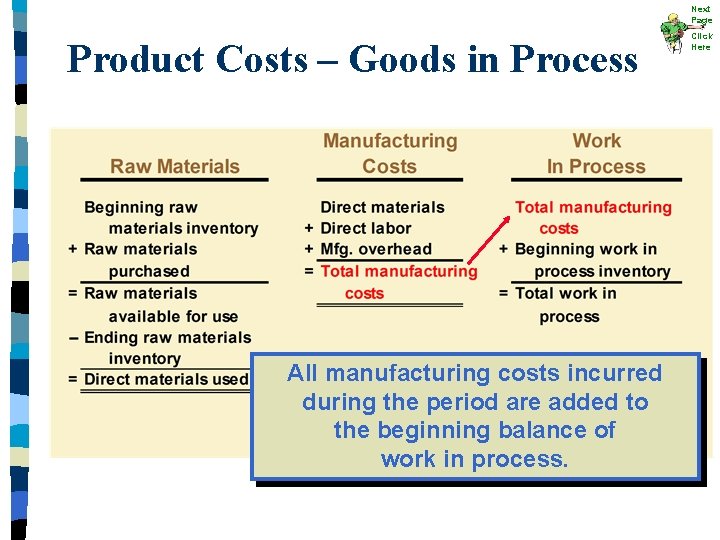
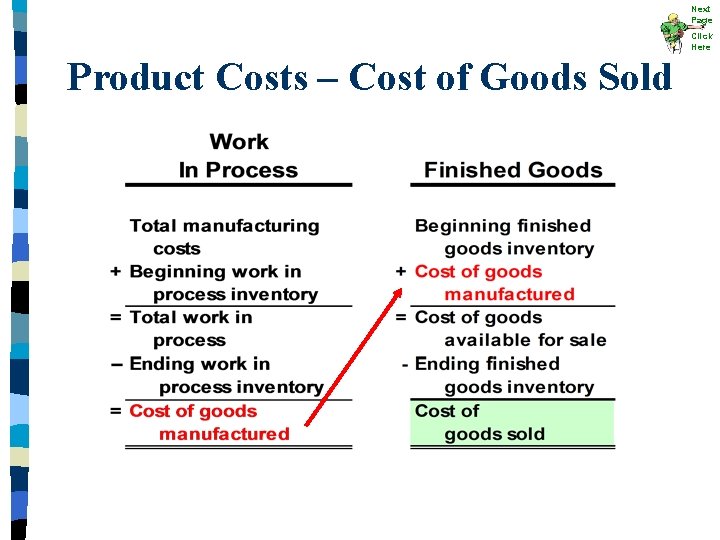
Next Page Product Costs – Goods in Process All manufacturing costs incurred during the period are added to the beginning balance of work in process. Click Here
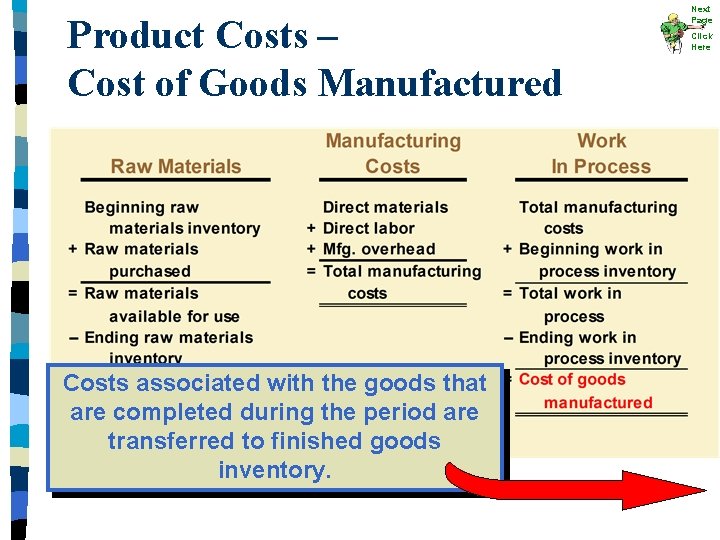
Product Costs – Cost of Goods Manufactured Costs associated with the goods that are completed during the period are transferred to finished goods inventory. Next Page Click Here
Next Page Click Here Product Costs – Cost of Goods Sold